
 Middle East and Africa Ultra-Low-Power Microcontroller Market | 2026-2036
Middle East and Africa Ultra-Low-Power Microcontroller Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Ultra-Low-Power Microcontroller Market Foresight
The gap between premium 32-bit ARM Cortex portfolios and commodity 8-bit offerings is realigning procurement patterns across the Middle East and Africa. Texas Instruments leverages its integrated wireless MCU lines to dominate industrial automation tenders in Saudi Arabia's giga-projects. STMicroelectronics anchors its position through deep specialization in healthcare-grade ultra-low-power designs that meet stringent medical device requirements. NXP Semiconpetes across automotive-qualified segments where extended temperature ranges and functional safety certifications differentiate supplier selection.
Ultra-low-power microcontrollers are semiconductor devices engineered to operate below one milliwatt in active states and sub-microamp levels during sleep modes, typically fabricated on sub-90nm process nodes with multiple power domains and clock gating architectures. These devices serve battery-constrained applications requiring months or years of unattended operation, from wearable biosensors to distributed industrial sensors. The 32-bit and ARM Cortex product categories command the dominant margin pool as developers migrate from legacy 8-bit architectures to handle complex edge-AI inference workloads. Consumer electronics and smart home applications represent the fastest-expanding demand vector, driven by UAE and Saudi residential construction booms mandating connected energy metering. Industrial automation remains the most mature application segment, with wired technology configurations still prevailing in factory floor deployments where electromagnetic interference resilience outweighs wireless convenience.
South Africa's National Regulator for Compulsory Specifications and the UAE's Telecommunications and Digital Government Regulatory Authority shape market access through electromagnetic compatibility and radio equipment type-approval frameworks that extend certification timelines for non-local suppliers. Saudi Arabia's Saudi Standards, Metrology and Quality Organization enforces energy-efficiency labeling rules that indirectly drive microcontroller selection toward lowest-active-power designs in white goods and HVAC controllers. Stakeholders must monitor how Gulf Cooperation Council harmonization of technical regulations alters the cost structure of multi-country product registrations relative to single-market entry strategies.
Market Dynamics
ARM Cortex-M33 cores with TrustZone security extensions are pulling procurement toward 32-bit platforms across industrial and residential segments, compressing the addressable market for legacy 8-bit alternatives as developers prioritize integrated cryptographic acceleration for connected device deployments.
Growth Catalysts
- Dubai Silicon Oasis cluster concentration:IoT device manufacturers co-locating near Jebel Ali logistics corridors reduce time-to-market for East African distribution channels, creating procurement pull effects across the Gulf.
- Saudi giga-project automation mandates:NEOM and Red Sea Project construction specifications require energy-harvesting sensor networks that specify sub-100nA sleep-mode consumption thresholds.
- South African residential energy management:Eskom's load-shedding crisis accelerates smart meter deployment, with 32-bit MCUs handling real-time demand-response algorithms in prepaid electricity systems.
Market Restraints
- Electromagnetic compliance fragmentation:Divergent type-approval timelines between South Africa's NRCS and UAE's TDRA extend product registration cycles, inflating go-to-market costs for multi-country portfolios.
- Wafer fabrication concentration:Foundry capacity for sub-40nm ultra-low-power processes concentrates in East Asian facilities, exposing procurement to shipping lane disruptions through the Red Sea corridor.
- 8-bit architecture persistence:Mature industrial sensor installations in Egypt and Nigeria continue specifying 8051-compatible cores, delaying 32-bit migration in price-sensitive maintenance contracts.
Strategic Opportunities
- Kenya and Ethiopia medical device expansion:Healthcare-grade ultra-low-power designs face limited local competition for wearable diagnostics serving rural clinic networks with intermittent grid access.
- GCC regulatory harmonization:Gulf Cooperation Council technical regulation alignment would collapse multi-country certification costs, favoring suppliers with established Saudi or UAE regulatory dossiers.
- Edge-AI inference at sensor nodes:Convergence of ARM Ethos-U microNPU coprocessors with Cortex-M55 cores enables voice-activated industrial safety systems without cloud connectivity dependency.
Industry Challenges
- Embedded security engineering scarcity:Firmware developers capable of implementing PSA Certified Level 2 security architectures remain concentrated in Cairo and Johannesburg, constraining ODM capacity expansion.
- Extended temperature qualification timelines:Automotive-grade AEC-Q100 testing for desert climate specifications adds 8-14 weeks to product release schedules, compressing competitive windows for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Ultra-Low-Power Microcontroller Market |
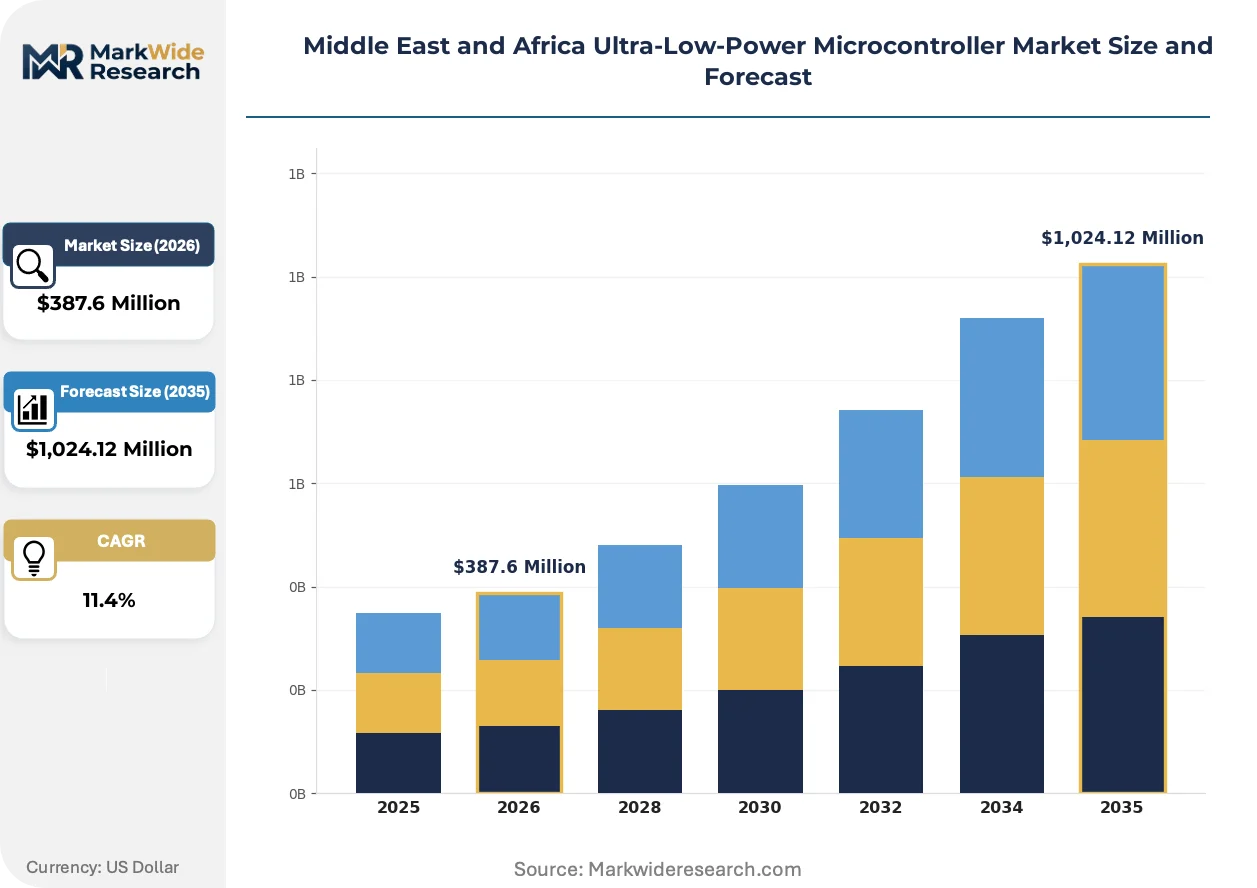
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 8-Bit, 16-Bit, 32-Bit, ARM Cortex Application: Consumer Electronics, Healthcare Devices, Industrial Automation, Smart Home Technology: Wireless, Wired, Integrated, Standalone End User: Manufacturers, Developers, Researchers, Educators |
| Companies Covered | Infineon Technologies AG, NXP Semiconductors, STMicroelectronics, Texas Instruments, Renesas Electronics Corporation, Microchip Technology Inc., Analog Devices Inc., Silicon Laboratories, ON Semiconductor, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Ultra-Low-Power Microcontroller Market Shifts & Advancements
Multi-protocol wireless integration and deterministic security architectures are compressing the traditional separation between connectivity silicon and application processing, collapsing BOM counts for battery-constrained designs.
ARM Cortex-M33 cores with integrated TrustZone security extensions are unifying previously discrete secure-element functions into single-die microcontroller implementations. Industrial automation OEMs in Saudi Arabia's manufacturing zones are specifying these unified platforms for machine-safety systems requiring IEC 61508 SIL-2 certification. The consolidation eliminates separate authentication ICs, reducing PCB area by 30-40% in space-constrained field devices.
Saudi Standards, Metrology and Quality Organization energy-efficiency labeling rules for white goods and HVAC controllers indirectly mandate lowest-active-power microcontroller selection. Appliance manufacturers serving the Kingdom must document standby power below 0.5W, forcing controller redesigns toward sub-50µA/MHz active consumption. This regulatory pressure propagates through supply chains serving Bahrain and Kuwait markets.
Smart home developers in UAE residential construction are compressing traditional distribution channels, procuring MCUs directly from authorized distributors rather than through subsystem integrators. This disintermediation accelerates design cycles for connected energy meters and security panels in Dubai's master-planned communities. Procurement teams now specify wireless MCUs with pre-certified sub-GHz stacks to bypass regional radio approval bottlenecks.
Middle East and Africa Ultra-Low-Power Microcontroller Market Segmentation
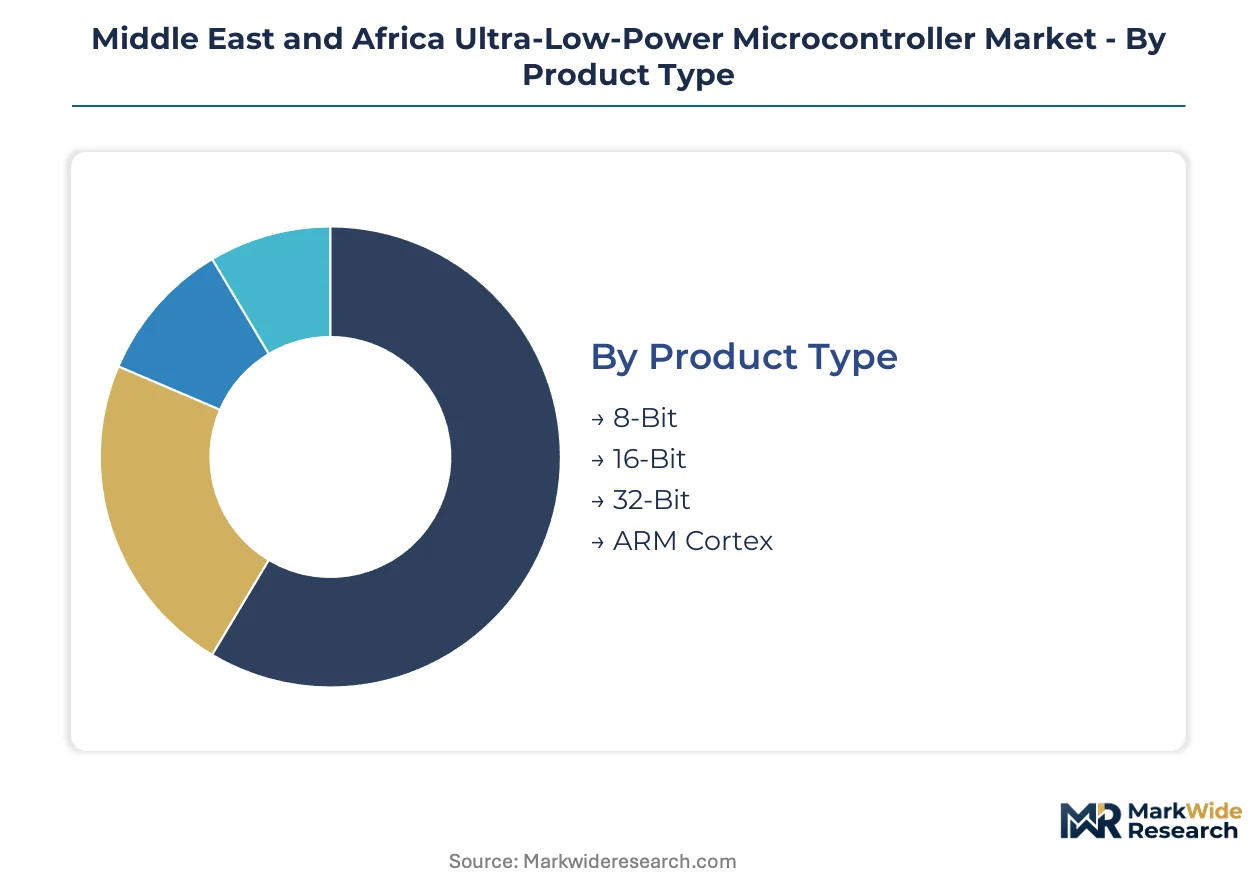
Ultra-low-power microcontroller procurement across the Middle East and Africa fragments sharply by integration depth and processing capability. Standalone deployments in legacy industrial settings coexist with deeply embedded system-on-chip configurations in Dubai's smart home construction pipeline. Understanding these segment boundaries clarifies where margin pools concentrate versus where price competition erodes supplier returns.
Product Type:
Integration depth varies dramatically across bit-width architectures, with standalone 8-bit devices persisting in maintenance-heavy industrial retrofits while 32-bit ARM Cortex cores embed deeply into multi-protocol wireless systems.
- 8-Bit:Legacy 8051-compatible cores dominate replacement cycles in Egyptian and Nigerian factory sensor networks where electromagnetic interference resilience outweighs processing demands. Procurement teams specify these for price-sensitive maintenance contracts that delay 32-bit migration.
- 16-Bit:Transitional architectures serve medical telemetry devices in Kenya's rural clinic networks, bridging the gap between ultra-low-cost 8-bit alternatives and complex 32-bit signal processing requirements.
- 32-Bit:ARM Cortex-M series cores handle real-time demand-response algorithms in South African prepaid electricity systems, with Eskom's load-shedding crisis accelerating deployment of sub-100nA sleep-mode capable devices.
- ARM Cortex:Cortex-M33 cores with TrustZone security extensions unify secure-element functions into single-die implementations for Saudi machine-safety systems requiring IEC 61508 SIL-2 certification, eliminating separate authentication ICs and reducing PCB area by 30-40%.
Volume placements concentrate in 32-bit architectures; the faster expansion belongs to ARM Cortex security-integrated variants.
Application:
Cost tier stratification separates mature industrial deployments from premium residential construction mandates, with smart home applications commanding hardware margins that factory floor automation cannot support.
- Consumer Electronics:Wearable biosensors and fitness trackers in UAE retail channels specify sub-50µA/MHz active consumption to extend battery life in compact form factors.
- Healthcare Devices:Wearable diagnostics serving Ethiopia's rural clinic networks with intermittent grid access demand healthcare-grade ultra-low-power designs with extended temperature qualification and PSA Certified Level 2 security architectures.
- Industrial Automation:Wired technology configurations prevail in Saudi giga-project manufacturing zones where electromagnetic interference resilience outweighs wireless convenience, though energy-harvesting sensor networks at NEOM specify sub-100nA sleep-mode thresholds.
- Smart Home:Connected energy meters and security panels in Dubai's master-planned communities drive procurement of wireless MCUs with pre-certified sub-GHz stacks, with developers procuring directly from authorized distributors to bypass regional radio approval bottlenecks.
Revenue concentrates in industrial automation; smart home applications are climbing the fastest as UAE and Saudi residential construction booms mandate connected energy metering.
Technology:
Supply concentration for wireless protocol stacks in Dubai Silicon Oasis clusters shapes competitive positioning, while wired alternatives retain dominance in electromagnetic-noise-intensive environments.
- Wireless:Multi-protocol integration combining Bluetooth Low Energy, Zigbee, and sub-GHz proprietary stacks collapses BOM counts for battery-constrained designs in smart home deployments across the Gulf.
- Wired:RS-485 and CAN bus configurations persist in South African mining automation and Saudi petrochemical sensor networks where deterministic latency and noise immunity are non-negotiable.
- Integrated:Single-die implementations merging application processing with radio front-ends reduce time-to-market for East African distribution channels through Dubai Silicon Oasis logistics corridors.
- Standalone:Discrete microcontroller plus external transceiver architectures survive in legacy Egyptian industrial installations where maintenance contracts specify 8051-compatible cores and procurement teams resist system redesign costs.
Shipment volumes favor wired configurations; integrated wireless-plus-processing solutions are gaining share fastest as Gulf developers prioritize reduced certification cycles.
End User:
Customer type determines purchasing authority and technical specification depth, with manufacturers wielding direct component procurement power that subsystem integrators once controlled.
- Manufacturers:White goods and HVAC controller producers serving Saudi Arabia must document standby power below 0.5W under Saudi Standards, Metrology and Quality Organization energy-efficiency labeling rules, forcing redesigns toward lowest-active-power microcontroller selection.
- Developers:Firmware engineering teams in Cairo and Johannesburg concentrate embedded security capability for PSA Certified Level 2 implementations, constraining ODM capacity expansion for connected device deployments.
- Researchers:Academic and national laboratory programs in the UAE and South Africa evaluate emerging ARM Ethos-U microNPU coprocessors for voice-activated industrial safety systems without cloud connectivity dependency.
- Educators:Technical training institutes across the Gulf Cooperation Council develop curriculum around Cortex-M33 TrustZone architectures to address scarcity of engineers capable of implementing deterministic security frameworks.
Procurement volumes concentrate with manufacturers; developer-facing direct sales are expanding most quickly as disintermediation accelerates design cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai Silicon Oasis anchors microcontroller procurement flows across the Middle East and Africa, with IoT device manufacturers clustering near Jebel Ali logistics corridors to reduce time-to-market for East African distribution channels.
United Arab Emirates
Smart home construction booms in Dubai's master-planned communities mandate connected energy metering systems. The Telecommunications and Digital Government Regulatory Authority enforces radio equipment type-approval frameworks that extend certification timelines for non-local suppliers. Developers in Dubai Silicon Oasis procure wireless MCUs directly from authorized distributors, bypassing traditional subsystem integrators.
Saudi Arabia
NEOM and Red Sea Project construction specifications require energy-harvesting sensor networks with sub-100nA sleep-mode consumption thresholds. The Saudi Standards, Metrology and Quality Organization enforces energy-efficiency labeling rules that indirectly drive microcontroller selection toward lowest-active-power designs. Manufacturing zones in Riyadh and the Eastern Province specify ARM Cortex-M33 cores with TrustZone security extensions for machine-safety systems.
South Africa
Eskom's load-shedding crisis accelerates smart meter deployment, with 32-bit MCUs handling real-time demand-response algorithms in prepaid electricity systems. The National Regulator for Compulsory Specifications enforces electromagnetic compatibility standards that filter out non-compliant imports. Johannesburg hosts concentrated firmware engineering capability for PSA Certified Level 2 security implementations.
Egypt
Mature industrial sensor installations in Cairo and Alexandria continue specifying 8051-compatible cores, delaying 32-bit migration in price-sensitive maintenance contracts. The country's national telecommunications regulator maintains type-approval requirements for radio equipment. The Cairo metropolitan area concentrates embedded security engineering scarce across the broader region.
Kenya
Healthcare-grade ultra-low-power designs face limited local competition for wearable diagnostics serving rural clinic networks with intermittent grid access. The national communications authority oversees equipment type-approval for imported medical devices. Nairobi anchors procurement coordination for East African distribution channels served through UAE logistics hubs.
Middle East and Africa Ultra-Low-Power Microcontroller Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Middle East and Africa ultra-low-power microcontroller market. Integrated device manufacturers with captive fabrication capacity anchor supply security for automotive and industrial tenders. Fabless specialists concentrate on rapid wireless protocol integration for consumer-facing applications. Tiered competition separates premium 32-bit ARM Cortex portfolios from commodity 8-bit alternatives. Dominant competitive moves include multi-protocol wireless integration and direct distributor relationships that disintermediate traditional subsystem integrators.
Within the integrated device manufacturer tier, Infineon Technologies AG and NXP Semiconductors occupy positions shaped by automotive qualification requirements and extended temperature range specifications. Texas Instruments exemplifies the wireless MCU specialist archetype through integrated radio-plus-processing portfolios. STMicroelectronics anchors the healthcare-grade specialization vector with deep ultra-low-power design expertise. These three companies represent distinct strategic postures: automotive-qualified scale, wireless integration leadership, and medical-grade precision respectively.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| NXP Semiconductors |
| STMicroelectronics |
| Texas Instruments |
| Renesas Electronics Corporation |
| Microchip Technology Inc. |
| Analog Devices Inc. |
| Silicon Laboratories |
| ON Semiconductor |
| Others |
Supply & Pricing Matrix
Firmware engineering scarcity in Cairo and Johannesburg anchors labor-cost differentials that widen pricing-tier spreads between PSA Certified Level 2 implementations and commodity 8-bit alternatives. This workforce concentration forces premium-tier suppliers to absorb certification-driven engineering premiums while economy-tier procurement exploits maintenance-contract price sensitivity across Egyptian and Nigerian industrial retrofits.
Pricing Analysis
Active-power consumption thresholds anchor value-based pricing for Saudi white goods and HVAC controllers facing Saudi Standards, Metrology and Quality Organization energy-efficiency labeling rules. Pricing stratifies across automotive-qualified, industrial-grade, and consumer-tier certification levels, with AEC-Q100 desert-climate qualification adding 8-14 weeks to release schedules that compress margins for new entrants. Cost compression in 8-bit maintenance contracts intensifies as procurement teams resist redesign investments despite 32-bit migration pressure. Industrial automation buyers in Saudi giga-projects exhibit lowest price sensitivity due to uptime guarantees, while Egyptian sensor network retrofits drive economy-tier volume.
Supply Chain Analysis
Sub-40nm wafer fabrication rests on East Asian foundry capacity, exposing procurement to Red Sea shipping lane disruptions that extend lead times for Dubai Silicon Oasis cluster manufacturers. Silicon wafers, photoresist chemicals, and advanced packaging substrates draw from Taiwan, South Korea, and Japan, creating single-source vulnerability for ultra-low-power process nodes. Distribution runs through Jebel Ali logistics corridors serving East African markets, with pre-certified wireless MCU stocks bypassing regional radio approval bottlenecks for UAE smart home developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around suppliers with captive certification dossiers and established regulatory relationships, as electromagnetic compliance fragmentation forces weaker players to absorb multi-country registration costs that erode project economics.
For Market Incumbents: Cement dominance by deepening captive fabrication relationships for sub-90nm process nodes and accelerating GCC regulatory harmonization lobbying to collapse multi-country certification burdens. Infineon, NXP, and STMicroelectronics must defend against fabless wireless specialists by controlling distributor relationships that disintermediate subsystem integrators in Dubai Silicon Oasis procurement flows. For New Entrants and Emerging Players: Enter via Kenya and Ethiopia medical device expansion where healthcare-grade ultra-low-power designs face limited local competition for wearable diagnostics serving rural clinic networks with intermittent grid access. Target direct developer sales in Johannesburg and Cairo firmware engineering clusters, bypassing traditional manufacturing procurement channels through PSA Certified Level 2 reference design partnerships. For Investors and Strategic Acquirers: Re-rating potential sits with fabless wireless MCU specialists given multi-protocol integration convergence collapsing BOM counts for battery-constrained Gulf smart home deployments. Acquisition targets should demonstrate established Saudi Standards, Metrology and Quality Organization or UAE Telecommunications and Digital Government Regulatory Authority dossiers. Watch GCC regulatory harmonization announcements as inflection indicators for multi-country registration cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Wireless Integration | Combining Bluetooth Low Energy, Zigbee, and sub-GHz stacks collapses BOM counts for Dubai smart home deployments. |
| TrustZone Security Certification | ARM Cortex-M33 PSA Certified Level 2 implementations eliminate separate authentication ICs in Saudi machine-safety systems. |
| GCC Regulatory Harmonization | Gulf Cooperation Council technical regulation alignment would collapse multi-country certification costs for established dossier holders. |
| Direct Distributor Relationships | Bypassing subsystem integrators accelerates design cycles for connected energy meters in Dubai master-planned communities. |
| Edge-AI MicroNPU Integration | ARM Ethos-U coprocessors with Cortex-M55 cores enable voice-activated industrial safety without cloud dependency. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated against primary interviews with microcontroller product managers, embedded firmware engineering directors, IoT device procurement leads, and semiconductor distribution channel partners. SEC 10-K disclosures, UAE Telecommunications and Digital Government Regulatory Authority type-approval databases, Saudi Standards, Metrology and Quality Organization energy-efficiency filings, and South African National Regulator for Compulsory Specifications electromagnetic compatibility registers provided demand-side validation. Bottom-up unit shipment estimates across bit-width architectures reconciled with top-down foundry capacity allocations.
Data-stream reconciliation across product type, application, technology configuration, and end-user segments shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectories weighted by procurement volume concentration in Dubai Silicon Oasis, Saudi giga-projects, and South African load-shedding response programs. Modeling incorporated ARM Cortex-M33 adoption curves, GCC regulatory harmonization probability assessments, and Red Sea logistics risk adjustments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged electromagnetic compliance fragmentation or East Asian foundry capacity constraints. Forecasts reflect assumptions around firmware engineering scarcity persistence and Gulf residential construction momentum. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Silicon-Based Anode Market
Semiconductor Devices
Global Gan Semiconductor Device Market
Semiconductor Devices
Global Trench Gate Power MOSFET Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
Global Through Silicon via (TSV) Technology Market
Semiconductor Devices
Hairpin Stator Market
Semiconductor Devices
United Arab Emirates (UAE) CEP Market
Semiconductor Devices
Embedded Multimedia Card Market
Semiconductor Devices
Temperature-Controlled Semiconductor Market
Semiconductor Devices
Americas Power Transistor Market
Semiconductor Devices
LTCC and HTCC Market
Semiconductor Devices
Quartz Crystal Oscillators Market
Semiconductor Devices
Silicon Epitaxial Wafer Market
Semiconductor Devices
Europe Touch Screen Controllers Market
Semiconductor Devices
Printed Circuit Board (PCB) Laminate Market
Semiconductor Devices
T-Con Board Market