
 Gan-On-Silicon Market | 2026-2036
Gan-On-Silicon Market Size, Share, and Industry Trends Forecast 2026-2036
Gan-On-Silicon Market Foresight
Multi-source wafer supply is rebalancing toward captive silicon substrates as foundries confront gallium nitride epitaxy bottlenecks. Infineon Technologies AG anchors European production through its Dresden fab complex, while Navitas Semiconductor leverages fabless partnerships to scale high-frequency power ICs without fixed-asset exposure. Innoscience dominates 8-inch GaN-on-silicon wafer output from its Zhuhai manufacturing base, sustaining cost advantages in consumer adapter applications.
Gan-on-silicon refers to gallium nitride epitaxial layers deposited on silicon substrates, typically achieving breakdown voltages above 650V with electron mobility exceeding 2,000 cm²/V·s, enabling high-efficiency power conversion in compact form factors. Power amplifiers within the component category lead revenue contribution due to 5G base station deployment cycles, while gallium nitride HEMTs in the technology dimension represent the fastest-growing segment as RF performance requirements intensify. DC-DC converters occupy mature margin pools in data center power architectures, though voltage regulators are gaining share in automotive 48V mild-hybrid systems.
FDA device-level electromagnetic compatibility standards, EPA energy efficiency regulations for external power supplies, and China's GB standards for grid-connected inverters collectively shape product certification requirements and market access timelines. The EU AI Act's infrastructure power provisions and REACH substance restrictions on semiconductor process chemicals add compliance layers for European-bound shipments. Stakeholders must monitor foundry utilization rates against substrate qualification timelines, as epitaxy capacity constraints could throttle volume scaling regardless of downstream design wins.
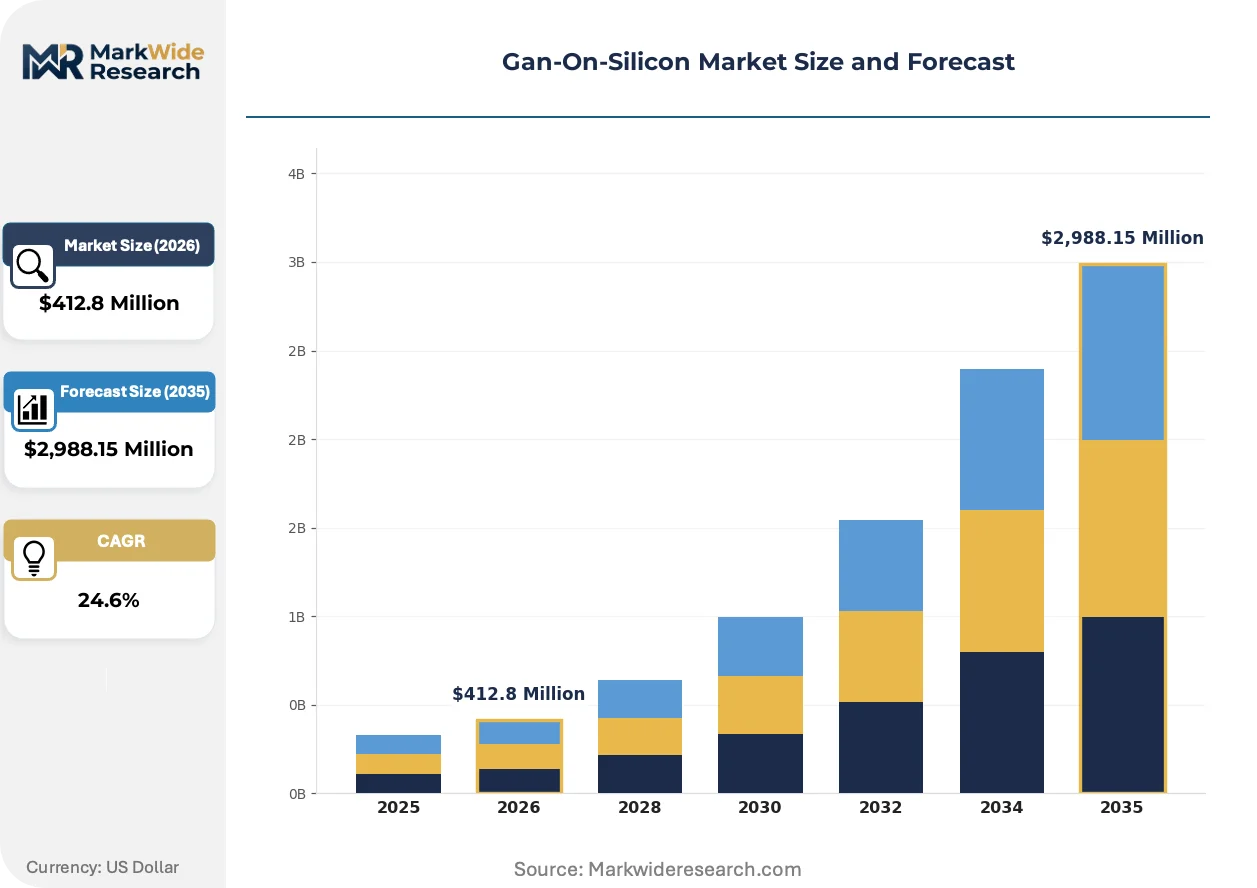
Market Dynamics
Epitaxy capacity bottlenecks are concentrating supply leverage among captive silicon substrate producers, forcing power semiconductor designers to secure multi-year wafer allocation agreements before committing to automotive platform wins.
Growth Catalysts
- EU Green Deal efficiency mandates:The regulation's tightening standards for power conversion losses in EV drivetrains are pulling GaN HEMT designs into 800V architectures. Automakers in Germany's automotive semiconductor corridor now specify GaN-on-silicon for onboard chargers.
- 5G base station deployment cycles:Power amplifiers within RF infrastructure are commanding priority allocation from foundries. Network equipment manufacturers in South Korea and Japan are qualifying GaN-on-silicon for massive MIMO arrays.
- China's dual carbon goals:The national framework is accelerating grid-tied inverter replacements. Domestic solar inverter producers are shifting from silicon IGBTs to GaN HEMTs in residential string inverter platforms.
Market Restraints
- Epitaxy equipment lead times:Metal-organic chemical vapor deposition reactor delivery schedules now extend eighteen months, constraining foundry expansion regardless of design win pipelines.
- Silicon substrate purity requirements:Dislocation density specifications for 8-inch GaN-on-silicon wafers reject standard CMOS-grade silicon, forcing dedicated ingot sourcing from suppliers in Japan and Germany.
- SiC MOSFET substitution threat:Silicon carbide devices above 900V breakdown voltage retain performance advantages in heavy-duty EV traction inverters, limiting GaN-on-silicon addressable market in premium automotive segments.
Strategic Opportunities
- India's PLI scheme for semiconductor manufacturing:The production-linked incentive framework is attracting GaN epitaxy investments for domestic power electronics. Local adapter and LED driver producers represent captive demand anchors.
- 48V mild-hybrid voltage regulators:Automotive tier-1 suppliers are redesigning belt-starter generator systems around GaN-based DC-DC stages. This voltage class sits below SiC optimization thresholds.
- EU AI Act infrastructure power provisions:The regulation's efficiency requirements for data center compute clusters are mandating power supply redesigns. Hyperscale operators in the Netherlands and Ireland are pre-qualifying GaN-based 48V rack architectures.
Industry Challenges
- GaN-specific reliability physics expertise:The talent pool for dynamic on-resistance characterization and threshold voltage drift modeling remains concentrated among a handful of academic laboratories and IDM veterans.
- Automotive AEC-Q101 qualification timelines:The stress-test protocol for wide-bandgap discretes adds twelve to eighteen months to product introduction schedules, compressing design window alignment with platform launches.
- REACH substance restrictions on semiconductor process chemicals:ECHA's evolving candidate list for gallium and ammonia precursors is forcing process chemistry requalification at European-bound foundries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gan-On-Silicon Market |
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $2,988.15 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Power Amplifiers, Voltage Regulators, DC-DC Converters, Integrated Circuits Application: Consumer Electronics, Telecommunications, Automotive, Industrial Equipment Technology: High-Efficiency Switches, RF Devices, Power Modules, Gallium Nitride HEMTs End User: OEMs, Electrical Distributors, Circuit Designers, Research Institutions |
| Companies Covered | Infineon Technologies AG, NXP Semiconductors N.V, Toshiba Corporation, Renesas Electronics Corporation, Texas Instruments Incorporated, Navitas Semiconductor, GaN Systems, Innoscience, Nexperia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gan-On-Silicon Market Shifts & Advancements
Process integration advances and regulatory efficiency mandates are compressing development cycles across power conversion applications. The technology base is fragmenting between automotive-grade reliability platforms and cost-optimized consumer designs.
GaN power ICs integrating gate drivers, protection logic, and power stages onto monolithic dies are modularizing subsystem design for adapter and charger OEMs. Consumer electronics brands in Taiwan and Shenzhen are adopting these devices to reduce bill-of-materials complexity and accelerate time-to-market for gallium nitride fast chargers. The integration trend is compressing margins for discrete component suppliers while expanding addressable unit volumes in mid-power applications.
EPA energy efficiency regulations for external power supplies are mandating active-mode efficiency minimums above 89% at 50% load. The standard is disqualifying traditional silicon-based flyback designs in North American-bound products. Adapter manufacturers are responding by redesigning around GaN HEMT primary switches and synchronous rectification, with California's CEC Title 20 adding standby power limits that further favor wide-bandgap architectures.
Aftermarket service unbundling is fragmenting procurement authority in data center power infrastructure. Colocation operators in Virginia and Frankfurt are separating UPS and rack PDU sourcing decisions from server procurement, creating specification influence for specialized power semiconductor distributors. This channel shift is elevating technical sales support and reference design availability as competitive differentiators over volume pricing alone.
Gan-On-Silicon Market Segmentation
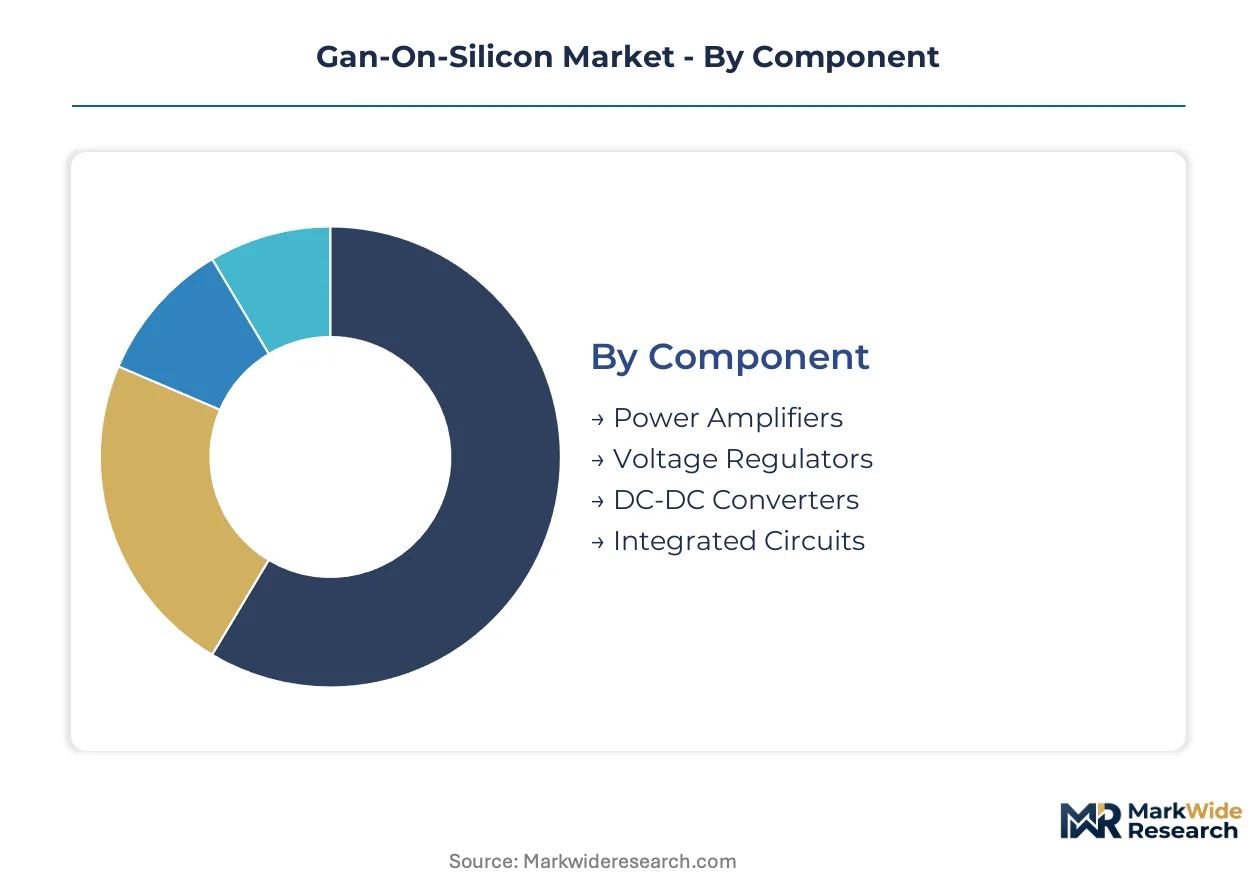
GaN-on-silicon technology fragments across power conversion and RF signal chains, with component-level economics diverging sharply between high-volume consumer adapters and automotive-grade reliability platforms. Application pull varies by voltage class and switching frequency requirements, creating distinct procurement behaviors among tier-1 suppliers and fabless design houses.
Component:
Volume concentration favors power stages in adapter and charger applications, while premium pricing attaches to RF amplification and integrated gate-drive solutions.
- Power Amplifiers:These devices amplify RF signals in 5G massive MIMO arrays and radar systems. Network equipment manufacturers in South Korea specify GaN-on-silicon for base station deployment cycles, prioritizing thermal performance and linearity over cost minimization.
- Voltage Regulators:Automotive 48V mild-hybrid systems are redesigning belt-starter generator stages around GaN-based DC-DC conversion. Tier-1 suppliers in Germany's automotive semiconductor corridor specify these components for efficiency gains below SiC optimization thresholds.
- DC-DC Converters:Data center power architectures represent mature margin pools for intermediate bus converters.
- Integrated Circuits:Monolithic GaN power ICs with gate drivers and protection logic reduce BOM complexity for consumer adapter OEMs.
Mature deployment sits with DC-DC Converters. Newer deployment is concentrated in Voltage Regulators.
Application:
Customer procurement authority splits between consumer electronics brands optimizing for cost-per-watt and automotive OEMs prioritizing AEC-Q101 qualification timelines.
- Consumer Electronics:Fast charger and adapter manufacturers in Taiwan and Shenzhen drive unit volume for 65W-140W USB-C power delivery. EPA energy efficiency regulations for external power supplies mandate active-mode efficiency minimums above 89%, disqualifying silicon-based flyback designs in North American-bound products.
- Automotive:Onboard chargers and DC-DC stages in 800V EV architectures specify GaN HEMTs for switching frequency advantages. The EU Green Deal's efficiency mandates pull designs into German automotive platforms, though SiC MOSFETs retain preference above 900V in heavy-duty traction inverters.
- Telecommunications:5G infrastructure deployment concentrates demand for RF power amplifiers.
- Industrial Equipment:Grid-tied solar inverters and motor drives represent emerging qualification pipelines.
Volume leadership belongs to Consumer Electronics. Value concentration is shifting toward Automotive.
Technology:
Process maturity separates established HEMT platforms from emerging integration approaches combining power stages with control logic.
- Gallium Nitride HEMTs:High-electron-mobility transistors achieve electron mobility exceeding 2,000 cm²/V·s on silicon substrates. These devices are climbing the fastest in RF performance applications, with foundries in Japan and Germany prioritizing epitaxy capacity for 5G base station and radar qualification programs.
- High-Efficiency Switches:Discrete power transistors for adapter primary stages and synchronous rectification dominate consumer electronics procurement. China's dual carbon goals accelerate residential string inverter replacements, pulling designs from silicon IGBTs toward GaN-based switching topologies.
- RF Devices:Low-noise amplifiers and mmWave front-ends serve defense and satellite communication markets.
- Power Modules:Multi-die packages integrating gate drivers and protection circuits address automotive reliability requirements.
Commercial scale favors High-Efficiency Switches. Technical differentiation is concentrating in Gallium Nitride HEMTs.
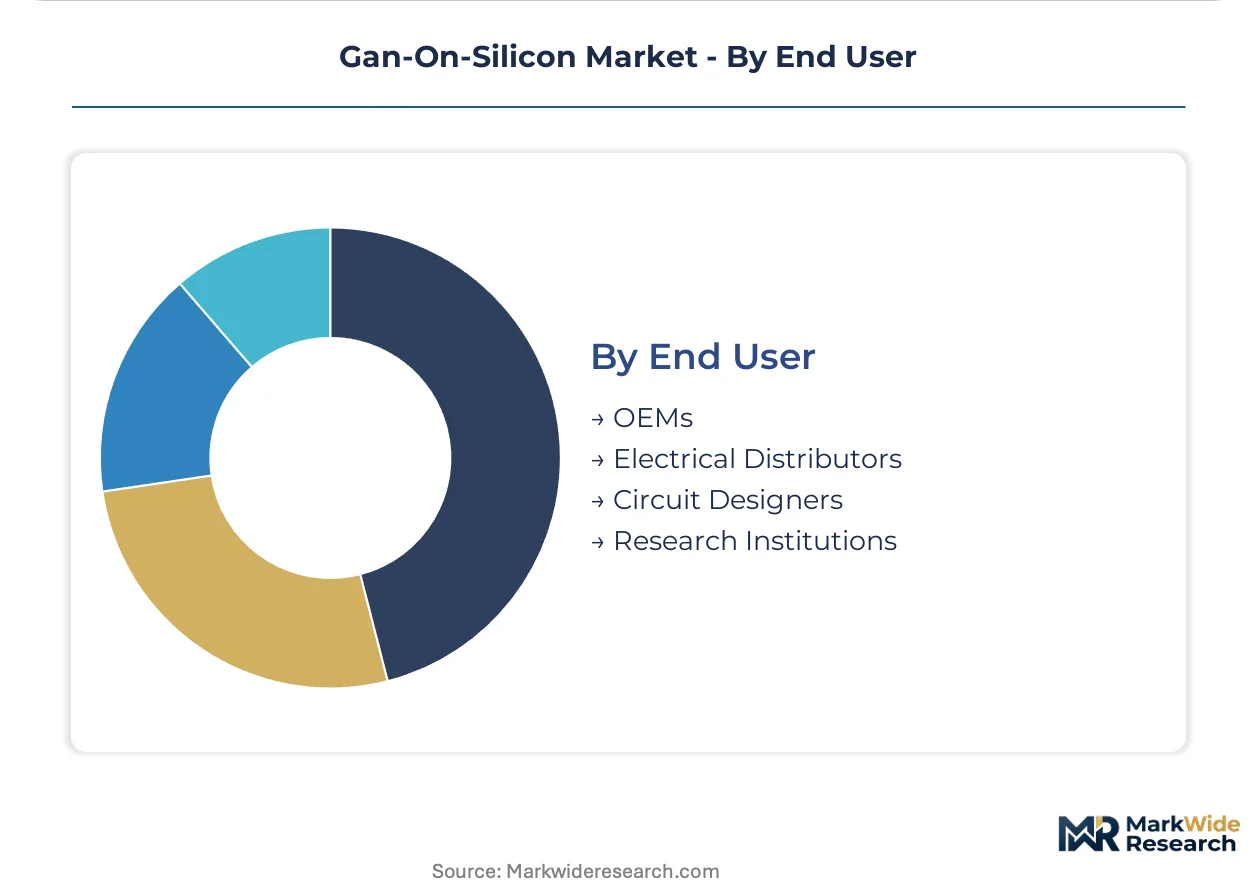
End User:
Procurement sophistication varies between specification authority holders and channel intermediaries with limited design influence.
- OEMs:Original equipment manufacturers in consumer electronics and automotive verticals hold direct foundry relationships for multi-year wafer allocation agreements. These stakeholders secure capacity before committing to platform wins, reflecting epitaxy bottlenecks in gallium nitride supply chains.
- Circuit Designers:Fabless power semiconductor houses specify GaN-on-silicon for adapter and charger reference designs. Design wins in Shenzhen and Taipei concentrate demand for integrated GaN power ICs with reduced external component counts.
- Electrical Distributors:Channel partners aggregate demand from mid-tier industrial and commercial customers.
- Research Institutions:Academic laboratories concentrate GaN-specific reliability physics expertise for dynamic on-resistance characterization.
Volume purchasing power rests with OEMs. Technical specification authority is migrating toward Circuit Designers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium precursor supply chains anchor production geography, with high-purity metal sourcing concentrated in China and Kazakhstan before epitaxy processing in East Asia and Europe.
China
Domestic solar inverter producers and EV manufacturers drive GaN HEMT qualification for 800V onboard chargers. The dual carbon goals framework mandates grid-tied inverter efficiency improvements, accelerating residential string inverter replacements. Innoscience's Zhuhai manufacturing base sustains 8-inch wafer output cost advantages for consumer adapter applications.
Germany
Automotive OEMs in the Munich-Dresden semiconductor corridor specify GaN-on-silicon for 48V mild-hybrid voltage regulators and DC-DC stages. The EU Green Deal's efficiency mandates pull designs into premium EV platforms. Infineon Technologies AG anchors European production through its Dresden fab complex, securing captive silicon substrate supply.
United States
Hyperscale data center operators in Virginia and Oregon pre-qualify GaN-based 48V rack architectures for AI compute clusters. The EPA energy efficiency regulations for external power supplies mandate active-mode efficiency minimums above 89%, disqualifying silicon flyback designs. Navitas Semiconductor leverages fabless partnerships to scale high-frequency power ICs without fixed-asset exposure.
South Korea
Network equipment manufacturers qualify GaN-on-silicon power amplifiers for 5G massive MIMO base station deployment cycles. The national 5G infrastructure investment program prioritizes thermal performance and linearity specifications. Seoul-based RF foundries concentrate epitaxy capacity for telecommunications qualification programs.
Japan
Industrial equipment producers and automotive tier-1 suppliers source high-purity silicon ingots for 8-inch GaN-on-silicon wafer production. METI's semiconductor supply chain resilience initiatives support domestic substrate qualification. Kyushu-based material suppliers maintain dislocation density specifications that reject standard CMOS-grade silicon.
Gan-On-Silicon Market Competitive Landscape
Global majors compete with regional champions across epitaxy capacity and substrate qualification timelines. The vendor base separates between captive silicon substrate producers with in-house foundry operations and fabless design houses accessing merchant epitaxy services. Three archetypes dominate: integrated device manufacturers controlling wafer supply, fabless power semiconductor specialists, and discrete component suppliers. Competitive moves concentrate on multi-year wafer allocation agreements and automotive AEC-Q101 qualification pipelines.
Among European integrated device manufacturers, Infineon Technologies AG exemplifies the captive-production archetype through its Dresden fab complex. Fabless specialists include Navitas Semiconductor, which occupies a position leveraging partnership models to avoid fixed-asset exposure. GaN Systems represents the discrete-component tier, sitting within merchant epitaxy supply chains. These three companies anchor the competitive structure across automotive-grade reliability platforms and cost-optimized consumer designs.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| NXP Semiconductors N.V |
| Toshiba Corporation |
| Renesas Electronics Corporation |
| Texas Instruments Incorporated |
| Navitas Semiconductor |
| GaN Systems |
| Innoscience |
| Nexperia |
| Others |
Supply & Pricing Matrix
Automotive OEM specifications for AEC-Q101 qualification timelines are compressing procurement windows, forcing foundries to pre-allocate epitaxy capacity years ahead of volume ramps and elevating pricing power among captive silicon substrate producers.
Pricing Analysis
Warranty and service bundling separates automotive-grade contracts from consumer electronics spot purchases, with tier-1 suppliers in Germany's Munich-Dresden corridor paying premiums for multi-year reliability guarantees. Three-tier pricing structure across automotive-certified, industrial-grade, and consumer-optimized tiers reflects certification investment recovery. Cost compression in consumer adapter segments is intensifying because Innoscience's Zhuhai scale advantages force second-tier competitors toward negative margins. Adapter OEMs in Shenzhen exhibit highest price sensitivity, while German automotive semiconductor buyers prioritize qualification certainty over unit cost.
Supply Chain Analysis
Reverse-logistics flows for failed power modules remain underdeveloped, with automotive warranty returns accumulating at tier-1 supplier facilities awaiting failure analysis protocols. Gallium precursor supply concentrates in China and Kazakhstan before epitaxy processing in Japan and Germany. High-purity silicon ingots, metal-organic chemical vapor deposition reactors, and ammonia process chemicals constitute critical input dependencies. Single-source vulnerability in 8-inch substrate qualification threatens foundry expansion timelines. Distribution runs through specialized power semiconductor distributors with technical sales support capabilities, particularly for data center and automotive qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epitaxy equipment lead times extending eighteen months are forcing capital-light fabless designers toward exit or acquisition, consolidating competitive structure around integrated device manufacturers with captive wafer supply.
For Market Incumbents: Deploy multi-year wafer allocation agreements as a defensive moat against emerging fabless competitors. Infineon Technologies AG's Dresden captive production anchors European automotive qualification pipelines, while backward integration into silicon substrate sourcing insulates against Japan-Germany ingot supply constraints. Capacity addition in 8-inch GaN-on-silicon wafer output sustains cost advantages against SiC MOSFET substitution above 900V. For New Entrants and Emerging Players: India's PLI scheme for semiconductor manufacturing opens a window for domestic epitaxy investments serving local adapter and LED driver demand. White-space targets include 48V mild-hybrid voltage regulators below SiC optimization thresholds and grid-tied solar inverters under China's dual carbon goals. Go-to-market through technical distributor partnerships with reference design support accelerates qualification timelines. For Investors and Strategic Acquirers: Re-rating potential sits with fabless power IC specialists given EPA energy efficiency regulations disqualifying silicon-based designs in North American-bound products. Long-term viability centers on automotive AEC-Q101 qualification pipelines and multi-year foundry relationships. Practitioners should monitor metal-organic chemical vapor deposition reactor delivery schedules against design win backlogs as an inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive AEC-Q101 Qualification Pipeline | Secures multi-year platform wins with German OEMs specifying GaN HEMTs for 800V architectures. |
| Multi-Year Wafer Allocation Agreement | Locks epitaxy capacity ahead of competitor commitments, reflecting eighteen-month equipment lead times. |
| GaN Power IC Monolithic Integration | Reduces BOM complexity for Shenzhen adapter OEMs pursuing fast-charger time-to-market compression. |
| Backward Integration into Silicon Substrate Supply | Captures dislocation density specification control from Kyushu-based material suppliers. |
| EU AI Act Infrastructure Power Compliance | Pre-qualifies 48V rack architectures with Netherlands and Ireland hyperscale operators. |
Research Methodology
Document review covered SEC 10-K filings, EPA energy efficiency regulation dockets, and EU Green Deal implementation guidelines, complemented by interviews with power semiconductor procurement directors at tier-1 automotive suppliers, foundry operations managers, and technical sales leads at specialized distributors. Primary fieldwork engaged epitaxy equipment specialists, AEC-Q101 test laboratory directors, and inverter platform engineers at solar OEMs. Secondary validation drew from customs trade data, IHS Markit vehicle production databases, and hyperscaler capex disclosures. Bottom-up segment sizing triangulated against top-down market aggregation.
Segment-level outputs across component, application, technology, and end-user dimensions were calibrated against foundry utilization rates and substrate qualification timelines throughout the projection horizon. CAGRs were derived from regression analysis of historical epitaxy capacity expansion against design win conversion rates. Industry-specific forecast inputs included metal-organic chemical vapor deposition reactor delivery schedules and automotive platform launch cadences.
Caveats apply where metal-organic chemical vapor deposition equipment delivery delays or REACH substance restrictions on gallium precursors could materially shift the outlook. Forecasts reflect assumptions around foundry utilization stability and automotive qualification timeline adherence. Practitioners should monitor epitaxy capacity utilization against substrate qualification backlogs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Ferroelectric FET Market
Semiconductor Devices
Laneth-16 Market
Semiconductor Devices
Global Current Sense Amplifier Market
Semiconductor Devices
Silicon Carbide Semiconductor Devices Market
Semiconductor Devices
Silicon Epitaxial Wafer Market
Semiconductor Devices
APAC Semiconductor Device in Consumer Industry Market
Semiconductor Devices
3D TSV Device Market
Semiconductor Devices
China Semiconductor Diode Market
Semiconductor Devices
APAC Semiconductor Device for Industrial Applications Market
Semiconductor Devices
Global Layer Pads Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
Global Transistor Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
India MLCC Market
Semiconductor Devices
5G Modems Market
Semiconductor Devices
Europe Semiconductor Device Market