
 Asia-Pacific Silicon Carbide Wafers Market | 2026-2036
Asia-Pacific Silicon Carbide Wafers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Silicon Carbide Wafers Market Outlook
Transition from silicon insulated-gate bipolar transistors to silicon carbide metal-oxide-semiconductor field-effect transistors is reconfiguring power module architectures for electric vehicles and renewable inverters. TankeBlue Semiconductor Co., Ltd. leverages proprietary physical vapor transport crystal growth to anchor domestic supply security for China's automotive tier ones. SICC Co., Ltd. sustains one of the region's broadest wafer diameter portfolios, spanning 4-inch through 8-inch formats. SK Siltron Co., Ltd. competes through backward integration into high-purity SiC powder synthesis, reducing feedstock exposure.
Silicon carbide wafers are monocrystalline substrates produced through sublimation growth from silicon and carbon precursors at temperatures exceeding 2,200 degrees Celsius, engineered for high-breakdown-voltage, high-temperature, and high-frequency semiconductor applications. The 6-inch diameter segment dominates current fab tool compatibility and device economics, while 8-inch qualification accelerates among power MOSFET manufacturers seeking die-per-wafer advantages. Electric vehicle traction inverters represent the fastest-growing application dimension, absorbing wafers from multiple product and technology categories as OEMs redesign thermal management around SiC switching losses.
China's MIIT governs semiconductor self-sufficiency targets through the 14th Five-Year Plan, conditioning subsidy access on domestic wafer sourcing percentages. Japan's METI and South Korea's MFDS coordinate export control alignments on advanced substrate equipment, shaping where capacity expansion proceeds. India's PLI scheme for specialty steel and electronics manufacturing extends incentive logic toward compound semiconductor materials. Stakeholders must monitor which jurisdictions secure qualified 8-inch epitaxy toolsets first, as this determines captive wafer output versus merchant supply dependence.
Market Dynamics
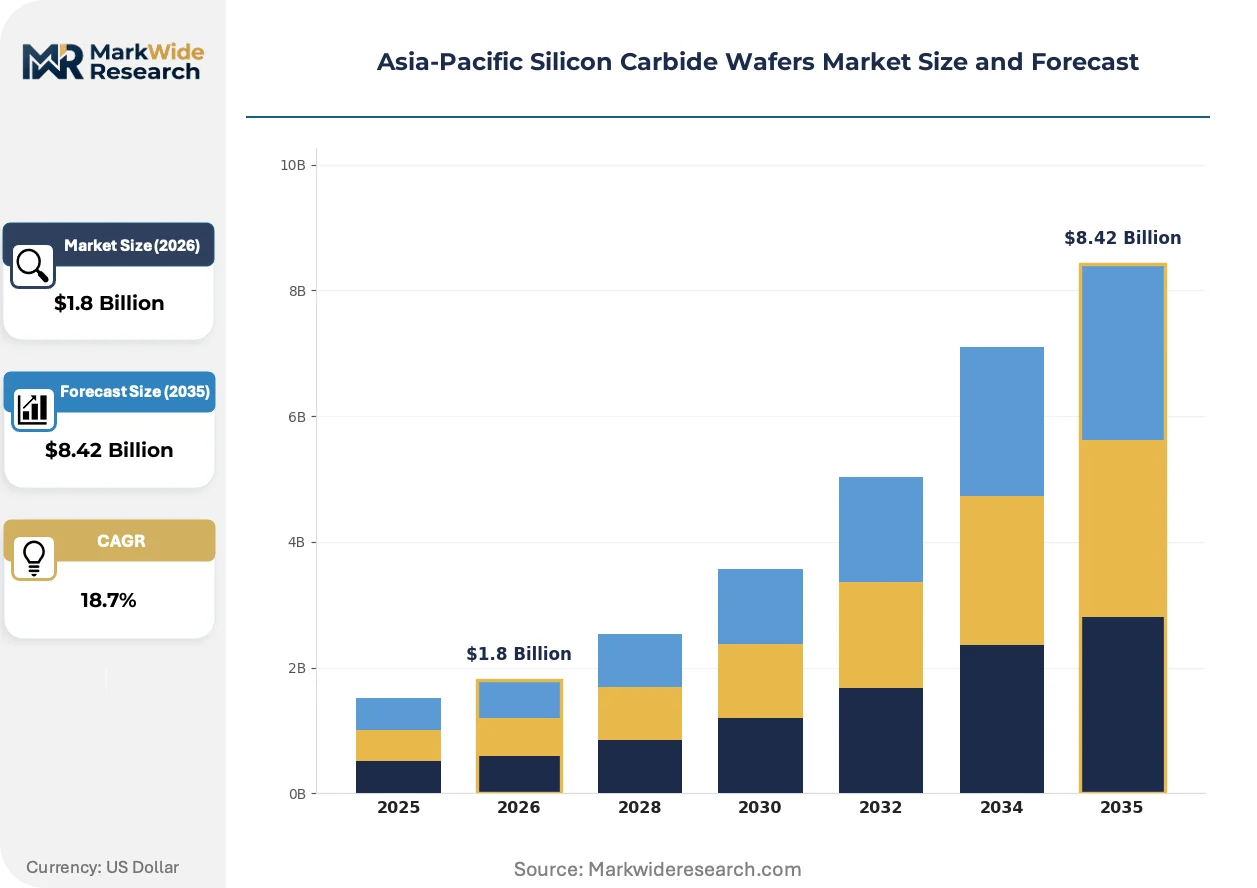
China's dual carbon goals and Japan's METI semiconductor subsidies are redirecting capital toward domestic ingot growth, tightening supply chains across the Asia-Pacific region. This structural reconfiguration is accelerating procurement of larger-diameter substrates as electric vehicle powertrains displace silicon insulated-gate bipolar transistors.
Growth Catalysts
- China's dual carbon goals:Binding emissions targets under the 14th Five-Year Plan mandate automotive electrification, concentrating wafer demand in Fujian and Shandong provinces where crystal pulling capacity scales fastest.
- Electric vehicle traction inverters:OEMs redesign thermal management around SiC switching losses, absorbing wafers from multiple product categories as powertrain architectures abandon silicon.
- MIIT semiconductor self-sufficiency targets:Subsidy access conditions on domestic wafer sourcing percentages force automotive tier ones to secure captive supply agreements with regional growers.
Market Restraints
- High-purity SiC powder supply concentration:Backward integration into powder synthesis remains limited to a handful of producers, exposing merchant wafer fabricators to feedstock bottlenecks.
- 8-inch epitaxy toolset scarcity:Qualified equipment for larger-diameter substrate processing concentrates among Japanese and European vendors, constraining capacity expansion timelines.
- Silicon superjunction MOSFET cost advantage:Mature silicon devices retain price-performance competitiveness in sub-600V applications, delaying SiC penetration in cost-sensitive inverter designs.
Strategic Opportunities
- India's PLI scheme extension:Incentive logic for specialty steel and electronics manufacturing is migrating toward compound semiconductor materials, opening fabrication greenfield opportunities.
- Renewable inverter deployment:Utility-scale solar and wind installations across Southeast Asia are adopting SiC power modules for efficiency gains in high-temperature environments.
- 8-inch wafer qualification acceleration:Die-per-wafer economics are driving power MOSFET manufacturers to validate larger formats, creating first-mover advantages for qualified substrate suppliers.
Industry Challenges
- Crystal growth technician scarcity:Physical vapor transport operation at temperatures exceeding 2,200 degrees Celsius demands specialized expertise that outpaces regional vocational training output.
- Export control alignment friction:Japan's METI and South Korea's MFDS coordinate restrictions on advanced substrate equipment, complicating cross-border capacity expansion planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Silicon Carbide Wafers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 4-Inch, 6-Inch, 8-Inch, 12-Inch End User: Power Electronics, RF Devices, LEDs, Photovoltaics Application: Electric Vehicles, Renewable Energy, Consumer Electronics, Industrial Automation Technology: Heterojunction, Power MOSFET, Diodes, Schottky Barrier |
| Companies Covered | TankeBlue Semiconductor Co., Ltd., SICC Co., Ltd., Xiamen Powerway Advanced Material Co., Ltd., Sumitomo Electric Industries, Ltd., Hebei Synlight Crystal Co., Ltd., SK Siltron Co., Ltd., Showa Denko K.K., CETC, Synlight, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Silicon Carbide Wafers Market Strategic Shifts
Silicon carbide metal-oxide-semiconductor field-effect transistors are virtualizing power module architectures, compressing thermal management systems and enabling higher switching frequencies across electric vehicle and renewable applications.
Virtualizing substrate inspection through machine-vision defect classification is virtualizing quality assurance workflows. Wafer manufacturers deploy automated optical systems to map micropipe density and stacking fault distributions at throughput rates manual inspection cannot match. This compression of characterization timelines is virtualizing the feedback loop between crystal growth and epitaxy qualification, shortening development cycles for 8-inch formats.
METI export controls on advanced SiC substrate manufacturing equipment are reshaping where capacity expansion proceeds. Japanese regulators coordinate with South Korean counterparts to restrict toolset transfers, forcing regional producers to develop indigenous equipment capabilities. Chinese wafer growers respond by accelerating domestic tool qualification programs, redirecting capital toward captive equipment supply chains.
Automotive tier ones are consolidating supplier relationships around vertically integrated substrate-to-device manufacturers. Long-term offtake agreements now specify diameter mix, epitaxy thickness, and defect density thresholds rather than commoditized wafer procurement. This concentration is most visible in China's Yangtze River Delta, where power module assemblers co-locate with qualified substrate sources to compress logistics exposure.
Asia-Pacific Silicon Carbide Wafers Market Segmentation
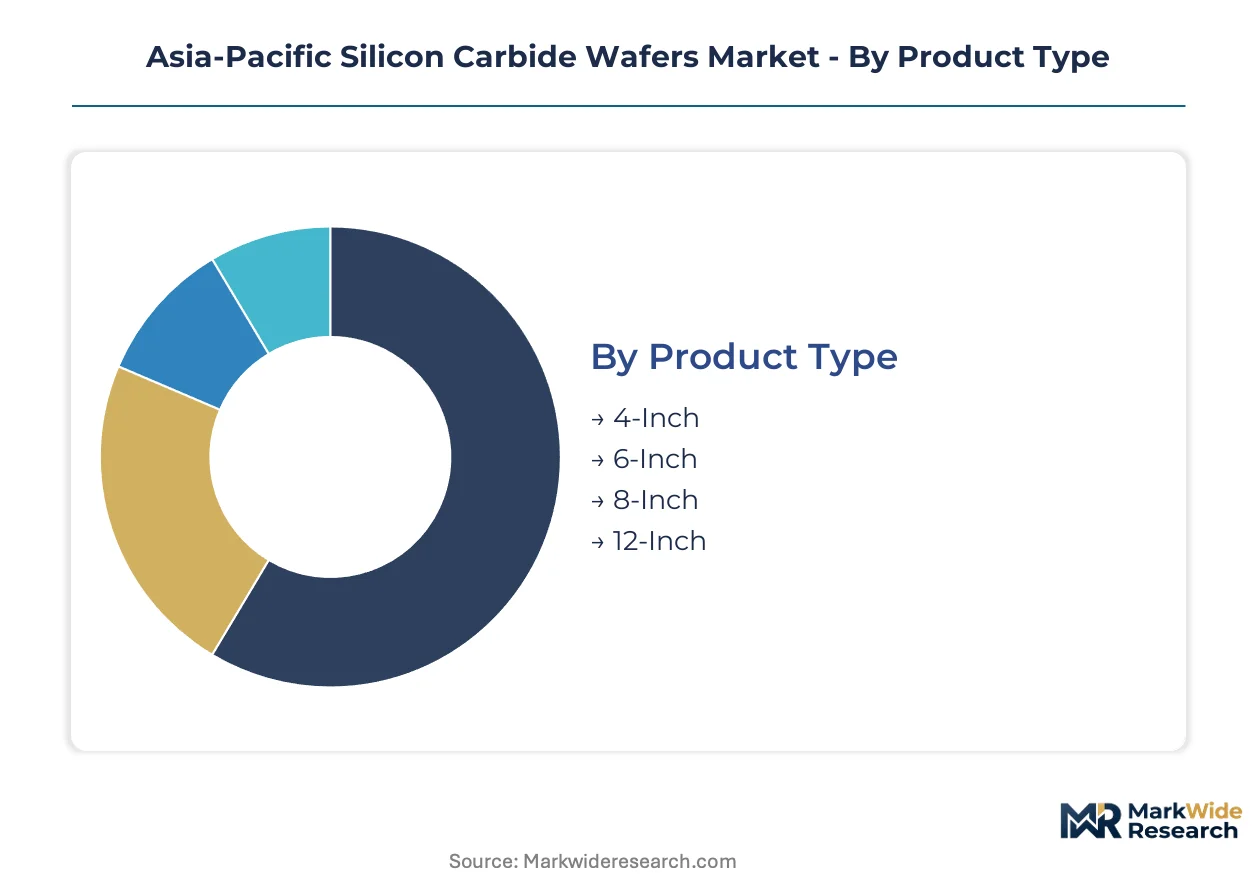
Diameter format selection determines fab tool compatibility and die economics across Asia-Pacific wafer procurement. Application-driven specifications vary sharply between automotive traction inverters and RF base station modules.
Product Type:
Diameter scale defines capital intensity, crystal defect tolerance, and equipment lock-in across the region's growth corridors.
- 4-Inch:Legacy format sustaining RF device and LED foundry operations in Japan and South Korea. Cost-sensitive power discrete manufacturers in Southeast Asia continue procurement for mature process nodes.
- 6-Inch:Monocrystalline substrates at this diameter balance established epitaxy tool compatibility with die-per-wafer economics. China's Fujian and Shandong provinces concentrate crystal pulling capacity for this format as domestic EV powertrain demand accelerates.
- 8-Inch:Larger-diameter wafers reduce edge exclusion losses and enable power MOSFET manufacturers to extract more dies per substrate. Qualification timelines compress as Japanese and Korean equipment vendors qualify epitaxy toolsets for automotive tier one specifications.
- 12-Inch:Experimental diameter facing thermal gradient control challenges during physical vapor transport growth. No qualified epitaxy or device fabrication infrastructure exists in the Asia-Pacific region.
6-Inch commands the established base. The steepest expansion runs through 8-Inch.
End User:
Device category determines substrate crystallinity requirements, surface preparation protocols, and defect density thresholds.
- Power Electronics:Traction inverters, onboard chargers, and DC-DC converters absorb the majority of 6-inch and 8-inch supply. China's MIIT sourcing mandates concentrate procurement around domestic wafer growers.
- RF Devices:High-frequency applications demand micropipe densities below one per square centimeter. Base station deployments across Japan and South Korea sustain demand for semi-insulating substrates.
- LEDs:Solid-state lighting applications tolerate higher defect densities than power devices. Cost pressure from gallium nitride-on-silicon alternatives constrains substrate specifications.
- Photovoltaics:Concentrated solar power systems utilize SiC substrates for thermal management components. Niche demand concentrates in Australia's utility-scale installations.
Power Electronics anchors volume procurement. RF Devices maintains premium pricing power.
Application:
Use-case thermal profiles and switching frequency requirements translate directly into substrate diameter and quality grade selection.
- Electric Vehicles:Traction inverter redesigns around SiC switching losses absorb wafers across multiple diameter categories. China's Yangtze River Delta hosts co-located substrate and power module assembly operations.
- Renewable Energy:Utility-scale solar and wind inverters adopt SiC modules for efficiency gains in high-temperature environments. Southeast Asian installations drive demand for industrial-grade substrates.
- Consumer Electronics:Fast-charging adapters and premium power supplies utilize Schottky diodes on smaller-diameter wafers. Cost constraints limit penetration against silicon superjunction MOSFETs.
- Industrial Automation:Motor drives and welding equipment require ruggedized power modules. Japanese and Korean automation OEMs specify extended temperature range substrates.
Electric Vehicles generates the dominant demand pull. Renewable Energy posts the most rapid climb.
Technology:
Device architecture determines epitaxy thickness, doping profiles, and termination structure complexity.
- Heterojunction:GaN-on-SiC configurations for RF power amplifiers demand ultra-low defect density substrates. Defense and telecommunications applications in Japan and South Korea sustain this segment.
- Power MOSFET:Vertical trench structures dominate EV traction inverter designs. 8-inch qualification accelerates among manufacturers seeking die-per-wafer advantages over planar geometries.
- Diodes:PiN structures serve high-voltage rectification in renewable inverters. Mature process technology sustains 4-inch and 6-inch procurement.
- Schottky Barrier:Low forward voltage drops suit consumer power supply applications. Cost pressure from silicon carbide JBS diodes constrains growth.
Power MOSFET captures investment concentration. Heterojunction preserves margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive power module assemblers and renewable inverter manufacturers dominate procurement across the Asia-Pacific region. Crystal pulling capacity concentrates in coastal industrial zones where MIIT subsidy conditions and METI equipment controls intersect. Domestic sourcing mandates from Beijing to Tokyo are reshaping where qualified substrate supply originates.
China
Electric vehicle traction inverter demand from BYD, NIO, and Xpeng absorbs the majority of 6-inch and 8-inch wafer output. MIIT's 14th Five-Year Plan conditions subsidy access on domestic wafer sourcing percentages above 70 percent. Fujian and Shandong provinces host the fastest-scaling crystal pulling corridors, with Xiamen and Jinan emerging as co-location hubs for substrate growth and power module assembly.
Japan
Sumitomo Electric and Showa Denko anchor RF device and automotive diode demand through heterojunction and Schottky barrier specifications. METI semiconductor subsidies redirect capital toward domestic ingot growth while coordinating export controls on advanced epitaxy toolsets with South Korean counterparts. Kyushu and Kansai industrial zones concentrate qualified substrate processing for defense and telecommunications applications.
South Korea
SK Siltron and Samsung SDI drive procurement for Hyundai-Kia electric vehicle platforms and industrial motor drive modules. MFDS alignment with Japanese METI restrictions on substrate equipment transfers complicates cross-border expansion planning. Busan-Ulsan and Seoul Capital Area clusters integrate backward into high-purity SiC powder synthesis to reduce feedstock exposure.
India
Utility-scale solar inverter deployments across Rajasthan and Gujarat generate emerging demand for industrial-grade substrates. PLI scheme extensions for specialty steel and electronics manufacturing are migrating toward compound semiconductor materials. Tamil Nadu and Karnataka fabrication greenfields attract preliminary investment interest from power discrete manufacturers seeking cost-sensitive sourcing alternatives.
Vietnam
Consumer electronics fast-charging adapter assembly for Samsung and Apple supply chains sustains modest 4-inch and 6-inch procurement. Cost pressure from silicon superjunction MOSFETs limits SiC penetration in sub-600V applications. Ho Chi Minh City and Bac Ninh industrial zones concentrate contract manufacturing without indigenous crystal growth capacity.
Asia-Pacific Silicon Carbide Wafers Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure consolidating around vertically integrated substrate-to-device manufacturers. Long-term offtake agreements now specify diameter mix, epitaxy thickness, and defect density thresholds rather than commoditized wafer procurement. Three archetypes dominate: captive automotive suppliers, merchant wafer growers with backward powder integration, and RF-focused heterojunction specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves as producers secure qualified 8-inch epitaxy toolsets.
Among China-based crystal growth specialists, TankeBlue Semiconductor Co., Ltd. and SICC Co., Ltd. exemplify the captive-supplier archetype serving domestic automotive tier ones under MIIT sourcing mandates. SK Siltron Co., Ltd. represents the backward-integrated model with in-house high-purity powder synthesis. Sumitomo Electric Industries, Ltd. anchors the RF-heterojunction premium tier alongside Showa Denko K.K., with both Japanese entities occupying positions shaped by METI equipment control coordination.
| Leading Market Players |
|---|
| TankeBlue Semiconductor Co., Ltd. |
| SICC Co., Ltd. |
| Xiamen Powerway Advanced Material Co., Ltd. |
| Sumitomo Electric Industries, Ltd. |
| Hebei Synlight Crystal Co., Ltd. |
| SK Siltron Co., Ltd. |
| Showa Denko K.K. |
| CETC |
| Synlight |
| Others |
Value Chain & Pricing Dynamics
High-purity SiC powder synthesis concentration in South Korea and Japan anchors margin capture at the feedstock tier, forcing merchant wafer fabricators into long-term offtake negotiations with backward-integrated suppliers. This upstream tightness transmits directly to substrate pricing power, particularly for 8-inch formats where epitaxy-ready surface preparation commands premium positioning.
Pricing Analysis
Cost-plus contracts indexed to high-purity SiC powder spot markets dominate procurement between ingot growers and automotive tier ones. Three-tier pricing structure across prime-grade, industrial-grade, and test-grade wafers separates qualification-track substrates from commodity LED feedstock. Pricing pressure stems from silicon superjunction MOSFET cost advantages in sub-600V inverter designs. Cost-sensitive power discrete manufacturers in Southeast Asia exhibit highest price sensitivity, while RF defense contractors in Japan tolerate substantial premiums for micropipe density guarantees below one per square centimeter.
Supply Chain Analysis
Contract manufacturing concentration rests with X-FAB, GlobalFoundries, and VIS for SiC device foundry services, while substrate growth remains captive to TankeBlue, SICC, and SK Siltron. Geographic supply concentration centers on China's Fujian and Shandong provinces, South Korea's Busan-Ulsan corridor, and Japan's Kyushu industrial zone. Raw material dependencies draw from petroleum coke precursors, high-purity silicon metal, and graphite crucible consumables. Single-source vulnerability concentrates around Japanese and European vendors for qualified 8-inch epitaxy toolsets. Distribution runs through direct long-term agreements rather than merchant spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific silicon carbide wafer demand is recovering through electric vehicle platform refresh cycles, with OEM thermal management redesigns absorbing capacity across multiple diameter formats.
For Market Incumbents: Build process IP moats around 8-inch crystal growth defect control. Secure captive high-purity powder synthesis through joint ventures with South Korean suppliers to reduce feedstock exposure. Accelerate qualification timelines for automotive tier one specifications before indigenous Chinese toolsets mature. For New Entrants and Emerging Players: Establish a beachhead in India's utility-scale solar inverter substrate supply, where PLI scheme extensions create fabrication greenfield openings. Target industrial-grade 6-inch procurement for renewable energy applications in Southeast Asia. Pursue co-location partnerships with power module assemblers in China's Yangtze River Delta to compress logistics costs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across 8-inch epitaxy tool qualification programs. Long-term viability favors vertically integrated substrate-to-device manufacturers with backward powder control over merchant wafer growers exposed to feedstock bottlenecks. Monitor METI-MFDS export control alignment friction as inflection signal for cross-border capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Powder Synthesis | SK Siltron's captive feedstock production reduces exposure to merchant SiC powder supply concentration. |
| 8-Inch Epitaxy Toolset Qualification | Japanese and Korean equipment vendors race to meet automotive tier one surface preparation specifications. |
| Long-Term Offtake Agreement Restructuring | Contracts now specify diameter mix, epitaxy thickness, and defect density thresholds rather than commoditized wafer volumes. |
| Co-Location with Power Module Assemblers | TankeBlue and SICC anchor supply security for BYD and NIO through Yangtze River Delta proximity. |
| Indigenous Equipment Supply Chain Development | Chinese wafer growers accelerate domestic tool qualification programs in response to METI export controls. |
Study Parameters
The analysis maps 4-inch through 8-inch diameter formats, power electronics and RF device end-use categories, and physical vapor transport growth technologies, each validated through crystal growth technicians, automotive tier one procurement directors, and epitaxy equipment vendors. Primary interviews with substrate quality engineers, power module thermal management specialists, and MIIT policy researchers combined with secondary validation from SEC filings of listed wafer manufacturers, customs trade data for SiC powder imports, and METI subsidy disbursement records. Bottom-up capacity buildout estimates from Fujian and Shandong provinces triangulate against top-down EV traction inverter demand projections.
Assumptions around MIIT domestic sourcing percentage enforcement and METI-MFDS export control continuity were held fixed, while electric vehicle penetration rates and renewable inverter deployment timelines were stress-tested across scenarios. Segmentation dimensions modeled include diameter format, end-use device category, application thermal profile, and crystal growth technology. CAGRs were derived from installed base evolution and replacement demand curves. Forecast inputs incorporate silicon carbide MOSFET die-per-wafer economics and silicon superjunction MOSFET price-performance competitiveness thresholds.
Sensitivities concentrate around 8-inch epitaxy toolset qualification delays and indigenous Chinese equipment supply chain maturation. Forecasts reflect documented assumptions regarding subsidy policy continuity and automotive platform redesign timelines. Cross-checking against power module assembler inventory disclosures and EV OEM thermal management specification releases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Printed Circuit Board (PCB) Laminate Market
Semiconductor Devices
Silicon-Based Anode Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Asia-Pacific Power Transistor Market
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
China Semiconductor Diode Market
Semiconductor Devices
5G Modems Market
Semiconductor Devices
Japan Semiconductor Device in Consumer Industry Market
Semiconductor Devices
India MLCC Market
Semiconductor Devices
Thick Film Devices Market
Semiconductor Devices
North America Silicon Carbide Wafers Market
Semiconductor Devices
Japan Semiconductor Device Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market