
 Middle East and Africa Silicon Carbide Wafers Market | 2026-2036
Middle East and Africa Silicon Carbide Wafers Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Silicon Carbide Wafers Market Foresight
Electric vehicle manufacturing is consolidating as the dominant demand vector for silicon carbide wafers across the Middle East and Africa. Wolfspeed, Inc. leverages its vertically integrated substrate production to anchor supply relationships with regional automotive assemblers. STMicroelectronics competes through its broad power electronics portfolio, while Infineon Technologies AG sustains technology leadership in high-voltage automotive modules.
Silicon carbide wafers are monocrystalline substrates produced through physical vapor transport or chemical vapor deposition, typically measuring 150 mm or 200 mm in diameter, with polytype 4H-SiC dominating power device applications due to its superior electron mobility and thermal conductivity. These wafers serve as the foundational material for high-efficiency power switching, radio frequency amplification, and photonic devices operating at elevated temperatures. Epitaxial wafers command premium positioning due to the added epi-layer processing required for device-grade material, while bulk wafers represent the volume base feeding downstream epi-house operations. Power electronics applications lead absolute consumption, though RF devices for telecommunications infrastructure represent the fastest-growing application segment as Gulf states deploy advanced networks.
South Africa's National Regulator for Compulsory Specifications and the UAE's Emirates Authority for Standardization and Metrology shape product entry requirements for semiconductor materials, while CE marking alignment remains essential for wafers destined for European-integrated supply chains. Saudi Arabia's Saudi Standards, Metrology and Quality Organization is developing localized technical regulations to support domestic advanced manufacturing ambitions. Stakeholders must monitor how national industrial localization mandates reshape procurement criteria and certification pathways across the region.
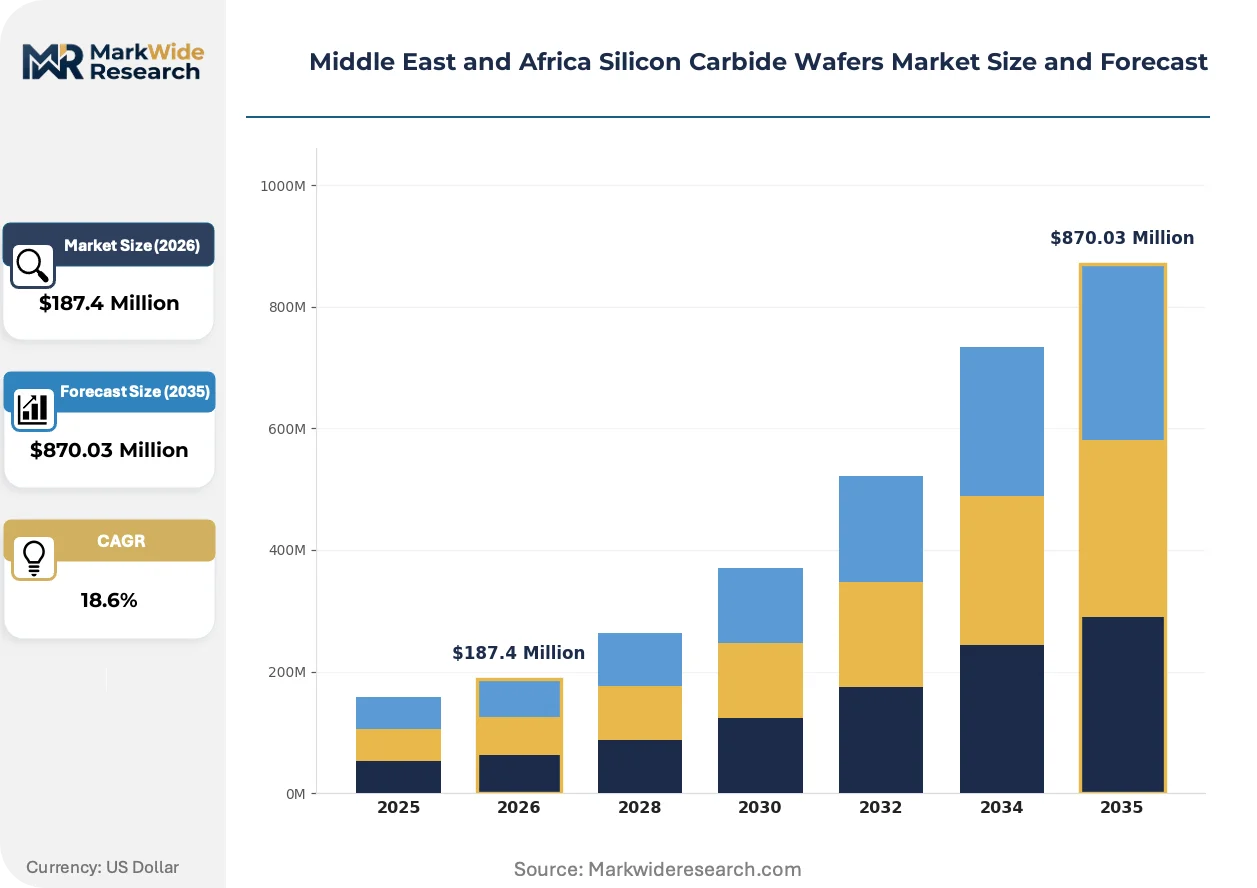
Market Dynamics
Electric vehicle powertrain electrification is compressing technology adoption cycles across the Middle East and Africa, forcing rapid localization decisions for silicon carbide substrate sourcing.
Growth Catalysts
- UAE Industrial Diversification Policies:Abu Dhabi's advanced manufacturing incentives are pulling semiconductor-adjacent ecosystems into Khalifa Industrial Zone, creating captive demand for 150 mm and 200 mm wafers.
- South Africa Renewable Procurement Mandates:The National Regulator for Compulsory Specifications is embedding SiC inverter requirements into utility-scale solar and wind tenders, expanding power electronics consumption beyond automotive.
- Saudi Domestic Manufacturing Ambitions:Saudi Standards, Metrology and Quality Organization technical regulations are mandating local content verification for advanced materials used in NEOM and Red Sea Project infrastructure.
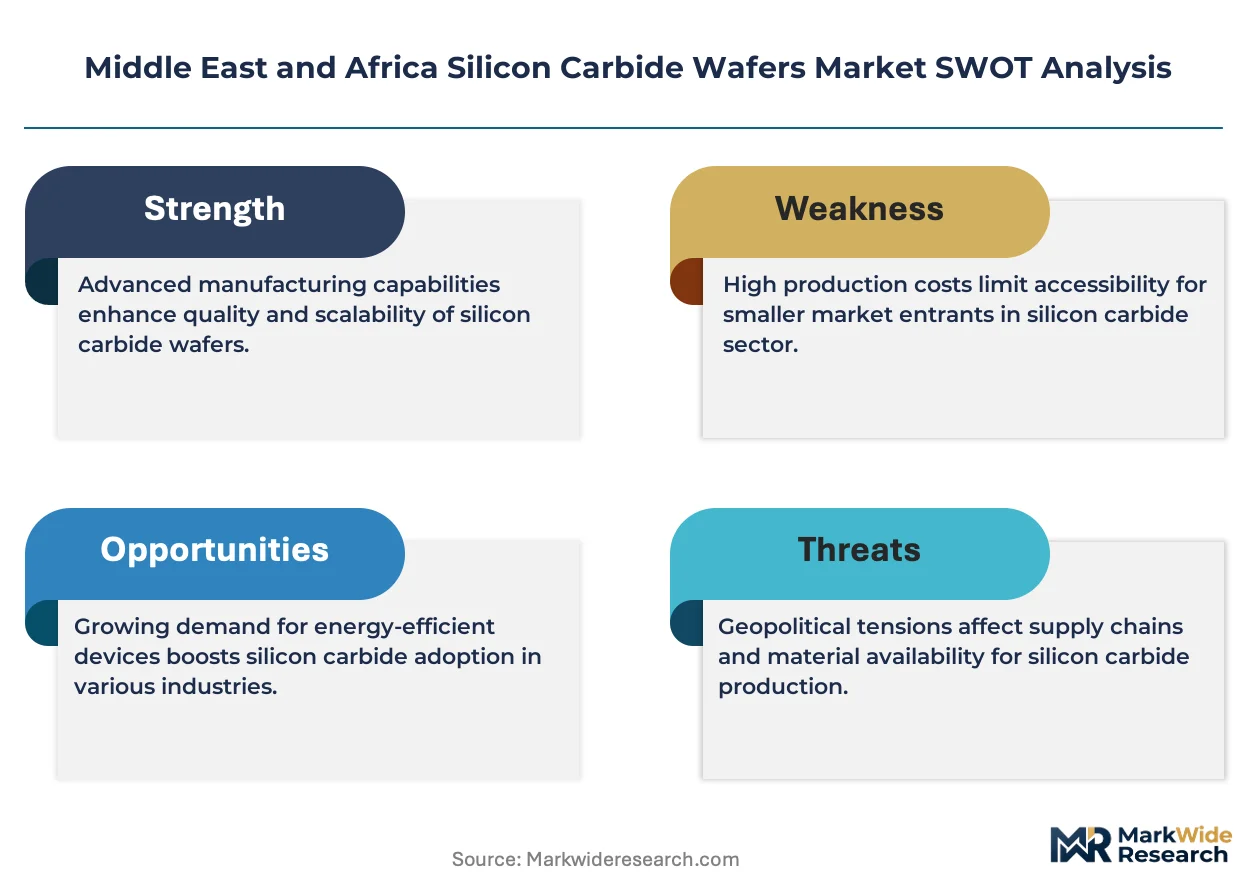
Market Restraints
- Substrate Supply Concentration:Physical vapor transport growth capacity remains concentrated among established North American and East Asian suppliers, exposing regional assemblers to allocation risk during demand surges.
- High-Purity Silicon and Graphite Input Volatility:Crucible-grade graphite and electronic-grade silicon feedstock pricing fluctuates with energy costs, compressing epi-house margins in Dubai and Johannesburg.
- 4H-SiC Defect Density Limitations:Micropipe and dislocation densities in bulk crystals above 150 mm diameter constrain device yield for 1200V automotive modules, slowing qualification timelines.
Strategic Opportunities
- Egyptian Automotive Assembly Expansion:Underpenetrated SiC inverter penetration in Cairo-based EV joint ventures offers first-mover positioning as local content rules tighten.
- Telecommunications RF Amplification:Gulf state 5G-Advanced and Open RAN deployments are accelerating gallium nitride-on-SiC demand for base station power amplifiers.
- Epitaxial Service Localization:Dubai Multi Commodities Centre free zone regulations are enabling third-party epi-layer processing hubs to serve African mining and Middle Eastern oilfield power conversion needs.
Industry Challenges
- Crystal Growth Technician Scarcity:Physical vapor transport furnace operation and defect characterization expertise remains concentrated outside the region, constraining indigenous 4H-SiC production scaling.
- Multi-Regulatory Certification Burden:Simultaneous compliance with UAE Emirates Authority for Standardization and Metrology, South African National Regulator for Compulsory Specifications, and CE alignment for European-integrated supply chains extends product entry timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Silicon Carbide Wafers Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Wafers, Epitaxial Wafers, Doped Wafers, Polished Wafers Application: Power Electronics, RF Devices, LED Lighting, Electric Vehicles End User: Aerospace, Automotive, Telecommunications, Consumer Electronics Distribution Channel: Direct Sales, Online Sales, Distributors, Value-Added Resellers |
| Companies Covered | Wolfspeed, Inc., STMicroelectronics, Infineon Technologies AG, ROHM Co., Ltd., SK Siltron Co., Ltd., II-VI Incorporated, Showa Denko K.K., SiCrystal, Toshiba Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Silicon Carbide Wafers Market Shifts & Advancements
Wafer processing workflows and supply chain architectures are restructuring around regional automotive electrification timelines and telecommunications infrastructure buildouts.
High-temperature chemical vapor deposition for thick epitaxial layers is decentralizing device manufacturing footprints. Regional automotive assemblers in Saudi Arabia and the UAE are adopting 150 mm epi-ready wafers at compressed qualification cycles. This technology is decentralizing the traditional concentration of power module fabrication in East Asian foundries.
Saudi Standards, Metrology and Quality Organization is developing localized technical regulations for advanced semiconductor materials to support domestic manufacturing ambitions. These draft standards are creating parallel certification pathways that diverge from legacy European-integrated frameworks. Power electronics suppliers serving NEOM infrastructure projects are most affected, adapting quality systems to dual-track compliance.
Buyer concentration among Gulf state sovereign wealth-backed automotive ventures is compressing supplier negotiation cycles. Tier-1 power module houses are displacing traditional distribution channels with direct mill relationships for bulk wafer allocation. This pattern is most visible in Abu Dhabi and Riyadh, where EV platform consolidation is reducing vendor fragmentation.
Middle East and Africa Silicon Carbide Wafers Market Segmentation
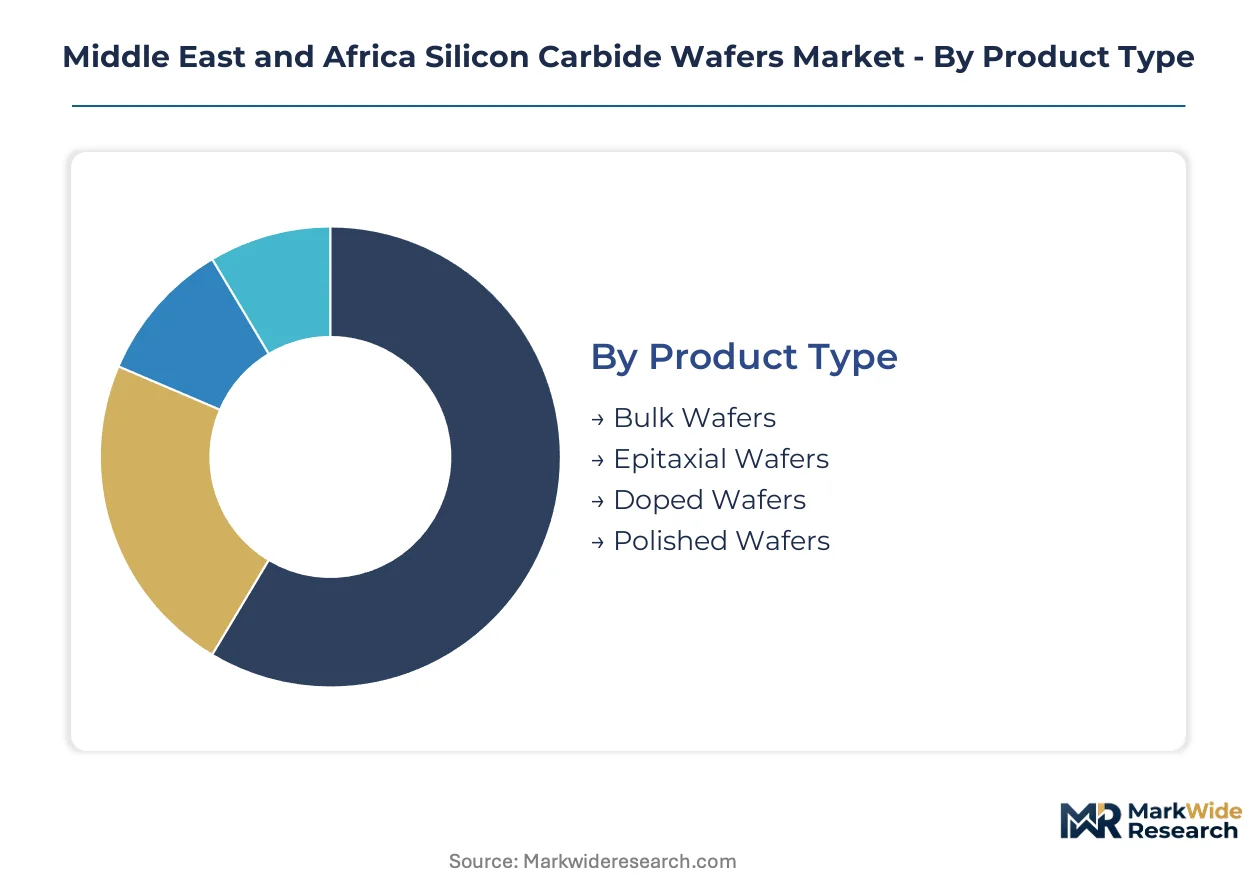
Segmentation reveals how capital requirements and technical specifications fragment demand across the Middle East and Africa. Wafer grade, application voltage, and end-use certification standards determine supplier selection and pricing tiers in this emerging procurement landscape.
Product Type:
Capital intensity escalates sharply with added processing layers, separating commodity substrate suppliers from premium epi-ready providers.
- Epitaxial Wafers:Device-grade substrates carry chemically deposited silicon carbide layers that meet precise thickness and doping specifications for power module fabrication. Demand concentrates in Abu Dhabi and Riyadh automotive ventures where 150 mm epi-ready specifications are compressing qualification timelines for EV inverters.
- Bulk Wafers:Unprocessed monocrystalline substrates serve as feedstock for third-party epi-houses and captive processing operations. South African solar inverter manufacturers and Dubai-based power conversion specialists source these for in-house epitaxial deposition to manage input cost volatility.
- Doped Wafers:Nitrogen or aluminum-doped substrates provide controlled carrier concentration for specific device architectures.
- Polished Wafers:Surface-finished substrates offer intermediate processing for applications tolerating slightly higher defect densities.
Most installed capacity flows through Bulk Wafers. Expansion is steepest in Epitaxial Wafers.
Application:
Operating voltage and thermal load requirements segment the market into distinct procurement channels with divergent qualification protocols.
- Power Electronics:High-efficiency switching devices for inverters and converters dominate absolute wafer consumption across the region. Saudi NEOM infrastructure projects and South African utility-scale renewable tenders are embedding silicon carbide requirements into procurement specifications.
- RF Devices:Gallium nitride-on-silicon carbide amplifiers for telecommunications infrastructure represent the segment gaining share fastest. UAE and Saudi 5G-Advanced deployments are accelerating base station power amplifier demand.
- Electric Vehicles:Traction inverter and onboard charger applications are consolidating as the primary demand vector for 150 mm and 200 mm wafers.
- LED Lighting:Solid-state lighting substrates constitute a mature, price-sensitive consumption channel with limited growth upside.
Power Electronics commands the largest share of regional procurement. RF Devices exhibits the steepest expansion trajectory.
End User:
Customer certification requirements and volume scale separate aerospace-grade specifications from high-volume automotive procurement.
- Automotive:EV powertrain electrification is compressing technology adoption cycles and forcing rapid localization decisions for substrate sourcing across Gulf state assembly operations.
- Aerospace:Radiation-hardened and high-temperature specifications for satellite and defense applications command premium positioning with extended qualification timelines.
- Telecommunications:Base station infrastructure buildouts in the UAE and Saudi Arabia are driving gallium nitride-on-silicon carbide consumption for RF amplification.
- Consumer Electronics:Power adapter and fast-charging applications represent a volume-driven, price-sensitive procurement segment.
Automotive absorbs the majority of regional wafer shipments. Telecommunications is climbing the fastest.
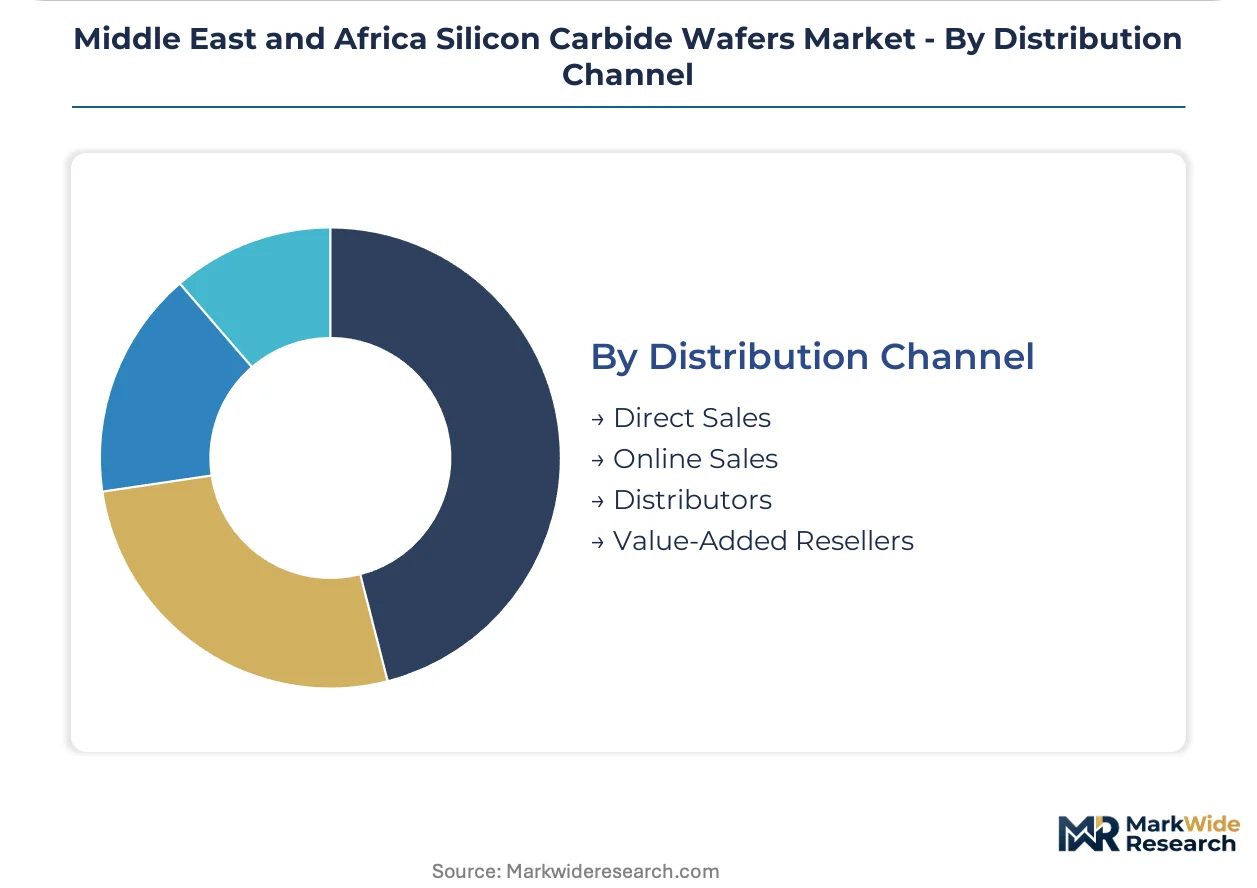
Distribution Channel:
Buyer concentration among sovereign wealth-backed ventures is restructuring traditional supply chain architectures toward direct procurement relationships.
- Direct Sales:Tier-1 power module houses are establishing direct mill relationships for bulk wafer allocation, displacing traditional distribution channels in Abu Dhabi and Riyadh.
- Distributors:Regional inventory stocking and technical support services remain essential for smaller epi-houses and research institutions in Johannesburg and Cairo.
- Value-Added Resellers:Technical specification assistance and local content verification support are valued by suppliers serving Saudi Standards, Metrology and Quality Organization compliance requirements.
- Online Sales:Small-volume procurement and sample ordering for R&D applications flow through digital channels with limited regional penetration.
Direct Sales channels handle the largest volume of regional transactions. Value-Added Resellers are expanding most quickly to support localization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling silicon carbide wafer procurement toward jurisdictions with streamlined certification pathways and sovereign-backed manufacturing incentives. The Middle East and Africa region presents divergent compliance cost structures, with Gulf states offering accelerated permitting against more rigorous South African technical standards.
United Arab Emirates
Abu Dhabi's Khalifa Industrial Zone anchors semiconductor-adjacent ecosystem development through advanced manufacturing incentives. The Emirates Authority for Standardization and Metrology maintains CE-aligned certification frameworks that reduce re-qualification burdens for European-integrated supply chains. Dubai Multi Commodities Centre free zone regulations are enabling third-party epitaxial processing hubs to serve regional power conversion demand.
Saudi Arabia
NEOM infrastructure projects and Red Sea Project developments are embedding silicon carbide requirements into utility-scale renewable tenders. The Saudi Standards, Metrology and Quality Organization is developing localized technical regulations that mandate local content verification for advanced materials. Riyadh-based EV platform consolidation is compressing supplier qualification timelines and reducing vendor fragmentation.
South Africa
Utility-scale solar and wind procurement mandates from the National Regulator for Compulsory Specifications are expanding power electronics consumption beyond automotive applications. The country's renewable energy independent power producer procurement programme embeds SiC inverter requirements into tender specifications. Johannesburg-based epi-houses are sourcing bulk wafers for in-house epitaxial deposition to manage input cost volatility.
Egypt
Cairo-based automotive joint ventures present underpenetrated silicon carbide inverter opportunities as local content rules tighten. The country's industrial development strategy targets component localization for electric vehicle assembly operations. Suez Canal Economic Zone positioning offers logistics advantages for wafer import and regional redistribution.
Middle East and Africa Silicon Carbide Wafers Market Competitive Landscape
Capacity expansion dominates the current landscape as established substrate producers race to capture Gulf state automotive procurement commitments. The vendor base concentrates around North American and East Asian suppliers with physical vapor transport growth capabilities, creating allocation risk exposure for regional assemblers during demand surges. Two strategic archetypes define competitive positioning: vertically integrated substrate-to-device houses and specialized epitaxial service providers. Capacity expansion and strategic partnerships represent the dominant competitive moves, with direct mill relationships displacing traditional distribution channels in Abu Dhabi and Riyadh.
Among North American substrate specialists, Wolfspeed, Inc. exemplifies the vertically integrated archetype through its captive production capabilities. STMicroelectronics occupies a position spanning broad power electronics portfolios, while Infineon Technologies AG anchors technology leadership positioning in high-voltage automotive modules. These three companies represent distinct strategic postures within a procurement landscape increasingly shaped by sovereign wealth-backed buyer concentration.
| Leading Market Players |
|---|
| Wolfspeed, Inc. |
| STMicroelectronics |
| Infineon Technologies AG |
| ROHM Co., Ltd. |
| SK Siltron Co., Ltd. |
| II-VI Incorporated |
| Showa Denko K.K. |
| SiCrystal |
| Toshiba Corporation |
| Others |
Supply & Pricing Matrix
Sovereign wealth-backed automotive ventures in Abu Dhabi and Riyadh are compressing supplier negotiation cycles and reshaping margin structures for silicon carbide substrate producers. Their direct mill relationships displace traditional distribution channels and force pricing discipline through volume concentration and local content verification mandates.
Pricing Analysis
Distributor margins for bulk wafers through Dubai-based inventory stocking operations sit wider than direct-to-OEM channels serving Khalifa Industrial Zone automotive assemblers. Three-tier pricing structure across premium epitaxial wafers, standard bulk substrates, and economy-grade polished wafers reflects certification grade and defect density specifications. Cost compression in the economy tier intensifies as Johannesburg-based epi-houses source unprocessed substrates to manage input volatility. South African solar inverter manufacturers exhibit highest price sensitivity due to renewable procurement margin constraints, while Saudi NEOM infrastructure contractors absorb premium positioning for verified local content.
Supply Chain Analysis
Crucible-grade graphite supply rests on Chinese and Japanese specialty carbon producers, while electronic-grade silicon feedstock draws from German and US chemical purification operations. Physical vapor transport furnace components and high-purity source materials anchor substrate production in North American and East Asian manufacturing clusters. Single-source vulnerability for 200 mm 4H-SiC crystal growth capacity exposes regional assemblers to allocation risk during demand surges. Distribution runs through direct mill relationships with sovereign-backed automotive ventures, supplemented by Dubai Multi Commodities Centre free zone hubs for African redistribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EV powertrain electrification shifts procurement toward device-grade epitaxial specifications with extended qualification timelines and premium positioning.
For Market Incumbents: Deepen captive epitaxial processing capabilities to defend margin position against third-party epi-house competition in Dubai and Johannesburg. Secure long-term offtake agreements with Saudi Standards, Metrology and Quality Organization-compliant suppliers before localized technical regulations harden procurement criteria. Capacity addition in UAE free zones offers geographic hedge against South African regulatory complexity.
For New Entrants and Emerging Players: Value-added resellers serving Saudi local content verification requirements represent the most penetrable channel archetype for qualification support services. Egyptian automotive joint ventures in Cairo offer white-space positioning as SiC inverter penetration remains underdeveloped relative to Gulf state assembly operations. Technical specification assistance bundled with bulk wafer sourcing addresses buyer capability gaps in emerging African markets.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized epitaxial service providers lacking backward integration into substrate production. Long-term viability over the next decade hinges on securing furnace operation expertise and defect characterization capabilities concentrated outside the region. The signal to watch is Saudi domestic manufacturing ambition execution—accelerated NEOM procurement timelines would validate premium positioning for localized supply chain assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Epitaxial Processing Localization | Dubai Multi Commodities Centre regulations enable third-party epi-layer hubs serving African mining power conversion demand. |
| Direct Mill Relationship Establishment | Tier-1 power module houses in Abu Dhabi and Riyadh displace traditional distribution channels for bulk wafer allocation. |
| Local Content Verification Capability | Saudi Standards, Metrology and Quality Organization compliance support creates differentiation for NEOM infrastructure suppliers. |
| High-Voltage Automotive Module Qualification | 1200V device yield improvement addresses micropipe density constraints slowing Saudi EV platform adoption. |
| RF Amplification Technology Partnership | Gulf state 5G-Advanced deployments accelerate gallium nitride-on-SiC demand for base station infrastructure. |
Research Methodology
Bottom-up power electronics demand modeling reconciled against top-down physical vapor transport capacity tracking forms the analytical core of this study. Primary interviews with crystal growth technicians, epi-house operations managers, Tier-1 power module procurement leads, and Saudi industrial development officials combined with secondary validation from SEC 10-K filings, customs and trade data, and Emirates Authority for Standardization and Metrology technical documentation. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Historical trendline analysis of wafer diameter migration from 150 mm toward 200 mm specifications informs the projection framework across the analysis window. Segmentation dimensions modeled include wafer grade tier, application voltage class, end-use certification standard, and regional production cluster. CAGRs derive from fitted growth curves applied to disclosed capacity expansion announcements and automotive platform electrification timelines. Forecast inputs incorporate Saudi NEOM infrastructure procurement schedules and South African renewable energy independent power producer tender specifications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to physical vapor transport furnace operator availability and 4H-SiC defect density breakthroughs. Projections reflect assumptions about sovereign wealth commitment continuity and regulatory localization pace. A small set of triggers—Saudi domestic crystal growth facility announcements, South African utility-scale inverter specification changes, and UAE semiconductor cluster incentive revisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Layer Pads Market
Semiconductor Devices
Analog and Mixed Signal Device Market
Semiconductor Devices
Semiconductor Device in Aerospace and Defense Industry Market
Semiconductor Devices
5G Automotive Grade Product Market
Semiconductor Devices
Europe Power Transistor Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Metal-Semiconductor-Metal Photodetector Market
Semiconductor Devices
Digital Tunable Capacitors Market
Semiconductor Devices
Monocrystalline Half-Chip Module Market
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
Global Transistor Market
Semiconductor Devices
Chip Crusher Market
Semiconductor Devices
China MCU Market
Semiconductor Devices
Polymer Core Solder Ball Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Multi-Junction Solar Cell Market