
 Europe Semiconductor Device Market | 2026-2036
Europe Semiconductor Device Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Semiconductor Device Market Insights
Automotive OEMs are redrawing procurement priorities across the Europe Semiconductor Device Market, shifting volume from consumer electronics toward electrification and autonomous systems. Infineon Technologies AG anchors power semiconductor supply through its verticalized manufacturing footprint in Dresden and Villach. STMicroelectronics N.V. competes across microcontroller and power discrete segments with deep ties to French and Italian automotive tier-ones. NXP Semiconductors N.V. dominates secure connectivity and radar processing for advanced driver-assistance platforms.
A semiconductor device is an electronic component fabricated from semiconductor materials—typically silicon, silicon carbide, or gallium nitride—engineered to control electrical current through doped p-n junctions, metal-oxide-semiconductor field-effect transistor gates, or epitaxial layer structures, serving functions from signal amplification to power switching and logic computation in electronic systems. Integrated circuits command the largest value share within product type segmentation, while power management technology generates outsized margin pools as electrification multiplies voltage-regulation and conversion requirements across automotive and industrial verticals. Mixed-signal processing is expanding fastest in application terms, driven by sensor fusion demands in automotive electronics and IoT devices requiring analog-to-digital interfaces at the edge.
The EU Chips Act, REACH chemical compliance through ECHA, and CE marking under the EU's Radio Equipment Directive collectively shape product standards, material sourcing constraints, and market access conditions for semiconductor devices sold across member states. Germany's KBA and France's ANSM impose functional safety and quality system requirements that filter supplier eligibility for automotive and medical applications. Stakeholders must monitor subsidy disbursement timelines under national Chips Act implementations and assess whether captive wafer capacity or fabless design partnerships better align with customer concentration in automotive electrification.
Market Dynamics
Automotive electrification is compressing procurement timelines across Europe's semiconductor value chain, forcing tier-one suppliers to secure multi-year capacity commitments for silicon carbide power modules and radar processors before vehicle platform locks.
Growth Catalysts
- EU Chips Act capital allocation:National subsidy frameworks in Germany, France, and Italy are accelerating 300mm fab construction and attracting design-center investments from fabless firms seeking proximity to automotive OEMs.
- Silicon carbide substrate qualification:Power semiconductor manufacturers are qualifying 8-inch SiC wafers for traction inverters, reducing switching losses and enabling higher voltage architectures in premium electric drivetrains.
- France-Italy automotive corridor demand:Stellantis and Renault-Nissan procurement teams are consolidating microcontroller and power discrete orders with European IDMs, prioritizing supply security over lowest-unit-cost sourcing.
Market Restraints
- Neon gas supply concentration:Ukraine and Russian feedstock disruptions have exposed European lithography laser dependency, with ASML's EUV systems requiring purified neon from constrained Eastern European refining capacity.
- REACH chemical compliance costs:ECHA substance-of-very-high-concern listings for fluorinated compounds used in etching and cleaning processes are forcing reformulation investments across Dresden and Leuven process lines.
- Third-party IP licensing thickets:RISC-V adoption in automotive MCUs is colliding with ARM architecture dominance, creating royalty stack uncertainty for European fabless designers targeting secure vehicle gateways.
Strategic Opportunities
- Poland-Czech packaging corridor:Underutilized OSAT capacity in Central European industrial zones offers cost-competitive fan-out wafer-level packaging for automotive sensor modules serving German OEMs.
- EU AI Act edge inference mandate:Regulatory requirements for deterministic AI processing in safety-critical automotive systems are creating demand for neuromorphic accelerators and in-memory compute architectures.
- GaN-on-Si power integration:Gallium nitride epitaxy on silicon substrates is converging with established CMOS back-end lines, enabling European foundries to enter consumer fast-charging and data center power supply markets without dedicated III-V fabs.
Industry Challenges
- Automotive functional safety certification backlog:ISO 26262 ASIL-D qualification timelines for mixed-signal SoCs are stretching to 18-24 months, delaying revenue recognition for design wins secured in 2023-2024.
- Legacy 200mm equipment scarcity:Analog and power discrete manufacturers face 12-month lead times for refurbished lithography and implant tools, constraining capacity expansion for industrial and medical grade devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Semiconductor Device Market |
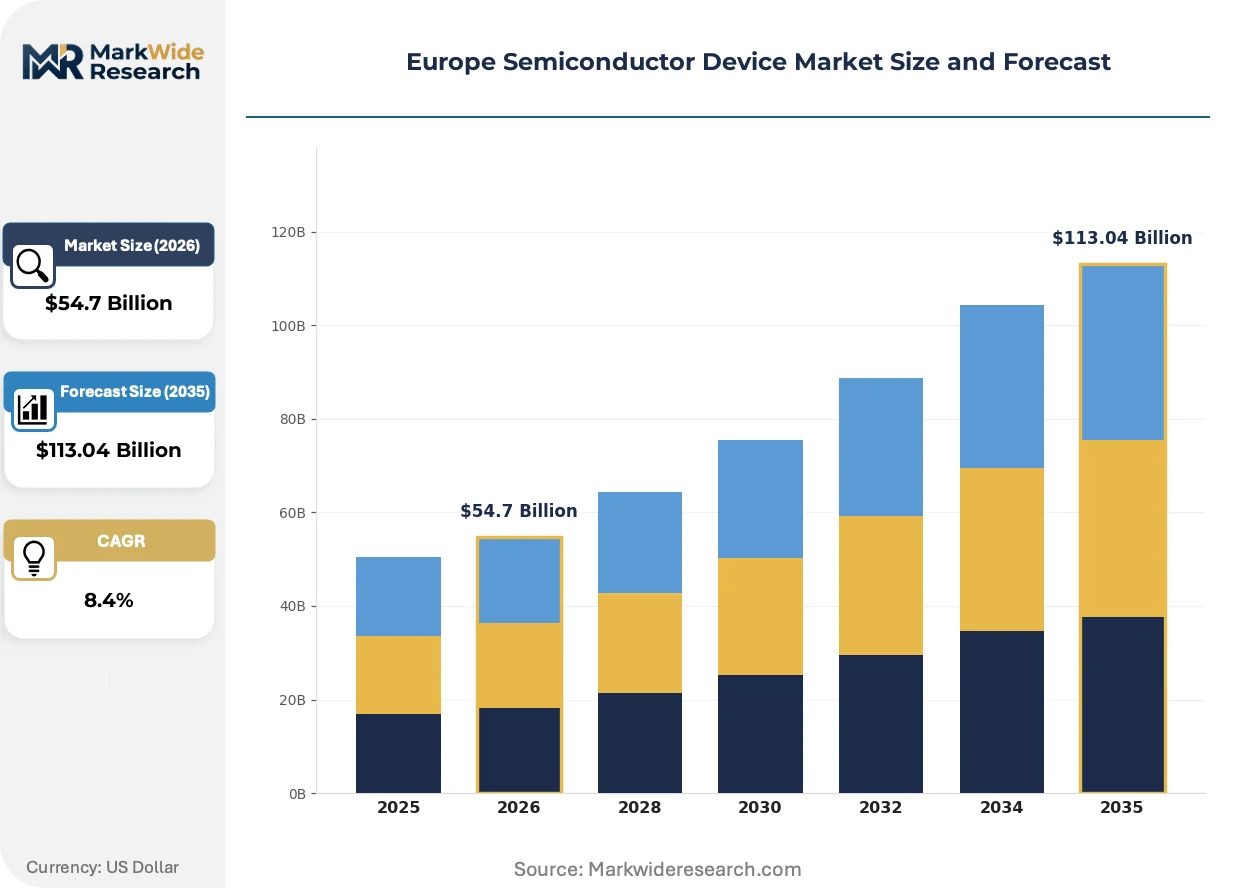
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $113.04 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Diodes, Transistors, Integrated Circuits Industry Vertical: Telecommunications, Automotive, Consumer Electronics, Industrial Automation Technology: Analog, Digital, Mixed-Signal, Power Management Application: Smartphones, Laptops, Automotive Electronics, IoT Devices |
| Companies Covered | Infineon Technologies AG, STMicroelectronics N.V., NXP Semiconductors N.V., ASML Holding N.V., ams OSRAM AG, Robert Bosch GmbH, Analog Devices Inc., onsemi Corporation, Texas Instruments Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Semiconductor Device Market Trends and Innovations
Chiplets and heterogeneous integration are fragmenting traditional monolithic SoC architectures, enabling European automotive semiconductor suppliers to mix process nodes and optimize cost-performance trade-offs across compute, memory, and analog functions.
Gallium nitride power transistors are decomposing the silicon MOSFET dominance in 48V mild-hybrid systems and onboard chargers, with Continental and Bosch power electronics divisions accelerating qualification timelines to secure 2026-2027 vehicle platform slots, compressing incumbent silicon supplier margins in sub-650V applications.
The EU's F-Gas Regulation phase-down is forcing semiconductor manufacturers to abandon sulfur hexafluoride etching chemistries in favor of fluorinated nitrile alternatives, with Infineon's Dresden fab and STMicroelectronics' Crolles line investing in abatement retrofits to maintain CE marking compliance for exported devices.
Long-term supply agreements are displacing spot-market purchasing for automotive-grade wafers and substrates, with German and French OEM procurement teams locking 3-5 year take-or-pay contracts directly with European IDMs, bypassing traditional distribution channels and compressing inventory buffers across the value chain.
Europe Semiconductor Device Market Segmentation
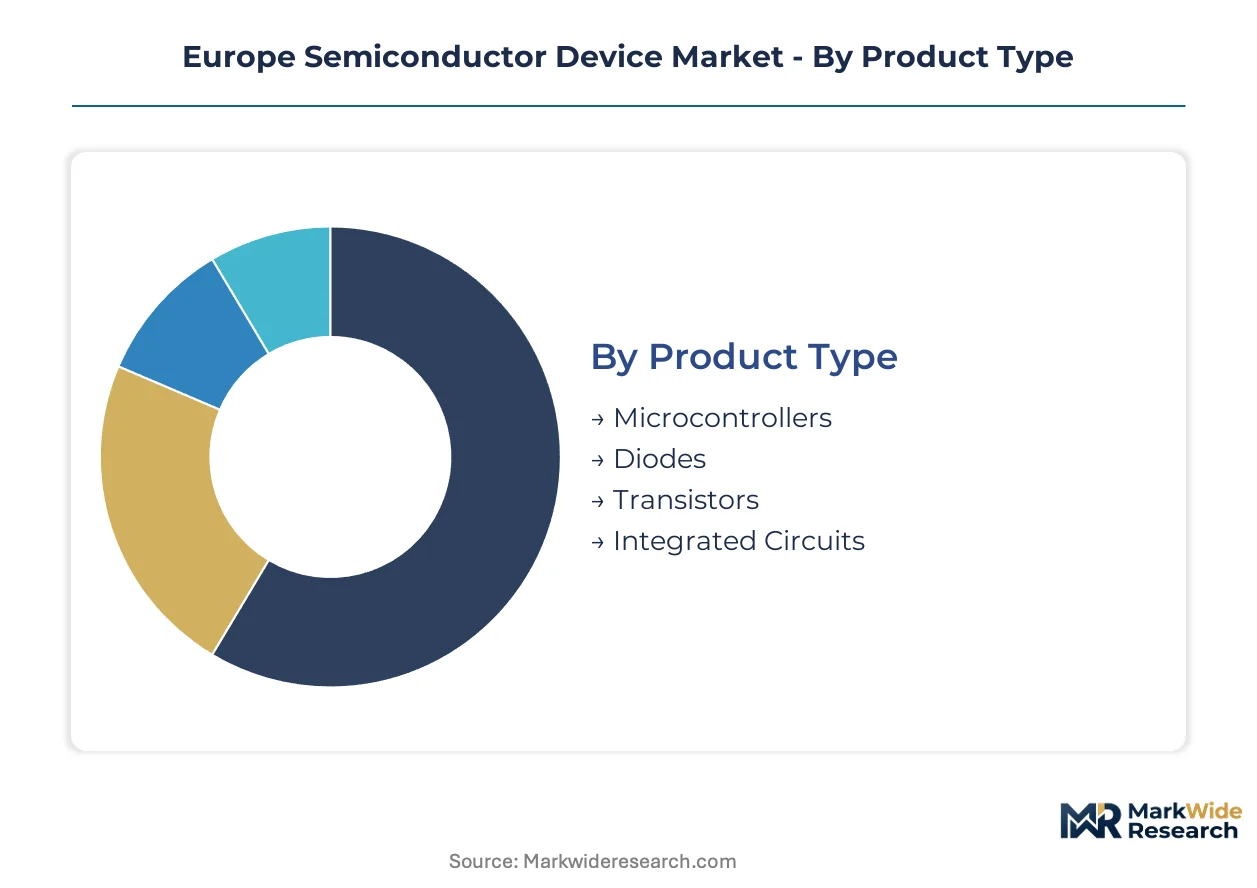
Semiconductor device segmentation across Europe tracks divergent sourcing patterns between captive automotive supply chains and export-driven consumer electronics. Understanding these splits clarifies where margin pools concentrate versus where volume scales.
Product Type:
Domestic demand concentrates in power discretes serving German and French automotive OEMs, while integrated circuits feed broader European electronics manufacturing for re-export.
- Microcontrollers:Embedded compute units integrate CPU cores with memory and peripheral interfaces on monolithic dies. French and Italian automotive tier-ones are consolidating 32-bit MCU procurement for domain controllers, prioritizing ASIL-B functional safety ratings over unit cost.
- Integrated Circuits:Monolithic assemblies of transistors, resistors, and capacitors fabricated on silicon substrates perform complex signal processing and logic functions. Dresden and Crolles fabs are expanding 300mm capacity for mixed-signal ICs serving Stellantis and Renault-Nissan platform requirements.
- Transistors:Three-terminal semiconductor devices amplify or switch electronic signals across bipolar and field-effect architectures.
- Diodes:Two-terminal p-n junction devices enable rectification, voltage regulation, and switching protection in power conversion circuits.
Integrated circuits command the established base. The steepest expansion runs through microcontrollers.
Industry Vertical:
Cost tier differentiation separates safety-certified automotive grades from commercial-industrial specifications, with certification overhead creating 40-60% price premiums.
- Automotive:Electrified drivetrains and ADAS platforms demand AEC-Q100 qualified devices with temperature ratings to 175°C. German KBA type-approval requirements filter supplier pools to IDMs with proven field reliability records.
- Industrial Automation:Programmable logic controllers, motor drives, and robotics systems require extended-temperature operation and galvanic isolation. Bavarian and Baden-Württemberg machine builders are sourcing power modules from Infineon's Villach fab.
- Telecommunications:Baseband processors, RF front-ends, and optical transceivers enable 5G infrastructure and fiber networks.
- Consumer Electronics:Mobile devices, wearables, and home appliances drive high-volume, short-lifecycle semiconductor demand.
Automotive verticals absorb the highest unit values. Industrial automation is climbing the fastest.
Technology:
Application requirements dictate technology selection, with automotive electrification forcing analog-digital boundary migration toward higher integration.
- Power Management:Voltage regulators, DC-DC converters, and battery management ICs condition and distribute electrical energy across system loads. Traction inverters and onboard chargers in premium EV platforms are driving 800V-rated SiC gate driver demand.
- Mixed-Signal:Circuits combining analog and digital processing on common substrates interface sensors with compute cores. Radar sensor fusion for highway autopilot functions requires high-speed ADC-DSP pipelines.
- Analog:Continuous signal processing through operational amplifiers, comparators, and voltage references supports sensor interfaces and power conditioning.
- Digital:Binary logic circuits execute computation, storage, and communication protocols across CMOS process nodes.
Power management holds the revenue base. Mixed-signal is expanding most quickly.
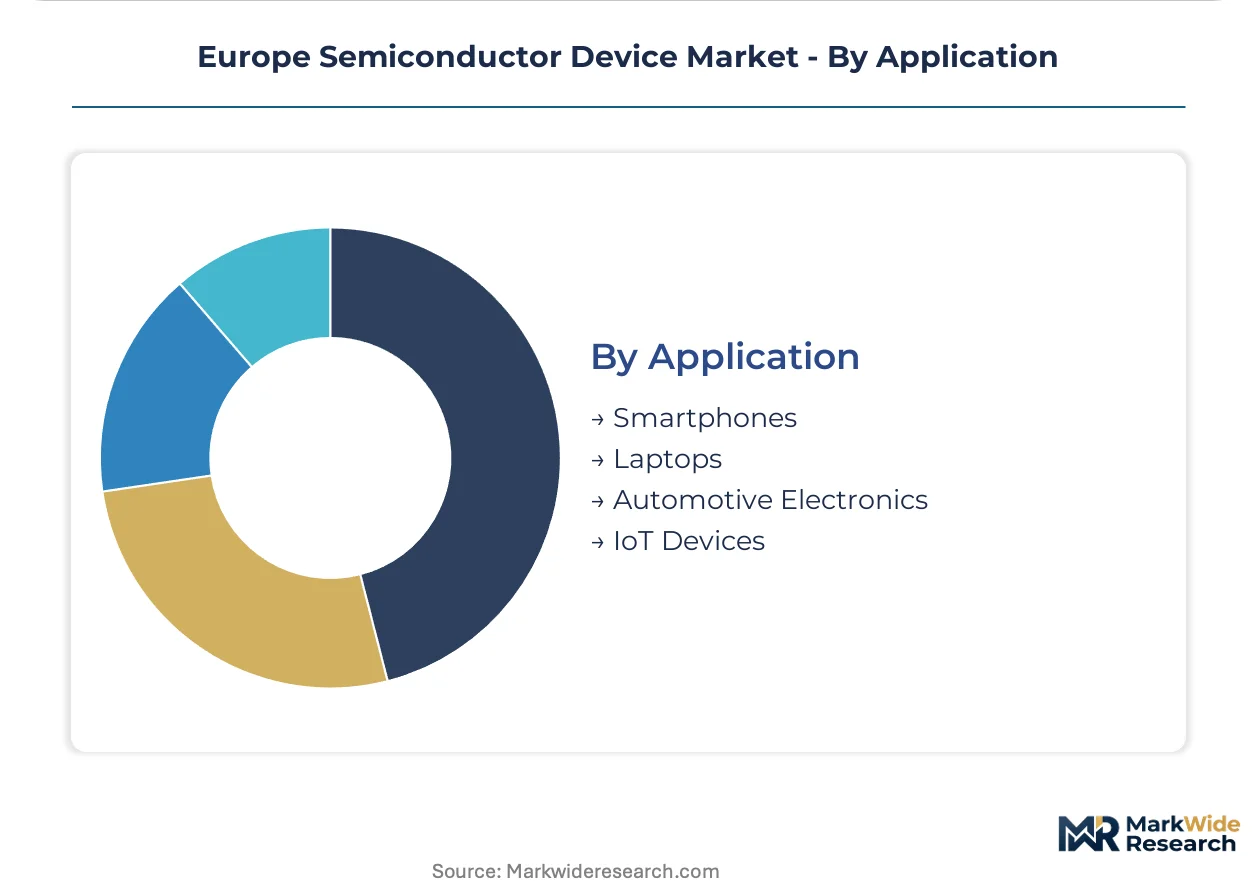
Application:
Customer type fragmentation separates long-cycle automotive platform commitments from volatile consumer electronics spot purchasing.
- Automotive Electronics:Engine control units, infotainment systems, and chassis electronics integrate hundreds of semiconductor devices per vehicle. French and German OEM procurement teams are locking 3-5 year supply agreements directly with STMicroelectronics and NXP.
- IoT Devices:Connected sensors, edge gateways, and industrial monitors require ultra-low-power wireless microcontrollers. Dutch agritech and German smart building deployments are driving sub-GHz radio and energy harvesting PMIC demand.
- Smartphones:Application processors, modem basebands, and RF front-ends enable mobile computing and connectivity.
- Laptops:CPUs, GPUs, and platform controller hubs support personal computing and enterprise mobility.
Automotive electronics anchors the value base. IoT devices are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor moves silicon wafers and lithography equipment between Dutch ports and Bavarian industrial zones, anchoring Europe's semiconductor logistics backbone. This multimodal infrastructure underwrites the region's supply security as automotive electrification accelerates procurement cycles.
Germany
Saxon fabs in Dresden and Villach process 300mm wafers for automotive power modules, while Munich-based OEM procurement teams lock multi-year supply agreements. The KBA enforces ISO 26262 ASIL-D functional safety standards that filter supplier eligibility for traction inverter components. Baden-Württemberg's Stuttgart region hosts Bosch power electronics divisions qualifying silicon carbide gate drivers for 800V EV platforms.
Netherlands
Veldhoven's lithography equipment cluster supplies EUV systems to fabs worldwide, with ASML's supply chain drawing purified neon from Eastern European refining networks. The Dutch national Chips Act implementation disburses capital grants for 200mm analog capacity expansion. Eindhoven's Brainport region anchors NXP's secure connectivity R&D for radar processing platforms.
France
Stellantis and Renault-Nissan procurement teams in Paris and Grenoble consolidate microcontroller orders with European IDMs, prioritizing supply security over unit cost optimization. ANSM imposes quality system requirements for medical-grade semiconductor applications. Crolles hosts STMicroelectronics' 300mm fab expansion serving mixed-signal automotive demand.
Italy
Agrate Brianza and Catania fabs produce power discretes and MEMS sensors for automotive tier-ones, with Italian government Chips Act subsidies accelerating 300mm capacity ramp. The national aerospace and defense procurement framework mandates European sourcing for mission-critical electronics. Milan's design centers specialize in RF front-ends for telecommunications infrastructure.
Belgium
Leuven's imec research consortium coordinates EUV lithography roadmaps with Dutch equipment suppliers and German automotive OEMs. Flanders' national subsidy framework attracts fabless design centers seeking proximity to European IDMs. Hasselt packaging facilities process fan-out wafer-level substrates for German automotive sensor modules.
Europe Semiconductor Device Market Competitive Landscape
Listed leaders compete with private specialists across capital allocation and capacity commitment timelines. The Europe Semiconductor Device Market structures around three tiers: vertically integrated European IDMs with captive fabs, global analog specialists with regional design centers, and equipment suppliers controlling lithography bottlenecks. Strategic moves concentrate on long-term supply agreement negotiations and heterogeneous integration partnerships mixing process nodes.
Among European IDMs, Infineon Technologies AG and STMicroelectronics N.V. occupy positions anchoring power semiconductor supply to German and French automotive corridors. NXP Semiconductors N.V. sits within the secure connectivity tier, exemplifying specialization in radar processing and vehicle gateway architectures. These three represent distinct archetypes: the vertically integrated power module supplier, the diversified microcontroller and discrete manufacturer, and the mixed-signal automotive processor designer.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| STMicroelectronics N.V. |
| NXP Semiconductors N.V. |
| ASML Holding N.V. |
| ams OSRAM AG |
| Robert Bosch GmbH |
| Analog Devices Inc. |
| onsemi Corporation |
| Texas Instruments Inc. |
| Others |
Pricing and Supply Chain Analysis
REACH chemical compliance through ECHA gates supplier qualification and price differentiation simultaneously, with fluorinated compound reformulation costs filtering margin structures across Dresden and Leuven process lines while automotive OEMs pay premiums for certified AEC-Q100 grades.
Pricing Analysis
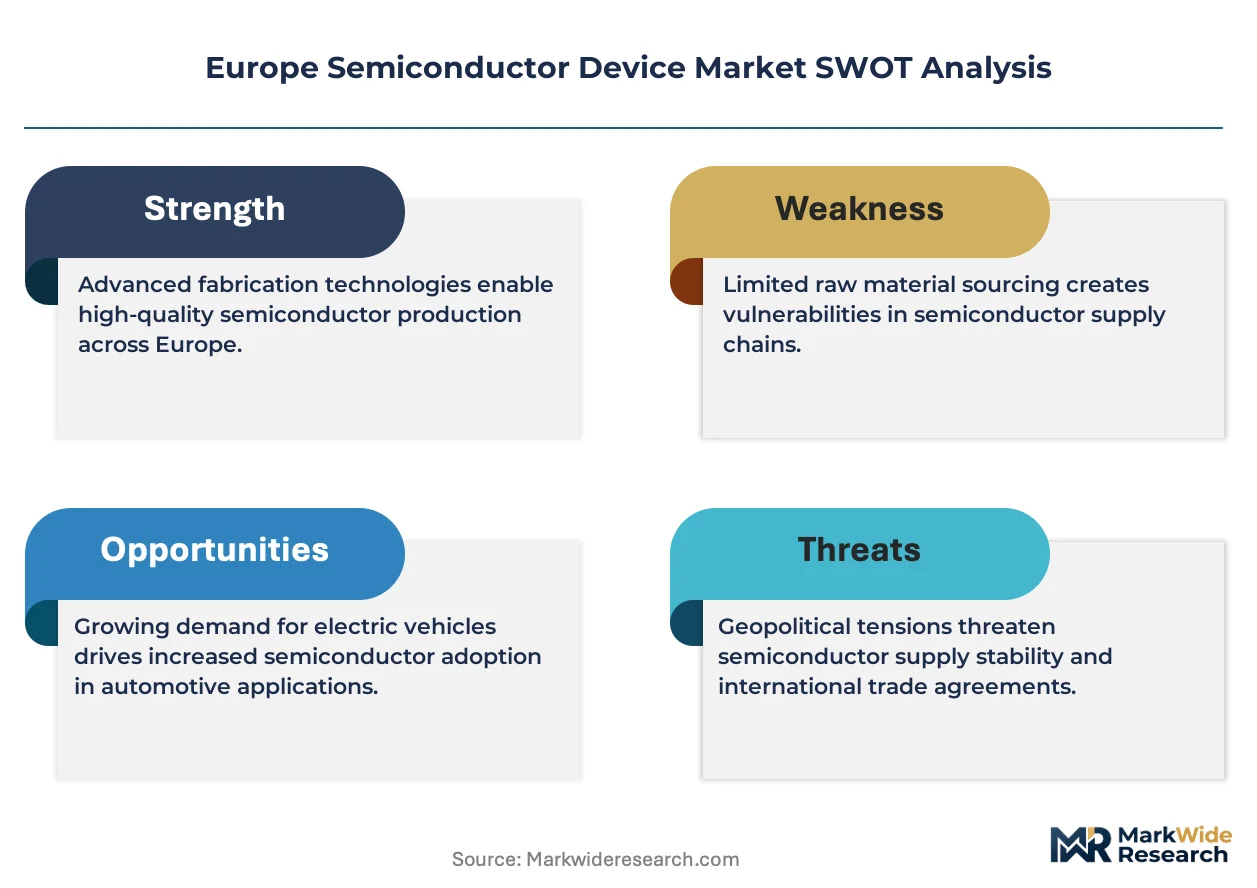
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with ASIL-D functional safety certification and volume scale driving price differentiation. Cost compression in standard-grade power discretes is intensifying because GaN-on-Si alternatives are eroding silicon MOSFET margins in sub-650V applications. Consumer electronics buyers exhibit highest price sensitivity, while German automotive OEM procurement teams show lowest sensitivity due to platform lock-in requirements.
Supply Chain Analysis
Germany and the Netherlands anchor lithography equipment and 300mm wafer fabrication, while Taiwan and South Korea feed advanced node dependencies. Neon gas purification draws from Ukrainian and Russian feedstock networks, creating single-source vulnerability for EUV laser systems. Distribution runs through Rhine-Main-Danube waterway corridors linking Dutch ports to Bavarian industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities are expanding faster than hardware sales, with predictive maintenance software for traction inverters and battery management systems outpacing discrete component revenue growth across German and French automotive corridors.
For Market Incumbents: Compound defensive positioning by deepening captive wafer capacity in Dresden and Villach against emerging GaN foundry competition, while accelerating ISO 26262 ASIL-D certification pipelines to lock tier-one supplier relationships before platform freezes.
For New Entrants and Emerging Players: ANSM fast-track pathways for medical-grade semiconductors offer white-space entry with lower incumbent density than automotive. Target Polish-Czech packaging corridors for cost-competitive fan-out wafer-level substrates serving German sensor module demand, leveraging OSAT partnerships to bypass fab capital requirements.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across 300mm analog capacity expansions, favoring asset-light fabless designers with proven automotive design wins. Watch EU Chips Act subsidy disbursement timelines as inflection signals for regional competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Direct OEM-IDM contracts bypass distribution and compress inventory buffers across German automotive corridors. |
| Backward Integration into SiC Substrates | 8-inch wafer qualification reduces switching losses and secures 800V EV platform slots. |
| REACH Compliance Reformulation | Fluorinated nitrile etching chemistry investments maintain CE marking access for exported devices. |
| Heterogeneous Integration Partnership | Chiplet architectures enable process node mixing across compute, memory, and analog functions. |
| GaN-on-Si Process Development | Epitaxy convergence with CMOS back-end lines opens consumer fast-charging markets without dedicated III-V fabs. |
Research Methodology
Operator-level perspectives from fab operations directors, automotive tier-one procurement leads, lithography equipment specialists, and ECHA compliance officers anchored the qualitative base. Primary interview insights combined with secondary validation from SEC semiconductor filings, EU Chips Act implementation documents, vehicle production databases, and customs wafer trade records. Bottom-up capacity modeling and top-down demand forecasting triangulated volume estimates.
Sensitivity analysis framed analytical uncertainty across the projection horizon, with segmentation modeled by product type, industry vertical, technology node, and application end-use. CAGRs derived from trend extrapolation and driver elasticity assessment, incorporating foundry utilization rates, EV platform rollout schedules, and regulatory compliance timeline assumptions.
The analysis sits within stated boundaries; outcomes outside sustained EU Chips Act funding or accelerated GaN substitution curves would require recalibration. Forecasts reflect documented assumptions about subsidy disbursement velocity and automotive electrification penetration. Recalibration cycles align with material shifts in foundry capacity commissioning and functional safety certification backlogs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
AIN DBC Ceramic Substrate Market
Semiconductor Devices
China Semiconductor Diode Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
Advanced IC Substrates Market
Semiconductor Devices
Ferroelectric FET Market
Semiconductor Devices
Japan Semiconductor Diode Market
Semiconductor Devices
Nano-Magnetic Devices Market
Semiconductor Devices
3D TSV Device Market
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
Die Spacer Market
Semiconductor Devices
Europe MLCC Market
Semiconductor Devices
Global Precision Parts Market
Semiconductor Devices
Spintronic Logic Devices Market
Semiconductor Devices
Global Bipolar Small Signal Transistor Market