
 Leadframes Market | 2026-2036
Leadframes Market Size, Share, and Industry Trends Forecast 2026-2036
Leadframes Market Outlook
EU REACH restrictions on nickel and lead content in electronic components is repositioning material specifications across the European supply chain. Mitsui High-tec, Inc. leverages its etching expertise to supply ultra-fine-pitch leadframes for advanced IC packages. SHINKO ELECTRIC INDUSTRIES CO., LTD. anchors high-volume production through integrated stamping and plating operations in Japan. ASM Pacific Technology Ltd. competes via equipment-to-materials verticality, selling both leadframe manufacturing tools and finished products.
Leadframes are metal structures—typically copper or iron-nickel alloys stamped or etched to precise tolerances—that provide electrical connections between semiconductor dies and external circuitry while mechanically supporting the chip during encapsulation. Stamping leadframes dominate high-volume consumer electronics packaging due to cost efficiency at tight pitch geometries, while etched leadframes command premium positioning in automotive and telecommunications applications requiring finer line resolution. Copper material segments capture the largest volume share given superior electrical conductivity, though alloy formulations gain traction where thermal-mechanical stability exceeds pure copper limits.
The US EPA oversees hazardous substance reporting for leadframe plating chemistries, while Japan's METI enforces JIS material standards that dictate alloy composition tolerances for automotive-qualified components. China's SAMR implements GB standards for semiconductor packaging materials that increasingly reference RoHS-aligned substance restrictions. Stakeholders must monitor evolving cross-border substance regulations while calibrating alloy development roadmaps against end-user qualification timelines.
Market Dynamics
Copper-alloy leadframe designs are displacing traditional iron-nickel formulations as China's MIIT dual carbon goals force domestic foundries to reduce embodied energy in semiconductor packaging materials.
Growth Catalysts
- Automotive Electronics Demand:EV powertrain modules require higher-density interconnects that only advanced leadframe architectures can deliver. South Korea's Pyeongtaek semiconductor corridor anchors this demand concentration.
- EU REACH Compliance:Restrictions on nickel and lead content in electronic components are repositioning material specifications across the European supply chain toward compliant copper formulations.
- Etching Process Refinement:Ultra-fine-pitch leadframe production for advanced IC packages now achieves line resolutions impossible with traditional stamping methods.
Market Restraints
- Raw Material Volatility:Copper price swings compress margin predictability for high-volume stamping operations dependent on pure copper feedstock.
- East Asian Supply Concentration:Manufacturing gravity in Japan's Kyushu packaging hub and South Korean corridors creates geographic vulnerability to regional disruptions.
- Technical Substitution Pressure:Fan-out wafer-level packaging reduces leadframe dependency in premium smartphone applications.
Strategic Opportunities
- Telecommunications Infrastructure:5G base station deployments require etched leadframes with signal integrity specifications that command premium positioning.
- Japan's METI Standards Alignment:JIS material standards for automotive-qualified components create certification moats for compliant suppliers.
- Copper-Alloy Formulation Convergence:Thermal-mechanical stability requirements are merging with conductivity demands in hybrid alloy development roadmaps.
Industry Challenges
- Plating Chemistry Expertise Gap:Hazardous substance reporting under US EPA guidelines requires specialized compliance personnel that suppliers struggle to recruit.
- Cross-Border Qualification Timelines:China's SAMR GB standards and EU REACH restrictions operate on misaligned review cycles, delaying product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leadframes Market |
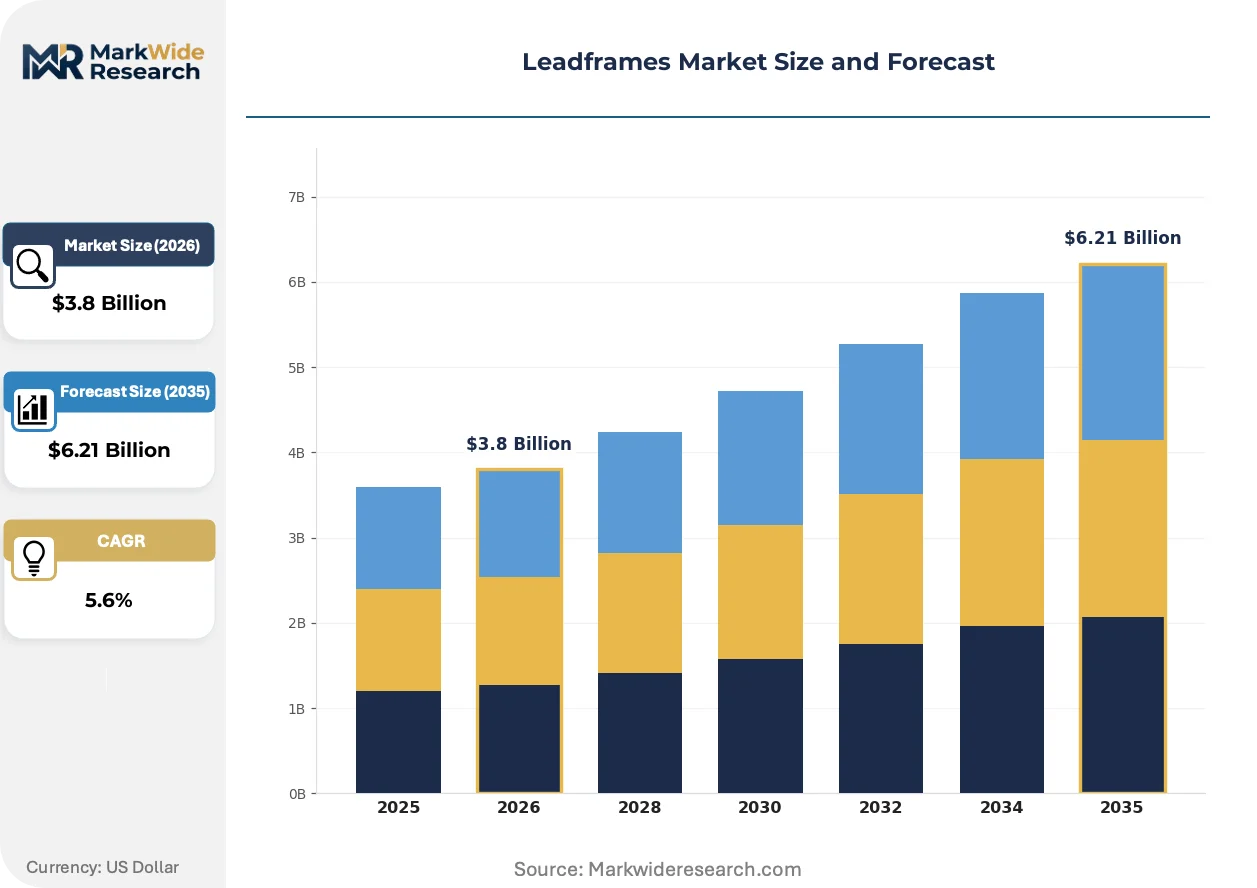
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stamping Leadframes, Etched Leadframes, Insert Molding Leadframes, Others Material: Copper, Alloy, Steel, Aluminum End User: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Applications Production Method: Punching, Photolithography, Injection Molding, Laser Cutting |
| Companies Covered | Mitsui High-tec, Inc., SHINKO ELECTRIC INDUSTRIES CO., LTD., ASM Pacific Technology Ltd., Chang Wah Technology Co., Ltd., Amkor Technology Inc., Ningbo Hualong Electronics Co., Ltd., Wuxi Huajing Electronics Co., Ltd., QPL Limited, Dynacraft Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leadframes Market Strategic Shifts
Etched leadframe fabrication is overtaking mechanical stamping as the dominant precision manufacturing paradigm, driven by automotive and telecommunications applications demanding finer line resolution than stamping tolerances permit.
Etching-based manufacturing is overtaking conventional stamping in automotive-qualified leadframe production. Tier-1 automotive electronics suppliers now specify etched architectures for EV inverter modules where thermal cycling reliability exceeds consumer-grade requirements. This shift is compressing the addressable market for pure stamping houses while expanding specialty etching capacity.
China's MIIT dual carbon goals are forcing foundries to recalibrate alloy selection criteria toward lower-embodied-energy copper formulations. Domestic semiconductor packaging material standards under SAMR increasingly reference RoHS-aligned substance restrictions that parallel EU REACH frameworks. Suppliers serving both markets must maintain dual-compliance documentation systems.
Buyer consolidation among automotive powertrain module integrators is shortening supplier qualification cycles from historical 18-month windows toward compressed 12-month timelines. Direct procurement relationships with foundry engineering teams are displacing traditional distributor-mediated sourcing for critical interconnect components. South Korea's Pyeongtaek corridor exhibits this pattern most acutely, where Samsung SDI and LG Energy Solution vertical integration demands accelerated supplier onboarding.
Leadframes Market Segmentation
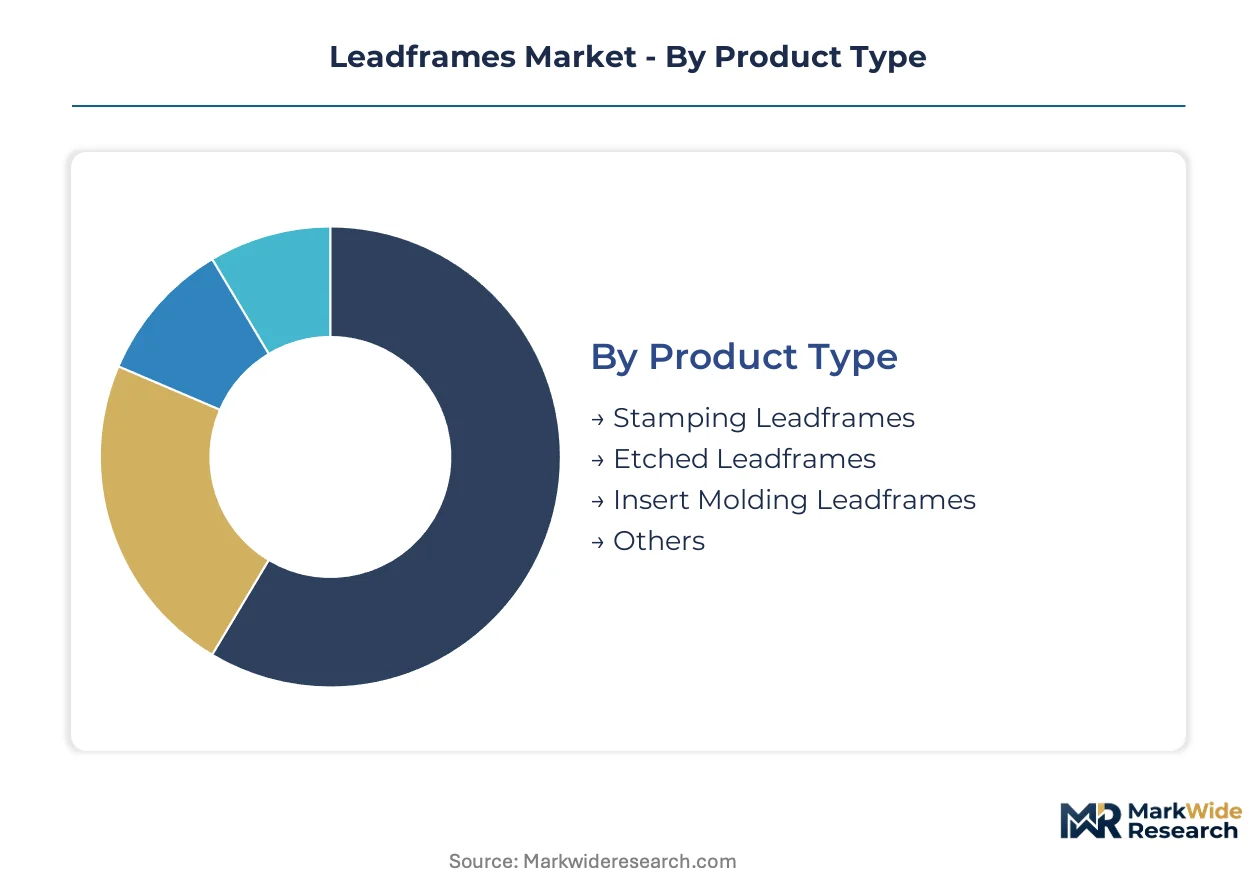
Leadframe segmentation reflects a fundamental tension between cost-driven stamping operations for commodity packaging and precision-etched architectures for reliability-critical applications. Material selection and production method choices cascade through qualification timelines, end-user pricing power, and geographic sourcing strategies.
Product Type:
Stamping dominates unit volumes while etched variants command premium positioning in automotive and telecommunications applications.
- Stamping Leadframes:Mechanical punching of copper or alloy strips achieves tight pitch geometries at high throughput rates. Consumer electronics packaging in South Korea's Pyeongtaek corridor absorbs the majority of this volume, though margin compression from copper price volatility constrains pure-play stamping houses.
- Etched Leadframes:Chemical milling enables line resolutions below 50 micrometers for advanced IC packages. EV powertrain module suppliers in Japan's Kyushu hub specify etched architectures where thermal cycling reliability exceeds consumer-grade requirements.
- Insert Molding Leadframes:Plastic encapsulation integration reduces assembly steps for high-pin-count devices.
- Others:Emerging additive-manufactured prototypes and hybrid stamping-etching processes serve niche qualification pipelines.
Mature deployment sits with Stamping Leadframes. Newer deployment is concentrated in Etched Leadframes.
Material:
Conductivity requirements clash with thermal-mechanical stability needs across alloy development roadmaps.
- Copper:Pure copper feedstock delivers superior electrical conductivity for signal-intensive applications. China's MIIT dual carbon goals are forcing foundries toward lower-embodied-energy copper formulations that parallel EU REACH substance restrictions.
- Alloy:Copper-iron and copper-nickel formulations balance conductivity with thermal expansion matching. Automotive-qualified components under Japan's METI JIS standards increasingly specify alloy compositions for power cycling durability.
- Steel:Iron-nickel alloys retain legacy positioning in hermetic military and aerospace packaging.
- Aluminum:Lightweight alternatives penetrate cost-sensitive LED and sensor applications where conductivity demands moderate.
Copper alloys are gaining share fastest as regulatory pressure merges with thermal performance requirements.
End User:
Automotive qualification cycles are compressing from historical norms while telecommunications infrastructure demands signal integrity premiums.
- Automotive Electronics:EV inverter modules and powertrain controllers require etched leadframes with extended temperature range specifications. Samsung SDI and LG Energy Solution vertical integration in South Korea demands accelerated supplier onboarding.
- Telecommunications:5G base station deployments command etched leadframes with controlled impedance characteristics for millimeter-wave frequencies.
- Consumer Electronics:Smartphone and wearable packaging absorbs high-volume stamping output, though fan-out wafer-level packaging erodes leadframe dependency in premium tiers.
- Industrial Applications:Motor drives and power supplies utilize standard stamped configurations with extended lead times.
Procurement concentration is shifting most acutely in Automotive Electronics, while Consumer Electronics retains volume leadership.
Production Method:
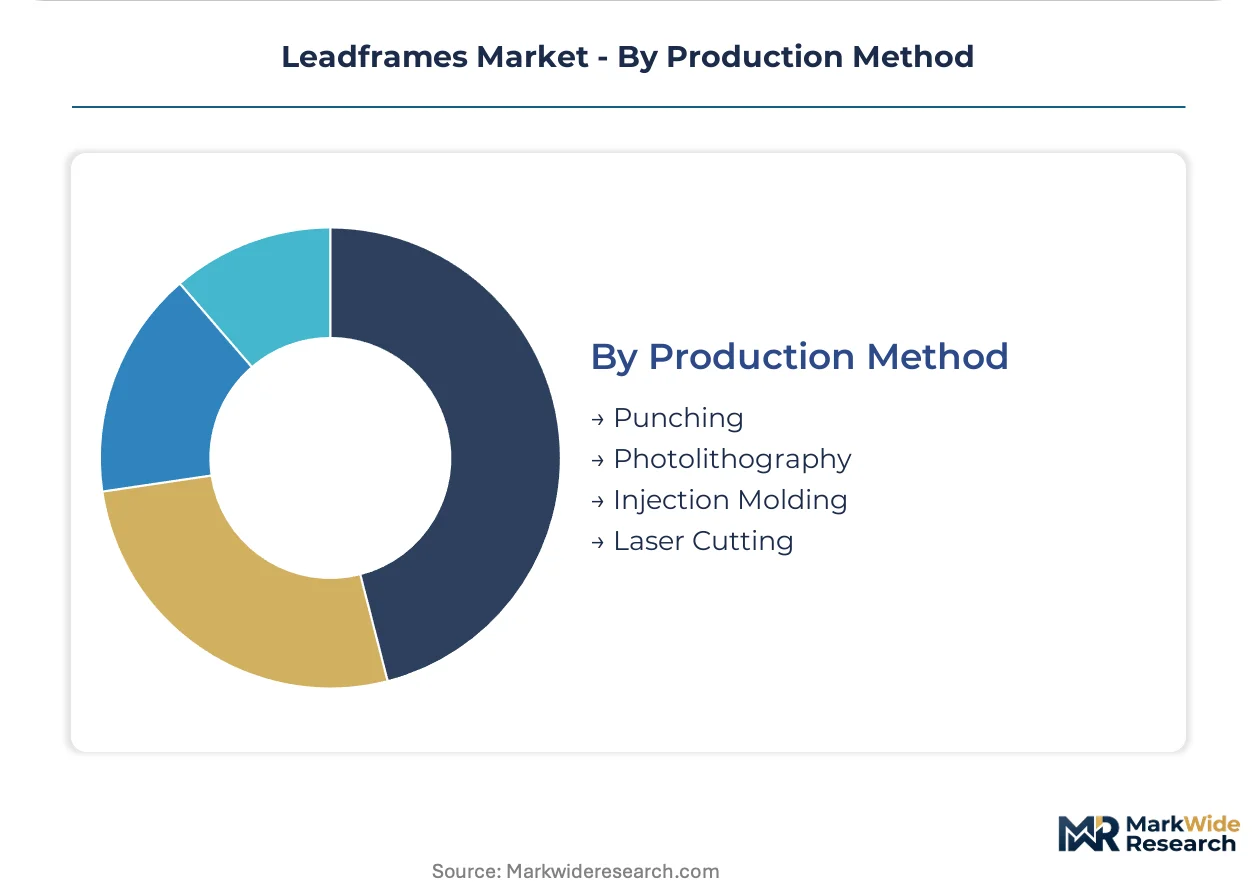
Photolithography capacity expansion is displacing mechanical punching in automotive-qualified production.
- Photolithography:Mask-based chemical etching achieves sub-50-micrometer feature resolution for ultra-fine-pitch packages. Mitsui High-tec etching expertise anchors supply for advanced IC architectures.
- Punching:Mechanical stamping maintains cost leadership for lead pitches above 100 micrometers in consumer electronics packaging.
- Laser Cutting:Direct-write ablation serves rapid prototyping and low-volume custom geometries without mask tooling costs.
- Injection Molding:Thermoplastic encapsulation integration streamlines high-pin-count device assembly.
Photolithography is climbing the fastest as automotive and telecommunications specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian fabrication capacity outpaces regional consumption, forcing European and North American packaging houses to import precision leadframes despite logistics premiums. This production-consumption divide concentrates margin capture with Japanese and South Korean etching specialists while downstream assemblers absorb freight and tariff costs.
China
MIIT dual carbon mandates are accelerating copper-alloy adoption across domestic foundries in Jiangsu and Zhejiang provinces. SAMR GB standards for semiconductor packaging materials now embed RoHS-aligned substance restrictions that parallel EU REACH frameworks. Shanghai's Zhangjiang Hi-Tech Park anchors etching capacity expansion serving automotive power module suppliers.
Japan
METI JIS material standards for automotive-qualified components create certification barriers that favor incumbent alloy suppliers. Kyushu's packaging hub concentrates etched leadframe demand from EV inverter module producers. Nagoya's Chubu corridor hosts precision stamping operations serving industrial motor drive applications with extended qualification timelines.
South Korea
Samsung SDI and LG Energy Solution vertical integration is compressing supplier onboarding cycles from 18 months toward 12 months. Pyeongtaek's semiconductor corridor anchors high-density interconnect demand for EV powertrain controllers. Sejong's materials research cluster is prototyping next-generation copper formulations for thermal cycling durability.
United States
EPA hazardous substance reporting requirements for plating chemistries are elevating compliance costs for import-dependent packaging houses. Texas Instruments and ON Semiconductor fabs in Arizona and Texas source etched leadframes from East Asian specialists. California's clean technology procurement standards are filtering into automotive electronics material specifications.
Germany
ECHA REACH restrictions on nickel and lead content are repositioning material specifications across Bavarian and Baden-Württemberg automotive supply chains. Bosch and Continental power electronics divisions specify etched architectures for 800V EV architectures. Stuttgart's precision manufacturing cluster is qualifying hybrid stamping-etching processes for cost-sensitive industrial applications.
Leadframes Market Competitive Environment
The competitive structure tilts toward integrated equipment-to-materials specialists rather than pure-play component fabricators. Japanese and South Korean incumbents anchor premium-tier positioning through etching expertise and automotive certification depth. Three archetypes dominate: precision etching specialists serving automotive reliability requirements, high-volume stamping houses absorbing consumer electronics volume, and equipment-integrated players selling manufacturing tools alongside finished leadframes. Capacity expansion and backward integration into captive alloy supply represent the dominant competitive moves.
Among Japanese fabricators, Mitsui High-tec, Inc. and SHINKO ELECTRIC INDUSTRIES CO., LTD. exemplify the etching-specialist archetype with automotive certification depth. ASM Pacific Technology Ltd. occupies a distinct position through equipment-to-materials verticality. These three entities anchor the competitive landscape without exhaustive representation of the 15–20 companies typically profiled in comprehensive market studies.
| Leading Market Players |
|---|
| Mitsui High-tec, Inc. |
| SHINKO ELECTRIC INDUSTRIES CO., LTD. |
| ASM Pacific Technology Ltd. |
| Chang Wah Technology Co., Ltd. |
| Amkor Technology Inc. |
| Ningbo Hualong Electronics Co., Ltd. |
| Wuxi Huajing Electronics Co., Ltd. |
| QPL Limited |
| Dynacraft Industries |
| Others |
Value Chain & Pricing Dynamics
China's MIIT dual carbon goals are gating both qualified supply and premium-tier pricing access, as foundries recalibrate alloy selection toward lower-embodied-energy copper formulations that satisfy parallel EU REACH substance restrictions. This environmental mandate concentrates pricing power with etching specialists capable of certifying compliant production while stamping houses absorb margin compression from feedstock volatility.
Pricing Analysis
Yield-guaranteed throughput contracts anchor value-based pricing for automotive-qualified etched leadframes, where thermal cycling reliability commands substantial premiums over consumer-grade stamped alternatives. Price differentiation separates JIS-certified alloy formulations from commodity copper feedstock, with certification tier and volume scale driving tiered premiums. Cost compression in high-volume stamping is intensifying because copper price swings erode margin predictability for pure-play operators. Automotive powertrain module integrators exhibit lowest price sensitivity due to qualification lock-in, while consumer electronics packaging houses remain most responsive to unit cost fluctuations.
Supply Chain Analysis
Scrap copper reclamation flows from Japanese and South Korean packaging hubs are tightening secondary feedstock circulation, reducing virgin material dependency for alloy formulation. Primary production concentrates in Japan, South Korea, and China, with etching capacity clustering in Kyushu and Pyeongtaek corridors. Raw material supply draws from Chilean copper concentrate, Indonesian nickel intermediates, and domestic Chinese refined metal. Single-source vulnerability runs through East Asian photolithography equipment dependency. Distribution runs through direct procurement relationships with foundry engineering teams, displacing traditional distributor-mediated sourcing for critical interconnect components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race, with players pursuing captive alloy supply to secure thermal-mechanical stability specifications and compress qualification timelines.
For Market Incumbents: Acquire specialty etching capacity in Japan's Kyushu hub to defend against fan-out wafer-level packaging substitution in premium smartphone tiers. Secure backward integration into copper-alloy smelting operations that satisfy China's SAMR GB standards and EU REACH nickel restrictions simultaneously. Deepen automotive certification depth under METI JIS protocols to extend qualification moats. For New Entrants and Emerging Players: Automotive powertrain module suppliers in South Korea's Pyeongtaek corridor represent the most penetrable entry vector, given compressed 12-month onboarding windows and limited qualified etching capacity. Target telecommunications infrastructure deployments requiring controlled-impedance etched architectures for 5G millimeter-wave frequencies. Partner with materials research clusters prototyping next-generation thermal cycling formulations. For Investors and Strategic Acquirers: Samsung SDI and LG Energy Solution direct procurement announcements are the leading indicator that automotive electronics integration is accelerating supplier consolidation timelines. Position for 5-10 year viability around equipment-to-materials verticality plays, where ASM Pacific Technology's model demonstrates sustainable margin capture. Monitor MIIT dual carbon enforcement intensity for early signals of alloy formulation preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Photolithography Capacity Expansion | Enables sub-50-micrometer feature resolution for EV inverter module specifications. |
| Captive Copper-Alloy Smelting | Secures thermal-mechanical stability control while satisfying China's MIIT embodied energy mandates. |
| JIS Certification Investment | Creates regulatory moats for automotive-qualified component supply under METI standards. |
| Direct Foundry Procurement Relationships | Displaces distributor intermediation in Samsung SDI and LG Energy Solution supply chains. |
| Dual-Compliance Documentation Systems | Aligns SAMR GB standards with EU REACH substance restrictions for cross-border market access. |
Study Parameters
Multi-period observation of alloy formulation adoption rates, etching capacity utilization, and automotive qualification cycle compression anchored the trend analysis, supplemented by interviews with leadframe manufacturing executives, foundry procurement directors, automotive electronics integration engineers, and plating chemistry compliance specialists. Secondary validation drew from METI JIS standard filings, SAMR GB standard publications, EPA hazardous substance reporting databases, and SEC 10-K disclosures from listed packaging material suppliers. Bottom-up segment sizing and top-down market triangulation converged on volume and value estimates.
Segment-weighting across production method, material composition, and end-use application dimensions structured the analytical framework throughout the projection horizon. Photolithography versus mechanical stamping penetration, copper-alloy versus pure copper feedstock mix, and automotive versus consumer electronics demand concentration were modeled as primary forecast drivers. CAGRs were derived from trend extrapolation of qualification timeline compression and environmental mandate enforcement intensity.
Caveats apply where MIIT dual carbon enforcement intensity, EU REACH substance restriction expansion, or fan-out wafer-level packaging substitution acceleration could materially shift the outlook. Practitioners should monitor automotive powertrain module vertical integration announcements and copper price volatility indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
IGBT Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
TC-SAW Filter Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
Global Automotive Mosfets Market
Semiconductor Devices
Global Substrate-Like PCB Market
Semiconductor Devices
APAC Semiconductor Device in Consumer Industry Market
Semiconductor Devices
Digital Transistor Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Multi-Chip Module (MCM) Market
Semiconductor Devices
Large-Size PV Silicon Wafer Market
Semiconductor Devices
Rad-Hard Mosfets Market
Semiconductor Devices
Japan MCU Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
Micro and Nano PLC Market