
 T-Con Board Market | 2026-2036
T-Con Board Market Size, Share, and Industry Trends Forecast 2026-2036
T-Con Board Market Insights
ISO 9001 quality management certification is redrawing competitive boundaries in the T-Con Board Market, filtering out suppliers lacking traceable manufacturing systems. Novatek Microelectronics leverages its vertically integrated IC design capabilities to dominate driver IC sourcing for television applications. Himax Technologies anchors its position through specialized timing controller architectures for automotive displays. Samsung System LSI competes by extending its captive demand from affiliated display panel operations into external merchant markets.
A T-Con Board is a semiconductor-based timing controller module that synchronizes row and column driver signals to liquid crystal or organic light-emitting diode panels, typically operating at refresh rates between 60 Hz and 240 Hz with embedded gamma correction and overdrive compensation circuits. Its primary commercial purpose is to ensure uniform pixel response and color accuracy across large-area displays. LCD T-Con remains the revenue backbone due to sustained television and monitor volume, while OLED T-Con captures expanding margin pools as premium smartphone and laptop adoption intensifies. Automotive displays represent the fastest-growing application segment, driven by dashboard digitization and regulatory mandates for rear-view camera systems.
RoHS substance restrictions in Europe and REACH chemical compliance frameworks constrain solder and substrate material choices, compelling redesigns of board-level interconnects. China's SAMR enforces GB standards for electromagnetic compatibility that gate market access for imported T-Con modules. Japan's METI promotes JIS-compliant energy efficiency benchmarks that shape product roadmaps for display interface semiconductors. Stakeholders must monitor how regional certification divergence affects platform consolidation strategies across multiple end-use verticals.
Market Dynamics
Automotive cockpit digitization is compressing development cycles for T-Con Board suppliers as OEMs demand automotive-grade timing controllers that satisfy ISO 26262 functional safety requirements alongside traditional display performance metrics.
Growth Catalysts
- GB Standards Compliance:China's SAMR mandates for electromagnetic compatibility and energy-efficient displays are forcing component upgrades across domestic panel supply chains, expanding addressable demand for certified T-Con modules.
- Automotive Display Mandates:Regulatory requirements for rear-view camera systems and digital instrument clusters in passenger vehicles are creating dedicated procurement channels for automotive-grade timing controllers.
- OLED Panel Migration:Premium smartphone and laptop manufacturers are adopting organic light-emitting diode technology at scale, requiring specialized T-Con architectures with distinct gamma correction and overdrive compensation circuits.
Market Restraints
- Driver IC Supply Concentration:Foundry capacity for high-voltage LDDI and OLED driver ICs concentrates in Taiwan and South Korea, exposing T-Con assemblers to allocation risk during semiconductor supply shocks.
- RoHS Substance Restrictions:ECHA's REACH framework and European RoHS directives constrain solder alloy compositions and halogen-free substrate materials, complicating board-level interconnect redesigns.
- LCD Volume Dependency:Sustained television and monitor shipments for liquid crystal displays generate revenue concentration risk as panel makers delay organic light-emitting diode transition timelines.
Strategic Opportunities
- India Display Manufacturing:PLI scheme incentives for semiconductor and display fabrication are attracting panel investments in Gujarat and Tamil Nadu, creating localized T-Con sourcing requirements.
- Dual Carbon Alignment:China's MEE enforcement of carbon intensity targets for electronics manufacturing is rewarding suppliers with verified low-carbon production processes and renewable energy certificates.
- Advanced Driver Assistance Systems:Integration of augmented reality head-up displays and surround-view camera systems is opening specification windows for high-refresh-rate timing controllers with extended temperature ranges.
Industry Challenges
- ISO 26262 Certification Timeline:Automotive functional safety documentation and third-party audit cycles extend product qualification periods, compressing time-to-revenue for new timing controller platforms.
- Legacy LCD Integration Complexity:Backward compatibility requirements for existing monitor and television chassis designs constrain architectural innovation and pin-count optimization in next-generation T-Con designs.
- Gamma Calibration Talent Scarcity:Specialized expertise in display color science and automated optical inspection for panel uniformity is concentrating among experienced engineering teams in East Asian manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | T-Con Board Market |
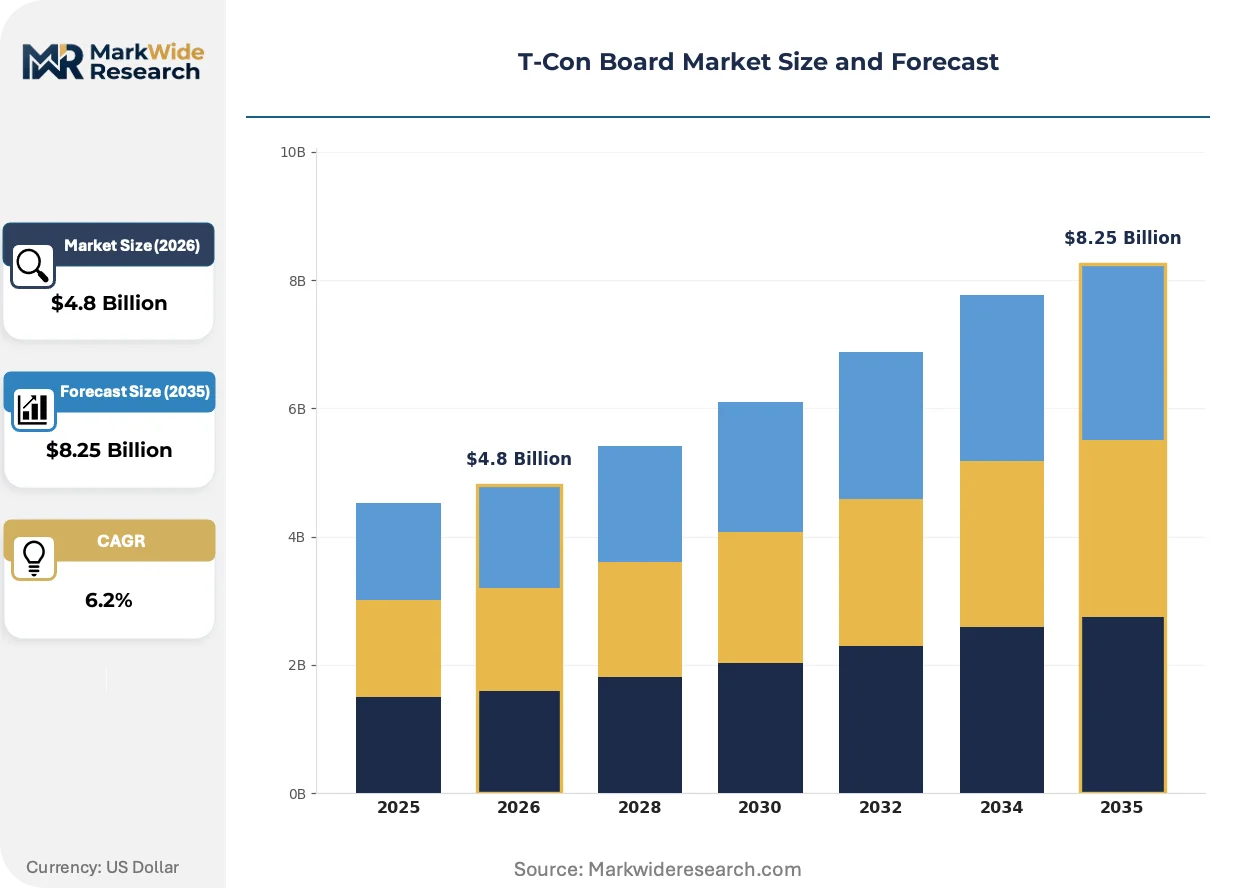
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD T-Con, OLED T-Con, LED T-Con, Mini-LED T-Con Application: Television, Monitors, Projectors, Laptops End User: Consumer Electronics, Professional Displays, Automotive Displays, Medical Equipment Technology: Digital Signal Processing, Image Processing, Color Management, Power Management |
| Companies Covered | Novatek Microelectronics, Himax Technologies, Samsung System LSI, Parade Technologies, MegaChips Corporation, Raydium Semiconductor, Sitronix, Silicon Works, Focal Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
T-Con Board Market Trends and Innovations
Silicon integration and packaging advances are redefining T-Con Board form factors as panel makers pursue bezel reduction and thermal efficiency in increasingly compact display modules.
System-in-package architectures for timing controllers are consolidating gamma buffer, power management, and timing generator functions onto single die or multi-chip modules. Automotive display module suppliers in Germany and Japan are qualifying these integrated solutions for instrument cluster applications. The technology is miniaturizing board footprints while reducing electromagnetic interference susceptibility in densely packed vehicle cockpits.
Japan's METI has revised JIS C 61000 electromagnetic compatibility benchmarks for display interface semiconductors, tightening radiated emission limits for timing controllers operating above 120 Hz refresh rates. Industrial display manufacturers serving medical and aviation verticals are accelerating redesign cycles to meet the updated certification windows. Premium monitor segments targeting professional color grading workflows are absorbing compliance costs fastest due to existing margin structures.
Consolidated procurement contracts are replacing discrete component sourcing as tier-one panel makers negotiate direct timing controller supply agreements with semiconductor houses. Korean and Taiwanese display conglomerates are internalizing T-Con specification authority, compressing merchant market access for independent board assemblers. The shift is most visible in television panel procurement, where annual volume commitments now dominate supplier selection criteria over unit pricing flexibility.
T-Con Board Market Segmentation
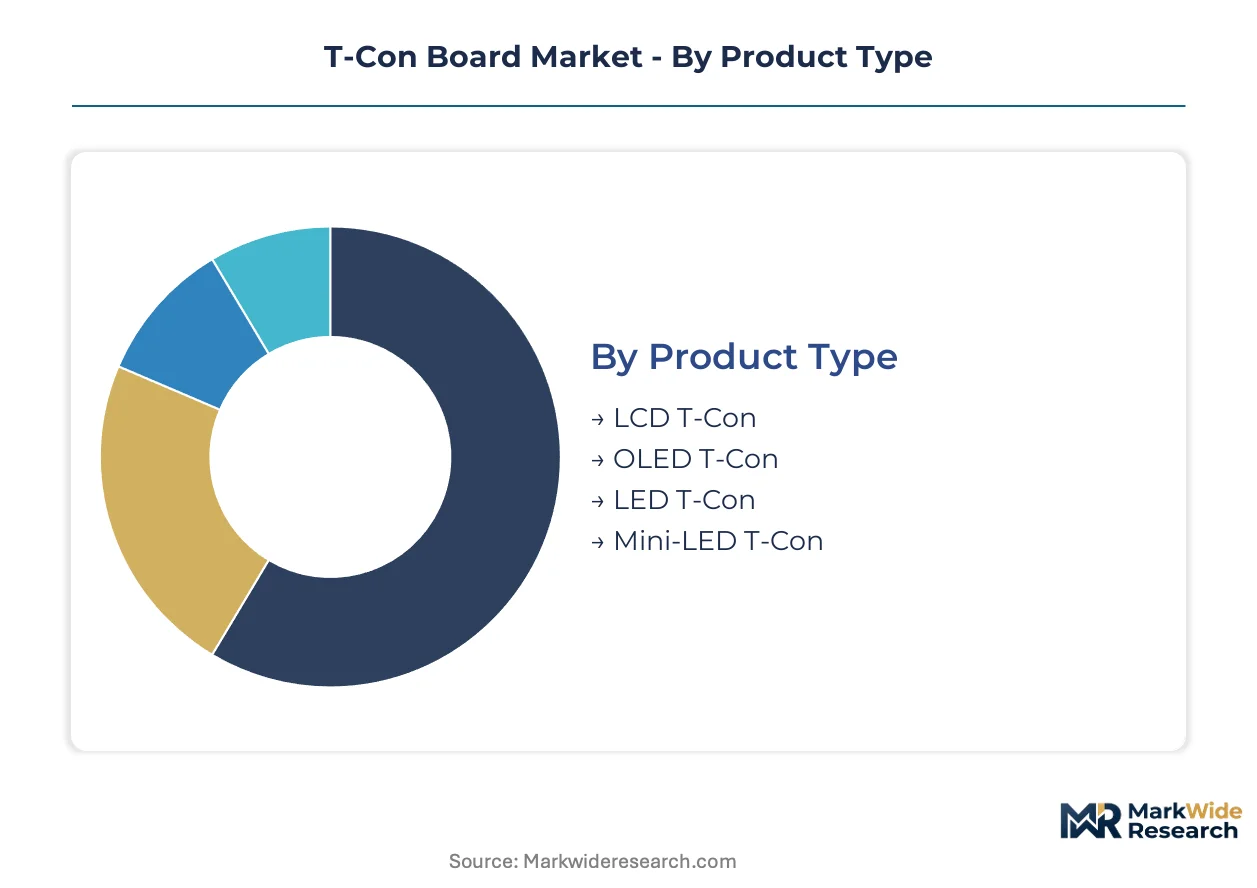
T-Con Board segmentation reveals how timing controller architectures diverge across display technologies and end-use requirements. Margin pools concentrate where panel complexity intersects with stringent certification demands, particularly in automotive and medical verticals.
Product Type:
Margin concentration tracks directly to panel technology transitions, with premium architectures capturing value from OLED migration and Mini-LED diffusion.
- LCD T-Con:Mature timing controller designs synchronize row and column drivers for twisted-nematic and in-plane switching liquid crystal panels. Television manufacturers in South Korea and Taiwan sustain procurement volume for 60-120 Hz mainstream displays, though margin compression intensifies as panel makers consolidate supplier bases.
- OLED T-Con:Specialized architectures incorporate distinct gamma correction curves and pixel compensation circuits for organic light-emitting diode panels. Smartphone and laptop brands in China are scaling procurement for flexible and foldable displays, driving specification upgrades for power-efficient timing generation.
- LED T-Con:Direct-backlight timing controllers manage local dimming zones for edge-lit and full-array LED configurations.
- Mini-LED T-Con:Dense zone-count controllers synchronize thousands of dimming segments for high-dynamic-range premium displays.
The dominant share belongs to LCD T-Con, while OLED T-Con is closing the gap fastest.
Application:
Application segmentation maps timing controller complexity to display size, refresh rate requirements, and color accuracy specifications.
- Television:Large-area timing controllers manage 4K and 8K resolution panels with variable refresh rate support for gaming and streaming interfaces. South Korean panel conglomerates anchor procurement volume, demanding annual cost-down trajectories that compress merchant supplier margins.
- Monitors:Professional and gaming display segments require 144-240 Hz timing controllers with low-latency overdrive compensation. Chinese contract manufacturers are expanding procurement for curved and ultrawide formats, stretching qualification cycles for new timing controller platforms.
- Projectors:Compact timing controllers synchronize microdisplay or DLP interface signals with portable and cinema-grade projection systems.
- Laptops:Thin-bezel timing controllers integrate power management and touch-signal routing for clamshell and convertible form factors.
Television commands the largest procurement base, though Monitors is expanding most quickly on gaming and professional workstation demand.
End User:
End-user segmentation separates consumer volume from premium verticals where certification and reliability requirements sustain pricing power.
- Automotive Displays:ISO 26262-compliant timing controllers synchronize instrument clusters, center-stack screens, and rear-view camera feeds. German and Japanese OEMs are mandating extended temperature ranges and electromagnetic immunity for cockpit digitization programs, extending supplier qualification timelines.
- Medical Equipment:Diagnostic and surgical displays require DICOM-calibrated timing controllers with grayscale precision and long-term luminance stability.
- Consumer Electronics:High-volume timing controllers serve television, smartphone, and tablet manufacturers with cost-optimized architectures.
- Professional Displays:Broadcast reference monitors and color-grading workstations demand factory-calibrated timing controllers with 10-bit or 12-bit color depth support.
Consumer Electronics retains the volume lead, yet Automotive Displays is gaining share fastest on regulatory mandates for camera and cluster digitization.
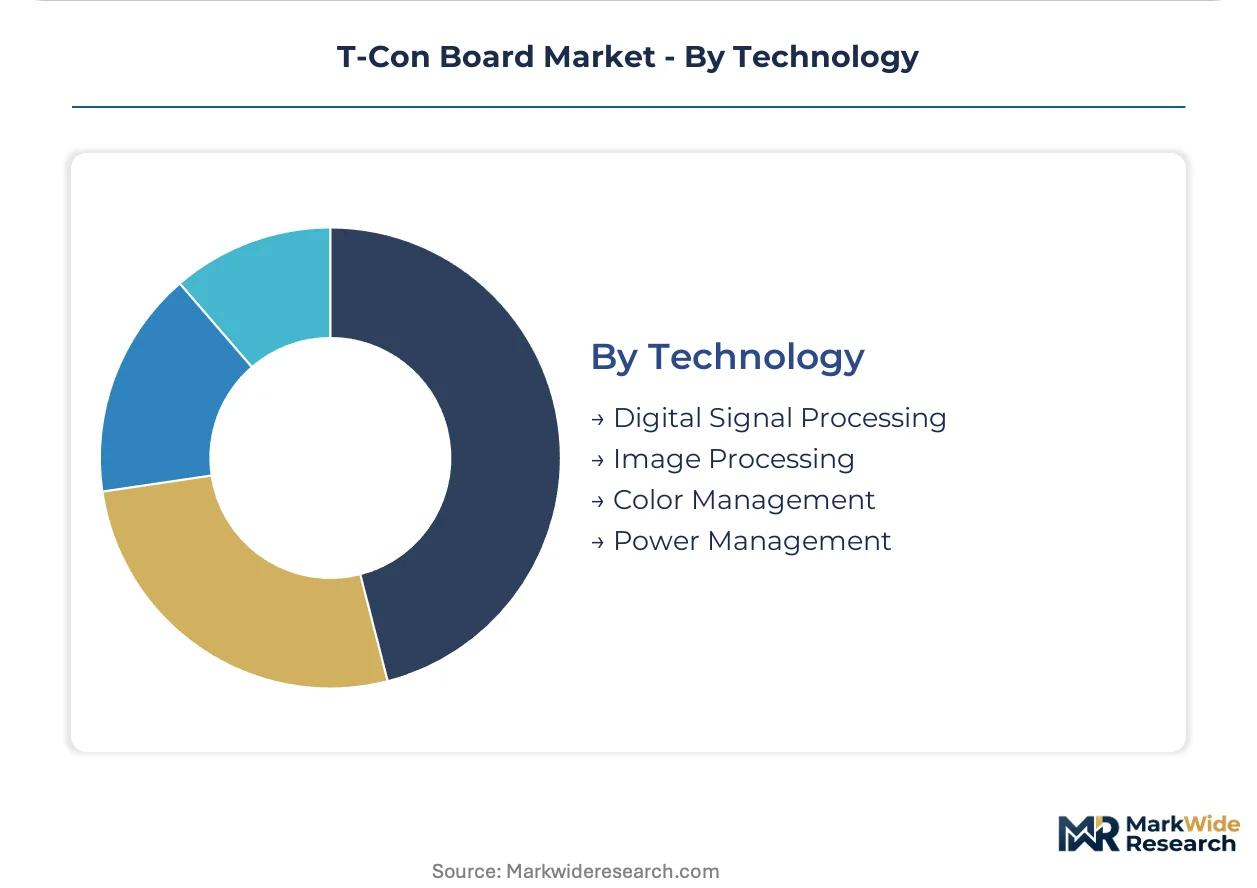
Technology:
Technology segmentation distinguishes functional blocks within timing controller silicon, with integration trends reshaping board-level component counts.
- Image Processing:Scaler and de-interlacer circuits manage resolution conversion and motion compensation for multi-format input compatibility. Panel makers in Taiwan are integrating these functions into system-on-chip architectures, displacing discrete timing controller variants in cost-sensitive television designs.
- Power Management:Integrated voltage regulators and gamma reference generators supply stable bias voltages to source and gate driver ICs. Automotive module suppliers in Japan are qualifying these integrated solutions for 12V and 48V vehicle electrical systems, tightening electromagnetic emission specifications.
- Digital Signal Processing:Timing generator and data formatter circuits serialize pixel data for panel interface standards.
- Color Management:Look-up tables and 3D gamma engines maintain color accuracy across temperature and aging conditions.
Image Processing holds the dominant functional share, while Power Management is climbing the fastest on automotive integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government industrial policies and carbon neutrality mandates are redrawing T-Con Board procurement geography, with incentive schemes in Asia-Pacific manufacturing clusters attracting the dominant share of new capacity investments.
China
Domestic panel conglomerates in Beijing and Shenzhen are scaling T-Con sourcing for 8K television and automotive display lines. SAMR enforces GB standards for electromagnetic compatibility that gate market access for imported modules. The Yangtze River Delta cluster around Shanghai and Suzhou concentrates timing controller assembly operations serving BOE and TCL CSOT fab expansions.
South Korea
Samsung Display and LG Display anchor captive demand for OLED T-Con architectures in Gyeonggi-do and Gyeongsang provinces. The country's national semiconductor regulator aligns product roadmaps with K-Display industry targets for foldable panel penetration. Seoul Capital Area engineering centers specialize in high-refresh-rate timing generators for gaming monitor exports.
Taiwan
Foundry capacity for driver ICs concentrates in Hsinchu Science Park, exposing T-Con assemblers to allocation risk during supply shocks. The island's industrial standards body enforces electromagnetic emission benchmarks for display interface semiconductors. Tainan and Taichung house merchant timing controller specialists serving AU Optronics and Innolux panel operations.
Japan
Automotive module suppliers in Aichi and Kanagawa prefectures qualify integrated T-Con solutions for instrument cluster applications. METI promotes JIS-compliant energy efficiency benchmarks that shape product roadmaps for timing controllers. The Chubu region around Nagoya hosts precision gamma calibration engineering teams concentrated among experienced display color science specialists.
India
PLI scheme incentives for semiconductor and display fabrication are attracting panel investments in Gujarat and Tamil Nadu, creating localized T-Con sourcing requirements. The country's national electronics regulator enforces BIS certification for electromagnetic compatibility in imported modules. The Delhi-Mumbai Industrial Corridor is emerging as a logistics hub for timing controller distribution to emerging domestic assembly operations.
T-Con Board Market Competitive Landscape
Listed leaders compete with private specialists across integrated circuit design capabilities, with public semiconductor houses leveraging capital market access against unlisted players prioritizing niche automotive certifications. The vendor base concentrates among East Asian timing controller architects with captive foundry relationships or fabless design expertise. Three archetypes dominate: vertically integrated IC designers controlling driver silicon supply, fabless specialists targeting automotive functional safety tiers, and diversified semiconductor houses extending display divisions into merchant markets. Competitive moves center on backward integration into driver IC sourcing and geographic expansion into India display manufacturing zones.
Within the fabless specialist tier, Novatek Microelectronics and Himax Technologies exemplify divergent positioning strategies, with the former representing television-volume timing controller platforms and the latter anchoring automotive-grade architectures. Samsung System LSI occupies a hybrid position, leveraging captive demand from affiliated display panel operations into external merchant markets. These three companies illustrate how competitive advantage in T-Con Board supply increasingly depends on control over upstream driver IC supply and certification depth in regulated automotive verticals.
| Leading Market Players |
|---|
| Novatek Microelectronics |
| Himax Technologies |
| Samsung System LSI |
| Parade Technologies |
| MegaChips Corporation |
| Raydium Semiconductor |
| Sitronix |
| Silicon Works |
| Focal Tech |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day foundry lead times for high-voltage driver ICs concentrate pricing power among Taiwanese and South Korean semiconductor houses, compressing margin flexibility for merchant T-Con assemblers dependent on external silicon allocation. This inventory-to-pricing linkage tightens most acutely during panel demand surges, when automotive-grade certification premiums widen against consumer-electronics commoditization.
Pricing Analysis
Certification level (ISO 26262 automotive-grade versus consumer electronics) creates the primary spread across T-Con Board procurement contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by functional safety documentation depth and electromagnetic compatibility testing rigor. Cost compression in television-volume LCD timing controllers is intensifying because Korean panel conglomerates consolidate annual supplier bases into single-source arrangements. Consumer electronics manufacturers exhibit highest price sensitivity, while German and Japanese automotive OEMs absorb premium pricing for extended temperature range and failure-mode coverage.
Supply Chain Analysis
Just-in-time inventory strategies dominate consumer electronics procurement, whereas automotive module suppliers maintain strategic stockpiles of ISO 26262-qualified timing controllers to buffer extended qualification cycles. Supply concentrates in Taiwan, South Korea, and China, with foundry capacity for LDDI and OLED driver ICs anchoring in Hsinchu Science Park and Gyeonggi-do province. Raw material dependencies center on halogen-free substrate laminates, RoHS-compliant solder alloys, and gamma reference voltage components. Single-source vulnerability concentrates in 12-inch foundry nodes for high-voltage driver silicon. Distribution runs through tier-one panel maker direct procurement contracts, displacing independent distributor channels in television and monitor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive cockpit digitization represents an early-cycle expansion story, with regulatory mandates for rear-view camera and instrument cluster displays accelerating specification upgrades ahead of mainstream OLED television transition timelines.
For Market Incumbents: Compound defensive positioning through backward integration into driver IC design capabilities and captive foundry relationships that buffer allocation shocks. Samsung System LSI and Novatek Microelectronics demonstrate how controlling upstream silicon supply secures volume commitments from Korean and Taiwanese panel conglomerates. Certification investment in ISO 26262 functional safety documentation extends qualification timelines that deter merchant-market entrants.
For New Entrants and Emerging Players: Automotive-grade gamma calibration services represent a service-layer gap where incumbent timing controller houses under-serve smaller German and Japanese Tier 2 module suppliers. White-space targets concentrate in India's emerging Gujarat and Tamil Nadu display manufacturing zones, where PLI scheme incentives attract panel investments lacking localized T-Con sourcing infrastructure. A direct technical sales model targeting instrument cluster engineering teams bypasses consolidated procurement channels dominating television procurement.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified semiconductor houses with under-optimized display divisions lacking automotive certification depth. Long-term viability over a five-to-ten year horizon favors specialists with vertically integrated IC design and captive foundry access over pure-play board assemblers exposed to Korean panel conglomerate procurement consolidation. The signal to watch is foldable smartphone panel yield rates, which determine OLED T-Con architecture standardization timelines and merchant market access windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Functional Safety Certification | ISO 26262 documentation opens procurement channels with German and Japanese OEM cockpit digitization programs. |
| Driver IC Backward Integration | In-house LDDI and OLED driver silicon design secures foundry allocation priority during semiconductor supply shocks. |
| India Manufacturing Localization | Gujarat and Tamil Nadu panel investments under PLI schemes create demand for domestically sourced timing controllers. |
| System-in-Package Architecture Migration | Consolidated gamma buffer and power management functions reduce board footprint for bezel-constrained automotive displays. |
| Dual Carbon Compliance Verification | MEE-enforced carbon intensity targets in China reward suppliers with renewable energy certificates and verified low-carbon processes. |
Research Methodology
A spread of perspectives from timing controller design engineers, automotive display module procurement managers, panel maker supply chain directors, and foundry capacity planners converged on the working assumptions shaping this analysis. Primary interviews with semiconductor house product marketing teams and secondary validation against SAMR GB standard filings, METI JIS benchmark revisions, and Korean Display Industry Association capacity announcements established demand-side parameters. Bottom-up triangulation across individual panel maker procurement volumes and top-down reconciliation with foundry utilization disclosures anchored supply-side estimates.
Segmentation dimensions modeled span display technology (LCD, OLED, Mini-LED), application vertical (television, automotive, monitor, medical), and functional integration level (discrete timing generator versus system-in-package). CAGRs were derived from panel shipment forecasts cross-referenced with timing controller content-per-unit assumptions and technology transition elasticity coefficients. Industry-specific inputs include automotive display mandate implementation schedules and OLED panel yield improvement trajectories across the projection horizon.
Underlying assumptions cover sustained television LCD volume, automotive regulatory mandate enforcement, and foundry capacity expansion timelines, with deviation risk concentrated in OLED transition acceleration and China-Taiwan trade policy shifts. Revision becomes warranted when automotive display penetration rates or foldable panel yield thresholds cross material inflection bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Superconductor Wire Market
Semiconductor Devices
Plastic Transistors Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Analog and Mixed Signal Device Market
Semiconductor Devices
Japan MCU Market
Semiconductor Devices
FPGA Market
Semiconductor Devices
Thick Film Devices Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market
Semiconductor Devices
Global Inp Wafer Market
Semiconductor Devices
Asia-Pacific Power Transistor Market
Semiconductor Devices
Nano-Magnetic Devices Market
Semiconductor Devices
Silicon Wafer Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
Global Probe Card Market
Semiconductor Devices
Silicon on Insulator Market