
 Veterinary Ventilators Market | 2026-2036
Veterinary Ventilators Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Ventilators Market Analytics
Polymer composites are displacing legacy metal housings and is recalibrating unit economics for mid-range ventilator lines. Midmark Corporation leverages its scale in clinical furniture to extend distribution reach into veterinary suites. Hallowell EMC anchors its position through specialization in compact anesthesia-integrated systems. Vetronic Services Ltd. competes on software-controlled platforms that synchronize with patient monitoring networks.
Veterinary ventilators are electromechanical life-support devices that deliver controlled respiratory assistance to animals via precision tidal volume regulation, typically ranging across species from small companion animals to large equine patients. These systems integrate pressure-limited and volume-targeted modes to manage acute respiratory distress, post-surgical recovery, and anesthesia maintenance in clinical settings. Portable systems are capturing the fastest expansion as mobile emergency units and field veterinary services proliferate. Stationary units retain the dominant share of revenue due to their integration into intensive care wards at large animal hospitals. Research facilities represent a concentrated margin pool where customized configurations command premium positioning.
FDA's Center for Veterinary Medicine governs device safety and performance labeling, while ISO 80601-2-80 establishes international technical benchmarks for ventilator basic safety and essential performance. The EPA's energy efficiency directives are influencing power supply design choices for manufacturers selling into US clinical environments. Stakeholders must weigh regulatory compliance investments against the fragmentation of national certification requirements as they prioritize geographic expansion decisions.
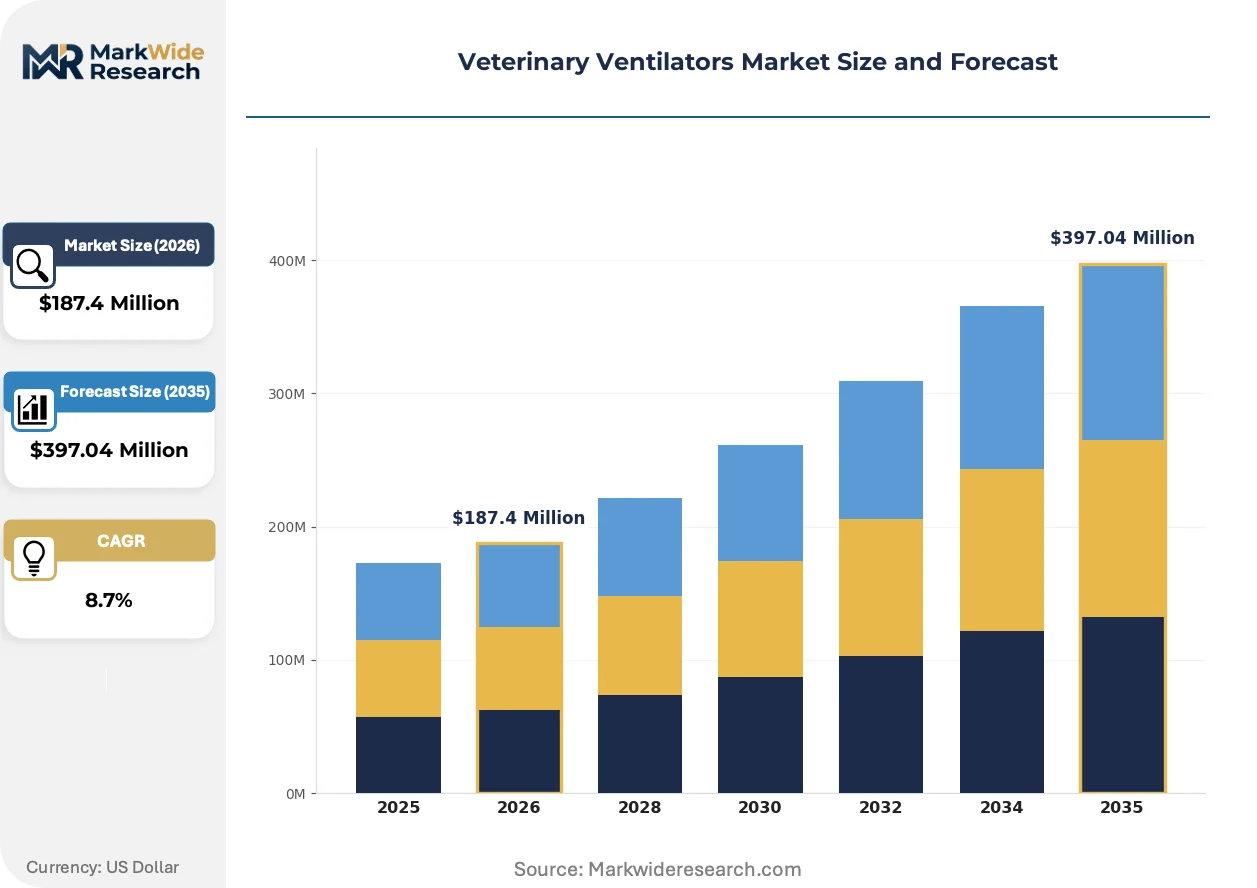
Market Dynamics
Polymer composite housings are compressing unit costs for mid-range ventilator lines while FDA Center for Veterinary Medicine oversight tightens quality thresholds for anesthesia-integrated systems entering US clinical channels.
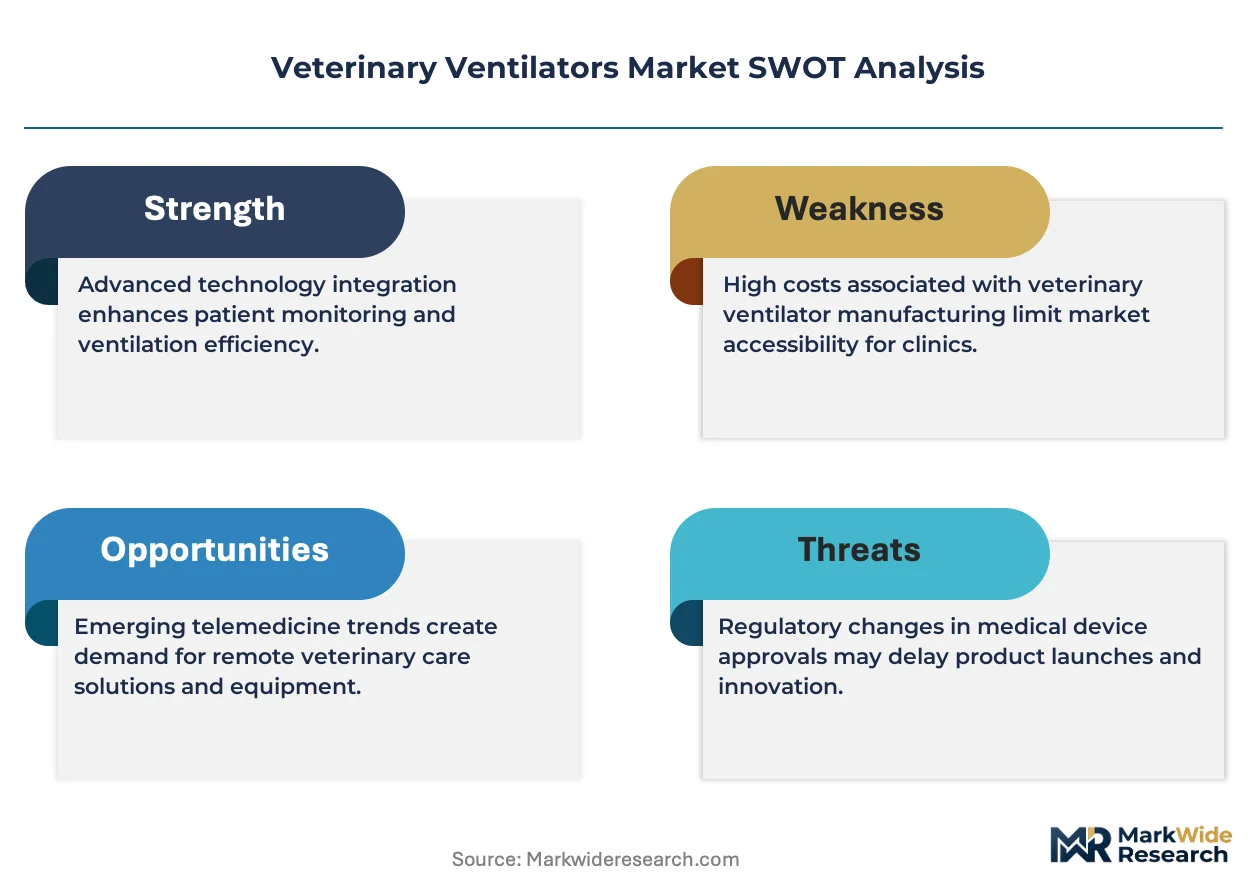
Growth Catalysts
- ISO 80601-2-80 harmonization:International safety benchmarks reduce certification friction for manufacturers expanding into European and Asia-Pacific veterinary markets.
- Emergency mobile units:Field veterinary services and disaster response teams drive portable system deployment across rural and remote service territories.
- Specialty hospital consolidation:Large animal hospital networks in the United States modernize intensive care wards, creating concentrated demand for stationary multi-mode ventilators.
Market Restraints
- Precision sensor supply concentration:Flow sensors and pressure transducers for tidal volume regulation depend on limited Asian component suppliers.
- FDA 510(k) pathway complexity:Novel software-controlled platforms face extended review timelines compared to predicate device clearances.
- Manual bag-valve-mask substitution:Cost-constrained small clinics retain manual resuscitation for routine anesthesia cases.
Strategic Opportunities
- Research facility customization:Preclinical toxicology and pharmaceutical testing centers command premium pricing for species-specific configurations.
- Telemedicine integration:Remote monitoring convergence with patient data networks enables subscription-based service models for distributed veterinary practices.
- EPA energy efficiency directives:Power supply redesign requirements create first-mover advantage for compliant manufacturers in US clinical environments.
Industry Challenges
- Veterinary critical care specialist shortage:Board-certified anesthesiologists and emergency clinicians remain scarce, limiting advanced ventilator utilization.
- Legacy device interoperability:Software platforms from prior hardware generations resist integration with modern patient monitoring networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Ventilators Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Multi-function, Anesthesia Application: Emergency Care, Intensive Care, Surgical Procedures, Respiratory Support End User: Veterinary Clinics, Animal Hospitals, Research Facilities, Zoos Technology: Mechanical Ventilation, Software-controlled, Manual, Gas Exchange |
| Companies Covered | MIDEN MEDICAL, Midmark Corporation, Vetronic Services Ltd., Hallowell EMC, Metran Co., Ltd., RWD Life Science Co., LTD, EICKEMEYER, VetEquip Inc., MINERVE Veterinary Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Ventilators Market Evolving Landscape
Connectivity architectures are transforming how respiratory assistance systems interface with broader clinical data infrastructure, compressing the gap between standalone devices and integrated care platforms.
Sensor fusion algorithms is unifying pressure, flow, and capnography inputs into single-control-loop ventilation management. Large specialty hospitals in the United States adopt these platforms fastest, consolidating vendor relationships around systems that synchronize with centralized monitoring stations. This convergence is unifying purchasing decisions that previously fragmented across anesthesia, ventilation, and monitoring suppliers.
EU Medical Device Regulation (MDR) classifies veterinary ventilators with human-equivalent software under stricter conformity assessment procedures. Manufacturers serving European markets must expand clinical evidence packages and notified body engagement timelines. Mid-range product lines face the steepest compliance cost increases as legacy technical documentation requires reconstruction.
Equipment leasing and managed service agreements are displacing capital purchase models among independent veterinary practices. Distributors in Germany and France now bundle preventive maintenance, software updates, and remote troubleshooting into per-procedure fees. This restructuring shifts working capital burdens from clinic owners to manufacturers while locking in multi-year supply relationships.
Veterinary Ventilators Market Segmentation
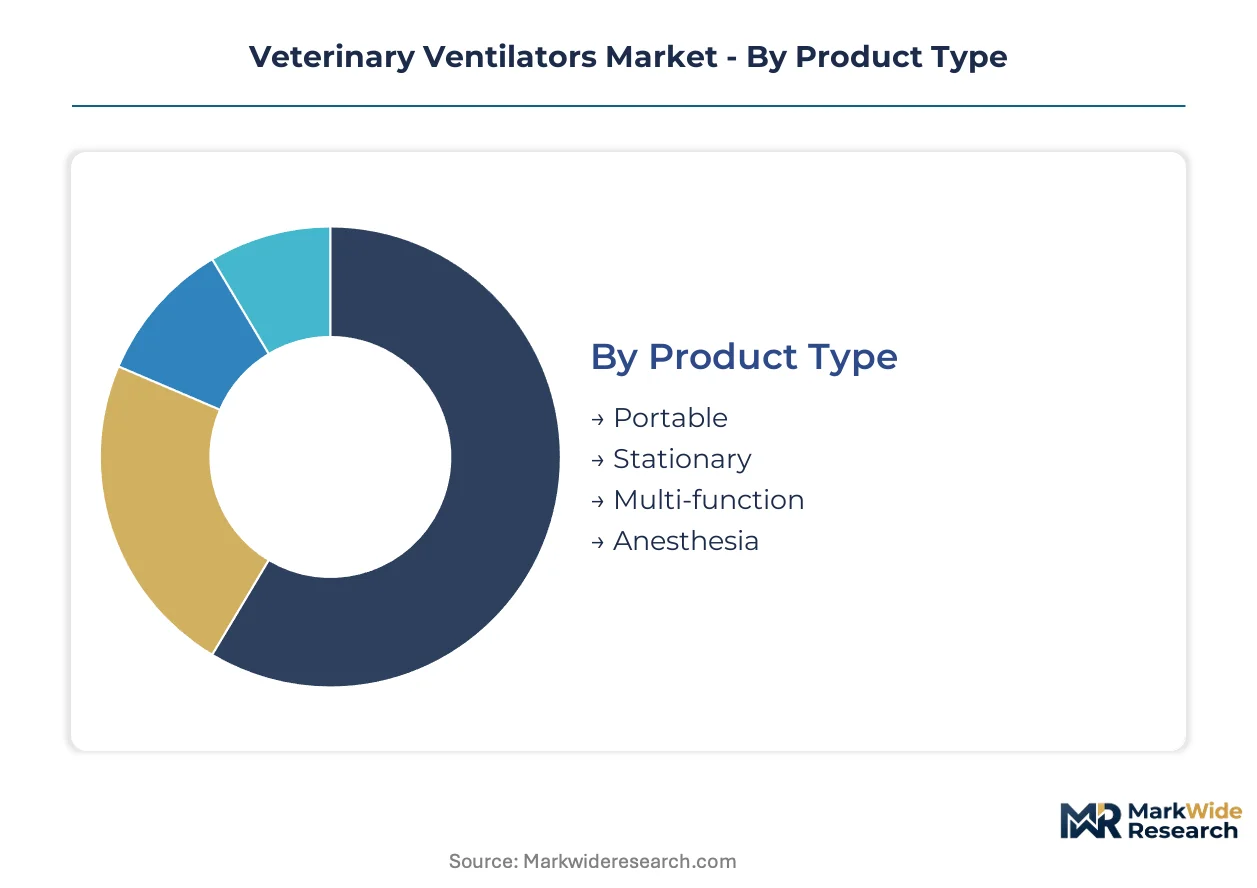
Veterinary ventilator segmentation reflects divergent integration strategies across clinical environments. Standalone emergency units demand rugged portability while anesthesia-integrated systems prioritize precision synchronization with surgical workflows.
Product Type:
Portable systems operate as field-deployable standalone units requiring battery autonomy and rapid setup protocols. Stationary configurations embed permanently into intensive care infrastructure with centralized gas supply integration.
- Portable:Battery-powered units with turbine-driven airflow achieve 4-8 hour operational autonomy for mobile emergency response. Demand clusters with field veterinary services and rural disaster response teams where grid-independent operation is mandatory.
- Stationary:Fixed-installation systems integrate with hospital gas manifold networks and centralized monitoring stations. Large animal hospital networks in the United States prioritize these configurations for 24-hour intensive care ward coverage.
- Multi-function:Modular platforms switch between volume-controlled, pressure-limited, and spontaneous breathing support modes.
- Anesthesia:Systems co-located with vaporizer circuits for surgical maintenance.
Volume placements concentrate in Stationary systems; the faster expansion belongs to Portable configurations.
Application:
Cost tier stratification separates high-acuity intervention from routine maintenance procedures. Emergency and intensive care applications command premium pricing through specialized monitoring capabilities.
- Emergency Care:Rapid-deployment ventilation for acute respiratory failure and trauma stabilization. Specialty animal hospital networks in the United States deploy these systems in dedicated triage bays with crash cart integration.
- Intensive Care:Prolonged mechanical support with weaning protocols for post-surgical recovery. Research facilities command premium configurations with species-specific tidal volume algorithms for toxicology studies.
- Surgical Procedures:Anesthesia maintenance with controlled ventilation during operative interventions.
- Respiratory Support:Chronic management of pneumonia, pulmonary edema, and neuromuscular conditions.
Revenue concentrates in Intensive Care applications; Emergency Care is climbing the fastest as specialty hospital consolidation accelerates.
End User:
Customer type determines procurement scale and service contract complexity. Institutional buyers negotiate multi-year managed service agreements while independent practices favor capital purchase or equipment leasing.
- Veterinary Clinics:Independent and small-group practices with limited critical care infrastructure.
- Animal Hospitals:Multi-specialty institutions with dedicated anesthesia and emergency departments. These facilities in the United States drive stationary ventilator procurement through intensive care ward modernization programs.
- Research Facilities:Preclinical testing centers requiring species-customizable configurations. Toxicology laboratories command premium pricing for GLP-compliant systems with validated software documentation.
- Zoos:Exotic and wildlife institutions with unique anatomical requirements for large mammals and avian species.
Procurement volume clusters with Animal Hospitals; Research Facilities deliver the steepest margin expansion.
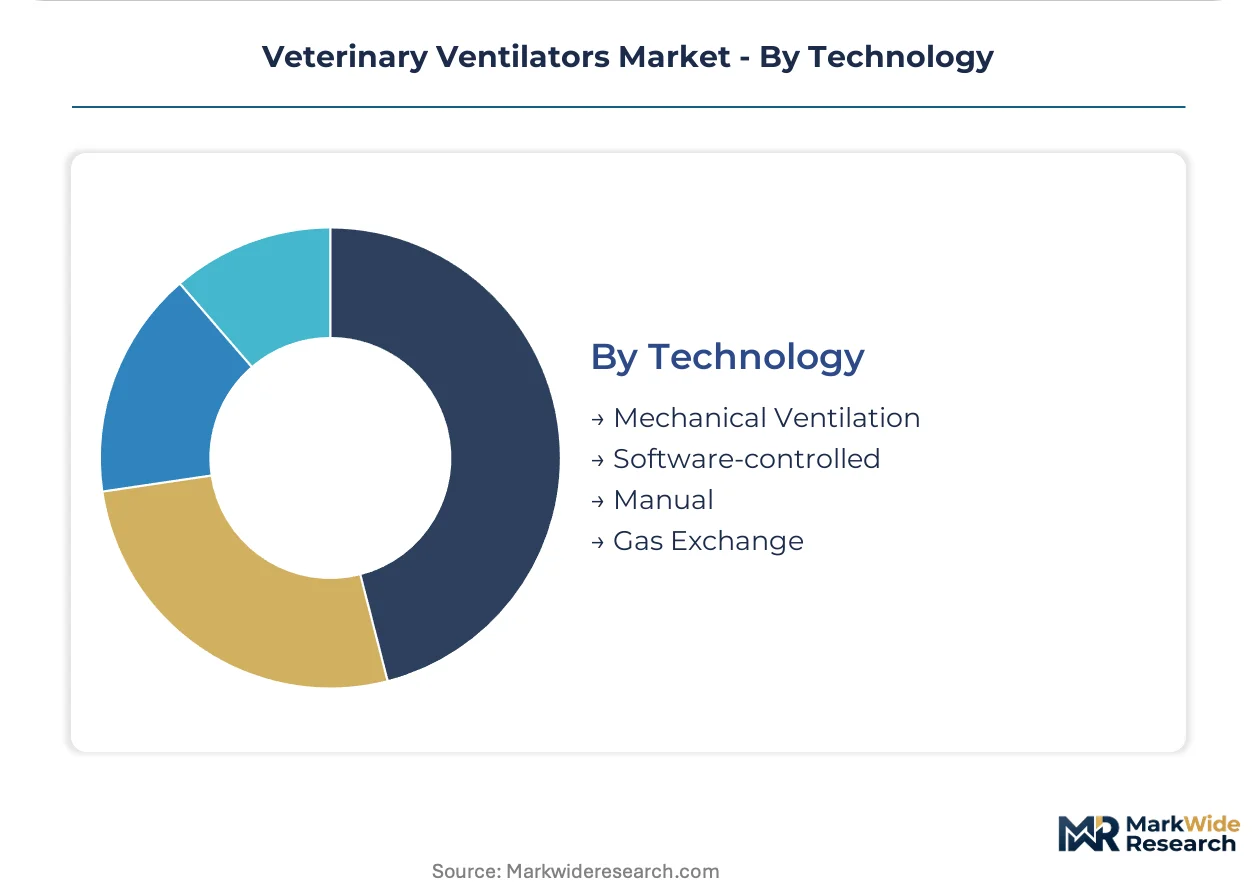
Technology:
Maturity gradients separate legacy pneumatic systems from digitally controlled platforms. Software integration depth determines interoperability with modern patient data networks.
- Mechanical Ventilation:Pneumatically driven systems with preset pressure and volume parameters. Cost-constrained small clinics retain these units for routine anesthesia maintenance where advanced monitoring is non-essential.
- Software-controlled:Microprocessor-regulated platforms with sensor fusion algorithms and remote monitoring capability. Large specialty hospitals adopt these fastest to synchronize with centralized patient data networks.
- Manual:Bag-valve-mask resuscitation without electromechanical assistance.
- Gas Exchange:Specialized systems for extracorporeal or advanced oxygenation support.
Installed base concentrates in Mechanical Ventilation; Software-controlled platforms are gaining share fastest through replacement cycles and new hospital construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States specialty animal hospital networks drive the highest procurement volumes for stationary intensive care ventilators. Germany's veterinary equipment distributors are pioneering managed service agreements that bundle maintenance with per-procedure fees. China's research facilities are scaling preclinical toxicology infrastructure requiring species-customizable configurations.
United States
Large animal hospital networks in Texas and California are modernizing intensive care wards with multi-mode stationary systems. FDA Center for Veterinary Medicine oversight tightens quality thresholds for anesthesia-integrated platforms entering clinical channels. The Research Triangle Park corridor in North Carolina concentrates toxicology laboratories commanding premium GLP-compliant ventilator configurations.
Germany
Independent veterinary practices in Bavaria and North Rhine-Westphalia are shifting from capital purchases to equipment leasing models. EU Medical Device Regulation classifies software-controlled veterinary ventilators under stricter conformity assessment procedures. The Stuttgart industrial cluster hosts precision sensor suppliers serving tidal volume regulation component needs.
China
Preclinical pharmaceutical testing centers in Shanghai and Beijing are expanding toxicology study capacity requiring validated software documentation. NMPA alignment with ISO 80601-2-80 standards accelerates domestic manufacturer certification timelines. The Suzhou biomedical manufacturing zone is attracting ventilator assembly operations serving Asia-Pacific research facility demand.
Japan
Companion animal emergency clinics in Tokyo and Osaka are adopting portable systems for mobile veterinary services. METI energy efficiency guidelines influence power supply design choices for clinical equipment manufacturers. The Nagoya medical device cluster specializes in compact anesthesia-integrated ventilation platforms for specialty hospitals.
United Kingdom
University veterinary teaching hospitals in London and Edinburgh are replacing legacy pneumatic systems with software-controlled platforms. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical benchmarks for device safety. The Cambridge life sciences corridor concentrates contract research organizations driving research facility ventilator procurement.
Veterinary Ventilators Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with anesthesia-integrated system suppliers commanding premium positioning against mid-range portable fabricators. The vendor base organizes into three tiers: full-suite critical care platform providers, compact emergency unit specialists, and research facility customization houses. Strategic consolidation concentrates around distribution network expansion and software platform interoperability capabilities.
Among North American clinical furniture specialists, Midmark Corporation exemplifies scale-driven distribution reach into veterinary suites. Hallowell EMC occupies a position within the compact anesthesia-integrated systems archetype. Vetronic Services Ltd. represents the software-controlled platform tier that synchronizes with patient monitoring networks.
| Leading Market Players |
|---|
| MIDEN MEDICAL |
| Midmark Corporation |
| Vetronic Services Ltd. |
| Hallowell EMC |
| Metran Co., Ltd. |
| RWD Life Science Co., LTD |
| EICKEMEYER |
| VetEquip Inc. |
| MINERVE Veterinary Equipment |
| Others |
Value Network & Pricing Analysis
Specialty animal hospital networks in the United States anchor procurement volume and enforce contract-based long-term offtake agreements that compress margins for mid-range portable fabricators while rewarding anesthesia-integrated system suppliers with premium positioning.
Pricing Analysis
Volume concentrates in stationary intensive care configurations while margin expansion accrues to software-controlled platforms with telemedicine integration capabilities. Pricing stratifies across premium anesthesia-integrated tiers, standard multi-mode stationary systems, and economy mechanical ventilation lines differentiated by FDA 510(k) clearance tier and ISO 80601-2-80 certification depth. Cost compression in mid-range portable units is intensifying because polymer composite housing adoption reduces bill-of-materials overhead. Independent veterinary clinics exhibit highest price sensitivity, whereas research facilities demonstrate lowest sensitivity due to GLP compliance requirements and species-customization premiums.
Supply Chain Analysis
Trans-Pacific freight volatility elevates landed costs for precision flow sensors and pressure transducers sourced from Taiwanese and South Korean component specialists. Final assembly concentrates in the United States, Germany, and China, with the Suzhou biomedical manufacturing zone capturing expanding Asia-Pacific research facility demand. Raw material dependencies span medical-grade polymer composites, precision-machined aluminum housings, and microprocessor-controlled turbine assemblies. Single-source vulnerability in Asian sensor suppliers creates procurement risk for tidal volume regulation subsystems. Distribution runs through veterinary equipment distributors in Germany and France pioneering managed service agreements, alongside direct hospital system contracts in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary ventilator economics function as a cost-of-compliance story where FDA Center for Veterinary Medicine oversight and EU MDR conformity assessment procedures erect regulatory moats favoring incumbent manufacturers with established clinical evidence packages and notified body relationships.
For Market Incumbents: Deploy software platform interoperability as the primary defensive lever. Consolidate vendor relationships with large animal hospital networks by synchronizing ventilation systems with centralized patient monitoring networks, neutralizing emerging entrants lacking legacy device integration capabilities. Deepen backward integration into precision sensor supply chains to mitigate Asian component concentration risk and secure tidal volume regulation subsystems against supply disruption.
For New Entrants and Emerging Players: Enter via research facility customization as the most penetrable white-space target, where GLP-compliant system requirements and species-specific configuration demands deter mass-market competitors. Target preclinical toxicology laboratories in the Research Triangle Park corridor and Shanghai pharmaceutical testing centers with validated software documentation and premium positioning. Pursue telemedicine-enabled subscription service models for distributed veterinary practices as the go-to-market angle, displacing capital purchase friction with per-procedure fee structures.
For Investors and Strategic Acquirers: The window for entry favors software-controlled platform specialists with FDA 510(k) clearance momentum and EU MDR technical documentation readiness. Long-term viability hinges on consolidation of anesthesia-integrated system capabilities with remote monitoring convergence, capturing multi-year managed service agreement recurring revenue streams. Monitor FDA review timeline compression for novel software-controlled platforms as the inflection signal indicating regulatory pathway predictability and reduced compliance friction for compliant players.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Reduces time-to-market for software-controlled platforms entering US clinical channels. |
| EU MDR Conformity Assessment Investment | Expands clinical evidence packages for veterinary ventilators with human-equivalent software classification. |
| Hospital System Partnership Development | Locks in multi-year supply relationships with large animal hospital networks modernizing intensive care wards. |
| Telemedicine Platform Integration | Enables subscription-based service models for distributed veterinary practices seeking operational flexibility. |
| Precision Sensor Supply Agreement | Secures tidal volume regulation components against Asian supplier concentration risk. |
Research Methodology
SEC filings, FDA 510(k) clearance databases, and ISO 80601-2-80 technical documentation formed the secondary backbone, supplemented by customs records tracking veterinary equipment trade flows. Primary interviews with veterinary critical care specialists, biomedical engineers at specialty animal hospitals, GPO contracts managers, and regulatory affairs leads at device manufacturers validated demand assumptions and procurement pattern shifts. Bottom-up and top-down triangulation reconciled unit placement data with revenue estimates across the projection horizon.
Bottom-up modeling segmented the market by product type, application, end user, and technology maturity, while top-down analysis cross-validated against macro veterinary care expenditure trends. CAGRs were derived from replacement cycle dynamics, new hospital construction pipelines, and software-controlled platform adoption curves. Forecast inputs incorporated EPA energy efficiency directive compliance timelines and EU MDR transition deadlines affecting manufacturer certification investments.
Revisions become necessary when FDA review timeline extensions, precision sensor supply disruptions, or veterinary critical care specialist shortage intensification materialize beyond modeled assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Chemotherapy Infusion Pumps Market
Medical Devices
Global Disability Devices Market
Medical Devices
PC-Based Resting Electrocardiograph Market
Medical Devices
Ultrasonic Skin Care Devices Market
Medical Devices
Buccal Drug Delivery System Market
Medical Devices
Hydrogel Contact Lenses Market
Medical Devices
Global Total Wrist Replacement Market
Medical Devices
Actigraphy Sensors & PSG Devices Market
Medical Devices
Heart Closure Devices Market
Medical Devices
Global Spirometers Market
Medical Devices
Implantable Neurostimulators Market
Medical Devices
Veterinary X-Ray Illuminators Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market
Medical Devices
Anterior Cervical Fixation Devices Market
Medical Devices
Non-Destructive Medical Technologies Market
Medical Devices
Global Anastomosis Devices Market