
 Eye Examination Equipment Market | 2026-2036
Eye Examination Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Eye Examination Equipment Market Analytics
The EU MDR is hardening conformity assessment pathways for Class IIa and IIb ophthalmic diagnostic devices, compelling manufacturers to expand clinical validation portfolios. Carl Zeiss Meditec AG leverages its captive optics foundry to sustain margin structures amid rising notified body fees. EssilorLuxottica anchors its equipment division through vertical control over lens-finishing workflows that bind examination hardware to consumable revenue streams. Alcon competes by dominating the cataract diagnostic-to-surgical continuum across integrated practice networks.
Eye examination equipment encompasses optoelectronic and mechanical instruments engineered to measure refractive error, intraocular pressure, visual field boundaries, and retinal morphology, typically resolving structures at 5-10 micron precision through confocal scanning or interferometric methods. These systems serve primary care screening, disease staging, and surgical planning across ophthalmology and optometry practices. Optical Coherence Tomography systems command the deepest margin pools due to software-locked consumables and subscription-based image analytics, while Digital Imaging platforms extend fastest into tele-ophthalmology workflows serving rural optical centers. Fundus Cameras retain volume leadership in diabetic retinopathy screening programs where portability and lower per-unit cost enable population-scale deployment.
The FDA's Quality System Regulation shapes device design controls and post-market surveillance for US-bound manufacturers, while ISO 13485 certification remains the baseline predicate for CE marking under the EU MDR framework. Japan's PMDA enforces distinct clinical evidence standards that delay market entry for novel wavefront aberrometry platforms. Stakeholders must monitor evolving harmonization gaps between FDA digital health guidance and EU AI Act risk classifications for autonomous diagnostic algorithms.
Market Dynamics
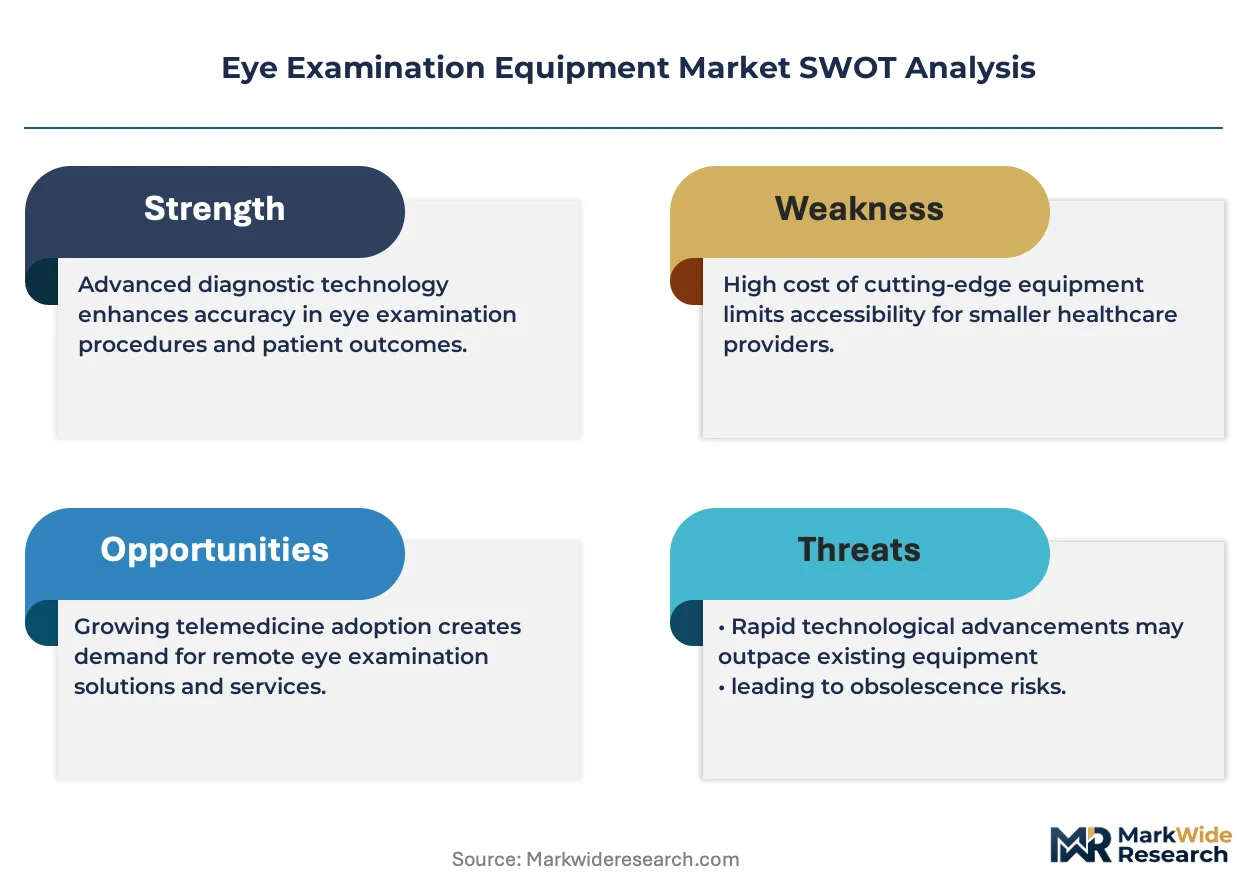
The EU MDR conformity assessment tightening is forcing ophthalmic diagnostic manufacturers to restructure clinical validation pipelines and absorb elevated notified body fees, compressing margin structures for mid-tier instrument suppliers while favoring vertically integrated producers with captive testing infrastructure.
Growth Catalysts
- Automated refraction systems:Hospital procurement across Germany and France is accelerating replacement cycles for legacy manual phoropters, driven by workflow efficiency mandates in university hospital networks.
- EU MDR Article 10:The regulation's tightened clinical evidence requirements for Class IIb devices is paradoxically strengthening incumbent positions by raising entry barriers for new market entrants.
- Tele-ophthalmology infrastructure:Rural optical centers in Spain and Italy are deploying portable fundus cameras with cloud connectivity to serve diabetic retinopathy screening programs at population scale.
Market Restraints
- Optical component concentration:Precision lens and interferometer element production concentrates in German and Swiss optics clusters, creating single-source vulnerability for OCT system manufacturers.
- Notified body capacity:The EU MDR transition has reduced active ophthalmic device notified bodies from twelve to four, extending certification timelines by fourteen to eighteen months.
- Software-locked consumables:Proprietary OCT imaging cartridges and analytics subscriptions lock buyers into vendor ecosystems, limiting price competition and secondary market liquidity.
Strategic Opportunities
- AI diagnostic algorithms:The EU AI Act's risk classification framework for autonomous diagnostic software creates first-mover advantage for manufacturers with pre-validated clinical evidence portfolios.
- Point-of-care integration:Convergence of wavefront aberrometry with smartphone-based screening tools opens primary care physician offices as a new channel previously served only by optometrists.
- Poland and Romania:Underpenetrated retinal imaging infrastructure in these EU member states presents volume opportunity as EU structural funds modernize regional hospital equipment.
Industry Challenges
- Clinical validation talent:Scarcity of ophthalmic biostatisticians and MDR technical file specialists is extending product development cycles and inflating regulatory consulting costs.
- Legacy system interoperability:Integration of new OCT platforms with existing hospital PACS and EMR architectures requires custom middleware development, complicating deployment timelines.
- ISO 13485 transition:The 2016 standard revision's risk management emphasis demands documentation overhauls that strain quality assurance departments at smaller instrument manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eye Examination Equipment Market |
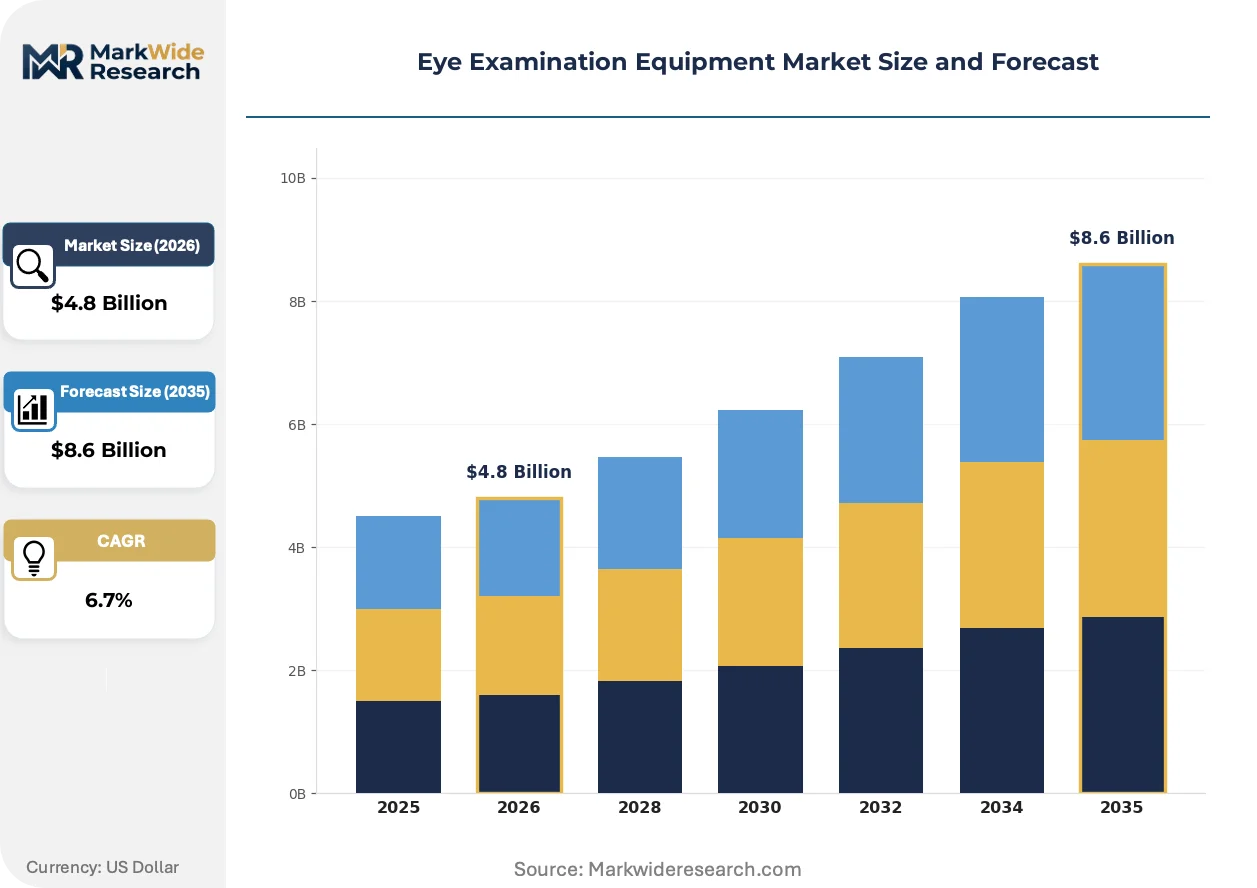
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ophthalmoscopes, Retinoscopes, Tonometers, Perimeters Technology: Digital Imaging, Optical Coherence Tomography, Wavefront Aberrometry, Fundus Cameras End User: Clinics, Hospitals, Research Laboratories, Optical Centers Application: Vision Screening, Glaucoma Detection, Cataract Assessment, Diabetic Retinopathy Diagnosis |
| Companies Covered | Carl Zeiss Meditec AG, EssilorLuxottica, Alcon, Topcon Corporation, Bausch Health Companies, Haag-Streit Holding AG, Nidek Co., Ltd., Johnson & Johnson Vision, Heidelberg Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eye Examination Equipment Market Evolving Landscape
Wavefront-guided diagnostic platforms are compressing the traditional separation between refraction measurement and surgical planning, enabling same-visit diagnostic-to-treatment workflows that reshape practice economics.
Spectral-domain OCT is consolidating retinal imaging market architecture by displacing time-domain systems through superior axial resolution and faster acquisition speeds. German university hospitals are completing fleet replacements within compressed eighteen-month windows. The technology is consolidating vendor market share around suppliers with integrated software-analytics ecosystems.
The EU AI Act's high-risk system classification for autonomous diagnostic algorithms is reshaping clinical evidence requirements for OCT interpretation software. Manufacturers must now submit prospective validation studies to notified bodies before CE marking. Retinal disease screening platforms face the steepest compliance burden, with several vendors pivoting to physician-assist rather than autonomous positioning.
Service unbundling is fragmenting traditional equipment procurement patterns in European optometry chains. Buyers are separating hardware acquisition from maintenance contracts and image analytics subscriptions, forcing manufacturers to defend recurring revenue through standalone software performance rather than hardware lock-in. This pattern is most pronounced in the Netherlands and Belgium where optical retail consolidation has concentrated buyer negotiating power.
Eye Examination Equipment Market Segmentation
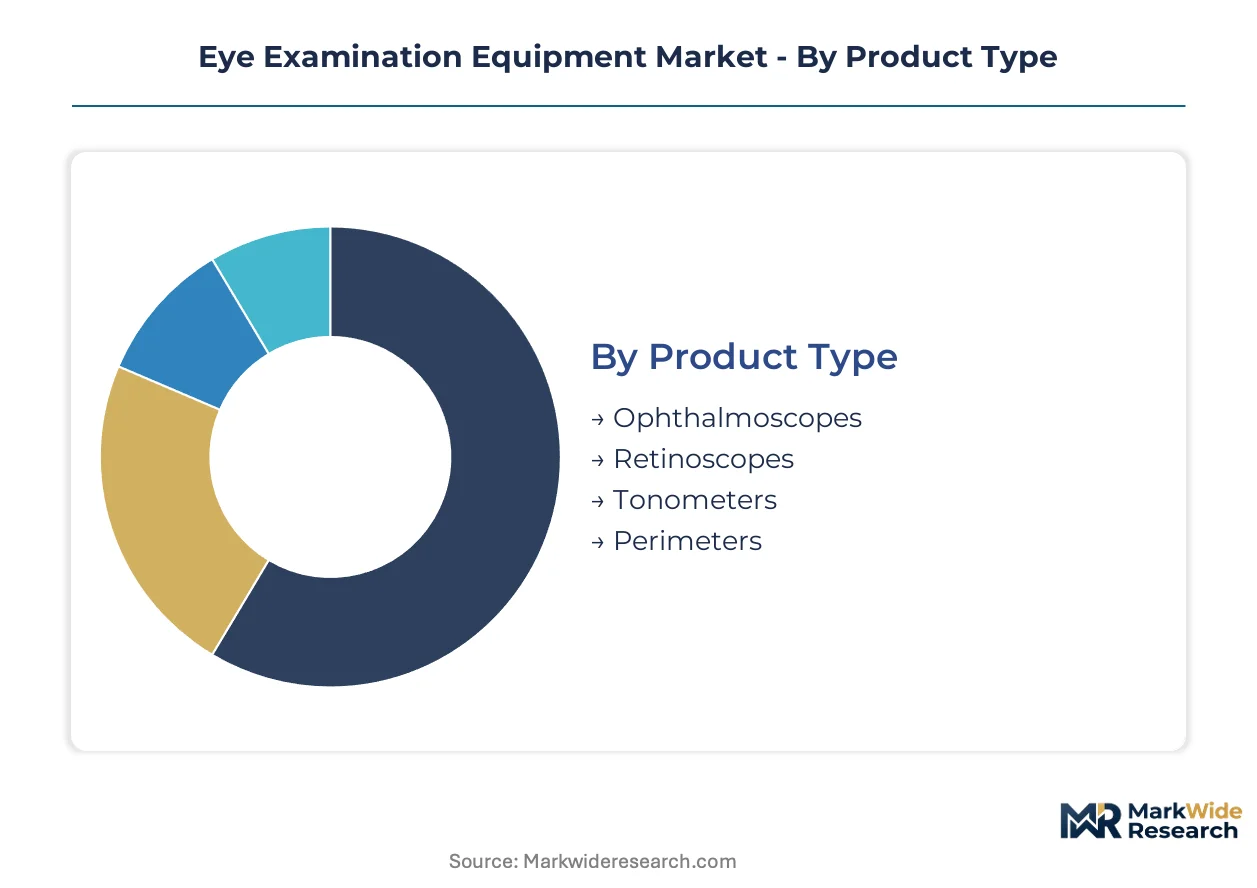
Equipment segmentation in ophthalmic diagnostics determines regulatory pathway complexity and procurement economics. Certification requirements vary sharply across product categories, with imaging systems facing stricter clinical evidence burdens than mechanical instruments.
Product Type:
EU MDR Class IIa classification covers manual diagnostic instruments, while Class IIb governs automated systems requiring notified body intervention. FDA 510(k) predicates differ substantially across mechanical versus optoelectronic categories.
- Ophthalmoscopes:Handheld devices employing direct or indirect illumination to visualize the fundus, typically operating at 5-20 diopter compensation range. German university hospitals are standardizing on LED-equipped models for reduced maintenance cycles in high-throughput screening programs.
- Retinoscopes:Instruments projecting a light streak onto the retina to objectively determine refractive error through neutralization techniques. Demand concentrates in French optometry training institutions modernizing didactic equipment fleets, constrained by procurement budget freezes in public health systems.
- Tonometers:Applanation and rebound variants measuring intraocular pressure for glaucoma screening.
- Perimeters:Automated static and kinetic systems mapping visual field defects.
Ophthalmoscopes sit at the top of the volume ranking, with tonometers climbing the fastest.
Technology:
Cost tier stratification separates premium subscription-locked platforms from capital-light hardware, reshaping customer acquisition economics across installation scales.
- Digital Imaging:CCD and CMOS sensor-based systems capturing anterior and posterior segment pathology at 12-24 megapixel resolution. Rural optical centers in Spain are deploying portable configurations for diabetic retinopathy screening programs, enabled by cloud connectivity subsidies from regional health authorities.
- Optical Coherence Tomography:Interferometric systems achieving 5-7 micron axial resolution through spectral-domain detection. German retinal clinics are consolidating vendor relationships around integrated software-analytics ecosystems, driven by reimbursement coding changes favoring quantitative biomarker reporting.
- Wavefront Aberrometry:Hartmann-Shack sensor arrays measuring higher-order optical aberrations for refractive surgery planning.
- Fundus Cameras:Non-mydriatic and mydriatic configurations for retinal photography.
Fundus cameras retain volume leadership across all technology tiers, while digital imaging platforms gain share fastest in tele-ophthalmology deployments.
End User:
Customer type dictates procurement modality, with hospital networks favoring capital leases and optical centers preferring outright purchase with unbundled service contracts.
- Clinics:Independent ophthalmology practices and group practices serving diagnostic and monitoring functions. Clinic procurement in Italy is fragmenting across regional purchasing consortia, complicating vendor contract negotiations.
- Hospitals:University medical centers and district general hospitals with integrated surgical departments. Hospital replacement cycles in France are compressing to eighteen-month windows for retinal imaging fleets, driven by EU structural fund availability.
- Research Laboratories:Academic and commercial R&D facilities requiring specialized imaging modalities.
- Optical Centers:Retail optometry chains and independent practices focusing on refraction and screening.
Optical centers command the highest unit volume, with hospitals generating the steepest revenue per installation.
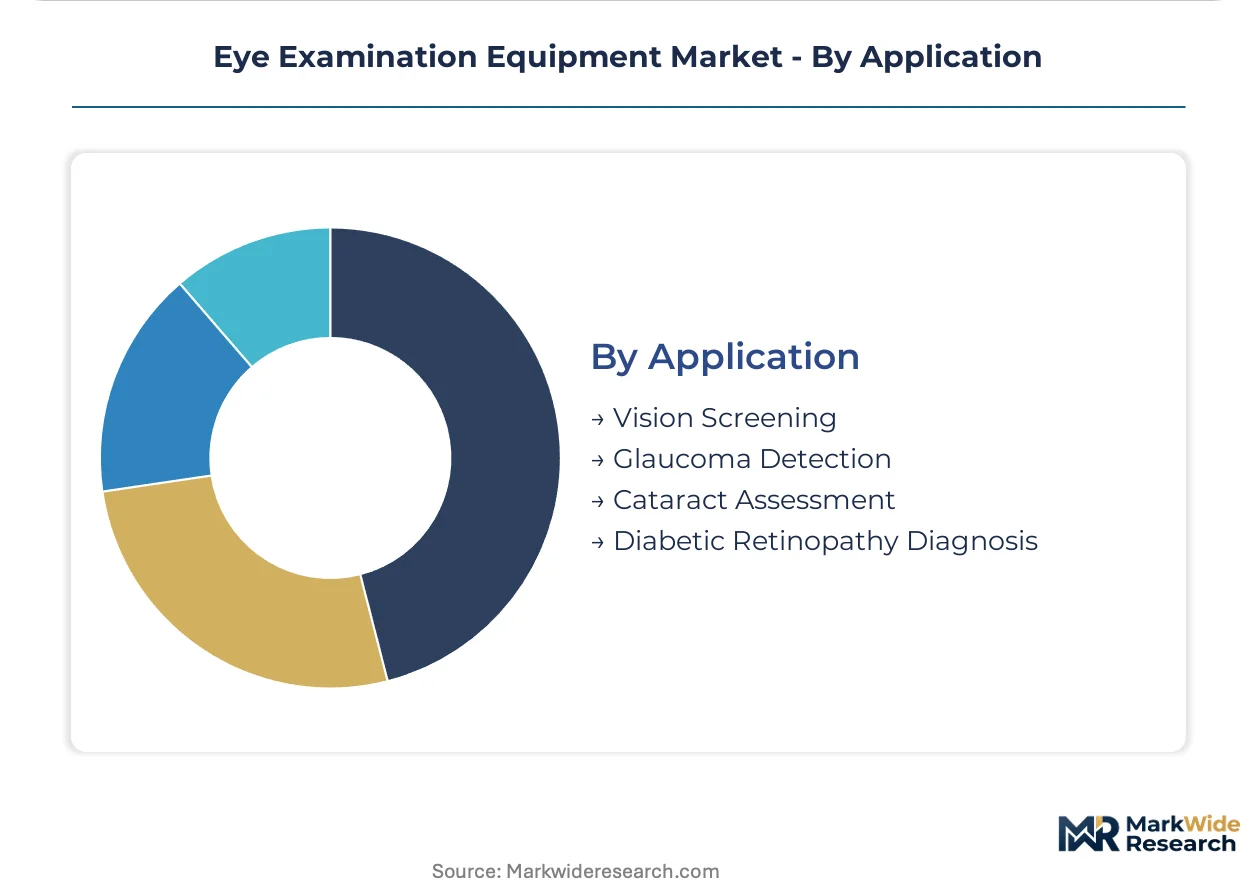
Application:
Clinical use case determines device specification requirements and reimbursement eligibility, with population screening programs driving distinct form factor demands from surgical planning applications.
- Vision Screening:Refractive error assessment and amblyopia detection in pediatric and adult populations. School-based screening mandates in Poland are accelerating automated photorefractor deployment, constrained by ophthalmologist shortage for confirmatory examinations.
- Glaucoma Detection:Intraocular pressure measurement, optic nerve imaging, and visual field analysis for disease staging. Glaucoma diagnostic workflows in Dutch hospital networks are integrating OCT ganglion cell analysis with traditional perimetry, responding to payer preference for structural-functional correlation.
- Cataract Assessment:Lens opacity grading and biometry for surgical planning.
- Diabetic Retinopathy Diagnosis:Microaneurysm detection and disease severity classification for population health management.
Vision screening generates the highest procedure volume, with diabetic retinopathy diagnosis expanding most quickly through national screening program scale-up.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision optics manufacturing for ophthalmic diagnostics during the late nineteenth century, establishing Jena and Oberkochen as foundational clusters where Zeiss and Leica scaled interferometric and photographic instruments. This heritage continues to shape equipment procurement patterns across university hospital networks.
Germany
University hospitals in Heidelberg, Tübingen, and Munich are completing eighteen-month replacement cycles for spectral-domain OCT fleets. The EU MDR's tightened Article 10 clinical evidence requirements favor domestic manufacturers with captive notified body relationships. The Mittelstand optics cluster around Wetzlar supplies precision interferometer elements to system integrators.
United States
Integrated practice networks in Texas and Florida are consolidating cataract diagnostic-to-surgical workflows under single-vendor contracts. FDA Quality System Regulation enforcement shapes design control documentation for software-locked consumable platforms. The Boston-Cambridge corridor hosts venture-backed wavefront aberrometry developers targeting physician-assist AI positioning.
Japan
PMDA clinical evidence standards delay market entry for novel autonomous diagnostic algorithms, protecting incumbent positions in retinal imaging. Tokyo and Osaka metropolitan hospitals favor domestic tonometer and perimeter manufacturers for maintenance responsiveness. Yokohama-based precision mechanics suppliers provide applanation sensor subassemblies.
France
Regional health authorities in Île-de-France and Provence-Alpes-Côte d'Azur subsidize cloud-connected fundus camera deployment for diabetic retinopathy screening. ANSM post-market surveillance requirements align with EU MDR implementation timelines. The Lyon biotech corridor hosts ophthalmic software analytics startups seeking CE marking for AI-assisted OCT interpretation.
China
NMPA innovation pathway approvals accelerate for domestic spectral-domain OCT systems targeting county hospital tier procurement. Provincial medical insurance bureaus in Guangdong and Jiangsu are expanding reimbursement for glaucoma screening devices. The Suzhou industrial park concentrates CCD sensor and optical coating suppliers serving equipment assemblers.
Eye Examination Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across software-analytics integration depth, with the former capturing recurring revenue through locked consumable ecosystems while the latter compete on capital equipment price. The vendor base stratifies into three tiers: integrated optics-to-software conglomerates with captive foundry capacity; mid-scale specialists concentrated in German and Japanese precision mechanics clusters; and emerging Asian assemblers leveraging component cost advantages. Dominant competitive moves include backward integration into optical element production and strategic partnerships with cloud infrastructure providers for tele-ophthalmology deployment.
Within the integrated conglomerate tier, Carl Zeiss Meditec AG and EssilorLuxottica exemplify divergent margin defense strategies—Zeiss through captive optics foundry control and EssilorLuxottica through vertical binding of examination hardware to lens-finishing consumable streams. Alcon occupies a position bridging diagnostic and surgical continuum dominance across North American integrated practice networks. These three entities represent distinct archetypes: precision optics heritage, retail-optical vertical integration, and surgical workflow convergence.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| EssilorLuxottica |
| Alcon |
| Topcon Corporation |
| Bausch Health Companies |
| Haag-Streit Holding AG |
| Nidek Co., Ltd. |
| Johnson & Johnson Vision |
| Heidelberg Engineering |
| Others |
Value Network & Pricing Analysis
Hospital procurement consolidation in Germany and France is forcing instrument manufacturers to absorb extended payment terms and unbundle service contracts, compelling supply chain restructuring toward modular component sourcing that compresses margin structures for mid-tier assemblers.
Pricing Analysis
Subscription-locked SaaS pricing for OCT analytics platforms dominates premium tiers, while transactional per-unit sales govern fundus camera and manual instrument segments. Price differentiation rests on CE marking tier under EU MDR Article 10 and captive optics foundry ownership. Cost compression in mid-tier automated refraction systems is intensifying because notified body fees have tripled since MDR implementation. Optical centers exhibit highest price sensitivity due to unbundled procurement patterns, whereas university hospital networks prioritize software integration depth over capital cost.
Supply Chain Analysis
Precision optics technician shortages in Wetzlar and Jena constrain interferometer element throughput for spectral-domain OCT manufacturers. Geographic supply concentration centers on Germany, Switzerland, and Japan for applanation sensor subassemblies and Hartmann-Shack microlens arrays. Raw material dependencies include specialty optical glass from Schott AG, CMOS sensors from Japanese fabs, and precision ball screws from Swiss machine shops. Single-source vulnerability in LED illumination modules creates tariff exposure risk from East Asian component feeders. Distribution runs through hospital GPO contracts in North America and regional purchasing consortia across EU member states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage value through Poland and Romania, where EU structural fund availability meets underpenetrated retinal imaging infrastructure and lower clinical validation labor costs versus Western European benchmarks.
For Market Incumbents: Acquire captive clinical validation capabilities and notified body consulting capacity to defend margin structures against EU MDR compliance cost inflation. Secure backward integration into precision interferometer element production to reduce exposure to German optics cluster bottlenecks. Prioritize software-analytics ecosystem lock-in over hardware margin defense as service unbundling accelerates in Benelux optical retail chains. For New Entrants and Emerging Players: Enter via physician-assist AI positioning for OCT interpretation software to sidestep EU AI Act high-risk system classification burdens facing autonomous diagnostic algorithms. Target diabetic retinopathy screening programs in Spanish and Italian rural optical centers as the most penetrable deployment channel. Pursue cloud infrastructure partnerships with regional health authority subsidy programs rather than direct hospital capital sales cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale wavefront aberrometry developers possessing pre-validated clinical evidence portfolios and PMDA Japan market entry pathways. Long-term viability hinges on convergence toward same-visit diagnostic-to-surgical workflow platforms across integrated practice networks. Monitor EU notified body capacity expansion announcements as the critical inflection signal for certification timeline compression and mid-tier manufacturer distress opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR Article 10 compliance secures hospital procurement eligibility in German university networks. |
| Hospital System Partnership | Single-vendor cataract diagnostic-to-surgical contracts lock out competitors across Texas and Florida IPNs. |
| Software Companion Development | Cloud-connected image analytics subscriptions defend recurring revenue against hardware unbundling trends. |
| Backward Integration into Optics | Captive interferometer element production insulates margin from Wetzlar cluster capacity constraints. |
| Reimbursement Strategy | Quantitative biomarker reporting codes in German retinal clinics drive OCT fleet replacement decisions. |
Research Methodology
Direct dialogue with hospital purchasing committee members, biomedical engineers at university medical centers, GPO contracts managers, ophthalmic device regulatory consultants, and optical center chain procurement directors grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, EU MDR notified body guidance documents, hospital procurement database records, and CMS Medicare reimbursement schedules. Bottom-up instrument shipment estimates and top-down healthcare capital expenditure patterns were triangulated to cross-validate market sizing.
Bottom-up modeling segmented volume and value across product type, technology tier, end-user category, and application use case throughout the forecast period. Analytical frameworks incorporated replacement cycle dynamics for spectral-domain OCT fleets, EU structural fund disbursement timelines, and tele-ophthalmology subsidy program scale-up trajectories. CAGRs were derived from fitted adoption curves weighted by reimbursement code changes and regulatory pathway complexity differentials.
Inputs from hospital procurement databases and notified body certification records were available through the study window; gaps in real-time optical component inventory data introduce uncertainty bands around near-term shipment estimates. Forecasts reflect documented assumptions regarding MDR transition completion timelines and AI Act implementation pacing. Material deviation in notified body capacity expansion or EU structural fund allocation triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Alexandrite Gemstone Lasers Market
Medical Devices
Ankle Syndesmosis Treatment Devices Market
Medical Devices
Global Surgical Microscopes Market
Medical Devices
Global Medical Device Security Market
Medical Devices
Smart Medical Devices Market
Medical Devices
Global Patient Warming Systems Market
Medical Devices
South Korea Drug Delivery Devices Market
Medical Devices
Drug Device Combination Products Market
Medical Devices
Europe Ultrasound Devices Market
Medical Devices
Wireless Portable Medical Devices Market
Medical Devices
Chest Drainage System Market
Medical Devices
MRI Safe Biopsy Needle Market
Medical Devices
Implantable Pulse Generator Market
Medical Devices
Japan Anesthesia Devices Market
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
Digital Reading Micropipettes Market