
 Acoustic Puncture Assist Devices Market | 2026-2036
Acoustic Puncture Assist Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustic Puncture Assist Devices Market Outlook
Precision-guided needle insertion standards are rotating toward higher-accuracy tiers as clinicians demand reduced complication rates in spinal and vascular access. Becton Dickinson leverages integrated ultrasound compatibility across its vascular access portfolio to sustain premium positioning. Teleflex anchors its competitive stance through specialized epidural and regional anesthesia needle sets. Smiths Medical differentiates via MRI-compatible device configurations for neurosurgical applications.
Acoustic puncture assist devices employ real-time audio feedback or ultrasonic wave detection to confirm needle tip position during percutaneous procedures, typically operating at frequencies between 2-15 MHz for tissue differentiation. These systems reduce inadvertent vessel or nerve puncture during epidural anesthesia, lumbar puncture, and central line placement. Automated devices command the strongest margin pools due to sensor fusion complexity and software validation requirements, while disposable devices expand volume through infection control mandates in hospital settings. Ultrasound-guided technology leads procedure adoption in cardiovascular and emergency medicine applications where real-time visualization proves critical.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation shape product development timelines and clinical evidence requirements for acoustic guidance systems. The EPA and OSHA maintain indirect influence through sterilization chemical standards and healthcare worker safety protocols affecting device reprocessing. Stakeholders must monitor evolving reimbursement codes for image-guided needle placement as payors recalibrate coverage for precision intervention technologies.
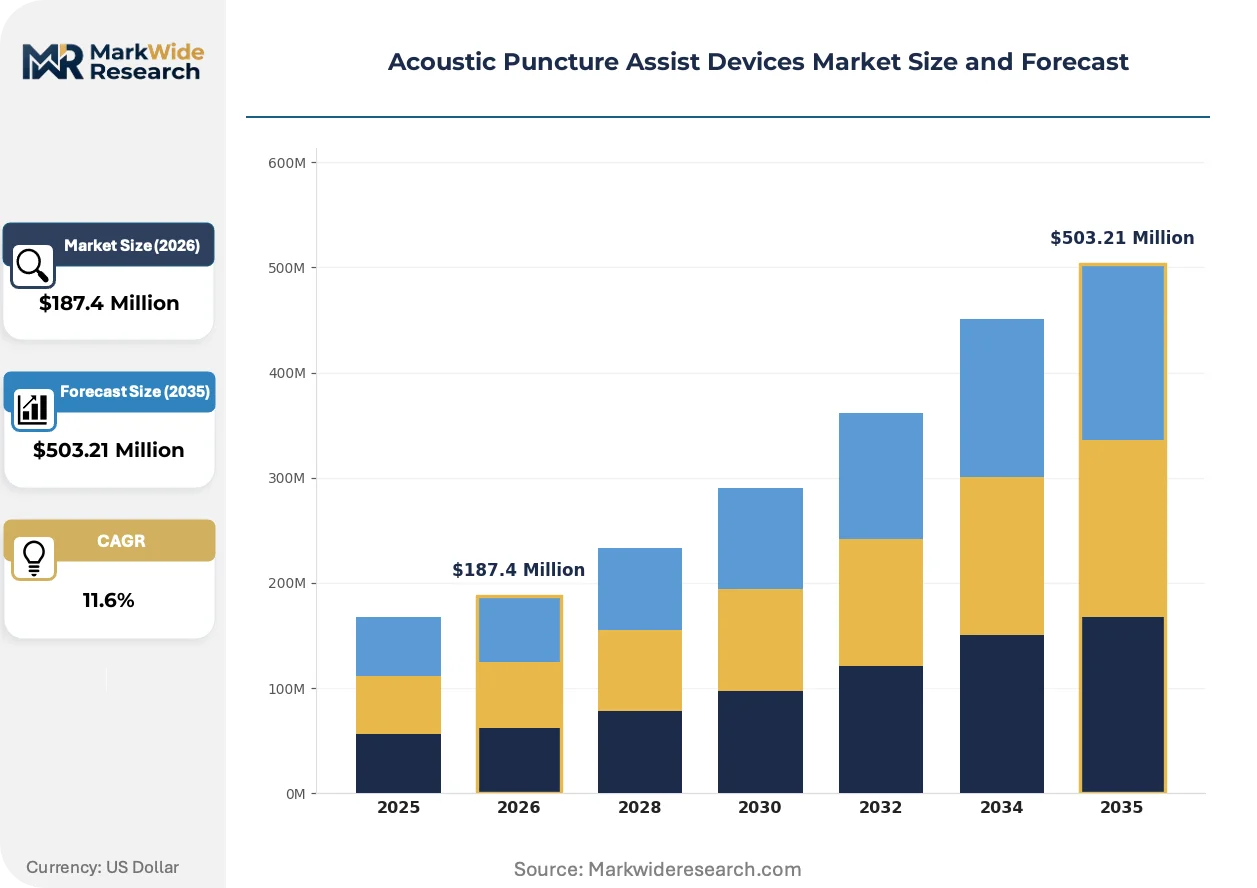
Market Dynamics
Sensor fusion complexity and software validation requirements are concentrating margin pools among automated acoustic guidance systems, while disposable alternatives expand through hospital infection control mandates.
Growth Catalysts
- EU Medical Device Regulation (MDR):CE marking under stricter clinical evidence requirements is accelerating hospital procurement of validated needle guidance systems for liability reduction.
- Minimally invasive intervention training:Expanding procedural education programs in the United States, Germany, and Japan are embedding acoustic feedback devices into standard anesthesia and emergency medicine curricula.
- Ultrasound compatibility:Integrated 2-15 MHz frequency systems are replacing standalone needle confirmation methods in cardiovascular access and regional anesthesia workflows.
Market Restraints
- Piezoelectric sensor supply:Concentration of high-frequency transducer manufacturing in East Asian foundries creates input vulnerability for automated device producers.
- FDA 510(k) pathway friction:Substantial equivalence demonstrations for software-enabled needle guidance extend development timelines and compress early-mover advantages.
- Optical navigation substitutes:Electromagnetic tracking systems for epidural placement are capturing select hospital budgets through established reimbursement codes.
Strategic Opportunities
- India's CDSCO fast-track:Accelerated device approval pathways for critical care technologies offer first-mover positioning in underpenetrated tertiary hospital networks.
- MRI-compatible configurations:Fusion of acoustic guidance with magnetic resonance imaging protocols opens neurosurgical applications previously closed to metallic instrument systems.
- Direct-to-ambulatory surgery center distribution:Bypassing traditional hospital supply chains captures outpatient procedural volume migrating from inpatient settings.
Industry Challenges
- Anesthesiologist training deficits:Real-time acoustic interpretation skills remain unevenly distributed across residency programs, slowing standardized adoption.
- Multi-modal integration complexity:Synchronizing audio feedback with existing ultrasound displays and electronic health record systems strains hospital IT infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustic Puncture Assist Devices Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Manual Devices, Automated Devices, Semi-Automated Devices, Disposable Devices End User: Hospitals, Urgent Care Centers, Clinics, Home Healthcare Technology: Ultrasound-Guided, MRI-Compatible, Radiofrequency, Laser-Assisted Application: Neurology, Cardiovascular, Oncology, Emergency Medicine |
| Companies Covered | Apad B.V., UNITRON NV, Equip Medikey, QRS International, Becton Dickinson, Teleflex, Cook Medical, B. Braun Melsungen, Smiths Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustic Puncture Assist Devices Market Strategic Shifts
Acoustic puncture assist technology is fragmenting into specialized configurations as procedural specificity overtakes universal device designs across anesthesia, emergency medicine, and interventional radiology.
Multi-frequency transducer arrays spanning 2-15 MHz are decomposing the traditional single-sensor architecture that dominated early-generation devices. Academic medical centers in the United States and Japan are piloting these systems for simultaneous tissue differentiation and needle tip confirmation. The structural consequence is compression of standalone low-frequency devices into commodity positioning while premium automated systems capture neurosurgical and high-risk vascular access applications.
CE marking under the EU Medical Device Regulation is tightening clinical evidence requirements for software-validated needle guidance systems. Manufacturers must now submit prospective usability studies rather than retrospective equivalence claims. European anesthesia device distributors are consolidating supplier relationships to manage documentation burdens, favoring established players with regulatory affairs infrastructure over emerging technology entrants.
Hospital procurement committees are unbundling device acquisition from disposable needle set contracts that previously locked purchasers into single-source arrangements. Ambulatory surgery centers in Germany and Japan are driving this shift through volume-based negotiations and preference for interoperable acoustic modules. The United States exhibits the most visible disruption as group purchasing organizations restructure anesthesia device categories to separate capital equipment from recurring consumable spend.
Acoustic Puncture Assist Devices Market Segmentation
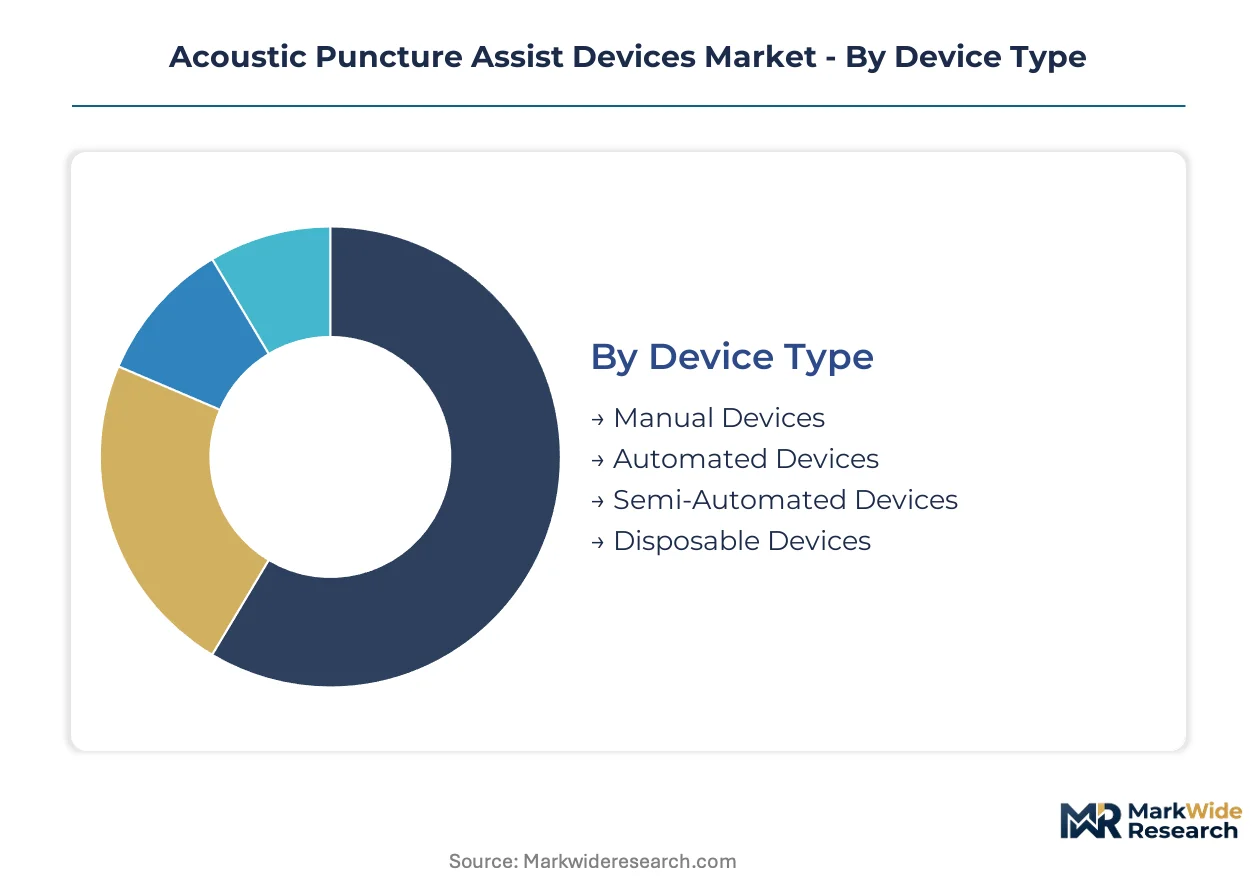
Acoustic puncture assist devices fragment across four structural dimensions where margin concentration diverges sharply. Device type and technology tiers separate premium automated systems from commodity disposables, while end-user and application splits reveal divergent procurement patterns across care settings.
Device Type:
Automated systems command the deepest margin pools due to sensor fusion complexity and software validation overhead, while disposable alternatives compete on infection control compliance and volume throughput.
- Automated Devices:Real-time needle tip confirmation systems integrate multi-frequency transducer arrays with algorithmic tissue differentiation. Demand concentrates in United States academic medical centers and German university hospitals where liability reduction justifies capital expenditure for high-risk epidural and vascular access procedures.
- Disposable Devices:Single-use acoustic guidance attachments eliminate cross-contamination risk in high-turnover intervention suites. Japanese emergency departments and ambulatory surgery centers in Germany are expanding procurement as sterilization capacity constraints tighten and infection control protocols harden.
- Manual Devices:Clinician-operated acoustic feedback tools without automated tip tracking.
- Semi-Automated Devices:Hybrid configurations requiring operator initiation with automated confirmation sequences.
The dominant share belongs to Automated Devices, while Disposable Devices is closing the gap fastest.
End User:
Procurement authority and reimbursement pathways create tiered access patterns across institutional buyers, with hospitals maintaining volume leadership while outpatient settings reshape contract structures.
- Hospitals:Integrated anesthesia and interventional radiology departments drive system-level purchases with dedicated capital budgets. United States health systems and Japanese tertiary centers are consolidating acoustic guidance into standardized needle placement protocols for spinal and central line procedures.
- Urgent Care Centers:Rapid-access facilities prioritize portable acoustic modules for fracture and soft-tissue interventions. German outpatient networks are piloting disposable-guided systems for same-day discharge protocols.
- Clinics:Specialist practices with limited procedure volumes favor leased or shared equipment models.
- Home Healthcare:Mobile nursing services requiring lightweight confirmation tools for peripherally inserted central catheter maintenance.
Hospitals retain the largest procurement footprint, though Urgent Care Centers are expanding most quickly.
Technology:
Frequency range and imaging compatibility define performance tiers, with ultrasound integration dominating procedural adoption while MRI compatibility unlocks neurosurgical applications previously inaccessible to metallic instrument systems.
- Ultrasound-Guided:2-15 MHz transducer systems provide real-time tissue visualization alongside acoustic needle confirmation. Cardiovascular access and emergency medicine applications in United States trauma centers and Japanese critical care units are embedding these systems as standard-of-care for central line placement.
- MRI-Compatible:Non-ferromagnetic acoustic sensors enable intraoperative guidance during magnetic resonance imaging. German neurosurgical clusters and United States academic centers are validating these configurations for deep brain stimulation and tumor biopsy procedures.
- Radiofrequency:Electromagnetic needle tracking systems competing for epidural placement budgets.
- Laser-Assisted:Optical coherence tomography integration for superficial tissue applications.
Ultrasound-Guided systems hold the dominant position, while MRI-Compatible configurations are gaining share fastest.
Application:
Procedural risk profiles and reimbursement differentiation concentrate investment in high-stakes interventions where needle misplacement carries severe liability exposure.
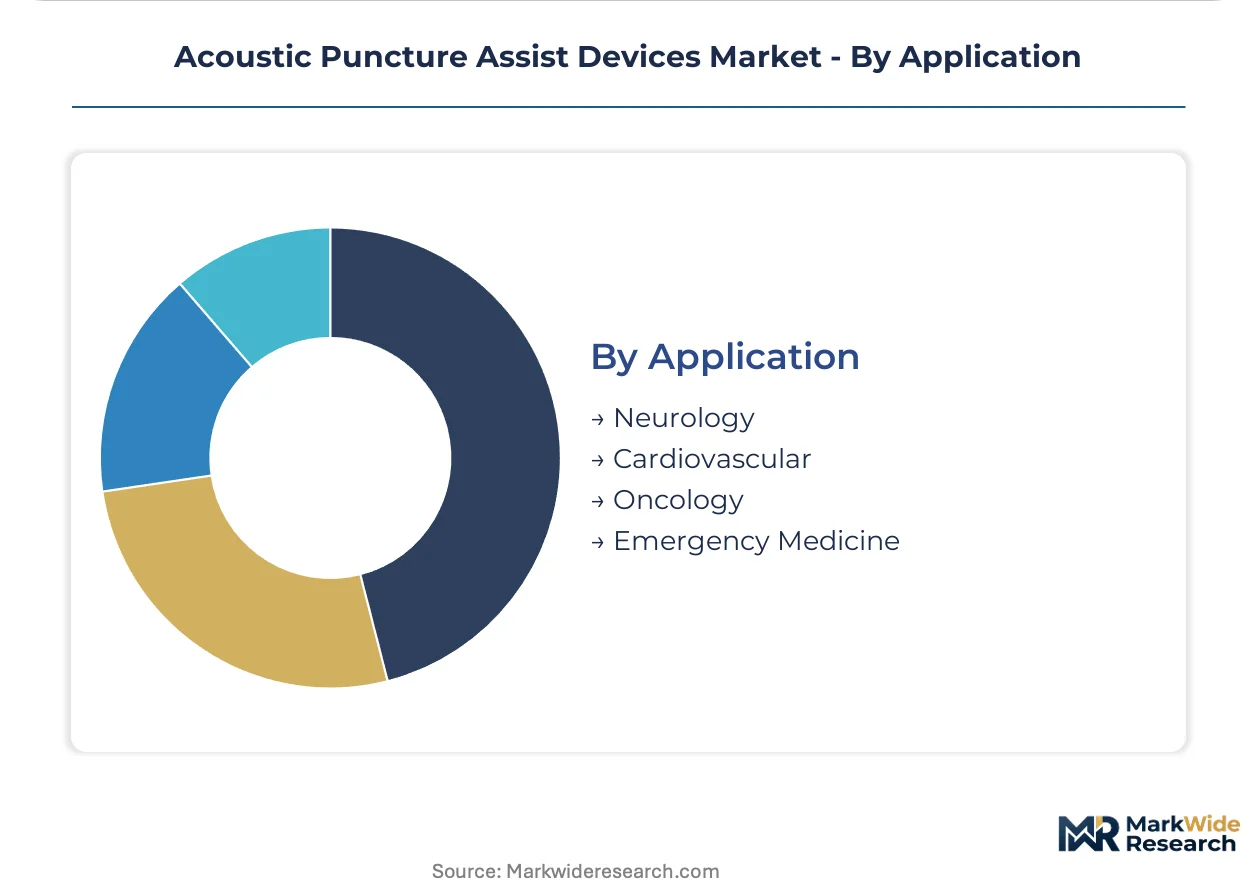
- Neurology:Lumbar puncture and intrathecal drug delivery require sub-millimeter precision for cerebrospinal fluid access. United States pediatric centers and German neurology departments are mandating acoustic confirmation for all non-emergent spinal procedures.
- Cardiovascular:Central venous catheterization and arterial line placement in high-risk patients. Japanese cardiac intervention suites and United States emergency departments are standardizing ultrasound-acoustic fusion for internal jugular and subclavian access.
- Oncology:Biopsy guidance for deep tissue sampling in radiology workflows.
- Emergency Medicine:Rapid vascular access under resuscitation conditions with limited visualization.
Neurology commands the dominant application share, with Cardiovascular expanding most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of acoustic puncture assist devices concentrate in German and Japanese manufacturing hubs, while import demand surges in United States health systems and Indian tertiary hospitals. Trade balances reflect technology gaps between established precision instrument producers and rapidly expanding clinical markets.
United States
FDA 510(k) clearance pathways for software-enabled needle guidance systems are tightening clinical evidence requirements, extending product development timelines. Academic medical centers in Boston and Stanford are piloting multi-frequency transducer arrays for simultaneous tissue differentiation. Hospital procurement committees are unbundling capital equipment from disposable contracts, reshaping supplier relationships.
Germany
CE marking under the EU Medical Device Regulation is mandating prospective usability studies for acoustic guidance systems, favoring established regulatory affairs infrastructure. University hospitals in Heidelberg and Munich are consolidating acoustic feedback into standardized spinal and epidural protocols. Ambulatory surgery centers in Bavaria are driving volume-based negotiations for interoperable acoustic modules.
Japan
PMDA approval pathways for critical care technologies are embedding acoustic puncture devices into emergency medicine curricula. METI industrial policy is supporting domestic sensor manufacturing to reduce piezoelectric transducer import dependence. Tokyo and Osaka medical clusters are validating MRI-compatible configurations for neurosurgical applications previously closed to metallic systems.
India
CDSCO fast-track approval pathways for critical care devices are opening first-mover positioning in underpenetrated tertiary networks. Government procurement under Ayushman Bharat is expanding access to precision needle guidance in district hospitals. Medical device parks in Andhra Pradesh and Gujarat are attracting contract manufacturing for disposable acoustic attachments.
United Kingdom
MHRA post-Brexit regulatory autonomy is recalibrating conformity assessment timelines for acoustic guidance systems. NHS England procurement frameworks are prioritizing infection control compliance in needle guidance contracts. London and Manchester teaching hospitals are integrating acoustic feedback into regional anesthesia training programs.
Acoustic Puncture Assist Devices Market Competitive Environment
Listed leaders compete with private specialists across regulatory affairs capability and sensor integration depth. The vendor base fragments across three tiers: diversified medtech conglomerates with anesthesia portfolios, dedicated vascular access specialists, and emerging sensor technology firms. Archetypes include ultrasound-platform integrators, disposable-focused infection control suppliers, and MRI-compatibility pioneers. Dominant competitive moves center on strategic partnerships for multi-modal integration and geographic licensing for emerging market access.
Within the diversified medtech tier, Becton Dickinson and Teleflex exemplify platform-scale positioning, while Smiths Medical occupies a specialized niche in MRI-compatible configurations. B. Braun Melsungen represents European engineering-focused manufacturing archetypes, and Cook Medical anchors the vascular access specialization vector. Apad B.V. and UNITRON NV sit within the emerging technology tier, reflecting Benelux sensor development clusters. These named entities illustrate competitive positioning without exhaustively mapping the full competitive set.
| Leading Market Players |
|---|
| Apad B.V. |
| UNITRON NV |
| Equip Medikey |
| QRS International |
| Becton Dickinson |
| Teleflex |
| Cook Medical |
| B. Braun Melsungen |
| Smiths Medical |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation simultaneously gate supplier qualification and stratify price tiers across automated acoustic guidance systems, disposable attachments, and manual device categories.
Pricing Analysis
Hospital procurement committees anchor pricing negotiations through unbundled capital equipment and disposable contract structures. Three-tier pricing structure across premium automated systems, standard semi-automated configurations, and economy manual devices reflects sensor fusion complexity and software validation overhead. Cost compression in the disposable tier is intensifying as infection control mandates expand volume throughput. Ambulatory surgery centers in Germany and Japan exhibit the highest price sensitivity, while United States academic medical centers prioritize liability reduction over unit economics.
Supply Chain Analysis
Port congestion along East Asian trade lanes elevates inbound logistics costs for piezoelectric transducer components sourced from Taiwanese and South Korean foundries. Manufacturing concentration in Germany and Japan for precision acoustic sensors draws from rare earth element processing in China and specialized polymer supply in the United States. Single-source vulnerability around high-frequency transducer arrays creates procurement risk for automated device producers. Distribution runs through hospital supply chains and group purchasing organizations, with direct-to-ambulatory surgery center channels expanding fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acoustic puncture assist technology fragmentation creates multiple niche entry points as procedural specificity overtakes universal device designs across anesthesia, emergency medicine, and interventional radiology workflows.
For Market Incumbents: Shield premium positioning in automated systems through accelerated FDA 510(k) submissions for multi-frequency transducer arrays. Deepen backward integration into piezoelectric sensor manufacturing to reduce East Asian supply exposure. Consolidate disposable needle set contracts before ambulatory surgery center procurement committees complete vendor unbundling.
For New Entrants and Emerging Players: Lead with MRI-compatible acoustic sensor configurations for neurosurgical applications in German and United States academic centers. Target India's CDSCO fast-track pathway for critical care device approval in underpenetrated tertiary hospital networks. Pursue direct distribution partnerships with ambulatory surgery centers bypassing traditional hospital supply chains.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated acoustic guidance systems due to sensor fusion complexity and software validation requirements. Acquisition candidates with established regulatory affairs infrastructure and CE marking documentation offer superior long-term viability. Monitor PMDA approval timelines for acoustic puncture devices as an inflection indicator for Japanese market penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Software-enabled needle guidance systems face tightening clinical evidence requirements from FDA reviewers. |
| CE Marking Pathway Investment | EU Medical Device Regulation mandates prospective usability studies rather than retrospective equivalence claims. |
| Hospital System Partnership | United States health systems consolidate acoustic guidance into standardized spinal and central line protocols. |
| Software Companion Development | Electronic health record integration strains hospital IT infrastructure and creates competitive differentiation. |
| Reimbursement Strategy | Payor recalibration of image-guided needle placement coverage shapes procurement committee decisions. |
Study Parameters
A standing panel of anesthesiology department heads, hospital purchasing committee members, biomedical engineers, and group purchasing organization contract managers provided ongoing calibration against secondary validation from FDA 510(k) filings, CE marking databases under EU MDR, hospital procurement records, and CMS Medicare reimbursement codes. Bottom-up device shipment estimates triangulated with top-down procedure volume modeling across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including trade flow data from German and Japanese manufacturing hubs and import statistics for United States health systems. Segmentation modeling spanned device type tiers, technology frequency ranges, end-user institutional categories, and application-specific procedural risk profiles. CAGRs derived from algorithmic curve fitting to historical adoption patterns and forward-looking regulatory timeline assumptions.
The analysis sits within stated boundaries; outcomes outside FDA clearance acceleration or piezoelectric supply stabilization would require recalibration. Forecasts reflect documented assumptions regarding training program expansion, reimbursement code evolution, and sensor manufacturing capacity additions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neurovascular Stent Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Adult Water Flosser Market
Medical Devices
Eye Massage Device Market
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market
Medical Devices
Organoids Kits Market
Medical Devices
Global Blood Warmer Devices Market
Medical Devices
Global Nebulizers Market
Medical Devices
Microneedle Flu Vaccine Market
Medical Devices
Minimally Invasive Spine Technologies Market
Medical Devices
Wireless Neurostimulator Market
Medical Devices
North America Sperm Separation Devices Market
Medical Devices
Hybrid Microcirculation Detector Market
Medical Devices
US Medical Device Outsourcing Market
Medical Devices
Laryngeal Masks Market
Medical Devices
Infertility Devices Market