
 Europe Small Wind Turbine Market | 2026-2036
Europe Small Wind Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Small Wind Turbine Market Foresight
European turbine blade manufacturing is realigning toward shorter, higher-efficiency profiles optimized for low-wind regimes. SD Wind Energy Limited leverages its Scottish engineering base to dominate distributed onshore supply across the British Isles. Aeolos Wind Energy Ltd anchors its position through permanent-magnet direct-drive designs that reduce maintenance intervals for remote installations. Kingspan Group PLC extends its building-integrated energy portfolio by competing on rooftop micro-turbine packages for commercial property developers.
A small wind turbine converts kinetic wind energy into electrical power through rotor blades driving a generator, typically rated below 100 kW with rotor diameters spanning 2 to 20 meters for residential, agricultural, or light industrial use. Horizontal axis configurations occupy the dominant share due to mature aerodynamic efficiency and established supply chains for fiberglass-nacelle assemblies. Off-grid installation types sustain the fastest expansion as rural electrification projects and energy-independent farms in Romania and Poland prioritize battery-coupled systems over grid extension. The below 10 kW capacity range concentrates margin pools in Germany and Denmark, where feed-in tariff residuals and self-consumption premiums support premium pricing for certified units.
The EU Green Deal and F-Gas Regulation shape equipment standards by mandating recyclable blade materials and restricting synthetic lubricants in nacelle drivetrains, while CE marking under the Machinery Directive governs noise and safety compliance for residential proximity installations. ECHA's REACH framework restricts epoxy resin chemistries, forcing manufacturers toward bio-based composites or thermoplastic alternatives. Stakeholders must monitor national implementation gaps between Brussels-level targets and permitting velocity in member states with fragmented spatial planning authority.
Market Dynamics
The EU Green Deal's tightening renewable targets are compressing permitting timelines and forcing manufacturers toward modular, recyclable blade architectures that cut lifecycle costs for distributed wind projects.
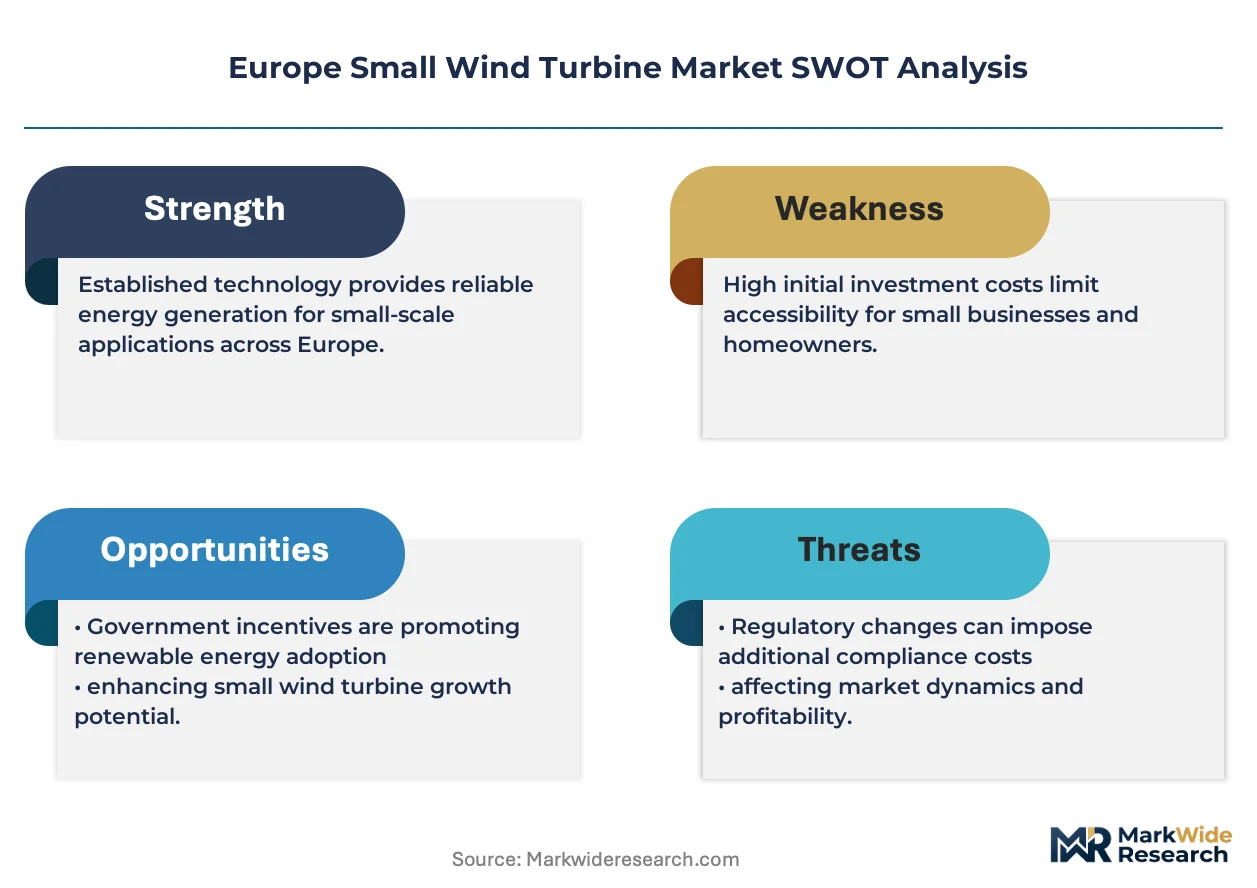
Growth Catalysts
- Revised Renewable Energy Directive:National mandates for distributed generation are accelerating farm cooperative investments in sub-100 kW systems across Germany's rural northern states.
- Battery-coupled off-grid architectures:Romanian and Polish agricultural operations are prioritizing energy-independent cold storage and irrigation over grid extension.
- Scotland's engineering cluster:Concentrated R&D in Glasgow-Edinburgh corridor is driving blade efficiency gains for low-wind regimes.
Market Restraints
- Epoxy resin supply constraints:ECHA REACH restrictions on thermoset chemistries are forcing costly retooling toward bio-based composites.
- Permanent-magnet rare earth dependency:Concentrated sourcing for direct-drive generators creates exposure to price volatility in neodymium-dysprosium markets.
- Grid connection queuing:Fragmented spatial planning authority in Italy and Spain delays revenue recognition for distributed projects.
Strategic Opportunities
- Building-integrated micro-turbines:Commercial property developers in Copenhagen and Amsterdam are testing rooftop packages for net-zero building certifications.
- F-Gas Regulation compliance services:Maintenance providers can capture recurring revenue from synthetic lubricant phase-out mandates.
- Polish agri-energy cooperatives:Underpenetrated eastern regions offer first-mover positioning for turn-key electrification bundles.
Industry Challenges
- CE marking timeline compression:Machinery Directive noise and safety compliance requires 12-18 month certification cycles that strain working capital.
- Aerodynamicist talent scarcity:Specialized rotor design expertise concentrates in Denmark and Germany, limiting expansion capacity elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Small Wind Turbine Market |
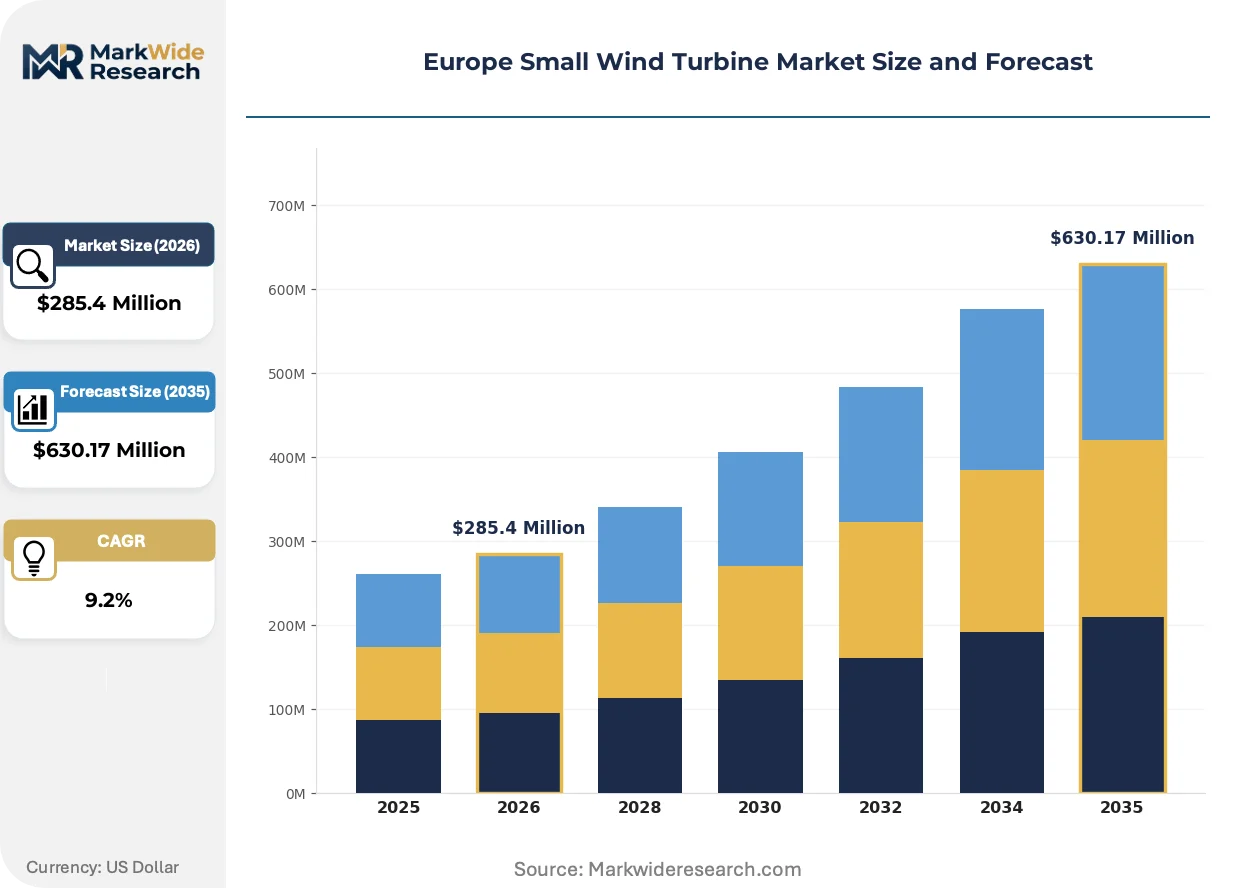
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $630.17 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
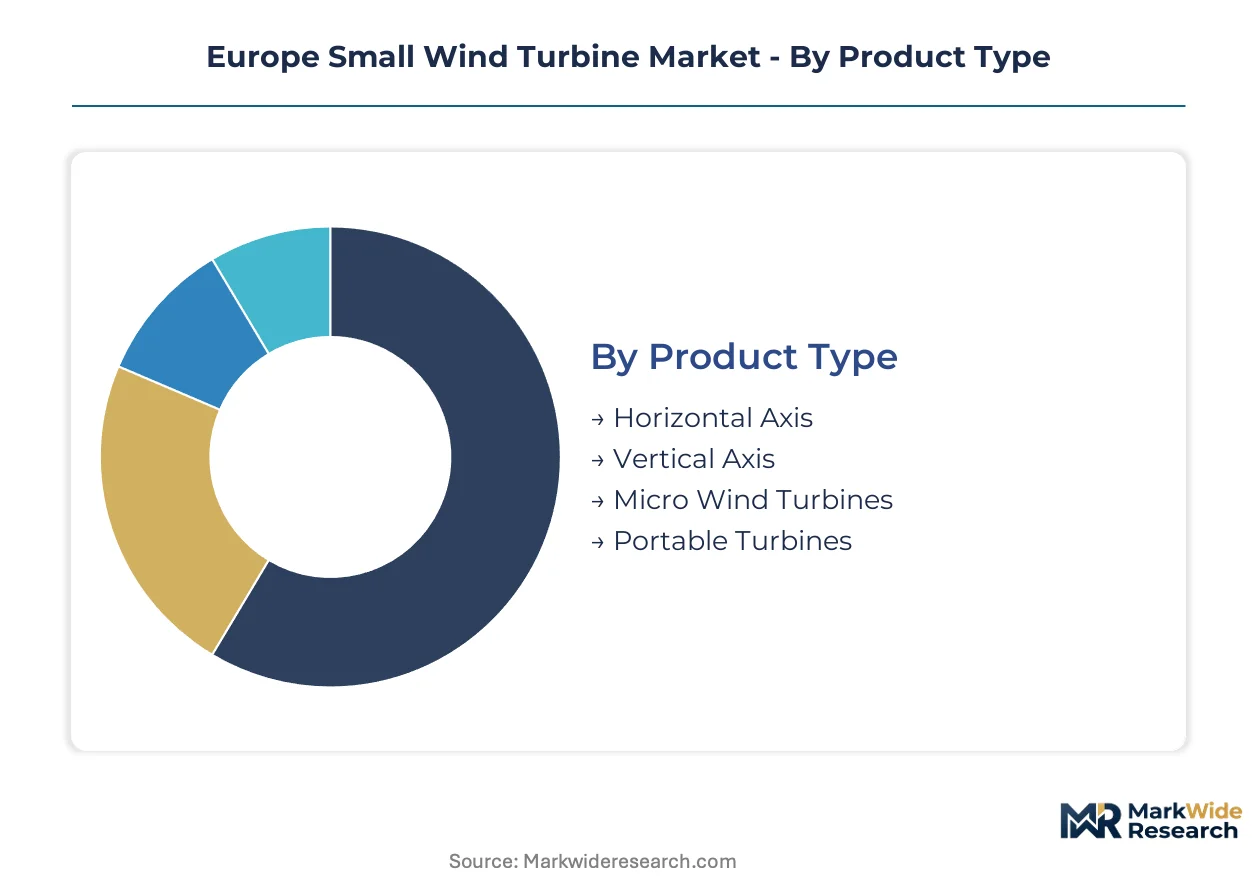
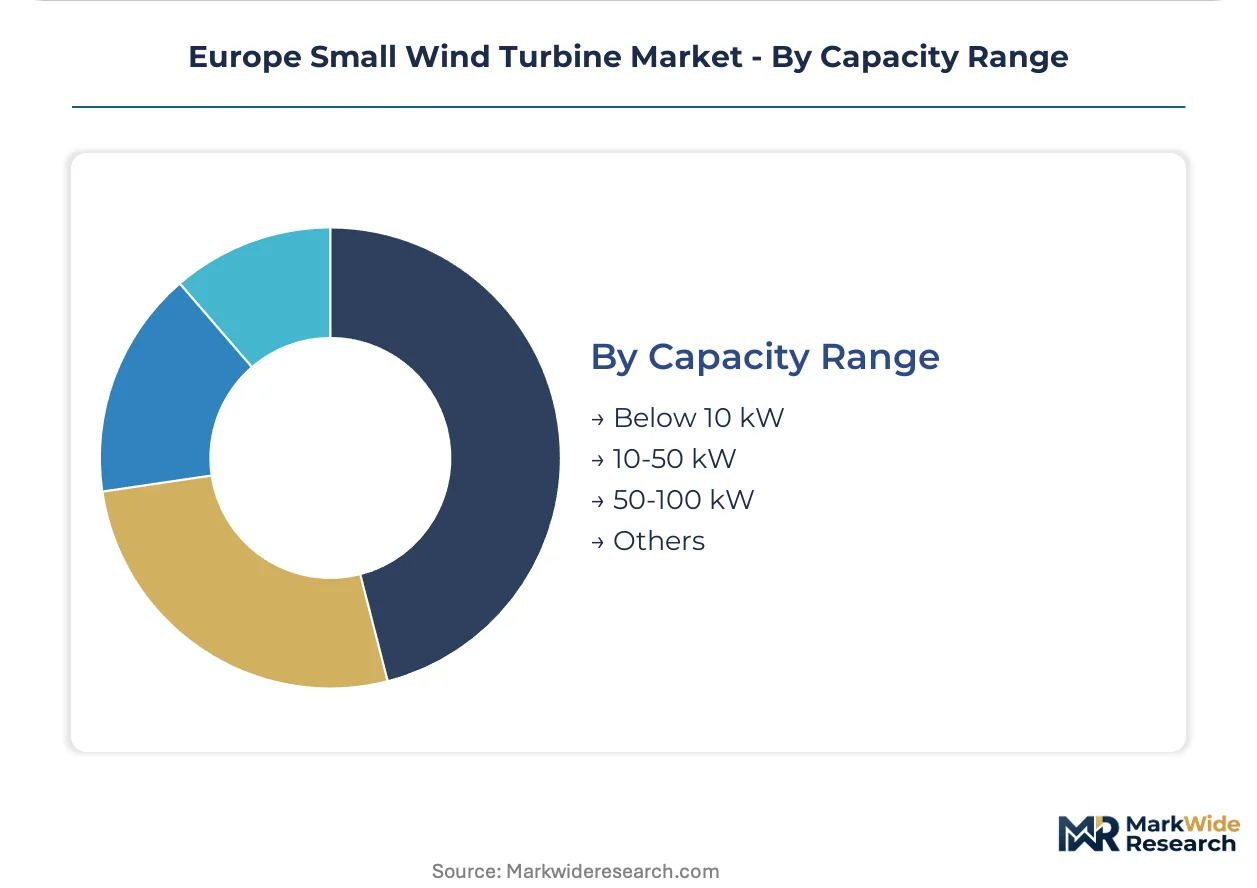
| Segmentation | Product Type: Horizontal Axis, Vertical Axis, Micro Wind Turbines, Portable Turbines End User: Residential, Commercial, Industrial, Agricultural Installation Type: On-Grid, Off-Grid, Hybrid, Community-Based Capacity Range: Below 10 kW, 10-50 kW, 50-100 kW, Others |
| Companies Covered | Northern Power Systems Srl, SD Wind Energy Limited, Aeolos Wind Energy Ltd, City Windmills Holdings PLC, Ryse Energy, Kingspan Group PLC, Envergate Energy AG, BORNAY AEROGENERADORES, TUGE Energia OU, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Small Wind Turbine Market Shifts & Advancements
Equipment manufacturers are racing to align product roadmaps with Brussels-level sustainability mandates while adapting blade geometries for Europe's low-wind resource profiles.
Glass-thermoplastic hybrid blades are consolidating market share as the dominant rotor material platform. Farm cooperatives in Schleswig-Holstein and Lower Saxony are specifying these units for 25-year design lifecycles without structural fatigue concerns. The shift is consolidating maintenance cost advantages for remote installations where crane access remains prohibitively expensive.
EU F-Gas Regulation phase-down schedules are forcing lubricant reformulation across nacelle drivetrains. Manufacturers must now qualify bio-based grease chemistries that withstand temperature cycling in Baltic coastal conditions. Danish and German OEMs are responding fastest, locking in preferred supplier status with certified maintenance networks.
Energy-as-a-service contracting is displacing outright equipment purchases among Polish and Romanian agricultural buyers. Leasing providers now bundle turbines with battery storage and predictive maintenance, absorbing performance risk that previously deterred capital-constrained farmers. This model is spreading fastest where feed-in tariff residuals no longer justify balance-sheet ownership.
Europe Small Wind Turbine Market Segmentation
Segmentation in the Europe Small Wind Turbine Market reveals how equipment specifications align with distinct regulatory environments and end-use economics across member states. Understanding these divisions helps manufacturers calibrate blade designs, drivetrain configurations, and service models to specific buyer requirements and permitting conditions.
Product Type:
Replacement cycles and upgrade pathways differ sharply across rotor architectures, with horizontal axis units demanding periodic blade refurbishment while vertical axis systems prioritize bearing longevity.
- Horizontal Axis:Fiberglass-nacelle assemblies with upwind rotor orientation dominate aerodynamic efficiency metrics. German farm cooperatives in Schleswig-Holstein specify these for grid-connected installations where feed-in tariff residuals justify premium certified units.
- Vertical Axis:Darrieus and Savonius configurations eliminate yaw mechanisms, reducing maintenance intervals for remote Romanian agricultural sites. Polish energy-as-a-service providers favor these for lease portfolios where crane access remains prohibitively expensive.
- Micro Wind Turbines:Sub-1 kW rooftop units serve Amsterdam and Copenhagen commercial developers pursuing net-zero building certifications.
- Portable Turbines:Collapsible mast designs address temporary power needs at Italian alpine construction sites and remote monitoring stations.
Volume placements concentrate in Horizontal Axis; the faster expansion belongs to Vertical Axis.
End User:
Customer procurement authority and capital constraints create four distinct buying behaviors, from balance-sheet ownership to third-party leasing arrangements.
- Residential:Individual homeowners in Denmark's coastal regions purchase sub-10 kW systems through certified installer networks. CE marking under the Machinery Directive and noise compliance requirements extend sales cycles to 12-18 months.
- Agricultural:Romanian and Polish farm cooperatives are displacing outright purchases with energy-as-a-service contracts bundling turbines, battery storage, and predictive maintenance.
- Commercial:Copenhagen and Amsterdam property developers test building-integrated rooftop packages for BREEAM and WELL certification compliance.
- Industrial:Small manufacturing estates in northern Germany pursue sub-100 kW systems for behind-the-meter consumption and peak shaving.
Commercial deployments show the steepest expansion trajectory; Agricultural contracts are climbing fastest in eastern member states.
Installation Type:
Grid interconnection economics and spatial planning authority fragmentation determine whether projects proceed as utility-coupled or islanded architectures.
- Off-Grid:Battery-coupled systems with lithium-ion or flow battery integration serve Romanian and Polish cold storage and irrigation operations. These configurations bypass grid extension costs and fragmented permitting timelines in Italy and Spain.
- On-Grid:Net-metered installations in Germany's rural northern states leverage residual feed-in tariff structures and self-consumption premiums.
- Hybrid:Solar-wind-battery combinations address resource intermittency for Alpine and Baltic coastal sites with complementary generation profiles.
- Community-Based:Shared ownership structures aggregate demand across multiple smallholders in Scottish Highlands and Welsh border regions.
Community-based models gain share fastest in Scotland; Off-grid architectures show the strongest volume concentration in Poland and Romania.
Capacity Range:
Unit scale determines supply chain sourcing, with sub-10 kW systems drawing from distributed manufacturing networks while 50-100 kW units require specialized drivetrain components.
- Below 10 kW:Compact rotor diameters of 2-7 meters serve residential and small commercial rooftops. German and Danish margin pools concentrate here due to certification premiums and established installer networks.
- 10-50 kW:Mid-scale units address farm cooperative and light industrial demand in Lower Saxony and Mecklenburg-Vorpommern.
- 50-100 kW:Larger rotor assemblies and permanent-magnet direct-drive generators reduce maintenance for remote Scottish and Irish installations.
- Others:Custom configurations above 100 kW fall outside standard small wind definitions but serve specialized industrial microgrids.
Below 10 kW systems dominate current placements; 10-50 kW units are expanding most quickly as Polish agri-energy cooperatives scale procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scottish engineering clusters and northern German manufacturing belts anchor blade fabrication and drivetrain assembly for distributed wind systems serving low-wind European regimes.
Germany
Farm cooperatives in Schleswig-Holstein and Lower Saxony drive sub-100 kW procurement for behind-the-meter consumption and residual feed-in tariff capture. The revised Renewable Energy Directive tightens distributed generation mandates, accelerating permitting timelines for rural installations. The Hamburg-Helgoland corridor concentrates nacelle assembly operations serving North Sea coastal demand.
United Kingdom
Scottish Highlands agricultural estates and Welsh border community ownership structures expand off-grid and community-based architectures. CE marking under the Machinery Directive governs noise compliance for residential-proximity installations, extending sales cycles for certified units. The Glasgow-Edinburgh engineering corridor dominates blade R&D for low-wind efficiency gains.
Poland
Agricultural cooperatives in eastern regions prioritize energy-as-a-service contracts bundling turbines with battery storage and predictive maintenance. EU Green Deal targets compress national implementation timelines for distributed generation. The Łódź-Łublin belt concentrates lease-provider activity for capital-constrained farm operations.
Romania
Rural electrification projects and cold storage irrigation operations favor battery-coupled off-grid systems over grid extension costs. ECHA REACH restrictions on epoxy resin chemistries force bio-based composite adoption in local supply chains. The Transylvanian plateau anchors agri-energy cooperative formation for energy-independent farm clusters.
Italy
Spanish and Italian agricultural operations expand small wind adoption for irrigation and cold storage, though fragmented spatial planning authority delays revenue recognition. The F-Gas Regulation mandates synthetic lubricant phase-out across nacelle drivetrains, requiring maintenance provider recertification. Alpine construction sites in northern Italy deploy portable turbine configurations for temporary power needs.
Europe Small Wind Turbine Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue building-integrated micro-turbine and energy-as-a-service contracting spaces. The vendor base stratifies across three maturity tiers: legacy horizontal-axis specialists, vertical-axis maintenance-optimized providers, and rooftop-integrated building energy entrants. Strategic archetypes include blade-efficiency engineering clusters, permanent-magnet direct-drive designers, and building-integrated energy portfolio extenders. Competitive moves concentrate on modular blade architecture retooling and certified maintenance network lock-in.
Within the Scottish engineering cluster, SD Wind Energy Limited exemplifies distributed onshore supply concentration across the British Isles. Aeolos Wind Energy Ltd anchors the permanent-magnet direct-drive archetype, representing reduced-maintenance design philosophy for remote installation economics. Kingspan Group PLC occupies the building-integrated energy extension position, competing on rooftop micro-turbine packaging for commercial property developer certification compliance.
| Leading Market Players |
|---|
| Northern Power Systems Srl |
| SD Wind Energy Limited |
| Aeolos Wind Energy Ltd |
| City Windmills Holdings PLC |
| Ryse Energy |
| Kingspan Group PLC |
| Envergate Energy AG |
| BORNAY AEROGENERADORES |
| TUGE Energia OU |
| Others |
Supply & Pricing Matrix
The EU Green Deal's recyclable blade mandates gate qualified supply and premium-tier pricing access, forcing manufacturers to absorb certification costs or forfeit high-margin German and Danish procurement channels to certified competitors.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium German OEMs from unbundled eastern European suppliers. Three-tier pricing structure across certified-premium, standard-CE, and economy-direct tiers reflects CE marking complexity and rare-earth magnet sourcing. Cost compression in economy-direct tiers is intensifying because Romanian and Polish buyers prioritize capital expenditure minimization over lifecycle service. Agricultural cooperatives in Poland exhibit highest price sensitivity; Copenhagen commercial developers show lowest sensitivity due to net-zero certification premiums.
Supply Chain Analysis
Single-source vulnerability sits with Chinese neodymium-dysprosium processing for permanent-magnet direct-drive generators. Blade fabrication draws from Scottish and northern German engineering clusters, while nacelle assembly rests on Danish and Spanish manufacturing belts. Tariff exposure on rare-earth imports creates margin instability for direct-drive specialists. Distribution runs through certified installer networks in Germany and Denmark, with lease-provider channels expanding fastest in Poland and Romania.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified blade manufacturing capacity constraints prop pricing power for incumbent OEMs with existing CE marking pathways and established Scottish-German supply bases.
For Market Incumbents: Lock in certified maintenance network exclusivity across Baltic and North Sea coastal zones before F-Gas Regulation lubricant phase-out mandates take full effect. Deepen backward integration into bio-based composite supply through partnerships with ECHA REACH-compliant resin suppliers to defend margin position against epoxy substitution cost shocks. Prioritize permanent-magnet recycling partnerships to offset rare-earth price volatility exposure. For New Entrants and Emerging Players: Launch via energy-as-a-service contracting models targeting Polish and Romanian agricultural cooperatives where capital constraints block outright equipment purchases. Polish agri-energy cooperatives represent the most penetrable white-space segment, with eastern regions showing minimal incumbent lease-provider presence. Pursue vertical-axis turbine specialization for remote installations where crane access costs eliminate horizontal-axis competition. For Investors and Strategic Acquirers: Scottish engineering cluster consolidation announcements are the leading indicator that blade efficiency R&D is concentrating into defensible competitive moats. Five-to-ten year viability favors acquirers of permanent-magnet direct-drive specialists with established rare-earth supplier relationships and remote-installation service footprints. Watch for Polish lease-provider profitability inflection as battery cost curves improve unit economics.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Fast-Track Certification | Compresses 12-18 month compliance timelines for German farm cooperative demand capture. |
| Bio-Based Composite Supply Agreement | Secures ECHA REACH-compliant resin access before epoxy restrictions tighten. |
| Rare-Earth Recycling Partnership | Reduces permanent-magnet generator exposure to Chinese neodymium-dysprosium volatility. |
| Energy-as-a-Service Platform Launch | Captures Polish and Romanian agricultural demand through lease bundling with battery storage. |
| Building-Integrated Micro-Turbine Development | Addresses Copenhagen and Amsterdam commercial developer net-zero certification requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with wind turbine OEM procurement directors, EPC contractors, agricultural cooperative energy managers, and certified installer network heads combined with ECHA REACH substance restriction databases, EU Green Deal implementation tracking, and national grid interconnection queue records. Bottom-up unit shipment tallies and top-down capacity installation estimates underwent cross-validation.
Data-stream reconciliation across manufacturer shipment disclosures, national renewable energy registry entries, and lease-provider contract announcements shaped the analytical framework. Segmentation dimensions modeled include rotor architecture, capacity tier, installation type, and end-use sector across the projection horizon. CAGRs derived from installed base growth trajectories, replacement cycle assumptions, and policy mandate implementation velocity. Forecast inputs incorporated feed-in tariff residual schedules and battery cost curve projections.
Regulatory implementation delays, rare-earth supply disruptions, and grid interconnection queue extensions are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on policy continuity and technology cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Brazil Wind Energy Market
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
Wind Power Forgings Market
Wind Energy Systems
Global Offshore Wind Market
Wind Energy Systems
Sweden Wind Power Market
Wind Energy Systems
Wind Tower Market
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Offshore Wind Power Market
Wind Energy Systems
Germany Wind Energy Market
Wind Energy Systems
Wind Turbine Gearbox and Direct Drive Systems Market
Wind Energy Systems
Wind Turbine Pitch Systems Market
Wind Energy Systems
Wind Services Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Wind Speed Alarm Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
Wind Turbine Lenses Market