
 Global Offshore Wind Market | 2026-2036
Global Offshore Wind Market Size, Share, and Industry Trends Forecast 2026-2036
Global Offshore Wind Market Outlook
Aftermarket service revenue is narrowing as turbine OEMs extend long-term service agreements and captive maintenance operations. Ørsted anchors its competitive position through integrated project development across the full asset lifecycle. Siemens Gamesa Renewable Energy dominates the offshore turbine supply base with specialized direct-drive platforms for salt-laden environments. Vestas Wind Systems leverages its onshore scale to compete on nacelle manufacturing cost curves.
Offshore wind denotes electricity generation from turbines mounted on fixed or floating substructures in marine environments, typically utilizing horizontal-axis machines with rotor diameters exceeding 150 meters and hub heights optimized for sustained ocean wind regimes. These installations feed baseload and peaking power into national grids while supporting industrial decarbonization targets. Fixed-bottom technology occupies the mature margin pool across shallow-water developments, while floating systems represent the fastest-growing segment as projects migrate into deeper Atlantic and Pacific waters. The end-user base concentrates among utilities with balance-sheet capacity to absorb construction risk, though independent power producers are gaining share through consortium structures.
The EU Green Deal and F-Gas Regulation shape equipment standards and refrigerant protocols for offshore substations across European waters. The UK's Contracts for Difference mechanism and Germany's Bundesnetzagentur auction rounds determine project economics and developer qualification thresholds. China's MIIT and GB standards govern domestic turbine certification and grid interconnection protocols. Stakeholders must monitor seabed leasing timelines and evolving floating foundation certification criteria as project frontiers move beyond established supply chain corridors.
Market Dynamics
Floating foundation technology is forcing a supply chain reconfiguration as developers abandon fixed-bottom economics in water depths exceeding 60 meters across the North Sea and Atlantic coastlines.
Growth Catalysts
- EU Green Deal auction mechanisms:Germany's Bundesnetzagentur and the UK's Contracts for Difference are compressing project development timelines and expanding pipeline visibility for utility-scale arrays.
- Industrial decarbonization mandates:Steel and chemical producers in the Netherlands and Denmark are signing long-term offtake agreements to secure renewable baseload from North Sea clusters.
- Monopile-to-jacket transition:Jacket substructures are displacing monopiles in deeper German Bight developments, opening fabrication contracts to specialized North Sea yards.
Market Restraints
- Steel input cost volatility:Fluctuations in European hot-rolled coil pricing are compressing turbine tower and foundation margins for EPC contractors.
- Installation vessel scarcity:Heavy-lift jack-up availability concentrates among a handful of North Sea operators, creating bottlenecks during summer construction windows.
- F-Gas Regulation compliance:The EU's phasedown of fluorinated gases is forcing substation redesigns and extending equipment qualification timelines for grid connection assets.
Strategic Opportunities
- Floating foundation certification:France and Portugal are advancing pre-commercial arrays that will establish DNV and Bureau Veritas protocols for commercial-scale deployment.
- Green hydrogen co-location:Electrolyzer integration at offshore substations is creating new revenue stacking models for developers with offtake contracts from ammonia and shipping fuel producers.
- Repowering early UK Round 1 sites:Aging 2-3 MW turbines off England's east coast present retrofit opportunities for 15 MW+ direct-drive platforms with enhanced capacity factors.
Industry Challenges
- High-voltage cable installation:Subsea HVDC routing through congested North Sea corridors requires coordination with existing oil and gas infrastructure and fishing grounds.
- Marine coordination expertise:Shortages of vessel masters with jack-up positioning experience are extending mobilization lead times and compressing installation seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Offshore Wind Market |
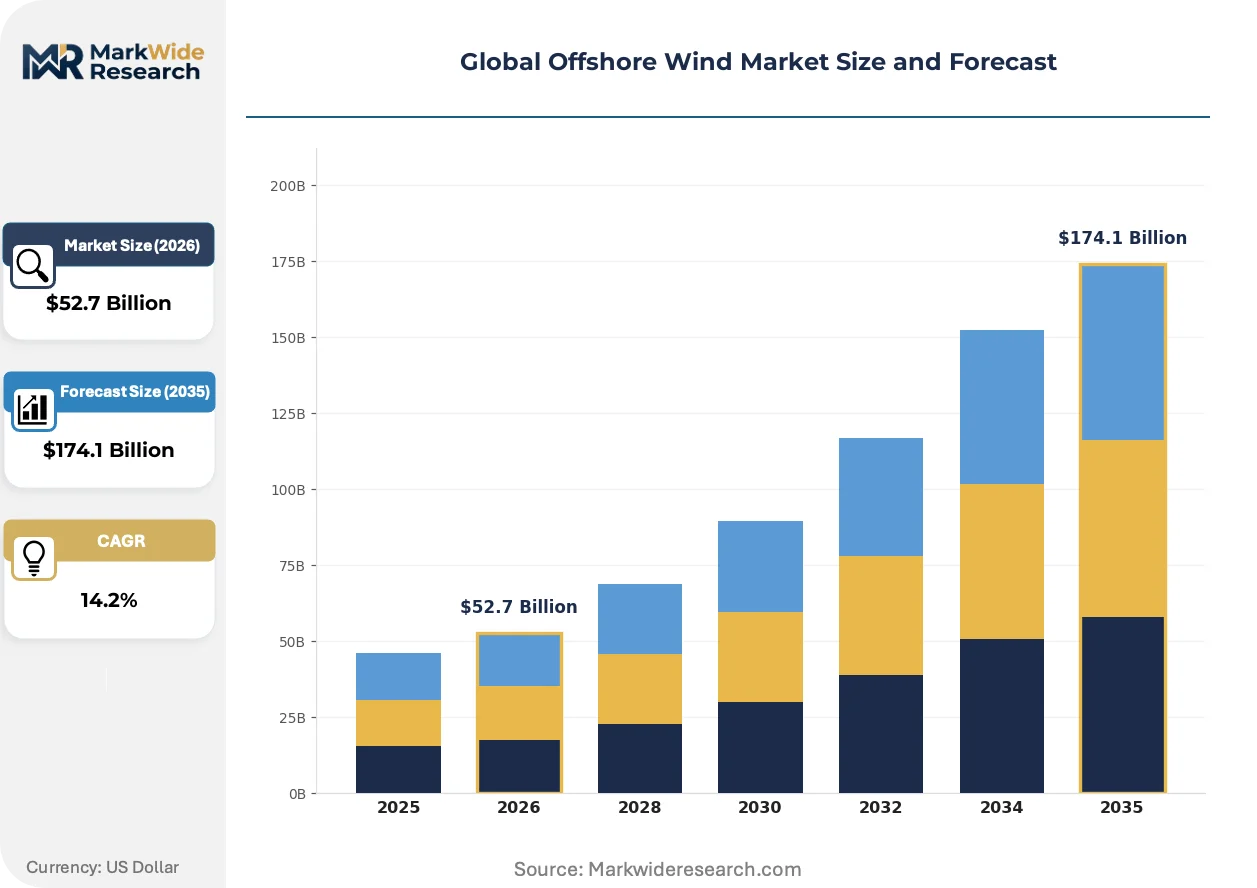
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $174.1 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fixed-Bottom, Floating, Hybrid, Turbine Type End User: Utilities, Independent Power Producers, Commercial Entities, Government Installation Type: Onshore, Offshore, Nearshore, Deepwater Service Type: Construction, Operation & Maintenance, Decommissioning, Consulting |
| Companies Covered | Ørsted, Iberdrola, RWE, Equinor, SSE Renewables, EDF Renewables, Siemens Gamesa Renewable Energy, Vestas Wind Systems, China Three Gorges Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Offshore Wind Market Strategic Shifts
Technology convergence between turbine scaling and floating platform engineering is compressing levelized cost trajectories while opening frontier geographies previously excluded from development.
Direct-drive permanent magnet generators are hybridizing with medium-speed geared architectures as OEMs optimize nacelle mass against torque density requirements. Siemens Gamesa and Vestas are both pursuing hybrid drivetrain configurations for their next offshore platforms. This hybridization is enabling rotor diameter expansion beyond 220 meters without exceeding crane capacity limits at marshaling ports.
The EU F-Gas Regulation is mandating SF6-free switchgear for offshore substations commissioned after 2026, forcing manufacturers to accelerate vacuum interrupter and fluoronitrile alternative designs. Grid operators in Germany and the Netherlands are now specifying F-gas-free equipment in tender documents. The substation electrical package segment is responding with accelerated type-testing programs at KEMA and CESI laboratories.
Utility procurement departments are consolidating turbine supply agreements into multi-site framework contracts spanning 3-5 project phases. Ørsted and RWE are unbundling installation and O&M services from turbine supply to capture margin through competitive tendering. This behavior is most visible in the UK and Danish markets where developer balance sheets support long-dated volume commitments.
Global Offshore Wind Market Segmentation
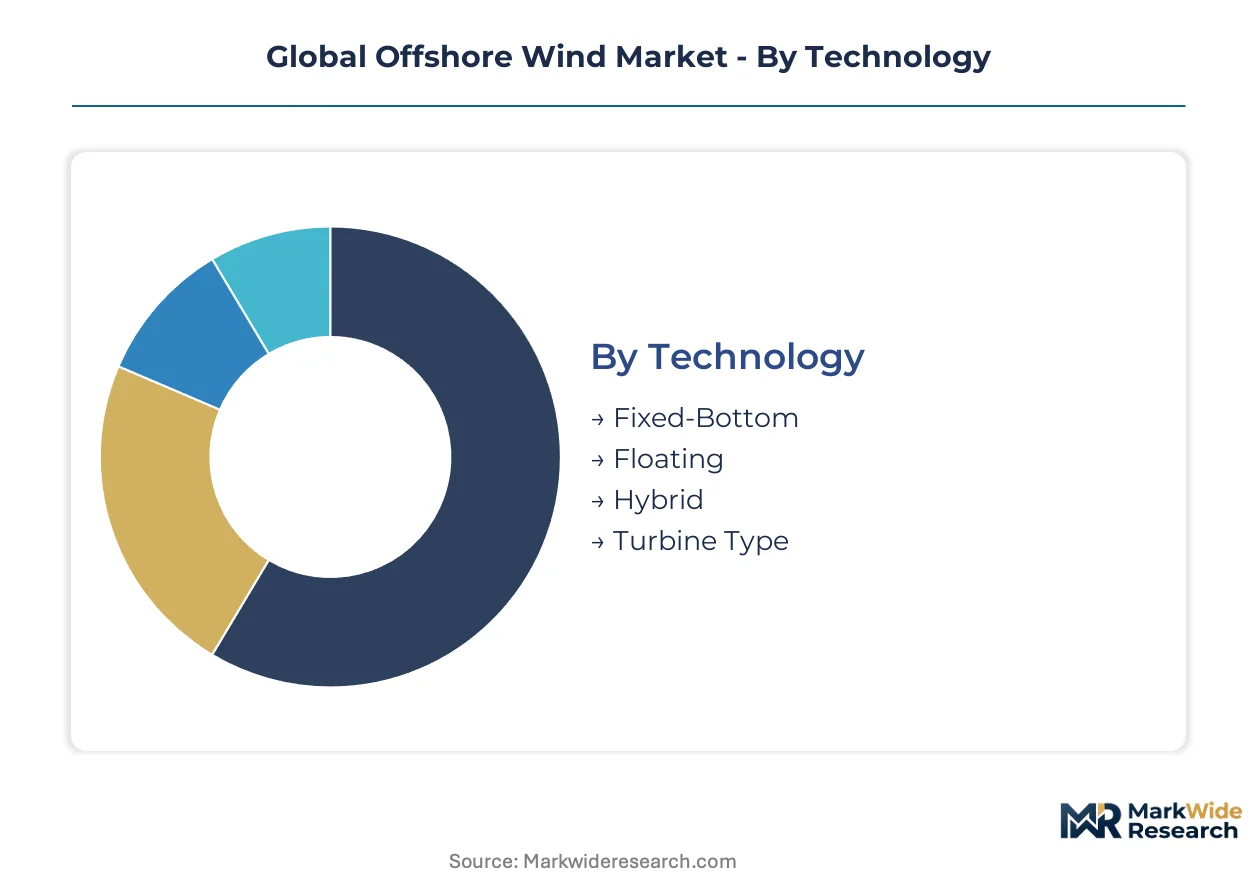
Offshore wind segmentation reveals how technology maturity, water depth economics, and procurement structures fragment addressable markets. Developers and suppliers must align capabilities against distinct risk-return profiles across foundation types, customer balance sheets, and installation environments.
Technology:
Mature fixed-bottom systems anchor shallow-water economics while emerging floating architectures unlock frontier geographies beyond 60-meter depths.
- Fixed-Bottom:Monopile and jacket substructures dominate water depths below 50 meters across the North Sea and Baltic basin. German Bight and UK East Coast clusters drive procurement volumes as established supply chains compress installation costs.
- Floating:Semi-submersible and tension-leg platforms enable development in Portuguese Atlantic waters and Japanese Pacific depths where seabed fixation proves uneconomical. France's pre-commercial arrays are establishing DNV certification protocols for commercial deployment.
- Hybrid:Combined fixed-floating systems address transitional depth zones with variable seabed conditions.
- Turbine Type:Direct-drive permanent magnet and medium-speed geared configurations optimize nacelle mass against torque density requirements.
Fixed-Bottom handles the majority of throughput; Floating is the fastest mover on share.
End User:
Balance sheet capacity determines risk absorption thresholds across the project development lifecycle.
- Utilities:Ørsted and RWE deploy integrated development models spanning origination through long-term operation. Their procurement consolidates multi-site framework agreements across UK and Danish auction rounds.
- Independent Power Producers:Consortium structures enable project participation without captive balance sheet depth. IPP share is climbing fastest as financial engineering unlocks non-utility capital.
- Commercial Entities:Steel and chemical producers in the Netherlands sign long-term offtake agreements to secure renewable baseload for industrial decarbonization mandates.
- Government:State-backed developers in China and Taiwan accelerate domestic pipeline execution through MIIT-directed procurement.
Utilities command the dominant capital deployment; Independent Power Producers are expanding most quickly through consortium mechanics.
Installation Type:
Water depth and distance from shore dictate vessel requirements, logistics complexity, and grid connection architecture.
- Onshore:Grid interconnection infrastructure and marshaling port facilities support turbine assembly sequences.
- Offshore:Heavy-lift jack-up vessels position turbines at commercial-scale arrays. UK and German developments concentrate installation demand during compressed summer windows.
- Nearshore:Reduced vessel specifications apply in sheltered waters with lower wave height exposure.
- Deepwater:Dynamic positioning vessels and floating foundation integration dominate Atlantic and Pacific frontier projects.
Offshore absorbs the principal installation spend; Deepwater is gaining share fastest as floating technology matures.
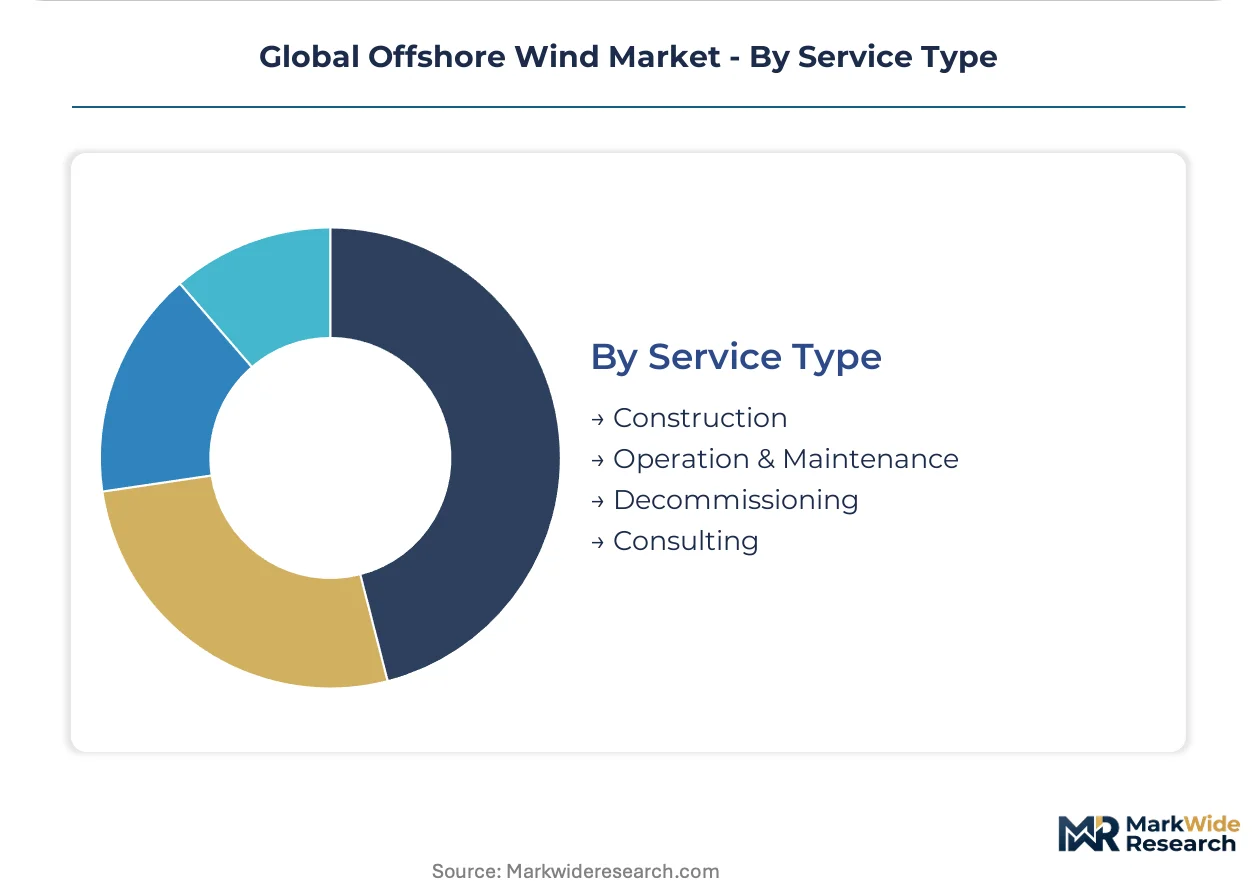
Service Type:
Revenue pools shift from construction intensity toward operational optimization as installed capacity ages.
- Construction:Foundation fabrication, turbine installation, and array cable laying consume the majority of project capex. North Sea yards specialize in jacket substructure production for deeper German developments.
- Operation & Maintenance:Long-term service agreements and captive maintenance operations are narrowing aftermarket revenue for third-party providers. OEMs extend direct O&M control through integrated project development models.
- Decommissioning:Early UK Round 1 sites approaching end-of-life create removal and repowering contracting opportunities.
- Consulting:Marine coordination, seabed leasing strategy, and F-Gas Regulation compliance advisory support developer decision-making.
Construction captures the dominant value share; Operation & Maintenance is climbing fastest as installed base scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive developers in China drive procurement volumes through state-directed auction mechanisms, while European utilities absorb premium costs for floating foundation certification and F-Gas Regulation compliance. The United Kingdom and Germany anchor the highest-value project pipelines, with Taiwan and Vietnam emerging as frontier markets where cost discipline determines developer qualification.
United Kingdom
Contracts for Difference auctions compress development timelines across the North Sea and Celtic Sea basins. The UK's seabed leasing authority, The Crown Estate, accelerates Round 4 and Round 5 site allocations. Scottish waters host floating foundation pre-commercial arrays establishing DNV certification protocols for deeper Atlantic developments.
Germany
Bundesnetzagentur auction rounds determine offshore project economics through zero-subsidy price discovery mechanisms. The F-Gas Regulation mandates SF6-free switchgear for substations commissioned after 2026. German Bight developments drive jacket substructure procurement from specialized North Sea fabrication yards in Bremerhaven and Cuxhaven.
China
MIIT-directed procurement consolidates turbine supply agreements under state-backed developers. GB standards govern domestic certification and grid interconnection protocols. Guangdong and Fujian provinces concentrate floating foundation pilot projects in deeper South China Sea waters beyond fixed-bottom viability.
Taiwan
Zonal development policy phases auction rounds across Changhua and Yunlin offshore zones. Bureau of Energy administrative procedures determine grid allocation and environmental impact assessment timelines. Kaohsiung marshaling ports support heavy-lift installation logistics for utility-scale arrays.
Vietnam
Feed-in tariff mechanisms attract international consortium structures lacking captive balance sheet depth. The Ministry of Industry and Trade governs power purchase agreement frameworks and grid connection standards. Binh Thuan and Ninh Thuan provinces concentrate nearshore development in lower wave-height exposure zones.
Global Offshore Wind Market Competitive Environment
Capability concentration sits with integrated project developers commanding full asset lifecycle control; scale advantage sits with turbine OEMs leveraging manufacturing cost curves across onshore and offshore platforms. The market structures around three tiers: utility-backed developers with captive procurement power, specialized foundation fabricators with marine yard access, and independent power producers accessing capital through consortium mechanics. Dominant competitive moves include long-term service agreement extension to capture O&M revenue pools, and multi-site framework contracting to compress turbine supply pricing across sequential auction rounds.
Among utility-anchored developers, Ørsted exemplifies integrated project development spanning origination through operation. Siemens Gamesa Renewable Energy and Vestas Wind Systems occupy positions as turbine supply anchors, with the former representing specialized direct-drive platform expertise and the latter illustrating scale-driven nacelle manufacturing economics. RWE sits within the European utility tier competing through unbundled installation and O&M service tendering.
| Leading Market Players |
|---|
| Ørsted |
| Iberdrola |
| RWE |
| Equinor |
| SSE Renewables |
| EDF Renewables |
| Siemens Gamesa Renewable Energy |
| Vestas Wind Systems |
| China Three Gorges Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese turbine component forging is compressing foundation and tower pricing across European procurement offices while forcing Baltic and North Sea fabricators into extended payment terms to retain yard utilization.
Pricing Analysis
Long-term service agreements now drive lifetime value capture as Ørsted and RWE unbundle O&M from turbine supply to compete on recurring revenue streams. Three-tier pricing structure across premium direct-drive platforms, standard geared configurations, and economy refurbished units separates OEM captive maintenance from third-party aftermarket providers. Cost compression in installation services is intensifying because heavy-lift vessel scarcity concentrates bargaining power among North Sea operators. Independent power producers exhibit highest price sensitivity through consortium bidding, while integrated utilities absorb premiums for full-lifecycle contracting.
Supply Chain Analysis
Export-control regimes on permanent-magnet rare earth processing limit generator component flows from Chinese separation facilities to European nacelle assembly plants. Supply concentrates in China for forged monopiles, South Korea for specialized jack-up vessels, and Germany for jacket substructure fabrication. The chain draws from European hot-rolled coil, Vietnamese steel processing, and Dysprosium-Terbium magnet alloys. Single-source vulnerability sits with DNV-certified floating foundation engineering concentrated in Norwegian and French naval architecture firms. Distribution runs through EPC contractor consortiums bundling turbine supply with installation and grid connection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Operation and maintenance revenue layers are expanding faster than hardware sales as turbine OEMs extend captive service agreements across 25-year asset lifecycles, creating recurring income visibility that project finance values above construction margins.
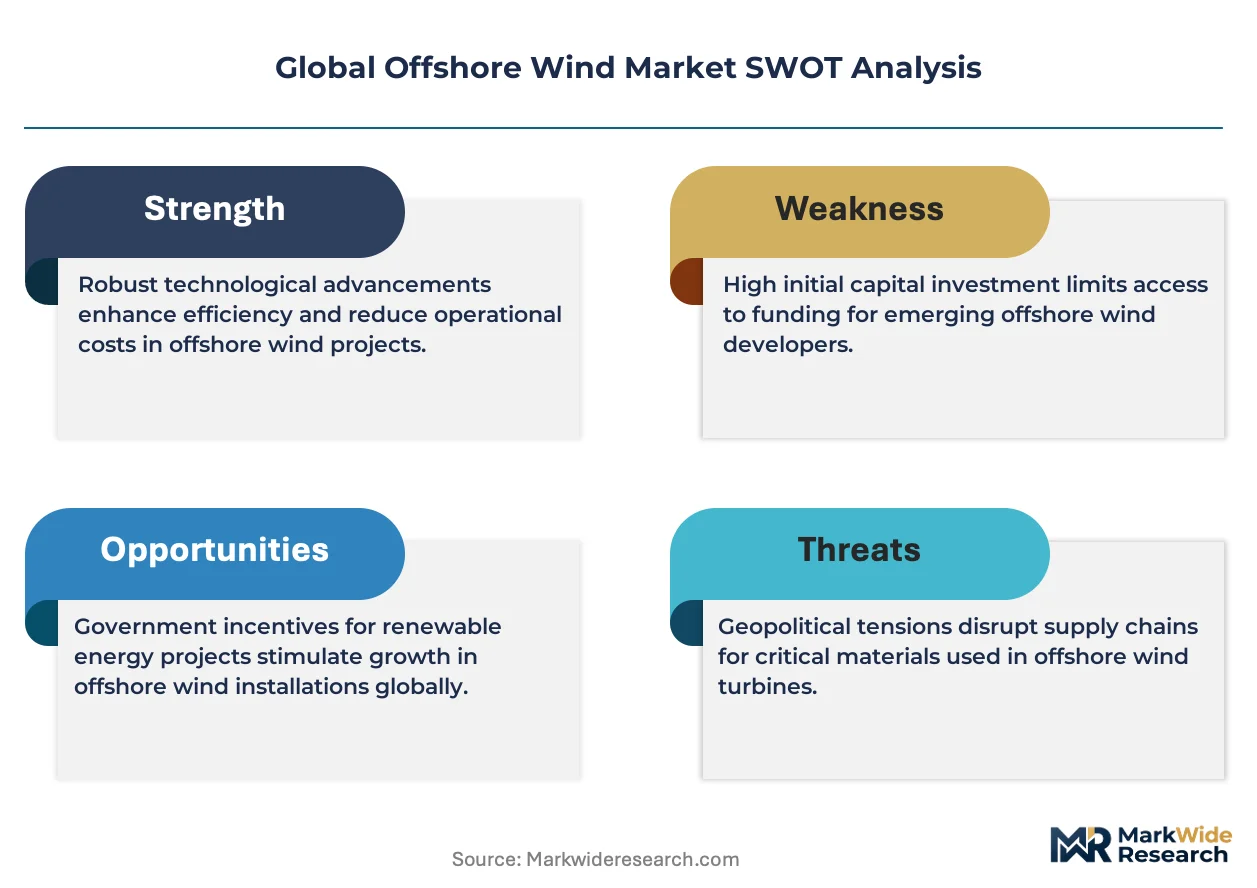
For Market Incumbents: Insulate foundation fabrication margins through backward integration into European steel rolling capacity and captive marshaling port access. Secure DNV certification protocols for floating substructures before Bureau Veritas establishes competing standards. Defend against independent power producer consortiums by locking multi-site framework contracts across sequential UK and German auction rounds. For New Entrants and Emerging Players: Floating foundation pre-commercial arrays in Portuguese Atlantic waters represent the most penetrable entry point for specialized marine engineering firms lacking utility balance sheet backing. Target electrolyzer co-location at offshore substations for ammonia and shipping fuel offtake contracts. Partner with existing heavy-lift vessel operators to bypass capital-intensive fleet ownership requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across floating foundation fabrication as semi-submersible platform engineering demands specialized naval yard infrastructure. Long-term viability favors developers with integrated origination-through-operation capabilities and captive seabed leasing pipelines. Monitor F-Gas Regulation compliance timelines as the signal indicating which substation electrical package suppliers will capture German and Dutch grid operator procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Floating Foundation Certification | DNV and Bureau Veritas protocols in French and Portuguese waters will unlock commercial-scale Atlantic and Pacific development. |
| Green Hydrogen Co-location | Electrolyzer integration at offshore substations creates revenue stacking for ammonia and shipping fuel producers. |
| Long-term Service Agreement Extension | OEMs capture O&M revenue pools by unbundling maintenance from turbine supply for Ørsted and RWE. |
| Jacket Substructure Fabrication | German Bight developments drive procurement from Bremerhaven and Cuxhaven yards as monopiles lose viability. |
| SF6-free Switchgear Deployment | EU F-Gas Regulation compliance accelerates vacuum interrupter adoption for substations commissioned after 2026. |
Study Parameters
The analysis maps fixed-bottom, floating, and hybrid foundation technologies, each validated through utility procurement officers, EPC project directors, turbine OEM supply chain managers, and marine coordination specialists. Primary interviews with these stakeholders combined with secondary validation from Bundesnetzagentur auction records, UK Contracts for Difference registers, DNV certification databases, and IEA offshore wind deployment statistics. Bottom-up project pipeline aggregation and top-down market sizing triangulate volume and value estimates.
Assumptions held fixed include EU Green Deal auction mechanism continuity and F-Gas Regulation phasedown timelines, while steel input cost volatility and vessel availability varied across scenarios. Segmentation dimensions modeled span foundation type, water depth tier, end-user balance sheet capacity, and installation environment across the projection horizon. CAGRs derive from auction round pipeline visibility and capacity factor improvements from next-generation direct-drive platforms.
Macroeconomic conditions sit as an overlay; deviation in European hot-rolled coil pricing, offshore installation vessel day rates, or seabed leasing timeline delays would shift the trajectory. Forecasts reflect these documented assumptions. Material shifts in floating foundation certification protocols or F-Gas Regulation enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Global Wind LIDAR Market
Wind Energy Systems
Wind Power Market
Wind Energy Systems
Wind Power SCADA Market
Wind Energy Systems
India Wind Energy Market
Wind Energy Systems
Wind Turbine Pitch System Sales Market
Wind Energy Systems
Wind Turbine Forged Tower Flange Market
Wind Energy Systems
Wind Power Couplings Market
Wind Energy Systems
Wind Energy Equipment Logistics Market
Wind Energy Systems
Europe Wind Power Equipment Market
Wind Energy Systems
Airborne Wind Turbines Market
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Wind Turbine Nacelle Market
Wind Energy Systems
Wind Blades NDT Market
Wind Energy Systems
Chile Wind Energy Market
Wind Energy Systems
Global Marine Wind Turbine Market
Wind Energy Systems
Middle-East and Africa Wind Power Market