
 Small Wind Turbine Market | 2026-2036
Small Wind Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Small Wind Turbine Market Analysis
Buyer concentration in the small wind turbine sector is decoupling from traditional utility-scale procurement patterns as agricultural cooperatives and remote industrial offtakers fragment demand across decentralized projects. Ryse Energy leverages its hybrid system architecture to serve island and off-grid communities across multiple continents. SD Wind Energy Ltd anchors its position through British manufacturing scale and direct-to-farmer distribution channels. Bergey Windpower Co. sustains decades of technical credibility in the American residential segment through conservative power curve ratings and extended warranty programs.
Small wind turbines convert kinetic wind energy into electrical power through rotor-driven generators, typically rated below 100 kW and designed for distributed deployment without extensive transmission infrastructure. Horizontal axis configurations dominate unit shipments due to higher aerodynamic efficiency and established certification protocols, while vertical axis designs occupy niche applications where omnidirectional wind capture and reduced noise signatures justify premium positioning. Grid-connected technology segments lead value generation where net metering policies remain active, though off-grid and hybrid systems represent the fastest-expanding category as battery cost curves improve rural project economics. Rooftop-mounted installations command elevated margins in urban commercial settings despite stricter structural engineering requirements.
FAA obstruction lighting standards, IEC 61400-2 design requirements, and local zoning ordinances collectively shape product certification costs and site approval timelines across the United States. EPA renewable energy incentives intersect with state-level interconnection rules to determine effective payback periods for agricultural and commercial adopters. Stakeholders must monitor evolving distributed generation tariff structures and emerging cybersecurity mandates for grid-connected small turbines as electrification priorities shift.
Market Dynamics
Hybrid energy architectures are restructuring deployment economics as lithium-ion battery cost curves intersect with distributed generation policy frameworks, compressing payback periods for agricultural and remote industrial adopters.
Growth Catalysts
- Rural Electrification Mandates:Sub-Saharan African government programs are accelerating off-grid turbine installations in agricultural corridors where grid extension remains economically prohibitive.
- Net Metering Preservation:State-level distributed generation tariffs in the American Midwest sustain favorable economics for farm-scale installations despite federal policy uncertainty.
- Blade Material Substitution:Advanced composite manufacturing is reducing rotor mass and enabling modular transport to remote sites without heavy-lift infrastructure.
Market Restraints
- Copper and Rare Earth Volatility:Permanent magnet supply concentration in processing facilities creates input cost instability for direct-drive generator architectures.
- IEC 61400-2 Certification Burden:Small turbine manufacturers face disproportionate testing costs relative to unit revenue, favoring incumbents with amortized laboratory infrastructure.
- Solar PV Cost Compression:Crystalline silicon module pricing is undercutting small wind in hybrid configurations where wind resource variability exceeds solar intermittency trade-offs.
Strategic Opportunities
- Island Microgrid Integration:Caribbean and Pacific island utilities are procuring wind-battery hybrids to displace diesel generation where fuel logistics consume operational budgets.
- Telecom Tower Power:Remote cellular infrastructure operators are adopting small turbines to reduce diesel runtime and tower maintenance cycles.
- Agrivoltaic-Wind Co-location:Dual-use land frameworks in Germany and the Netherlands are permitting turbine deployment within solar arrays without agricultural land conversion penalties.
Industry Challenges
- Installation Technician Scarcity:Certified small wind technicians remain concentrated in legacy markets, constraining deployment velocity in emerging geographies.
- Grid Interconnection Queues:Distribution utility backlogs for impact studies and equipment upgrades delay commercial project commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Wind Turbine Market |
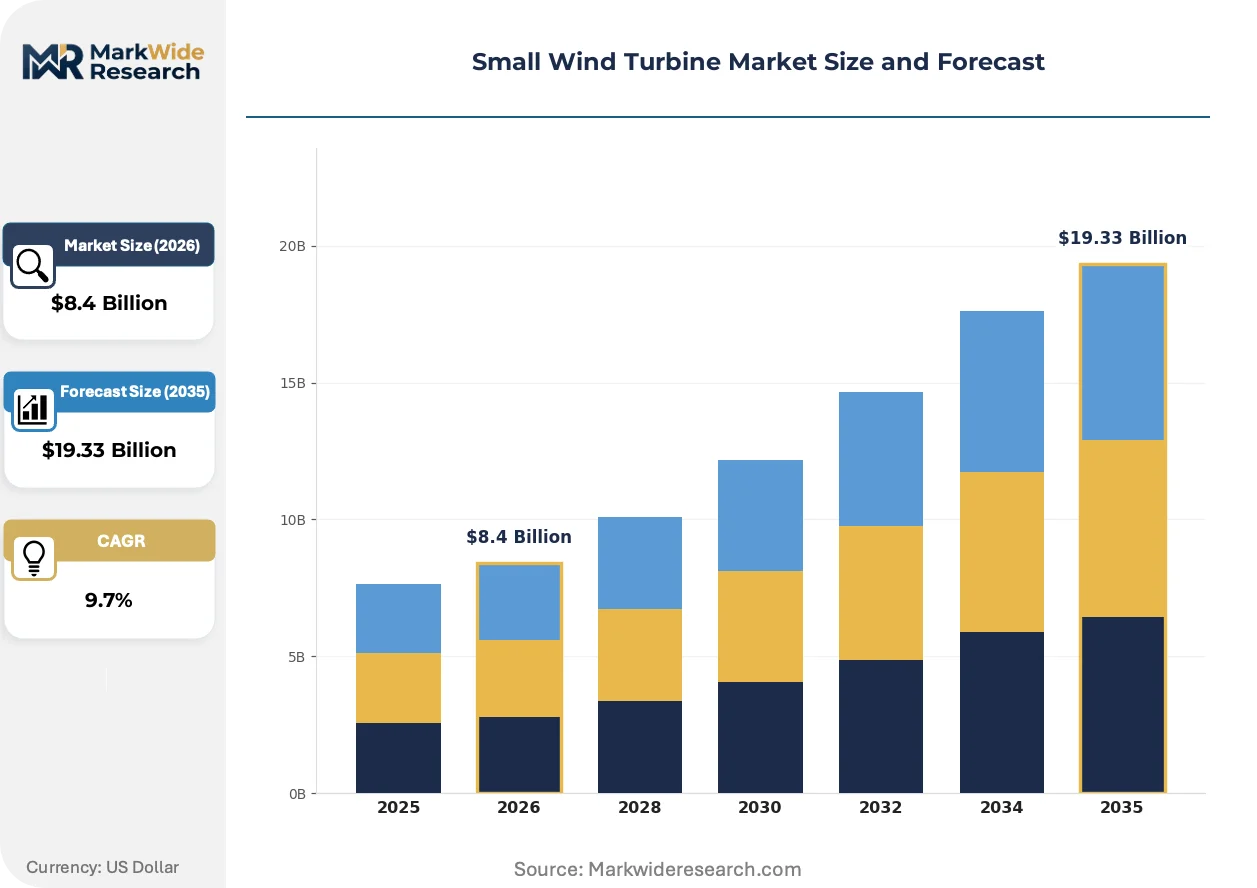
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis, Vertical Axis, Rooftop-mounted, Portable Technology: Grid-connected, Off-grid, Hybrid Systems, Smart Turbines End User: Residential, Commercial, Agricultural, Remote Areas Installation: Onshore, Offshore, Rooftop, Ground-mounted |
| Companies Covered | Ryse Energy, SD Wind Energy Ltd, Bergey Windpower Co., Eocycle Technologies Inc., Xzeres Wind Corporation, Aeolos Wind Energy Ltd., Kingspan Group, TUGE Energia, Northern Power Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Wind Turbine Market Emerging Trajectories
Active pitch control systems and predictive maintenance algorithms are converging to reshape operational economics, reducing lifetime cost structures while extending service intervals for distributed turbine fleets.
Condition monitoring hardware is automating fault detection in drivetrain components before catastrophic failure. Agricultural cooperatives in the American Midwest are retrofitting existing installations with vibration sensors and oil particulate analyzers. This capability is automating maintenance scheduling and compressing unplanned downtime intervals for remote sites without on-site technical staff.
The EU Green Deal's renewable hydrogen production targets are redirecting small turbine deployment toward electrolyzer co-location projects. Electrolyzer offtake agreements now dominate project finance structures in Denmark and the Netherlands. Grid-connected turbines in these configurations are securing 15-20 year power purchase contracts that were previously unavailable to sub-100kW installations.
Direct-to-farmer distribution channels are displacing traditional installer networks in North American agricultural markets. Equipment manufacturers are establishing regional service hubs and financing partnerships with agricultural credit unions. This channel restructuring is most advanced in Iowa and Illinois, where cooperative purchasing agreements now account for the dominant share of new unit deployments.
Small Wind Turbine Market Segmentation
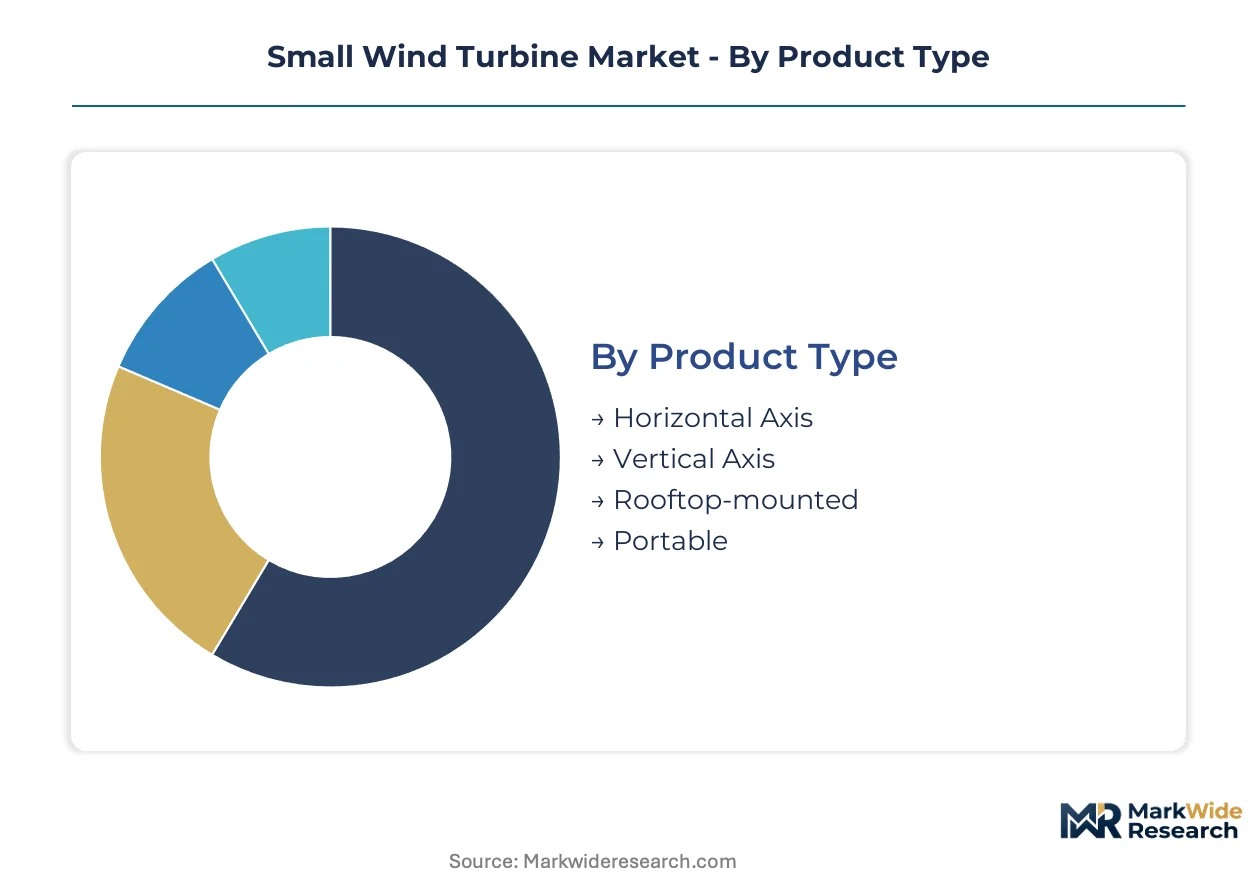
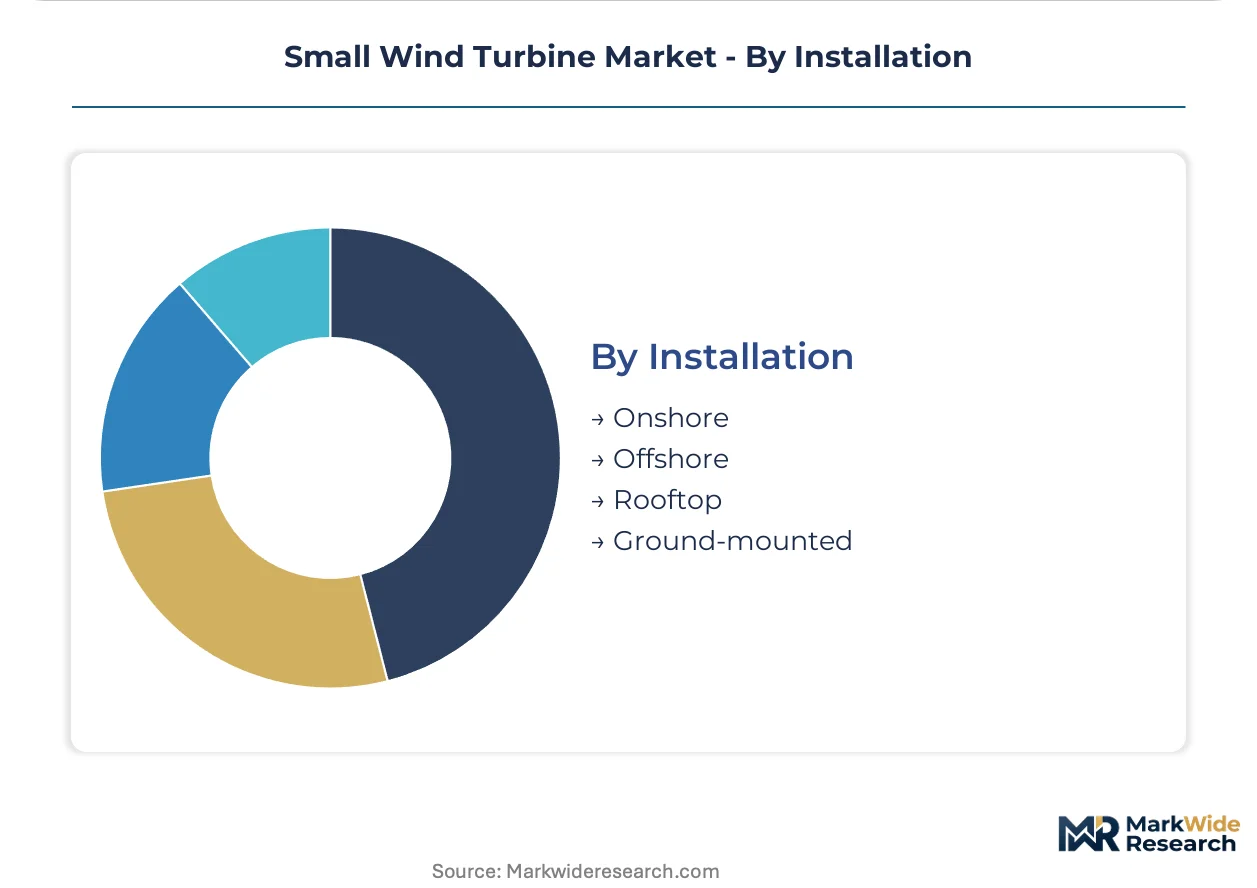
Segmentation in the small wind turbine market determines certification pathways, financing structures, and distribution channel selection. Product configuration and deployment context shape everything from FAA lighting requirements to agricultural credit union lending terms.
Product Type:
Customization intensity varies from standardized horizontal axis units to bespoke rooftop installations requiring structural engineering review.
- Horizontal Axis:Rotor blades rotate around a horizontal shaft, capturing wind through aerodynamic lift with higher efficiency coefficients. Agricultural cooperatives in the American Midwest concentrate procurement here, driven by established IEC 61400-2 certification protocols and conservative power curve ratings that satisfy lender risk assessments.
- Vertical Axis:Omnidirectional rotors eliminate yaw mechanisms and reduce noise signatures through lower tip speeds. Urban commercial installations in Germany and the Netherlands favor this configuration where zoning ordinances restrict audible emissions and turbulent wind patterns dominate.
- Rooftop-mounted:Compact designs integrate with building structures, requiring site-specific structural analysis and mounting hardware.
- Portable:Modular, transportable units deploy to remote sites without permanent foundations, serving disaster relief and temporary industrial power needs.
Most installed capacity flows through Horizontal Axis. Expansion is steepest in Rooftop-mounted.
Technology:
Cost tier separation distinguishes premium smart turbine architectures from basic off-grid configurations.
- Grid-connected:Synchronous generators feed utility networks under net metering or feed-in tariff frameworks. Sub-Saharan African rural electrification programs are accelerating procurement here where grid extension costs prove prohibitive and national utilities seek distributed generation assets.
- Hybrid Systems:Wind-solar-battery integration optimizes capacity factors and reduces diesel runtime in remote applications. Caribbean island utilities are deploying these configurations to displace fuel logistics costs that consume operational budgets.
- Off-grid:Standalone battery-coupled systems serve locations beyond transmission infrastructure, common in telecom tower power applications.
- Smart Turbines:Embedded sensors and predictive algorithms automate pitch control and maintenance scheduling, commanding premium positioning.
Grid-connected retains the dominant share of value generation. Hybrid Systems are climbing the fastest as lithium-ion cost curves improve.
End User:
Application context drives specification divergence from residential noise constraints to agricultural durability requirements.
- Agricultural:Farm-scale installations range from 10kW to 100kW, powering irrigation pumps, grain drying, and livestock operations. Direct-to-farmer distribution channels through Iowa and Illinois agricultural credit unions are restructuring procurement patterns, with cooperative purchasing agreements now accounting for dominant deployment share.
- Remote Areas:Off-grid communities and industrial sites prioritize reliability over efficiency metrics. Island microgrids across the Pacific and Caribbean are procuring wind-battery hybrids to reduce diesel generator runtime and eliminate fuel logistics vulnerabilities.
- Residential:Sub-10kW units serve single-family homes, constrained by zoning setbacks and homeowner association restrictions.
- Commercial:Urban and suburban businesses seek renewable energy credentials and demand charge reduction.
Agricultural absorbs the majority of unit shipments. Remote Areas are gaining share fastest as electrification mandates accelerate.
Installation:
Geographic and structural deployment context determines foundation requirements, permitting complexity, and maintenance access economics.
- Ground-mounted:Tower foundations anchor turbines in open terrain, enabling taller hub heights and cleaner wind resources. The American Midwest concentrates deployment here, with FAA obstruction lighting standards and local zoning ordinances shaping site approval timelines.
- Onshore:Terrestrial installations across varied terrain, subject to national electrical codes and environmental review.
- Rooftop:Building-integrated mounting requires structural engineering certification and typically limits turbine scale.
- Offshore:Marine environments demand corrosion-resistant materials and specialized installation vessels, rare below 100kW scale.
Ground-mounted dominates cumulative capacity. Rooftop is expanding most quickly in urban commercial settings despite elevated structural engineering costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified small wind technicians concentrate in legacy markets, constraining deployment velocity in emerging geographies while established manufacturing clusters anchor regional supply chains.
United States
Agricultural cooperatives across Iowa and Illinois drive farm-scale procurement through direct-to-farmer distribution channels. FAA obstruction lighting standards and local zoning ordinances shape site approval timelines. The American Midwest concentrates ground-mounted installations where net metering policies sustain favorable project economics.
Germany
Feed-in tariff revisions redirect installer focus toward self-consumption models in distributed agricultural settings. EU Green Deal renewable hydrogen targets redirect small turbine deployment toward electrolyzer co-location projects. The Netherlands and Germany jointly permit agrivoltaic-wind co-location within solar arrays without agricultural land conversion penalties.
China
Dual carbon goals accelerate distributed generation deployment across rural electrification corridors. GB standards and MIIT directives shape certification pathways for sub-100kW turbine architectures. Yangtze River Delta manufacturing clusters supply composite blade materials to domestic and export markets.
Denmark
Electrolyzer offtake agreements dominate project finance structures for grid-connected turbines. National renewable hydrogen production targets secure 15-20 year power purchase contracts previously unavailable to small-scale installations. Copenhagen-area technical institutes train specialized technicians for hybrid system integration.
Kenya
Rural electrification programs accelerate off-grid turbine installations in agricultural corridors where grid extension remains economically prohibitive. National utility distributed generation asset procurement prioritizes wind-battery hybrids. Nairobi-based installer networks expand into neighboring sub-Saharan markets.
Small Wind Turbine Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers, with market structure fragmenting across hybrid system integrators, British manufacturing scale players, and American residential segment incumbents. Three archetypes dominate: hybrid architecture specialists serving island microgrids, direct-to-farmer distributors leveraging agricultural credit union partnerships, and conservative power curve rating defenders emphasizing extended warranty programs. Competitive moves concentrate on geographic expansion into telecom tower power applications and backward integration into advanced composite blade manufacturing.
Within the hybrid system tier, Ryse Energy exemplifies the island and off-grid community specialist archetype across multiple continents. SD Wind Energy Ltd represents British manufacturing scale with direct-to-farmer distribution channel positioning. Bergey Windpower Co. anchors the American residential segment through technical credibility built across decades of conservative power curve ratings.
| Leading Market Players |
|---|
| Ryse Energy |
| SD Wind Energy Ltd |
| Bergey Windpower Co. |
| Eocycle Technologies Inc. |
| Xzeres Wind Corporation |
| Aeolos Wind Energy Ltd. |
| Kingspan Group |
| TUGE Energia |
| Northern Power Systems Inc. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap manufacturers anchor rotor blade and generator assembly capacity across Denmark and northern Germany, translating generational balance-sheet discipline into stable pricing for agricultural cooperatives while resisting margin erosion from volatile rare earth inputs.
Pricing Analysis
Bundled turnkey installation services separate from unbundled equipment-only transactions across most procurement channels. Three-tier pricing structure across IEC 61400-2 certified premium units, standard agricultural configurations, and economy off-grid systems reflects certification burden amortization and warranty duration. Pricing pressure stems from solar PV module cost compression in hybrid configurations where lithium-ion battery pairing favors solar dominance. Agricultural cooperatives in Iowa and Illinois exhibit highest price sensitivity through cooperative purchasing agreements, while Caribbean island utilities accepting 15-20 year power purchase contracts show lowest sensitivity due to diesel displacement economics.
Supply Chain Analysis
Freight costs for modular blade transport constrain site selection economics where heavy-lift infrastructure remains absent. Composite manufacturing concentrates in China, Denmark, and the American Midwest, drawing from carbon fiber feedstock and epoxy resin suppliers. Permanent magnet generators rest on rare earth processing concentration creating single-source vulnerability through Chinese separation facilities. Distribution runs through direct-to-farmer channels displacing traditional installer networks in North American agricultural markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where agricultural cooperatives and island utilities are redirecting procurement toward predictive maintenance-enabled smart turbines with embedded condition monitoring.
For Market Incumbents: Cement technical credibility through conservative power curve ratings and extended warranty programs that satisfy agricultural credit union risk assessments. Deepen backward integration into advanced composite blade manufacturing to offset rare earth cost volatility. Defend against solar PV substitution in hybrid configurations by emphasizing wind capacity factor advantages in temperate coastal zones. For New Entrants and Emerging Players: The premium-to-economy price gap in telecom tower power applications offers white-space entry where diesel runtime reduction commands urgent procurement. Target Pacific and Caribbean island microgrids where fuel logistics consume operational budgets and incumbent service networks remain thin. Pursue electrolyzer co-location project finance structures in Denmark and the Netherlands where EU Green Deal hydrogen targets secure long-dated offtake agreements unavailable elsewhere. For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid system integrators with island microgrid installation track records and established technician training partnerships. Long-term viability favors specialists with captive blade manufacturing and battery integration capabilities over pure-play turbine assemblers. Watch feed-in tariff revision trajectories in Germany and net metering policy durability in the American Midwest as inflection indicators for distributed generation asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Blade Manufacturing | Captive carbon fiber supply secures rotor mass reduction and modular transport economics for remote site deployment. |
| Predictive Maintenance Platform Deployment | Vibration sensors and oil particulate analyzers automate fault detection for agricultural cooperatives without on-site technical staff. |
| Electrolyzer Co-location Partnership | Grid-connected turbines in Denmark secure 15-20 year power purchase contracts through EU Green Deal hydrogen production mandates. |
| Direct-to-Farmer Distribution Channel Expansion | Regional service hubs and agricultural credit union financing partnerships in Iowa and Illinois accelerate cooperative purchasing agreement capture. |
| Island Microgrid Integration Certification | Wind-battery hybrid validation for Caribbean and Pacific utilities displaces diesel generation where fuel logistics dominate operational budgets. |
Methodological Framework
Multiple input streams — structured interviews with turbine OEM engineering directors, agricultural cooperative procurement managers, and island utility planning officers; secondary validation through IEC certification databases, FERC interconnection queues, and EIA distributed generation statistics; customs records for composite blade trade flows — were reconciled through bottom-up installation tracking and top-down market sizing across the analysis window.
Data-stream reconciliation anchored volume projections to segmented deployment economics by technology configuration and end-use application. The analytical framework modeled horizontal versus vertical axis adoption, grid-connected against hybrid system penetration, and ground-mounted versus rooftop installation share across the projection horizon. CAGRs derived from policy incentive trajectories, lithium-ion cost curve assumptions, and agricultural electrification program commitments in sub-Saharan Africa and the American Midwest.
Caveats apply where feed-in tariff revisions, net metering policy rescissions, or rare earth supply disruptions could materially shift the outlook. Forecasts reflect assumptions about technician training pipeline expansion and distribution utility interconnection queue clearance rates. A model refresh is warranted upon material change in EU Green Deal hydrogen production subsidy levels or FAA obstruction lighting standard revisions affecting small turbine siting economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Peru Wind Energy Market
Wind Energy Systems
Europe Wind Power Equipment Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Japan Wind Energy Market
Wind Energy Systems
Double-Fed Wind Turbine Market
Wind Energy Systems
Sweden Wind Energy Market
Wind Energy Systems
Wind Turbine Control System Market
Wind Energy Systems
India Wind Energy Market
Wind Energy Systems
Germany Wind Energy Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Ecuador Wind Energy Market
Wind Energy Systems
Global Offshore Wind Market
Wind Energy Systems
Chile Wind Energy Market
Wind Energy Systems
Offshore Wind Power Market
Wind Energy Systems
Wind Power SCADA Market
Wind Energy Systems
Quiet Wind Turbine Market