
 Wind Power Forgings Market | 2026-2036
Wind Power Forgings Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Power Forgings Market Insights
The EU Green Deal is shifting procurement criteria for wind farm developers toward verified low-carbon steel forgings, tightening supply qualification. Bharat Forge leverages its Indian forge network to serve European OEMs seeking alternative sourcing. Thyssenkrupp anchors German manufacturing with integrated steel-to-forging capability for offshore towers. Scot Forge specializes in custom open-die production for prototype and replacement turbine shafts across North American wind corridors.
Wind power forgings are metal components shaped under compressive force, typically produced from low-alloy steels with tensile strengths exceeding 600 MPa to withstand cyclic rotor loads and corrosive offshore environments. These parts form the structural backbone of drivetrains, connecting hubs to gearboxes and generators in multi-megawatt turbines. Flanges and shafts dominate current output volumes, reflecting their ubiquity across onshore and offshore nacelle designs, while rings and housings capture expanding margin pools as turbine diameters grow. Steel retains absolute material share due to fatigue resistance requirements, though specialized alloys gain traction in direct-drive permanent magnet generators where electromagnetic and mechanical stresses converge.
FDA, EPA, and OSHA standards govern worker exposure and environmental compliance at US forge facilities, while REACH and CE marking regulate chemical content and structural certification for European-sourced components. China's GB standards and MIIT directives shape domestic content rules that constrain foreign forge participation in national wind tenders. Stakeholders must monitor evolving carbon border adjustment mechanisms and local content thresholds that threaten to fragment forge supply chains into regionally captive networks.
Market Dynamics
The offshore turbine capacity race beyond 15 MW is compressing forge lead times and forcing capacity reallocation toward extra-large rings and shafts that only a handful of facilities can produce. OEM qualification cycles now stretch 18-24 months, locking supplier relationships before final investment decisions on wind farms.
Growth Catalysts
- EU Green Deal low-carbon steel mandates:The framework's embodied carbon thresholds for structural components are redirecting procurement toward forge shops with electric arc furnace feedstock and verified Scope 3 data.
- Direct-drive generator proliferation:Permanent magnet synchronous generators eliminate gearboxes but demand larger forged rotor hubs with tighter dimensional tolerances, expanding addressable component value per turbine.
- China's coastal province installation surge:Provincial renewable portfolio standards in Jiangsu and Guangdong are accelerating 10+ MW offshore deployment, absorbing domestic forge capacity and tightening export availability.
Market Restraints
- Scrap steel price volatility:Electric arc furnace operators face margin compression when shredded auto scrap fluctuates, forcing long-term contract renegotiations with wind OEMs.
- European forge concentration:Germany, Italy, and Spain host 70% of EU heavy forging capacity for wind, creating single-source vulnerability when maintenance cycles collide.
- Heat treatment bottleneck:Quenching and tempering furnaces sized for 12+ meter shafts require 48-hour thermal cycles that throttle throughput regardless of forging press availability.
Strategic Opportunities
- India PLI scheme for renewable manufacturing:Production-linked incentives for wind component exports are attracting forge investments in Maharashtra and Tamil Nadu to serve Middle East and African markets.
- Floating offshore foundation forgings:Tension leg platforms and semi-submersible designs require novel mooring connector geometries that incumbent suppliers have not tooled for.
- Blade root bearing integration:Conventional three-point suspension drivetrains are giving way to integrated main bearing housings that combine forged rings with planetary gear interfaces.
Industry Challenges
- Ultrasonic testing technician scarcity:ASME and EN standards for 300+ millimeter section forgings require certified Level II inspectors that training pipelines have not replenished.
- Multi-axis machining alignment:Five-meter diameter flanges demand simultaneous five-side machining with micron-level concentricity that legacy horizontal boring mills cannot achieve.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Power Forgings Market |
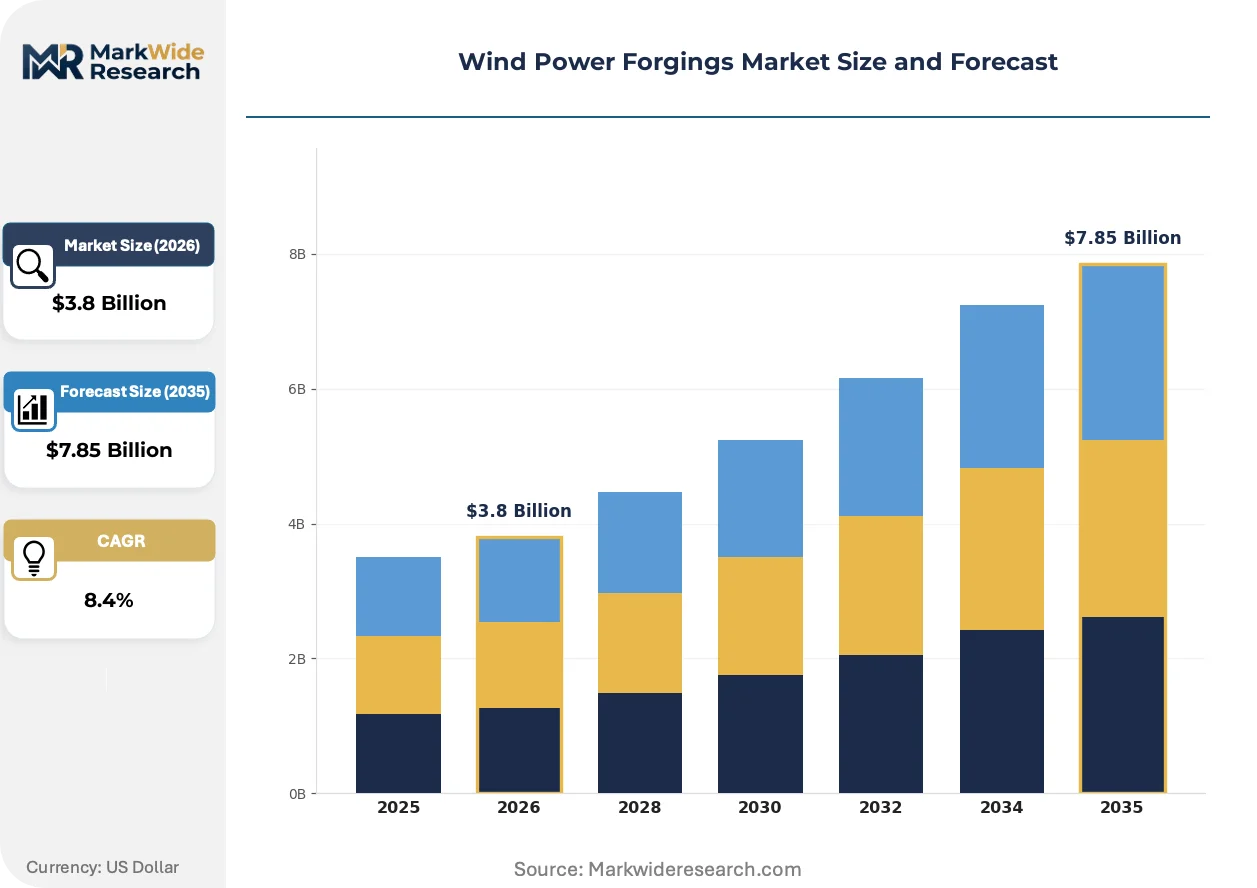
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flanges, Shafts, Rings, Housings Material: Steel, Aluminum, Titanium, Alloys Application: Turbine Components, Gearboxes, Hub Assemblies, Rotor Blades End User: OEMs, Component Manufacturers, Wind Farm Operators, Maintenance Providers |
| Companies Covered | Bharat Forge, Scot Forge, Thyssenkrupp, China First Heavy Industries, Larsen & Toubro, Forgital Group, Ellwood Group, Jiangsu Pacific Precision Forging, Bruck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Power Forgings Market Trends and Innovations
Digital thread implementation is compressing the gap between melt shop chemistry control and final dimensional inspection, allowing forge shops to certify components before cutting test coupons. This integration of process data is reshaping how OEMs audit supplier quality systems.
Hybrid steel-titanium bearing races are integrating composite material layers into forged outer rings to reduce nacelle weight in turbines exceeding 20 MW rated capacity. Siemens Gamesa and Vestas are qualifying these hybrid designs for North Sea projects where crane lift constraints dominate installation economics. The technology is integrating electromagnetic simulation with mechanical forging parameters to optimize grain flow around sensor mounting bosses.
REACH Annex XVII restrictions on chromium VI compounds in anti-corrosion coatings are forcing forge shops to convert from chromate-based passivation to trivalent chrome or silane-based alternatives. The industrial consequence is extended salt spray testing cycles that delay component release by 6-8 weeks. Offshore tower flanges for Baltic Sea projects are most affected, with German TÜV auditors requiring documentation of coating migration paths through supply chains.
Consolidated procurement desks at major OEMs are replacing discrete component tenders with multi-year framework agreements covering shafts, rings, and housings across turbine platforms. Tier-one suppliers are responding by absorbing secondary forging houses to secure capacity commitments. This concentration is most visible in Denmark and Germany, where Vestas and Siemens Gamesa procurement teams have reduced qualified forge suppliers by 40% since 2022.
Wind Power Forgings Market Segmentation
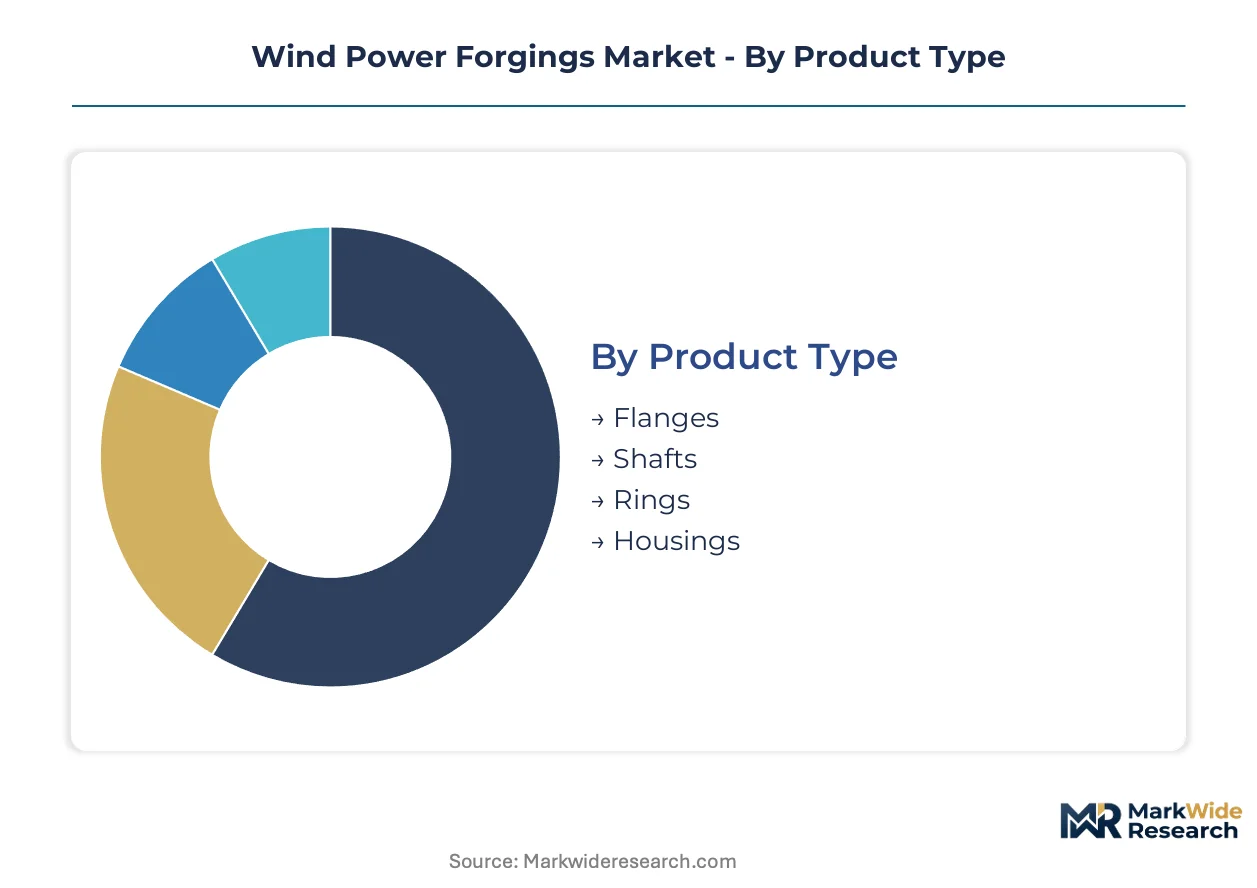
Wind power forgings exhibit sharp demand heterogeneity across product geometries and material specifications. Turbine scaling beyond 15 MW is fragmenting procurement into volume-driven standard components and precision-engineered specialty forgings with divergent margin profiles.
Product Type:
Volume production concentrates in legacy shaft and flange geometries, while premium value migrates toward integrated housings and extra-large rings for direct-drive architectures.
- Flanges:Circular forged plates with bolt-hole patterns connect tower sections and nacelle modules, typically produced from normalized low-alloy steel grades. Demand clusters in China and Germany where coastal offshore projects require 5+ meter diameter tower flanges with through-thickness toughness properties specified by DNV certification.
- Shafts:Step-forged cylindrical components transmit rotor torque to gearboxes or generators, demanding longitudinal grain flow alignment for fatigue resistance. Procurement from European OEMs favors integrated steel-to-forging suppliers with in-house heat treatment capacity, compressing lead times for 12+ meter main shafts.
- Rings:Seamless rolled rings form bearing races and hub interfaces, with dimensional tolerances tightening as rotor diameters expand.
- Housings:Complex enclosed geometries for gearbox and generator enclosures capture expanding margin pools through multi-axis machining integration.
Mature deployment sits with flanges and shafts. Newer deployment is concentrated in rings and housings for direct-drive and floating foundation architectures.
Material:
Cost tier stratification separates commodity steel grades from performance-optimized alloys and emerging lightweight alternatives.
- Steel:Low-alloy quenched-and-tempered grades dominate absolute tonnage, with specified minimum yield strengths of 355-690 MPa per EN 10025-3 offshore standards. Chinese forge capacity expansion tracks Jiangsu and Guangdong provincial installation targets, absorbing domestic electric arc furnace output before export availability.
- Alloys:Nickel-chromium-molybdenum formulations address extreme section thickness requirements in 20+ MW turbine shafts, where ultrasonic testing protocols exceed standard commercial grades. Premium pricing reflects vacuum degassing and ladle metallurgy investments at specialized European melt shops.
- Aluminum:Cast-forged hybrid approaches reduce nacelle weight in prototype direct-drive generators, though fatigue performance limits structural load-bearing applications.
- Titanium:Hybrid bearing race applications integrate forged titanium layers with steel substrates for corrosion-critical offshore environments.
Steel retains mature manufacturing scale and certification heritage. Alloys are gaining share fastest in extra-large component specifications beyond standard mill capacity.
Application:
Customer engineering integration levels distinguish captive in-house forging from merchant supply to external drivetrain assemblers.
- Turbine Components:Main shafts, bedplates, and tower flanges constitute the foundational structural category, with procurement cycles synchronized to nacelle assembly schedules at Vestas, Siemens Gamesa, and Goldwind facilities.
- Gearboxes:Planetary carrier forgings and ring gears require case-hardening compatibility and tooth-form machining allowances, with ZF and Winergy qualifying suppliers on 18-month validation protocols.
- Hub Assemblies:Pitch bearing housings and blade root connectors integrate forged rings with cast iron or welded steel structures, demanding thermal expansion coefficient matching across material interfaces.
- Rotor Blades:Forged root inserts and T-bolt anchors transfer aerodynamic loads into blade laminate structures, with geometry standardization lagging behind metal component categories.
Hub assemblies represent the fastest-expanding application segment as integrated main bearing designs displace conventional three-point suspension architectures.
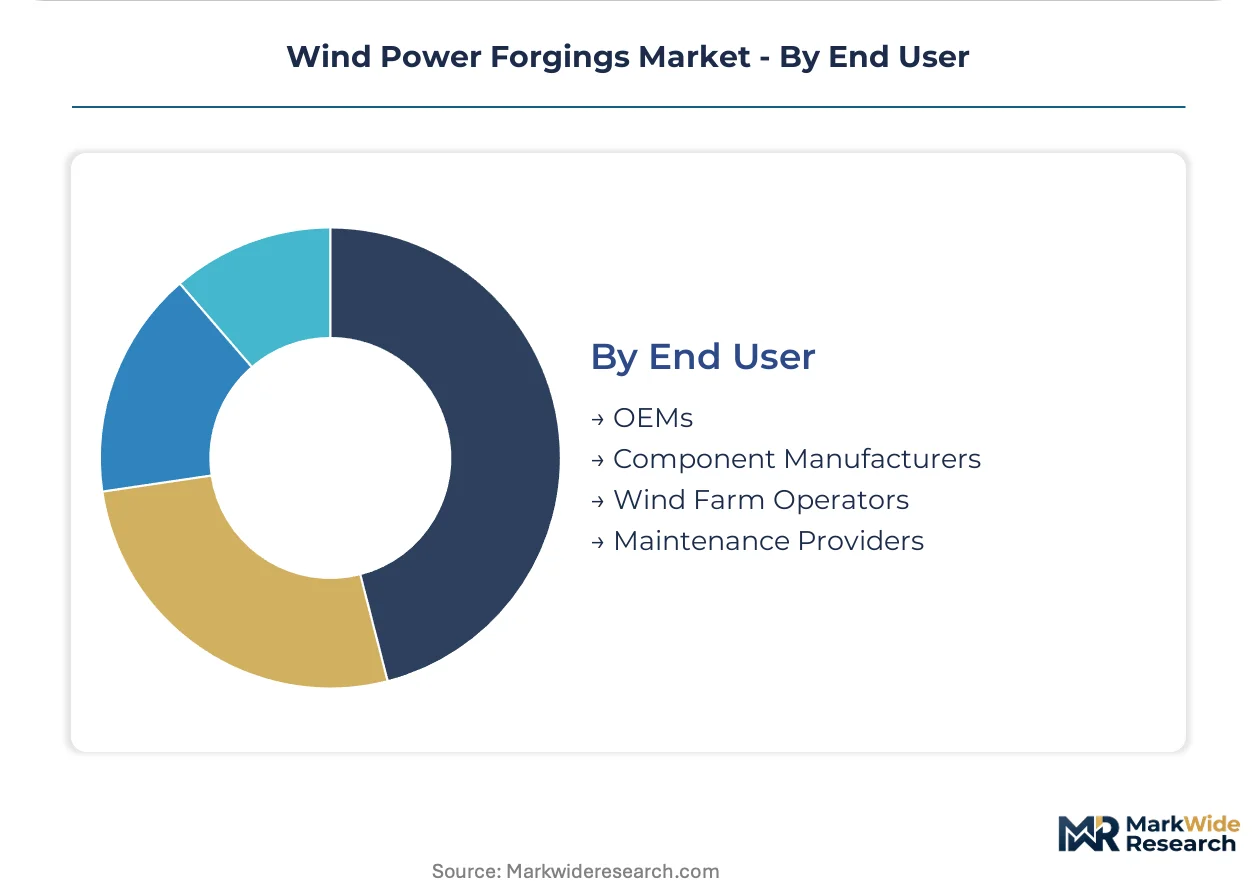
End User:
Procurement authority concentration varies between integrated OEMs and fragmented aftermarket channels with divergent technical specification depth.
- OEMs:Vestas, Siemens Gamesa, Goldwind, and Envision dominate annual forging procurement volume, consolidating supplier bases through multi-year framework agreements that lock capacity 24-36 months ahead of installation.
- Component Manufacturers:Independent gearbox producers and bearing suppliers source forgings for integration into subassemblies sold to multiple OEM platforms, requiring broader material grade certifications.
- Wind Farm Operators:Utility and independent power producer procurement focuses on replacement shafts and flanges for end-of-warranty turbines, with specification adherence to original design documents rather than evolving platform standards.
- Maintenance Providers:Specialized repair contractors source prototype-scale open-die forgings for root-cause failure investigations and non-standard retrofits.
OEM procurement exhibits mature consolidation patterns. Maintenance providers are concentrating newer demand for life-extension engineering and failure analysis applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures roughly two-thirds of global wind power forging tonnage yet consumes nearly as much domestically, tightening export availability for European and Indian developers. Germany and India operate the next-largest forge capacities, while the United States and Japan maintain specialized positions in prototype and precision components.
China
Jiangsu and Guangdong provincial governments have accelerated 10+ MW offshore wind deployment through renewable portfolio standards that absorb domestic forge output. MIIT directives enforce domestic content rules constraining foreign participation in national tenders. Nantong and Yancheng host concentrated heavy forging clusters where electric arc furnace operators supply tower flanges to Goldwind and Envision assembly lines.
Germany
North Sea offshore projects beyond 15 MW capacity compress forge lead times for extra-large rings and shafts that only integrated steel-to-forging suppliers can produce. EU Green Deal embodied carbon thresholds redirect procurement toward shops with verified Scope 3 data and electric arc furnace feedstock. The Ruhr industrial corridor anchors German capacity, with Thyssenkrupp facilities in Bochum and Dortmund supplying Siemens Gamesa nacelle programs.
India
Production-linked incentives for renewable component exports attract forge investments in Maharashtra and Tamil Nadu to serve Middle East and African markets. CEA grid integration mandates accelerate domestic turbine installation, competing for forge capacity with export orders. Pune and Chennai industrial belts concentrate Bharat Forge operations that supply European OEMs seeking alternative sourcing outside China.
United States
Onshore wind repowering cycles and offshore lease auctions in the Atlantic drive demand for prototype-scale open-die forgings and replacement shafts. OSHA and EPA standards govern worker exposure and environmental compliance at forge facilities in Texas and the Great Lakes region. Scot Forge in Illinois specializes in custom production for North American wind corridors, serving maintenance providers and independent power producers directly.
Japan
Domestic offshore wind auctions in Hokkaido and Kyushu require forged components for typhoon-resistant turbine designs with enhanced fatigue specifications. METI feed-in tariff adjustments shape project economics that filter down to forge procurement timing. Nagoya and Osaka industrial zones maintain precision forging capacity for bearing races and gearbox components in direct-drive generator architectures.
Wind Power Forgings Market Competitive Landscape
The competitive structure tilts toward integrated steel-to-forging conglomerates with captive melt shop capacity. Tier-one suppliers absorb secondary forging houses to secure multi-year framework commitments from consolidated OEM procurement desks. Three archetypes dominate: integrated steel producers with in-house forging, independent merchant forgers with open-die specialization, and diversified industrial conglomerates with renewable component divisions. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as 18-24 month qualification cycles lock supplier relationships before final investment decisions.
Among Indian and European fabricators, Bharat Forge, Thyssenkrupp, and Scot Forge occupy distinct positions within this structure. Bharat Forge exemplifies the diversified conglomerate archetype, leveraging geographic positioning to serve multiple regional markets. Thyssenkrupp represents integrated steel-to-forging capability with domestic European anchoring. Scot Forge sits within the independent merchant tier, specializing in custom open-die production for non-standard applications and aftermarket channels.
| Leading Market Players |
|---|
| Bharat Forge |
| Scot Forge |
| Thyssenkrupp |
| China First Heavy Industries |
| Larsen & Toubro |
| Forgital Group |
| Ellwood Group |
| Jiangsu Pacific Precision Forging |
| Bruck |
| Others |
Pricing and Supply Chain Analysis
Scrap steel procurement costs cascade through electric arc furnace operations into three distinct pricing tiers for wind power forgings, with shredded auto scrap volatility compressing margins at merchant forges while integrated steel-to-forging suppliers capture upstream arbitrage through captive melt shop supply.
Pricing Analysis
Component fatigue-life guarantees anchor value-based pricing for main shafts and tower flanges, with OEMs paying premiums for verified ultrasonic testing protocols and DNV-GL certification tiers that reduce field failure liability. Price differentiation rests on heat treatment depth and dimensional tolerance bands, with 12+ meter shafts commanding standard-economy premiums against smaller onshore components. Cost compression in commodity flanges is intensifying because Chinese export availability tightens under MIIT domestic content directives. Aftermarket maintenance providers exhibit highest price sensitivity, while offshore developers under EU Green Deal mandates absorb certification premiums without volume negotiation.
Supply Chain Analysis
Dual-sourcing requirements from Vestas and Siemens Gamesa procurement desks mandate qualified backup suppliers for critical shaft and ring geometries, fragmenting capacity commitments across Thyssenkrupp, Bharat Forge, and China First Heavy Industries. Raw material dependencies draw from electric arc furnace scrap, nickel-chromium-molybdenum alloy additives, and specialized quenching oils. Single-source vulnerability concentrates in 15+ MW offshore shafts where only German and Chinese facilities maintain press tonnage and heat treatment furnace scale. Distribution runs through direct mill-to-nacelle-assembly logistics with ocean freight for tower flanges and precision trucking for machined shafts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU Green Deal embodied carbon thresholds and REACH Annex XVII coating restrictions erect regulatory moats that reward forge shops with verified Scope 3 data and chromate-free surface treatment investments.
For Market Incumbents: Extend qualification timeline leverage by locking 24-36 month framework agreements before competitor capacity comes online, while absorbing secondary forging houses in Maharashtra and Tamil Nadu to secure India PLI scheme positioning against Bharat Forge expansion. Threat of direct-drive generator proliferation demands backward integration into vacuum degassing ladle metallurgy for 20+ MW shaft grades. For New Entrants and Emerging Players: Begin with floating offshore foundation mooring connectors where novel tension leg platform geometries lack tooled incumbent supply, targeting Middle East and African markets through Chennai export corridors. White-space exists in hybrid steel-titanium bearing race prototyping for 20+ MW North Sea projects. Go-to-market angle: partner with maintenance providers for non-standard retrofits bypassing OEM procurement consolidation. For Investors and Strategic Acquirers: Consolidated procurement desk reduction of qualified forge suppliers by 40% since 2022 is the leading indicator that captive capacity scarcity will persist through the analysis window. Long-term viability favors integrated steel-to-forging conglomerates with electric arc furnace feedstock and in-house heat treatment depth. Acquisition target archetype: merchant forges with open-die specialization and ASME Level II inspector training pipelines. Signal to watch: OEM framework agreement announcements preceding final investment decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Electric arc furnace investments in Maharashtra and Tamil Nadu serve Middle East export demand under India PLI scheme incentives. |
| Backward Integration | Captive melt shop supply insulates Thyssenkrupp and Bharat Forge from shredded auto scrap price volatility affecting merchant competitors. |
| Green Certification Program | Verified Scope 3 data unlocks EU Green Deal procurement for Baltic Sea tower flanges with embodied carbon thresholds. |
| Long-term Supply Agreement | Multi-year framework commitments from Vestas and Siemens Gamesa lock capacity 24-36 months ahead of offshore installation. |
| Joint Venture | Technology licensing partnerships transfer direct-drive generator forging tolerances to India-based operations serving European OEMs. |
Research Methodology
Multi-period observation of turbine capacity scaling, forge qualification cycle duration, and scrap steel price volatility anchored the trend analysis, supplemented by interviews with nacelle assembly procurement directors, heavy forge plant managers, offshore project development engineers, and aftermarket maintenance contractors. Secondary validation drew from customs trade data, SEC filings of integrated steel producers, MIIT directive releases, and DNV-GL certification registries. Bottom-up forge capacity utilization estimates triangulated against top-down OEM installation pipelines.
Segment-weighting across product type, material grade, application integration level, and end-user procurement authority shaped the analytical framework. CAGRs were derived from installation pipeline absorption rates and capacity expansion timelines across the projection horizon. Industry-specific forecast inputs included OEM framework agreement announcement tracking and heat treatment furnace commissioning schedules.
Policy reversal in EU carbon border adjustment implementation, scrap steel price spike persistence, and ultrasonic testing technician training pipeline failure are the dominant revision risks to modeled forge output and pricing tier stability. Deviation in EU Green Deal low-carbon steel mandate enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Energy Foundation Market
Wind Energy Systems
Wind Power SCADA Market
Wind Energy Systems
Wind Turbine Forged Tower Flange Market
Wind Energy Systems
Bladeless Wind Turbines Market
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Wind Turbine Brakes Market
Wind Energy Systems
Portugal Wind Energy Market
Wind Energy Systems
Spain Wind Energy Market
Wind Energy Systems
Wind Energy Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Drive Market
Wind Energy Systems
Lubricants for Wind Turbine Market
Wind Energy Systems
Drone Wind Turbine Blade Inspection Market
Wind Energy Systems
Wind Turbine Shaft Market
Wind Energy Systems
Global Small Wind Power Market