
 Wind Turbine Gearbox Repair and Refurbishment Market | 2026-2036
Wind Turbine Gearbox Repair and Refurbishment Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Gearbox Repair and Refurbishment Market Analysis
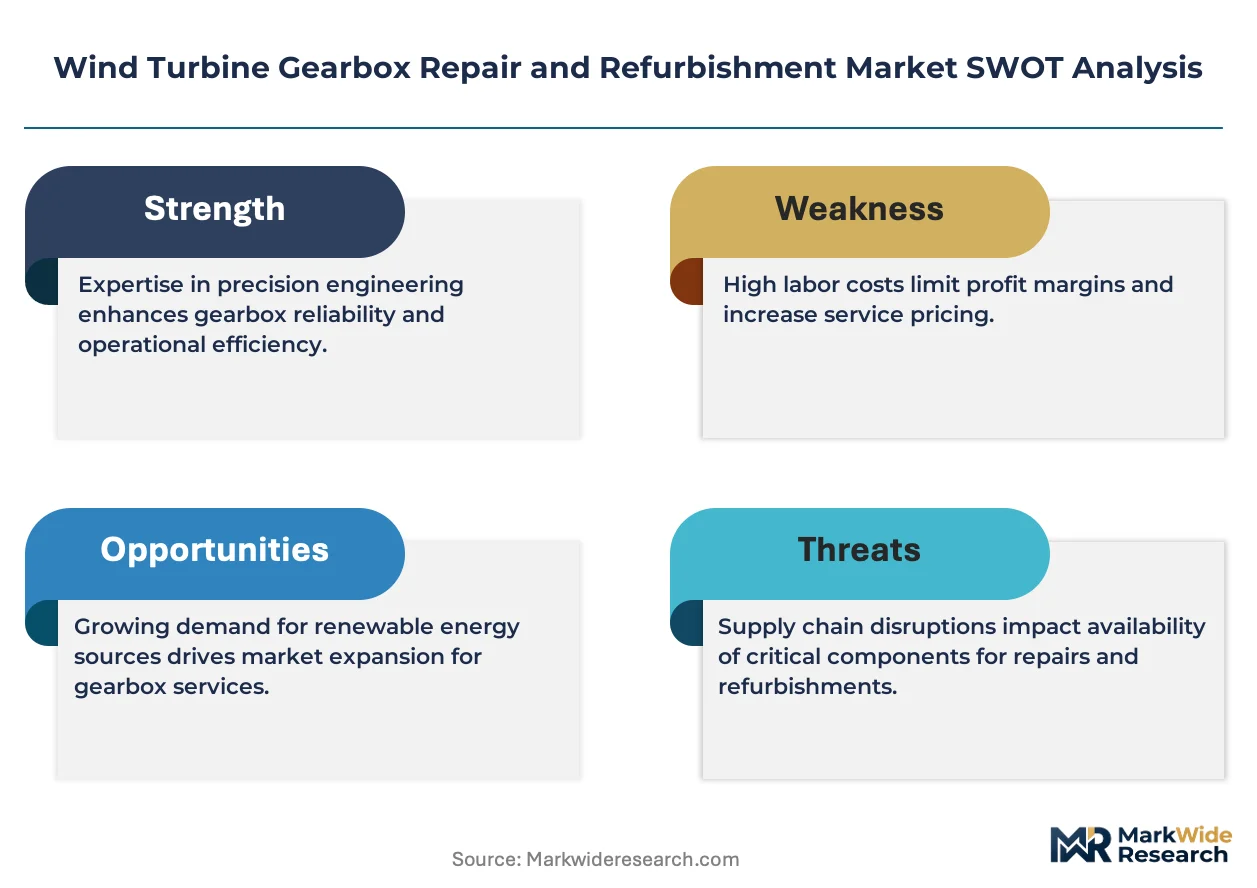
Offshore wind farm operators is redrawing procurement priorities for gearbox services as turbine ratings exceed 10 MW and vessel-access costs reshape maintenance economics. ZF Friedrichshafen AG leverages its planetary gear expertise to anchor long-term service contracts with European offshore developers. Siemens Gamesa Renewable Energy SA sustains integrated lifecycle offerings that combine original equipment knowledge with in-house refurbishment capacity.
Wind turbine gearbox repair and refurbishment encompasses the disassembly, non-destructive testing, re-machining, and reassembly of multi-stage planetary and parallel-shaft gearboxes operating under cyclic torque loads exceeding 5 MNm. The practice extends gearbox service life from 20 to 25-plus years while avoiding capital-intensive full replacements. Service type segmentation shows overhaul work capturing the deepest margin pools due to labor intensity and specialized inspection requirements, whereas condition monitoring technology adoption is accelerating fastest as operators shift from calendar-based to predictive maintenance regimes. Gearbox type segmentation reveals planetary gear configurations dominating offshore applications where torque density requirements are most severe.
German operators face KBA-equivalent certification requirements for drivetrain component integrity, while REACH and the EU F-Gas Regulation govern lubricant disposal and refrigerant handling during gearbox decommissioning. The EPA oversees hazardous waste protocols for US-based refurbishment facilities, creating compliance cost differentials across the Atlantic. Stakeholders must monitor how condition monitoring technology maturation alters the trade-off between preventive overhaul schedules and run-to-failure replacement strategies.
Market Dynamics
The offshore wind sector's pivot to 15 MW-plus turbines is compressing gearbox replacement cycles and elevating precision overhaul requirements. Vessel-access economics now dominate maintenance scheduling, forcing operators to cluster repairs around weather windows and specialized jack-up availability.
Growth Catalysts
- EU F-Gas Regulation:Mandatory refrigerant recovery protocols during gearbox decommissioning are expanding refurbishment volumes as operators avoid full system replacements.
- Condition monitoring platforms:Vibration analysis and oil particle sensors are enabling predictive maintenance regimes that route failing units to overhaul before catastrophic damage.
- German onshore fleet aging:Dense service infrastructure and 20-year-plus installed base create sustained demand for drivetrain refurbishment.
Market Restraints
- Bearing supply concentration:Specialty steel and precision bearing manufacturing clusters in Japan and Germany, exposing service providers to input cost volatility and extended lead times.
- REACH compliance friction:Lubricant disposal and re-refining certification requirements add procedural overhead to refurbishment workflows.
- Direct-drive substitution:Gearless turbine architectures are capturing share in onshore segments above 4 MW, constraining long-term gearbox service addressable market.
Strategic Opportunities
- Floating offshore wind:Mooring-dynamic platforms in Portugal and France will require mobile repair vessels and remote diagnostic capabilities absent from fixed-foundation service models.
- Digital twin integration:Physics-based degradation modeling combined with SCADA telemetry is enabling remaining-useful-life contracting and performance-guaranteed overhaul pricing.
- India's wind repowering mandate:Sub-MW turbine replacement programs are creating secondary market demand for refurbished gearbox redeployment in distributed generation.
Industry Challenges
- Specialized technician scarcity:Planetary gear assembly and magnetic particle inspection require apprenticeship pipelines that European technical institutes have not scaled to match demand.
- KBA-equivalent certification timelines:German drivetrain integrity approvals extend refurbishment turnaround by six to eight weeks, compressing vessel-window utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Gearbox Repair and Refurbishment Market |
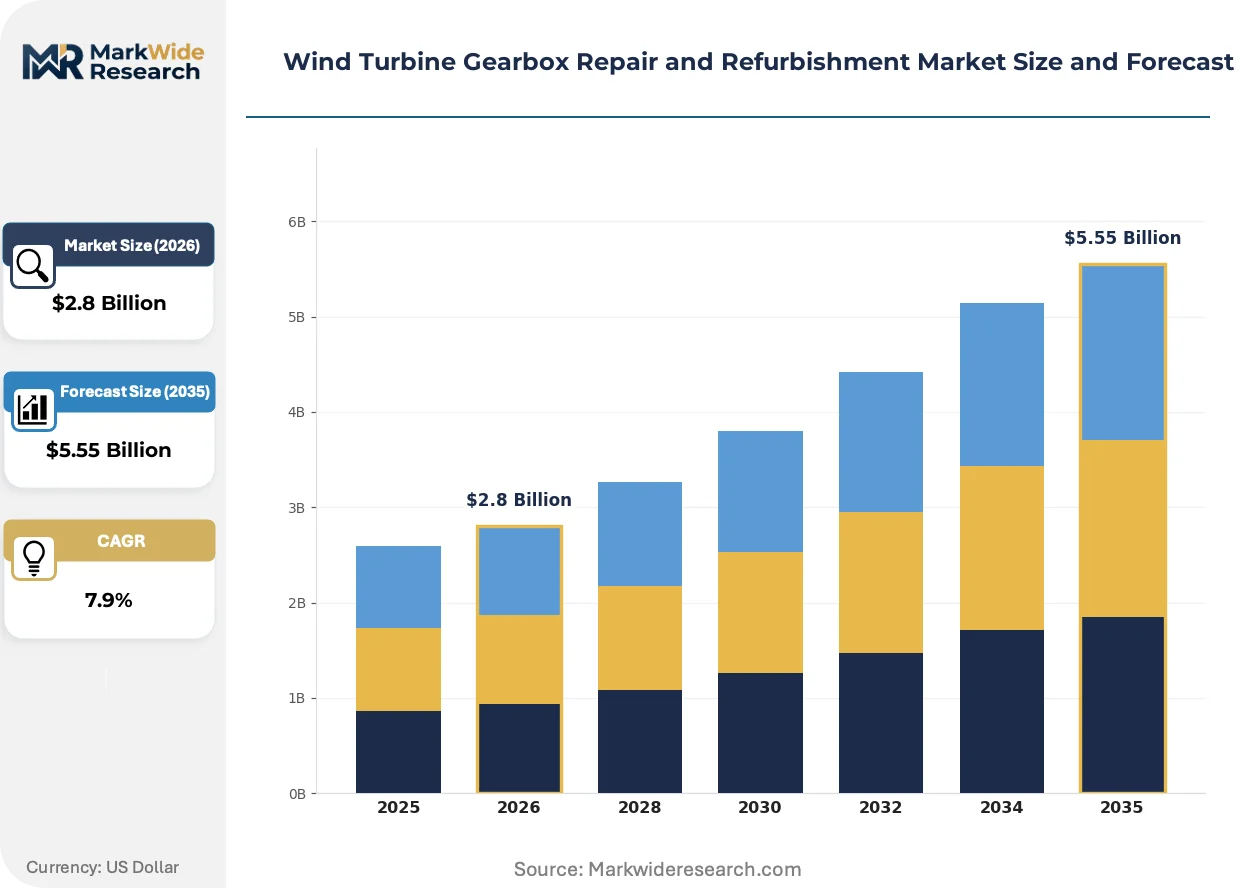
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Repair, Overhaul, Replacement, Maintenance End User: Wind Farm Operators, OEMs, Service Providers, Utilities Gearbox Type: Parallel Shaft, Planetary Gear, Spur Gear, Helical Gear Technology: Condition Monitoring, Predictive Maintenance, Simulation, Diagnostics |
| Companies Covered | Siemens Gamesa Renewable Energy SA, GE Vernova, ZF Friedrichshafen AG, Vestas Wind Systems A/S, Moventas Gears Oy, Winergy AG, Enercon GmbH, Stork Gears & Services BV, SKF Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Gearbox Repair and Refurbishment Market Emerging Trajectories
Additive manufacturing of bearing races and gear teeth is reshaping component sourcing strategies for high-wear refurbishment segments. Digital thread integration from OEM build records to service history is compressing diagnostic lead times.
Directed energy deposition and cold spray metallization is supplanting conventional welding and sleeving for shaft repair in high-torque planetary stages. Offshore operators in the North Sea are adopting these processes to reduce crane-dependent component exchanges. The technology is supplanting traditional remanufacturing by enabling in-situ restoration without full gearbox removal.
REACH and the EU F-Gas Regulation are tightening documentation requirements for lubricant chain-of-custody and refrigerant handling during gearbox decommissioning. Refurbishment facilities face expanded audit scopes for hazardous waste manifests and recovery equipment calibration. German service providers are responding by integrating certified re-refining partnerships and closed-loop oil management systems.
Service contracting is unbundling from OEM captive arrangements as independent repair specialists demonstrate equivalent KBA-equivalent certification quality. Danish and UK offshore operators are segmenting procurement between condition monitoring (retained in-house), major overhauls (competed to qualified independents), and emergency replacements (tied to OEM availability guarantees). This unbundling is most advanced in the North Sea, where vessel-day rates incentivize repair-time minimization over single-source convenience.
Wind Turbine Gearbox Repair and Refurbishment Market Segmentation
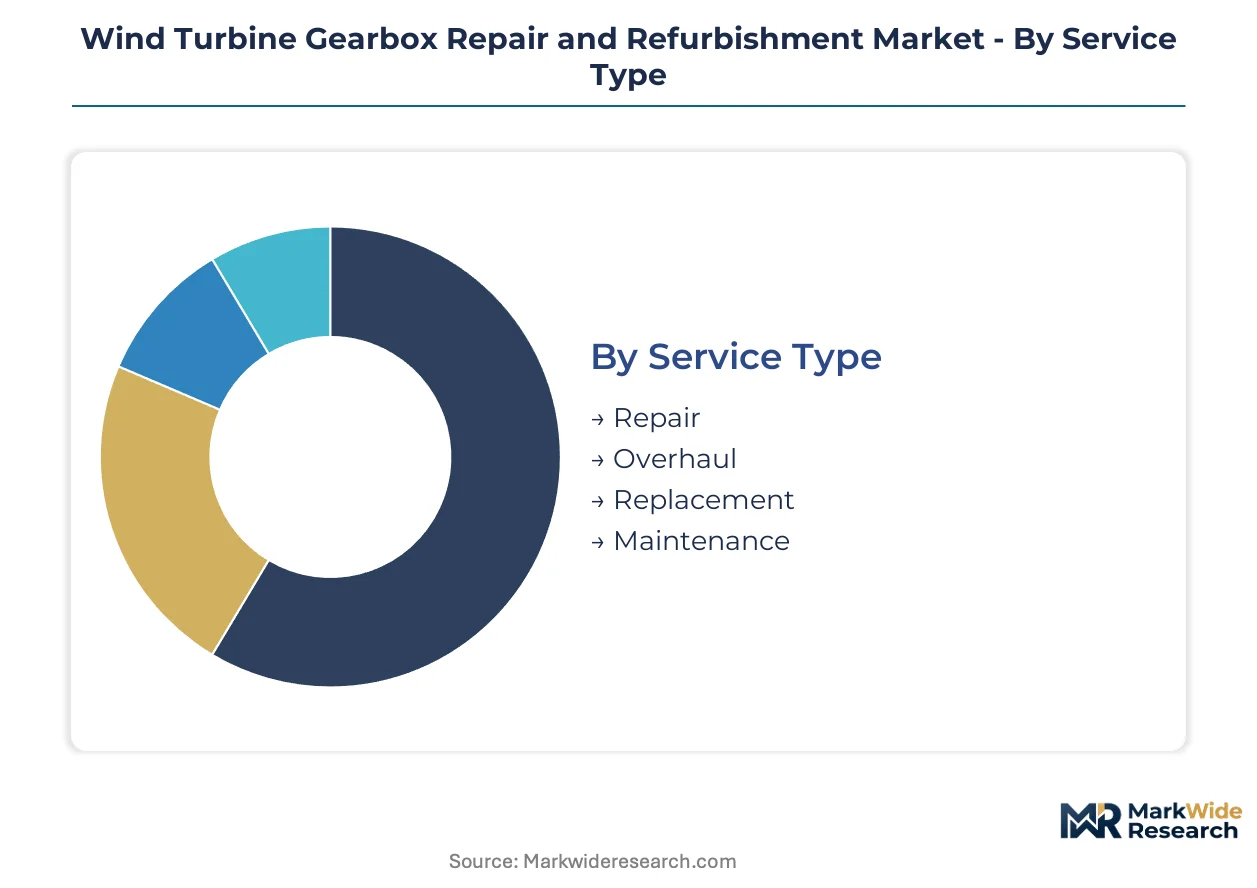
Segmentation in wind turbine gearbox services determines margin capture and capital allocation. Service intensity varies sharply across turbine vintages and offshore exposure, while technology adoption splits procurement budgets between predictive systems and corrective interventions.
Service Type:
Overhaul work faces the strongest displacement risk from direct-drive turbine substitution, whereas repair services benefit from extended fleet lifecycles.
- Overhaul:Complete disassembly, non-destructive testing, and re-machining of multi-stage gearboxes under cyclic torque loads exceeding 5 MNm. German onshore operators commission the deepest overhaul volumes due to dense service infrastructure and KBA-equivalent certification requirements that favor refurbishment over replacement.
- Repair:Targeted component replacement and localized re-machining addressing bearing races, gear teeth, and shaft surfaces. North Sea offshore developers cluster repair campaigns around vessel availability windows, compressing turnaround demands.
- Replacement:Full gearbox exchange programs triggered by catastrophic damage or end-of-life economics.
- Maintenance:Scheduled lubricant changes, seal inspections, and alignment verification preserving baseline performance.
Overhaul retains volume leadership; predictive-enabled repair holds the steepest expansion curve.
End User:
Procurement concentration varies by fleet scale and in-house technical depth, with cost-tier differentiation separating integrated operators from outsourced arrangements.
- Wind Farm Operators:Asset owners managing 100-plus unit fleets increasingly unbundle condition monitoring from major overhaul procurement. Danish and UK offshore operators segment contracts between in-house diagnostics, independent repair specialists, and OEM emergency guarantees.
- Service Providers:Independent repair specialists demonstrating KBA-equivalent certification quality are capturing share from OEM captive arrangements.
- OEMs:Original equipment manufacturers leverage build-record archives and warranty obligations to anchor lifecycle service contracts.
- Utilities:Vertically integrated power generators with diversified generation portfolios treat gearbox services as standardized maintenance procurement.
Wind farm operators command the largest addressable spend; service providers are gaining share fastest through certification equivalence.
Gearbox Type:
Torque density requirements and accessibility constraints create divergent refurbishment economics across configurations.
- Planetary Gear:Multi-stage epicyclic configurations delivering highest torque density for 10 MW-plus offshore turbines. ZF Friedrichshafen AG and Siemens Gamesa anchor service contracts around planetary expertise, with North Sea operators demanding precision overhaul capabilities for these high-load stages.
- Parallel Shaft:Simpler two or three-stage configurations dominating onshore installations below 5 MW. German aging fleets sustain parallel-shaft refurbishment volumes through accessible service infrastructure.
- Helical Gear:Angled tooth engagement configurations balancing load distribution with manufacturing complexity.
- Spur Gear:Straight-cut tooth designs limited to auxiliary drives and lower-torque applications.
Planetary gear commands premium pricing; parallel shaft maintains installed-base scale.
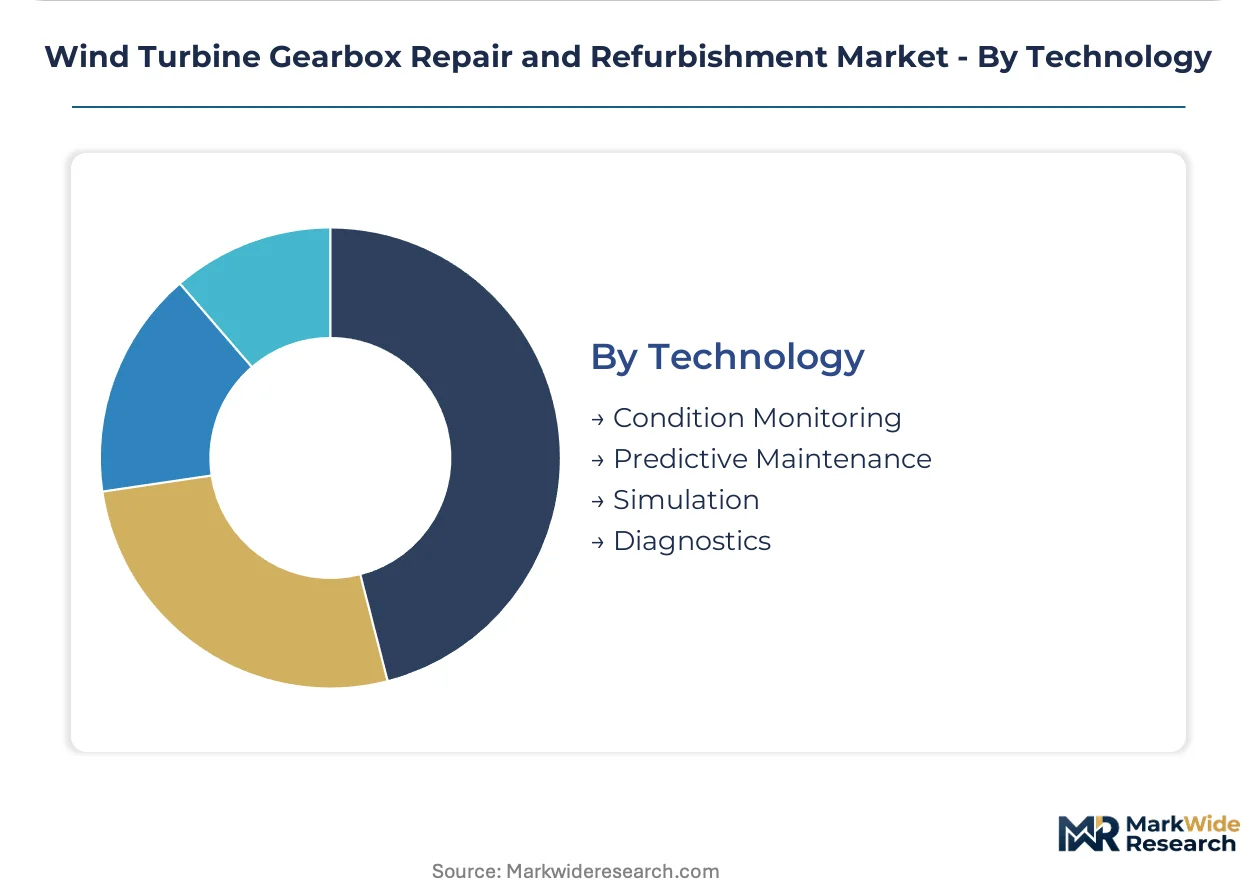
Technology:
Adoption maturity separates predictive platforms from legacy diagnostic approaches, with integration depth determining contract value capture.
- Condition Monitoring:Vibration analysis and oil particle sensors enabling calendar-to-predictive maintenance transitions. Offshore operators deploy these systems to route failing units to overhaul before catastrophic damage eliminates weather-window repair options.
- Predictive Maintenance:Machine-learning degradation models forecasting remaining useful life and optimizing replacement timing.
- Diagnostics:Root-cause analysis protocols identifying failure modes from SCADA telemetry and inspection data.
- Simulation:Physics-based digital twins modeling load cycles and wear progression for overhaul scope definition.
Condition monitoring holds installed-base penetration; predictive maintenance is climbing the fastest as analytics platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German service providers export precision overhaul capacity to North Sea offshore operators, while US Gulf Coast facilities process onshore drivetrain refurbishment for aging Texas and Oklahoma fleets.
Germany
Aging onshore turbine fleets exceeding 20 years of service life sustain dense overhaul volumes across Lower Saxony and Bavaria. The KBA-equivalent certification requirements for drivetrain component integrity extend refurbishment turnaround timelines by six to eight weeks. Hamburg anchors specialized service infrastructure where independent repair specialists compete with OEM captive arrangements.
United Kingdom
North Sea offshore operators cluster gearbox repairs around vessel availability windows and jack-up barge schedules. The Health and Safety Executive oversees offshore maintenance protocols that elevate documentation requirements for component traceability. Aberdeen hosts concentrated service logistics coordinating between Scottish offshore arrays and continental European refurbishment facilities.
United States
Texas and Oklahoma onshore wind corridors generate sustained demand for parallel-shaft gearbox refurbishment as installed capacity ages past original design life. The EPA oversees hazardous waste protocols for lubricant disposal and component decommissioning, creating compliance cost differentials with European counterparts. Houston-area service hubs coordinate inland transport logistics for multi-ton drivetrain components.
Denmark
Danish offshore developers pioneered unbundled procurement models separating condition monitoring from major overhaul contracts. The Danish Energy Agency enforces technical standards for turbine component integrity that favor refurbishment over replacement where economically viable. Copenhagen-based technical institutes face apprenticeship pipeline constraints for planetary gear assembly and magnetic particle inspection specializations.
China
Domestic wind installations exceeding 300 GW cumulative capacity create secondary market demand for gearbox redeployment in distributed generation applications. The National Energy Administration implements repowering mandates for sub-MW turbine replacement programs. Jiangsu and Shandong provinces concentrate manufacturing clusters where precision bearing supply constraints intersect with local refurbishment capacity expansion.
Wind Turbine Gearbox Repair and Refurbishment Market Vendor Landscape
Listed leaders compete with private specialists across certification equivalence and service contracting flexibility. The vendor base separates into OEM-integrated lifecycle providers, independent repair specialists with KBA-equivalent credentials, and component-focused precision manufacturers. Three archetypes dominate: integrated energy conglomerates leveraging original equipment archives, independent service specialists capturing share through turnaround speed, and bearing manufacturers extending into adjacent drivetrain services. Competitive moves concentrate on strategic partnerships for vessel-access coordination and technology licensing for additive repair processes.
Within the integrated provider tier, Siemens Gamesa Renewable Energy SA and GE Vernova exemplify archetypes combining original equipment knowledge with in-house refurbishment capacity. ZF Friedrichshafen AG occupies a position among precision drivetrain specialists leveraging planetary gear expertise for long-term service contracts. These three entities represent distinct competitive vectors: captive lifecycle control, component-scale technical depth, and multi-brand service neutrality.
| Leading Market Players |
|---|
| Siemens Gamesa Renewable Energy SA |
| GE Vernova |
| ZF Friedrichshafen AG |
| Vestas Wind Systems A/S |
| Moventas Gears Oy |
| Winergy AG |
| Enercon GmbH |
| Stork Gears & Services BV |
| SKF Group |
| Others |
Supply Flow & Price Mechanics
KBA-equivalent certification requirements for drivetrain component integrity simultaneously gate supplier qualification and stratify price tiers in the wind turbine gearbox repair market. German operators pay substantial premiums for certified overhaul capacity, while uncertified independents compete on turnaround speed at lower price points.
Pricing Analysis
Next-generation 15 MW-plus offshore turbines command premium overhaul pricing against prior-generation 5-8 MW units and aging sub-5 MW onshore fleets. Three-tier pricing structure across OEM-authorized premium, KBA-certified standard, and non-certified economy levels reflects certification grade and geographic delivery cost differentials. Cost compression in economy-tier parallel-shaft refurbishment is intensifying because Indian and Chinese service providers are expanding capacity. Utility buyers with standardized maintenance procurement exhibit highest price sensitivity; North Sea offshore developers with vessel-window constraints show lowest.
Supply Chain Analysis
Port congestion at Hamburg and Bremerhaven elevates inbound logistics costs for precision bearing shipments originating from Japan and Germany. Specialty steel and bearing manufacturing concentrates in Japan, Germany, and Sweden, while refurbishment capacity clusters in Germany, Denmark, and the United Kingdom. Supply chain risk centers on single-source vulnerability for high-torque planetary stage components. Distribution runs through OEM-authorized service hubs, independent specialist facilities, and mobile repair vessels for offshore applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic particle inspection and planetary gear assembly expertise constitutes the critical bottleneck constraining market expansion, with European technical institutes failing to scale apprenticeship pipelines to match demand from North Sea offshore operators.
For Market Incumbents: Compound certification advantage by deepening KBA-equivalent credentials into floating offshore wind service protocols before independent specialists achieve equivalence. Anchor long-term contracts with vessel-access coordination capabilities that compress turnaround timelines during weather windows. Direct-drive turbine substitution in onshore segments above 4 MW threatens parallel-shaft overhaul volumes; offset through precision planetary expertise for 10 MW-plus offshore units. For New Entrants and Emerging Players: Lead with additive manufacturing capabilities for bearing race and gear tooth restoration, targeting North Sea operators seeking crane-dependent component exchange reduction. India's wind repowering mandate for sub-MW turbine replacement programs offers the most penetrable geography for refurbished gearbox redeployment. Pursue certified re-refining partnerships to satisfy REACH lubricant chain-of-custody requirements as a differentiated entry credential. For Investors and Strategic Acquirers: EU F-Gas Regulation reshapes the acquisition landscape by expanding refurbishment volumes as operators avoid full system replacements to escape mandatory refrigerant recovery protocols. Long-term viability favors service providers with integrated condition monitoring platforms and physics-based digital twin capabilities. Monitor condition monitoring technology maturation as the inflection signal altering preventive overhaul versus run-to-failure replacement economics.| Strategic Initiative | Industry Significance |
|---|---|
| KBA-Equivalent Certification Investment | German drivetrain integrity approvals extend turnaround timelines but lock in premium pricing tiers. |
| Mobile Repair Vessel Deployment | Floating offshore wind in Portugal and France demands remote diagnostic capabilities absent from fixed-foundation models. |
| Additive Manufacturing Integration | Directed energy deposition enables in-situ shaft restoration without full gearbox removal for North Sea operators. |
| Digital Twin Platform Development | Physics-based degradation modeling combined with SCADA telemetry enables remaining-useful-life contracting. |
| Re-Refining Partnership Formation | Closed-loop oil management systems satisfy REACH documentation requirements for lubricant chain-of-custody. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EIA wind capacity data, IEA renewable energy reports, FERC interconnection filings, and OEM technical documentation. Interviews with offshore maintenance directors, independent repair facility operators, gearbox OEM procurement teams, and classification society surveyors anchor demand-side validation. Customs records for precision bearing imports and SEC filings from listed energy conglomerates provide supply-side triangulation. Bottom-up service provider capacity estimates and top-down fleet aging projections cross-validate market sizing.
Segmentation dimensions modeled include service type intensity, gearbox configuration torque density, end-user procurement concentration, and technology adoption maturity across the projection horizon. CAGRs derive from installed base depreciation curves, replacement cycle compression factors, and predictive maintenance penetration trajectories. Forecast inputs incorporate vessel-access cost inflation, direct-drive substitution rates, and floating offshore wind deployment timelines.
The analysis sits within stated boundaries; outcomes outside EU F-Gas Regulation enforcement intensity, REACH compliance friction levels, or technician apprenticeship scaling would require recalibration. Forecasts reflect assumptions on condition monitoring platform maturation, bearing supply concentration persistence, and offshore turbine rating trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Power Generation Equipment MRO Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Global Power Rental Systems Market
Power Equipment
Romania Power EPC Market
Power Equipment
Deaerators Market
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
France Power EPC Market
Power Equipment
Power Recovery Winches Market
Power Equipment
Industrial Gas Turbine Ignition System Market
Power Equipment
Australia Power EPC Market
Power Equipment
Natural Gas Turbine Market
Power Equipment
North America Exhaust Heat Recovery System Market
Power Equipment
Gas Fixed Power Capacitors Sales Market
Power Equipment
Kazakhstan Power EPC Market
Power Equipment
Asia-Pacific Gas Turbine Service Market
Power Equipment
Thailand Power EPC Market