
 Wind Services Market | 2026-2036
Wind Services Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Services Market Analysis
Modular service bundling is realigning how fleet operators procure turbine support. Vestas Wind Systems A/S anchors its offering through long-term output-based agreements that lock in availability commitments. Siemens Gamesa Renewable Energy S.A. competes with integrated digital platforms that unify condition monitoring and spare parts logistics across multi-brand fleets.
Wind services encompass the technical maintenance, installation, and performance optimization of wind energy infrastructure, requiring specialized access equipment, vibration analysis protocols, and blade repair composites to sustain nameplate capacity factors over twenty-plus year design lives. The service type dimension shows maintenance commanding the largest revenue pool while inspection segments gain traction as insurers mandate more frequent structural assessments; the technology dimension reveals condition monitoring systems outpacing legacy control upgrades as operators prioritize predictive failure detection over reactive fault response.
The EU Green Deal and F-Gas Regulation shape refrigerant handling protocols for turbine cooling systems, while national maritime regulators in Germany, Denmark, and the Netherlands impose vessel-emission standards on offshore access logistics. Stakeholders must weigh the capital intensity of specialized offshore service vessels against the margin compression risk from standardized onshore maintenance commoditization.
Market Dynamics
Offshore wind farm operators in the North Sea basin are consolidating service procurement around lifecycle asset management contracts, compressing vendor margins while demanding integrated digital-physical capabilities from maintenance providers.
Growth Catalysts
- EU Green Deal O&M mandates:Tighter operational standards for turbine availability and refrigerant handling are forcing operators to upgrade service contracts, expanding addressable revenue pools for specialized providers.
- Condition monitoring convergence:Vibration analysis protocols fused with predictive analytics are reducing unplanned downtime, creating pull for integrated hardware-software service bundles.
- North Sea clustering:Proximity of offshore arrays in German, Danish, and Dutch waters enables vessel-sharing economies that lower per-turbine service costs and improve technician utilization rates.
Market Restraints
- Specialized vessel scarcity:Purpose-built offshore access craft face construction backlogs at European shipyards, constraining deployment capacity for deep-water maintenance.
- Blade composite input volatility:Carbon fiber and epoxy resin prices fluctuate with energy feedstock costs, compressing repair service margins during commodity spikes.
- F-Gas Regulation compliance friction:Refrigerant recovery and disposal protocols for turbine cooling systems add procedural overhead that slows maintenance turnaround times.
Strategic Opportunities
- Baltic Sea expansion:Polish and Lithuanian offshore lease auctions are creating greenfield demand for installation and commissioning services without incumbent vendor lock-in.
- Multi-brand fleet integration:Operators mixing Vestas, Siemens Gamesa, and GE turbines seek unified monitoring platforms that transcend OEM silos.
- Output-based contracting models:Availability guarantees and energy yield commitments are displacing time-and-materials billing, favoring providers with balance sheet depth to underwrite performance risk.
Industry Challenges
- Certified technician pipeline gaps:GWO safety training and blade repair specializations face enrollment bottlenecks that outstrip offshore workforce expansion needs.
- Legacy SCADA integration complexity:Retrofitting predictive maintenance modules onto decade-old turbine control architectures requires custom protocol translation that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Services Market |
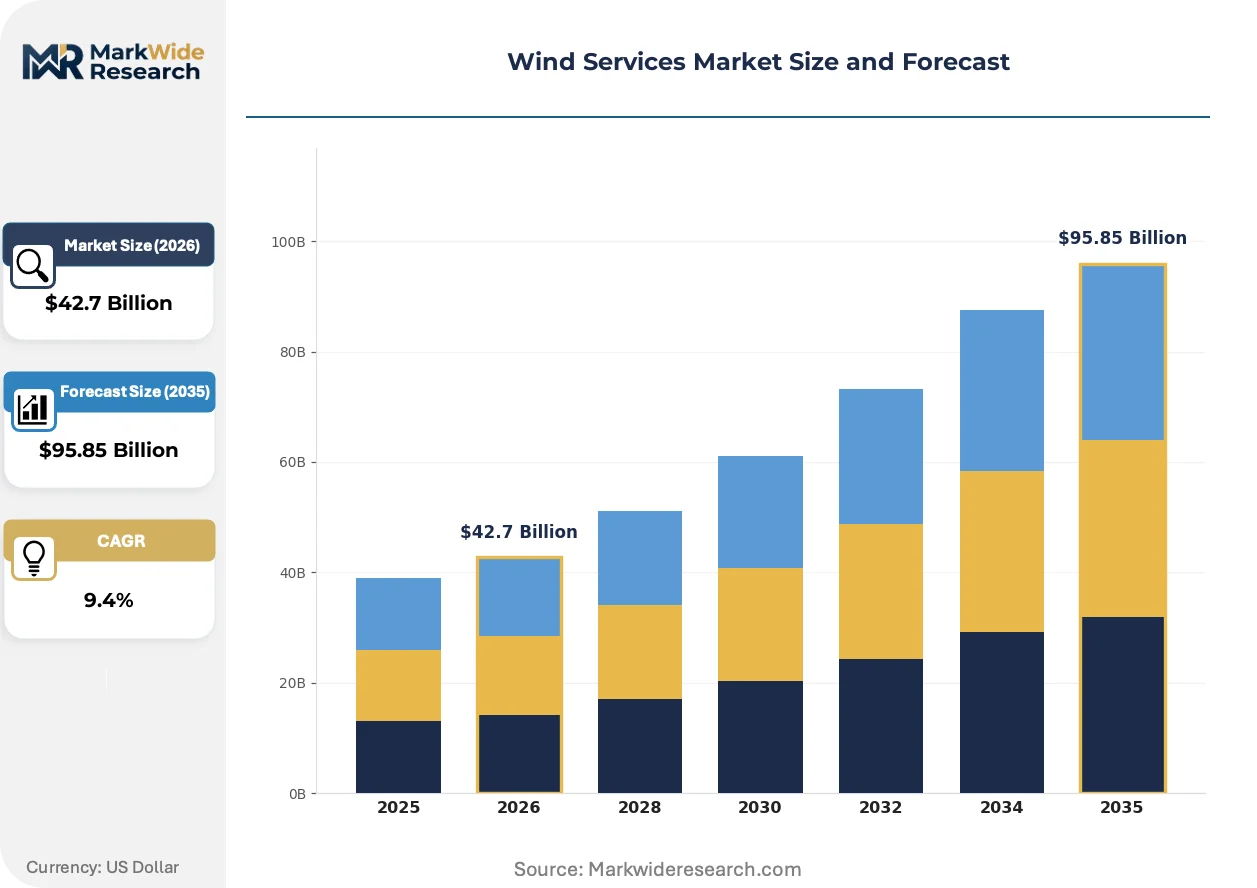
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $95.85 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Installation, Consultation, Inspection Technology: Turbine Design, Control Systems, Energy Management, Condition Monitoring End User: Utilities, Independent Power Producers, Offshore Operations, Onshore Facilities Application: Power Generation, Grid Integration, Energy Storage, Asset Management |
| Companies Covered | Nordex SE, MingYang Smart Energy Group Co., Ltd., Vestas Wind Systems A/S, Suzlon Energy Limited, Envision Energy Technology (Shanghai) Co., Ltd., Siemens Gamesa Renewable Energy S.A., Goldwind Science & Technology Co., Ltd., Invenergy, GE Renewable Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Services Market Emerging Trajectories
Digital twins and autonomous inspection drones are compressing the feedback loop between fault detection and corrective action, reshaping how operators prioritize capital deployment across maintenance versus replacement decisions.
Digital twin technology for drivetrain components is absorbing real-time sensor feeds from gearbox bearings and generator windings to simulate remaining useful life. Offshore operators in the North Sea basin are adopting these platforms fastest, driven by accessibility constraints that magnify the cost of unplanned failures. The technology is absorbing service budget allocations previously directed toward scheduled component replacements, deferring capital expenditure until degradation models justify intervention.
The EU F-Gas Regulation is mandating leak detection systems and refrigerant recovery protocols for turbine cooling circuits. Service providers must now deploy certified technicians with specialized handling equipment, adding cost layers to routine maintenance visits. German maritime regulators are enforcing these standards most stringently, inspecting vessel-based service operations for compliance during port calls.
Long-term service agreements are displacing ad-hoc maintenance procurement as offshore asset owners seek to transfer operational risk to specialized providers. Energy utilities with limited in-house technical depth are driving this consolidation, favoring contractors offering integrated availability warranties. Danish and Dutch offshore clusters exhibit the most advanced contracting sophistication, with ten-to-fifteen year performance commitments now standard for new arrays.
Wind Services Market Segmentation
Service procurement patterns in wind energy diverge sharply between offshore and onshore contexts, between utility-scale fleets and distributed assets, and between predictive digital platforms and legacy reactive maintenance. Understanding these axes clarifies where margin pools concentrate and where commoditization pressures bite hardest.
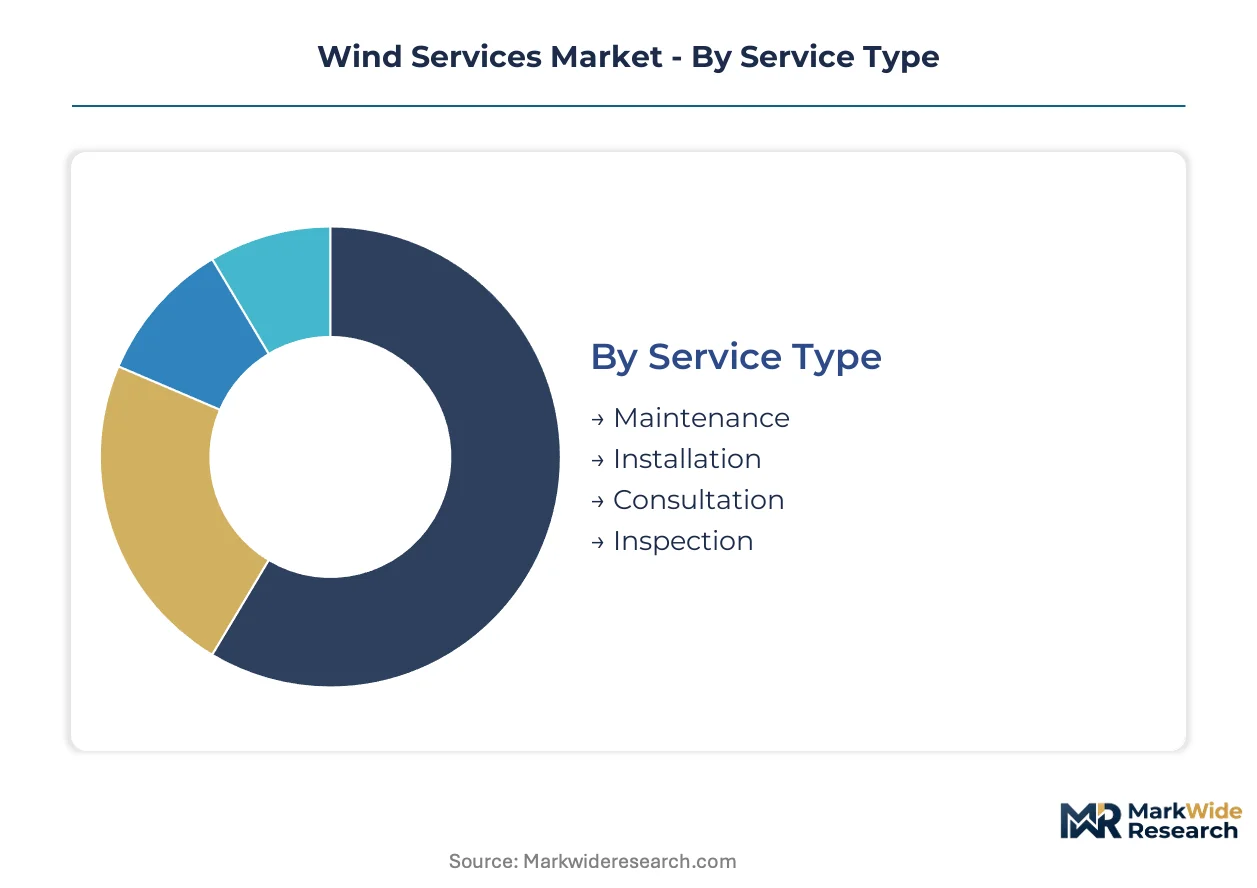
Service Type:
Technical specification intensity varies dramatically across service categories, with some demanding continuous vessel deployment and others executable through periodic technician rotation.
- Maintenance:Scheduled and corrective interventions on drivetrains, blades, and electrical systems sustain nameplate capacity factors across twenty-plus year design lives. German and Danish offshore clusters drive demand for integrated availability contracts that bundle routine servicing with emergency response. EU Green Deal O&M mandates tighten refrigerant handling protocols, adding compliance layers to every site visit.
- Installation:Heavy-lift vessel coordination, foundation bolting, and grid connection commissioning require marine logistics expertise distinct from operational maintenance. Polish and Lithuanian Baltic Sea lease auctions generate greenfield demand without incumbent vendor relationships, opening procurement to new entrants.
- Consultation:Yield optimization studies and lifetime extension assessments support asset refinancing decisions.
- Inspection:Structural blade assessments and tower integrity surveys respond to insurer mandates for more frequent documentation.
Mature deployment sits with Maintenance. Newer deployment is concentrated in Inspection.
Technology:
Capital allocation across technology tiers reflects operator priorities—some favoring hardware reliability, others betting on software-driven prediction.
- Condition Monitoring:Vibration analysis protocols fused with predictive analytics detect bearing degradation and gearbox misalignment before catastrophic failure. North Sea operators adopt these platforms fastest given accessibility constraints that magnify unplanned downtime costs. Real-time sensor feeds from generator windings feed digital twin simulations that defer capital expenditure until degradation models justify intervention.
- Control Systems:Pitch regulation and yaw optimization firmware upgrades extract incremental energy yield from existing rotor swept areas. Retrofitting predictive modules onto decade-old SCADA architectures requires custom protocol translation that extends deployment timelines.
- Turbine Design:Aerodynamic modeling and load case validation support OEM warranty claims and retrofit engineering.
- Energy Management:Grid code compliance and curtailment optimization balance wholesale market participation against mechanical fatigue accumulation.
Control Systems dominate installed base penetration. Condition Monitoring exhibits the steepest expansion trajectory as predictive capabilities displace scheduled component replacement.
End User:
Procurement sophistication correlates with fleet scale and in-house technical depth, fragmenting vendor strategies across customer tiers.
- Utilities:Vertically integrated energy companies with limited renewable technical depth favor long-term performance commitments that transfer operational risk. Danish and Dutch offshore clusters exhibit the most advanced contracting, with ten-to-fifteen year availability warranties now standard.
- Offshore Operations:Purpose-built vessel fleets and helicopter logistics distinguish this segment from onshore service economics. German maritime regulators enforce emission standards on access craft, inspecting compliance during port calls.
- Independent Power Producers:Financial investors without operational heritage seek turnkey service wrap that bundles monitoring, maintenance, and spare parts.
- Onshore Facilities:Distributed wind and repowering projects face margin compression from standardized maintenance commoditization.
Utilities anchor long-term contract volume. Independent Power Producers are expanding fastest as financial ownership of wind assets proliferates.
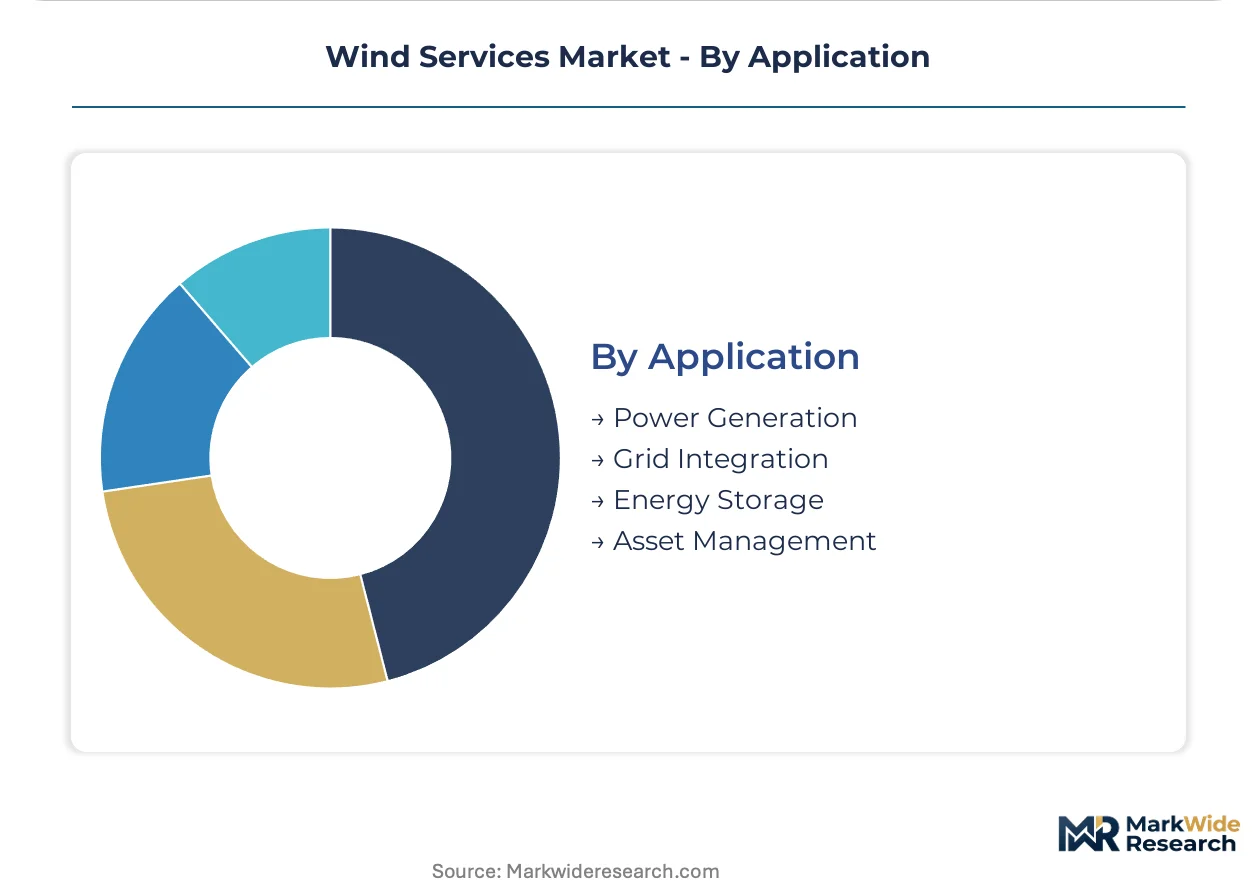
Application:
Value capture potential varies by application based on regulatory treatment and revenue stack complexity.
- Power Generation:Turbine availability directly determines wholesale electricity revenue and renewable certificate eligibility. Output-based contracting with availability guarantees displaces time-and-materials billing, favoring providers with balance sheet depth to underwrite performance risk.
- Asset Management:Lifecycle cost optimization and end-of-life decommissioning planning absorb growing service budget share as early European offshore arrays approach design life limits.
- Grid Integration:Frequency response and voltage regulation services monetize grid stability capabilities beyond pure energy production.
- Energy Storage:Co-located battery integration and hybrid control systems represent emerging service adjacencies.
Power Generation commands mature service spend. Asset Management is gaining share fastest as fleet aging concentrates owner attention on residual value extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service demand concentrates where installed capacity meets harsh operating conditions. Germany consumes specialized offshore maintenance while China builds domestic service capacity to match its manufacturing scale. The United States lags in offshore deployment but sustains onshore repowering cycles.
Germany
North Sea offshore clusters drive integrated availability contracts covering full turbine lifecycles. The EU F-Gas Regulation mandates refrigerant handling protocols that add compliance costs to every service visit. Port infrastructure at Bremerhaven and Cuxhaven anchors vessel logistics for deep-water array maintenance.
China
Domestic OEMs are internalizing service capabilities to match massive onshore installations along the Gobi corridor. National renewable auction mechanisms now require minimum operational performance guarantees. The Jiangsu and Guangdong coastal provinces host emerging offshore clusters demanding specialized access vessel fleets.
United States
Onshore repowering in Texas and the Great Plains sustains blade repair and drivetrain replacement demand. The Inflation Reduction Act production tax credit extensions stabilize long-term service contract economics. Vineyard Wind and South Fork arrays off Massachusetts and Rhode Island are creating first-mover offshore service requirements.
United Kingdom
Dogger Bank and Hornsea developments anchor the world's largest operational offshore fleet. The Contracts for Difference scheme mandates strict availability thresholds that transfer operational risk to service providers. Aberdeen and Grimsby service hubs compete for technician training and vessel berthing capacity.
Denmark
Ørsted's Kriegers Flak and Thor arrays demonstrate ten-to-fifteen year performance contracting sophistication. National maritime regulators enforce vessel emission standards during port inspections at Esbjerg. The Kattegat and Baltic zones create differentiated service requirements from North Sea exposure conditions.
Wind Services Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists for contract margins across the wind services value chain. Market structure tilts toward consolidation as long-term availability agreements demand balance sheet depth few mid-scale providers possess. Three archetypes dominate: OEM-captive service divisions, independent multi-brand maintenance platforms, and vessel-heavy offshore specialists. Competitive moves center on fleet standardization partnerships and predictive analytics licensing rather than asset-heavy expansion.
Among European OEM-captive providers, Vestas Wind Systems A/S and Siemens Gamesa Renewable Energy S.A. occupy positions defined by proprietary turbine knowledge and installed base access. Chinese fabricators including Goldwind Science & Technology Co., Ltd. and MingYang Smart Energy Group Co., Ltd. represent a distinct archetype building domestic service density before geographic expansion. Independent operators such as Nordex SE and Suzlon Energy Limited exemplify the multi-brand platform model seeking unified monitoring contracts across mixed turbine fleets.
| Leading Market Players |
|---|
| Nordex SE |
| MingYang Smart Energy Group Co., Ltd. |
| Vestas Wind Systems A/S |
| Suzlon Energy Limited |
| Envision Energy Technology (Shanghai) Co., Ltd. |
| Siemens Gamesa Renewable Energy S.A. |
| Goldwind Science & Technology Co., Ltd. |
| Invenergy |
| GE Renewable Energy |
| Others |
Supply Flow & Price Mechanics
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating certified refrigerant handling protocols that only specialized technicians with dedicated equipment can execute. German maritime regulators enforce these standards during port inspections, compressing margins for non-compliant operators while allowing certified providers to command availability premiums.
Pricing Analysis
Margin tightening in offshore maintenance reflects vessel-sharing economies that commoditize routine service while predictive analytics bundles sustain pricing power. Three-tier pricing structure across integrated lifecycle contracts, modular service packages, and ad-hoc emergency response separates balance sheet-heavy incumbents from mid-scale independents. Price differentiation hinges on GWO-certified technician depth and digital twin platform maturity. Utilities with limited technical staff exhibit lowest price sensitivity; independent power producers in Baltic greenfield zones drive hardest negotiation.
Supply Chain Analysis
Refurbishment flows for gearbox components and generator windings concentrate reverse logistics around Bremerhaven, Esbjerg, and Grimsby service hubs. Blade repair composites draw from carbon fiber suppliers in Germany, epoxy resin producers in the Netherlands, and specialized tooling fabricators in Denmark. Single-source vulnerability sits with purpose-built offshore access vessels facing European shipyard construction backlogs. Distribution runs through OEM-captive service divisions, independent multi-brand platforms, and vessel-heavy offshore specialists competing for long-term availability contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Condition monitoring systems are displacing legacy SCADA-reactive maintenance, compressing timelines between fault detection and corrective action across the wind services value chain.
For Market Incumbents: Anchor integrated digital-physical capabilities through predictive analytics licensing partnerships that transcend OEM silos. Deepen backward integration into specialized vessel fleets to defend against margin compression from standardized onshore commoditization. Threat: Baltic Sea greenfield auctions attracting new entrants without incumbent relationships. Lever: Balance sheet depth to underwrite ten-to-fifteen year performance commitments. For New Entrants and Emerging Players: Autonomous inspection drones offer technology-first wedge into Polish and Lithuanian offshore lease zones lacking established vendor relationships. Target multi-brand fleet operators seeking unified monitoring platforms across Vestas, Siemens Gamesa, and GE turbine mixes. Go-to-market angle: Output-based contracting with availability guarantees backed by digital twin simulations. For Investors and Strategic Acquirers: Ten-to-fifteen year performance contracting standardization in Danish and Dutch clusters is the leading indicator that long-term service agreement consolidation will accelerate. Viability window favors providers with GWO-certified technician pipelines and vessel emission compliance infrastructure. Acquisition archetype: Independent multi-brand platforms with predictive maintenance software assets. Monitor: F-Gas Regulation enforcement intensity during German port inspections.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Absorbs service budgets previously directed toward scheduled component replacements in North Sea clusters. |
| Specialized Vessel Fleet Expansion | Addresses construction backlogs at European shipyards constraining deep-water maintenance deployment capacity. |
| GWO Certification Program Investment | Closes technician pipeline gaps that outstrip offshore workforce expansion needs in German waters. |
| Multi-Brand Monitoring Partnership | Captures procurement from operators mixing Vestas, Siemens Gamesa, and GE turbines seeking unified platforms. |
| Baltic Sea Geographic Expansion | Exploits Polish and Lithuanian lease auctions without incumbent vendor lock-in or established relationships. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with utility planning officers, IPP project developers, EPC contractors, and vessel fleet operators. WindEurope deployment statistics, German maritime authority inspection records, Danish energy agency auction documentation, and EU F-Gas Regulation compliance filings supplied validation layers. Bottom-up project pipeline analysis and top-down capacity factor modeling enabled triangulation across data streams.
Segmentation granularity modeled service type, technology tier, end-user sophistication, and application revenue stack across the projection horizon. Offshore versus onshore deployment patterns, predictive versus reactive maintenance adoption curves, and utility-scale versus distributed asset procurement behaviors shaped analytical frameworks. CAGRs derived from installed capacity expansion trajectories, O&M cost escalation assumptions, and digital platform penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under vessel construction delays and carbon fiber price volatility. Assumptions reflect EU Green Deal mandate enforcement trajectories and national renewable auction mechanisms. Practitioners should monitor German port inspection intensity and Baltic Sea lease award timing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Rotor Blade Market
Wind Energy Systems
Wind Power Composite Market
Wind Energy Systems
South Korea Wind Energy Market
Wind Energy Systems
Belgium Wind Energy Market
Wind Energy Systems
Wind Turbine Blades Market
Wind Energy Systems
Asia-Pacific Wind Turbine Rotor Blade Market
Wind Energy Systems
Wind Power Market
Wind Energy Systems
United Kingdom Offshore Wind Energy Market
Wind Energy Systems
Wind Turbine Lenses Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Multi-Rotor Wind Turbine Market
Wind Energy Systems
Wind Turbine Scrap Market
Wind Energy Systems
Wind Power Converter Systems Market
Wind Energy Systems
Poland Wind Energy Market
Wind Energy Systems
Wind Turbine Market
Wind Energy Systems
Wind Blades NDT Market