
 Wind Turbine Equipment Market | 2026-2036
Wind Turbine Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Equipment Market Insights
Project finance and power purchase agreement structures is fragmenting the competitive landscape for turbine suppliers. Vestas Wind Systems A/S leverages its blade manufacturing scale to secure long-term supply contracts with independent power producers. Siemens Gamesa Renewable Energy SA anchors its position through specialized offshore turbine platforms designed for harsh marine environments. Goldwind Science & Technology Co., Ltd. competes on integrated drivetrain technology that reduces operational expenditure for Chinese utility buyers.
Wind turbine equipment encompasses the complete mechanical and electrical assembly that converts kinetic wind energy into grid-synchronized electricity, typically featuring rotor diameters exceeding 150 meters for utility-scale units and power ratings from 2 MW to 15 MW depending on application. Horizontal axis turbines dominate installed capacity due to proven aerodynamic efficiency and established supply chains, while offshore turbines represent the fastest-expanding category as developers push into deeper waters with floating foundation systems. Within the component dimension, blades capture the largest share of capital expenditure given their composite material intensity and transportation logistics, whereas control systems command disproportionate margin pools through software-defined performance optimization and predictive maintenance integration.
FERC interconnection standards and the EU Green Deal domestic content thresholds are reshaping where manufacturers must locate blade and nacelle assembly to qualify for subsidized offtake agreements. China's MIIT efficiency mandates and GB standards for grid-code compliance filter market access for imported drivetrain components. Stakeholders must monitor how divergent certification regimes between the EPA's environmental review timelines and ECHA's REACH substance restrictions alter project development cadences and equipment sourcing strategies.
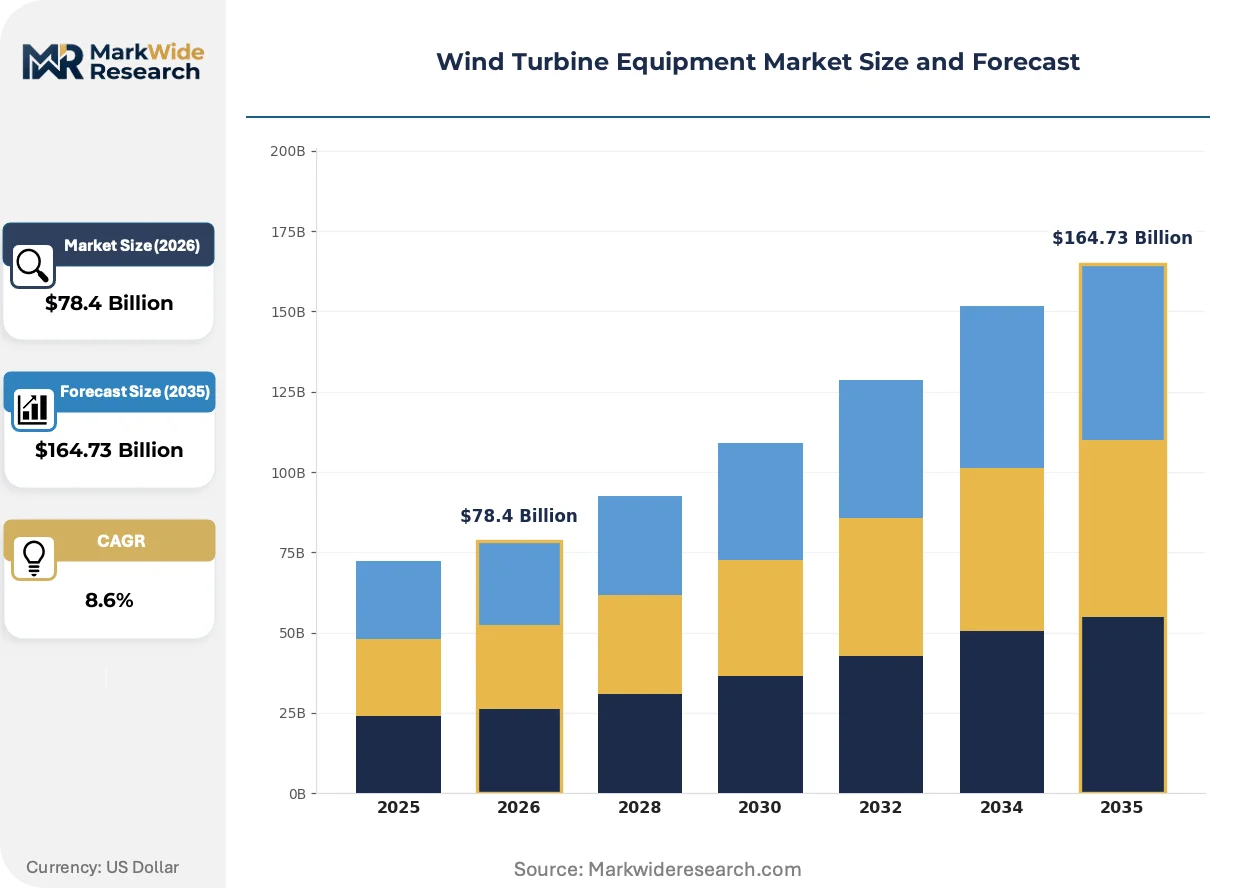
Market Dynamics
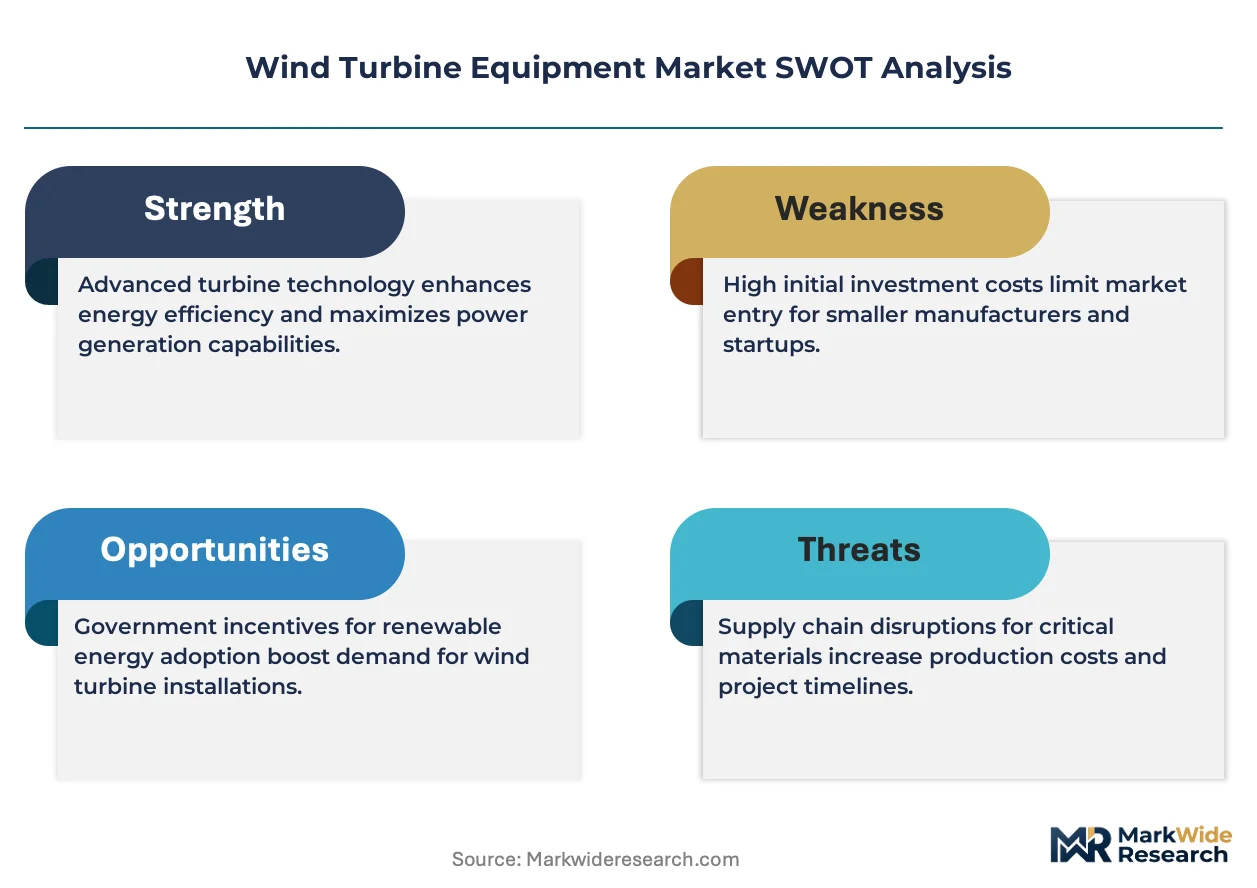
Offshore wind farm developers are scaling procurement of larger turbine units, forcing manufacturers to retool blade factories and nacelle assembly lines for 15 MW-plus platforms that strain existing port infrastructure and vessel fleets.
Growth Catalysts
- EU Green Deal domestic content thresholds:Germany and Denmark have tightened local assembly requirements for subsidized offtake agreements, compelling turbine OEMs to establish blade manufacturing within these jurisdictions.
- Floating foundation systems:Developers in deeper waters are deploying semi-submersible platforms that unlock wind resources beyond fixed-bottom depth limits, expanding addressable seabed acreage.
- Coastal province pipelines:State-backed developers in Jiangsu and Guangdong command multi-gigawatt project queues that concentrate demand for utility-scale drivetrain components.
Market Restraints
- Carbon fiber and balsa wood supply concentration:Blade manufacturers face input cost volatility as aerospace and automotive sectors compete for limited prepreg capacity from specialized composite suppliers.
- FERC interconnection queue backlogs:US grid connection timelines stretching 3-5 years delay revenue recognition for turbine suppliers and strain project finance structures.
- GB standards compliance barriers:China's MIIT efficiency mandates filter market access for imported drivetrain components, fragmenting equipment sourcing strategies across certification regimes.
Strategic Opportunities
- Floating offshore wind in Japan:METI feed-in tariff revisions and port infrastructure investments are creating first-mover openings for turbine OEMs with semi-submersible platform experience.
- Control system software convergence:Integration of predictive maintenance algorithms with SCADA platforms is enabling performance-based service contracts that capture recurring revenue streams.
- Independent power producer procurement:Merchant developers in Texas and the US Midwest are bypassing traditional utility offtake structures, creating direct sales channels for turbine suppliers with balance-sheet financing capacity.
Industry Challenges
- Specialized technician shortages:Blade repair and offshore installation crews require composite manufacturing skills and marine safety certifications that training pipelines have failed to match deployment timelines.
- Type certification timeline compression:IEC 61400-22 certification cycles for new 15 MW platforms now span 18-24 months, delaying commercial operation dates and triggering liquidated damages clauses.
- REACH substance restriction compliance:ECHA's evolving restrictions on epoxy resin hardeners are forcing reformulation of blade laminates mid-production cycle without guaranteed performance equivalence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Equipment Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Horizontal Axis Turbines, Vertical Axis Turbines, Offshore Turbines, Onshore Turbines Component: Blades, Gearbox, Generator, Control Systems Technology: GE Wind Technology, Siemens Gamesa Technology, Vestas Technology, Nordex Technology Application: Utility Scale, Distributed Generation, Remote Areas, Off-grid Systems |
| Companies Covered | Vestas Wind Systems A/S, Siemens Gamesa Renewable Energy SA, Goldwind Science & Technology Co., Ltd., General Electric Company, Nordex SE, Enercon GmbH, MingYang Smart Energy Group Co., Ltd., Envision Energy, Suzlon Energy Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Equipment Market Trends and Innovations
Direct-drive permanent magnet generators are displacing geared drivetrain architectures across the offshore segment, compressing maintenance intervals and altering rare earth supply chain dependencies.
Segmented blade manufacturing using thermoplastic resin infusion is rendering obsolete single-piece fiberglass layup methods that constrained rotor diameter scaling. European OEMs have adopted modular joint designs for 100-meter-plus blades. This shift is compressing transportation logistics costs and enabling on-site assembly at remote port facilities.
EPA environmental review timelines under NEPA are extending project development cadences for US offshore wind leases, forcing developers to front-load survey expenditures before turbine procurement commitments. Developers are responding by pre-ordering vessel slots and fabricating foundations ahead of final investment decisions, locking capital earlier in project cycles.
Merchant offtake structures are displacing traditional power purchase agreements in deregulated US markets, concentrating buyer risk onto developers and their equipment suppliers. Independent power producers in ERCOT and PJM territories now seek turbines with merchant-capable availability guarantees rather than traditional energy-based warranties. This behavioral shift is most visible in Texas, where merchant projects dominate the interconnection queue.
Wind Turbine Equipment Market Segmentation
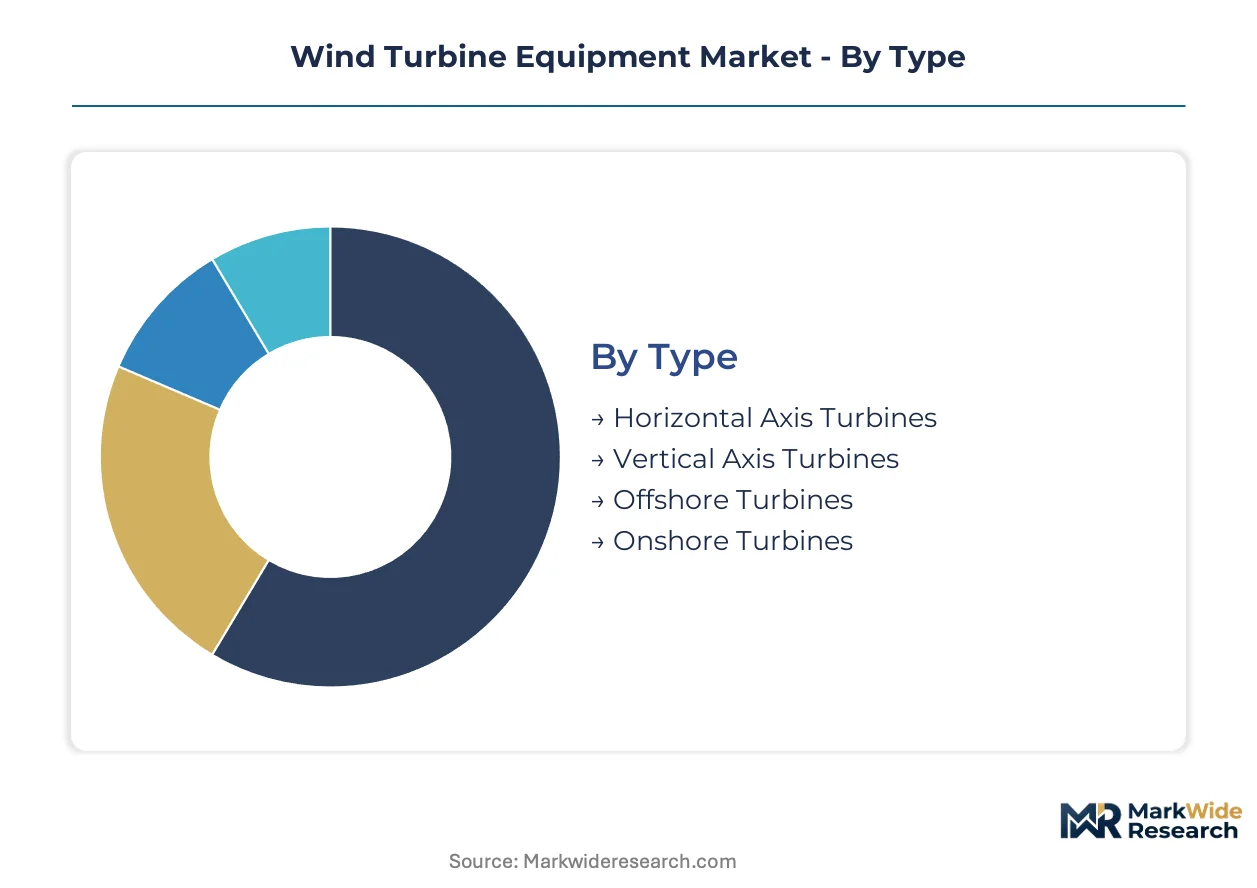
Wind turbine equipment segmentation reveals how technology maturity, component economics, and deployment context reshape procurement patterns across utility and distributed applications. Equipment buyers prioritize different specifications based on grid connection scale, maintenance access, and foundation requirements.
Type:
Mature horizontal axis designs dominate installed base economics while emerging vertical axis configurations address niche distributed applications.
- Horizontal Axis Turbines:Upwind rotor orientation with three-blade configurations delivers proven aerodynamic efficiency above 45% capacity factor for utility-scale arrays. Demand concentrates in the US Great Plains and Chinese Inner Mongolia where state grid corporations procure multi-hundred-megawatt clusters.
- Offshore Turbines:Fixed-bottom and floating platforms rated 12-15 MW feature corrosion-resistant nacelle sealing and helicopter-accessible service decks. Procurement is scaling fastest in German North Sea lease areas and Guangdong coastal waters where seabed depth exceeds 50 meters.
- Vertical Axis Turbines:Darrieus and H-rotor designs eliminate yaw mechanism complexity for urban rooftop installations.
- Onshore Turbines:Land-based units span 2-6 MW ratings with modular tower sections for road-transport logistics.
Horizontal axis turbines retain volume leadership; offshore turbines hold the steepest expansion curve.
Component:
Cost tier differentiation separates high-margin control electronics from capital-intensive structural elements with volatile input material exposure.
- Blades:Glass fiber and carbon fiber composite structures exceeding 100 meters in length capture the largest share of turbine bill-of-materials. Procurement is tightening around balsa wood core suppliers in Ecuador and prepreg resin formulators serving Vestas and Siemens Gamesa blade factories.
- Control Systems:Pitch regulation, power conversion, and SCADA integration modules command disproportionate margin pools through software-defined performance optimization. Demand is concentrating with independent power producers in ERCOT and PJM territories seeking merchant-capable availability guarantees.
- Gearbox:Planetary and helical stages translate rotor torque to generator synchronous speed with 25-year design life.
- Generator:Doubly-fed induction and permanent magnet synchronous architectures define electrical output characteristics.
Blades retain volume leadership; control systems hold the steepest expansion curve.
Technology:
Customer type segmentation separates integrated OEM platforms from licensed technology transfers for regional manufacturing joint ventures.
- GE Wind Technology:Cypress platform with two-piece blade design and digital twin predictive analytics targets North American utility procurement. Licensing agreements with Indian manufacturers address domestic content requirements under CEA renewable purchase obligations.
- Siemens Gamesa Technology:SG 14-236 DD direct-drive platform with 236-meter rotor diameter leads offshore ratings. Demand is scaling with Ørsted and Equinor project pipelines in Danish and UK lease waters.
- Vestas Technology:EnVentus modular architecture spans 2 MW to 6 MW with shared component families.
- Nordex Technology:Delta4000 series emphasizes cold climate adaptations and grid-forming inverter capabilities.
GE Wind Technology retains volume leadership in North America; Siemens Gamesa Technology holds the steepest expansion curve in offshore applications.
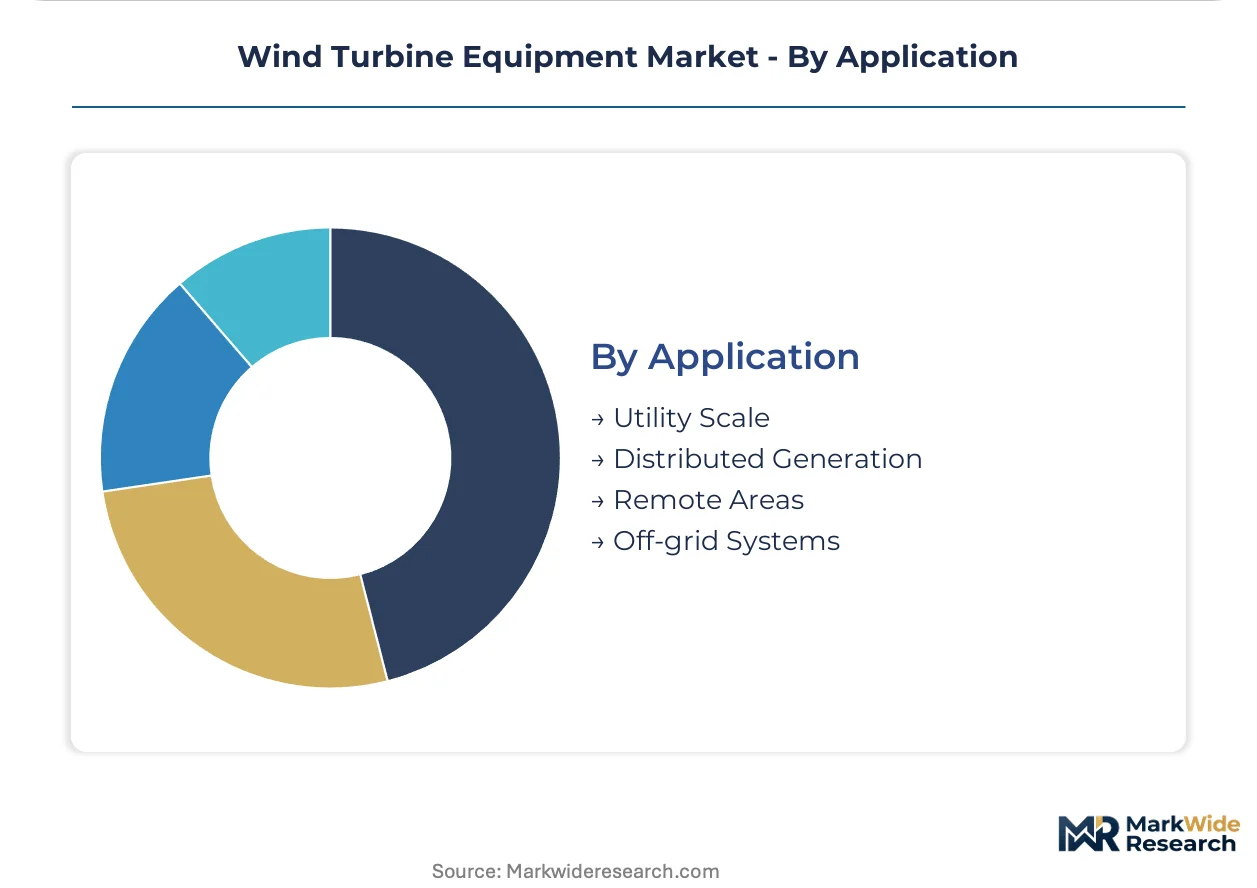
Application:
Geography and grid infrastructure availability determine whether centralized utility arrays or decentralized distributed generation delivers lower levelized cost of energy.
- Utility Scale:Grid-connected wind farms exceeding 100 MW capacity utilize high-voltage substations and dedicated transmission corridors. Deployment concentrates in Texas ERCOT zone and Chinese Gansu province where state-backed developers command land access and interconnection priority.
- Distributed Generation:Behind-the-meter and community-scale installations under 5 MW serve commercial and industrial offtakers. Growth is accelerating in Minnesota and Iowa agricultural regions where rural electric cooperatives aggregate farmer-owned turbine investments.
- Remote Areas:Diesel displacement and mining camp power applications in Alaska and Canadian territories.
- Off-grid Systems:Battery-hybrid configurations for island and frontier electrification.
Utility scale retains volume leadership; distributed generation holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in wind turbine equipment tilt toward net-importing jurisdictions with aggressive capacity targets, while manufacturing-heavy economies balance domestic installation with component exports. Exchange rate volatility and shipping cost swings amplify regional cost differentials for blade and nacelle procurement.
United States
ERCOT interconnection queues in Texas concentrate utility-scale procurement, with merchant developers bypassing traditional utility offtake structures. FERC Order 2023 reforms aim to accelerate grid connection timelines stretching 3-5 years. Blade manufacturing clusters in Colorado and Iowa supply interior wind corridors while East Coast ports retrofit for offshore component staging.
China
State-backed developers in Jiangsu and Guangdong provinces command multi-gigawatt offshore pipelines that absorb 15 MW-plus turbine output. MIIT efficiency mandates and GB standards for grid-code compliance filter market access for imported drivetrain components. Yangtze River Delta manufacturing bases export nacelle assemblies to Southeast Asian markets.
Germany
North Sea lease areas drive demand for floating foundation-compatible turbines as developers push beyond 50-meter seabed depths. EU Green Deal domestic content thresholds compel blade manufacturing localization for subsidized offtake agreements. Port infrastructure in Bremerhaven and Cuxhaven strains under 100-meter blade handling requirements.
Denmark
Ørsted and Copenhagen Infrastructure Partners project pipelines anchor North Sea deployment schedules. National offshore wind targets tighten local assembly requirements alongside EU procurement rules. Esbjerg port expansion targets floating platform integration capacity for deeper-water developments.
Japan
METI feed-in tariff revisions and port infrastructure investments create first-mover openings for floating offshore wind. Domestic shipyards in Nagasaki and Yokohama retool for semi-submersible platform fabrication. Grid interconnection constraints in Tohoku and Hokkaido delay project commissioning despite resource quality.
Wind Turbine Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in blade materials, power electronics, and control systems. The supplier base consolidates around full-turbine OEMs with multi-gigawatt manufacturing footprints, while niche players occupy sub-assembly layers with specialized certification requirements. Three archetypes dominate: integrated platform vendors with global service networks, regional license-holders leveraging technology transfers for domestic content compliance, and component pure-plays in composite manufacturing and generator winding. Competitive moves center on port-adjacent factory placement for offshore logistics efficiency and predictive maintenance software integration to capture recurring service revenue.
Among integrated platform vendors, Vestas Wind Systems A/S and Siemens Gamesa Renewable Energy SA occupy positions spanning onshore and offshore technology generations, while Goldwind Science & Technology Co., Ltd. exemplifies the Asia-Pacific regional champion archetype with integrated drivetrain capabilities. These three represent contrasting geographic anchors and technology licensing strategies that shape procurement options for utility buyers across certification regimes.
| Leading Market Players |
|---|
| Vestas Wind Systems A/S |
| Siemens Gamesa Renewable Energy SA |
| Goldwind Science & Technology Co., Ltd. |
| General Electric Company |
| Nordex SE |
| Enercon GmbH |
| MingYang Smart Energy Group Co., Ltd. |
| Envision Energy |
| Suzlon Energy Ltd |
| Others |
Pricing and Supply Chain Analysis
Carbon fiber and balsa wood supply concentration determines both pricing tier spreads and supply chain shape in wind turbine equipment. Input cost volatility from Ecuadorian balsa harvests and aerospace-competing prepreg capacity compresses margins for blade manufacturers while forcing geographic sourcing diversification.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels based on certification grade and volume scale. Premium tiers command spreads for IEC 61400-certified offshore platforms with 15 MW-plus ratings, while economy tiers serve Chinese domestic markets under GB standards compliance. Cost compression in standard-tier onshore turbines is intensifying because merchant developers in ERCOT and PJM territories negotiate availability-guarantee contracts rather than traditional energy-based warranties. Independent power producers exhibit highest price sensitivity; integrated utilities with captive offtake structures show lowest.
Supply Chain Analysis
Export-control regimes limiting rare earth magnet flows from China reshape procurement strategies for direct-drive permanent magnet generators. Manufacturing concentrates in China, Germany, and Denmark for nacelle assembly; blade fabrication clusters in Spain, the United States, and Brazil for balsa core proximity. Supply chains draw from carbon fiber prepreg formulators, rare earth processors, and cast iron foundries. Single-source vulnerability runs through neodymium-dysprosium supply corridors. Distribution runs through port-adjacent staging facilities serving offshore installation vessel fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among state-backed developers in China and merchant independent power producers in the United States, fragmenting procurement leverage across fewer large-scale counterparties.
For Market Incumbents: Insulate blade manufacturing margins through captive balsa wood supply agreements with Ecuadorian plantation operators and backward integration into carbon fiber prepreg formulation. Capacity addition in Bremerhaven and Cuxhaven addresses EU Green Deal domestic content thresholds. Certification investment in IEC 61400-22 type approval acceleration compresses commercial operation timelines against emerging Chinese OEM competition.
For New Entrants and Emerging Players: Establish a beachhead in floating offshore wind control systems where predictive maintenance software convergence creates recurring revenue openings. Japan's METI feed-in tariff revisions and semi-submersible platform demand represent the most penetrable geography. Licensing direct-drive generator technology from established European OEMs provides fastest go-to-market credibility.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors component pure-plays over integrated platform vendors. Long-term viability centers on software-defined control systems and blade material science capabilities rather than assembly-scale manufacturing. Acquisition target archetype: predictive maintenance algorithm developers with SCADA integration depth. Watch FERC interconnection queue reform implementation as inflection indicator for US demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Port-Adjacent Manufacturing Footprint | Reduces blade transportation logistics costs for 100-meter-plus rotors destined for offshore projects. |
| Predictive Maintenance Platform Integration | Captures recurring service revenue through SCADA-embedded algorithms that optimize turbine availability. |
| Domestic Content Compliance Investment | Qualifies turbine suppliers for subsidized offtake agreements under EU Green Deal threshold requirements. |
| Floating Foundation Technology Licensing | Unlocks deeper-water seabed acreage beyond fixed-bottom depth limits in Japanese and European lease areas. |
| Rare Earth Supply Agreement Diversification | Mitigates magnet cost volatility for direct-drive generators amid export-control regime uncertainties. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, independent power producer project developers, EPC contractors, and blade manufacturing plant managers and refined through secondary validation. Primary fieldwork encompassed turbine OEM procurement teams, offshore installation vessel operators, and grid interconnection specialists. Secondary sources included EIA generation data, IEA renewable energy reports, FERC interconnection queue filings, and project development databases tracking capacity pipelines. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Demand-supply balance modeling anchored forecast construction throughout the projection horizon. Segmentation dimensions spanned turbine type, component category, technology platform, and application scale alongside regional regulatory framework clusters. CAGRs derived from installed capacity growth rates, capacity factor improvements, and unit cost decline curves. Industry-specific inputs incorporated vessel fleet availability constraints, port infrastructure investment schedules, and certification timeline compression effects.
Stress conditions across rare earth price volatility, carbon fiber supply disruption, and interconnection queue duration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology transition pacing and regulatory enforcement intensity. Material shifts in EU Green Deal domestic content threshold calibration or FERC Order 2023 implementation scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Power Cables Market
Power Equipment
Egypt Power EPC Market
Power Equipment
Nigeria Power EPC Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Turbine Governor Market
Power Equipment
Digital Power Conversion Market
Power Equipment
South America Nuclear Power Plant Equipment Market
Power Equipment
Clean Steam Separator Market
Power Equipment
Power Equipment Testing Market
Power Equipment
Global Power Supply Market
Power Equipment
Air Preheater Market
Power Equipment
North America Power Plant Boiler Market
Power Equipment
Chad Power EPC Market
Power Equipment
Power Plant Maintenance Market
Power Equipment
Power Generation Equipment MRO Market
Power Equipment
Natural Gas Turbine Market