
 Wind Turbine Operation and Maintenance Market | 2026-2036
Wind Turbine Operation and Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Operation and Maintenance Market Analysis
Predictive maintenance software is pivoting from optional add-on to core contract deliverable, embedding vibration analytics and blade-damage algorithms into long-term service agreements. Siemens Gamesa Renewable Energy anchors its offshore portfolio with digital monitoring packages bundled across twenty-year contracts. Vestas competes through its in-house logistics network, controlling spare-part availability across multiple continents. GE Vernova specializes in gearbox refurbishment programs that extend turbine life beyond original design specifications.
Wind turbine operation and maintenance encompasses scheduled inspections, unplanned repairs, component swaps, and condition-based interventions on horizontal-axis generators typically rated from two to fifteen megawatts. Blade erosion repair, pitch-system calibration, and generator rewinding preserve capacity factors above thirty-five percent across twenty-five-year asset lifespans. Predictive maintenance contracts capture the fastest-expanding margin pool as sensor density per nacelle triples and machine-learning diagnostics reduce unscheduled downtime. Offshore wind commands premium pricing structures due to vessel-access constraints and corrosive salt-air environments that accelerate drivetrain degradation. Routine maintenance retains the largest revenue base but faces margin compression as standardized service protocols commoditize basic inspection work.
The EU Green Deal mandates turbine recyclability disclosures and carbon-footprint reporting that reshape supplier qualification criteria across European markets. Germany's KBA enforces offshore safety certifications for technician transfer vessels, while REACH compliance governs lubricant and coating chemistries used in blade manufacturing and field repair. China's MEE imposes emissions benchmarks on steel-forging operations that feed gearbox and tower production. Stakeholders must weigh performance-based contract structures against fixed-price exposure as turbine scale, remote-site complexity, and regulatory stringency intensify in parallel.
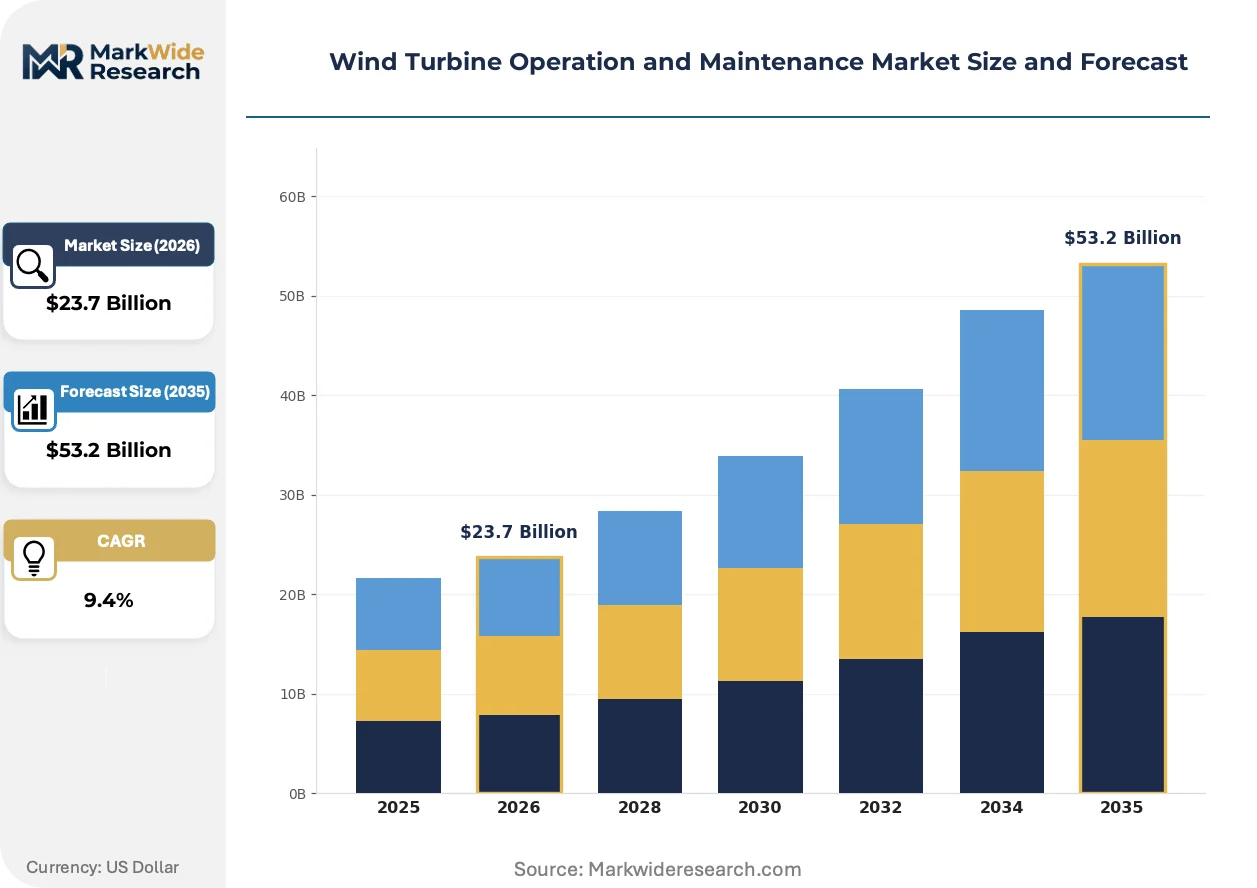
Market Dynamics
Predictive maintenance software is compressing contract structures from time-based to condition-based models, embedding vibration analytics and blade-damage algorithms into long-term service agreements across aging offshore fleets.
Growth Catalysts
- EU Green Deal mandates:Turbine recyclability disclosures and carbon-footprint reporting reshape supplier qualification criteria across European procurement frameworks, accelerating digital traceability adoption.
- Floating wind proliferation:North Sea basin installations multiply vessel-access constraints that favor integrated service providers with dedicated offshore logistics capabilities.
- Machine-learning diagnostics:Sensor density per nacelle triples, reducing unscheduled downtime and converting predictive maintenance from optional add-on to core contract deliverable.
Market Restraints
- Specialized vessel scarcity:Germany's KBA enforces offshore safety certifications for technician transfer vessels, constraining fleet availability and inflating day-rate structures.
- Corrosive salt-air degradation:Offshore drivetrain components require accelerated replacement cycles, compressing margin pools on routine maintenance contracts.
- Steel-forging emissions benchmarks:China's MEE imposes carbon intensity limits on gearbox and tower production inputs, reshaping upstream supply economics.
Strategic Opportunities
- Floating wind in deeper waters:Scotland and Portugal expand lease areas beyond fixed-foundation limits, creating demand for motion-compensated access systems and dynamic cable expertise.
- Performance-based contract structures:Availability guarantees and energy-output warranties displace fixed-price exposure, aligning service provider incentives with asset owner returns.
- Blade-leading-edge erosion repair:Advanced coating chemistries compliant with REACH regulations extend blade life cycles, opening specialized refurbishment service lines.
Industry Challenges
- Certified technician shortages:GWO safety credentials and offshore medical clearances create bottlenecks for vessel-based maintenance crews across the North Sea.
- Legacy SCADA integration:Proprietary data protocols from multiple OEM generations obstruct unified fleet analytics platforms.
- Spare-part inventory positioning:Multi-megawatt component lead times force capital-intensive stocking strategies at regional port hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Operation and Maintenance Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $53.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Routine Maintenance, Corrective Maintenance, Predictive Maintenance, Component Replacement End User: Utilities, Independent Power Producers, Green Energy Companies, Government Entities Technology: Onshore Wind, Offshore Wind, Hybrid Systems, Floating Wind Systems Contract Type: Fixed Price, Cost Plus, Time and Material, Performance-Based |
| Companies Covered | Vestas, Siemens Gamesa Renewable Energy, GE Vernova, Nordex SE, Goldwind, Suzlon Energy Limited, ENERCON GmbH, Dongfang Electric Corporation, Ming Yang Smart Energy Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Operation and Maintenance Market Emerging Trajectories
Digital twin technology and autonomous inspection systems are restructuring how operators monitor turbine health, shifting intervention timing from calendar schedules to real-time condition triggers.
Drone-based blade inspection combined with photogrammetry damage mapping is automating defect detection across offshore arrays. Danish and German operators deploy these systems quarterly, reducing rope-access technician deployments by half. The technology is automating crack-propagation tracking that previously required manual ultrasonic testing.
REACH compliance revisions now govern lubricant chemistries and coating formulations used in blade manufacturing and field repair. Industrial consequence includes reformulation costs passed through supply chains and qualification delays for new repair materials. Offshore segments in the North Sea face the tightest substitution timelines as legacy stocks deplete.
Service contract unbundling separates routine inspections from major component replacement, allowing asset owners to arbitrage specialist providers. Independent service companies capture gearbox refurbishment and generator rewinding work that OEMs previously bundled. This fragmentation concentrates in Germany and the United Kingdom where turbine fleets exceed ten-year operational age.
Wind Turbine Operation and Maintenance Market Segmentation
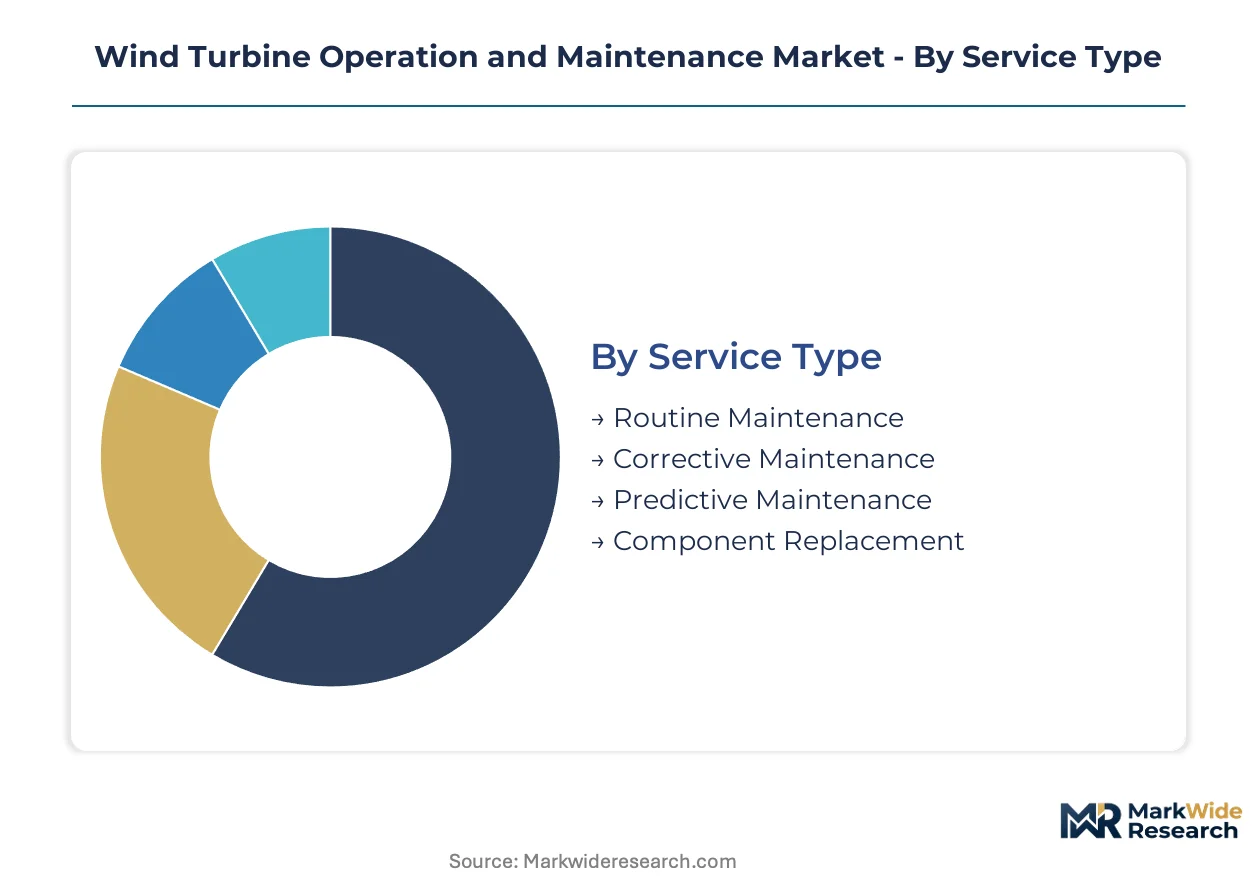
Service differentiation in wind turbine O&M determines margin capture and contract duration. Technology deployment patterns reshape logistics requirements and technician specialization needs across turbine fleets.
Service Type:
Maintenance intensity varies with turbine age, foundation type, and sensor instrumentation density.
- Routine Maintenance:Scheduled inspections, lubrication cycles, and bolt-torque verification preserve manufacturer warranty terms. German and Danish operators bundle these services through multi-year agreements to secure vessel-access windows in the North Sea.
- Predictive Maintenance:Vibration analytics, oil particle counting, and blade-damage algorithms embedded in SCADA systems trigger interventions before failure. Sensor density per nacelle triples across aging offshore fleets, converting this category from optional add-on to core contract deliverable.
- Corrective Maintenance:Unplanned repairs address gearbox seizures, generator faults, and pitch-system failures.
- Component Replacement:Major swaps of drivetrain assemblies, blades, and towers require heavy-lift vessels and port staging.
Routine maintenance leads on scale; predictive maintenance leads on momentum.
End User:
Procurement sophistication correlates with fleet size and in-house technical capabilities.
- Utilities:Vertically integrated operators with captive service divisions favor long-term performance contracts. Iberdrola and Ørsted self-perform core maintenance while outsourcing specialized blade repair to certified contractors.
- Independent Power Producers:Asset-light developers rely on OEM service agreements to satisfy lender availability guarantees. These entities drive demand for unbundled contracts separating routine inspections from major component replacement.
- Green Energy Companies:Sustainability-focused investors prioritize carbon-footprint reporting and recyclability disclosures mandated by EU Green Deal procurement frameworks.
- Government Entities:State-owned generators in China and emerging markets favor fixed-price structures to limit budget variance.
Utilities dominate contract value; independent power producers are expanding most quickly.
Technology:
Foundation and siting decisions determine access logistics, corrosion exposure, and maintenance intervals.
- Offshore Wind:Fixed-foundation installations in the North Sea command premium pricing due to vessel-access constraints and salt-air degradation accelerating drivetrain wear. Motion-compensated gangways and helicopter transfers add cost layers absent from onshore equivalents.
- Floating Wind Systems:Dynamic cable management and platform motion introduce novel failure modes requiring specialized technician training. Scotland and Portugal expand lease areas beyond fixed-foundation limits, creating first-mover opportunities for integrated service providers.
- Onshore Wind:Mature technology with standardized maintenance protocols faces margin compression as inspection work commoditizes.
- Hybrid Systems:Co-located solar-wind assets share grid infrastructure and maintenance crews.
Onshore wind leads on installed base; floating wind systems show the steepest expansion trajectory.
Contract Type:
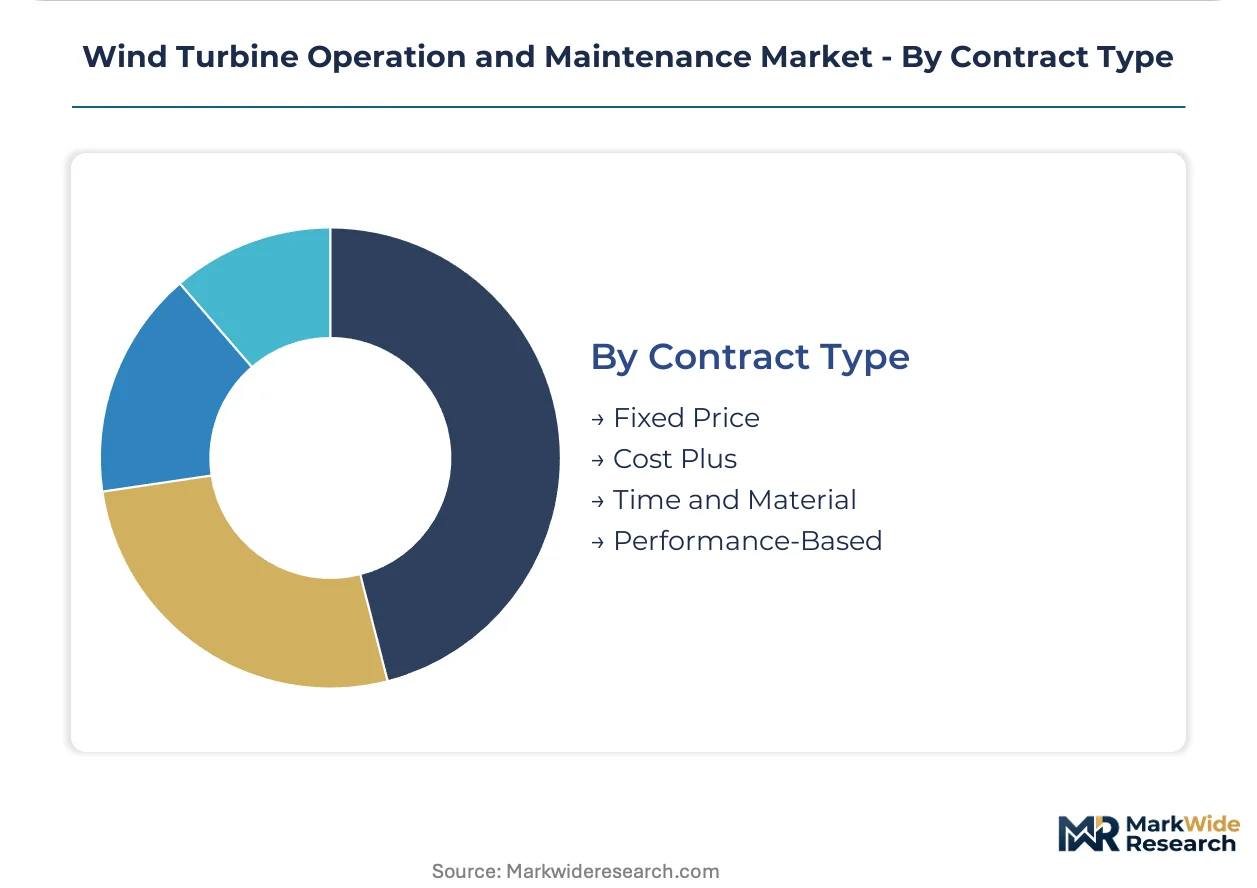
Pricing structures align risk allocation with performance visibility.
- Performance-Based:Availability guarantees and energy-output warranties displace fixed-price exposure, aligning service provider incentives with asset owner returns. German and UK offtake agreements increasingly mandate these structures for projects above ten years operational age.
- Fixed Price:Predictable budgeting appeals to government entities and infrastructure funds with yield-focused investment criteria.
- Cost Plus:Transparent pass-through of vessel day-rates and spare-part costs dominates early-stage floating wind projects with uncertain failure rates.
- Time and Material:Ad-hoc arrangements for unplanned repairs outside master service agreements.
Fixed price leads on contract count; performance-based leads on value migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's offshore technician certification requirements create steeper barriers than China's emissions benchmarks on upstream steel production, diverging regulatory intensities across the two largest wind O&M procurement markets.
Germany
The KBA enforces offshore safety certifications for technician transfer vessels that constrain fleet availability and inflate day-rate structures. EU Green Deal mandates on turbine recyclability disclosures reshape supplier qualification criteria across procurement frameworks. Hamburg and Bremerhaven anchor the North Sea service hub where integrated providers stage motion-compensated gangway systems.
United Kingdom
Offshore wind lease expansions beyond fixed-foundation limits multiply demand for dynamic cable expertise and floating platform maintenance. Performance-based contract structures with availability guarantees displace fixed-price exposure for assets exceeding ten years operational age. Aberdeen and Grimsby concentrate specialized vessel operations and blade-leading-edge repair facilities.
China
The MEE imposes carbon intensity limits on steel-forging operations feeding gearbox and tower production, reshaping upstream supply economics. State-owned generators favor fixed-price service structures to limit budget variance across provincial wind portfolios. Jiangsu and Guangdong coastal provinces host the densest concentrations of offshore turbine installations requiring vessel-based intervention.
Denmark
National renewable energy auctions tighten performance requirements that accelerate predictive maintenance adoption across aging turbine fleets. Ørsted's captive service divisions self-perform core maintenance while outsourcing specialized blade repair to certified contractors. Esbjerg functions as the primary North Sea logistics coordination point for multi-contractor operations.
United States
The IRA production tax credit extensions sustain capacity factor optimization investments across utility-scale wind portfolios. FERC interconnection queue reforms compress project commissioning timelines that strain regional technician availability. Texas and Oklahoma onshore clusters drive demand for standardized inspection protocols as fleet ages exceed original design assumptions.
Wind Turbine Operation and Maintenance Market Vendor Landscape
Top-tier vendors anchor integrated service portfolios spanning predictive analytics and offshore logistics, while mid-tier specialists capture unbundled component refurbishment and blade repair contracts. The vendor base stratifies across OEM-captive divisions, independent service companies, and emerging digital-native entrants. Three archetypes dominate: full-stack providers bundling twenty-year agreements, component specialists targeting gearbox and generator rewind markets, and logistics-anchored operators controlling vessel access. Competitive positioning hardens through M&A consolidation of regional service networks and strategic partnerships securing motion-compensated gangway technology.
Within the OEM-captive tier, Vestas and Siemens Gamesa Renewable Energy exemplify divergent strategic postures toward digital integration and logistics control. GE Vernova occupies a position emphasizing drivetrain refurbishment programs that extend asset life cycles beyond original specifications. These three entities represent the spectrum from in-house logistics networks to predictive analytics bundling across long-term offshore contracts.
| Leading Market Players |
|---|
| Vestas |
| Siemens Gamesa Renewable Energy |
| GE Vernova |
| Nordex SE |
| Goldwind |
| Suzlon Energy Limited |
| ENERCON GmbH |
| Dongfang Electric Corporation |
| Ming Yang Smart Energy Group |
| Others |
Supply Flow & Price Mechanics
Steel price indices from China and Germany cascade through wind turbine O&M supply chains into three-tier pricing structures across premium, standard, and economy service levels. Vessel day-rate volatility in the North Sea feeds directly into offshore contract premiums while onshore inspection commoditization compresses margins at the economy tier.
Pricing Analysis
Capacity additions in China's steel-forging sector are reshaping price floors for gearbox refurbishment and tower maintenance across European markets. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and vessel access complexity. Price differentiation intensifies between REACH-compliant coating services and legacy material stocks as regulatory deadlines approach. Independent power producers exhibit highest price sensitivity due to yield-focused investment criteria, while utility operators accept premium tiers for availability guarantees.
Supply Chain Analysis
Specialized vessel supply rests on shipbuilders in South Korea, Norway, and the Netherlands serving North Sea offshore logistics. Critical inputs span motion-compensated gangway systems, corrosion-resistant lubricant formulations, and multi-megawatt drivetrain components. Single-source vulnerability concentrates in helicopter transfer certification capacity constrained by Germany's KBA. Distribution runs through regional port hubs at Bremerhaven, Esbjerg, and Grimsby staging spare-part inventories for just-in-time vessel loading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wind turbine O&M offers margin expansion through predictive maintenance software converting from optional add-on to core contract deliverable, compressing cost-to-serve while extracting premium pricing for condition-based interventions.
For Market Incumbents: Hedge against independent service company fragmentation by securing captive logistics networks and embedding digital monitoring into long-term agreements. Vestas-style in-house spare-part positioning and Siemens Gamesa-style analytics bundling defend against unbundling pressures from component specialists targeting gearbox refurbishment markets. For New Entrants and Emerging Players: The premium-to-economy price gap in floating wind maintenance opens white-space targeting for motion-compensated access system operators. Scotland and Portugal lease expansions beyond fixed-foundation limits present the most penetrable geography, with dynamic cable expertise as the differentiated go-to-market angle against OEM-captive incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with logistics-anchored operators controlling vessel access in the North Sea basin. Long-term viability hinges on twenty-year service agreement backlogs and floating wind first-mover positioning. Watch GWO-certified technician availability as the inflection signal for contract fulfillment capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Integration | Machine-learning diagnostics embedded in SCADA systems convert unscheduled downtime into scheduled interventions across aging offshore fleets. |
| Offshore Logistics Capability Buildout | Motion-compensated gangway investments at Bremerhaven and Grimsby secure vessel-access windows for technician transfers in the North Sea. |
| REACH-Compliant Coating Reformulation | Advanced blade-leading-edge repair materials qualified under EU chemical regulations extend asset life cycles beyond original specifications. |
| Floating Wind Service Partnership | Dynamic cable expertise alliances with Scotland and Portugal lease operators capture first-mover advantage in beyond-fixed-foundation markets. |
| Performance-Based Contract Structuring | Availability guarantees and energy-output warranties align service provider incentives with Ørsted and Iberdrola asset owner returns. |
Methodological Framework
Bottom-up turbine fleet modeling reconciled against top-down service contract tracking forms the analytical core of this study. Primary interviews with offshore logistics coordinators, predictive maintenance software engineers, GWO-certified technician training providers, and port hub procurement managers combined with secondary validation from IEA wind deployment databases, FERC interconnection queue filings, EU Green Deal procurement frameworks, and OEM service agreement disclosures. Triangulation across stakeholder inputs and published project development pipelines ensures coverage of both operational fleet scale and emerging contract structures.
Input-output matrices map turbine age profiles and foundation types against service intensity requirements across the projection horizon. Segmentation dimensions span service type, end-user procurement sophistication, technology siting category, and contract pricing structure. CAGRs derive from fitted adoption curves for predictive maintenance penetration and floating wind installation trajectories. Forecast inputs incorporate EU auction tightening timelines, China's MEE steel-forging benchmarks, and KBA vessel certification backlogs.
Caveats apply where regulatory deadline shifts or technician training bottlenecks could materially shift the outlook. Forecasts reflect assumptions on sensor cost decline curves and machine-learning diagnostic accuracy improvement. A small set of named triggers warrants ongoing watch: GWO credential availability, motion-compensated gangway manufacturing capacity, and REACH substitution timeline compliance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
United Kingdom Renewable Energy Market
Wind Energy Systems
Offshore Wind Cable Market
Wind Energy Systems
Dual Rotor Wind Turbine Market
Wind Energy Systems
Asia-Pacific Large Wind Turbine Market
Wind Energy Systems
Wind Turbine Lenses Market
Wind Energy Systems
South Korea Wind Energy Market
Wind Energy Systems
Japan Wind Energy Market
Wind Energy Systems
Small Scale Single and Multi-Rotor Wind Turbine Market
Wind Energy Systems
Floating Wind Turbine Market
Wind Energy Systems
Wind Power Converter Systems Market
Wind Energy Systems
Airborne Wind Turbines Market
Wind Energy Systems
Wind Power Couplings Market
Wind Energy Systems
Wind Turbine Brakes Market
Wind Energy Systems
Global Wind Power Coatings Market
Wind Energy Systems
Brazil Wind Energy Market
Wind Energy Systems
Wind Tower Market