
 Germany Wind Energy Market | 2026-2036
Germany Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Wind Energy Market Foresight
Utility-scale procurement is bifurcating from cooperative-led distributed projects as offshore auctions attract larger balance sheets. Nordex Group leverages its onshore manufacturing footprint in Rostock to serve regional utility demand. Enercon GmbH anchors the direct-drive segment through its gearless turbine architecture. Siemens Gamesa Renewable Energy competes aggressively in offshore tenders with its SG 14-236 DD platform.
Germany wind energy encompasses the conversion of kinetic atmospheric flow into electrical power through aerodynamic rotor blades coupled to electromechanical generators, typically operating at hub heights between 80 and 150 meters and rotor diameters exceeding 160 meters for modern onshore units. The primary commercial purpose is grid-connected bulk power supply with ancillary frequency regulation services. Onshore installations dominate installed capacity but face saturation in northern federal states where wind resource density peaks. Offshore deployment represents the fastest-expanding application segment as water depths beyond 50 meters favor floating foundation pilots. Permanent magnet generator technology leads the technology split due to higher efficiency at partial load, though rare earth supply constraints create margin pressure across the value chain.
The Bundesnetzagentur governs offshore grid connection tenders under the Netzausbaugesetz framework, while KBA certification requirements apply to transport logistics for oversized turbine components. EEG 2023 reforms have shifted subsidy mechanisms from fixed tariffs to competitive auctions, reshaping developer bidding strategies and project finance structures. Stakeholders must monitor North Sea grid congestion timelines and hydrogen corridor integration plans to calibrate capacity commitment decisions.
Market Dynamics
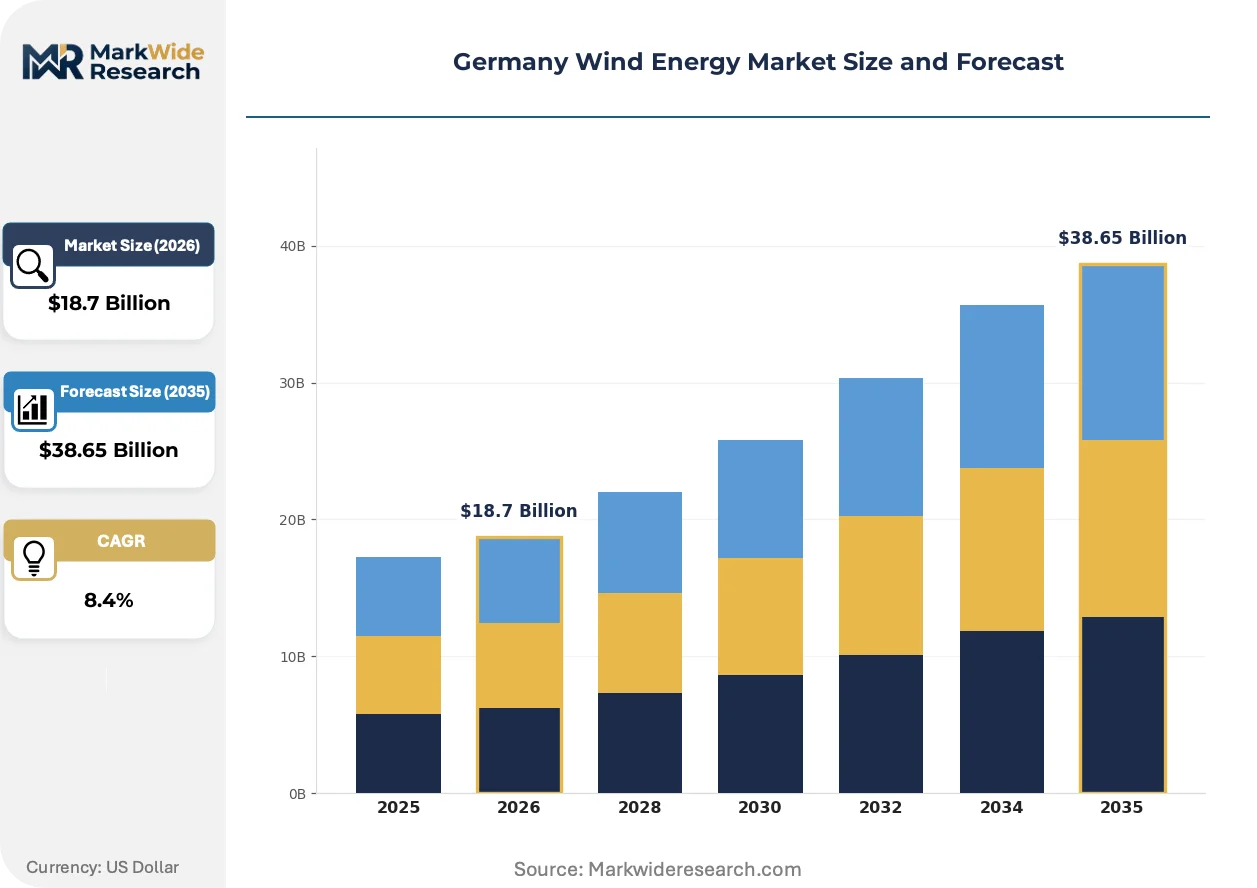
The EEG 2023 auction mechanism is compressing developer margins while accelerating offshore capacity commitments, forcing balance sheet restructuring across German wind portfolios.
Growth Catalysts
- Netzausbaugesetz Grid Expansion:Bundesnetzagentur tenders for North Sea offshore connections are de-risking project timelines for utility-scale developers.
- Floating Foundation Pilots:Water depths beyond 50 meters in the German Bight are unlocking acreage previously inaccessible to fixed-bottom installations.
- Hydrogen Corridor Integration:Electrolyzer co-location at offshore substations is creating dual-revenue streams that improve project financeability.
Market Restraints
- Rare Earth Supply Concentration:Permanent magnet generator dependence on Chinese-processed neodymium creates input cost volatility and geopolitical exposure.
- Onshore Saturation in Northern States:Schleswig-Holstein and Lower Saxony face permitting exhaustion as wind resource density peaks against land-use constraints.
- KBA Transport Certification:Oversized component logistics face bottlenecks from specialized vehicle approval timelines and route clearance requirements.
Strategic Opportunities
- Baltic Sea Underpenetration:Mecklenburg-Vorpommern offshore zones offer lower competition intensity compared to congested North Sea lease areas.
- Repowering Onshore Fleet:15-20 year old turbines in Brandenburg and Saxony-Anhalt present blade-tip extension and nacelle upgrade potential.
- Frequency Regulation Services:Grid code reforms by Bundesnetzagentur are creating ancillary revenue streams from synthetic inertia provision.
Industry Challenges
- Specialized Installation Vessel Shortage:Heavy-lift jack-up availability for 15MW+ turbines constrains offshore construction windows.
- Grid Synchronization Complexity:Phase-angle regulation with legacy coal and nuclear retirement schedules creates stability management burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Wind Energy Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Onshore, Offshore, Floating, Hybrid Technology: Permanent Magnet, Doubly Fed Induction Generator, Synchronous Generator, Direct Drive Application: Power Generation, Grid Support, Remote Area Electrification, Water Pumping End User: Energy Providers, Utilities, Independent Power Producers, Cooperatives |
| Companies Covered | Nordex Group, Enercon GmbH, Vestas Wind Systems A/S, Siemens Gamesa Renewable Energy, RWE AG, Orsted A/S, General Electric Company, EnBW, PNE AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Wind Energy Market Shifts & Advancements
Turbine scale escalation and auction-driven procurement compression are restructuring the German wind value chain around capital intensity and manufacturing consolidation.
Direct-drive generator architecture is bifurcating the onshore supply base. Enercon's gearless platform eliminates gearbox maintenance burdens for German utility operators. The technology is compressing service contract margins while extending operational life assumptions in project finance models.
EEG 2023's shift from fixed tariffs to competitive auctions is reshaping developer bidding behavior. Project sponsors now absorb merchant price exposure rather than transferring it to grid operators. This mechanism is forcing vertical integration into offtake origination and power purchase agreement structuring.
Utility procurement patterns are consolidating around balance-sheet-backed consortia. Smaller municipal utilities are ceding tender participation to multi-utility alliances with stronger credit ratings. This concentration is most visible in North Sea offshore rounds where bid bonds and completion guarantees filter out sub-scale participants.
Germany Wind Energy Market Segmentation
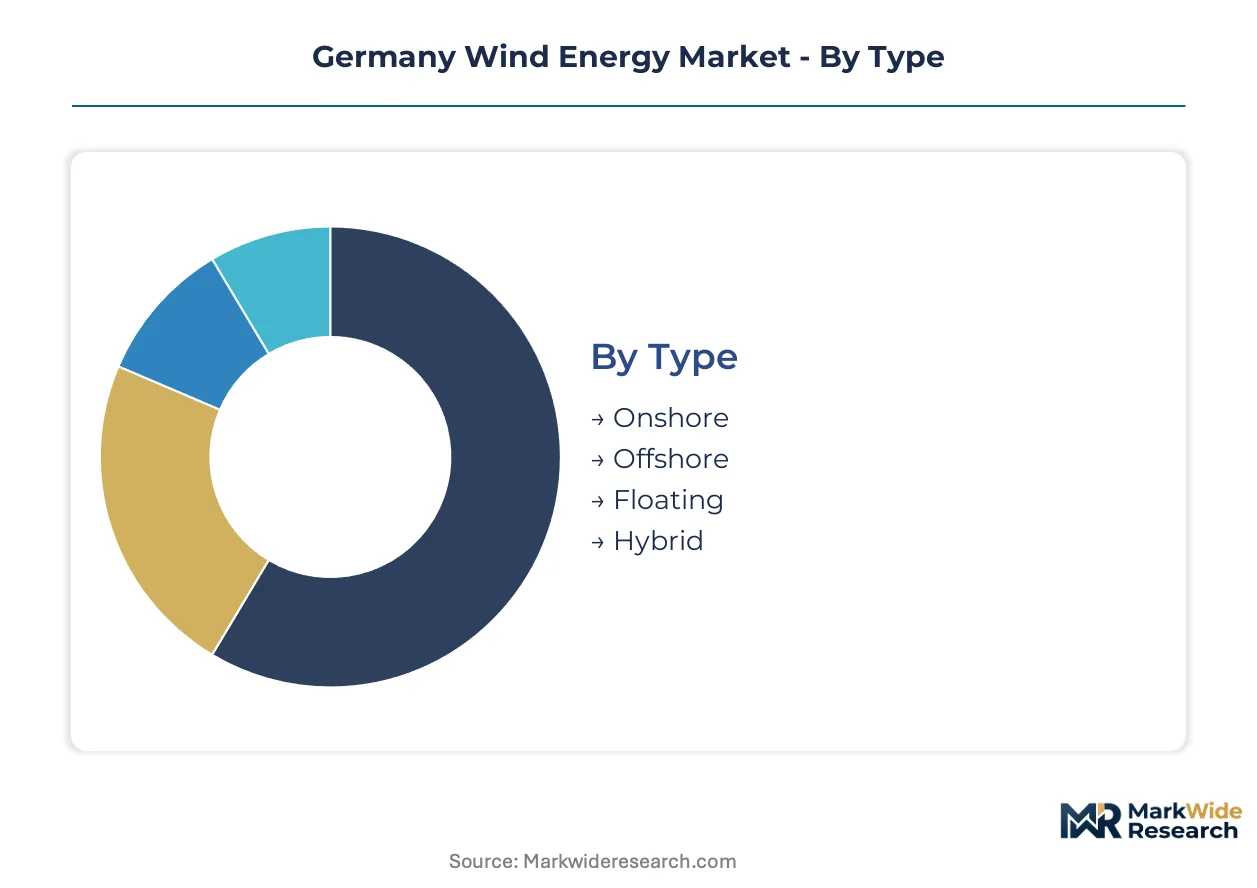
German wind energy segmentation reflects divergent regulatory treatment across installation environments and generator architectures. EEG 2023 auction mechanics and Bundesnetzagentur grid codes create distinct compliance burdens that reshape competitive positioning within each category.
Type:
Bundesnetzagentur licensing timelines differentiate fixed-bottom from floating installations through separate environmental impact assessment tracks under the Netzausbaugesetz framework.
- Onshore:Turbines sited across Schleswig-Holstein and Lower Saxony operate at hub heights between 80 and 150 meters with rotor diameters exceeding 160 meters. Permitting exhaustion in northern federal states concentrates repowering demand in Brandenburg and Saxony-Anhalt where older fleets require blade-tip extension or nacelle replacement.
- Offshore:Fixed-bottom installations in the North Sea basin connect through expanding grid infrastructure tendered by Bundesnetzagentur. Water depths favoring 15MW+ turbines strain heavy-lift jack-up vessel availability and compress construction windows around seasonal weather limits.
- Floating:Pilot projects beyond 50-meter depths in the German Bight test tension-leg and semi-submersible foundations. KBA transport certification for oversized floating platform components adds logistics complexity absent from fixed-bottom supply chains.
- Hybrid:Co-located wind and electrolyzer configurations at offshore substations generate dual revenue streams through hydrogen corridor integration.
Established volume favors onshore; emerging adoption favors floating.
Technology:
Generator architecture selection hinges on partial-load efficiency targets and rare earth supply security considerations.
- Permanent Magnet:Neodymium-based rotor configurations deliver superior efficiency at variable wind speeds. Chinese-processed rare earth concentration creates input cost volatility and geopolitical exposure that compresses manufacturing margins.
- Doubly Fed Induction Generator:Partial-scale power electronics reduce converter costs compared to full-conversion alternatives. German utility operators favor this technology for grid support applications requiring synthetic inertia provision.
- Synchronous Generator:Wound-rotor designs eliminate permanent magnet dependence. Niche deployment concentrates in repowering projects where existing gearbox infrastructure can be retained.
- Direct Drive:Gearless architectures eliminate gearbox maintenance burdens and extend operational life assumptions in project finance models. Enercon GmbH anchors this segment through its proprietary platform.
Permanent magnet dominates new capacity; direct drive gains share in utility-scale procurement.
Application:
Revenue model differentiation separates bulk power supply from ancillary service streams.
- Power Generation:Grid-connected bulk supply constitutes the primary commercial purpose across EEG 2023 auction rounds. Merchant price exposure now sits with developers rather than grid operators.
- Grid Support:Frequency regulation and synthetic inertia services create ancillary revenue streams under Bundesnetzagentur grid code reforms. Phase-angle regulation complexity rises with coal and nuclear retirement schedules.
- Remote Area Electrification:Islanded or weak-grid configurations serve agricultural and industrial loads in eastern federal states with limited transmission infrastructure.
- Water Pumping:Mechanical wind power for irrigation and drainage persists in heritage agricultural zones with legacy infrastructure.
Power generation commands capacity share; grid support expands revenue per megawatt.
End User:
Balance sheet strength filters participation in competitive auction rounds.
- Energy Providers:Vertically integrated majors with captive offtake portfolios absorb merchant price exposure through power purchase agreement origination.
- Utilities:Multi-utility alliances with investment-grade credit ratings dominate North Sea offshore tenders where bid bonds and completion guarantees exclude sub-scale participants.
- Independent Power Producers:Project finance-dependent developers face margin compression from EEG 2023 auction mechanisms and rising cost of capital.
- Cooperatives:Municipal and citizen-led structures cede offshore participation to larger consortia while retaining onshore distributed project development.
Utility consortia capture offshore volume; cooperatives retain onshore distributed niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The BorWin3 grid connection corridor underwrites Germany's offshore expansion by linking North Sea wind clusters to onshore substations. This infrastructure backbone concentrates development activity in coastal federal states where port facilities and cable manufacturing clusters align.
Schleswig-Holstein
Port of Cuxhaven heavy-lift terminals and blade manufacturing at Lauenburg anchor the onshore supply chain. EEG 2023 auction participation rates here exceed other states as land availability tightens. Repowering demand concentrates in Dithmarschen district where 2000s-era turbines reach end-of-design-life.
Lower Saxony
Emden offshore logistics hub and Nordex Rostock manufacturing serve North Sea installation campaigns. Bundesnetzagentur grid connection tenders for BorWin4 and DolWin6 de-risk project timelines for utility consortia. Brake and Wilhelmshaven port expansions handle nacelle and tower component throughput.
Mecklenburg-Vorpommern
Baltic Sea offshore zones face lower lease competition than North Sea blocks. Mukran port on Rügen island tests floating foundation assembly for 50-meter-plus water depths. KBA transport certification bottlenecks for oversized components constrain inland turbine delivery routes.
Brandenburg
Prignitz and Uckermark districts host aging onshore fleets installed during 2005-2010 EEG feed-in tariff waves. Repowering economics favor blade-tip extensions over full nacelle replacement given existing grid connection capacity. Local cooperatives retain project development rights against utility-scale acquisition pressure.
North Rhine-Westphalia
Ruhr industrial demand centers absorb wind power through direct corporate PPAs bypassing EEG auction mechanisms. ThyssenKrupp and other heavy manufacturers anchor offtake agreements for renewable electricity supply. Grid congestion on 380kV west-east transmission corridors limits north German wind penetration.
Germany Wind Energy Market Competitive Landscape
Listed leaders compete with private specialists across auction participation and balance-sheet capacity. Utility-scale offshore tenders filter participation toward investment-grade entities with captive offtake portfolios. Three archetypes dominate: vertically integrated energy majors, turbine OEMs with captive service arms, and project developers dependent on external construction finance. Competitive moves concentrate on PPA origination capabilities and grid connection queue positioning.
Among turbine manufacturers, Nordex Group, Enercon GmbH, and Siemens Gamesa Renewable Energy occupy distinct technology positions. Nordex represents the scale-driven archetype with Rostock manufacturing footprint. Enercon exemplifies the direct-drive specialist model through gearless architecture. Siemens Gamesa anchors the offshore-heavy portfolio with SG 14-236 DD platform credentials. Each sits within different risk-reward profiles under EEG 2023 auction mechanics.
| Leading Market Players |
|---|
| Nordex Group |
| Enercon GmbH |
| Vestas Wind Systems A/S |
| Siemens Gamesa Renewable Energy |
| RWE AG |
| Orsted A/S |
| General Electric Company |
| EnBW |
| PNE AG |
| Others |
Supply & Pricing Matrix
Take-or-pay offtake structures in EEG 2023 auction rounds lock in both turbine component supply access and long-term price visibility for German utility consortia, compressing merchant risk exposure while binding OEMs to fixed delivery schedules.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments turbine procurement by certification grade and after-sales service bundling. Premium tiers command pricing power through Bundesnetzagentur grid code compliance and extended warranty coverage, while economy tiers face cost compression from rare earth input volatility. Independent power producers exhibit highest price sensitivity due to project finance leverage constraints, whereas vertically integrated energy majors absorb pricing premiums for delivery certainty.
Supply Chain Analysis
Just-in-time inventory strategies dominate nacelle assembly, but strategic stockpiling of neodymium magnets and carbon fiber pre-preg has intensified among Rostock-based manufacturers. Supply concentration in China for rare earth processing, Denmark for blade molds, and Spain for power electronics creates single-source vulnerability on magnet inputs. Distribution runs through Emden and Cuxhaven port clusters for offshore components, with KBA-certified heavy-transport operators handling inland turbine delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German wind energy hardware margins are flattening while service-attach revenues from predictive maintenance and blade repair contracts expand faster than turbine sales, creating recurring-revenue pools that improve capital efficiency.
For Market Incumbents: Consolidate service contract portfolios through acquisition of regional maintenance specialists to lock in aftermarket revenue streams. Capture backward integration into rare earth magnet recycling to hedge Chinese supply concentration. Prioritize certification investment for 15MW+ offshore platforms before vessel availability constraints tighten construction windows.
For New Entrants and Emerging Players: Floating foundation engineering services represent a service-layer gap where incumbent OEMs under-serve pilot project demand. Target Mecklenburg-Vorpommern Baltic Sea zones for lower auction competition intensity. Deploy through joint venture structures with port authorities to secure assembly site access without capital-heavy manufacturing footprints.
For Investors and Strategic Acquirers: Capital is best deployed toward project developers with queued grid connection rights and captive PPA origination capabilities. Long-term viability favors entities with electrolyzer co-location strategies for hydrogen corridor integration. Monitor Bundesnetzagentur offshore tender announcement timing as inflection indicator for capacity commitment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Offshore Capacity Buildout | 15MW+ turbine deployment in North Sea zones leverages BorWin grid expansion timelines. |
| Power Purchase Agreement Origination | Corporate offtake with ThyssenKrupp and Ruhr industrial buyers bypasses EEG auction exposure. |
| Technology Licensing for Floating Platforms | Tension-leg foundation patents unlock German Bight acreage beyond 50-meter depths. |
| Vertical Integration into Electrolyzer Co-location | Offshore substation hydrogen production creates dual-revenue streams under Netzausbaugesetz frameworks. |
| Green Certification Program | EEG 2023 compliance documentation accelerates auction bid qualification for utility consortia. |
Research Methodology
Desk research of Bundesnetzagentur tender documentation, EEG regulatory filings, and North Sea grid connection databases preceded structured interviews with utility planning officers, IPP project developers, EPC contractors, and offshore vessel operators. Secondary validation drew from IEA wind deployment statistics, German federal network agency reports, and customs data on turbine component imports. Bottom-up project pipeline analysis triangulated against top-down capacity targets across the analysis window.
Variance decomposition across technology type, installation environment, and end-user archetype shaped the analytical framework. Modeled segmentation tracked onshore versus offshore deployment, generator architecture preferences, and utility versus cooperative ownership structures. CAGRs were derived from auction round capacity allocations and grid connection commissioning schedules, with input assumptions on turbine cost curves and financing cost trajectories.
Forecasts assume regulatory continuity in EEG 2023 auction mechanisms and Netzausbaugesetz grid expansion timelines; material policy shifts on feed-in tariffs or offshore lease terms would require re-modeling. Rare earth supply disruptions, vessel availability constraints, or accelerated coal retirement schedules represent specific risk factors that could revise capacity deployment trajectories. Practitioners should keep alternative scenarios live as hydrogen corridor integration plans and Baltic Sea floating pilot results evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Double-Fed Wind Turbine Market
Wind Energy Systems
Wind Turbine Tower Market
Wind Energy Systems
Dual Rotor Wind Turbine Market
Wind Energy Systems
Wind Power Couplings Market
Wind Energy Systems
Denmark Wind Energy Market
Wind Energy Systems
Belgium Wind Energy Market
Wind Energy Systems
Global Wind Automation Market
Wind Energy Systems
Thailand Wind Energy Market
Wind Energy Systems
Wind Turbine Gearbox Market
Wind Energy Systems
Offshore Wind Cable Market
Wind Energy Systems
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market
Wind Energy Systems
Wind Turbine Cables Market
Wind Energy Systems
Italy Wind Energy Market
Wind Energy Systems
Wind Turbine Market
Wind Energy Systems
Wind Energy Foundation Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Drive Market