
 Wind Turbine Pitch Systems Market | 2026-2036
Wind Turbine Pitch Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Pitch Systems Market Outlook
Capital-intensity divergence between integrated drivetrain manufacturers and standalone pitch component suppliers is reorganizing competitive tiers in wind turbine pitch systems. Moog leverages its precision motion control heritage to dominate high-reliability electromechanical actuators for offshore installations. Vestas Wind Systems anchors its pitch strategy through captive supply integration across its global turbine fleet. Bosch Rexroth competes on hydraulic pitch expertise, sustaining market presence through specialized high-pressure system engineering.
Wind turbine pitch systems comprise electromechanical or hydraulic actuation mechanisms that adjust blade angle of attack to optimize aerodynamic efficiency and enable rotor speed regulation across variable wind conditions. These systems typically incorporate servo motors, planetary gearboxes, battery backup units, and programmable logic controllers capable of sub-degree positioning accuracy under dynamic load cycles exceeding 10^8 operations. Active pitch control systems now represent the dominant product architecture, with hydraulic pitch control retaining structural share in cold-climate and high-wind-speed installations where torque density requirements favor fluid power. Sensor-based technology segments are expanding fastest as blade load monitoring and predictive maintenance protocols displace scheduled component replacement cycles.
IEC 61400-4 gearbox standards and the EU F-Gas Regulation constrain hydraulic fluid specifications and pitch bearing lubrication protocols, compelling OEMs to redesign seal systems and validate alternative working fluids. China's GB standards and NMPA-equivalent wind equipment certification framework mandate domestic content thresholds that reshape supplier qualification pathways for foreign pitch system vendors. Stakeholders must monitor evolving grid code requirements in Germany and the United States, where frequency response capabilities and fault ride-through specifications increasingly dictate pitch controller firmware architecture and response latency thresholds.
Market Dynamics
Offshore wind farm operators are forcing a technology transition from hydraulic to electromechanical pitch actuation systems, driven by the EU F-Gas Regulation's phase-down of fluorinated greenhouse gases used in hydraulic fluids and the need for predictive maintenance capabilities in remote marine environments.
Growth Catalysts
- IEC 61400-4 gearbox standards:Certification protocols for pitch bearing durability are accelerating replacement cycles and expanding the addressable aftermarket for component suppliers.
- China's domestic OEM scaling:Turbine manufacturing capacity concentration in Jiangsu and Guangdong provinces is generating localized demand for pitch system integration services.
- Sensor-based blade load monitoring:Fiber optic strain sensing technology is displacing scheduled maintenance intervals with condition-based intervention protocols.
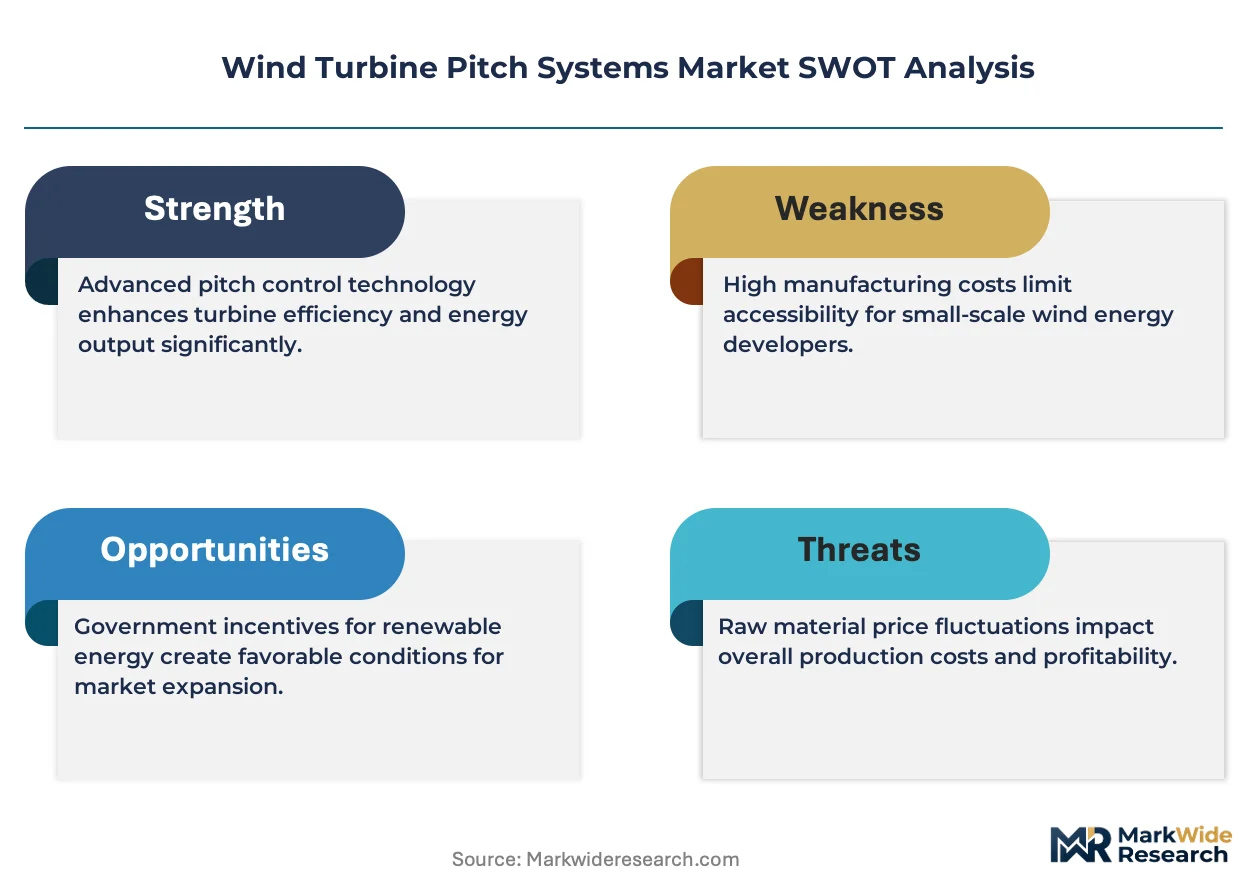
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet servo motors depend on neodymium processing facilities concentrated in Inner Mongolia, creating input cost volatility and geopolitical exposure.
- Hydraulic fluid incompatibility:The EU F-Gas Regulation's HFC-134a phase-down timeline forces cold-climate operators to validate alternative working fluids with inferior low-temperature viscosity properties.
- Sealed electromechanical actuator IP ratings:Salt spray corrosion resistance requirements for offshore installations exceed standard IEC 60529 specifications, limiting qualified supplier pools.
Strategic Opportunities
- Retrofit aftermarket in Germany:Aging onshore turbine fleets installed during the 2000-2010 expansion require pitch controller firmware upgrades to meet modern grid code frequency response specifications.
- Digital twin convergence:Physics-based blade load modeling combined with SCADA data analytics enables predictive pitch bearing failure detection before surface crack propagation.
- Direct-drive turbine architectures:Gearless generator designs eliminate gearbox maintenance but increase pitch system duty cycles, expanding actuator replacement revenue streams.
Industry Challenges
- Electromechanical-hydraulic system integration:Mixed-technology turbine fleets require maintenance technicians trained in both high-voltage servo diagnostics and high-pressure fluid power troubleshooting.
- IECRE certification timeline compression:Component-level type certification for pitch controllers now requires synchronized validation across multiple notified bodies, extending product launch schedules.
- Legacy hydraulic inventory stranding:Cold-climate operators holding pre-F-Gas Regulation fluid stocks face accelerated obsolescence as seal compatibility warranties expire.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Pitch Systems Market |
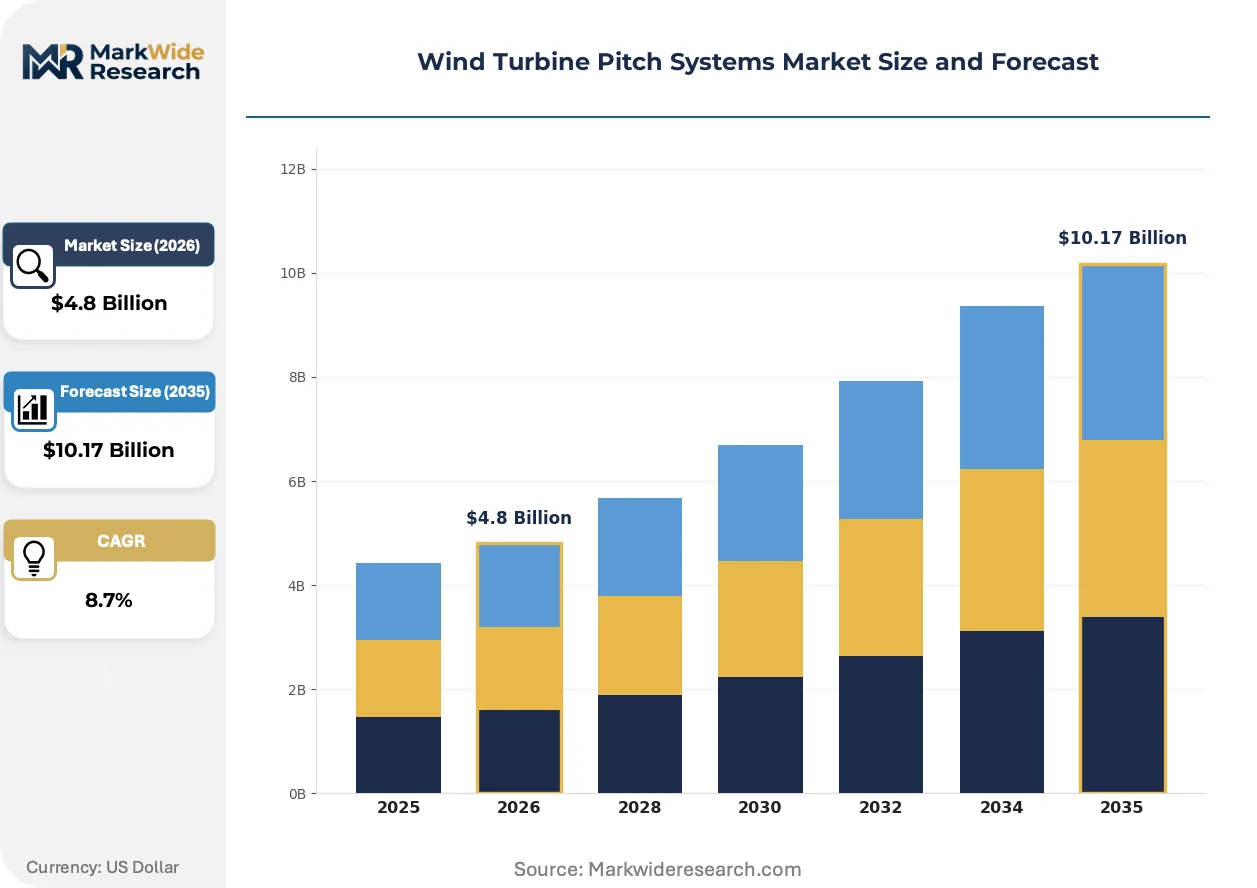
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Pitch Systems, Passive Pitch Systems, Electrical Pitch Control, Hydraulic Pitch Control Technology: Direct Drive, Gearbox, Sensor-based, Variable Speed End User: Wind Farm Operators, OEMs, Independent Power Producers, Utilities Installation: Onshore, Offshore, Retrofit, New Build |
| Companies Covered | Moog, KEB Automation, Vestas Wind Systems, SSB Wind Systems, KK Wind Solutions, Siemens Gamesa Renewable Energy, Bosch Rexroth, Mita Teknik, Enercon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Pitch Systems Market Strategic Shifts
Digitalization of pitch system architecture is compressing maintenance intervals and enabling remote diagnostics, while regulatory pressure on working fluids and bearing lubricants forces material science innovation in seal compounds and synthetic ester formulations.
Electromechanical pitch actuation is bifurcating the installed base between legacy hydraulic systems and sealed servo-motor architectures. Offshore wind farm operators in the North Sea and Baltic Sea are specifying electromechanical systems exclusively for new installations. This technology split is compressing aftermarket parts commonality and forcing suppliers to maintain dual qualification pathways.
The EU F-Gas Regulation's hydrofluorocarbon phase-down mandates are constraining hydraulic fluid specifications for cold-climate installations. OEMs are redesigning seal systems to accommodate synthetic ester alternatives with inferior thermal stability. High-wind-speed onshore sites in Scotland and Norway are most affected, with operators extending validation timelines for alternative working fluids.
Service contract unbundling is disrupting traditional full-service agreements between turbine OEMs and wind farm operators. Independent service providers are capturing pitch system maintenance through specialized electromechanical actuator expertise. This procurement fragmentation is most visible in the United States, where utility-scale independent power producers are disaggregating component-level service awards.
Wind Turbine Pitch Systems Market Segmentation
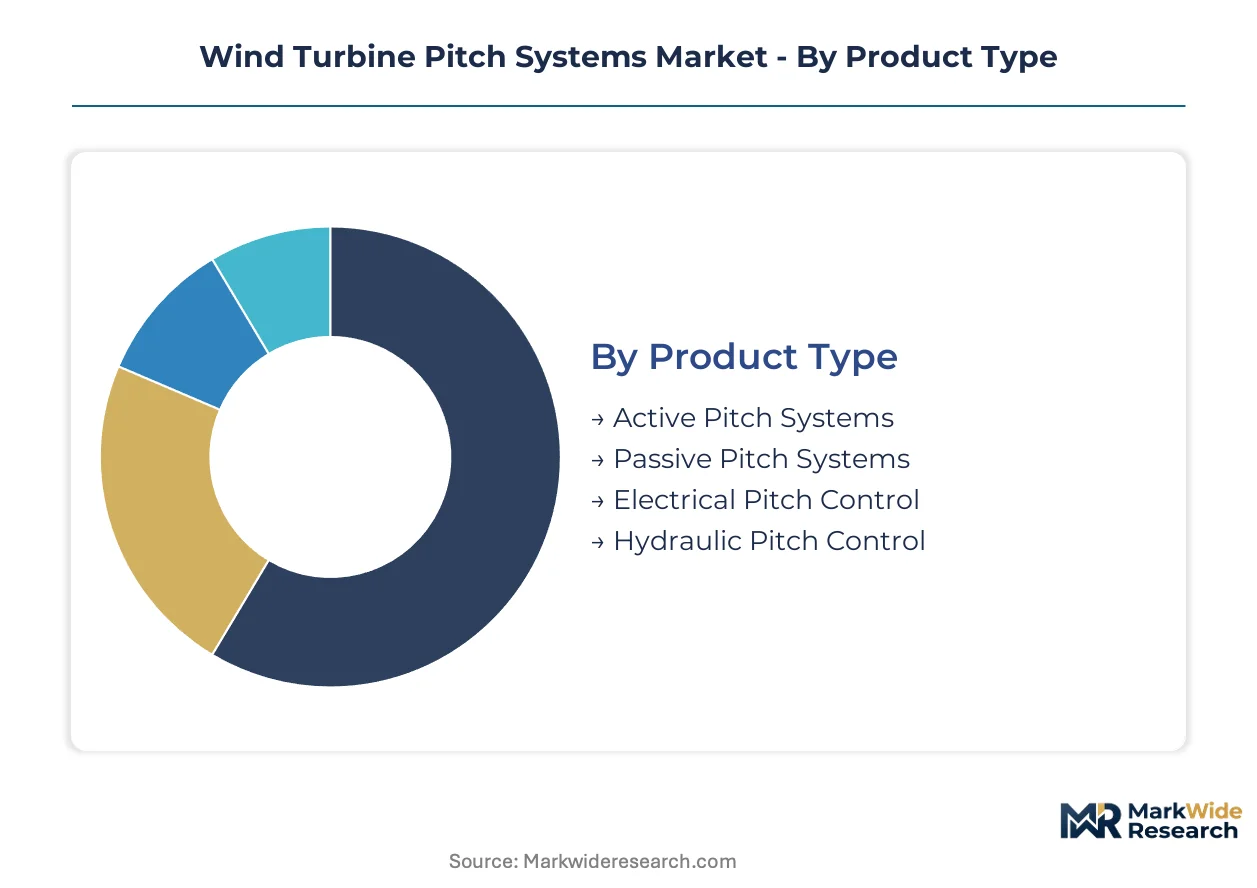
Pitch system architecture determines maintenance economics and regulatory compliance pathways across turbine vintages. Technology choices in this market segment equipment suppliers into distinct competitive tiers based on actuation principles and control intelligence.
Product Type:
Margin pools concentrate in electromechanical architectures where sealed actuator designs command premium pricing for offshore reliability requirements.
- Active Pitch Systems:These systems employ real-time blade angle adjustment through servo-controlled actuators responding to wind speed and load data. Offshore wind farm operators in the North Sea and Baltic Sea specify active pitch exclusively for new installations, driven by remote diagnostic requirements and the EU F-Gas Regulation's hydrofluorocarbon phase-down mandates.
- Electrical Pitch Control:Brushless DC servo motors with planetary gearboxes deliver sub-degree positioning accuracy across 10^8 operational cycles. China's domestic OEM scaling in Jiangsu and Guangdong provinces is absorbing electrical pitch capacity fastest, as GB standards certification favors integrated electromechanical suppliers with localized production.
- Passive Pitch Systems:Centrifugal force mechanisms adjust blade pitch without external power, limiting application to small-scale turbines below 100kW rated capacity.
- Hydraulic Pitch Control:High-pressure fluid power systems retain structural share in cold-climate installations where torque density requirements exceed electromechanical alternatives.
The dominant share belongs to Active Pitch Systems, while Electrical Pitch Control is closing the gap fastest.
Technology:
Volume concentration tracks generator architecture choices, with direct-drive designs eliminating gearbox maintenance but intensifying pitch system duty cycles.
- Sensor-based:Fiber optic strain sensing and blade load monitoring enable condition-based maintenance protocols displacing scheduled replacement cycles. Germany's aging onshore fleet retrofit demand concentrates here, as modern grid code frequency response specifications require real-time load data integration.
- Direct Drive:Gearless generator designs remove mechanical transmission complexity while increasing pitch actuator operational frequency. Scotland and Norway high-wind-speed sites favor this architecture for its reduced drivetrain maintenance exposure.
- Gearbox:Conventional drivetrains with integrated pitch bearing assemblies dominate installed base maintenance revenue.
- Variable Speed:Power electronics coupling rotor speed to grid frequency requirements, with pitch control optimizing aerodynamic efficiency across variable wind regimes.
Sensor-based technology is expanding most quickly, though Direct Drive retains the largest installed base footprint.
End User:
Procurement authority fragmentation is reshaping supplier relationships, with independent power producers disaggregating component-level service awards from traditional full-service agreements.
- Wind Farm Operators:Asset owners prioritizing predictive maintenance capabilities and unplanned downtime reduction. United States utility-scale operators are unbundling service contracts fastest, creating specialized electromechanical actuator procurement channels.
- OEMs:Turbine manufacturers integrating pitch systems through captive supply or qualified vendor programs. Vestas anchors its global fleet through integrated pitch strategy, while Chinese OEMs localize supplier qualification pathways under NMPA-equivalent certification frameworks.
- Independent Power Producers:Non-utility generators with direct procurement authority over component replacement and upgrade cycles.
- Utilities:Vertically integrated electricity providers with standardized equipment specifications across multi-site portfolios.
Wind Farm Operators command the dominant procurement volume, while Independent Power Producers are gaining contractual autonomy fastest.
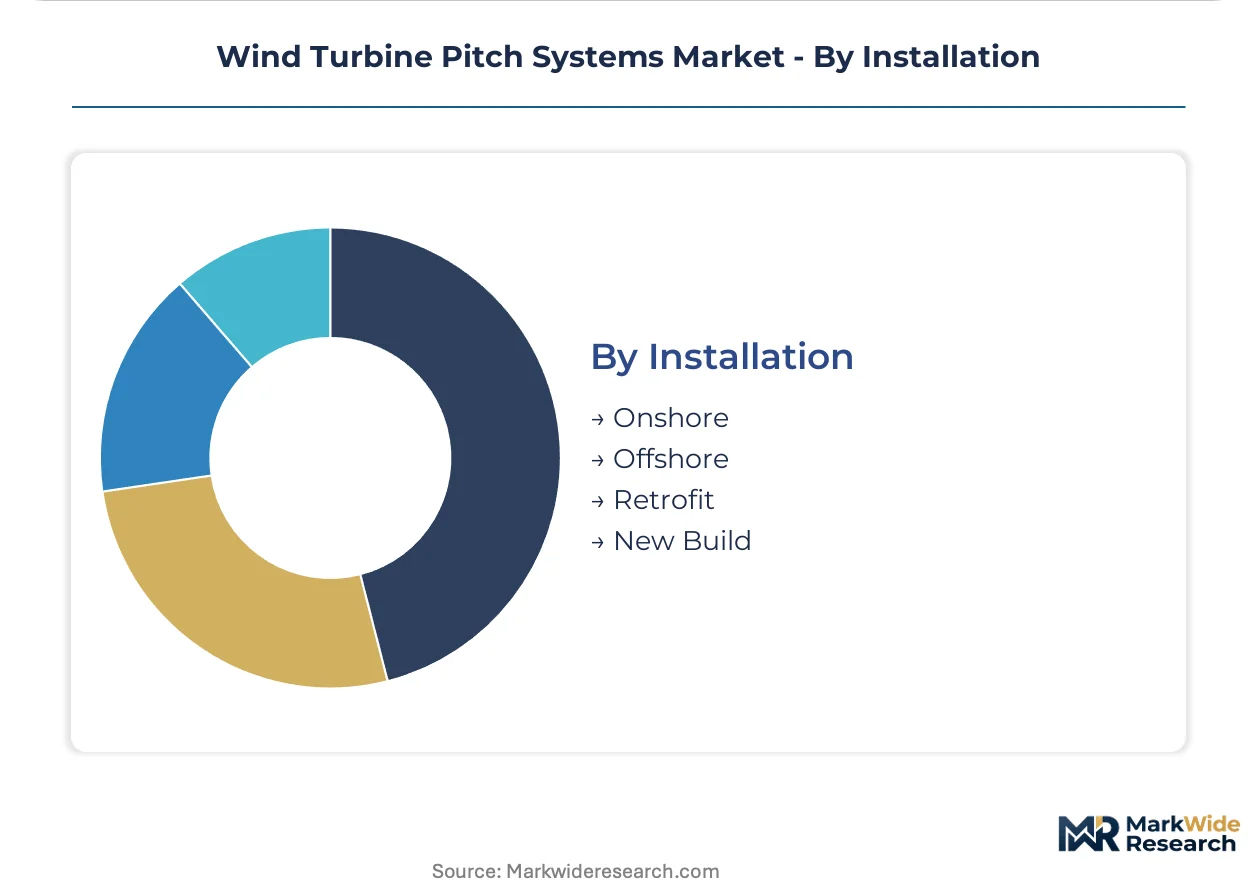
Installation:
Site classification determines environmental protection specifications and maintenance access economics, with salt spray corrosion resistance requirements exceeding standard IEC 60529 ratings for marine applications.
- Offshore:Installations in marine environments requiring IP-rated sealed actuators and remote diagnostic architecture. The EU F-Gas Regulation and IEC 61400 standards constrain hydraulic system specifications, accelerating electromechanical transition.
- New Build:Greenfield turbine installations incorporating latest pitch controller firmware and grid code compliance from commissioning.
- Onshore:Land-based installations representing volume concentration in China, Germany, and the United States.
- Retrofit:Existing turbine upgrades including pitch controller firmware modernization and bearing replacement cycles.
New Build captures the dominant share of current investment, while Retrofit is climbing the fastest as aging fleets require grid code compliance upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts. Chinese wind farm operators prioritize unit cost minimization through domestic supplier qualification. North Sea offshore developers accept electromechanical system premiums for predictive maintenance access in remote marine environments.
China
Domestic OEM scaling in Jiangsu and Guangdong provinces absorbs pitch system capacity fastest. GB standards and NMPA-equivalent certification frameworks mandate domestic content thresholds that reshape foreign supplier pathways. Turbine manufacturing clusters in Yangtze River Delta and Pearl River Delta concentrate electromechanical actuator demand from Goldwind and Envision.
Germany
Aging onshore fleets installed during 2000-2010 expansion require pitch controller firmware upgrades for modern grid code compliance. The EU F-Gas Regulation constrains hydraulic fluid specifications, compelling seal system redesigns. Industrial concentration in Lower Saxony and North Rhine-Westphalia hosts Siemens Gamesa and Enercon service operations targeting retrofit aftermarket.
United States
Utility-scale independent power producers disaggregate component-level service awards from traditional full-service agreements. FERC grid code requirements for frequency response capabilities dictate pitch controller firmware architecture. Texas and Iowa wind corridors concentrate demand for electromechanical actuator expertise among specialized independent service providers.
United Kingdom
Scotland's high-wind-speed onshore sites favor hydraulic pitch retention where torque density requirements exceed electromechanical alternatives. The EU F-Gas Regulation's HFC-134a phase-down forces cold-climate operators to validate synthetic ester alternatives. Aberdeen and Glasgow industrial bases support North Sea offshore electromechanical transition programs.
Norway
Arctic wind installations confront hydraulic fluid incompatibility under tightening EU environmental mandates. Direct-drive turbine architectures eliminate gearbox maintenance while intensifying pitch system duty cycles. Stavanger and Bergen engineering clusters develop sealed electromechanical actuators exceeding standard IEC 60529 salt spray specifications.
Wind Turbine Pitch Systems Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the pitch systems value chain. Integrated drivetrain manufacturers capture margin through captive supply integration, while standalone component specialists compete on electromechanical actuator reliability metrics. The market structures around three archetypes: precision motion control heritage firms, hydraulic system engineering specialists, and turbine OEMs with vertical supply chain control. Consolidation pressure manifests through strategic partnerships for sensor-based blade load monitoring and geographic expansion into Chinese domestic OEM qualification pathways.
Within the precision motion control tier, Moog and Bosch Rexroth occupy distinct positioning vectors. Moog exemplifies electromechanical actuator specialization for offshore reliability requirements. Bosch Rexroth anchors hydraulic pitch expertise amid regulatory transition pressure. Among turbine OEMs with integrated strategies, Vestas Wind Systems represents captive supply chain control across global fleet installations. KEB Automation and SSB Wind Systems sit within the standalone component specialist tier competing on firmware architecture and grid code response latency.
| Leading Market Players |
|---|
| Moog |
| KEB Automation |
| Vestas Wind Systems |
| SSB Wind Systems |
| KK Wind Solutions |
| Siemens Gamesa Renewable Energy |
| Bosch Rexroth |
| Mita Teknik |
| Enercon |
| Others |
Value Chain & Pricing Dynamics
Ninety-day actuator inventory cycles at North Sea offshore developers concentrate procurement leverage among electromechanical specialists while compressing hydraulic component pricing power. This lead-time asymmetry between sealed servo-motor architectures and legacy fluid-power systems feeds directly into supplier tier stratification and contract term divergence across turbine vintages.
Pricing Analysis
Aftermarket service contracts and extended warranty tiers drive lifetime value capture more than initial equipment sales. Three-tier pricing structure across offshore-certified premium, onshore standard, and retrofit economy levels reflects IEC 61400-4 certification grade and geographic delivery cost differentials. Cost compression in economy-tier hydraulic spares is intensifying because EU F-Gas Regulation fluid phase-downs strand legacy inventory. Chinese domestic OEMs exhibit highest price sensitivity, while North Sea operators accept premium positioning for predictive maintenance access.
Supply Chain Analysis
Port congestion at Hamburg and Rotterdam elevates inbound logistics costs for European electromechanical actuator assembly, while container availability constraints on Asia-Europe trade lanes disrupt just-in-time delivery schedules. Manufacturing concentration rests on China for rare earth processing and servo motor winding, Germany for precision gearbox production, and Denmark for blade integration engineering. Neodymium magnet supply, high-pressure hydraulic seal compounds, and fiber optic strain sensors anchor raw material dependencies. Single-source vulnerability in Inner Mongolia rare earth refining poses structural risk. Distribution runs through turbine OEM captive supply networks and independent service provider procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified technicians capable of diagnosing both high-voltage servo faults and high-pressure hydraulic failures remain scarce across mixed-technology turbine fleets, constraining maintenance capacity expansion and inflating service contract premiums.
For Market Incumbents: Shield installed base relationships through backward integration into predictive maintenance software and firmware update services. Electromechanical-hydraulic system integration complexity threatens OEM service contract renewal rates. Prioritize certification investment for IECRE component-level type approval to compress product launch timelines against emerging competitors. For New Entrants and Emerging Players: Differentiate on fiber optic blade load monitoring integration and cold-climate synthetic ester fluid validation capabilities. Germany's aging onshore fleet retrofit aftermarket offers the most penetrable entry point. Pursue white-label electromechanical actuator supply partnerships with Chinese domestic OEMs seeking GB standards compliance pathways. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-transition play because EU F-Gas Regulation mandates and IEC 61400 standard evolution guarantee replacement cycle acceleration regardless of new installation velocity. Acquisition target archetype: standalone sensor-based blade monitoring specialists with SCADA analytics integration. Watch for inflection when cold-climate operators complete synthetic ester fluid validation and trigger bulk hydraulic system replacement orders.| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Actuator Capacity Expansion | Moog and Bosch Rexroth are scaling sealed servo-motor production for North Sea offshore exclusivity requirements. |
| Predictive Maintenance Platform Integration | Digital twin convergence with SCADA analytics enables blade bearing failure detection before crack propagation. |
| Backward Integration into Rare Earth Magnet Supply | Permanent magnet servo motor manufacturers seek upstream control over neodymium processing to reduce Inner Mongolia exposure. |
| Synthetic Ester Fluid Validation Partnership | Cold-climate operators in Scotland and Norway collaborate with seal manufacturers on EU F-Gas Regulation compliance. |
| GB Standards Certification Pathway Investment | Foreign pitch system vendors establish localized production in Jiangsu and Guangdong to meet NMPA-equivalent domestic content thresholds. |
Study Parameters
Desk research of IEC 61400 certification databases, EU F-Gas Regulation implementation filings, and Chinese GB standards documentation preceded structured interviews with wind farm operations directors, pitch system maintenance technicians, turbine OEM procurement managers, and independent service provider executives. Primary fieldwork combined with secondary validation from customs trade records, SEC filings of listed turbine manufacturers, and IEA wind deployment statistics. Bottom-up unit economics modeling and top-down market sizing triangulation anchored volume estimates.
Variance decomposition across actuation technology type, installation environment classification, and end-user procurement authority shaped the analytical framework. Segmentation dimensions modeled include product architecture, generator technology, buyer type, and site classification across the projection horizon. CAGRs derived from installed base replacement cycle analysis and new build capacity absorption curves. Forecast inputs incorporated grid code compliance upgrade timelines and rare earth magnet price volatility indices.
Material uncertainties — regulatory timeline acceleration for hydraulic fluid phase-downs, geopolitical disruption to rare earth supply chains, and offshore installation weather delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification pathway durations and domestic content threshold enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Multi-Rotor Wind Turbine Market
Wind Energy Systems
Spain Wind Energy Market
Wind Energy Systems
China Wind Turbine Rotor Blade Market
Wind Energy Systems
Peru Wind Energy Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Ecuador Wind Energy Market
Wind Energy Systems
Wind Turbine Gearbox and Direct Drive Systems Market
Wind Energy Systems
Wind Turbine Cables Market
Wind Energy Systems
Global Wind Automation Market
Wind Energy Systems
Steel Wind Tower Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Control System Market
Wind Energy Systems
Wind Cones Market
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Ireland Wind Energy Market
Wind Energy Systems
Wind Energy Equipment Market
Wind Energy Systems
Global Marine Wind Turbine Market