
 Europe Silicon Carbide Market | 2026-2036
Europe Silicon Carbide Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Silicon Carbide Market Foresight
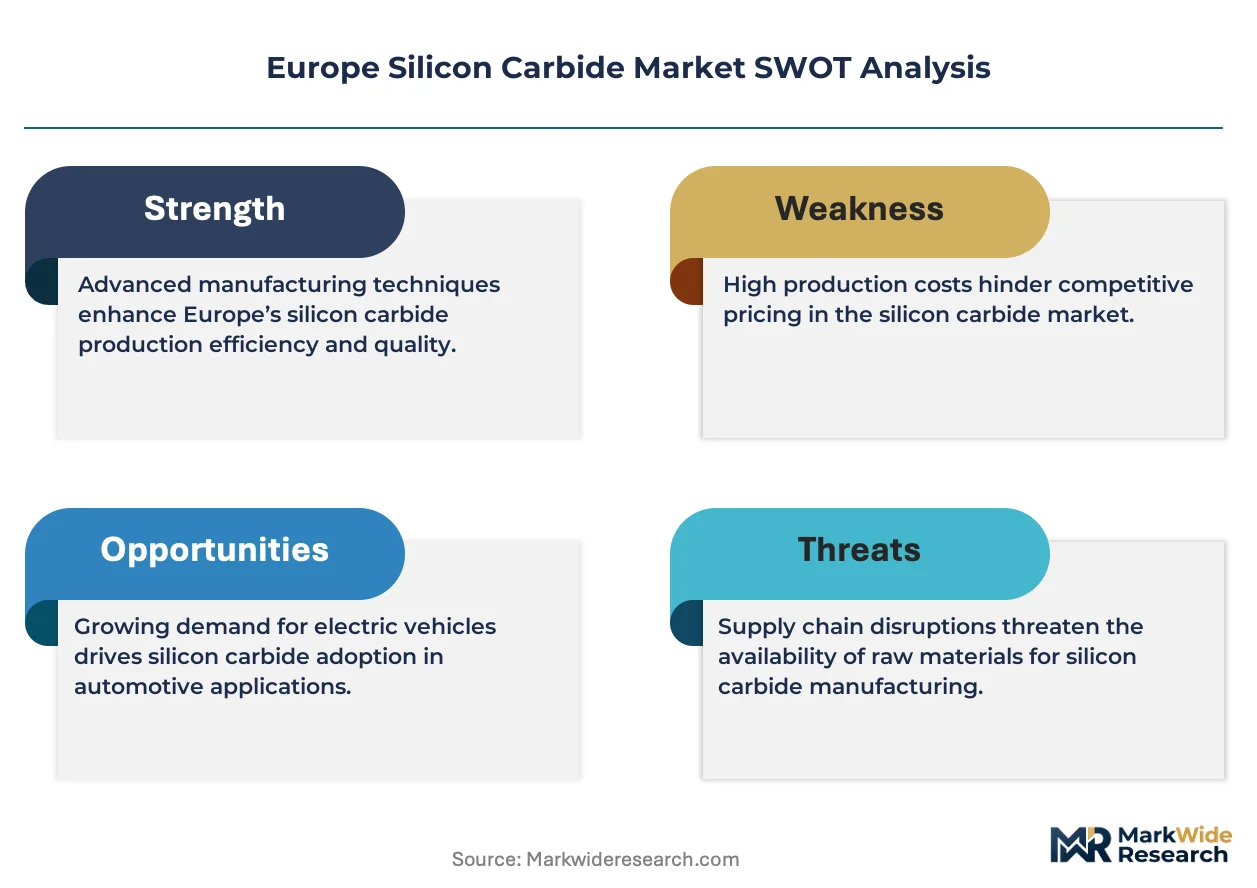
Aftermarket service revenue for SiC module diagnostics and refurbishment is reshaping margin pools across the European supply chain. Infineon Technologies AG leverages its Dresden fab capacity to dominate automotive-grade SiC substrate production. STMicroelectronics anchors its Catania-originated technology leadership through integrated SiC wafer and device manufacturing. Saint-Gobain specializes in high-purity SiC powder supply, sustaining critical upstream material access for European device fabricators.
Silicon carbide is a wide-bandgap semiconductor composed of silicon and carbon atoms arranged in a crystalline lattice, with a bandgap of approximately 3.26 eV that enables operation at temperatures exceeding 200°C and switching frequencies above 100 kHz. Its primary industrial purpose centers on power conversion efficiency in high-voltage applications where silicon devices incur prohibitive switching losses. SiC power devices command the dominant share of current revenue, reflecting automotive inverter demand, while SiC epitaxial layers represent the fastest-growing segment as device makers internalize epi-wafer capabilities to capture margin. Power electronics applications lead volume consumption, though electric vehicle components are accelerating most rapidly as OEMs redesign platforms around 800-volt architectures.
The EU Green Deal, REACH chemical compliance, and F-Gas Regulation collectively mandate higher energy efficiency standards that directly favor SiC adoption in power conversion equipment. EMA and national regulators across Germany, France, and Italy are incorporating wide-bandgap semiconductor requirements into industrial motor efficiency frameworks. Stakeholders must monitor how the EU AI Act and emerging CSRD disclosure rules alter capital allocation transparency for SiC supply chain investments.
Market Dynamics
The transition to 800-volt electric vehicle architectures is compressing design cycles across European automotive supply chains. This voltage platform shift demands SiC power devices capable of higher switching frequencies and thermal tolerance than silicon IGBTs can deliver, forcing simultaneous retooling of inverter manufacturing and charging infrastructure procurement.
Growth Catalysts
- EU Green Deal efficiency mandates:The framework's industrial motor efficiency requirements explicitly favor wide-bandgap semiconductors in power conversion equipment above 75 kW rated output.
- Traction inverter redesign:Germany's automotive corridor is converting production lines from 400-volt to 800-volt systems, each requiring complete SiC module substitution.
- F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases eliminate cooling-dependent silicon solutions in high-temperature industrial environments.
Market Restraints
- Substrate supply concentration:High-purity SiC boule production clusters among a limited set of crystal growth specialists, creating single-source vulnerability for European device fabricators.
- Epitaxial wafer cost structure:Defect-free 150mm SiC epi-layers require precursor gas inputs whose pricing fluctuates with semiconductor-grade silane availability.
- Silicon super-junction persistence:Mature MOSFET technology retains cost advantage below 600-volt applications, delaying SiC penetration in auxiliary automotive loads.
Strategic Opportunities
- CSRD disclosure acceleration:Corporate sustainability reporting requirements create procurement preference for SiC-based efficiency improvements that reduce Scope 2 emissions in industrial facilities.
- Rail traction electrification:France and Italy are modernizing regional locomotive fleets, opening demand for 3.3 kV SiC modules in auxiliary power units and main inverters.
- Grid-scale storage integration:Battery energy storage system developers in the Netherlands and Denmark are specifying SiC-based DC-DC converters for improved round-trip efficiency.
Industry Challenges
- Power electronics talent scarcity:European universities produce insufficient graduates with combined wide-bandgap device physics and thermal packaging expertise to match hiring demand from automotive Tier-1 suppliers.
- AEC-Q101 qualification timelines:Automotive-grade SiC module certification requires 12-18 months of accelerated life testing, delaying revenue recognition for new product introductions.
- Legacy inverter integration friction:Retrofitting SiC devices into existing silicon-optimized gate driver architectures demands complete control loop redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Silicon Carbide Market |
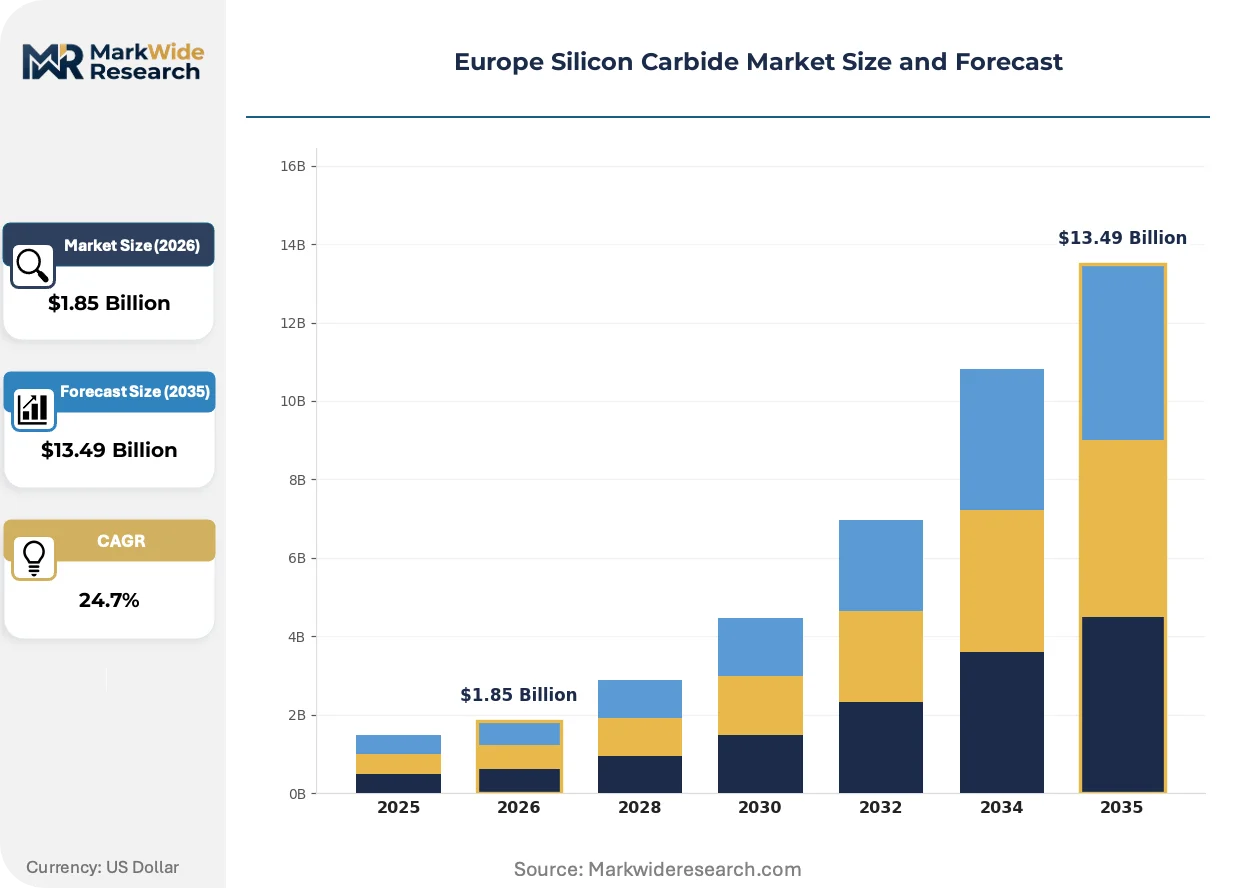
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $13.49 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SiC Wafer, SiC Substrate, SiC Power Device, SiC Epitaxial Layer Application: Power Electronics, RF Devices, Electric Vehicle Components, Industrial Motor Drives End User: Automotive, Telecommunications, Aerospace, Consumer Electronics Technology: Modular Inverters, High-Voltage Applications, Photovoltaic Inverters, High-Frequency Applications |
| Companies Covered | Infineon Technologies AG, STMicroelectronics, Saint-Gobain, Fiven ASA, Grindwell Norton, CoorsTek, Entegris, Esd-Sic bv, Washington Mills, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Silicon Carbide Market Shifts & Advancements
Wafer-scale manufacturing advances are collapsing cost differentials between silicon carbide and legacy semiconductor technologies. Three interconnected developments are reshaping how European device fabricators compete.
Gate-oxide interface engineering is collapsing reliability barriers that previously limited SiC MOSFET deployment to premium automotive segments. Bosch and Continental are qualifying second-generation trench designs for mass-market EV platforms, compressing the price-performance gap against silicon super-junction devices. This process innovation enables 175°C continuous operation without derating, eliminating liquid cooling in mid-range passenger vehicle inverters.
REACH chemical compliance revisions are tightening traceability requirements for conflict minerals in semiconductor supply chains. The 2024 update to Annex XVII restricts tantalum and tungsten sourcing from unverified smelters, forcing SiC substrate manufacturers to requalify crucible suppliers. German device fabricators are responding by integrating blockchain-based material provenance tracking from powder sourcing through epitaxial growth.
Automotive OEMs are consolidating inverter procurement around vertically integrated module suppliers capable of simultaneous SiC chip and packaging design. Volkswagen's platform consolidation strategy eliminates discrete component purchasing in favor of complete powertrain subsystem sourcing, concentrating negotiation leverage among three approved European suppliers. This buyer concentration is most visible in Germany's Baden-Württemberg manufacturing corridor, where Tier-1 engineering resources are co-locating with OEM technical centers.
Europe Silicon Carbide Market Segmentation
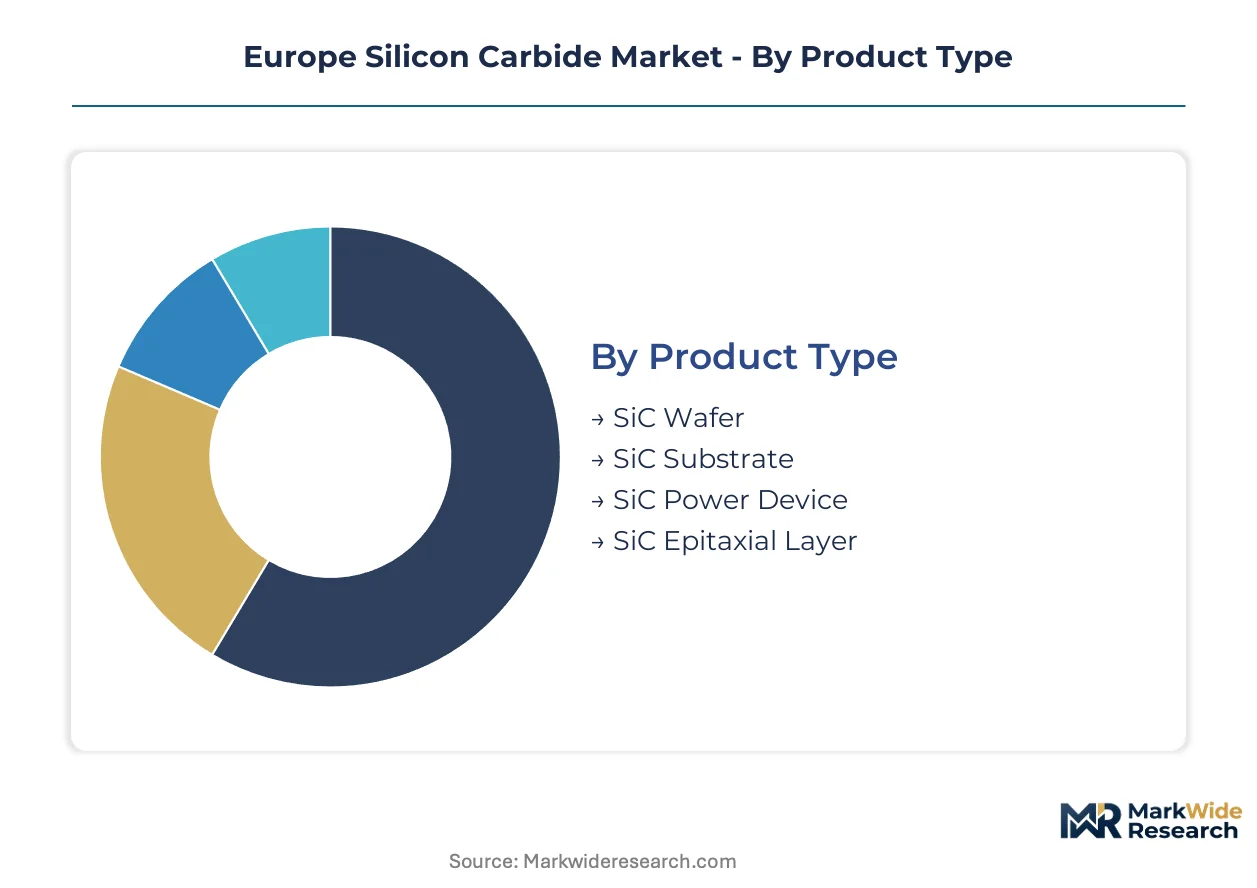
Segmentation of the Europe Silicon Carbide Market reveals distinct value capture zones across the supply chain. Product type stratification separates upstream material suppliers from downstream device integrators, while application segmentation exposes how automotive electrification concentrates demand within specific voltage and frequency domains.
Product Type:
Mature wafer and substrate segments anchor baseline supply capacity, while emerging epitaxial layer capabilities are reshaping margin distribution across European fabricators.
- SiC Power Device:These MOSFETs and Schottky diodes convert electrical energy in high-voltage systems with switching losses below 10% of comparable silicon IGBTs. German automotive OEMs specify these devices for 800-volt traction inverters, where the EU Green Deal's efficiency mandates eliminate silicon alternatives above 75 kW output.
- SiC Epitaxial Layer:Thin crystalline films grown atop substrates determine device electrical performance and yield. French and Italian device makers are internalizing epi-wafer production to reduce dependency on external foundries, capturing margin that previously flowed to Asian suppliers.
- SiC Wafer:Sliced boules form the foundational material for all downstream processing.
- SiC Substrate:Polished wafers ready for epitaxial deposition or direct device fabrication.
SiC Power Device retains volume leadership; SiC Epitaxial Layer holds the steepest expansion curve.
Application:
Cost tier stratification separates premium automotive applications from commoditized industrial motor drives, with RF devices occupying a specialized mid-tier position.
- Electric Vehicle Components:Traction inverters, onboard chargers, and DC-DC converters leverage SiC's thermal tolerance to eliminate liquid cooling systems. BMW and Volkswagen platform redesigns around 800-volt architectures are accelerating procurement volumes through Germany's Baden-Württemberg manufacturing corridor.
- Power Electronics:Industrial converters and uninterruptible power supplies exploit wide-bandgap efficiency gains to meet EMA motor efficiency frameworks. Dutch grid-scale battery developers specify these systems for improved round-trip efficiency in energy storage integration.
- RF Devices:Base station amplifiers and radar systems exploit high electron mobility in SiC substrates.
- Industrial Motor Drives:Variable frequency drives for pumps and compressors benefit from reduced switching losses.
Power Electronics commands installed base dominance; Electric Vehicle Components gains share fastest.
End User:
Customer type concentration varies sharply, with automotive procurement consolidating around vertically integrated module suppliers while aerospace maintains fragmented qualification pathways.
- Automotive:OEM platform consolidation strategies eliminate discrete component purchasing in favor of complete powertrain subsystem sourcing. Bosch and Continental qualify second-generation trench MOSFET designs for mass-market EV platforms, compressing price-performance gaps against silicon alternatives.
- Aerospace:Satellite power systems and aircraft actuation demand radiation-hardened devices with extended qualification timelines.
- Telecommunications:5G base station deployments drive demand for high-frequency RF power amplifiers.
- Consumer Electronics:Premium laptop chargers and adapter applications exploit compact thermal profiles.
Automotive retains volume leadership; Aerospace holds the steepest expansion curve.
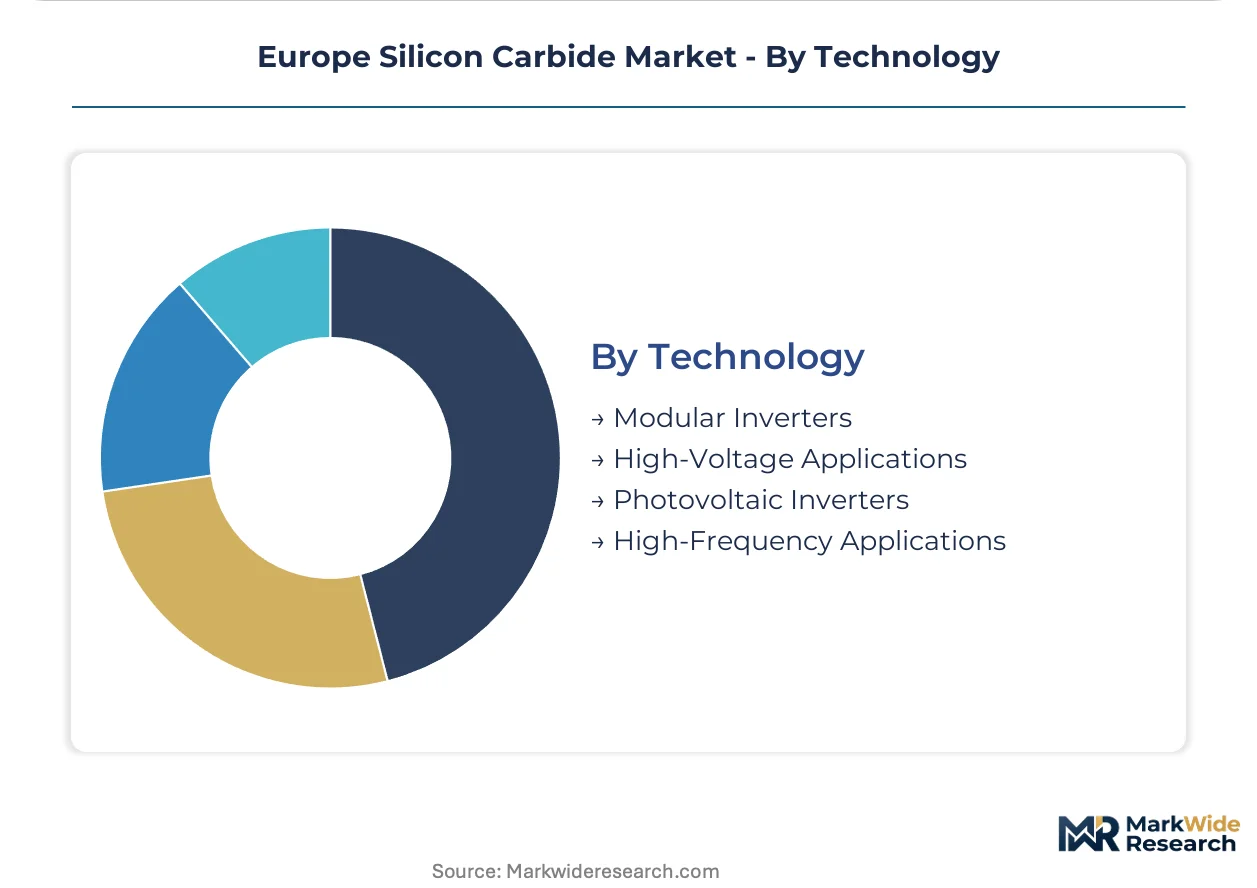
Technology:
Volume distribution skews toward modular architectures that package multiple SiC dies with integrated gate drivers and thermal management, while high-voltage applications remain specialized.
- Modular Inverters:Integrated power modules combine SiC chips with ceramic substrates and advanced bonding techniques in standardized footprints. Tier-1 suppliers co-locate engineering resources with OEM technical centers to compress design cycles for platform-specific variants.
- High-Voltage Applications:3.3 kV and 6.5 kV devices serve rail traction and grid infrastructure where silicon IGBTs face thermal limitations. France and Italy are modernizing regional locomotive fleets, opening demand for these modules in auxiliary power units.
- Photovoltaic Inverters:String and central inverters for solar installations exploit high switching frequencies to reduce magnetics size.
- High-Frequency Applications:Resonant converters and wireless power transfer systems leverage SiC's low switching losses.
Modular Inverters commands volume dominance; High-Voltage Applications gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Southern Europe exhibit the highest price elasticity, squeezing margins on standard-grade substrates, while German automotive OEMs absorb premium pricing for AEC-Q101 qualified devices without volume reduction.
Germany
BMW, Volkswagen, and Bosch anchor procurement of SiC power devices for 800-volt traction inverters. The KBA incorporates wide-bandgap semiconductor requirements into type-approval frameworks for electric powertrains. Baden-Württemberg's manufacturing corridor concentrates Tier-1 engineering resources co-located with OEM technical centers.
France
Rail traction electrification drives demand for 3.3 kV SiC modules in auxiliary power units and main inverters. ANSM enforces REACH chemical compliance revisions that restrict conflict mineral sourcing from unverified smelters. Île-de-France hosts Saint-Gobain's high-purity SiC powder operations sustaining upstream material access.
Italy
STMicroelectronics anchors integrated SiC wafer and device manufacturing from its Catania-originated technology base. The EMA's industrial motor efficiency frameworks explicitly favor wide-bandgap semiconductors above 75 kW rated output. Emilia-Romagna's automotive suppliers are converting production lines to accommodate SiC module substitution.
Netherlands
Grid-scale battery energy storage developers specify SiC-based DC-DC converters for improved round-trip efficiency. CSRD disclosure rules create procurement preference for efficiency improvements that reduce Scope 2 emissions in industrial facilities. Eindhoven's semiconductor equipment cluster supports epitaxial wafer production tooling.
United Kingdom
Aerospace satellite power systems demand radiation-hardened devices with extended qualification timelines. The UK's national semiconductor strategy allocates funding for wide-bandgap material research facilities. South East England's research corridors host university partnerships targeting wide-bandgap device physics expertise development.
Europe Silicon Carbide Market Competitive Landscape
Capability concentration sits with substrate and epitaxial specialists; scale advantage sits with integrated device fabricators with captive wafer supply. European device makers cluster around automotive qualification pathways, while material suppliers compete on powder purity and crystal defect density. Two archetypes dominate: vertically integrated semiconductor conglomerates controlling substrate-through-module production, and specialized ceramic material houses supplying high-purity feedstock. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with foundry alliances and long-term supply agreements displacing spot market procurement.
Among Germany-based semiconductor conglomerates, Infineon Technologies AG occupies a position exemplifying captive substrate production through Dresden fab capacity. STMicroelectronics represents the integrated European device fabricator archetype with Catania-originated technology leadership spanning wafer and device manufacturing. Saint-Gobain anchors the specialized material supplier tier, sustaining critical upstream powder access for European device fabricators.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| STMicroelectronics |
| Saint-Gobain |
| Fiven ASA |
| Grindwell Norton |
| CoorsTek |
| Entegris |
| Esd-Sic bv |
| Washington Mills |
| Others |
Supply & Pricing Matrix
Rhine-Alpine Corridor freight rates dictate landed cost differentials for SiC substrates entering European fabrication facilities, compressing margins for distributors while amplifying pricing power among German device makers with captive wafer supply. This logistics cost dynamic reinforces a bifurcated market where automotive OEMs absorb premium pricing for AEC-Q101 qualified modules and Southern European industrial buyers squeeze standard-grade substrate margins.
Pricing Analysis
Aftermarket service revenue from SiC module diagnostics and refurbishment drives lifetime value capture across the European supply chain. Three-tier pricing structure across premium, standard, and economy levels separates automotive-grade qualified devices from industrial-grade alternatives and commodity powder feedstock. Pricing pressure stems from epitaxial wafer cost volatility tied to semiconductor-grade silane availability. Automotive OEMs in Germany's Baden-Württemberg corridor exhibit lowest price sensitivity, while Southern European industrial motor drive purchasers demand aggressive standard-grade discounts.
Supply Chain Analysis
High-purity SiC powder feedstock draws from Saint-Gobain's French operations and selected Asian metallurgical-grade suppliers, creating raw material dependencies for European substrate growers. SiC boule production rests on precision thermal processing equipment and graphite crucible supply chains concentrated in Germany, Japan, and the USA. Single-source vulnerability for 150mm substrate supply creates structural risk for device fabricators without captive crystal growth. Distribution runs through Tier-1 module suppliers co-located with OEM technical centers, displacing spot market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's silicon carbide market sits in early-cycle expansion as 800-volt EV platform redesigns force complete SiC substitution in traction inverters ahead of silicon super-junction cost parity.
For Market Incumbents: Insulate substrate supply positions through long-term powder offtake agreements with Saint-Gobain and internalization of epitaxial wafer production to capture margin flowing to Asian foundries. Add 150mm boule growth capacity in Dresden or Catania to reduce single-source exposure. Accelerate AEC-Q101 qualification pipelines to defend against emerging silicon carbide entrants from power semiconductor conglomerates.
For New Entrants and Emerging Players: Pursue white-space opportunities in rail traction auxiliary power units across France and Italy, where 3.3 kV module demand outpaces qualified European supply. Target grid-scale battery energy storage DC-DC converter specifications in the Netherlands and Denmark, segments with lower automotive qualification barriers. Lead with efficiency benchmarking against silicon IGBT baselines to bypass entrenched supplier relationships.
For Investors and Strategic Acquirers: Specialized epitaxial wafer foundries with established 150mm defect-free production represent the most attractive acquisition archetype for portfolio exposure to SiC margin capture. Frame long-term viability around 5-10 year automotive platform electrification commitments from BMW, Volkswagen, and Stellantis. Monitor CSRD disclosure acceleration as the inflection signal for industrial procurement preference shifts toward SiC-based efficiency investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Production | Captures margin from external foundries while securing supply for automotive qualification pipelines. |
| Epitaxial Wafer Capacity Expansion | Addresses defect-free 150mm supply constraints that bottleneck German automotive inverter production. |
| Rail Traction Module Qualification | Opens French and Italian locomotive modernization demand outside saturated automotive procurement channels. |
| Long-term Powder Supply Agreement | Locks in Saint-Gobain high-purity SiC feedstock access against REACH conflict mineral traceability tightening. |
| Gate-Oxide Interface R&D Partnership | Accelerates second-generation trench MOSFET reliability for 175°C continuous operation without liquid cooling. |
Research Methodology
The analysis maps SiC power devices, epitaxial layers, wafers, and substrates, each validated through procurement directors at automotive Tier-1 suppliers, platform engineers at German OEMs, and aftermarket service managers. Primary interviews with crystal growth specialists, powder metallurgists, and rail traction electrification planners combined with secondary validation from KBA type-approval frameworks, EMA motor efficiency directives, and SEC filings from listed semiconductor conglomerates. Bottom-up and top-down triangulation cross-checked regional production capacity against automotive platform electrification timelines.
Assumptions held fixed include EU Green Deal efficiency mandate enforcement and F-Gas Regulation phase-down schedules, while variables included 800-volt platform adoption rates and silicon super-junction cost compression trajectories. Segmentation dimensions spanned product type, application voltage tier, end-user industry concentration, and regional regulatory cluster. CAGRs derived from installed base replacement modeling and content-per-vehicle expansion across the projection horizon. Forecast inputs incorporated REACH chemical compliance revision timing and CSRD disclosure rule implementation.
Sensitivities concentrate around substrate supply disruption, automotive platform redesign delays, and silicon carbide-silicon cost parity acceleration. Forecasts reflect assumptions about crystal growth yield improvements and epitaxial defect density reductions. Material shifts in EU industrial motor efficiency enforcement or fluorinated gas regulatory tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
Global Scintillator Market
Semiconductor Material
Polymethylhydrosiloxane Market
Semiconductor Material
Fullerene Market
Semiconductor Material
Zinc Oxide Nanoparticles Market
Semiconductor Material
Synthetic Sapphire Market
Semiconductor Material
Silicon Tetrachloride Market
Semiconductor Material
Big Size Synthetic Diamond Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Semiconductor Materials Market
Semiconductor Material
Gallium Trichloride Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Europe Silicone Market