
 Global Dicamba Herbicide Market | 2026-2036
Global Dicamba Herbicide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dicamba Herbicide Market Foresight
ISO 17025 accreditation for analytical testing is redrawing competitive barriers in dicamba formulation quality assurance. Bayer Crop Science leverages its integrated seed-trait-chemistry platform to dominate dicamba-tolerant soybean systems. BASF sustains R&D intensity in low-volatility salt formulations that reduce off-target movement liability. Albaugh specializes in generic dicamba manufacturing, competing on price in agricultural retailer channels.
Dicamba is a synthetic auxin herbicide belonging to the benzoic acid chemical family, typically formulated as dimethylamine salt or diglycolamine salt with vapor pressures below 1 x 10⁻⁷ mm Hg in low-volatility variants, designed for post-emergence broadleaf weed control in tolerant crops. Concentrated liquid formulations capture the dominant volume share due to farmer familiarity with tank-mix flexibility and custom application rates. Emulsifiable concentrate growth reflects demand in specialty plantations where equipment compatibility varies. Crop farmers represent the deepest end-user pool, though agricultural cooperatives are consolidating procurement to negotiate volume-based distributor pricing.
EPA label requirements mandate downwind buffers and application cutoff dates, directly constraining dicamba sales windows in US soybean and cotton regions. EFSA evaluations under EU pesticide renewal procedures influence formulation standards adopted by exporters serving European grain import specifications. Brazil's national agricultural regulator, MAPA, governs dicamba registration timelines that determine when multinationals can launch tolerant seed-chemistry bundles. Stakeholders must monitor drift litigation precedents and state-level cutoff rule variations that could abruptly reshape product liability exposure and geographic market access.
Market Dynamics
Low-volatility salt formulation technology is compressing application windows while EPA buffer mandates and state-level cutoff rules are fragmenting product registration pathways across soybean and cotton growing regions.
Growth Catalysts
- Dicamba-tolerant seed-chemistry bundles:Integrated trait platforms in Brazil's soybean belt are pulling herbicide demand through bundled procurement contracts with agricultural cooperatives.
- EPA 24(c) special local need registrations:State-level flexibility for drift mitigation technologies is opening supplemental sales windows in the US cotton belt beyond federal label restrictions.
- Resistant weed pressure:Palmer amaranth and waterhemp infestations across the US Midwest are forcing crop farmers toward auxin-based rotation chemistry.
Market Restraints
- Active ingredient supply concentration:Generic manufacturing clusters in China and India create input vulnerability for formulators dependent on imported dicamba acid.
- Off-target movement liability:Vapor drift incidents trigger crop damage claims that compress insurance availability and elevate legal exposure for applicators.
- Glyphosate-glufosinate substitution:Competing herbicide-tolerant seed systems in corn and soy displace dicamba acreage where resistance management protocols favor non-auxin modes of action.
Strategic Opportunities
- Argentina soybean expansion:Underpenetrated acreage in the Pampas region offers first-mover positioning for tolerant trait-chemistry bundles ahead of full regulatory clearance.
- Drone-based precision application:UAV spray systems with real-time wind monitoring are enabling buffer reduction waivers and expanding treatable acreage per day.
- EU grain import compliance services:Exporters to European markets require residue testing and MRL certification that creates adjacent revenue streams for accredited analytical laboratories.
Industry Challenges
- Applicator certification bottlenecks:State-mandated dicamba-specific training requirements create workforce scarcity during compressed spring application windows.
- Legacy tank-mix incompatibility:Low-volatility formulations require equipment calibration and cleanout protocols that slow adoption among custom applicators with diversified chemistry portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dicamba Herbicide Market |
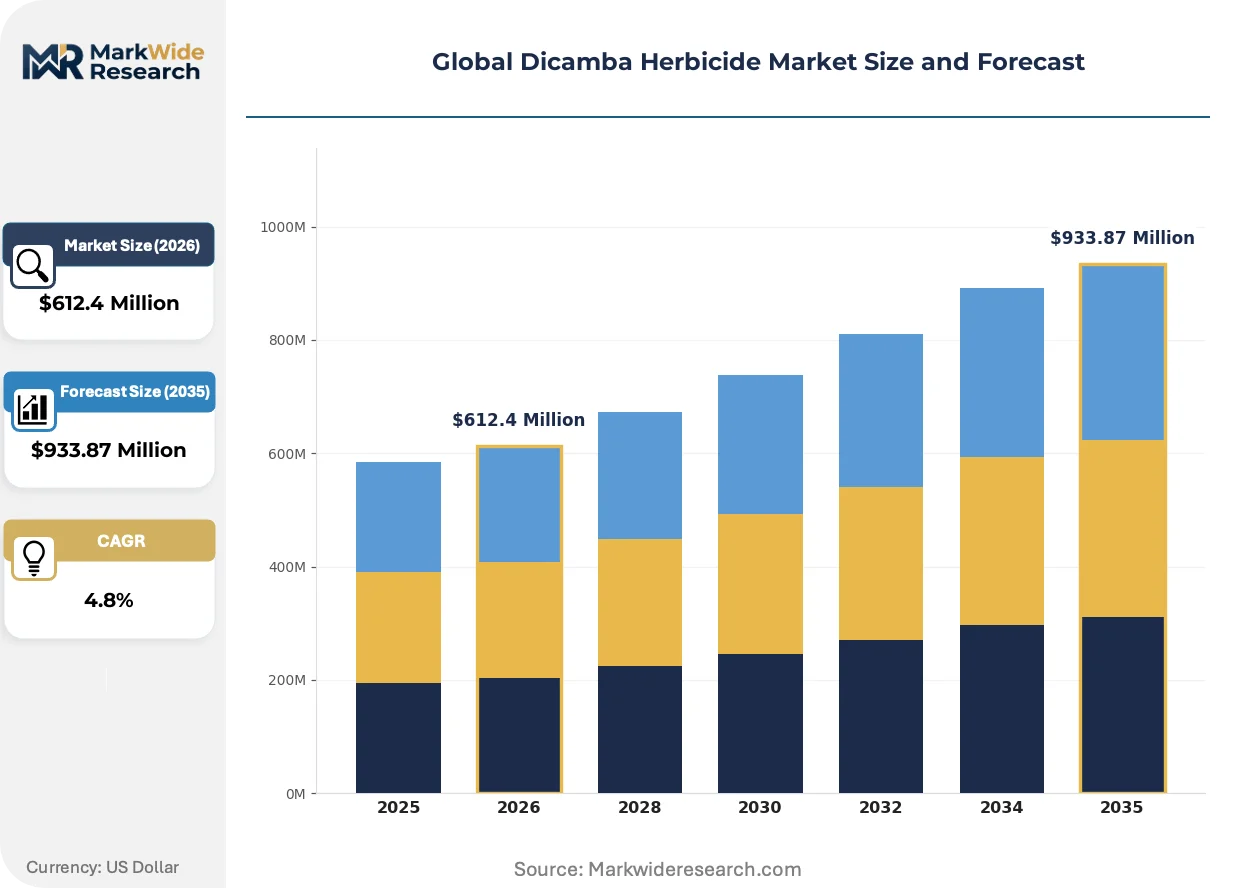
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $933.87 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Concentrated Liquid, Ready-to-Use Liquid, Emulsifiable Concentrate Application: Corn, Soybean, Cotton, Wheat, Turf Management End User: Crop Farmers, Specialty Plantations, Agricultural Cooperatives, Government Agencies Distribution Channel: Direct Sales, Agricultural Retailers, Online Platforms, Wholesale Distributors |
| Companies Covered | Bayer Crop Science, Syngenta, BASF, Corteva Agriscience, FMC Corporation, Nufarm, UPL, ADAMA, Albaugh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dicamba Herbicide Market Shifts & Advancements
Formulation chemistry and application hardware are converging to address volatility concerns while regulatory fragmentation forces geographic customization of product development pipelines.
Low-volatility diglycolamine salt formulations are replacing dimethylamine variants in post-emergence soybean applications. Custom applicators in the US Midwest are retrofitting sprayers with hooded booms and wind sensors to meet label requirements. This hardware-software integration is miniaturizing the effective treatment zone and compressing per-acre labor inputs.
EPA's 2020 registration amendments mandating downwind buffers and cutoff dates have triggered state-level 24(c) petition activity. Formulators now maintain parallel label versions to accommodate Illinois, Indiana, and Arkansas cutoff rule variations. The compliance burden falls heaviest on regional distributors managing inventory across divergent regulatory territories.
Agricultural cooperatives are consolidating procurement into volume-based tender contracts that bypass traditional retail channels. Multi-state buying groups in the US corn-soy belt now negotiate directly with manufacturers for season-long supply commitments. This disintermediation is most visible in Iowa and Minnesota where cooperative market share in crop protection inputs exceeds forty percent.
Global Dicamba Herbicide Market Segmentation
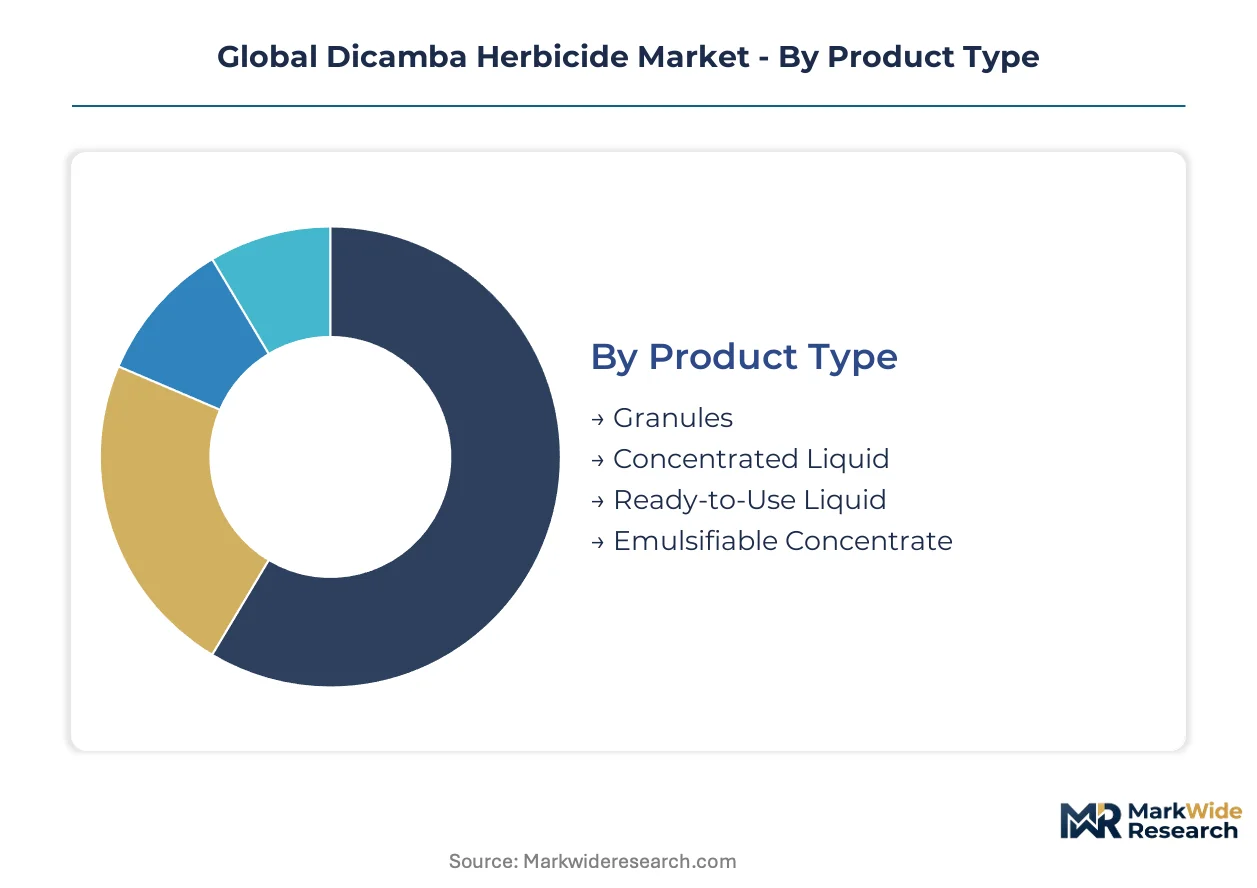
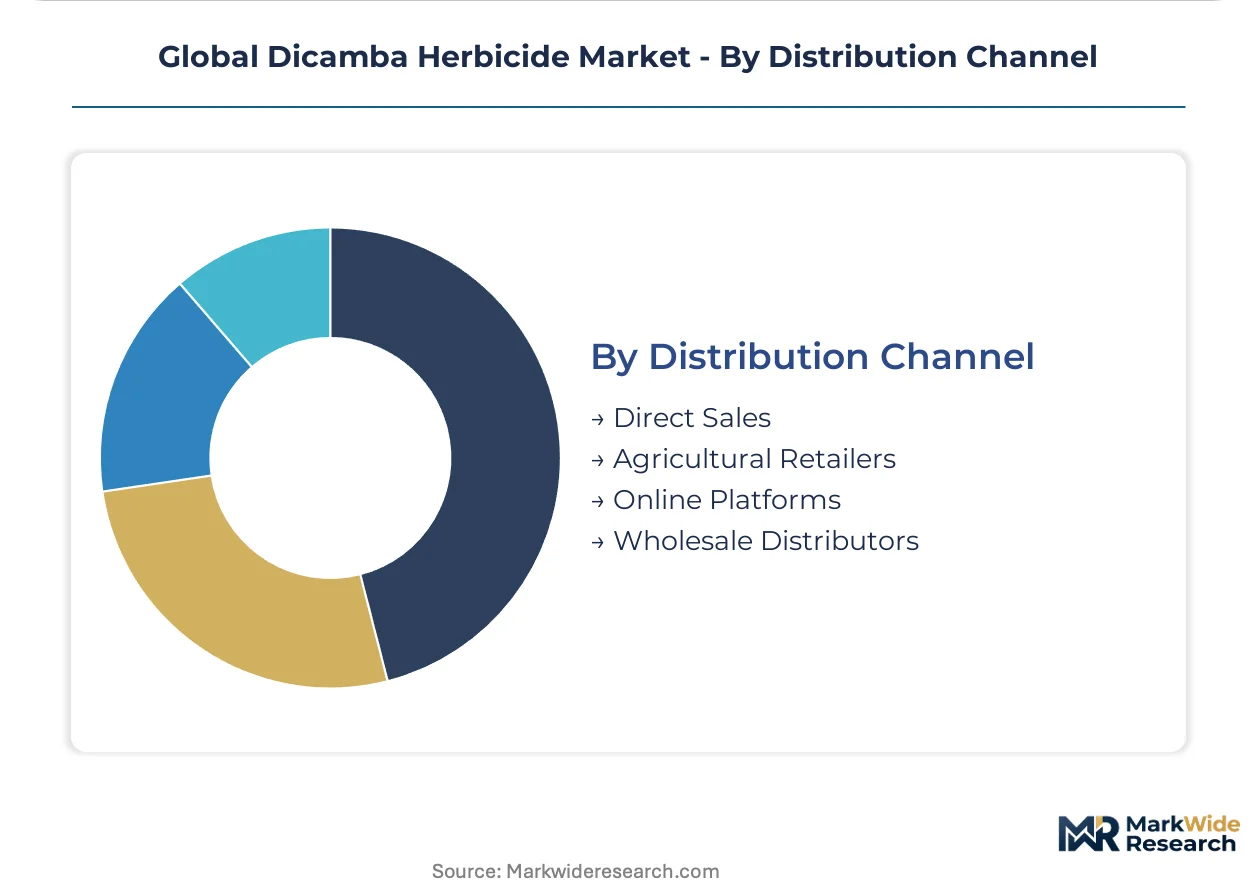
Dicamba herbicide segmentation reflects divergent regulatory tolerances across crop systems and the operational constraints of drift-sensitive application windows. Product form and distribution channel choices directly determine compliance feasibility in jurisdictions with divergent buffer mandates.
Product Type:
EPA volatility restrictions and state-level formulation registrations create tiered market access where salt chemistry and physical form dictate geographic eligibility.
- Concentrated Liquid:Dimethylamine and diglycolamine salt formulations dominate post-emergence applications in dicamba-tolerant soybean systems. Demand concentrates in the US corn-soy belt where farmers prioritize tank-mix flexibility for resistant weed programs; EPA cutoff date variations across Illinois, Indiana, and Arkansas compress effective sales windows for standard formulations.
- Emulsifiable Concentrate:Oil-in-water systems with enhanced spreading and sticking properties serve specialty plantations in Brazil's Cerrado where equipment compatibility varies across contractor fleets. Adoption climbs fastest in Mato Grosso and Goiás where cooperative procurement consolidates around bundled trait-chemistry packages.
- Granules:Controlled-release matrix formulations reduce volatility exposure in buffer-adjacent acreage.
- Ready-to-Use Liquid:Pre-diluted formats eliminate field mixing errors for smallholder compliance in fragmented landholdings.
Established volume favors Concentrated Liquid; emerging adoption favors Emulsifiable Concentrate.
Application:
Trait-chemistry bundle penetration varies sharply by crop, with seed system availability and resistance pressure determining chemistry rotation economics.
- Soybean:Dicamba-tolerant trait platforms in Brazil and the US drive the deepest herbicide pull-through, with MAPA registration timelines in Brazil and EPA 24(c) state petitions in the US creating parallel market development pathways. Resistant Palmer amaranth pressure across the Midwest forces auxin rotation where glyphosate efficacy has collapsed.
- Cotton:Post-emergence applications in the US cotton belt depend on drift mitigation technology adoption for buffer waiver eligibility; Arkansas and Tennessee cutoff rules fragment treatable acreage timing.
- Corn:Atrazine-glyphosate-dicamba stacked programs compete with glufosinate-tolerant alternatives in resistance management protocols.
- Wheat:Fall and spring broadleaf control in hard red winter wheat regions faces rotational crop restrictions that limit post-harvest application flexibility.
- Turf Management:Professional lawn care and golf course maintenance in the US Southeast and Midwest operates under municipal ordinances that ban or restrict phenoxy herbicide use near sensitive populations.
Soybean and Cotton command premium formulation investment; Wheat and Turf Management operate at margin compression due to regulatory and substitute chemistry pressure.
End User:
Procurement consolidation and certification requirements are restructuring channel economics across farmer types and institutional buyers.
- Crop Farmers:Individual operators in Iowa and Minnesota face compressed spring application windows and state-mandated dicamba-specific training bottlenecks that constrain workforce availability.
- Agricultural Cooperatives:Multi-state buying groups in the US corn-soy belt now negotiate direct manufacturer contracts exceeding forty percent input share in key counties; volume tenders disintermediate traditional retail margins.
- Specialty Plantations:Sugarcane and citrus operations in Brazil's São Paulo state require customized application protocols for tree crop sensitivity.
- Government Agencies:Highway right-of-way and invasive species programs in the US face budget volatility and public comment periods that delay seasonal procurement.
Cooperative consolidation favors volume-based supply commitments; specialty plantation fragmentation sustains distributor service premiums.
Distribution Channel:
Regulatory territory fragmentation and inventory risk allocation determine channel profitability across direct and intermediary routes.
- Agricultural Retailers:Regional distributors manage parallel label versions for Illinois, Indiana, and Arkansas cutoff rule variations, with inventory write-down risk concentrated in Q2 application season compression.
- Direct Sales:Manufacturer-to-cooperative contracts in Iowa and Minnesota bypass retail markup through season-long supply commitments with price escalation clauses.
- Wholesale Distributors:National networks aggregate generic dicamba acid from China and India for formulator supply, with import tariff and currency exposure affecting margin stability.
- Online Platforms:E-commerce penetration remains limited by applicator certification requirements and restricted-use pesticide regulations that mandate in-person verification.
Retailer inventory risk favors Direct Sales growth; Wholesale Distributor concentration in generic supply creates input vulnerability for non-integrated formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA buffer mandates and Brazil's MAPA registration timelines are accelerating geographic specialization in dicamba formulation deployment. Farmers in tolerant-seed corridors face divergent state-level cutoff rules that reshape procurement timing. Regulatory fragmentation forces manufacturers to maintain parallel label versions across jurisdictions.
United States
Dicamba-tolerant soybean systems in Iowa and Illinois drive concentrated herbicide pull-through from agricultural cooperatives. EPA 24(c) special local need registrations in Arkansas and Tennessee create supplemental sales windows beyond federal label restrictions. Custom applicators across the Midwest corn-soy belt retrofit sprayers with hooded booms and wind sensors to satisfy drift mitigation requirements.
Brazil
Soybean farmers in Mato Grosso and Goiás expand dicamba adoption through bundled trait-chemistry procurement contracts with agricultural cooperatives. MAPA governs registration timelines that determine when multinationals can launch integrated seed-herbicide platforms. The Cerrado region's specialty plantation contractors favor emulsifiable concentrate formats for equipment compatibility across diversified fleets.
Argentina
Underpenetrated soybean acreage in the Pampas region offers first-mover positioning for tolerant trait-chemistry bundles ahead of full regulatory clearance. The country's national agricultural regulator evaluates residue standards that influence exporter compliance protocols. Farmers in Buenos Aires province face rotational crop restrictions that limit post-harvest application flexibility.
Canada
Health Canada PMRA reviews govern dicamba registration for canola and soybean systems in prairie provinces. Manitoba and Saskatchewan growers confront compressed spring windows similar to US Midwest conditions. Agricultural retailers in the Red River Valley manage inventory risk across provincial boundary variations in buffer mandates.
Australia
TGA-aligned state regulators enforce drift mitigation protocols for summer crop applications in Queensland and New South Wales. Cotton growers in the Darling Downs adopt precision spray systems with real-time wind monitoring to expand treatable acreage per day. Grain exporters to European markets require residue testing and MRL certification that creates demand for accredited analytical services.
Global Dicamba Herbicide Market Competitive Landscape
Player mix skews toward integrated seed-trait-chemistry conglomerates with captive distribution networks. The vendor base concentrates around three strategic tiers: multinational platform owners with bundled procurement contracts, generic formulators competing on price in agricultural retailer channels, and regional distributors managing parallel label versions for regulatory territory fragmentation. Dominant competitive moves include backward integration into low-volatility salt formulation R&D and direct manufacturer-to-cooperative supply contracts that disintermediate traditional retail margins.
Within the integrated platform tier, Bayer Crop Science and BASF occupy positions anchored to dicamba-tolerant seed systems and low-volatility formulation portfolios. Albaugh exemplifies the generic manufacturing archetype, competing on price points through agricultural retailer channels. Corteva Agriscience represents the mid-tier consolidator vector, bridging trait development with regional distribution scale.
| Leading Market Players |
|---|
| Bayer Crop Science |
| Syngenta |
| BASF |
| Corteva Agriscience |
| FMC Corporation |
| Nufarm |
| UPL |
| ADAMA |
| Albaugh |
| Others |
Supply & Pricing Matrix
Diglycolamine salt formulations displacing dimethylamine variants are redrawing procurement geography toward integrated formulators with captive acid supply, compressing margins for non-integrated competitors while elevating price premiums for volatility-certified products.
Pricing Analysis
Certification level creates the primary spread between ISO 17025-accredited analytical-grade formulations and uncertified commodity supply. Three-tier pricing structure across premium low-volatility salts, standard dimethylamine formulations, and economy generic acid concentrates dominates contract negotiations. Cost compression in standard-tier products is intensifying because Brazilian and US cooperative buyers consolidate procurement into volume tenders. Agricultural cooperatives in Iowa and Minnesota exhibit highest price sensitivity; specialty plantation contractors in Brazil's Cerrado accept premium positioning for equipment-compatible emulsifiable concentrates.
Supply Chain Analysis
Just-in-time inventory strategies prevail among US Midwest agricultural retailers managing parallel label versions for Illinois, Indiana, and Arkansas cutoff variations, while Brazilian cooperatives favor strategic stockpiles ahead of MAPA registration windows. Active ingredient manufacturing concentrates in China and India for generic acid supply, with formulation finishing anchored in the US corn-soy belt and Brazil's São Paulo state. Dicamba acid production rests on chlorinated intermediate feedstocks and specialized amine coupling agents. Single-source vulnerability in Chinese acid supply creates exposure for non-integrated formulators. Distribution runs through agricultural retailer networks in fragmented regulatory territories and direct manufacturer-to-cooperative contracts in consolidated procurement zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dicamba herbicide markets sit in early-cycle expansion as Brazil's MAPA registration timelines unlock tolerant seed-chemistry bundle penetration across underpenetrated soybean acreage.
For Market Incumbents: Compound platform advantages by deepening backward integration into low-volatility salt R&D and locking multi-season supply commitments with consolidating cooperatives. Glyphosate-glufosinate substitution in resistance management protocols threatens acreage retention; defend through bundled trait-chemistry pricing that embeds herbicide supply into seed procurement contracts. For New Entrants and Emerging Players: Applicator certification bottlenecks during compressed spring windows represent a service-layer gap where incumbents under-serve. Target drone-based precision application services in the US cotton belt where buffer reduction waivers reward real-time wind monitoring technology. White-space exists in EU grain import compliance services for residue testing and MRL certification. Go-to-market through accredited analytical laboratories serving export-oriented grain handlers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed generic formulators lacking integrated seed-trait platforms. Long-term viability hinges on regulatory continuity in EPA and MAPA jurisdictions alongside drift litigation precedent stability. Monitor acquisition candidates with ISO 17025 accreditation and established 24(c) registration pathways. Revision becomes warranted when state-level cutoff rule fragmentation exceeds three divergent versions or when vapor drift liability verdicts exceed insurance capacity thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Volatility Salt R&D | Captive formulation technology reduces off-target movement liability exposure for applicators. |
| Direct Manufacturer-to-Cooperative Contracts | Volume tenders in Iowa and Minnesota disintermediate traditional agricultural retailer margins. |
| Drone-Based Precision Application Services | UAV systems with wind sensors enable EPA buffer reduction waivers in cotton belt states. |
| EU Grain Import Compliance Certification | Accredited residue testing creates adjacent revenue for laboratories serving export handlers. |
| Parallel Label Version Maintenance | Formulators managing Illinois, Indiana, and Arkansas cutoff variations capture regulatory fragmentation premiums. |
Research Methodology
A spread of perspectives from dicamba formulator R&D directors, agricultural cooperative procurement managers, custom applicator fleet operators, and EPA regulatory affairs specialists converged on the working assumptions driving volume and value estimates. Primary interviews with MAPA registration consultants and Brazilian seed-chemistry bundle strategists supplemented secondary validation through EPA 24(c) registration databases, MAPA regulatory filings, US customs trade data for dicamba acid imports, and SEC 10-K disclosures from integrated platform owners. Bottom-up acreage penetration modeling triangulated against top-down herbicide expenditure flows across the analysis window.
Segmentation dimensions modeled include formulation salt chemistry, physical product form, crop system application, end-user procurement archetype, and distribution channel structure across the projection horizon. CAGRs derived from regression against resistant weed pressure indices, trait platform adoption curves, and regulatory registration timeline probabilities. Industry-specific forecast inputs incorporated Palmer amaranth infestation mapping and state-level 24(c) petition approval rates.
Forecasts assume regulatory continuity in EPA label frameworks and MAPA registration procedures; material policy shifts including federal cutoff date revisions or Brazilian residue standard changes would require re-modeling. Revision becomes warranted when vapor drift litigation precedents alter insurance availability or when glyphosate resistance patterns accelerate non-auxin chemistry substitution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
India Crop Protection Chemicals Market
Crop Protection
Vietnam Insecticide Market
Crop Protection
India Insecticide Market
Crop Protection
Grain and Cereal Crop Protection Market
Crop Protection
Iprodione Market
Crop Protection
India Herbicide Market
Crop Protection
Crop Bactericides Market
Crop Protection
Fumigation Service Market
Crop Protection
South America Nematicides Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
Global Termite Control Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
Global Aquatic Herbicides Market
Crop Protection
China Insecticide Market
Crop Protection
South America Molluscicides Market
Crop Protection
Global Insect Growth Regulators Market