
 Europe Soil Treatment Market | 2026-2036
Europe Soil Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Soil Treatment Market Foresight
Aftermarket soil testing and advisory revenue is fragmenting across independent agronomy labs and input manufacturers. BASF SE leverages its biologicals portfolio to bundle microbial inoculants with digital soil diagnostics. Syngenta AG anchors its position through integrated seed-and-soil platforms that tie treatment recommendations to variety selection. Novozymes specializes in enzyme-based bioremediation formulations, competing directly with chemical remediation providers on cost-per-hectare outcomes.
Soil treatment encompasses physical, chemical, and biological interventions applied to agricultural and disturbed soils to restore fertility, mitigate contamination, or optimize structure for plant productivity, typically involving pH correction, organic matter incorporation, or microbial inoculation at application rates calibrated to soil tests and crop requirements. Biological amendments now lead product type demand as farmers phase out synthetic inputs ahead of EU regulatory deadlines. Horticulture applications are expanding fastest among application categories, driven by protected cultivation expansion in the Netherlands and Italy where substrate replacement cycles create recurring treatment demand. Soil amendment dominates treatment method volumes, though bio-remediation commands premium pricing on reclaimed industrial and vineyard sites.
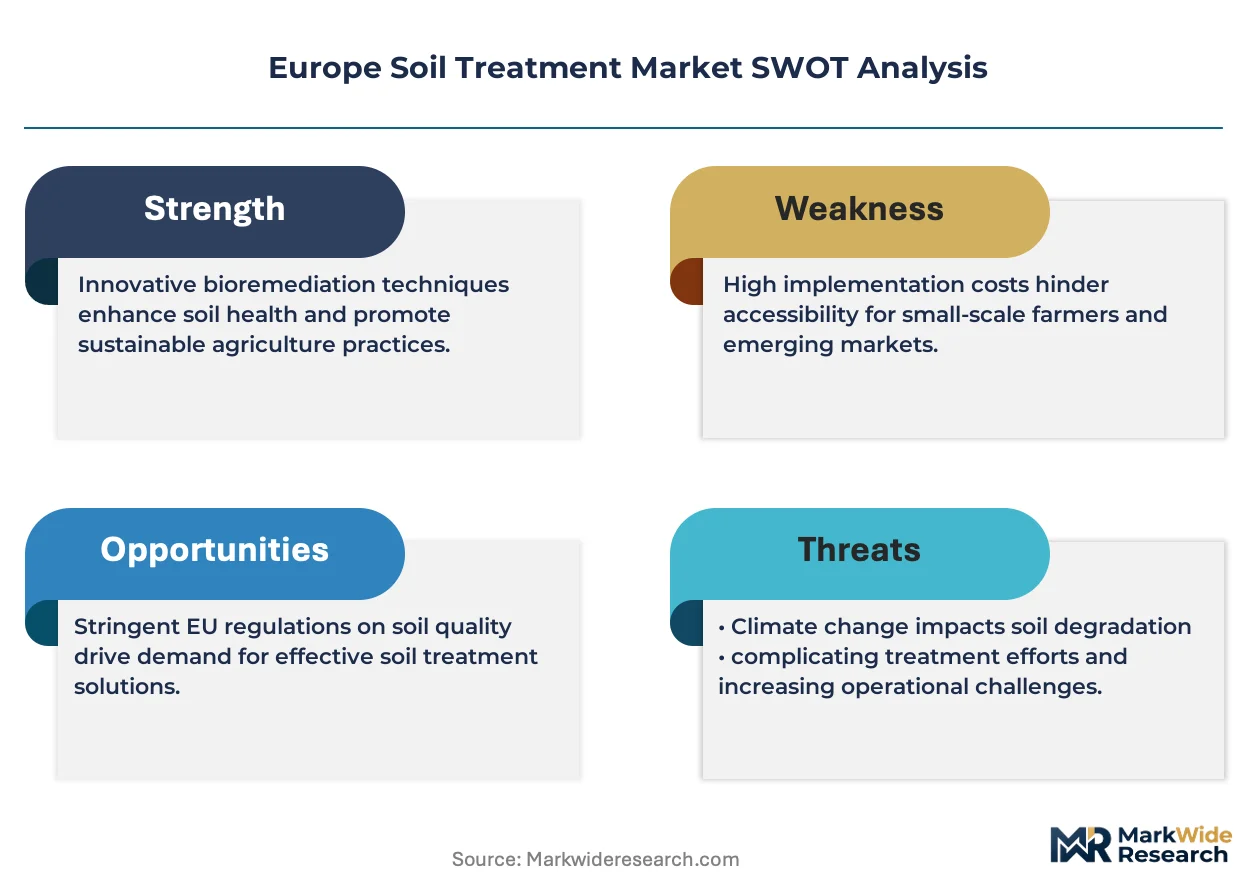
The EU Green Deal, REACH, and F-Gas Regulation collectively constrain chemical soil treatment formulations while mandating contamination disclosure and remediation on land transfers. EFSA and national regulators under the EU AI Act are evaluating precision agriculture data platforms that guide variable-rate soil treatment, creating compliance obligations for algorithmic agronomy tools. Stakeholders must monitor how the CSRD extends supply-chain sustainability reporting to farm-level input sourcing, as this will determine which treatment categories qualify for preferential procurement by food processors and retailers.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing chemical treatment windows while redirecting procurement toward biological amendments, forcing input manufacturers to restructure formulation portfolios ahead of compliance deadlines.
Growth Catalysts
- CSRD-linked farm sustainability reporting:Large cooperatives in France's cereal belt are retrofitting soil management protocols to meet disclosure mandates, creating certified demand for organic and bioremediation-based solutions.
- Protected cultivation expansion:Horticulture applications accelerate in the Netherlands and Italy as substrate replacement cycles generate recurring biological amendment demand from greenhouse operators.
- REACH chemical thresholds:Tightening authorization lists for synthetic soil treatments redirect R&D budgets toward enzyme-based and microbial alternatives that bypass regulatory friction.
Market Restraints
- Biological input cost volatility:Fermentation-derived inoculants face price pressure from energy-intensive production and substrate supply constraints in Eastern European manufacturing hubs.
- Technical performance inconsistency:Microbial amendments exhibit variable field efficacy across soil pH gradients and climatic zones, limiting grower confidence in biological-only protocols.
- Substitution threat from precision agriculture:Variable-rate nutrient application technologies reduce blanket soil treatment volumes by targeting interventions to specific management zones.
Strategic Opportunities
- Underpenetrated vineyard remediation:Spain and Portugal's wine regions present white space for bio-remediation services on reclaimed industrial sites where premium pricing commands acceptance.
- Technology convergence:Digital soil diagnostics platforms integrating EFSA-evaluated algorithms under the EU AI Act enable subscription-based advisory revenue alongside physical amendment sales.
- Regulatory tailwind from F-Gas phase-down:The 2030 reduction targets for fluorinated greenhouse gases accelerate grower transitions to biological fumigation alternatives in intensive vegetable production.
Industry Challenges
- Microbiologist talent scarcity:Formulation development and field advisory functions face recruitment gaps as agronomy programs emphasize chemistry over soil biology curricula.
- Certification timeline compression:EU organic and biostimulant registration pathways under the Fertilising Products Regulation require 18-36 month validation cycles that lag behind product innovation cadence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Soil Treatment Market |
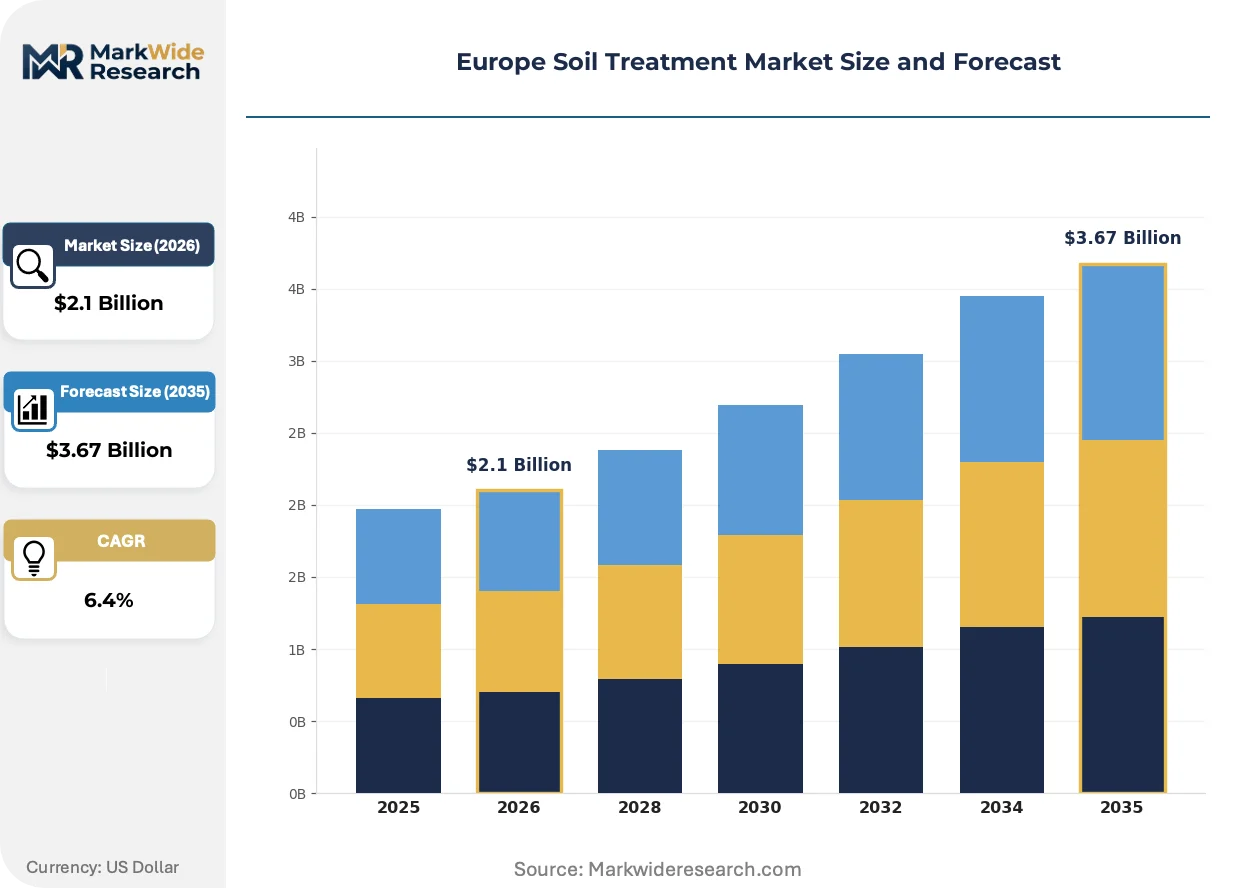
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
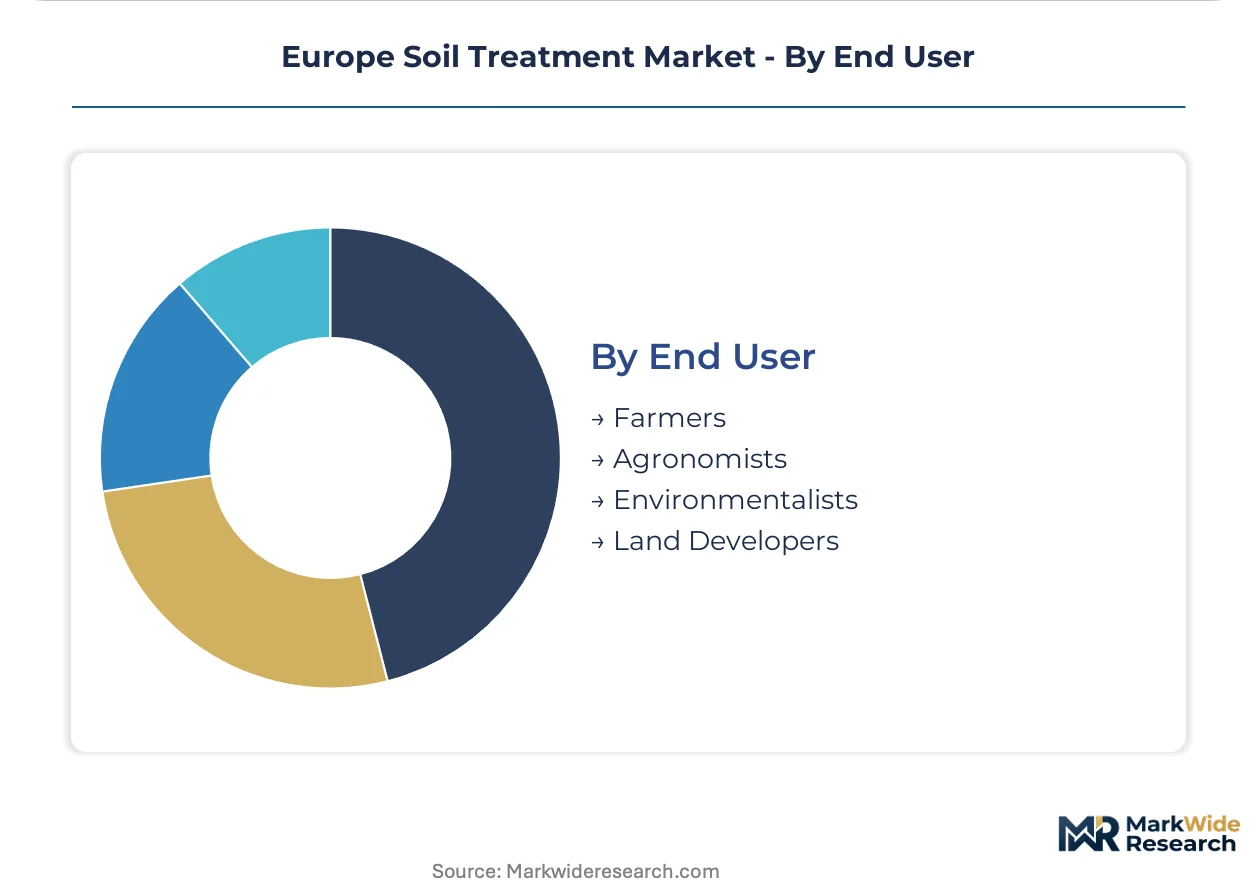
| Segmentation | Product Type: Biological, Chemical, Physical, Organic Application: Agriculture, Horticulture, Landscaping, Forestry Treatment Method: Soil Amendment, Bio-remediation, Soil Aeration, Mulching End User: Farmers, Agronomists, Environmentalists, Land Developers |
| Companies Covered | BASF SE, Syngenta AG, Bayer Crop Science, K+S Aktiengesellschaft, SQM Europe N.V., Novozymes, UPL Limited, Compo Expert, Evonik Industries AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Soil Treatment Market Shifts & Advancements
Biological soil treatment is migrating from niche organic applications toward mainstream conventional agriculture as regulatory pressure and cost convergence erode the chemical-biological performance gap.
Enzyme-based bioremediation formulations are migrating from industrial site cleanup toward vineyard and orchard applications where residual contamination tolerance is lowest. Large estate growers in Bordeaux and Tuscany pilot these treatments to accelerate pesticide degradation ahead of organic conversion timelines. The shift compresses remediation contract durations from multi-year chemical extraction programs to single-season biological interventions.
REACH authorization reviews and the EU F-Gas Regulation are systematically delisting broad-spectrum soil fumigants, forcing manufacturers to withdraw methyl bromide alternatives and accelerate microbial antagonist development. Horticulture greenhouse operators in the Netherlands face the steepest compliance cliffs, driving fastest adoption of biofumigation protocols using Brassica cover crop incorporation.
Buyer concentration among food processors and retailers is imposing tiered sustainability verification requirements that cascade to farm-level input sourcing. French cereal cooperatives now mandate soil treatment documentation for CSRD supply-chain reporting, displacing anonymous commodity purchases with certified biological amendment contracts. This procurement rationalization concentrates volume with suppliers offering integrated testing-advisory-product bundles.
Europe Soil Treatment Market Segmentation
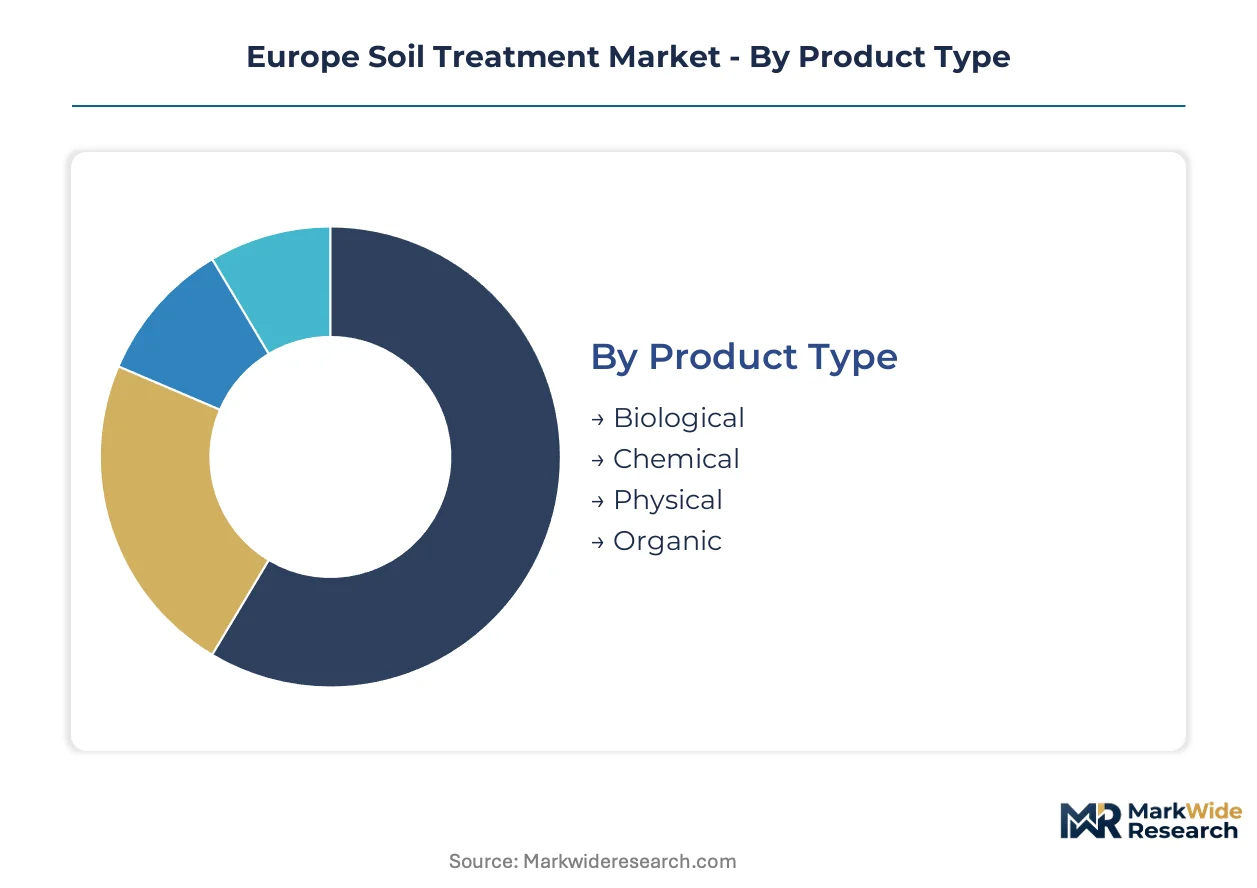
Segmentation in soil treatment reveals distinct procurement rhythms across product categories and end-user profiles. Understanding these cycle-time variations enables suppliers to align inventory and advisory resources with actual field-level demand patterns across European agricultural systems.
Product Type:
Biological amendments turn over fastest as seasonal inoculation protocols drive repeat purchases, while physical treatments exhibit the longest replacement cycles due to infrastructure permanence.
- Biological:Microbial inoculants and enzyme formulations derived from fermentation processes. Demand concentrates in Spain and Italy's specialty crop sectors where growers phase out synthetics ahead of EU regulatory deadlines.
- Chemical:Synthetic pH correctors, fumigants, and nutrient stabilizers. French cereal cooperatives are retrofitting procurement protocols to meet CSRD-linked sustainability reporting, redirecting volume toward certified alternatives.
- Physical:Tillage modifications, drainage systems, and structural amendments. Vineyard remediation in Portugal's Douro Valley drives specialized contracting for terracing and erosion control.
- Organic:Compost-based and biochar amendments meeting EU organic certification standards. Dutch greenhouse operators generate recurring demand through substrate replacement cycles in protected cultivation.
Biological amendments dominate installed base momentum. Physical treatments are where expansion concentrates for premium vineyard and estate applications.
Application:
Cost tier differentiation separates commodity-scale agricultural deployment from precision horticulture where input spending per hectare multiplies.
- Agriculture:Broadacre cereal and oilseed operations requiring pH correction and nutrient stabilization. France's intensive cereal belt generates volume demand through cooperative procurement structures.
- Horticulture:Protected cultivation and nursery operations with recurring substrate treatment needs. The Netherlands leads adoption intensity where greenhouse replacement cycles create predictable biological amendment demand.
- Landscaping:Urban green space and recreational turf management. Italian municipal contracts increasingly specify organic-only protocols under regional sustainability mandates.
- Forestry:Reforestation site preparation and contaminated woodland remediation. Scandinavia's industrial forest estates pilot bio-remediation for legacy pollutant binding.
Agriculture commands the largest absolute spending. Horticulture is climbing the fastest as protected cultivation expands across Southern Europe.
Treatment Method:
Volume concentration favors amendment applications while margin capture concentrates in specialized remediation services requiring technical certification.
- Soil Amendment:Organic matter incorporation, pH correction, and structural improvement applied across broadacre systems. German mixed farms deploy variable-rate lime and compost based on precision soil diagnostics.
- Bio-remediation:Enzyme and microbial treatments targeting contaminant degradation. Bordeaux estate growers pilot these protocols to accelerate pesticide degradation ahead of organic conversion timelines.
- Soil Aeration:Mechanical decompaction and drainage enhancement for waterlogged or trafficked soils. UK arable contractors provide seasonal services for heavy clay management zones.
- Mulching:Surface organic or synthetic cover applications for moisture retention and weed suppression. Italian orchardists integrate bio-mulch with cover crop termination under regenerative protocols.
Soil amendment dominates treatment volumes. Bio-remediation is gaining share fastest as regulatory pressure accelerates vineyard and brownfield site cleanup demand.
End User:
Customer type determines contract structure, with institutional buyers demanding integrated testing-advisory bundles while individual farmers prioritize input cost efficiency.
- Farmers:Owner-operators and cooperative members making direct input procurement decisions. French cereal cooperatives now mandate soil treatment documentation for CSRD supply-chain compliance.
- Agronomists:Independent and manufacturer-affiliated advisors prescribing treatment protocols. Independent labs in Germany fragment aftermarket testing revenue alongside input manufacturer diagnostic platforms.
- Environmentalists:Conservation organizations and remediation contractors addressing contaminated sites. Portugal's industrial site reclamation programs drive bio-remediation service contracting.
- Land Developers:Construction and real estate entities requiring pre-transfer contamination disclosure and treatment. REACH-mandated due diligence on brownfield transactions generates compliance-driven demand.
Farmers represent the largest customer base. Land developers are where expansion concentrates as mandatory contamination disclosure tightens across EU member states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in France's cereal belt exhibit the lowest price elasticity, accepting certified biological premiums for CSRD compliance, while German mixed farmers remain highly sensitive to per-hectare input costs despite regulatory pressure.
France
Large cooperatives in the Île-de-France and Hauts-de-France cereal belts drive certified biological amendment demand through CSRD-linked procurement mandates. REACH chemical thresholds under ECHA supervision redirect cooperative R&D budgets toward enzyme-based alternatives. Bordeaux estate growers in Nouvelle-Aquitaine pilot bio-remediation protocols to accelerate pesticide degradation ahead of organic conversion timelines.
Germany
Mixed farming operations across Bavaria and North Rhine-Westphalia deploy variable-rate lime and compost based on precision soil diagnostics, prioritizing cost efficiency per hectare. The national implementation of the EU F-Gas Regulation accelerates transitions away from synthetic fumigants in intensive vegetable production. Independent agronomy labs in Lower Saxony fragment aftermarket testing revenue alongside manufacturer diagnostic platforms.
Netherlands
Greenhouse operators in the Randstad region generate recurring biological amendment demand through substrate replacement cycles in protected cultivation. The EU Green Deal's Farm to Fork strategy tightens chemical input thresholds faster than the European average here. Wageningen-area research clusters pilot EFSA-evaluated algorithmic agronomy tools under the EU AI Act compliance framework.
Spain
Specialty crop growers in Andalusia and Valencia expand biological amendment programs ahead of EU regulatory deadlines, accepting performance variability for compliance certainty. National transposition of the Fertilising Products Regulation creates 18-36 month validation bottlenecks for new biostimulant registrations. Reclaimed industrial sites near Barcelona present white space for premium bio-remediation contracting.
Italy
Horticulture applications accelerate in Emilia-Romagna and Sicily as protected cultivation expansion generates recurring treatment demand from greenhouse operators. Regional sustainability mandates under the EU Green Deal increasingly specify organic-only protocols for municipal landscaping contracts. Tuscan vineyard estates pilot enzyme-based bioremediation to compress multi-year chemical extraction programs into single-season biological interventions.
Europe Soil Treatment Market Competitive Landscape
Capability concentration sits with specialized biological formulators; scale advantage sits with integrated agricultural input conglomerates. The market structure reflects a tiered hierarchy where multinational agrochemical groups leverage distribution density against focused biotechnology specialists competing on technical performance validation. Three archetypes dominate: diversified chemical-biological hybrids, pure-play microbial fermentation specialists, and integrated seed-and-soil platform operators. Competitive moves center on diagnostic-advisory bundling and backward integration into fermentation capacity to secure substrate supply.
Within the diversified chemical-biological tier, BASF SE and Syngenta AG exemplify integrated platform strategies that tie soil treatment recommendations to broader input portfolios. Novozymes occupies a distinct position as a pure-play enzyme and microbial fermentation specialist competing on bioremediation cost-per-hectare outcomes. These three companies represent contrasting strategic postures: the first two anchor their soil treatment offerings within comprehensive agricultural input ecosystems, while the third exemplifies focused biological expertise without legacy chemical portfolio constraints.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta AG |
| Bayer Crop Science |
| K+S Aktiengesellschaft |
| SQM Europe N.V. |
| Novozymes |
| UPL Limited |
| Compo Expert |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's energy-cost volatility feeds directly into biological amendment pricing power, concentrating margin capture with fermentation facilities near Rotterdam and Antwerp while forcing peripheral suppliers to absorb transport premiums or cede volume to integrated manufacturers with captive logistics.
Pricing Analysis
Long-term offtake contracts dominate biological amendment procurement as French cereal cooperatives lock in certified supply for CSRD compliance windows, though spot purchasing persists for seasonal pH correction materials. Three-tier pricing structure across premium certified-organic, standard biological, and economy chemical tiers reflects EU organic certification grade and after-sales advisory bundling. Cost compression in economy chemical tiers is intensifying because REACH authorization withdrawals strand inventory ahead of compliance cliffs. German mixed farmers exhibit highest price sensitivity per hectare, while Bordeaux estate growers accept premium bio-remediation pricing for accelerated organic conversion.
Supply Chain Analysis
EU dual-use export controls on precision fermentation technology limit bioreactor component flows from German and Dutch engineering clusters to Eastern European manufacturing hubs, constraining capacity expansion. Supply concentration rests on Denmark, Germany, and the Netherlands for microbial inoculant fermentation; substrate supply draws from Ukrainian agricultural residues and Brazilian sugarcane derivatives. Single-source vulnerability concentrates in specialized enzyme feedstocks where Novozymes and BASF maintain captive strain libraries. Distribution runs through cooperative procurement aggregators in France and independent agronomy advisory networks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of formulation microbiologists with field validation expertise is compressing product development timelines and inflating R&D compensation costs, creating structural advantage for incumbents with established university partnerships and apprenticeship pipelines.
For Market Incumbents: Entrench diagnostic-advisory bundling by acquiring independent soil testing labs in Germany's fragmented aftermarket, locking in data streams that guide variable-rate treatment recommendations. Accelerate backward integration into fermentation substrate supply through long-term offtake agreements with Ukrainian agricultural processors, insulating margin pressure from energy-cost volatility. The priority threat is precision agriculture platforms that displace blanket amendment volumes through zone-targeted interventions.
For New Entrants and Emerging Players: Pursue vineyard bio-remediation contracting in Spain's reclaimed industrial zones near Barcelona and Portugal's Douro Valley, where premium pricing tolerance and regulatory-driven cleanup mandates create penetrable white space. Target greenhouse operator segments in Italy's expanding protected cultivation sector through substrate replacement cycle timing. The strongest go-to-market angle is EFSA pre-submission consulting bundled with biostimulant registration navigation, compressing the 18-36 month Fertilising Products Regulation validation bottleneck for grower clients.
For Investors and Strategic Acquirers: The 2030 F-Gas phase-down deadline reshapes the acquisition landscape toward microbial antagonist developers with horticulture greenhouse validation data. Five-to-ten year viability favors pure-play biological formulators over diversified chemical hybrids facing stranded asset risk from REACH delistings. Target acquisition archetype: mid-cap enzyme specialists with vineyard estate reference accounts and existing EU organic certification. The signal to watch is CSRD supply-chain reporting scope expansion to farm-level input sourcing, which would revalue certified amendment contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Supply | Captive access to Ukrainian agricultural residues reduces fermentation cost volatility against energy-price spikes. |
| Diagnostic-Platform Acquisition | Integrated soil testing-advisory bundling locks in CSRD-linked cooperative procurement in France's cereal belt. |
| EFSA Pre-Submission Consulting Launch | Regulatory navigation services compress Fertilising Products Regulation validation timelines for biostimulant entrants. |
| Vineyard Bio-Remediation Service Expansion | Premium contracting on reclaimed industrial sites near Barcelona exploits mandatory contamination disclosure under REACH. |
| University Microbiology Pipeline Partnership | Apprenticeship pipelines address formulation talent scarcity constraining R&D velocity across European competitors. |
Research Methodology
Cross-validation between executive interviews at biological input manufacturers and customs trade data anchors the qualitative findings on supply concentration. Primary fieldwork encompassed fermentation plant managers, cooperative procurement leads in France, independent agronomy lab directors in Germany, and EFSA regulatory affairs specialists. Secondary validation drew from ECHA authorization databases, EU F-Gas Regulation implementation reports, Fertilising Products Regulation registration filings, and national agricultural census data. Bottom-up treatment volume estimates triangulate against top-down input manufacturer revenue allocations.
Calibration against historical biological amendment adoption curves in the Netherlands and vineyard conversion timelines in Bordeaux refined segment-specific growth assumptions across the projection horizon. The analytical framework models product type, application method, treatment category, and end-user procurement structure dimensions. CAGRs derive from logistic diffusion curves fitted to regulatory deadline proximity and cooperative compliance spending patterns. Industry-specific forecast inputs include CSRD reporting mandate phasing and F-Gas phase-down compliance cliff timing.
Sensitivities concentrate around EFSA algorithmic agronomy tool evaluations under the EU AI Act and potential REACH authorization list accelerations. Forecasts embed assumptions on cooperative procurement consolidation rates and energy-cost pass-through elasticity in fermentation economics. Material shifts in EU Green Deal implementation speed or biostimulant registration pathway duration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
China Crop Protection Chemicals Market
Crop Protection
Fosthiazate Market
Crop Protection
Inorganic Fungicide Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
Global Insect Pest Control Market
Crop Protection
Vietnam Fungicide Market
Crop Protection
Asia-Pacific Molluscicides Market
Crop Protection
South America Molluscicides Market
Crop Protection
Global Insecticides Market
Crop Protection
North America Molluscicides Market
Crop Protection
Crop Protection Chemicals Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
Tebufenozide Market
Crop Protection
Asia-Pacific Crop Protection Chemicals Market
Crop Protection
Pre-Emergent Herbicide Market
Crop Protection
South America Acaricides Market