
 Europe Molluscicides Market | 2026-2036
Europe Molluscicides Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Molluscicides Market Foresight
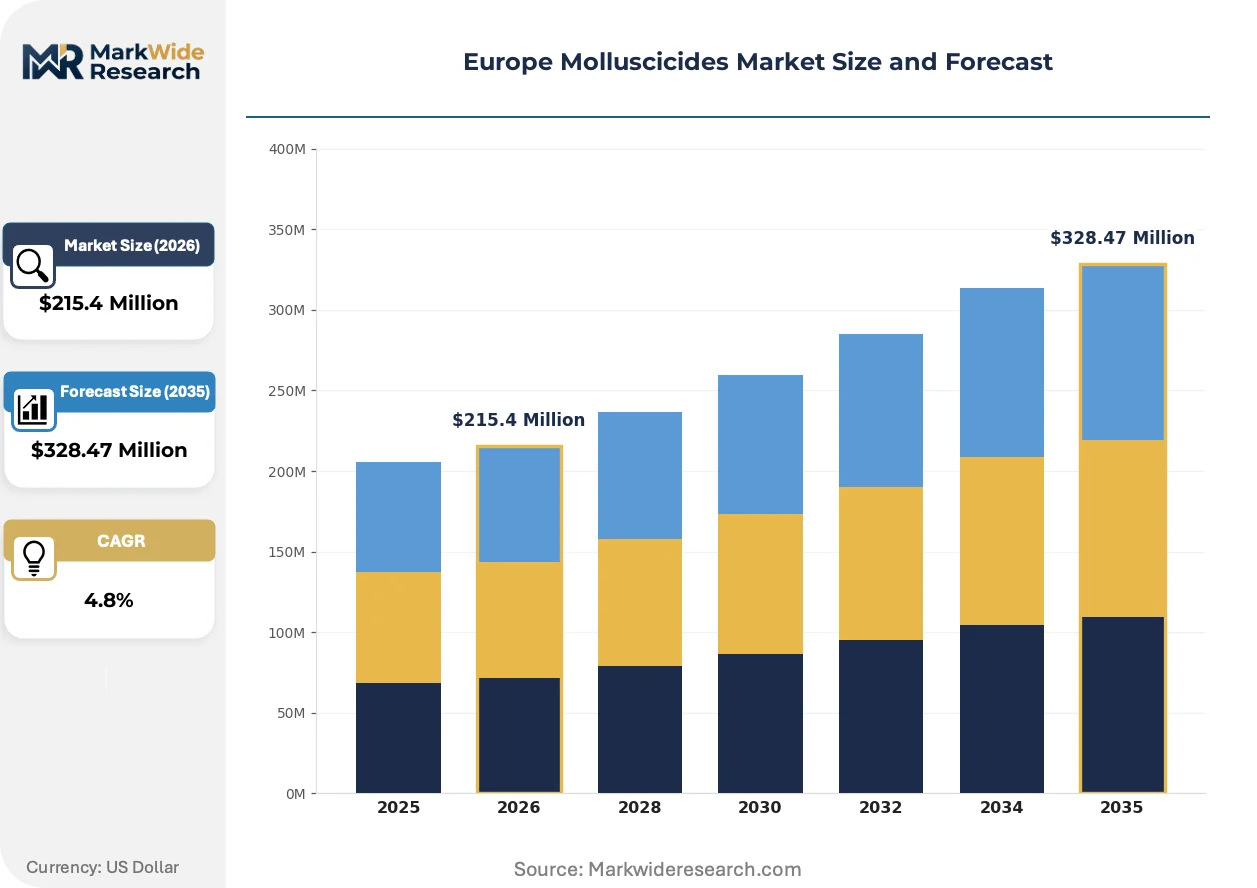
Copper-based chemistries is hardening cost positions across the Europe molluscicides market as ferric phosphate gains share against legacy metaldehyde formulations. BASF SE leverages its agrochemical formulation depth to sustain leadership in pelletized delivery systems. Bayer AG anchors southern European distribution through dedicated horticulture channels. Lonza Group AG differentiates via toll manufacturing partnerships that supply private-label molluscicide brands.
Molluscicides are biocidal or pesticidal formulations designed to control gastropod pests—primarily slugs and snails—through contact, ingestion, or repellency mechanisms, with active concentrations typically ranging from one to five percent depending on target species and crop context. Their primary commercial purpose is to protect high-value seedlings, leafy vegetables, and perennial crops from yield losses exceeding economic thresholds during wet growing seasons. Ferric phosphate now leads product type demand as metaldehyde faces phased withdrawal pressures across multiple EU member states. Agriculture dominates application volume, though turf management represents the fastest-expanding margin pool as golf course and sports ground maintenance professionalizes. Granule formulations occupy the largest formulation share, yet liquid concentrates are gaining traction in precision-spray vineyard programs.
EMA and EFSA frameworks govern active substance approval and residue limits under EU Regulation 1107/2009, while REACH compliance shapes formulation chemistry transitions and environmental risk assessments. The EU Green Deal and F-Gas Regulation indirectly pressure manufacturers toward lower-toxicity, biodegradable carriers that align with Farm-to-Fork sustainability targets. Stakeholders must monitor pending active substance renewals and national derogation timelines to anticipate supply discontinuities and reposition portfolios toward ferric phosphate and biological alternatives before regulatory deadlines crystallize competitive advantage.
Market Dynamics
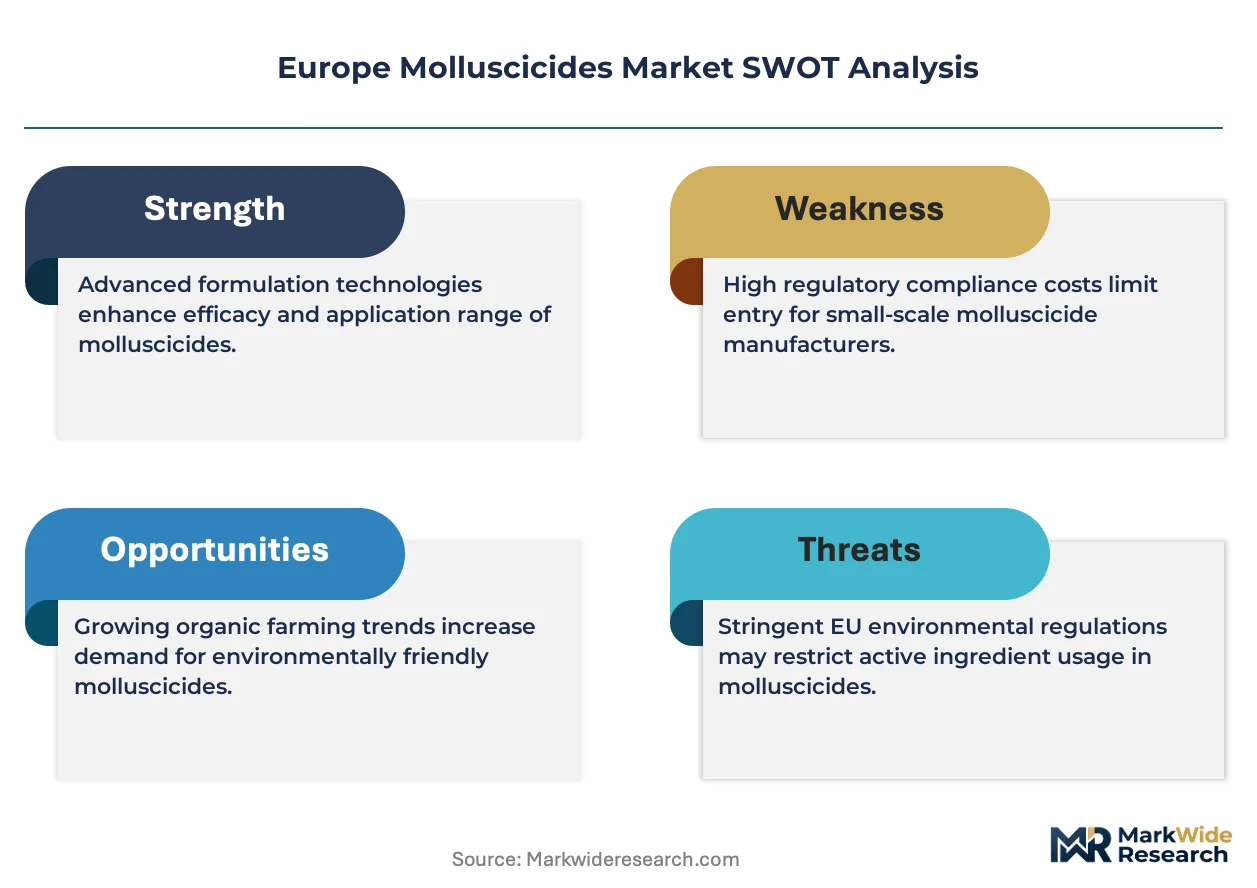
Metaldehyde phase-out mandates across EU member states are forcing immediate portfolio restructuring toward ferric phosphate alternatives, compressing formulation timelines and redistributing competitive advantage toward registrants with existing bioactive pipelines.
Growth Catalysts
- EU Green Deal compliance pressure:Farm-to-Fork sustainability targets accelerate adoption of biodegradable carrier systems in Mediterranean horticulture zones.
- Vineyard protection intensity:Spanish and Italian wine producers expand molluscicide application during wet growing seasons to safeguard high-value perennial crops.
- Ferric phosphate efficacy gains:Improved pellet durability and rainfastness properties match legacy metaldehyde performance without environmental persistence risks.
Market Restraints
- Active substance renewal uncertainty:EFSA evaluation timelines for copper-based chemistries create supply discontinuity risks for southern European growers.
- Granule formulation cost premiums:Precision-pellet manufacturing requires specialized extrusion equipment that smaller compounders cannot access.
- Biological substitute competition:Nematode-based gastropod control products gain traction in organic certification channels.
Strategic Opportunities
- Portuguese market underpenetration:Limited local formulation capacity leaves room for toll-manufactured private-label entry in cork oak and olive sectors.
- Turf management professionalization:Golf course maintenance contracts increasingly specify integrated pest management protocols requiring scheduled molluscicide rotation.
- Liquid concentrate vineyard programs:Precision-spray application technology enables drift-reduced coverage in steep-terrain French and German wine regions.
Industry Challenges
- REACH dossier preparation expertise:Environmental risk assessment documentation requires toxicology specialists that mid-tier formulators struggle to retain.
- Metaldehyde inventory stranding:National derogation timeline variations complicate working capital management across multi-country distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Molluscicides Market |
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $328.47 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metaldehyde, Ferric Phosphate, Methyl Eugenol, Others Application: Agriculture, Horticulture, Turf Management, Others Formulation: Granules, Pellets, Liquids, Others Distribution Channel: Online, Offline, Agricultural Cooperatives, Retailers |
| Companies Covered | BASF SE, Lonza Group AG, Bayer AG, Adama Agricultural Solutions Ltd., Certis Europe B.V., Neudorff GmbH Kg, De Sangosse SAS, Doff Portland Ltd., American Vanguard Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Molluscicides Market Shifts & Advancements
Formulation chemistry is pivoting toward biodegradable matrices as regulatory pressure compounds against persistent active ingredients. Delivery mechanism innovation now determines competitive positioning as much as active substance selection.
Microencapsulated ferric phosphate is absorbing moisture-activated release characteristics previously exclusive to metaldehyde pellets. French and Italian vineyard operators adopt these formulations for extended protection through variable spring rainfall patterns. The technology is absorbing premium positioning in high-value crop segments while compressing commodity pellet margins.
REACH authorization timelines for copper sulfate pentahydrate are tightening residue limit thresholds across member states. This industrial consequence accelerates substitution toward iron-based alternatives in organic agriculture channels. Spanish citrus and vegetable cooperatives face the most acute compliance pressure and are pre-registering ferric phosphate variants ahead of renewal deadlines.
Specialist distributors are consolidating procurement authority across southern European horticulture cooperatives. Independent agrochemical retailers in France and Italy lose volume to dedicated horticulture channels operated by multinational registrants. This concentration is most visible in the Languedoc-Roussillon and Sicily regions where vineyard consolidation drives centralized input purchasing.
Europe Molluscicides Market Segmentation
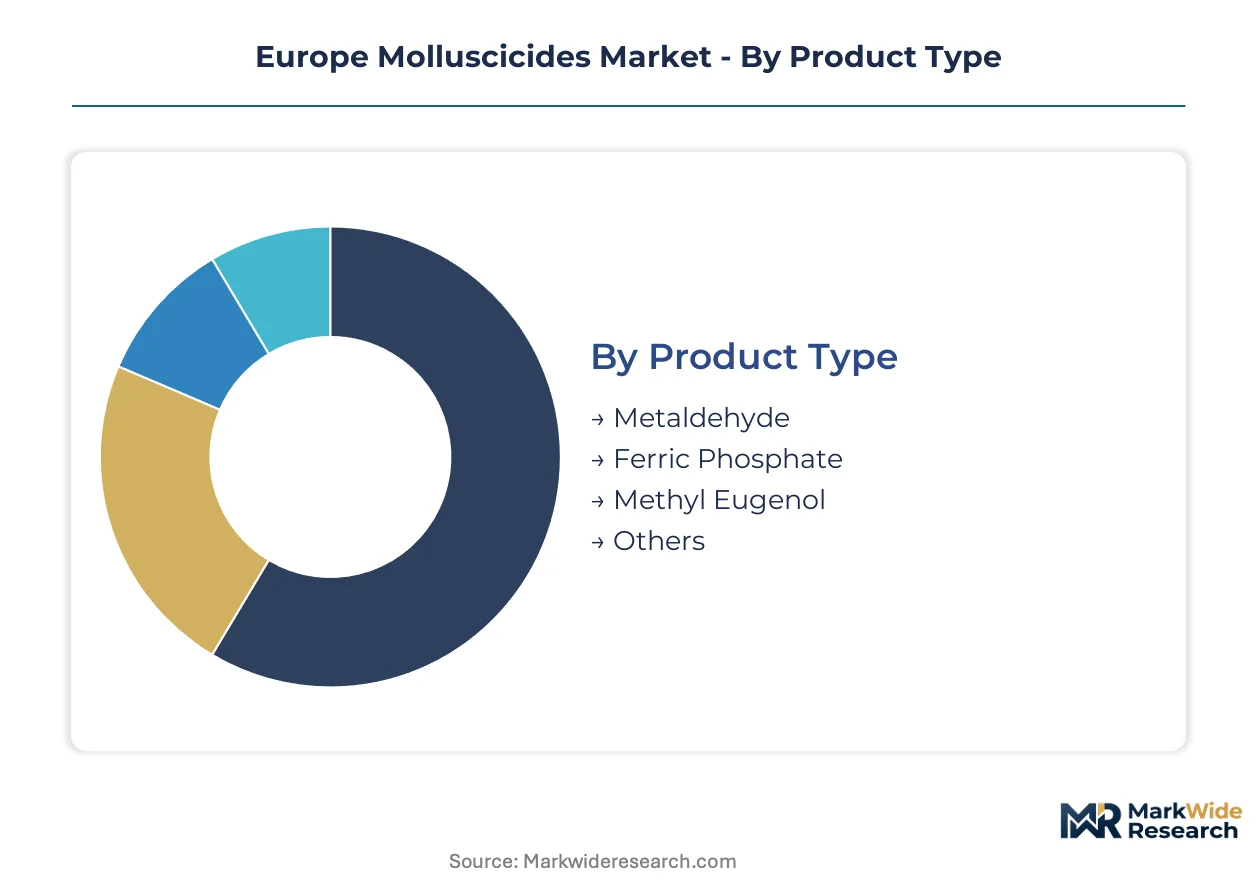
Segmentation in the Europe molluscicides market reveals how regulatory pressure and crop value concentration reshape procurement patterns. Buyers select active substances and formulations based on compliance timelines, terrain constraints, and integrated pest management protocols.
Product Type:
Buyers prioritize residue profile and renewal certainty when selecting active substances, with environmental persistence now outweighing unit efficacy in tender evaluations.
- Metaldehyde:Neurotoxic active historically dominant in wet-climate applications. Italian and Spanish growers face inventory stranding risks as national derogation timelines diverge across member states.
- Ferric Phosphate:Iron-based alternative with improved pellet rainfastness matching legacy performance. Vineyard operators in France and Germany expand application as metaldehyde withdrawals accelerate.
- Methyl Eugenol:Pheromone-based attractant formulation used in targeted trapping systems. Limited penetration outside specialized organic certification channels.
- Others:Nematode biologicals and copper sulfate variants serving niche organic compliance requirements. EFSA renewal uncertainty constrains copper adoption.
Ferric phosphate leads on scale; metaldehyde retains momentum only where derogations extend.
Application:
End-use value concentration determines formulation premium tolerance, with perennial crop protection commanding specialized delivery systems.
- Agriculture:Broad-acre vegetable and cereal production requiring cost-efficient broadcast application. Spanish citrus cooperatives drive volume procurement through centralized input purchasing.
- Horticulture:High-value seedling and protected crop operations in Mediterranean greenhouse clusters. Italian nursery operators specify microencapsulated pellets for extended release.
- Turf Management:Golf course and sports ground maintenance contracts specifying scheduled rotation protocols. French golf estates in Brittany and Provence professionalize procurement through dedicated horticulture channels.
- Others:Public green space and railway embankment programs with standardized tender specifications. Municipal buyers prioritize lowest-unit-cost granule formulations.
Agriculture dominates absolute volume; turf management climbs fastest on contract professionalization.
Formulation:
Application equipment and terrain accessibility dictate physical form selection, with precision-spray technology reshaping vineyard preferences.
- Granules:Broadcast-ready particles for mechanical spreader deployment across flat arable land. German and Polish field crop operators favor cost-optimized granule economics.
- Pellets:Extruded precision-dose units with moisture-activated release characteristics. French and Italian vineyard slopes require pellet stability against runoff.
- Liquids:Concentrate formulations for drift-reduced precision spraying in steep-terrain wine regions. German Pfalz and French Alsace operators trial liquid concentrate compatibility with existing sprayer fleets.
- Others:Gel baits and wettable powders serving specialized organic and smallholder channels. Limited scale due to application labor intensity.
Granules capture greatest volume; liquids gain share fastest on precision-spray vineyard adoption.
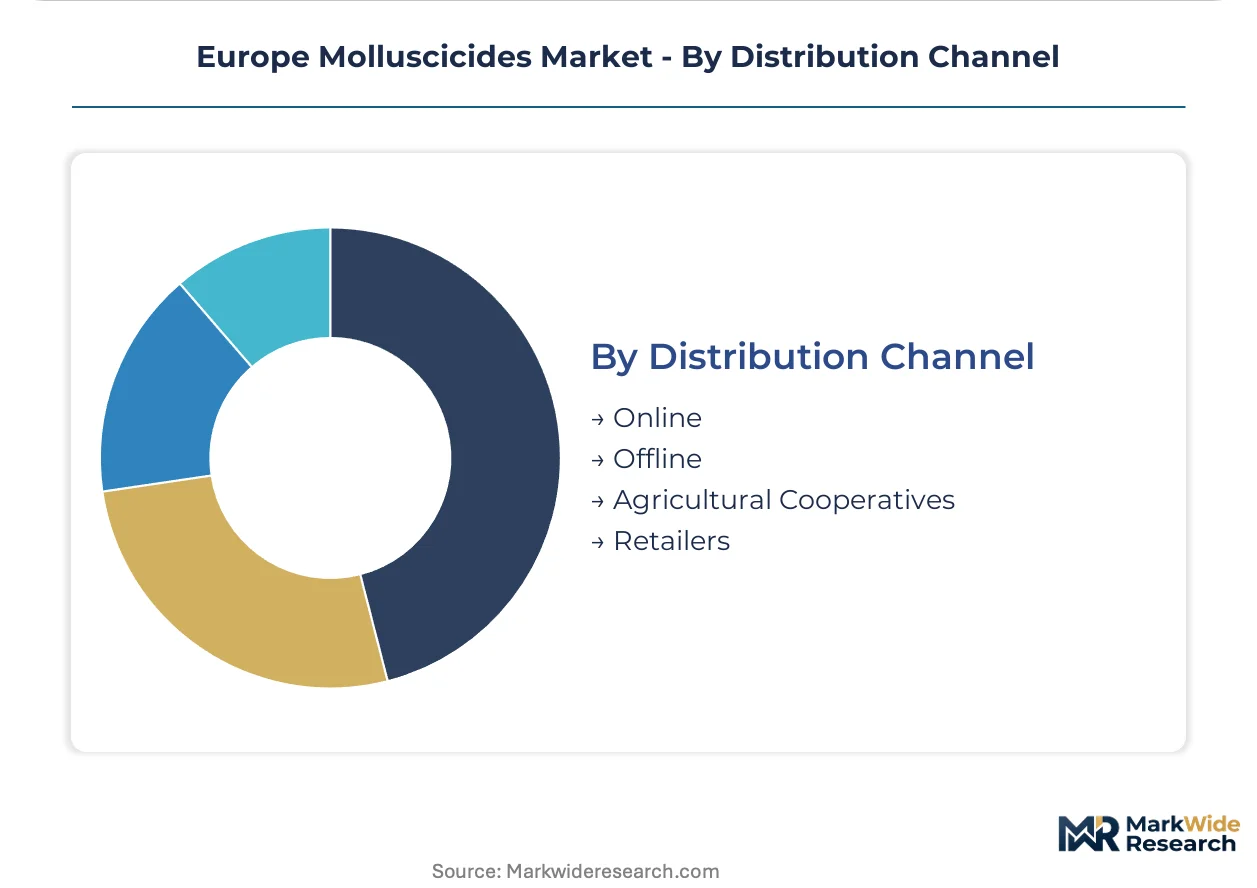
Distribution Channel:
Procurement authority concentration among cooperative buyers is compressing independent retail margins and favoring direct registrant relationships.
- Online:Direct-to-farm platforms capturing smaller vineyard and specialty crop orders. Italian and Spanish digital agrochemical marketplaces expand SKU breadth.
- Offline:Traditional agricultural merchant networks with technical advisory services. French independent retailers lose volume to cooperative consolidation in Languedoc-Roussillon.
- Agricultural Cooperatives:Centralized purchasing bodies dominating southern European horticulture input procurement. Spanish citrus and vegetable cooperatives pre-register ferric phosphate variants ahead of regulatory deadlines.
- Retailers:Garden center and home improvement channels serving amateur grower segments. Limited to consumer-packaged pellet formats with restricted active concentrations.
Agricultural cooperatives lead on scale; online channels expand most quickly on convenience positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish citrus cooperatives and Italian vineyard consortiums anchor procurement intensity across Mediterranean horticulture zones, with regulatory pressure from the EU Green Deal and F-Gas Regulation reshaping formulation preferences toward biodegradable carriers.
Spain
Valencia citrus groves and Andalusian olive estates drive ferric phosphate uptake as metaldehyde derogations tighten. EFSA evaluation timelines for copper-based chemistries create supply uncertainty for organic certification channels. Catalan vineyard clusters near Barcelona trial microencapsulated pellets for extended rainfastness during variable spring conditions.
Italy
Sicilian citrus cooperatives and Tuscan wine producers expand molluscicide application to protect high-value perennial crops from gastropod damage. REACH compliance documentation requirements strain mid-tier formulator resources. Emilia-Romagna nursery operators specify precision-dose pellets for protected greenhouse seedling operations.
France
Languedoc-Roussillon vineyard consolidation drives centralized input purchasing through dedicated horticulture channels. ANSM residue monitoring protocols tighten enforcement of EMA environmental risk assessments. Alsace and Pfalz-border wine regions trial liquid concentrate formulations for drift-reduced precision spraying on steep slopes.
Germany
Baden-Württemberg and Rhineland-Palatinate vineyard operators lead adoption of precision-spray application technology for liquid molluscicide concentrates. KBA-aligned agricultural equipment standards influence sprayer fleet compatibility requirements. Bavarian field crop producers favor cost-optimized granule formulations for broad-acre cereal protection.
Portugal
Alentejo cork oak plantations and Douro Valley vineyards present underpenetrated demand for toll-manufactured private-label molluscicides. Limited local formulation capacity leaves procurement dependent on Spanish and French supply chains. Portuguese agricultural cooperatives pre-register ferric phosphate variants ahead of anticipated metaldehyde withdrawal deadlines.
Europe Molluscicides Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and distribution channel depth, producing a tiered structure where multinational registrants control pelletized delivery innovation while specialized compounders serve cooperative procurement channels. The competitive landscape stratifies into three archetypes: integrated agrochemical conglomerates with dedicated horticulture divisions, toll-manufacturing specialists supplying private-label brands, and regional formulators focused on national derogation compliance. Dominant competitive moves include backward integration into precision-extrusion equipment for pellet manufacturing and strategic partnerships with southern European agricultural cooperatives to secure volume commitments ahead of regulatory deadlines.
Within the integrated agrochemical tier, BASF SE and Bayer AG exemplify multinational registrants leveraging formulation depth and dedicated horticulture channels respectively. Lonza Group AG occupies a distinct position as a toll-manufacturing specialist supplying private-label molluscicide brands to cooperative buyers. These three companies represent the primary competitive anchors across chemistry innovation, distribution control, and manufacturing flexibility vectors in the European market.
| Leading Market Players |
|---|
| BASF SE |
| Lonza Group AG |
| Bayer AG |
| Adama Agricultural Solutions Ltd. |
| Certis Europe B.V. |
| Neudorff GmbH Kg |
| De Sangosse SAS |
| Doff Portland Ltd. |
| American Vanguard Corporation |
| Others |
Supply & Pricing Matrix
Spanish and Italian cooperative procurement consolidation is forcing formulation manufacturers toward specialized pellet extrusion capacity and biodegradable carrier investments, compressing margins on commodity granules while concentrating pricing power with toll-manufacturing specialists.
Pricing Analysis
Input-cost pass-through from ferric phosphate active ingredient sourcing and precision-extrusion equipment depreciation is reshaping contract structures. Three-tier pricing structure across premium microencapsulated pellets, standard rainfast granules, and economy bulk formulations reflects certification grade and volume scale differentiation. Pricing pressure stems from metaldehyde inventory stranding as national derogation timelines diverge. Municipal buyers in public green space tenders exhibit highest price sensitivity; vineyard cooperatives in France and Italy tolerate premium positioning for extended-release formulations.
Supply Chain Analysis
Reverse-logistics flows for expired metaldehyde stockpiles are straining distributor working capital across multi-country networks. Active ingredient manufacturing concentrates in Germany, China, and India; formulation and pellet extrusion centers on Spain, France, and Italy. Raw material dependencies include iron phosphate feedstock, biodegradable starch matrices, and moisture-barrier packaging films. Single-source vulnerability sits with specialized extrusion equipment suppliers. Distribution runs through agricultural cooperative procurement hubs and dedicated horticulture channels operated by multinational registrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story: vineyard and turf management buyers are shifting procurement specifications toward microencapsulated ferric phosphate with biodegradable carriers, rewarding registrants with formulation depth and penalizing commodity granule suppliers.
For Market Incumbents: Extend pellet manufacturing capacity in southern European horticulture zones ahead of metaldehyde withdrawal deadlines. Deepen backward integration into precision-extrusion equipment to defend against toll-manufacturing specialists. Secure multi-year supply agreements with Spanish citrus and Italian vineyard cooperatives before regulatory deadlines crystallize competitive advantage. For New Entrants and Emerging Players: Portuguese cork oak and olive sector cooperatives represent an underserved buyer archetype with limited local formulation capacity. Private-label ferric phosphate entry through toll-manufacturing partnerships offers the most penetrable path. Digital agrochemical marketplaces in Italy and Spain provide direct-to-farm go-to-market access without legacy distribution infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with toll-manufacturing specialists possessing REACH dossier preparation expertise and cooperative channel relationships. Long-term viability over a multi-year horizon favors registrants with existing bioactive pipelines over metaldehyde-dependent formulators. Monitor EFSA active substance renewal timelines for copper-based chemistries as inflection indicators for substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision-Extrusion Equipment | Captures pellet manufacturing margin previously lost to specialized machinery suppliers in Germany and Switzerland. |
| Biodegradable Carrier Formulation Transition | Aligns product portfolios with EU Green Deal Farm-to-Fork sustainability targets ahead of regulatory enforcement. |
| Long-term Supply Agreement with Cooperative Buyers | Locks volume commitments from Spanish citrus and Italian vineyard consortiums before metaldehyde withdrawal deadlines. |
| REACH Dossier Preparation Capability Investment | Enables continued market access as EFSA evaluation timelines tighten residue limit thresholds across member states. |
| Liquid Concentrate Precision-Spray Compatibility Development | Opens vineyard segments in steep-terrain Alsace and German Pfalz regions with drift-reduced application requirements. |
Research Methodology
Coverage spans Mediterranean horticulture zones in Spain, Italy, and France, with primary inputs from each, combining interviews with agrochemical formulators, cooperative procurement managers, and vineyard operations directors with secondary validation through EFSA active substance renewal databases, REACH registration dossiers, and EU customs trade data. Bottom-up volume modeling triangulates against top-down value estimates.
Granularity-level modeling operates at active substance by formulation by application tier, with ferric phosphate, metaldehyde, and copper-based chemistries tracked separately across granule, pellet, and liquid concentrate forms through agriculture, horticulture, and turf management end-uses. CAGRs derive from segment-level growth rate synthesis across the projection horizon. Forecast inputs include regulatory deadline schedules, cooperative procurement volume commitments, and vineyard acreage protection intensity indices.
Underlying measurement precision varies by segment; ferric phosphate and metaldehyde product categories carry tighter precision than emerging biological alternatives. Forecasts reflect documented assumptions regarding derogation timeline adherence and active substance renewal outcomes. Practitioners should monitor EFSA evaluation announcements and national metaldehyde withdrawal decrees for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Global Home and Garden Pesticides Market
Crop Protection
South America Molluscicides Market
Crop Protection
Grain Protectant Market
Crop Protection
US Herbicide Market
Crop Protection
Europe Nematicide Market
Crop Protection
China Crop Protection Chemicals Market
Crop Protection
Asia-Pacific Crop Protection Chemicals Market
Crop Protection
Asia-Pacific Nematicides Market
Crop Protection
Pre-Emergent Herbicide Market
Crop Protection
China Fungicide Market
Crop Protection
Indoor Vertical Farm Safe Crop Protection Chemistry Market
Crop Protection
Global SDHI Fungicide Market
Crop Protection
United States Nematicides Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
United Kingdom Crop Protection Chemicals Market
Crop Protection
Europe Seed Treatment Market