
 Canada Pulses Market | 2026-2036
Canada Pulses Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Pulses Market Intelligence
Bulk-to-retail packaging reconfiguration is consolidating buyer choice across the Canada Pulses Market, as processors shift toward pre-portioned pouches and branded bag formats for supermarket and online channels. AGT Food and Ingredients leverages its vertically integrated processing network to dominate premium ingredient supply. The Scoular Company anchors its position through extensive prairie origination infrastructure. BroadGrain Commodities specializes in identity-preserved handling for export-certification requirements.
Canada pulses comprise dried seeds of leguminous crops—principally lentils, chickpeas, peas, and beans—harvested at maturity with moisture content below 14% and graded by seed size, color uniformity, and defect thresholds under CFIA standards; these crops fix atmospheric nitrogen, reducing input costs, and serve as protein-dense inputs for human consumption, animal feed, and fractionated ingredients. Lentils occupy the largest volume share due to established export pipelines into South Asian markets, while peas represent the fastest-expanding category as starch and protein extraction capacity builds across the prairies. Ingredient-grade processing commands superior margins versus whole-pulse commodity trade.
Health Canada governs nutrition labeling and novel food approvals for pulse-derived proteins, while CFIA enforces seed grading, varietal registration, and phytosanitary certification for export access; the Canadian Grain Commission maintains binding standards for dockage, moisture, and foreign matter that directly determine price realization at primary elevators. Stakeholders must monitor evolving EU deforestation regulation traceability requirements and domestic carbon-accounting frameworks that will reshape sourcing protocols and capital allocation across prairie processing assets.
Market Dynamics
Ingredient-grade fractionation capacity is concentrating capital allocation across Saskatchewan and Alberta, as processors redirect investment from commodity handling toward protein and starch extraction facilities serving plant-based food manufacturers.
Growth Catalysts
- CFIA phytosanitary certification alignment:Streamlined export protocols for Indian and Turkish buyers are accelerating containerized shipment velocities through Vancouver and Prince Rupert terminals.
- Pulse protein extraction technology:Wet-fractionation systems deployed at prairie processing hubs are converting yellow peas into isolates with functionality matching soy and dairy proteins.
- Saskatchewan's production cluster:Concentrated lentil and pea acreage within 200 kilometers of Regina creates unmatched origination density for identity-preserved contracting.
Market Restraints
- Freight rate volatility:Container shipping cost swings between Asia-Pacific destinations compress export margins for containerized pulse shipments.
- Single-origin concentration risk:Saskatchewan's dominance in red lentil production exposes buyers to regional drought or disease pressure without viable alternative sourcing.
- EU deforestation regulation traceability:Pending geolocation documentation requirements for farm-level sourcing are forcing costly supply chain reconfiguration ahead of compliance deadlines.
Strategic Opportunities
- Alberta protein extraction hub development:Underutilized processing capacity in Lethbridge and Medicine Hat offers brownfield expansion sites for pea-protein isolate production.
- Pet food protein inclusion:Premium dog and cat food formulations are substituting pulse concentrates for rendered animal proteins at midwestern US manufacturing facilities.
- Clean Fuel Regulations carbon credits:Pulse crop rotation qualifying for federal offset protocols generates ancillary revenue streams for prairie farm operations.
Industry Challenges
- Seed varietal registration timelines:CFIA's multi-year cultivar approval process delays commercial deployment of disease-resistant genetics with improved protein content.
- Fractionation wastewater treatment:Wet-processing facilities face municipal discharge limits requiring capital-intensive effluent systems in water-stressed prairie regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Pulses Market |
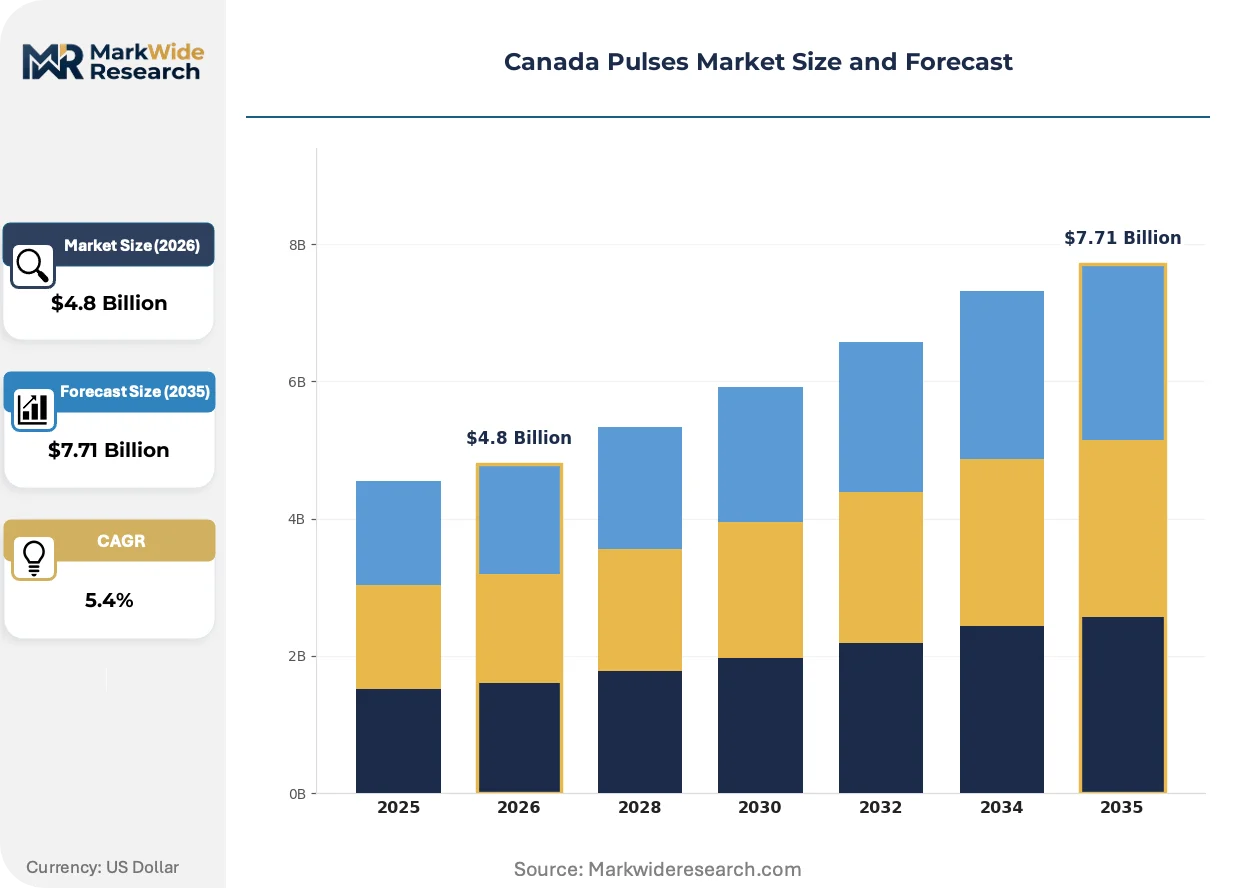
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lentils, Chickpeas, Peas, Beans End Use: Food Products, Feed, Snacks, Ingredients Distribution Channel: Supermarkets, Online Retail, Wholesale, Specialty Stores Packaging Type: Bags, Cans, Bulk, Pouches |
| Companies Covered | Archer Daniels Midland Company, The Scoular Company, AGT Food and Ingredients, Olam International, Ingredion Inc., BroadGrain Commodities, Bunge Limited, Adani Wilmar, Cargill Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Pulses Market Strategic Shifts & Innovations
Processing technology and regulatory compliance requirements are restructuring competitive advantage away from commodity trading scale and toward ingredient functionality certification.
Air classification systems for dry protein concentration are overtaking traditional wet-fractionation at smaller-scale prairie facilities. Mid-tier processors in Manitoba are adopting these units to bypass wastewater infrastructure constraints. The shift is compressing minimum viable scale for protein ingredient production from 100,000-tonne to 20,000-tonne annual throughput.
Health Canada's updated nutrition labeling regulations for plant-based protein content claims are forcing reformulation documentation across packaged food categories. Manufacturers must now validate protein digestibility-corrected amino acid scores for pulse-derived ingredients. Snack bar and meat alternative producers are responding by securing certified analytical testing from third-party laboratories.
Direct contracting between prairie farm operations and ingredient processors is displacing open-market elevator sales for premium-grade pulses. Large-scale buyers are establishing multi-year offtake agreements with specific varietal and protein-content specifications. This pattern concentrates most visibly in the Red River Valley, where identity-preserved handling infrastructure supports traceability requirements for European export customers.
Canada Pulses Market Segmentation
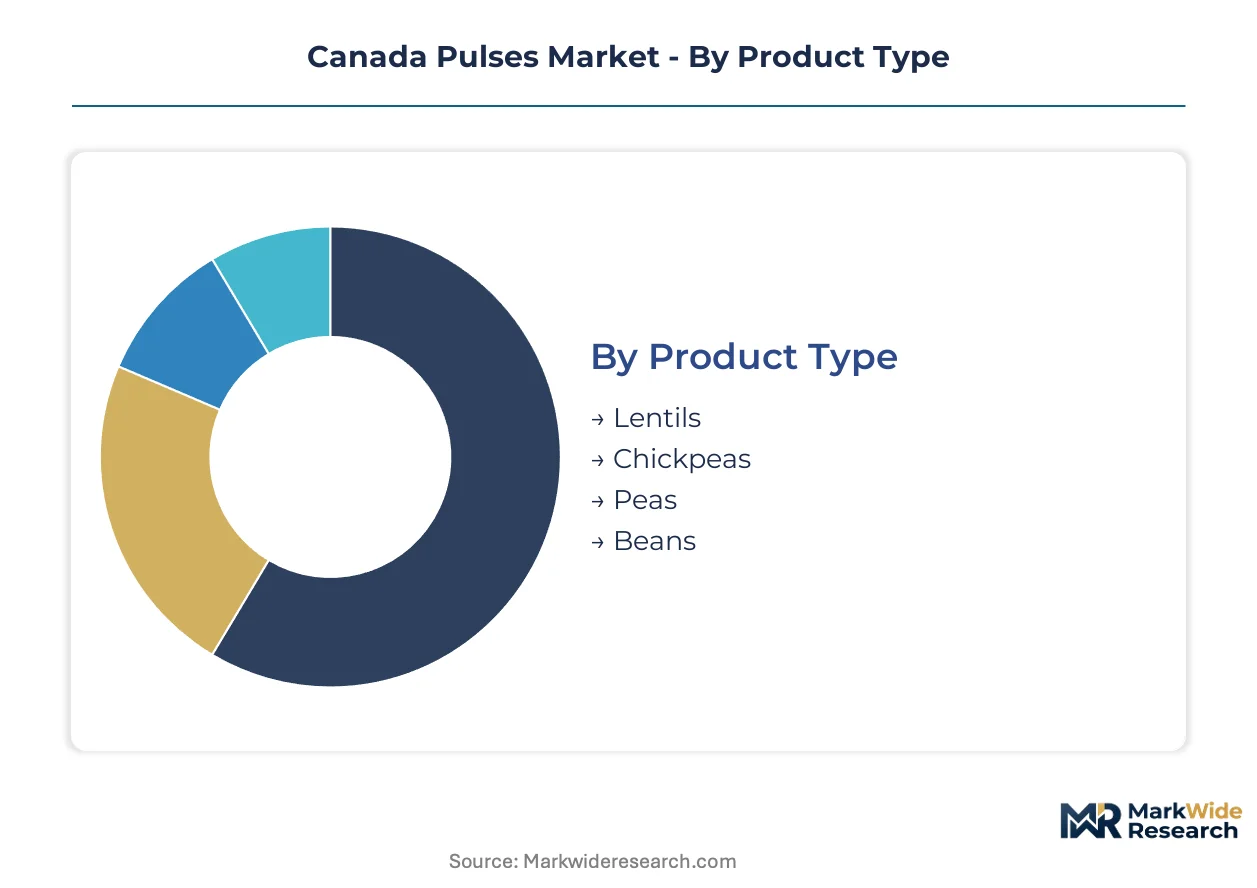
Pulse processors in Canada must align product specifications with distinct buyer requirements across export commodity, ingredient-grade fractionation, and packaged retail channels. Segmentation reveals how CFIA grading standards, extraction technology thresholds, and packaging format preferences partition margin capture across the value chain.
Product Type:
Protein content and starch composition differentiate processing economics across pulse varieties, with fractionation technology favoring specific crop architectures.
- Lentils:Red and green varieties graded by seed size uniformity and decortication yield under CFIA standards. Saskatchewan's Red River Valley concentrates red lentil acreage for South Asian export pipelines, though disease pressure from anthracnose is accelerating varietal turnover timelines.
- Peas:Yellow and green field peas with starch contents above 45% enable wet-fractionation into isolates matching soy protein functionality. Alberta and Manitoba processing hubs are expanding extraction capacity to supply plant-based meat manufacturers in the US Midwest.
- Chickpeas:Kabuli and desi types with thick seed coats require specialized dehulling equipment; prairie production remains limited relative to global supply from India and Turkey.
- Beans:Navy, black, and pinto varieties serve canning and dry-pack channels with lower protein concentration than peas or lentils, constraining ingredient-grade premiumization.
Lentils lead on scale; peas lead on momentum.
End Use:
Margin structures diverge sharply between commodity whole-pulse trade and value-added ingredient processing, reshaping capital allocation across prairie facilities.
- Food Products:Whole pulses packaged for retail and foodservice channels, with Health Canada labeling regulations governing protein content claims. Canned and dry-pack formats dominate supermarket placement.
- Ingredients:Protein concentrates, isolates, and starches extracted via wet or dry fractionation. Wet-processed pea isolates command superior margins supplying plant-based dairy and meat analog producers.
- Feed:Dehulled splits and processing byproducts directed to swine and poultry rations, with pricing tethered to soybean meal benchmarks.
- Snacks:Roasted, puffed, and extruded pulse products targeting gluten-free and high-protein positioning in convenience retail.
Ingredients capture margin expansion; food products anchor volume throughput.
Distribution Channel:
Channel selection determines packaging configuration, certification documentation, and working capital intensity for prairie processors and exporters.
- Wholesale:Bulk container shipments through Vancouver and Prince Rupert terminals to Indian, Turkish, and UAE buyers, with CFIA phytosanitary certification enabling market access.
- Supermarkets:Pre-portioned retail packs with bilingual labeling and organic or non-GMO certifications; Loblaws and Sobeys chains dominate domestic placement.
- Online Retail:Direct-to-consumer and subscription formats emphasizing heritage varietals and small-lot provenance; packaging durability requirements differ from brick-and-mortar.
- Specialty Stores:Ethnic grocers and natural food retailers stocking identity-preserved lentils and heritage beans with traceability documentation.
Wholesale dominates export tonnage; online retail climbs fastest on consumer premiumization.
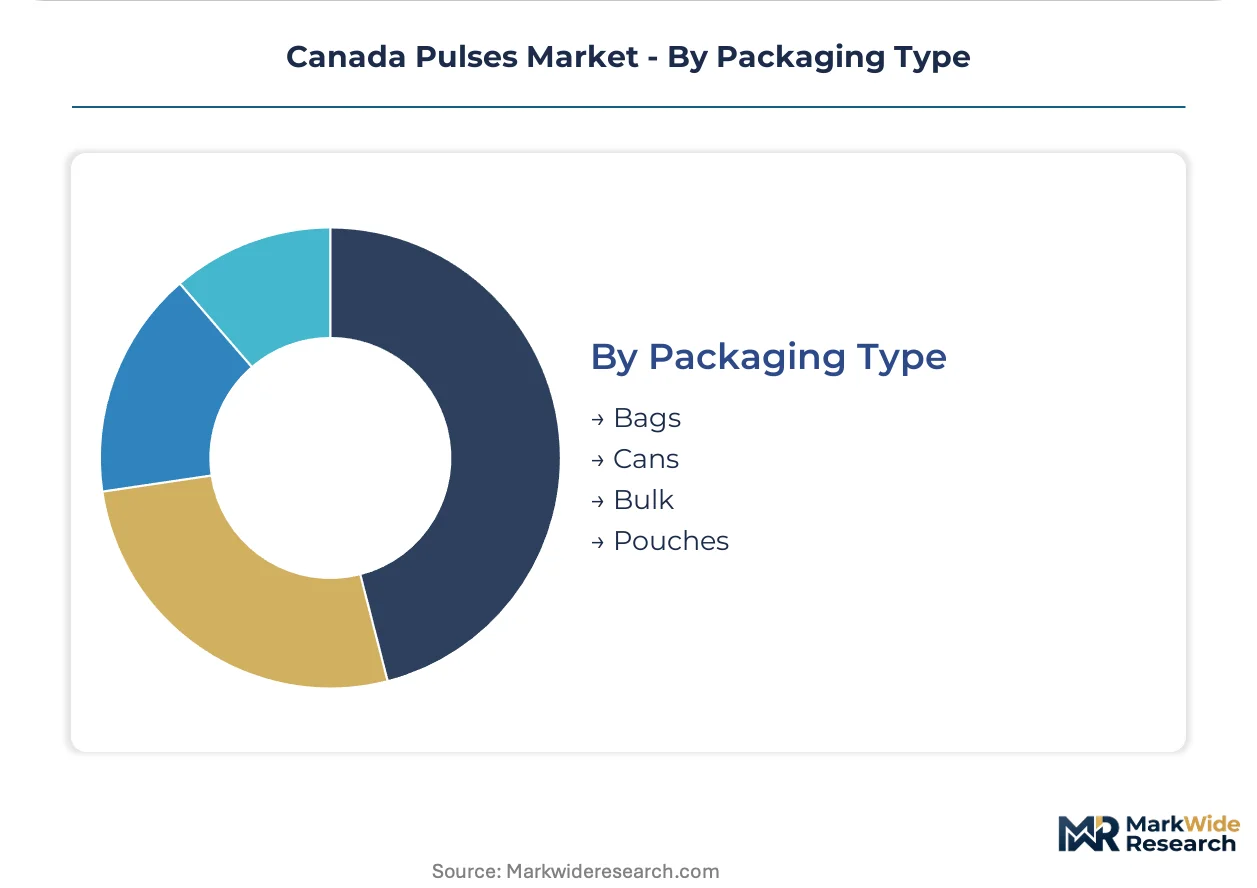
Packaging Type:
Packaging format signals quality tier and determines shelf-life extension, with material costs and recyclability regulations influencing processor selection.
- Bulk:Unpackaged shipments to ingredient processors and repackagers; minimizes per-unit cost but requires rigorous moisture control and contamination prevention during prairie elevator storage and rail transfer.
- Bags:Woven polypropylene sacks for foodservice and industrial buyers, with multi-wall paper alternatives for organic-certified product lines.
- Pouches:Stand-up and flat formats with reseal features for retail premium positioning; flexible packaging converters in Winnipeg and Calgary serve regional processor demand.
- Cans:Retort-processed ready-to-eat pulses for North American supermarket shelves; metal packaging costs and recycling infrastructure constraints limit growth relative to flexible alternatives.
Bulk leads on agricultural throughput; pouches gain share fastest on retail premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pulse cultivation in Canada traces its commercial roots to Saskatchewan's prairie settlement era, when immigrant farming communities established lentil and dry pea production systems adapted to semi-arid conditions. Federal research stations at Swift Current and Melfort developed early varieties that enabled export-scale output by the 1970s.
Saskatchewan
Red lentil and yellow pea acreage concentrates within the Brown and Dark Brown soil zones surrounding Regina and Saskatoon. CFIA's seed certification program governs varietal purity standards for export-bound shipments through the Canadian Grain Commission's binding grade schedules. The Regina processing corridor hosts multiple fractionation facilities converting prairie peas into protein isolates for North American plant-based food manufacturers.
Alberta
Field pea and faba bean production extends across the Peace River region and central parkland belt, with growers supplying both domestic feed mills and Asian export channels. Health Canada's novel food approval pathway regulates pulse protein ingredients entering Canadian consumer products. Lethbridge and Medicine Hat harbor underutilized processing infrastructure attracting brownfield investment for protein extraction capacity.
Manitoba
The Red River Valley specializes in identity-preserved handling systems supporting traceability requirements for European Union buyers facing deforestation regulation compliance deadlines. Provincial crop insurance programs administered through Manitoba Agricultural Services Corporation mitigate weather-related yield volatility for contracted acreage. Winnipeg-based packaging converters supply flexible pouch formats to regional processors serving domestic retail channels.
British Columbia
Container terminal capacity at Vancouver and Prince Rupert anchors export logistics for prairie-origin pulses destined for Indian, Turkish, and Chinese markets. Transport Canada regulations govern railcar allocation priorities between grain and containerized cargo moving through mountain corridor infrastructure. Lower Mainland food manufacturers source specialty chickpea and bean varieties from interior irrigated districts for ethnic food processing.
Canada Pulses Market Key Industry Players
Premium-margin players sit above commodity-margin players across ingredient-grade fractionation versus whole-pulse export channels. The competitive structure stratifies between vertically integrated processors controlling origination through extraction, regional commodity handlers with elevator networks, and multinational traders leveraging ocean freight scale. Three archetypes dominate: prairie-anchored fractionation specialists, global agribusiness trading houses, and identity-preserved logistics providers. Capacity expansion and backward integration into captive protein extraction represent the primary competitive vectors reshaping positioning.
Among North American agribusiness conglomerates, Archer Daniels Midland Company and Cargill Incorporated exemplify scale-driven trading and processing archetypes with continental origination networks. AGT Food and Ingredients occupies a position within the prairie-anchored specialist tier, representing vertically integrated control from Saskatchewan farm contracting through ingredient manufacturing. The Scoular Company anchors the regional commodity handling archetype with extensive elevator infrastructure across the prairie belt.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| The Scoular Company |
| AGT Food and Ingredients |
| Olam International |
| Ingredion Inc. |
| BroadGrain Commodities |
| Bunge Limited |
| Adani Wilmar |
| Cargill Incorporated |
| Others |
Cost & Logistics Intelligence
EU deforestation regulation traceability mandates gate qualified supply access for premium-tier pulse exports, forcing prairie processors to absorb identity-preserved handling costs or surrender EU market positioning to certified competitors. This sustainability compliance burden stratifies pricing power between traceability-equipped operators and commodity-grade handlers.
Pricing Analysis
Contract-based long-term offtake agreements dominate premium ingredient channels, separating identity-preserved pulses with protein-content guarantees from standard-grade elevator sales. Price differentiation hinges on CFIA certification tier and organic accreditation status. Cost compression in standard-grade commodity trade is intensifying because container freight volatility erodes export margins. Small-scale organic buyers exhibit highest price sensitivity; plant-based meat manufacturers show lowest sensitivity due to functionality requirements.
Supply Chain Analysis
Regional distribution centers in Regina and Saskatoon anchor hub-and-spoke patterns feeding Vancouver and Prince Rupert container terminals. Geographic supply concentration centers on Saskatchewan, Alberta, and Manitoba prairie belts. Raw material flows draw from certified seed stock, nitrogen-fixing crop rotations, and varietal-specific farm contracting. Single-origin concentration risk threatens resilience when drought hits Saskatchewan's Red River Valley. Distribution runs through vertically integrated processor networks and independent elevator cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada Pulses Market reads as a late-cycle quality story where ingredient-grade fractionation commands sustainable premiums. Buyer procurement is shifting toward protein digestibility-corrected amino acid scores as the definitive premium specification.
For Market Incumbents: Acquire brownfield protein extraction facilities in Lethbridge and Medicine Hat to preempt competitor capacity additions. Lock in multi-year varietal contracts with Saskatchewan growers before seed registration timelines compress available genetics. This defends margin position against wet-fractionation specialists entering from adjacent oilseed processing.
For New Entrants and Emerging Players: Launch via direct-to-subscription channels targeting heritage lentil varieties with small-lot provenance documentation. Alberta's underutilized processing infrastructure offers the most penetrable geography for brownfield pea-protein isolate production. Lead with pet food protein inclusion as the fastest path to offtake agreements with midwestern US manufacturers.
For Investors and Strategic Acquirers: Roll-up economics work for prairie-anchored fractionation specialists because ingredient-grade certification creates customer switching costs that commodity handlers cannot replicate. Long-term viability favors operators with captive origination and extraction assets. Watch CFIA seed varietal registration acceleration as the signal indicating competitive moat durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prairie Origination | Captive supply of identity-preserved yellow peas secures protein isolate feedstock for plant-based meat manufacturers. |
| Wet-Fractionation Capacity Buildout | Pea-protein isolate production in Alberta brownfield sites captures margin expansion from US Midwest dairy alternatives demand. |
| EU Traceability Certification Program | Geolocation documentation compliance defends European export access against pending deforestation regulation enforcement. |
| Pet Food Protein Supply Agreement | Pulse concentrate offtake contracts with midwestern US manufacturers diversify revenue beyond human food channels. |
| Direct-to-Consumer Heritage Launch | Subscription formats for small-lot lentils bypass wholesale margin compression and build brand equity in premium segments. |
Research Approach
Multiple input streams — processor production data, export customs records, and farm-level contracting disclosures — were reconciled against secondary validation from CFIA grading statistics and Canadian Grain Commission trade flows. Primary interviews with prairie elevator operators, ingredient procurement managers at plant-based food manufacturers, CFIA regulatory affairs specialists, and agricultural extension officers informed operational assumptions. Secondary sources included Statistics Canada crop production surveys, Health Canada novel food approval databases, and EU deforestation regulation implementation guidance. Bottom-up facility capacity modeling and top-down export value triangulation anchored volume estimates.
Data-stream reconciliation across the projection horizon applied segmentation dimensions of pulse variety, processing grade tier, and end-use application channel. CAGRs were derived from fitted trend analysis of historical production volumes and forward capacity expansion announcements. Industry-specific forecast inputs incorporated wet-fractionation yield curves and protein concentrate pricing spreads versus commodity whole-pulse benchmarks.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained drought conditions in Saskatchewan or accelerated EU traceability enforcement timelines. Outputs reflect documented assumptions regarding seed varietal adoption rates and fractionation technology deployment schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Bangladesh Rice Market
Grains
Europe Rice Market
Grains
Wheat Bran Market
Grains
South Africa Maize Market
Grains
White Beans Market
Grains
Soy Grits Market
Grains
Global Grain Analysis Market
Grains
Rye Market
Grains
Ancient and Specialty Grain Flour Market
Grains
00 Flour Market
Grains
Quinoa Flour Market
Grains
Global Grain Mill Products Market
Grains
China Wheat Protein Market
Grains
Wild Rice Market
Grains
Lentil Market
Grains
India Rice Market