
 Europe Scintillator Market | 2026-2036
Europe Scintillator Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Scintillator Market Intelligence
A shift from fragmented multi-source crystal procurement toward captive supply arrangements is consolidating among major European scintillator vendors. Saint-Gobain S.A. leverages its vertically integrated cerium-doped lutetium crystal production to anchor premium medical imaging contracts across France and Germany. Hamamatsu Photonics K.K. competes through sustained R&D intensity in silicon photomultiplier pairing technologies. Kromek Group specializes in cadmium zinc telluride alternatives for portable radiation detection units deployed by British emergency response agencies.
Scintillators are luminescent materials that convert ionizing radiation into detectable visible light through excitation and fluorescence decay, with critical performance parameters including light yield, energy resolution, and decay time constants measured in nanoseconds. Their primary commercial purpose centers on radiation quantification across medical diagnostics, nuclear safeguards, and particle physics instrumentation. Inorganic scintillators dominate high-value medical imaging installations where lutetium-based crystals command premium positioning due to superior stopping power and energy resolution. Organic and plastic scintillators occupy faster-growing niches in large-area homeland security portals and high-energy physics calorimeters where cost scalability outweighs absolute resolution requirements. Liquid scintillator solutions sustain specialized demand within research institutions conducting neutrino detection experiments.
The EU Medical Device Regulation and CE marking requirements enforced by national competent authorities shape product certification pathways for clinical scintillator deployments, while REACH compliance administered by ECHA governs restricted substance thresholds in crystal dopant chemistries. The F-Gas Regulation indirectly influences cooling system specifications for scintillator readout electronics in continental installations. Stakeholders must monitor evolving MDR technical documentation requirements and assess whether backward integration into raw crystal growth or forward integration into detector module assembly offers more defensible margin protection against regulatory compliance cost escalation.
Market Dynamics
The European scintillator market is consolidating around captive cerium-doped lutetium crystal supply chains as Saint-Gobain and Hamamatsu lock in premium medical imaging contracts through backward integration into raw material growth. This structural concentration is compressing procurement options for mid-tier detector assemblers while elevating compliance burdens under the EU Medical Device Regulation.
Growth Catalysts
- MDR Traceability Mandates:The EU Medical Device Regulation's material documentation requirements are filtering out non-compliant suppliers and concentrating volume among certified crystal growers.
- PET-CT Upgrade Cycles:German university hospitals are expanding scintillator procurement for molecular imaging infrastructure replacements.
- Homeland Security Screening:French and British border agencies are deploying large-area portal detectors for cargo and passenger inspection.
Market Restraints
- Lutetium Supply Concentration:Rare earth processing for lutetium-based crystals depends on a narrow supplier base concentrated outside Europe.
- REACH Dopant Restrictions:ECHA's evolving substance thresholds limit cerium and other activator chemistries in crystal formulations.
- Cadmium Zinc Telluride Substitution:CZT semiconductor detectors are capturing share in portable radiation detection for emergency response applications.
Strategic Opportunities
- Silicon Photomultiplier Convergence:Pairing solid-state SiPM readouts with fast organic scintillators opens compact medical imaging form factors.
- Eastern European Penetration:Polish and Romanian diagnostic centers remain undersupplied with premium lutetium crystal detector modules.
- F-Gas Cooling Retrofits:The EU F-Gas Regulation's phasedown timeline creates replacement demand for scintillator readout electronics thermal management systems.
Industry Challenges
- Crystal Growth Specialist Shortage:Czochralski and Bridgman furnace operation expertise is scarce across European manufacturing bases.
- CE Marking Timeline Compression:MDR technical documentation reviews by German BfArM and French ANSM are extending certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Scintillator Market |
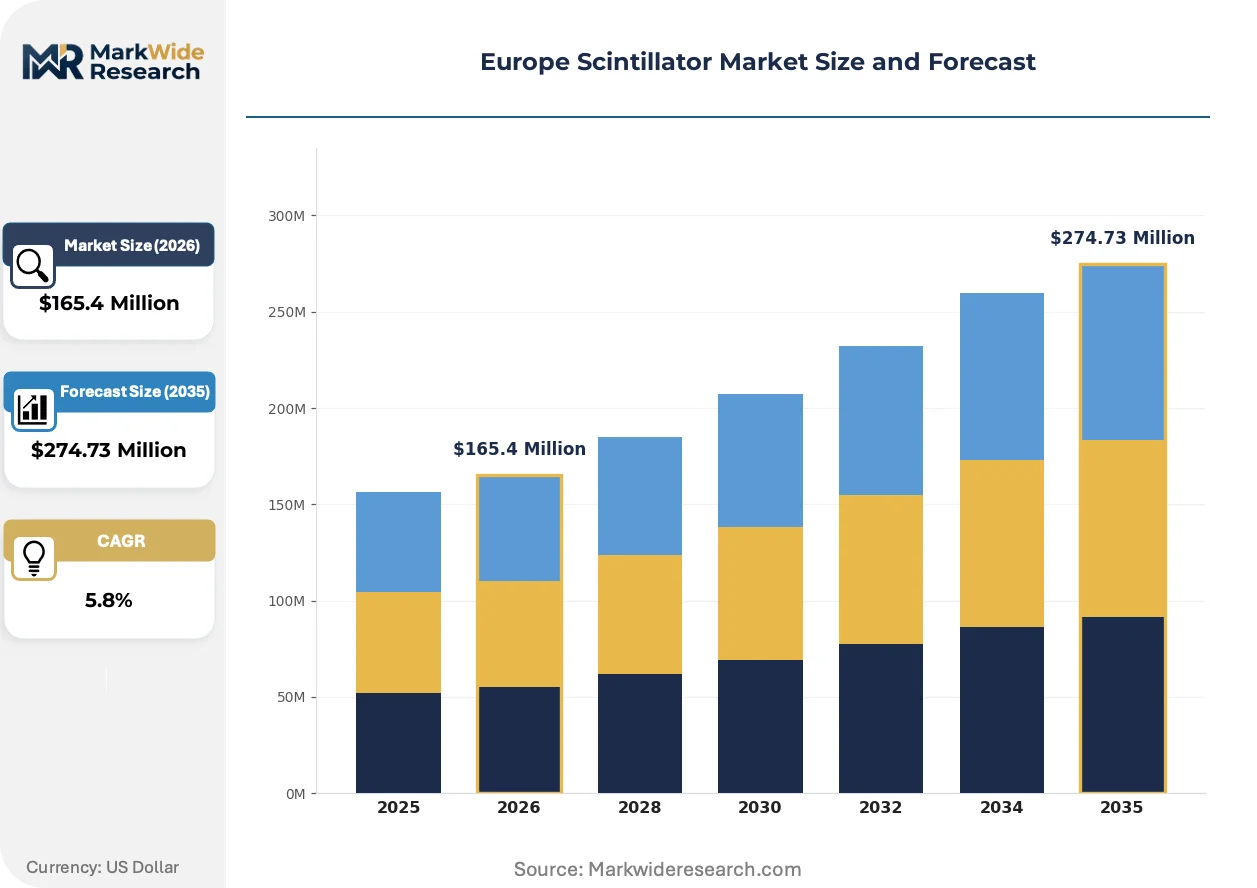
| Market Size in 2026 | $165.4 Million |
| Market Size in 2035 | $274.73 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Scintillators, Inorganic Scintillators, Plastic Scintillators, Liquid Scintillators End User: Healthcare Facilities, Research Institutions, Industrial Applications, Nuclear Power Plants Application: Medical Imaging, Radiation Detection, High Energy Physics, Homeland Security Form: Single Crystal, Polycrystalline, Powder, Solution |
| Companies Covered | Saint-Gobain S.A., Hamamatsu Photonics K.K., Dynasil Corporation of America, Hitachi High Tech Corporation, Mirion Technologies Inc., Rexon Components, Inc., Scintacor, Crytur, Kromek Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Scintillator Market Strategic Shifts & Innovations
Silicon photomultiplier pairing with fast-decay organic scintillators is unifying detection speed with solid-state reliability, compressing the traditional photomultiplier tube supply chain. This convergence is reshaping competitive positioning across medical imaging and portable detection segments.
Lutetium-yttrium oxyorthosilicate crystals doped with cerium are unifying high light yield with fast decay constants for time-of-flight PET systems. Siemens Healthineers and Philips are integrating these crystals into next-generation molecular imaging platforms. The technology is unifying detector performance tiers that previously required separate crystal formulations.
REACH compliance administered by ECHA is tightening restricted substance thresholds in scintillator dopant chemistries. Manufacturers are reformulating activator concentrations and exploring alternative rare earth elements. Medical imaging crystal suppliers face the steepest reformulation costs due to MDR material traceability requirements.
Hospital procurement departments are consolidating scintillator contracts under multi-year detector module supply agreements. This behavior is displacing spot-market crystal purchases and compressing vendor margins. German university hospital networks are pioneering this shift through centralized purchasing consortia.
Europe Scintillator Market Segmentation
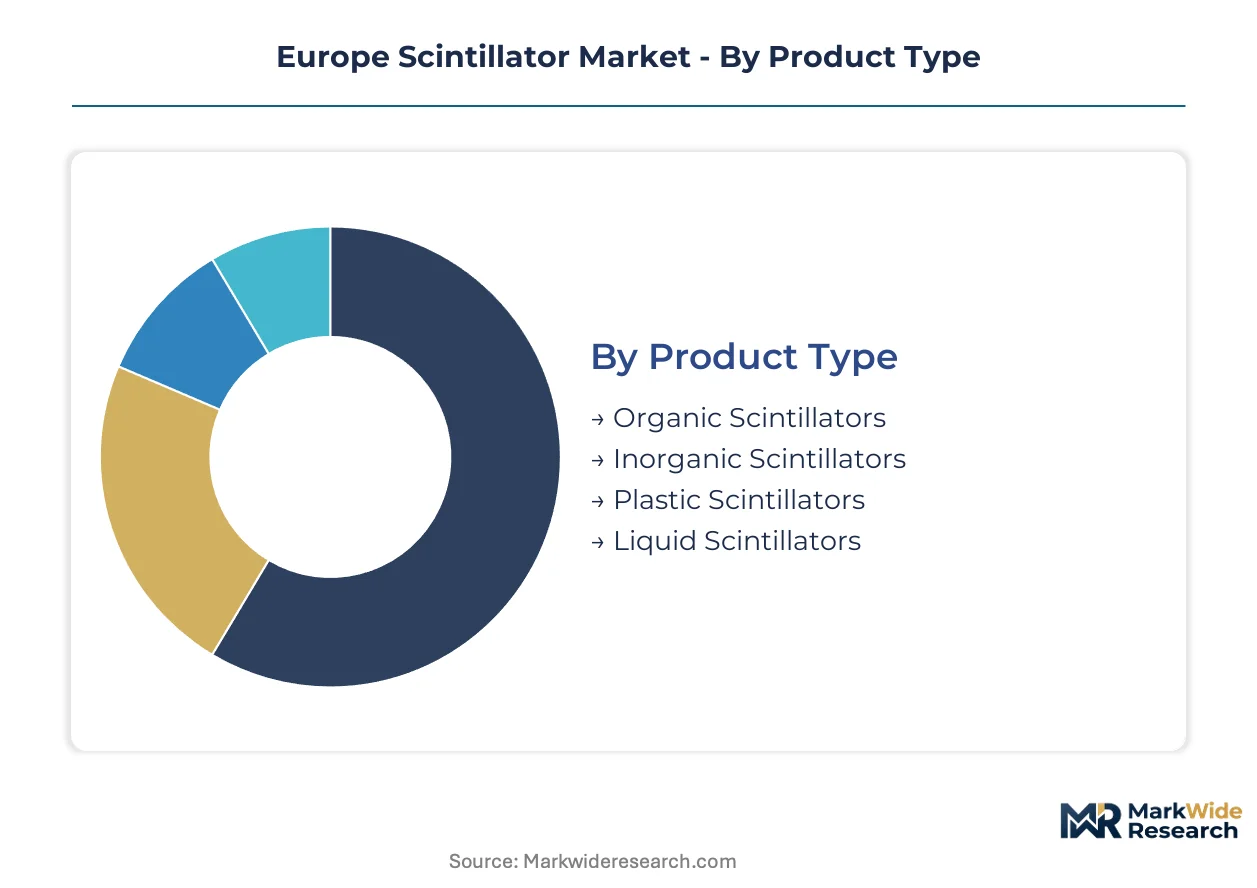
Scintillator procurement across Europe fragments sharply by certification burden, with MDR traceability requirements filtering supplier eligibility for clinical segments while industrial applications face lighter CE marking pathways. Understanding where regulatory thresholds concentrate margin pressure clarifies why certain product categories command premium positioning.
Product Type:
MDR material documentation requirements fall heaviest on inorganic crystal formulations deployed in clinical settings, while organic and plastic variants navigate simpler conformity assessment routes for non-medical applications.
- Inorganic Scintillators:Lutetium-based crystals doped with cerium deliver superior stopping power and energy resolution for time-of-flight PET systems. German university hospitals concentrate procurement for molecular imaging upgrades, though REACH dopant restrictions from ECHA are forcing activator reformulations that elevate compliance costs.
- Organic Scintillators:These fast-decay compounds pair with silicon photomultiplier readouts to enable compact medical imaging form factors. French and British homeland security agencies are deploying large-area portal configurations for cargo screening, where detection speed outweighs absolute resolution requirements.
- Plastic Scintillators:Cost-scalable formulations serve high-energy physics calorimeters and budget-constrained radiation portals across Eastern European research centers.
- Liquid Scintillators:Specialized solutions sustain neutrino detection experiments at CERN and select Italian physics institutes.
Leading the category by volume: Inorganic Scintillators. Growing fastest: Organic Scintillators.
End User:
Procurement scale and contract duration diverge dramatically across customer types, with hospital networks consolidating multi-year supply agreements while research institutions retain spot-market flexibility.
- Healthcare Facilities:German university hospital networks are pioneering centralized purchasing consortia that displace fragmented crystal sourcing. MDR technical documentation reviewed by BfArM and ANSM extends certification timelines, concentrating volume among pre-qualified vendors.
- Homeland Security:French and British border agencies deploy large-area portal detectors for passenger and cargo inspection, with procurement flowing through defense-adjacent procurement frameworks.
- Research Institutions:CERN and Italian neutrino physics programs sustain specialized liquid scintillator demand outside commercial volume tiers.
- Nuclear Power Plants:French and Finnish operators maintain steady radiation monitoring procurement through utility-specific supply chains.
Healthcare Facilities dominate absolute spend. Homeland Security procurement is expanding most quickly.
Application:
Performance specifications and price tolerance stratify by use case, with medical imaging tolerating premium crystal costs for resolution gains while security applications prioritize cost scalability across detector area.
- Medical Imaging:Time-of-flight PET systems from Siemens Healthineers and Philips integrate cerium-doped lutetium-yttrium oxyorthosilicate crystals. German diagnostic centers anchor regional demand for molecular imaging infrastructure replacements.
- Homeland Security:Large-area portal deployments across French and British border crossings favor plastic and organic scintillators where detection speed matters more than energy resolution.
- Radiation Detection:British emergency response agencies are procuring portable units from Kromek Group featuring cadmium zinc telluride alternatives to traditional scintillator formulations.
- High Energy Physics:CERN calorimeter installations and Italian neutrino experiments sustain niche liquid and plastic scintillator procurement outside commercial pricing tiers.
Medical Imaging leads by revenue concentration. Homeland Security applications are gaining share fastest.
Form:
Manufacturing complexity and unit economics separate single-crystal premium positioning from powder and solution alternatives serving cost-sensitive or experimental niches.
- Single Crystal:Czochralski-grown lutetium formulations command premium placement in time-of-flight PET systems. Saint-Gobain's vertically integrated cerium-doped production anchors supply for French and German medical imaging contracts.
- Polycrystalline:Lower-cost ceramic formulations serve industrial radiation monitoring where energy resolution thresholds relax.
- Powder:Bulk activator materials feed captive crystal growth operations and specialized research formulations.
- Solution:Liquid scintillator cocktails sustain neutrino detection and environmental radioassay applications at CERN and select Italian research stations.
Single Crystal forms dominate premium contract value. Polycrystalline alternatives are climbing fastest in industrial penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lutetium supply routes through Chinese rare earth processors constrain crystal growth capacity across European manufacturing bases. German university hospitals anchor medical imaging demand. French and British border agencies drive security screening procurement.
Germany
University hospital networks in Munich and Heidelberg are consolidating PET-CT upgrade contracts under centralized purchasing consortia. BfArM reviews of MDR technical documentation are extending certification timelines for scintillator module suppliers. The Baden-Württemberg industrial corridor hosts precision optics clusters serving detector readout electronics.
France
ANSM enforcement of material traceability requirements is filtering non-compliant crystal suppliers from clinical procurement channels. Saint-Gobain's vertically integrated cerium-doped lutetium production anchors premium medical imaging contracts across the Île-de-France region. French border agencies are deploying large-area portal detectors at Channel tunnel crossings.
United Kingdom
British emergency response agencies are procuring portable radiation detection units featuring cadmium zinc telluride alternatives to traditional scintillator formulations. The UK Home Office frameworks govern homeland security screening procurement for cargo and passenger inspection. Oxfordshire research clusters sustain specialized liquid scintillator demand for neutrino physics programs.
Italy
Gran Sasso National Laboratory and select physics institutes maintain niche procurement of liquid scintillator cocktails for underground neutrino detection experiments. Italian regulators apply CE marking pathways for research instrumentation that bypass MDR clinical certification burdens. The Milan-Turin industrial axis supports precision manufacturing of detector housing assemblies.
Poland
Diagnostic centers in Warsaw and Krakow remain undersupplied with premium lutetium crystal detector modules relative to Western European infrastructure density. Polish medical device distributors are bridging supply gaps through German and French vendor relationships. The Lower Silesian manufacturing zone is emerging as a cost-competitive location for detector module assembly operations.
Europe Scintillator Market Key Industry Players
Global majors compete with regional champions across certification-heavy clinical segments and lighter-touch industrial applications. The vendor base stratifies into three tiers: vertically integrated crystal growers commanding premium medical contracts, specialized detector assemblers serving mid-market radiation monitoring, and research-focused boutiques capturing niche physics instrumentation. Dominant competitive moves include backward integration into raw material growth and forward integration into detector module assembly.
Within the integrated-manufacturer tier, Saint-Gobain S.A. and Hamamatsu Photonics K.K. represent contrasting geographic anchors for European supply security. Kromek Group occupies a position among British-based specialists in alternative semiconductor detection technologies. These three exemplify how competitive positioning diverges between crystal-centric and solid-state readout approaches.
| Leading Market Players |
|---|
| Saint-Gobain S.A. |
| Hamamatsu Photonics K.K. |
| Dynasil Corporation of America |
| Hitachi High Tech Corporation |
| Mirion Technologies Inc. |
| Rexon Components, Inc. |
| Scintacor |
| Crytur |
| Kromek Group |
| Others |
Cost & Logistics Intelligence
Rare earth oxide price indices for lutetium feedstock cascade through European crystal growth operations into three distinct procurement tiers, with MDR-compliant medical-grade crystals commanding substantial premiums over industrial radiation monitoring formulations. German hospital purchasing consortia leverage volume aggregation to compress unit costs, while spot-market buyers in Eastern European diagnostic centers absorb elevated pricing from fragmented sourcing.
Pricing Analysis
Warranty and calibration service bundling separates premium detector module contracts from unbundled crystal-only transactions, with multi-year technical support agreements adding fifteen to twenty-five percent to base hardware pricing. Three-tier pricing structure across MDR-certified, CE-marked industrial, and uncertified research grades reflects certification investment recovery timelines. Pricing pressure stems from CZT semiconductor substitution in portable detection segments, squeezing mid-tier scintillator margins. Hospital procurement committees demonstrate lowest price sensitivity due to reimbursement-protected capital budgets, while Eastern European distributors face acute cost compression from budget-constrained public health systems.
Supply Chain Analysis
Lutetium oxide supply rests on Chinese rare earth separation facilities and limited Malaysian processing capacity, creating geographic concentration risk for European crystal growers dependent on high-purity feedstock. Czochralski furnace components draw from German precision engineering clusters and Japanese thermal management specialists. Single-source vulnerability in cerium activator supply from Chinese refiners threatens formulation continuity under REACH substance restrictions. Distribution runs through Saint-Gobain's captive vertical network for premium medical contracts, while mid-tier detector assemblers source through independent crystal distributors with elongated lead times.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe scintillator market functions as a cost-of-compliance arena where MDR material traceability requirements erect formidable barrier-to-entry moats, concentrating volume among pre-certified crystal growers and filtering speculative entrants from clinical procurement channels.
For Market Incumbents: Deploy backward integration into cerium-doped lutetium crystal growth to anchor supply security against Chinese rare earth export volatility. Incumbents should consolidate hospital purchasing consortia relationships through dedicated technical documentation support teams that compress BfArM and ANSM certification timelines. CZT semiconductor encroachment in portable detection demands accelerated SiPM pairing R&D to defend detector module attach rates. For New Entrants and Emerging Players: The premium-to-economy price gap in Eastern European diagnostic infrastructure offers viable entry positioning for mid-tier crystal suppliers willing to navigate extended CE marking pathways outside MDR jurisdiction. Polish and Romanian radiation monitoring installations remain undersupplied relative to Western European density, presenting white-space capture opportunities through distributor partnership models rather than direct hospital contracting. Target research institution spot procurement for liquid scintillator formulations where regulatory burden relaxes and technical specifications favor boutique supply. For Investors and Strategic Acquirers: The window for entry favors crystal growth specialists with demonstrated Czochralski furnace operational expertise and established ECHA compliance track records. Long-term viability hinges on supply security architecture that transcends Chinese rare earth dependency through alternative feedstock arrangements or recycling infrastructure. Watch lutetium oxide spot price volatility as the primary inflection signal for margin compression risk across the value chain.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Processing | Captive lutetium supply from Malaysian separation facilities insulates Saint-Gobain against Chinese export quota volatility. |
| MDR Technical Documentation Investment | Pre-qualified status with BfArM and ANSM unlocks German and French hospital network procurement volumes. |
| SiPM Pairing Technology Development | Hamamatsu's solid-state readout convergence compresses traditional photomultiplier tube supply chain dependencies. |
| Eastern European Distribution Partnership | Polish medical device distributors bridge supply gaps for undersupplied Warsaw and Krakow diagnostic centers. |
| CZT Alternative Detector Portfolio | Kromek Group's semiconductor radiation detection captures British emergency response procurement outside crystal formulations. |
Research Approach
Independent corroboration across crystal growth facility technical directors, hospital biomedical engineering procurement leads, and ECHA regulatory affairs specialists underwrites the qualitative findings on compliance cost structures. Primary interviews with detector module assembly operations managers, GPO contracts administrators at German university hospital networks, and homeland security screening equipment program officers informed supply chain concentration assessments. Secondary validation drew from EMA MDR guidance documents, ECHA REACH substance restriction updates, customs trade data on rare earth oxide imports, and SEC filings of publicly traded scintillator vendors. Bottom-up crystal volume estimates triangulated against top-down medical imaging equipment installation forecasts.
Rate-of-change decomposition across the analysis window isolates volume drivers by product type, end-user segment, application, and geographic adoption cluster. Segmentation modeling incorporated inorganic versus organic scintillator chemistry splits, healthcare facility versus homeland security procurement channels, medical imaging versus radiation detection applications, and single-crystal versus polycrystalline form factors. CAGRs derive from fitted growth curves applied to base-year market sizing, with cross-checks against PET-CT upgrade cycle timing and border security infrastructure deployment schedules.
Inputs from ECHA substance restriction consultations and BfArM MDR technical documentation review timelines were available through the study window; gaps in proprietary crystal growth yield data and hospital purchasing consortia contract terms introduce uncertainty bands around volume concentration estimates. Forecasts reflect assumptions on lutetium oxide supply continuity and REACH dopant threshold evolution that regulatory shifts could materially revise. A small set of triggers—Chinese rare earth export policy, MDR audit intensity fluctuations, and CZT cost-performance improvements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Modulators Market
Optical Components
Optical Transceiver Market
Optical Components
Flexible Glass for Flexible Electronics Market
Optical Components
Optical Fiber and Plastic Conduit Market
Optical Components
Asia-Pacific Tunable Laser Market
Optical Components
Global Optical Diode Market
Optical Components
CMP Polishing Machine Market
Optical Components
Laser Photomask Market
Optical Components
Ring Panel Filters Market
Optical Components
Machine Vision Light Source Market
Optical Components
Optical Time-Domain Reflectometer Market
Optical Components
High Power Double-Clad Fiber Bragg Grating Market
Optical Components
UAE Lithium Niobate Modulator Market
Optical Components
Global Non Dispersive Infrared (NDIR) Market
Optical Components
Photosensitive Glass Market
Optical Components
Electro Optical System Market