
 Vision Processing Unit Market | 2026-2036
Vision Processing Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Vision Processing Unit Market Analysis
Semiconductor distribution through tier-one electronics manufacturing service providers is reconfiguring as automotive and robotics OEMs demand direct VPU sourcing relationships. NVIDIA Corporation leverages its CUDA software ecosystem to sustain design-in loyalty across autonomous vehicle programs. Intel Corporation anchors x86-adjacent vision workloads through its Movidius product line in industrial camera deployments. Qualcomm Technologies competes on power-efficiency metrics for battery-constrained robotics and drone platforms.
A vision processing unit is a dedicated microprocessor architected to accelerate computer vision and image processing workloads through parallel vector operations, typically achieving multiple tera-operations per second while maintaining sub-10-watt thermal envelopes for edge deployment. The device integrates ISP pipelines, neural network accelerators, and memory subsystems to execute real-time object detection, segmentation, and depth estimation in industrial and mobility contexts. Embedded vision processors command the largest revenue share due to their integration into camera modules and sensor hubs, while AI-driven vision technology captures the fastest expansion as transformer-based architectures displace convolutional networks in accuracy-critical applications. Automotive imaging applications concentrate margin pools where functional safety certification under ISO 26262 creates qualification barriers.
FDA scrutiny of AI-enabled diagnostic imaging in the United States elevates VPU traceability requirements for healthcare device submissions, while EMA parallel guidance on machine-learning-based medical devices shapes European procurement specifications. China's NMPA and MIIT coordinate GB standards for intelligent vehicle camera systems, mandating domestic testing protocols that influence supplier qualification. Stakeholders must monitor how jurisdictional divergence in AI hardware certification fragments platform development roadmaps and inflates compliance staffing.
Market Dynamics
Transformer-based vision architectures are compressing qualification cycles for automotive VPUs while fragmenting software ecosystems around proprietary inference frameworks. This architectural shift forces silicon vendors to recalibrate IP roadmaps against ISO 26262 functional safety timelines.
Growth Catalysts
- EU AI Act Conformity Assessments:Mandatory third-party evaluation of high-risk AI systems is accelerating certified VPU procurement for medical imaging and autonomous mobility in Germany and France.
- Edge AI Inference Localization:Data sovereignty requirements in China's Yangtze River Delta electronics corridor are mandating on-device processing for surveillance and industrial quality inspection.
- Neural Network Accelerator Integration:Dedicated NPU blocks within camera modules are enabling real-time depth estimation for warehouse robotics without host processor dependency.
Market Restraints
- Advanced Node Wafer Allocation:Sub-7nm fabrication capacity concentration at TSMC creates allocation risk for automotive-grade VPU tape-outs during consumer electronics demand spikes.
- ISO 26262 Certification Burden:ASIL-D qualification timelines extending 18-24 months delay revenue recognition for new automotive vision processor entrants.
- GPU-NPU Substitution Pressure:Discrete AI accelerators in data center training workloads are capturing silicon R&D investment that might otherwise flow to edge vision silicon.
Strategic Opportunities
- India PLI Scheme for Electronics:Production-linked incentives for semiconductor assembly and testing are attracting VPU packaging investments in Gujarat and Tamil Nadu.
- Event-Based Vision Sensing:Integration of dynamic vision sensors with conventional frame-based pipelines opens neuromorphic processing applications for drone collision avoidance.
- Direct OEM Sourcing:Automotive manufacturers in Japan are bypassing tier-one EMS providers to negotiate long-term VPU supply agreements with silicon vendors.
Industry Challenges
- Functional Safety Talent Scarcity:ASIL-qualified verification engineers command 40-60% salary premiums, constraining European and Japanese VPU design team scaling.
- Legacy Camera Interface Migration:MIPI CSI-2 to MIPI CSI-3 transition requires simultaneous sensor hub and VPU redesign, complicating platform refresh cycles for industrial camera OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vision Processing Unit Market |
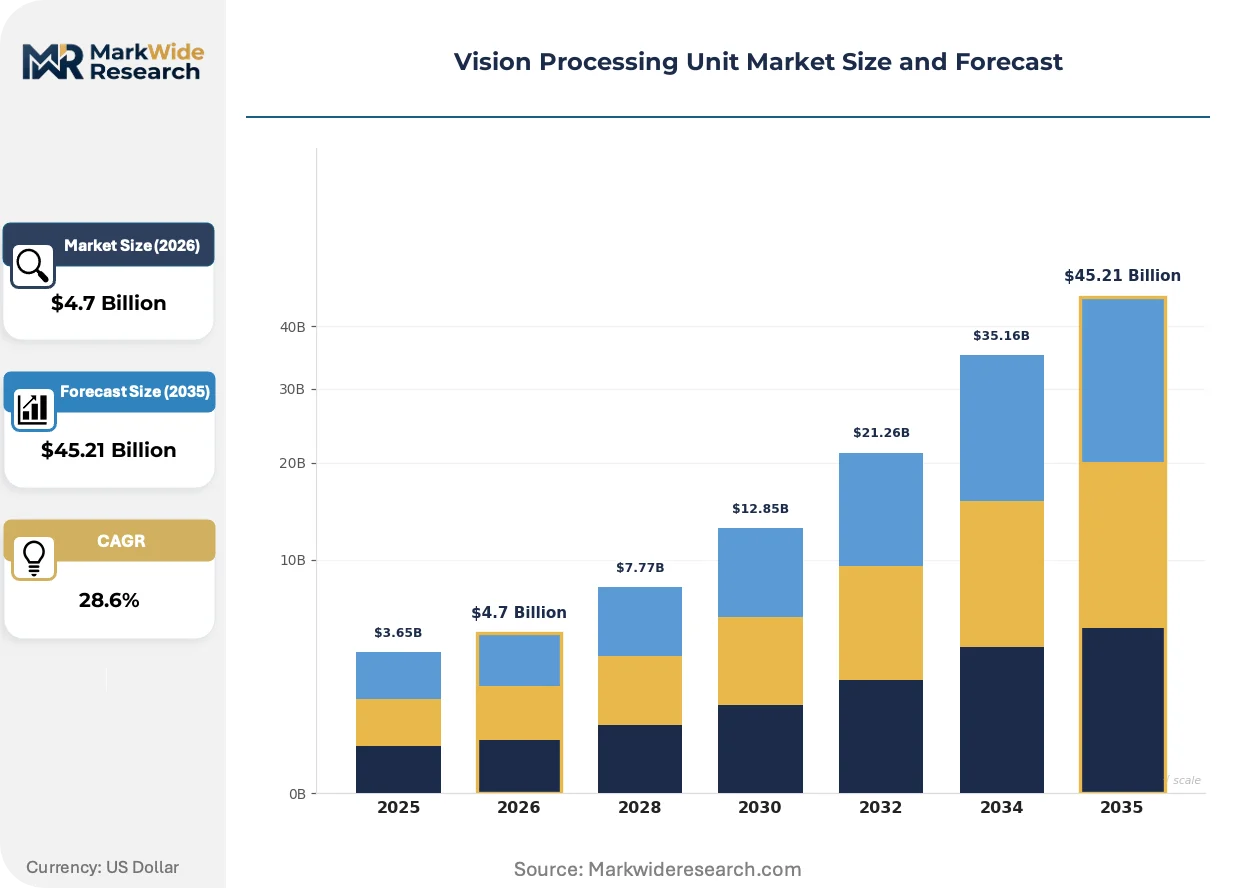
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $45.21 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Vision Processors, Standalone Processors, ASICs, FPGAs Application: Surveillance, Robotics, Automotive Imaging, Machine Vision End User: Healthcare, Automotive, Industrial Automation, Consumer Electronics Technology: AI-Driven Vision, Image Recognition, Computer Vision, Optical Flow |
| Companies Covered | Intel Corporation, NVIDIA Corporation, Qualcomm Technologies, Texas Instruments, Samsung Electronics, MediaTek, CEVA, Cadence Design Systems, Ambarella, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vision Processing Unit Market Emerging Trajectories
Vision processor architectures are fragmenting around divergent inference frameworks as transformer models displace convolutional networks in accuracy-critical deployments. This shift is compressing hardware-software co-design cycles and forcing new certification strategies.
Transformer-based attention mechanisms are migrating from natural language processing into computer vision workloads, enabling unified multimodal perception for autonomous driving systems. Automotive Tier-1 suppliers in Germany and Japan are adopting these architectures for lane-keeping and pedestrian prediction. The technology is migrating from research environments into pre-production vehicle programs, collapsing the traditional 3-5 year silicon qualification window.
The EU AI Act's risk-based classification system is mandating conformity assessments for high-risk computer vision applications in medical diagnostics and mobility. Device manufacturers must demonstrate traceability across training data, model versioning, and hardware inference logs. European healthcare OEMs are responding by embedding VPU selection criteria directly into procurement specifications, favoring vendors with pre-certified toolchains.
Automotive and robotics OEMs are consolidating VPU sourcing through direct silicon vendor relationships, disintermediating traditional electronics manufacturing service providers. This channel compression is most visible in Germany's automotive supply chain, where Mercedes-Benz and BMW have established dedicated semiconductor procurement offices. The shift is forcing EMS providers to reposition around system integration and thermal management services rather than component distribution.
Vision Processing Unit Market Segmentation
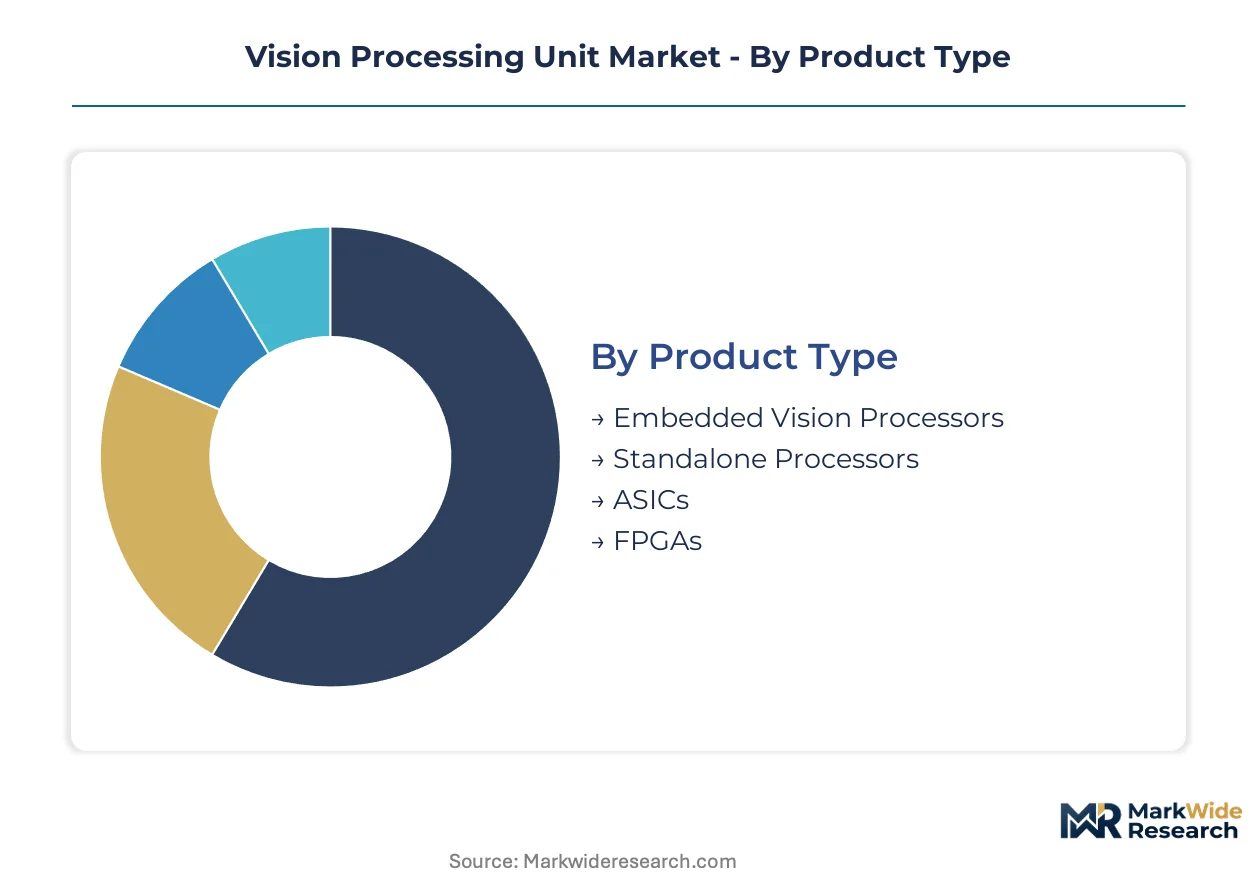
Vision processing unit architectures diverge sharply by deployment context, thermal constraints, and software ecosystem lock-in. Segmentation reveals where silicon vendors concentrate R&D investment versus where margin pools attract new entrants.
Product Type:
Mature packaged solutions dominate automotive qualification pipelines, while emerging discrete accelerators capture robotics prototyping cycles.
- Embedded Vision Processors:These system-on-chip designs integrate ISP pipelines, neural network accelerators, and memory controllers into camera modules and sensor hubs. Automotive OEMs in Germany and Japan specify these for lane-keeping and pedestrian detection systems where ISO 26262 ASIL-B certification gates procurement.
- ASICs:Application-specific integrated circuits deliver deterministic latency for industrial quality inspection lines in China's Yangtze River Delta manufacturing corridor. NMPA and MIIT GB standards for intelligent vehicle camera systems are accelerating domestic ASIC qualification timelines.
- Standalone Processors:Discrete VPUs with dedicated thermal solutions serve high-frame-rate machine vision applications.
- FPGAs:Field-programmable gate arrays enable algorithm reconfiguration for research environments and prototype validation.
Embedded vision processors handle the majority of throughput; ASICs are climbing the fastest on share as automotive programs freeze architectures.
Application:
Cost tier stratification separates safety-critical automotive deployments from price-sensitive surveillance integrations.
- Automotive Imaging:Functional safety certification under ISO 26262 creates 18-24 month qualification barriers that concentrate margin pools among incumbent silicon vendors. Mercedes-Benz and BMW procurement offices in Germany negotiate direct supply agreements bypassing traditional EMS distribution.
- Robotics:Warehouse automation and drone platforms demand sub-10-watt thermal envelopes with real-time depth estimation capabilities. EU AI Act conformity assessments for high-risk autonomous systems are tightening processor traceability requirements in France and Germany.
- Surveillance:China's data sovereignty mandates in the Yangtze River Delta electronics corridor require on-device processing for facial recognition and crowd analytics.
- Machine Vision:Industrial camera deployments favor x86-adjacent architectures for compatibility with existing quality control software stacks.
Automotive imaging commands premium pricing tiers; robotics is expanding most quickly as transformer architectures compress hardware-software co-design cycles.
End User:
Customer type determines certification burden, with regulated medical and automotive verticals imposing documentation requirements that consumer electronics bypass.
- Automotive:Tier-1 suppliers in Germany and Japan are consolidating VPU sourcing through direct silicon vendor relationships, disintermediating electronics manufacturing service providers. KBA type approval processes and METI technical standards shape procurement specifications.
- Healthcare:FDA scrutiny of AI-enabled diagnostic imaging elevates VPU traceability requirements for device submissions, while EMA parallel guidance on machine-learning-based medical devices shapes European procurement. Embedded vision processors with pre-certified toolchains capture specification advantages.
- Industrial Automation:Factory floor deployments prioritize deterministic latency over neural network flexibility.
- Consumer Electronics:Battery-constrained smartphones and AR glasses drive power-efficiency optimization at the expense of functional safety documentation.
Automotive end users generate the largest revenue concentration; healthcare is gaining share fastest as diagnostic imaging AI attracts venture deployment.
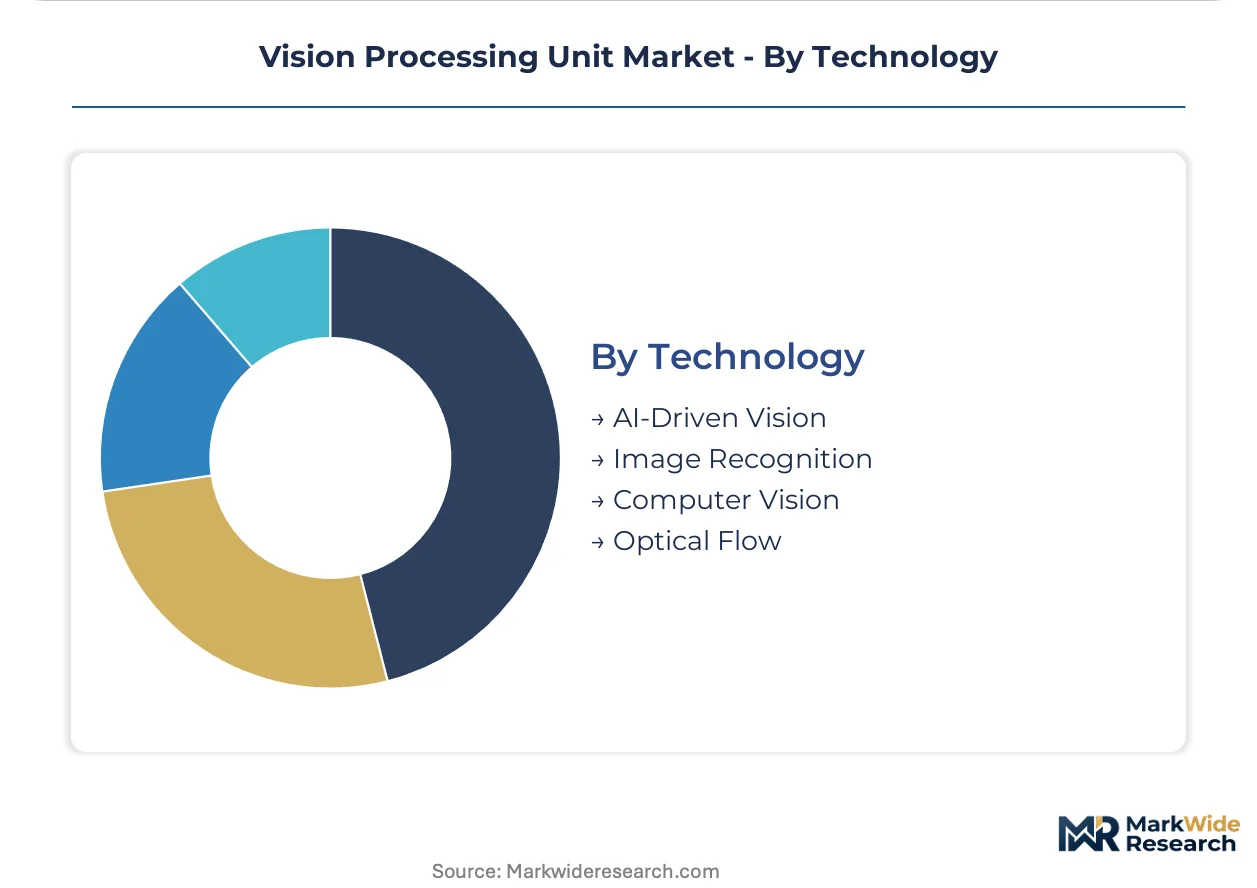
Technology:
Volume concentration follows inference framework standardization, with proprietary software ecosystems creating switching costs that fragment platform development.
- AI-Driven Vision:Transformer-based attention mechanisms are displacing convolutional networks in accuracy-critical deployments, collapsing traditional 3-5 year silicon qualification windows. NVIDIA's CUDA software ecosystem sustains design-in loyalty across autonomous vehicle programs.
- Computer Vision:Established algorithm libraries and OpenCV compatibility anchor industrial camera and surveillance deployments where migration costs exceed performance gains from neural approaches.
- Image Recognition:Classical feature extraction methods persist in resource-constrained edge devices.
- Optical Flow:Motion estimation algorithms enable drone collision avoidance and gesture recognition without full scene understanding.
Computer vision handles legacy deployment volume; AI-driven vision shows the steepest expansion trajectory as attention mechanisms migrate from natural language processing into perception workloads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes and functional safety mandates are redrawing VPU procurement geography. Direct OEM-silicon vendor relationships now bypass traditional distribution channels in automotive-heavy economies.
China
Yangtze River Delta electronics clusters drive embedded vision processor demand for surveillance and industrial inspection. NMPA and MIIT coordinate GB standards mandating domestic testing protocols for intelligent vehicle camera systems. Shanghai and Suzhou manufacturing corridors concentrate ASIC tape-out activity for automotive Tier-1 suppliers.
Germany
Mercedes-Benz and BMW procurement offices negotiate direct VPU supply agreements, disintermediating EMS providers. KBA type approval processes under EU AI Act conformity assessments tighten processor traceability for autonomous driving systems. Bavaria and Baden-Württemberg host functional safety engineering talent pools supporting ASIL-D qualification pipelines.
United States
FDA scrutiny of AI-enabled diagnostic imaging elevates VPU traceability requirements for healthcare device submissions. NHTSA autonomous vehicle guidance shapes pre-certification roadmaps for automotive vision silicon. Michigan and California automotive design centers anchor North American demand for ISO 26262-qualified processors.
Japan
Automotive OEMs expand VPU procurement for lane-keeping and pedestrian prediction systems. METI technical standards and PMDA parallel guidance on machine-learning devices influence supplier qualification timelines. Nagoya and Tokyo metropolitan areas concentrate robotics vision deployment for warehouse automation platforms.
India
PLI scheme incentives for semiconductor assembly and testing attract VPU packaging investments in Gujarat and Tamil Nadu. CDSCO emerging guidance on AI-based medical devices shapes diagnostic imaging procurement specifications. Bengaluru and Hyderabad electronics corridors develop embedded vision capabilities for drone and robotics OEMs.
Vision Processing Unit Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. CUDA software ecosystems and x86-adjacent architectures create switching costs that fragment platform development. Dominant archetypes include full-stack silicon vendors, specialized neural network accelerator designers, and industrial camera module integrators. Competitive moves concentrate on direct OEM sourcing relationships and functional safety certification pre-positioning.
Within the full-stack tier, NVIDIA Corporation and Intel Corporation anchor contrasting software ecosystems for autonomous vehicle and industrial deployments. Qualcomm Technologies occupies a position emphasizing power-efficiency metrics for battery-constrained platforms. These three exemplify how proprietary inference frameworks are compressing hardware-software co-design cycles across automotive and robotics verticals.
| Leading Market Players |
|---|
| Intel Corporation |
| NVIDIA Corporation |
| Qualcomm Technologies |
| Texas Instruments |
| Samsung Electronics |
| MediaTek |
| CEVA |
| Cadence Design Systems |
| Ambarella |
| Others |
Supply Flow & Price Mechanics
TSMC's Hsinchu Science Park fabrication complex anchors wafer allocation dynamics that cascade through automotive VPU pricing tiers, concentrating margin pressure on fabless entrants during consumer electronics demand spikes. Sub-7nm capacity constraints at this node translate directly into 18-24 month lead time premiums for ASIL-D qualified silicon, compressing procurement flexibility for German and Japanese OEMs.
Pricing Analysis
Certification level creates the primary spread between automotive-grade and industrial-tier VPUs. Three-tier pricing structure across ASIL-D automotive, ASIL-B industrial, and uncertified commercial levels reflects ISO 26262 qualification investment recovery. Cost compression in the commercial surveillance tier intensifies because Chinese domestic suppliers are flooding Yangtze River Delta corridors with unqualified alternatives. Robotics OEMs demonstrate highest price sensitivity due to battery-constrained BOM budgets, while healthcare device manufacturers absorb premiums for FDA-traceable supply chains.
Supply Chain Analysis
Advanced node silicon feedstock draws from Taiwan, South Korea, and the United States in roughly descending volume order. EUV lithography equipment, advanced packaging substrates, and high-bandwidth memory constitute critical input dependencies. Single-source vulnerability concentrates at TSMC for sub-7nm automotive tape-outs, creating allocation risk during smartphone SoC demand surges. Distribution runs through direct OEM procurement offices in Germany and Japan, bypassing traditional EMS tier-one distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
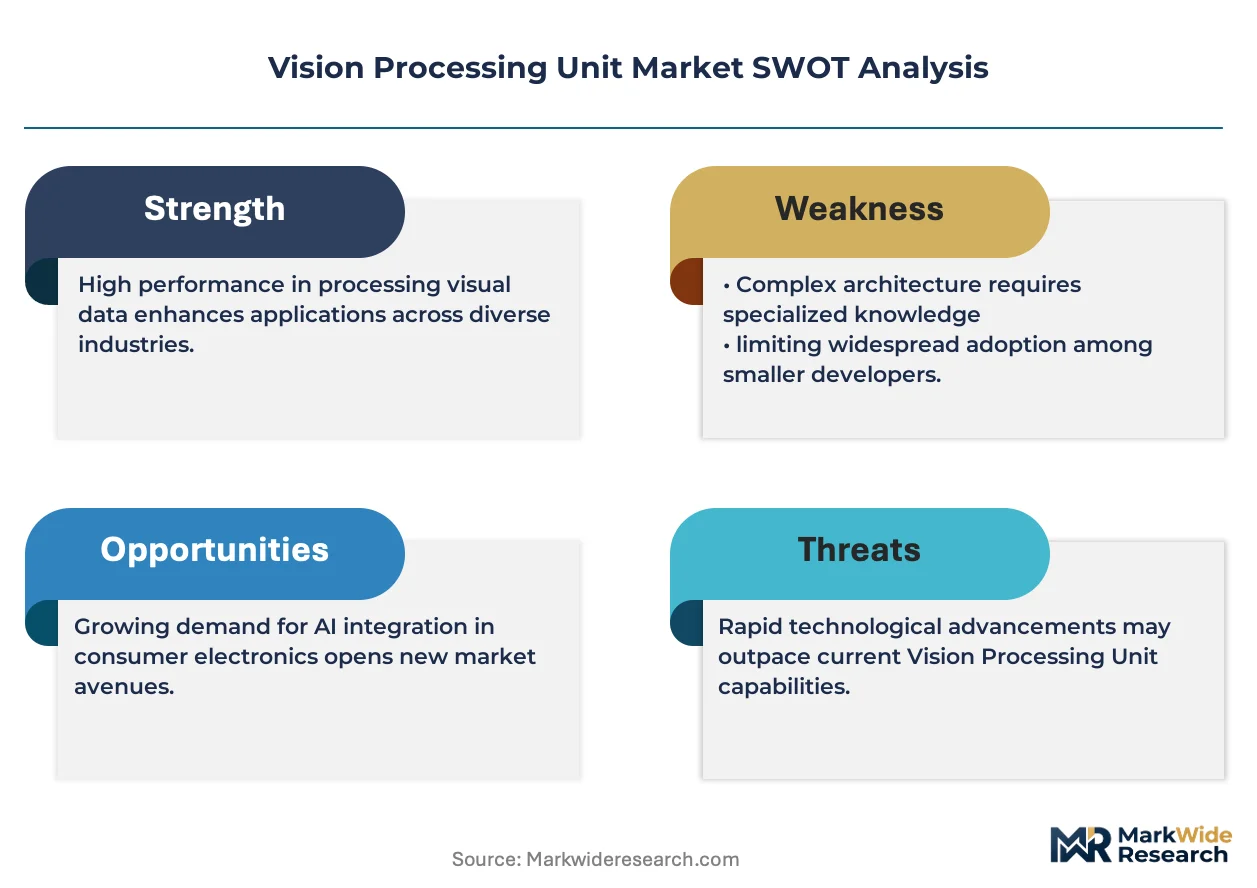
This market functions as a defensive-moat story where CUDA software ecosystems and ISO 26262 certification pipelines create switching costs that entrench incumbents. Regulatory entrenchment through functional safety timelines extends competitive protection beyond typical semiconductor cycles.
For Market Incumbents: Harden software ecosystem lock-in through proprietary inference framework pre-certification with EU AI Act conformity assessment bodies. Deepen upstream control over advanced packaging capacity in Taiwan and South Korea to defend against allocation risk during consumer electronics demand spikes. Threat substitution from transformer-based architectures compressing hardware-software co-design cycles demands accelerated NPU-ISP integration roadmaps. For New Entrants and Emerging Players: India's Gujarat and Tamil Nadu semiconductor assembly corridors represent the most penetrable entry point for VPU packaging investments under PLI scheme incentives. Event-based vision sensing integration for drone collision avoidance offers uncrowded specification territory outside automotive ASIL qualification barriers. Go-to-market execution should anchor on direct robotics OEM relationships in Japan's Nagoya metropolitan area, bypassing channel conflict with entrenched automotive distributors. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because functional safety certification timelines create 18-24 month revenue recognition delays that filter out undercapitalized competitors. Acquisition targets should screen for ASIL-qualified verification engineering teams in Bavaria and Baden-Württemberg. Signal to watch is EU AI Act third-party assessment body accreditation expansion, which will concentrate procurement specification authority among pre-certified toolchain vendors.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Pipeline Investment | ISO 26262 qualification barriers in Germany and Japan filter competitor entry. |
| Direct OEM Procurement Office Establishment | Mercedes-Benz and BMW sourcing relationships bypass EMS distribution margins. |
| Transformer Architecture NPU Integration | Attention mechanism hardware acceleration collapses legacy CNN deployment timelines. |
| EU AI Act Conformity Pre-Certification | Third-party assessment alignment captures high-risk medical imaging procurement. |
| India PLI Scheme Packaging Investment | Gujarat and Tamil Nadu assembly capacity diversifies geographic supply risk. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC semiconductor filings, EU regulatory guidance documents, and automotive production databases. Semiconductor procurement executives at German Tier-1 suppliers, functional safety verification engineers in Japan, and robotics platform architects in China's Yangtze River Delta provided structured input. Bottom-up demand modeling from camera module shipment data triangulates against top-down silicon wafer allocation estimates from foundry disclosure patterns.
Forecast inputs include transformer architecture adoption curves, ISO 26262 certification pipeline throughput, and regional production-linked incentive scheme implementation across the analysis window. Segmentation dimensions cover product architecture type, application safety criticality, end-user regulatory burden, and inference framework standardization. CAGRs derive from installed base replacement cycles and content-per-vehicle expansion in autonomous driving systems.
Stress conditions across EU AI Act enforcement timing, TSMC advanced node allocation priority shifts, and transformer model compression rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about automotive qualification timeline stability and robotics battery constraint persistence. Cross-checking against NHTSA autonomous vehicle guidance and PMDA machine-learning device submission trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Japan Digital X-Ray Market
Imaging
High-Resolution 3D X-Ray Microscopy Market
Imaging
Microscopic Camera Market
Imaging
Pan-Tilt-Zoom (PTZ) Camera Market
Imaging
3D Time-Of-Flight Image Sensor Market
Imaging
Underwater Camera Market
Imaging
Global Label-Free Array Systems Market
Imaging
Contact Image Sensor Market
Imaging
Infrared Imaging Software Market
Imaging
Europe Thermal Imaging Systems Market
Imaging
Camera Stabilizer Market
Imaging
Global Document Scanner Market
Imaging
Automotive 3D Imaging Market
Imaging
Uncooled Infrared Imaging Market
Imaging
Video Processing Solutions Market
Imaging
Global Phosphor Plate Scanners Market