
 Global Optical Diode Market | 2026-2036
Global Optical Diode Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Diode Market Outlook
Multi-source procurement for indium phosphide substrates is restructuring supply security across the optical diode value chain. II-VI Incorporated leverages captive crystal growth capabilities to sustain wafer supply continuity. Lumentum Holding Inc. anchors North American telecom laser production through specialized foundry partnerships. Jenoptik AG dominates precision optics assembly for industrial diode modules in European automation markets.
An optical diode is a unidirectional photonic component that permits light transmission in one direction while blocking reverse propagation, typically achieving isolation ratios exceeding 30 dB through Faraday rotator crystals and polarizing beam splitters. These devices protect laser sources from back-reflection damage in high-power fiber systems and stabilize signal integrity across wavelength-division multiplexing networks. Laser diodes command the largest value share among product types due to their irreplaceable role in coherent transceivers, while avalanche photodiodes deliver the fastest growth trajectory as datacenter operators upgrade to 800G receiver sensitivity thresholds. Silicon-based technology retains cost advantages in consumer volume applications, though indium phosphide platforms capture premium margins in telecom-grade devices.
The US FCC governs optical equipment certification for telecommunications infrastructure, while the EU RoHS directive restricts hazardous substances in diode manufacturing materials. Japan's METI promotes domestic photonics capabilities through targeted industrial standards that shape procurement criteria for telecom providers. Stakeholders must monitor divergence between US export controls on compound semiconductor substrates and China's accelerating GB standards localization to anticipate supply route disruptions.
Market Dynamics
Datacenter interconnect buildouts by telecom providers are compressing procurement cycles for high-isolation optical components while China's MIIT mandates restructure substrate sourcing patterns across the value chain.
Growth Catalysts
- 800G Receiver Upgrades:Datacenter operators are replacing legacy photodetectors with avalanche photodiodes to meet sensitivity thresholds for next-generation coherent transceivers.
- EU RoHS Directive:Hazardous substance restrictions are accelerating material substitutions in diode manufacturing, creating certified-supplier premiums for compliant component vendors.
- Jena-Berlin Photonics Corridor:Germany's precision optics cluster is concentrating industrial diode module assembly capacity for European automation markets.
Market Restraints
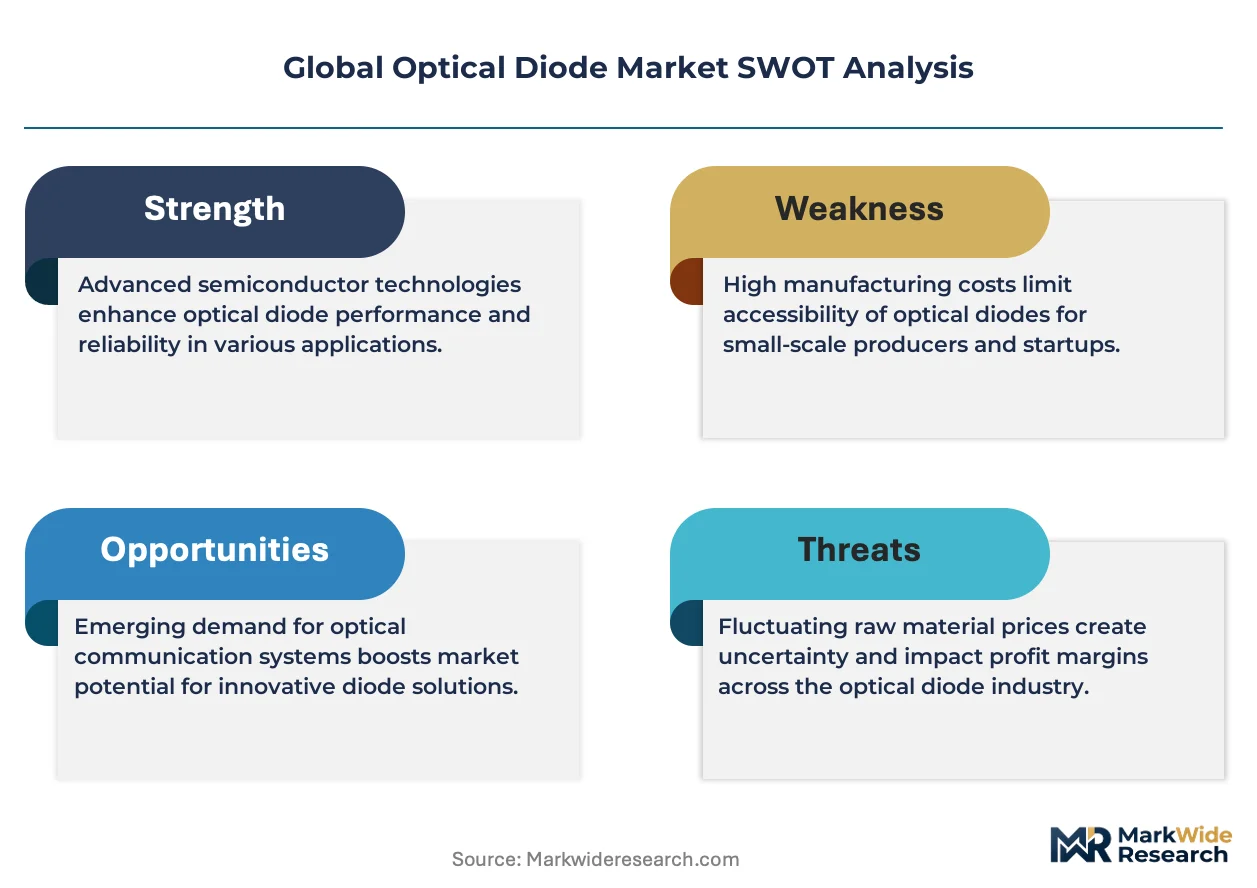
- Indium Phosphide Substrate Concentration:Limited qualified wafer suppliers create supply security vulnerabilities for telecom-grade laser production.
- Faraday Rotator Crystal Costs:Specialized magneto-optic materials command premium pricing that compresses margins in high-volume consumer applications.
- US Export Controls:Compound semiconductor substrate restrictions are fragmenting supply routes and forcing dual-sourcing strategies.
Strategic Opportunities
- China's GB Standards Localization:Accelerating domestic certification requirements are creating captive demand for locally manufactured optical isolators.
- Silicon Photonics Convergence:Hybrid integration of silicon platforms with III-V materials is opening cost-reduction pathways for consumer LiDAR modules.
- Industrial Automation Channels:Direct OEM partnerships for precision diode modules are displacing traditional distributor networks in European markets.
Industry Challenges
- Compound Semiconductor Talent Gap:Shortages of crystal growth engineers and optoelectronic packaging specialists are extending development timelines.
- FCC Certification Timelines:Extended optical equipment approval processes for telecommunications infrastructure are delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Diode Market |
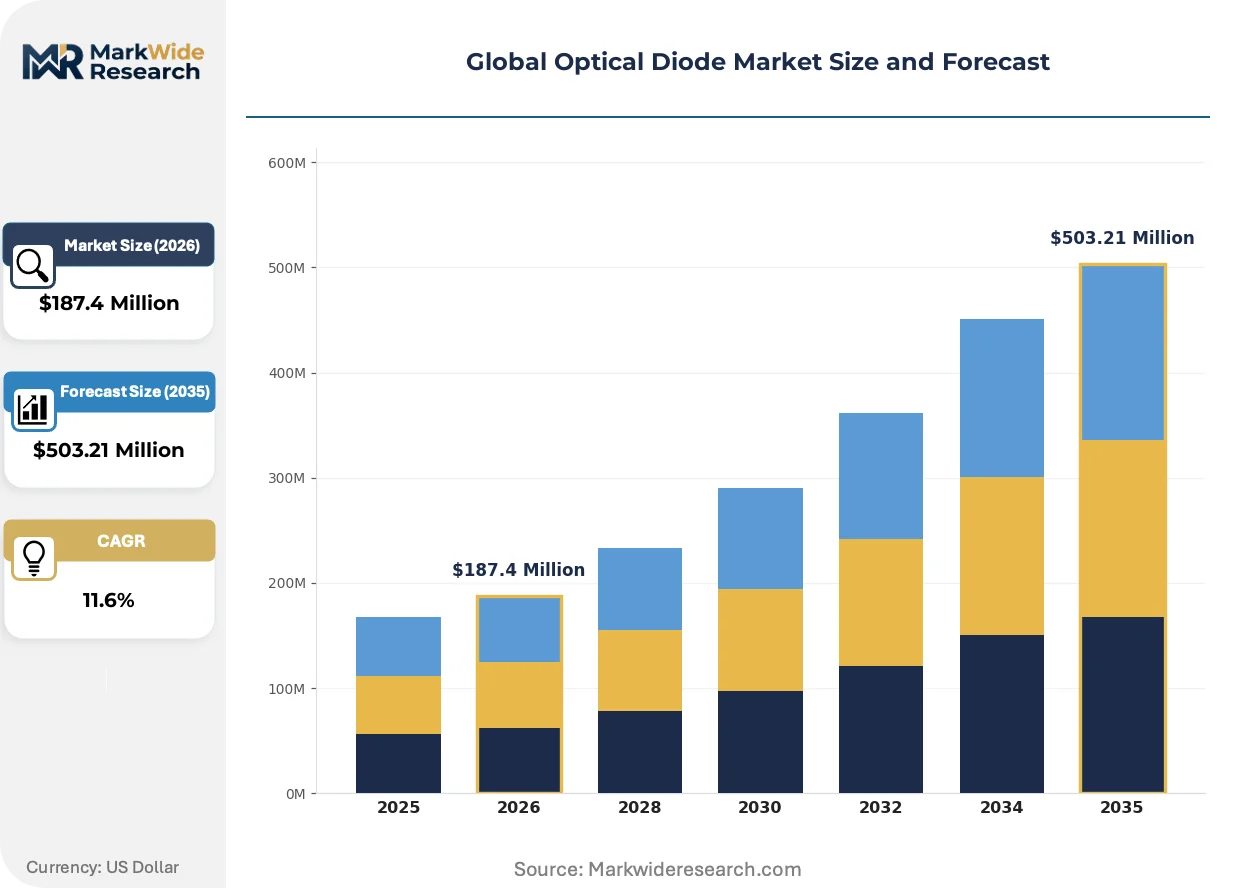
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Diodes, Laser Diodes, Photo Diodes, Avalanche Diodes Application: Telecommunications, Consumer Electronics, Industrial Applications, Medical Devices Technology: Silicon-based, Gallium Nitride, Indium Phosphide, Organic Photonic End User: Telecom Providers, Electronics Manufacturers, Healthcare Facilities, Research Institutions |
| Companies Covered | II-VI Incorporated, IPG Photonics Inc., Jenoptik AG, Lumentum Holding Inc., Coherent Corp., ams-OSRAM AG, Nichia Corporation, ROHM Co., Ltd., TRUMPF GmbH + Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Diode Market Strategic Shifts
Photonic integration architectures are compressing component counts while regulatory divergence between major economies is fragmenting certification pathways and sourcing strategies.
Coherent DSP-photonic integration is consolidating transceiver architectures by embedding optical isolation functions directly within silicon photonic chips. Cloud operators at hyperscale datacenters are adopting these consolidated modules to reduce fiber coupling losses. This consolidation is displacing discrete optical diode assemblies in 800G and 1.6T line cards.
Japan's METI industrial standards are mandating domestic content ratios for photonics procurement by NTT and regional telecom providers. These requirements are redirecting supply contracts toward Japan-qualified component vendors. Telecom laser suppliers are establishing local assembly operations to maintain access to this procurement channel.
Buyer consolidation among hyperscale datacenter operators is compressing component qualification cycles and unbundling after-sales service contracts. Traditional value-added distributors are losing share to direct manufacturer relationships with Meta, Google, and Microsoft. This channel shift is most visible in North American markets where three buyers control majority 800G transceiver demand.
Global Optical Diode Market Segmentation
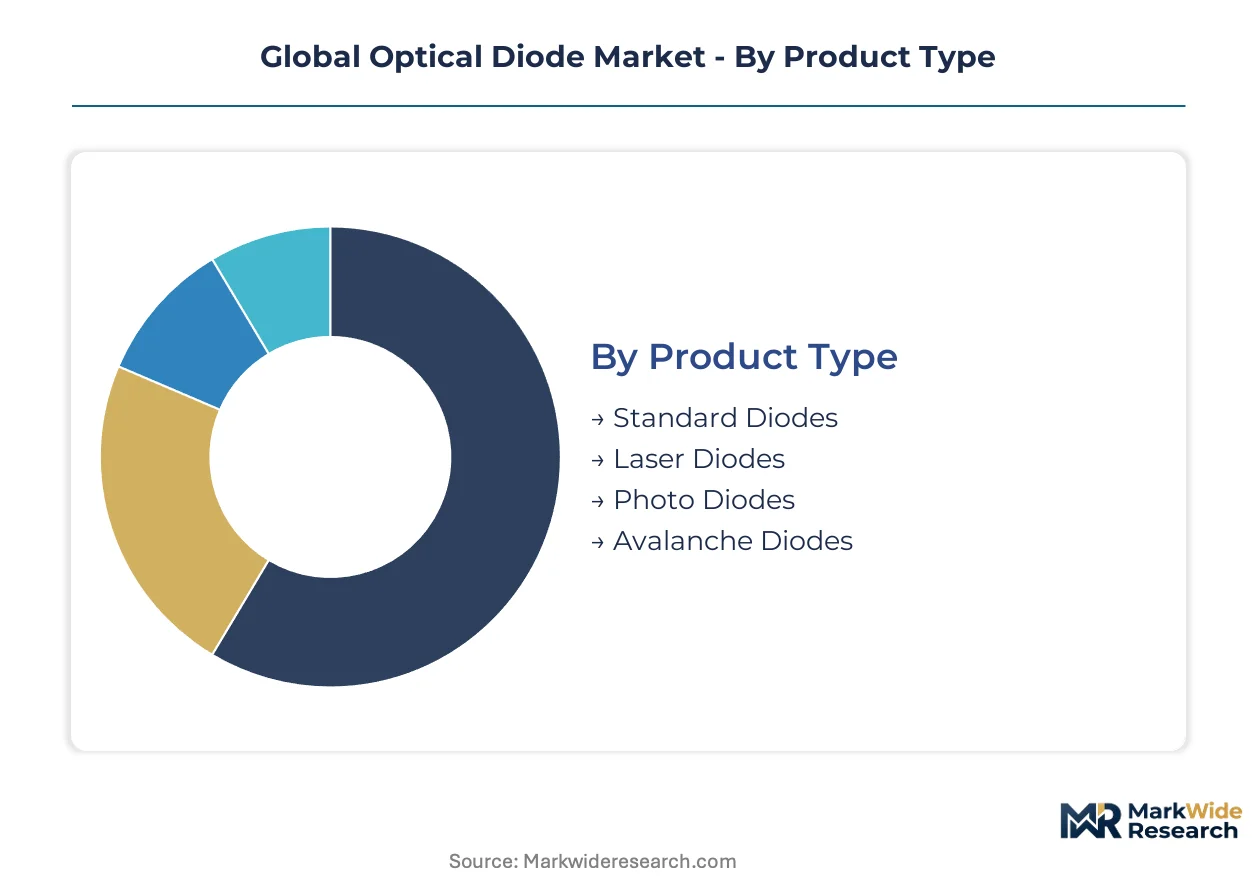
Optical diode procurement patterns diverge sharply across technical specifications and end-use requirements. Component buyers prioritize isolation ratios, wavelength precision, and thermal stability depending on deployment context.
Product Type:
Performance thresholds and manufacturing complexity separate commodity from precision-grade components.
- Laser Diodes:Coherent light sources built on indium phosphide or gallium arsenide substrates deliver the narrow linewidth essential for wavelength-division multiplexing systems. Telecom providers in Germany's Jena-Berlin corridor source these for 800G transceiver builds. Faraday rotator integration protects against back-reflection damage in high-power fiber deployments.
- Avalanche Diodes:These photodetectors exploit internal gain multiplication to achieve sensitivity below -30 dBm, meeting 800G receiver thresholds at hyperscale datacenters. China's MIIT-mandated domestic sourcing is redirecting supply contracts toward local qualified vendors.
- Photo Diodes:Standard PIN structures dominate consumer LiDAR and optical sensing applications where cost sensitivity exceeds performance demands.
- Standard Diodes:Basic isolation components serve industrial automation feedback loops with moderate isolation ratio requirements.
Mature deployment sits with Laser Diodes. Newer deployment is concentrated in Avalanche Diodes.
Application:
End-use environments dictate certification requirements and reliability specifications.
- Telecommunications:Undersea cables and terrestrial fiber networks demand hermetic packaging and 25-year operational lifespans. FCC certification timelines for optical equipment create extended qualification cycles. EU RoHS compliance adds material substitution constraints for European deployments.
- Industrial Applications:Factory automation systems in Germany's photonics manufacturing corridor require precision diode modules with vibration resistance and thermal cycling durability. Direct OEM partnerships are displacing traditional distributor channels.
- Consumer Electronics:Smartphone 3D sensing and AR headset modules prioritize silicon-based cost structures over III-V performance premiums.
- Medical Devices:Optical coherence tomography and laser surgical equipment must satisfy FDA device clearance or equivalent national regulator pathways.
Volume concentration favors Telecommunications. Margin expansion is strongest in Industrial Applications.
Technology:
Substrate selection determines wavelength range, power handling, and integration pathway.
- Indium Phosphide:Lattice-matched to telecom wavelengths from 1.3 to 1.6 microns, this platform captures premium pricing in coherent transceivers. Limited qualified wafer suppliers create supply security vulnerabilities addressed through multi-source procurement strategies.
- Silicon-based:CMOS-compatible fabrication enables consumer-scale volumes at foundry economics. Hybrid integration with III-V materials is opening cost pathways for LiDAR modules.
- Gallium Nitride:Wide bandgap properties support visible and ultraviolet emission for display and sterilization applications.
- Organic Photonic:Solution-processable materials enable flexible form factors in emerging wearable and biomedical deployments.
Revenue concentration rests with Indium Phosphide. Silicon-based platforms are climbing the fastest on unit volume.
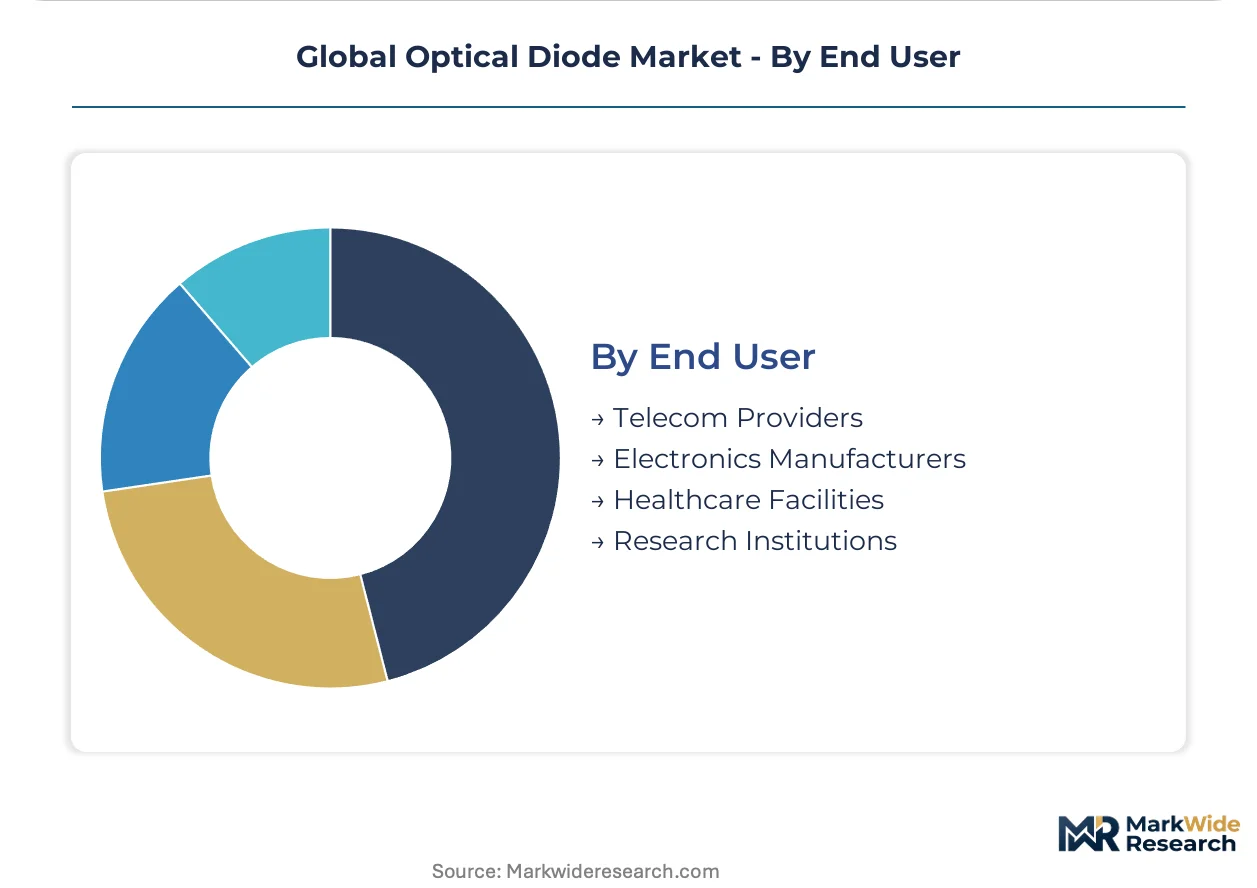
End User:
Procurement authority and technical specification ownership vary across buyer types.
- Telecom Providers:NTT, Deutsche Telekom, and Verizon consolidate 800G transceiver demand, compressing component qualification cycles and unbundling service contracts. Japan's METI domestic content ratios redirect supply toward locally qualified vendors.
- Electronics Manufacturers:Foxconn, Luxshare, and comparable contract manufacturers specify diode performance for smartphone and computing OEMs. China's GB standards localization creates captive demand for certified optical isolators.
- Healthcare Facilities:Hospital systems and clinic networks procure through specialized medical device distributors with regulatory compliance expertise.
- Research Institutions:National laboratories and university photonics centers drive prototype demand for emerging organic and quantum photonic architectures.
Procurement scale concentrates with Telecom Providers. Specification influence is expanding most quickly among Electronics Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indium phosphide substrate production concentrates in Japan, Germany, and the United States, anchoring regional supply security strategies for telecom-grade optical components.
United States
Hyperscale datacenter operators in Virginia and Oregon compress 800G transceiver procurement cycles. FCC certification timelines for optical telecommunications equipment extend product qualification periods. Silicon photonics development clusters in California's Bay Area drive hybrid integration research for consumer LiDAR cost reduction.
Germany
The Jena-Berlin photonics corridor concentrates precision optics assembly for industrial automation diode modules. EU RoHS hazardous substance restrictions accelerate material substitutions in manufacturing. Direct OEM partnerships in Baden-Württemberg displace traditional distributor networks for factory automation systems.
China
MIIT mandates for domestic optical component sourcing redirect supply chains toward local qualified vendors. GB standards localization creates captive demand for certified optical isolators. Yangtze River Delta manufacturing bases scale avalanche photodiode production for 800G receiver upgrades.
Japan
NTT and regional telecom providers consolidate transceiver demand under METI domestic content ratio requirements. JIS industrial standards shape procurement criteria for photonics vendors. Kanto region assembly operations maintain access to Japan-qualified component channels.
South Korea
Electronics manufacturers specify diode performance for smartphone 3D sensing modules bound for export markets. MFDS regulatory pathways govern medical device optical component clearance. Seoul Capital Area contract manufacturers integrate silicon-based photodetectors for cost-sensitive consumer applications.
Global Optical Diode Market Competitive Environment
Multi-source procurement strategies dominate the current landscape as substrate supply security reshapes vendor relationships. The market structures around three tiers: integrated compound semiconductor specialists with captive crystal growth, precision optics assemblers serving industrial automation, and foundry-dependent designers relying on external wafer supply. Strategic archetypes include vertical integration advocates securing indium phosphide supply chains, regional qualification specialists navigating Japan's METI content requirements, and silicon photonics convergents pursuing hybrid III-V integration. Capacity expansion and strategic partnerships constitute the dominant competitive moves.
Among compound semiconductor specialists, II-VI Incorporated and Lumentum Holding Inc. exemplify the integrated archetype with positions anchored in North American telecom laser production. Jenoptik AG occupies a precision optics position within Germany's industrial automation supply base. These three represent distinct strategic postures: substrate security through captive supply, foundry partnership networks, and regional cluster concentration respectively.
| Leading Market Players |
|---|
| II-VI Incorporated |
| IPG Photonics Inc. |
| Jenoptik AG |
| Lumentum Holding Inc. |
| Coherent Corp. |
| ams-OSRAM AG |
| Nichia Corporation |
| ROHM Co., Ltd. |
| TRUMPF GmbH + Co. KG |
| Others |
Value Chain & Pricing Dynamics
EU RoHS hazardous substance restrictions gate qualified supply access and premium-tier pricing for telecom-grade optical diodes, forcing material substitutions that separate certified vendors from commodity assemblers. Buyers unbundling after-sales service contracts from component procurement compress margin capture for traditional distributors serving hyperscale datacenter operators.
Pricing Analysis
Warranty and field-service bundling now separates premium-tier suppliers from unbundled commodity vendors in 800G transceiver procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in consumer LiDAR modules intensifies as silicon photonics hybrid integration reduces III-V material premiums. Electronics manufacturers exhibit highest price sensitivity, while telecom providers prioritize isolation ratio performance over unit economics.
Supply Chain Analysis
Reverse-logistics flows for Faraday rotator crystal refurbishment remain underdeveloped, creating stranded value in end-of-life telecom isolators. Indium phosphide substrate supply concentrates in Japan, Germany, and the United States, with crystal growth capacity anchoring regional vendor strategies. The value chain draws from specialized magneto-optic materials, compound semiconductor wafers, and precision optical coatings. Single-source vulnerability for qualified indium phosphide suppliers fragments procurement security. Distribution runs through direct manufacturer relationships with hyperscale datacenter operators, displacing traditional value-added distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coherent DSP-photonic integration is displacing discrete optical diode assemblies in 800G and 1.6T line cards, compressing the addressable market for standalone isolator vendors while opening hybrid integration opportunities.
For Market Incumbents: Hedge substrate supply exposure through multi-source indium phosphide procurement agreements and captive crystal growth investments. Secure FCC certification pipelines for consolidated silicon photonic modules before qualification cycles extend further. Defensive consolidation around precision optics assembly in Germany's Jena-Berlin corridor preserves industrial automation margins against silicon photonics encroachment. For New Entrants and Emerging Players: Silicon photonics-first wedge positions exploit cost-reduction pathways for consumer LiDAR modules through hybrid III-V integration. Target China's GB standards localization requirements for captive optical isolator demand. Direct OEM partnerships for industrial automation diode modules displace distributor-dependent incumbents in European markets. For Investors and Strategic Acquirers: METI domestic content ratio enforcement in Japan is the leading indicator that regional qualification specialists will command acquisition premiums. Compound semiconductor specialists with captive crystal growth capabilities present viable targets over a multi-year holding period. Monitor divergence between US export controls and China's accelerating standards localization for supply route disruption signals.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Indium Phosphide Crystal Growth | II-VI Incorporated secures wafer supply continuity against substrate concentration risks. |
| Silicon Photonics Hybrid Integration | Cost pathways open for LiDAR modules through CMOS-compatible III-V bonding. |
| GB Standards Localization Compliance | China's MIIT mandates redirect supply contracts toward certified domestic vendors. |
| Direct OEM Partnership Expansion | Jenoptik AG displaces distributor networks in Baden-Württemberg automation markets. |
| METI Content Ratio Qualification | NTT procurement criteria favor Japan-qualified assembly operations in Kanto region. |
Study Parameters
Multi-period observation of hyperscaler capex disclosures, FCC certification filings, and compound semiconductor trade flows anchored the trend analysis, supplemented by interviews with telecom procurement directors, photonics R&D leads, crystal growth engineers, and industrial automation OEMs. Secondary validation drew from SEC 10-K filings, EU RoHS compliance databases, Japan's METI industrial standards publications, and China MIIT policy circulars. Bottom-up vendor capacity assessments and top-down demand modeling from datacenter interconnect buildouts were triangulated for convergence.
Segment-weighting across product type, application, technology platform, and end-user procurement authority informed the analytical framework over the projection horizon. Indium phosphide versus silicon-based technology splits, 800G receiver upgrade penetration curves, and regional regulatory divergence patterns shaped CAGR derivation. Telecom provider consolidation ratios and distributor channel displacement rates provided industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated silicon photonics substitution or escalated US-China substrate export restrictions. Practitioners should monitor METI domestic content enforcement thresholds and GB standards certification velocity for early demand inflection signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Flip-Chip VCSEL Market
Optical Components
US Optical Sensors Market
Optical Components
Raman Amplifier Market
Optical Components
Global Diffractive Optical Elements Market
Optical Components
100G Optical Transceivers Market
Optical Components
Europe Lithium Niobate Modulator Market
Optical Components
VCSEL for Data Communication Market
Optical Components
Erbium Oxide Market
Optical Components
Global Optical Imaging System Market
Optical Components
Global Hybrid Photonic Integrated Circuit Market
Optical Components
Faraday Rotator Market
Optical Components
Acousto Optic Devices Market
Optical Components
Waveguide Phase Shifter Market
Optical Components
Optical Encoder Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
Acousto Optical Cavity Dumper Market