
 Electro Optical System Market | 2026-2036
Electro Optical System Market Size, Share, and Industry Trends Forecast 2026-2036
Electro Optical System Market Foresight
Defense organizations are reorganizing procurement priorities around multi-spectral target acquisition and unmanned platform payloads. L3Harris Technologies leverages in-house laser designator production to control critical component supply for military customers. BAE Systems anchors European sovereign capability through its Glasgow-based electro-optical manufacturing center. Lockheed Martin competes on integrated sensor-to-shooter architectures that bundle imaging with fire-control systems.
Electro optical systems integrate photodetectors, laser emitters, and signal processing electronics to convert between optical and electrical signals for sensing, communication, and directed-energy applications. These systems operate across ultraviolet through long-wave infrared wavelengths, with cooled mercury cadmium telluride focal plane arrays enabling thermal resolution below 20 millikelvin for precision targeting. Imaging sensors capture the largest revenue pool among product types due to persistent demand for high-definition infrared modules in surveillance and medical diagnostics. Photonic integrated circuits represent the fastest-expanding technology segment as silicon photonics reduces size, weight, and power consumption in aerospace and consumer electronics applications.
The US Department of Defense imposes ITAR-controlled export restrictions on thermal imaging cores, creating market access barriers for non-US suppliers. EAR and FCC regulations govern civilian laser safety classifications and electromagnetic compatibility for electro-optical devices sold in commercial markets. Stakeholders must monitor divergence between US ITAR and EU dual-use export control regimes as transatlantic defense industrial cooperation faces renewed licensing friction.
Market Dynamics
Defense procurement is pivoting from standalone sensors to fused multi-spectral architectures, compressing vendor margins while elevating systems integrators who control software-defined targeting pipelines.
Growth Catalysts
- JADC2 Architecture Mandate:The US Department of Defense's Joint All-Domain Command and Control framework forces interoperability standards across air, land, sea, space, and cyber domains, mandating common electro-optical data formats.
- Mercury Cadmium Telluride Maturation:Cooled MCT focal plane arrays now achieve thermal resolution below 20 millikelvin, enabling precision targeting at extended ranges for armored vehicle upgrades.
- German Armored Modernization:Rheinmetall and Hensoldt anchor electro-optical supply chains for NATO battlefield awareness programs, concentrating demand in Central European manufacturing clusters.
Market Restraints
- ITAR Export Controls:US State Department restrictions on thermal imaging cores block non-US suppliers from accessing cooled infrared technology, fragmenting global supply availability.
- Indium Antimonide Supply Concentration:Critical infrared detector substrate production concentrates in a handful of specialized foundries, exposing the value chain to single-source disruption risk.
- Laser Safety Certification Burden:EAR and FCC classification requirements for civilian laser emitters extend commercial product development timelines by 18-24 months.
Strategic Opportunities
- Silicon Photonics Convergence:Photonic integrated circuits merging optical and electronic functions on single chips address size-weight-power constraints in unmanned aerial platforms.
- Medical Diagnostics Expansion:High-definition infrared modules penetrate ophthalmic imaging and surgical navigation systems, diversifying revenue beyond defense dependence.
- EU Dual-Use Harmonization:Proposed alignment between US ITAR and European export control regimes could reduce transatlantic licensing friction for cross-border defense contracts.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Cooled infrared system design requires specialized expertise in Dewar vacuum packaging and microcooler integration, with limited university pipeline output.
- Legacy Platform Integration Complexity:Retrofitting electro-optical suites into fielded armored vehicles demands mechanical adaptation to existing turret architectures and power budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electro Optical System Market |
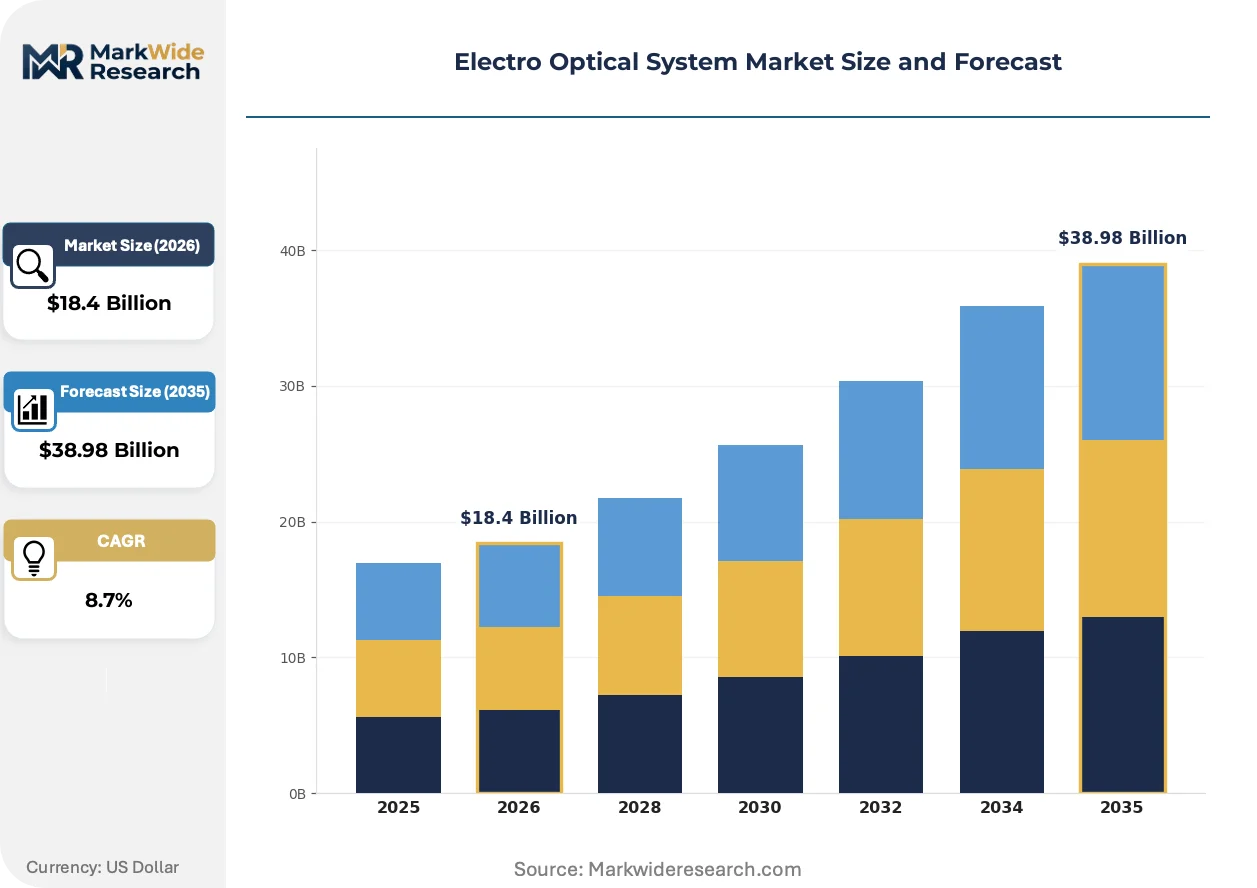
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $38.98 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Systems, Night Vision Devices, Imaging Sensors, Optical Filters Technology: Photonic Integrated Circuits, Quantum Dots, Fiber Optics, Image Processing Application: Military Surveillance, Aerospace Navigation, Medical Imaging, Consumer Electronics End User: Defense Organizations, Aerospace Firms, Healthcare Providers, Electronics Manufacturers |
| Companies Covered | L3Harris Technologies Inc., BAE Systems plc, Lockheed Martin Corporation, Teledyne FLIR, Thales Group, Raytheon Technologies Corporation, Leonardo S.p.A, Elbit Systems Ltd., Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electro Optical System Market Shifts & Advancements
Silicon photonics is compressing electro-optical system footprints while regulatory divergence between transatlantic export regimes is forcing dual-track product development strategies.
Photonic integrated circuits are decomposing traditional discrete optical assemblies into monolithic silicon substrates. Aerospace prime contractors now specify PIC-based solutions for satellite communications payloads. This integration is decomposing the historical boundary between optical component suppliers and semiconductor foundries, forcing electro-optical vendors to develop in-house silicon design capabilities or surrender margin to fab partners.
REACH substance restrictions and RoHS compliance deadlines are accelerating substitution of lead-based solder and cadmium-containing coatings in infrared detector housings. European defense contractors face simultaneous pressure from CSRD sustainability disclosure requirements and F-Gas Regulation limits on cooling system refrigerants. German electro-optical manufacturers are responding by redesigning thermal management architectures around closed-cycle Stirling coolers with helium working fluid.
Defense procurement offices are consolidating vendor panels around qualified sensor-to-shooter system integrators rather than discrete component suppliers. Prime contractors now bundle imaging, laser designation, and fire-control software under single contract vehicles, displacing historical best-of-breed purchasing patterns. This concentration is most visible in US Army ground combat vehicle programs, where L3Harris and Lockheed Martin compete on integrated architecture awards rather than standalone sighting systems.
Electro Optical System Market Segmentation
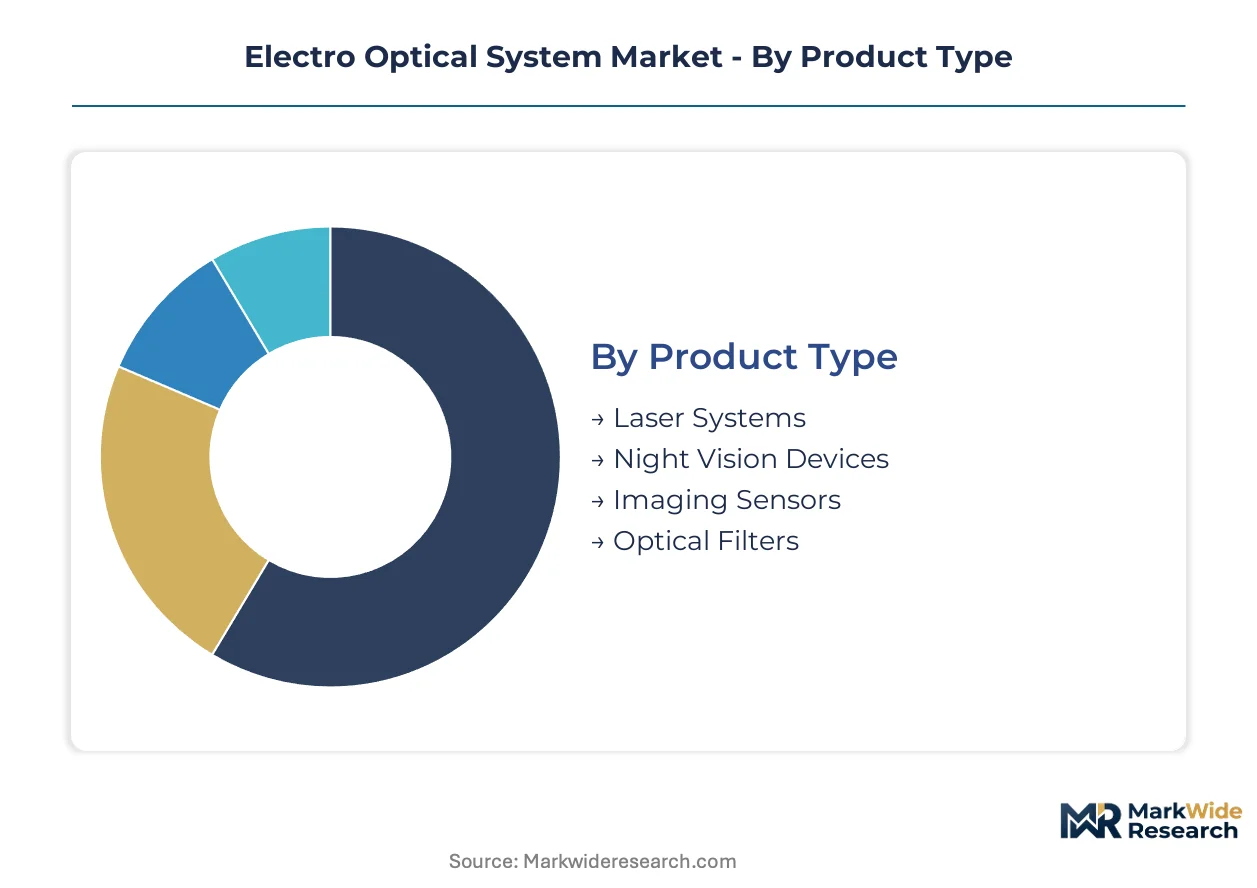
Electro-optical system architectures fragment across product, technology, application, and end-user dimensions, with substitution pressure strongest where silicon photonics encroaches on legacy discrete optical assemblies. Procurement patterns diverge sharply between defense-grade cooled infrared and commercial uncooled alternatives.
Product Type:
Laser systems and night vision devices face acute substitution pressure from solid-state alternatives, while imaging sensors resist displacement through sustained performance gaps in thermal resolution.
- Imaging Sensors:Cooled mercury cadmium telluride focal plane arrays deliver thermal resolution below 20 millikelvin for precision targeting applications. US Army ground combat vehicle programs concentrate procurement in Texas and Michigan manufacturing clusters, constrained by ITAR export controls on thermal imaging cores.
- Laser Systems:Solid-state and fiber laser architectures displace legacy chemical laser designs across directed-energy and rangefinding applications. German defense procurement through Rheinmetall anchors European demand for eye-safe laser designators in armored vehicle upgrades.
- Night Vision Devices:Image intensifier tubes compete with emerging digital night vision for infantry applications.
- Optical Filters:Thin-film and holographic designs segment by wavelength selectivity requirements.
Imaging sensors anchors the volume base while photonic integrated circuits gain share at the steepest rate.
Technology:
Cost tier stratification separates defense-qualified heritage technologies from commercial-scale silicon photonics, with volume manufacturing economics favoring monolithic integration.
- Photonic Integrated Circuits:Silicon photonics merges optical and electronic functions on single substrates, compressing size-weight-power metrics for aerospace payloads. Satellite communications prime contractors in California and Massachusetts now specify PIC-based solutions for inter-satellite links.
- Image Processing:Real-time target tracking algorithms and sensor fusion software define competitive differentiation in multi-spectral architectures. JADC2 interoperability mandates force common data formats across US Air Force and Navy procurement programs.
- Quantum Dots:Colloidal synthesis enables tunable emission wavelengths for display and sensing applications.
- Fiber Optics:Single-mode and multi-mode fiber segments persist in telecommunications and laser delivery systems.
Photonic integrated circuits command premium pricing in aerospace while image processing scales most rapidly across defense and commercial adjacencies.
Application:
Customer type divergence separates classified defense procurement from regulated medical device pathways, with certification burden varying by application jurisdiction.
- Military Surveillance:Multi-spectral imaging suites integrate short-wave infrared through long-wave infrared bands for battlefield awareness. NATO member state procurement concentrates demand in German and Polish manufacturing corridors for armored vehicle situational awareness.
- Medical Imaging:High-definition infrared modules penetrate ophthalmic diagnostics and surgical navigation systems. FDA 510(k) clearance pathways and EU MDR conformity assessment extend development timelines relative to consumer electronics.
- Aerospace Navigation:Star trackers and optical gyroscopes serve satellite attitude determination.
- Consumer Electronics:Time-of-flight sensors and lidar modules enable smartphone depth sensing and automotive autonomy.
Military surveillance absorbs the largest absolute investment while medical imaging expands most quickly into diagnostic adjacencies.
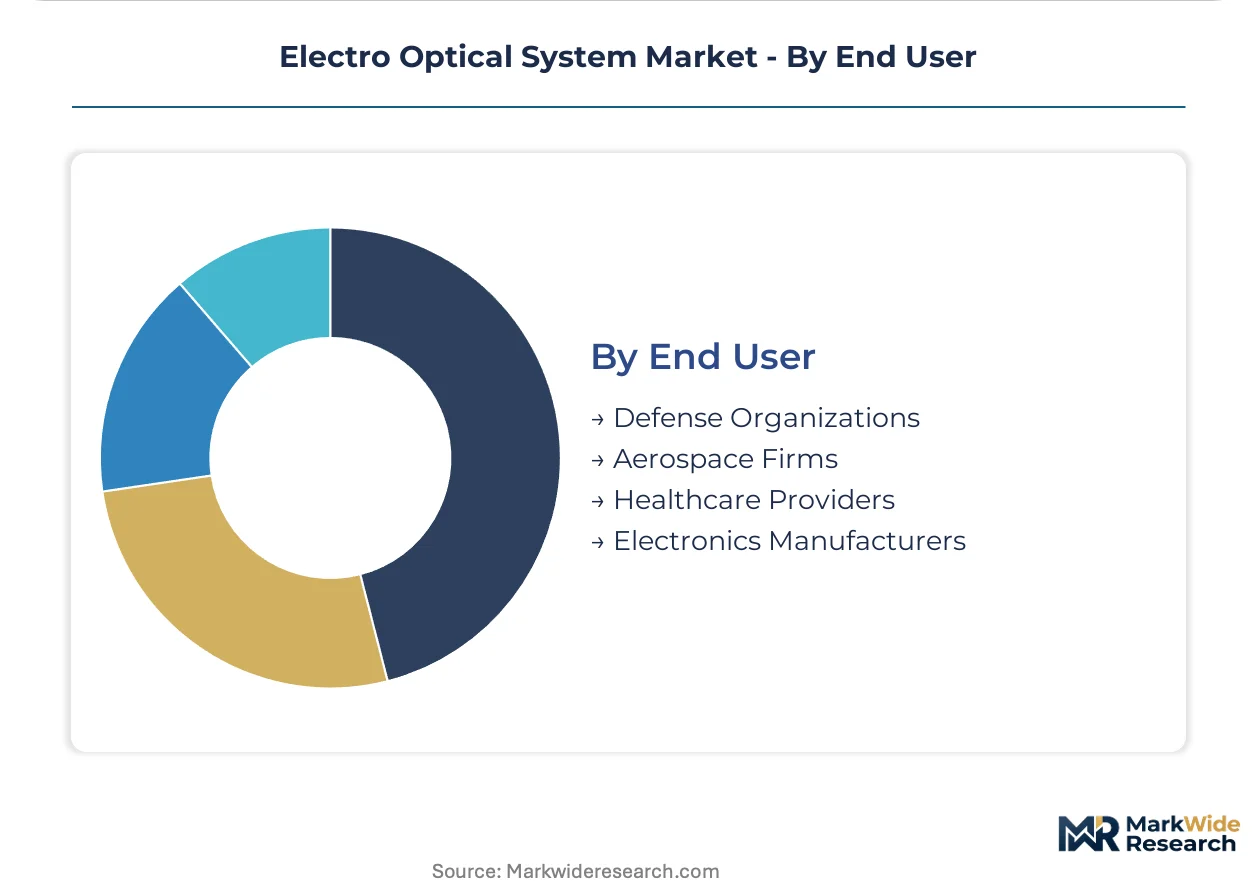
End User:
Supply concentration varies by end-user sophistication, with defense organizations demanding captive supply chains and electronics manufacturers sourcing from merchant foundries.
- Defense Organizations:US Department of Defense JADC2 architecture mandates drive interoperability requirements across air, land, sea, space, and cyber domains. Cooled infrared detector procurement flows through qualified prime contractors with ITAR-compliant manufacturing facilities.
- Healthcare Providers:Hospital systems and diagnostic imaging centers specify electro-optical modules for endoscopic and ophthalmic applications. Reimbursement coding from CMS and analogous European health technology assessment bodies shapes equipment acquisition cycles.
- Aerospace Firms:Prime contractors integrate electro-optical payloads for satellite and unmanned platform missions.
- Electronics Manufacturers:Consumer device assemblers source uncooled infrared and time-of-flight sensors from Asian merchant suppliers.
Defense organizations dominate absolute procurement value while healthcare providers demonstrate the steepest adoption trajectory in commercial infrared diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German electro-optical exports flow primarily into NATO procurement channels, while US ITAR-controlled thermal cores circulate through qualified defense industrial corridors. Asian manufacturing clusters absorb merchant uncooled infrared for commercial electronics integration.
United States
The Department of Defense's JADC2 architecture mandates interoperability standards across multi-domain operations. ITAR export controls on cooled mercury cadmium telluride focal plane arrays restrict foreign access to precision targeting technology. Texas and Michigan manufacturing clusters concentrate US Army ground combat vehicle electro-optical procurement.
Germany
Rheinmetall and Hensoldt anchor electro-optical supply chains for NATO armored vehicle modernization programs. REACH substance restrictions and F-Gas Regulation limits on cooling system refrigerants force thermal management redesigns. Bavaria-based manufacturers respond with closed-cycle Stirling coolers using helium working fluid.
China
MIIT standards govern domestic electro-optical component certification for telecommunications and consumer electronics applications. Dual carbon goals accelerate silicon photonics adoption in data center interconnects. Yangtze River Delta foundries scale photonic integrated circuit production for merchant sensor markets.
Israel
Defense procurement prioritizes multi-spectral targeting systems for unmanned platform payloads. The national regulator oversees dual-use export licensing for infrared technology transfers. Tel Aviv-area engineering clusters specialize in real-time image processing algorithms for sensor fusion architectures.
Japan
METI industrial policy supports domestic focal plane array production for aerospace and medical imaging applications. JIS standards specify electromagnetic compatibility requirements for electro-optical devices. Kanto region precision optics manufacturers supply star trackers and optical gyroscopes for satellite attitude determination.
Electro Optical System Market Competitive Landscape
Listed leaders compete with private specialists across defense contracting channels, creating a tiered structure where prime contractors bundle integrated systems while component vendors supply discrete technologies. The vendor base stratifies between ITAR-qualified US primes, European sovereign capability champions, and Asian merchant suppliers. Three archetypes dominate: systems integrators controlling sensor-to-shooter architectures, sovereign defense champions with captive manufacturing, and silicon photonics foundries serving commercial scale. Competitive moves center on strategic partnerships for JADC2 compliance and backward integration into critical detector substrates.
Within the systems integrator tier, L3Harris Technologies Inc. and Lockheed Martin Corporation exemplify prime contractors bundling imaging, laser designation, and fire-control software under single contract vehicles. BAE Systems plc anchors European sovereign capability through UK-based electro-optical manufacturing. These three occupy positions where defense procurement consolidation favors qualified integrators over discrete component suppliers.
| Leading Market Players |
|---|
| L3Harris Technologies Inc. |
| BAE Systems plc |
| Lockheed Martin Corporation |
| Teledyne FLIR |
| Thales Group |
| Raytheon Technologies Corporation |
| Leonardo S.p.A |
| Elbit Systems Ltd. |
| Northrop Grumman Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between US defense primes and mercury cadmium telluride substrate suppliers lock in multi-year supply access while anchoring price visibility against indium antimonide spot market volatility. These contracts insulate procurement budgets from cryogenic cooler component shortages that disrupt German armored vehicle upgrade timelines.
Pricing Analysis
Technology-generation pricing gaps separate cooled mercury cadmium telluride arrays commanding premium positioning from uncooled vanadium oxide microbolometers competing on unit economics. Three-tier pricing structure across ITAR-restricted defense-grade, dual-use commercial, and consumer electronics tiers reflects certification burden and thermal resolution performance. Pricing pressure stems from silicon photonics foundries absorbing optical functions onto monolithic substrates at scale. Defense organizations demonstrate lowest price sensitivity due to mission-critical requirements, while medical device OEMs face reimbursement-constrained procurement ceilings.
Supply Chain Analysis
Strategic stockpiling of indium antimonide substrates and mercury cadmium telluride wafers dominates defense-tier procurement, contrasting with just-in-time merchant sourcing for consumer infrared sensors. Supply concentrates in US, Germany, and Japan for cooled focal plane array manufacturing, with China scaling uncooled detector foundries. Critical dependencies include germanium optics, indium antimonide substrates, and Stirling cooler compressors. Single-source vulnerability in MCT epitaxy equipment exposes lead times to US export licensing delays. Distribution runs through qualified prime contractor channels for defense applications and Asian merchant distributors for commercial electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat arena where ITAR regulatory entrenchment and JADC2 certification switching costs protect incumbent positions against merchant foundry encroachment.
For Market Incumbents: Consolidate backward integration into mercury cadmium telluride substrate production to secure supply against indium antimonide foundry concentration risk. Expand silicon photonics design capabilities in-house or through fab partnerships to defend margin position against semiconductor foundry margin capture. Lock in JADC2-compliant software architectures to elevate switching costs for defense procurement offices evaluating alternative sensor-to-shooter integrators.
For New Entrants and Emerging Players: Real-time sensor fusion software gaps in legacy prime contractor offerings present white-space entry points for algorithm-specialist firms. Target medical imaging OEMs in ophthalmic and surgical navigation segments where FDA 510(k) pathways offer faster commercial traction than ITAR defense qualification. Pursue partnership-based go-to-market models with established German electro-optical manufacturers seeking silicon photonics competency augmentation.
For Investors and Strategic Acquirers: Capital is best deployed toward silicon photonics design houses with aerospace payload qualifications and dual-use technology portfolios. Long-term viability across the projection horizon rests on regulatory moat sustainability and JADC2 architecture lock-in durability. Watch for EU-US dual-use export control harmonization proposals as inflection signals for transatlantic contract accessibility expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Substrates | Captive mercury cadmium telluride supply secures ITAR-compliant manufacturing against indium antimonide foundry bottlenecks. |
| Silicon Photonics Design Capability Buildout | Monolithic integration addresses size-weight-power constraints in unmanned aerial platform payload specifications. |
| JADC2 Software Architecture Certification | Common data format compliance qualifies vendors for US Air Force and Navy multi-domain command contracts. |
| Medical Device Regulatory Pathway Investment | FDA 510(k) and EU MDR clearances diversify revenue beyond defense procurement cyclicality. |
| EU Dual-Use Export Control Harmonization Lobbying | Reduced transatlantic licensing friction expands addressable market for cross-border NATO defense contracts. |
Research Methodology
Initial hypotheses were tested against primary input from defense procurement officers, electro-optical systems engineers, cryogenic cooler manufacturing specialists, and medical device regulatory affairs leads and refined through secondary validation against SEC 10-K filings, US Department of Defense budget justification documents, EU dual-use export control registers, and German federal procurement databases. Bottom-up segment sizing triangulated with top-down macroeconomic elasticity checks across the analysis window.
Variance decomposition across product type, technology generation, application jurisdiction, and end-user sophistication tiers structured the analytical framework. CAGRs were derived from segment-level volume and value buildups normalized against defense procurement cycle phasing and silicon photonics adoption S-curves. Forecast inputs incorporated JADC2 architecture deployment timelines, REACH substance restriction compliance deadlines, and F-Gas Regulation thermal management redesign schedules.
Underlying assumptions cover sustained ITAR export control stringency and NATO armored modernization program continuity, with deviation risk concentrated in EU-US regulatory harmonization outcomes and indium antimonide supply disruption events. Revision becomes warranted when silicon photonics performance thresholds cross cooled infrared equivalence thresholds or transatlantic licensing friction metrics shift materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
3-7mm Galvo Scanner Market
Optical Components
High Power Double-Clad Fiber Bragg Grating Market
Optical Components
Prism Coupler Market
Optical Components
ROADM WSS Component Market
Optical Components
Fiber Optic Collimating Lens Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
Duplication Disc Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Asia-Pacific Optical Film Market
Optical Components
US Optical Sensors Market
Optical Components
North America Optical Film Market
Optical Components
Optical Transceiver Market
Optical Components
Coherent Optical Equipment Market
Optical Components
Display Optical Film Market
Optical Components
Package Shell for Optical Communication Modules Market