
 Portable Gas Chromatograph Market | 2026-2036
Portable Gas Chromatograph Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Gas Chromatograph Market Outlook
Micro-fabricated column arrays and MEMS-based thermal conductivity detectors is rewriting the cost-performance frontier for handheld analytical instruments. Thermo Fisher Scientific leverages its ion trap mass spectrometer integration to sustain premium positioning in pharmaceutical field audits. Agilent Technologies anchors its position through capillary flow technology that compresses separation times for petrochemical clients. PerkinElmer competes on modular detector architectures that swap between FID and TCD configurations without factory recalibration.
A portable gas chromatograph is a self-contained analytical instrument that separates volatile compounds via coated capillary columns, typically 10–30 meters in length, using carrier gas flow rates of 1–2 mL per minute, with detection limits reaching parts-per-billion for environmental contaminants. Its primary commercial purpose is delivering laboratory-grade qualitative and quantitative analysis at remote sites without sample degradation from transport delays. Miniaturized systems now capture the fastest expansion trajectory as battery-operated units shrink to under five kilograms while retaining dual-column resolution. Environmental Monitoring applications lead absolute revenue contribution due to EPA Method TO-15 enforcement for ambient air toxics, though Pharmaceutical Analysis commands the highest per-unit margins from validation-heavy cGMP compliance requirements.
EPA Method TO-15 and the ECHA REACH framework tighten detection thresholds for benzene and halogenated volatiles, forcing instrument upgrades at municipal air stations and industrial fence-line monitors. FDA cGMP Annex 15 and the EU GMP Chapter 6 guidelines mandate periodic verification of chromatographic systems, creating recurring calibration and service revenue pools for deployed portable fleets. Stakeholders must weigh the trade-off between detector sensitivity gains from micro-GC architectures and the certification burden of qualifying novel column chemistries under existing pharmacopeial methods.
Market Dynamics
Micro-fabricated column architectures and MEMS-based detection systems are compressing instrument footprints below five kilograms while preserving laboratory-grade resolution, fundamentally altering deployment economics for field analytical services.
Growth Catalysts
- EPA Method TO-15 Enforcement:Ambient air monitoring stations across the United States face mandatory upgrades for benzene and halogenated volatile detection, accelerating replacement cycles for legacy laboratory-bound systems.
- Shale Corridor Field Deployment:Hydrocarbon fingerprinting at wellheads and pipeline interconnections eliminates sample degradation risks and laboratory turnaround delays for upstream operators.
- MEMS Thermal Conductivity Detectors:Silicon-micro machined sensor arrays reduce power consumption and warm-up times, enabling battery-operated deployment in remote environmental monitoring stations.
Market Restraints
- Helium Carrier Gas Supply Concentration:Qatar and the United States control over eighty percent of global helium refining capacity, exposing instrument operators to price volatility and allocation disruptions.
- Pharmacopeial Recertification Burden:Novel column chemistries require extensive validation under USP and EP monographs before pharmaceutical manufacturers accept field-generated data for cGMP compliance.
- Laboratory Service Contract Lock-in:Centralized analytical facilities operate under multi-year service agreements that penalize early termination, slowing portable unit adoption at industrial sites.
Strategic Opportunities
- EU F-Gas Regulation Phase-Down:Restrictions on hydrofluorocarbon refrigerants create demand for portable leak detection and verification systems at cold storage facilities and chemical processing plants.
- India Environmental Monitoring Expansion:The Central Pollution Control Board mandates continuous ambient air quality monitoring in tier-two industrial cities lacking laboratory infrastructure.
- Hyphenated Detection Convergence:Integration of ion mobility spectrometry with micro-GC separation expands compound identification capability for explosive trace and chemical warfare agent detection.
Industry Challenges
- Analytical Chemist Field Deployment Shortage:Interpretation of complex chromatograms at remote sites requires specialized training that instrument vendors struggle to embed in standard operator certification programs.
- Multi-Detector Calibration Drift:Flame ionization and thermal conductivity configurations demand distinct reference standards and maintenance protocols, complicating fleet standardization for rental service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Gas Chromatograph Market |
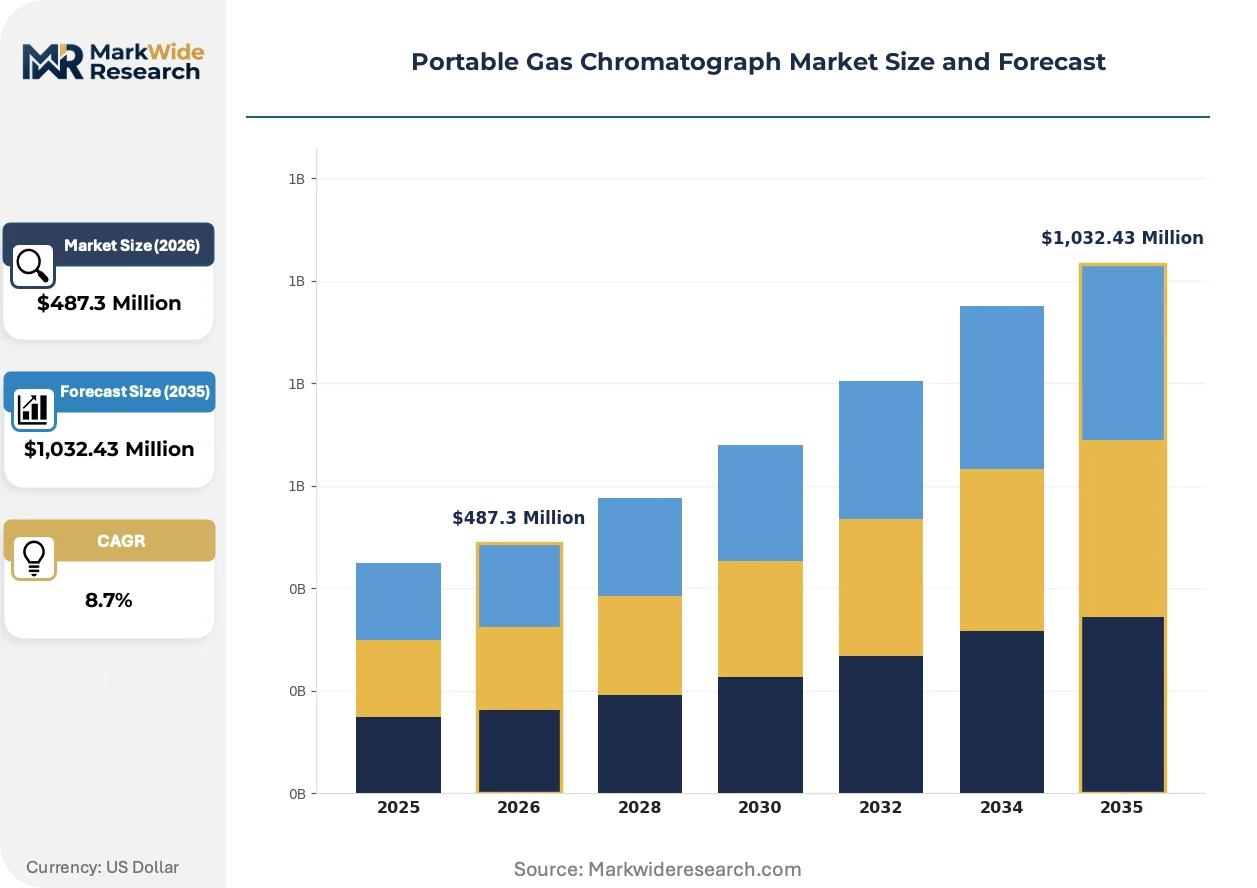
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Column, Dual Column, Multi-Column, Miniaturized Application: Environmental Monitoring, Food Safety, Pharmaceutical Analysis, Petrochemical Testing End User: Laboratories, Research Institutions, Manufacturing Plants, Field Testing Deployment: On-site, Portable, Desktop, Hybrid |
| Companies Covered | Emerson Electric Co., Thermo Fisher Scientific, Agilent Technologies, PerkinElmer, Shimadzu Corporation, ABB Ltd., Siemens AG, Bruker, Horiba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Gas Chromatograph Market Strategic Shifts
Portable gas chromatography is transitioning from laboratory extension to autonomous field decision-tool, with hardware miniaturization, detection hyphenation, and service model unbundling converging to reshape buyer value expectations.
Silicon-micro machined column substrates with integrated heaters are rendering obsolete conventional fused-silica capillary assemblies that require external oven temperature control. Environmental remediation contractors in the United States and Germany now specify chip-based systems for same-day soil vapor intrusion assessments. The elimination of thermal mass reduces power draw by orders of magnitude, compressing battery weight and enabling true handheld operation.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in consumer products tighten detection thresholds for import screening at European customs facilities. Industrial hygiene laboratories serving toy and textile manufacturers face expanded analytical workloads that fixed laboratory capacity cannot absorb. Portable units with photoionization detection are deploying at port-of-entry inspection stations to triage samples before laboratory confirmation.
Equipment leasing and managed service contracts are displacing capital purchase models for municipal air quality networks with constrained instrumentation budgets. Dutch and Belgian environmental agencies now contract chromatographic monitoring as operational expenditure, transferring calibration and maintenance liability to instrument vendors. The shift compresses procurement cycles from multi-year capital appropriations to annual service renewals.
Portable Gas Chromatograph Market Segmentation
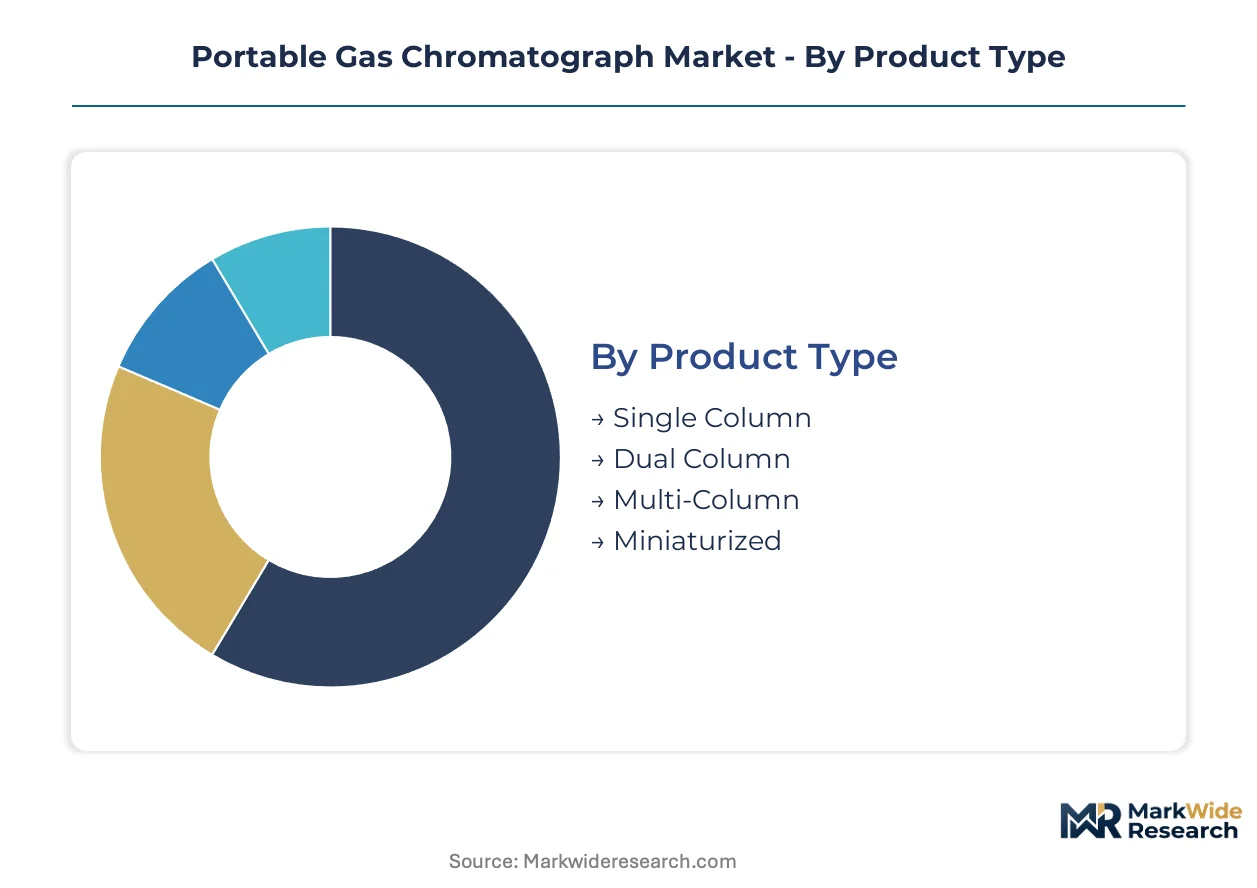
Portable gas chromatograph segmentation reveals divergent replacement cycles across product architectures, with miniaturized units refreshing every 3-4 years versus 8-10 year lifespans for laboratory-hardened systems. Application-driven purchasing further stratifies the market, as environmental compliance mandates force faster upgrade cadences than pharmaceutical validation protocols permit.
Product Type:
Replacement velocity varies dramatically across column architectures, with single-column systems turning over fastest due to obsolescence pressure from MEMS-based alternatives while multi-column platforms persist through decade-long service contracts.
- Single Column:Basic separation architecture employing one coated capillary column with external oven temperature control. Municipal air quality stations in Germany and the United States deploy these for benzene monitoring under EPA Method TO-15, though operators face replacement pressure as chip-based alternatives drop below five kilograms.
- Miniaturized:Silicon-micro machined substrates with integrated heaters eliminate thermal mass and external oven requirements. Environmental remediation contractors specify these for same-day soil vapor intrusion assessments, compressing power draw and enabling true handheld battery operation.
- Dual Column:Parallel separation channels enable confirmatory analysis or simultaneous detection of complementary compound classes. Petrochemical field services favor this architecture for hydrocarbon fingerprinting at wellheads.
- Multi-Column:Complex valve-switching configurations support comprehensive speciation across extended boiling point ranges. Research institutions deploy these for method development requiring maximum analytical flexibility.
Single Column anchors the volume base while Miniaturized gains share at the steepest rate.
Application:
Regulatory enforcement intensity determines margin structure across use cases, with compliance-heavy applications commanding service premiums versus commodity testing workflows.
- Environmental Monitoring:Ambient air toxics detection governed by EPA Method TO-15 and ECHA REACH frameworks. Field-deployable units at fence-line monitors and municipal stations face mandatory detection threshold upgrades, accelerating replacement cycles for legacy laboratory-bound systems.
- Pharmaceutical Analysis:cGMP-compliant chromatographic verification under FDA Annex 15 and EU GMP Chapter 6 guidelines. Per-unit margins peak here due to validation-heavy documentation requirements and recurring calibration service contracts.
- Petrochemical Testing:On-site hydrocarbon fingerprinting eliminates sample degradation from transport delays. Shale corridor operators in the United States deploy portable units at wellheads and pipeline interconnections.
- Food Safety:Residue screening and contaminant detection for import verification. European customs facilities deploy portable units with photoionization detection to triage samples before laboratory confirmation under REACH Annex XVII restrictions.
Environmental Monitoring anchors the volume base while Pharmaceutical Analysis commands the highest service attach rates.
End User:
Capital availability and technical staffing depth create distinct procurement patterns, with centralized laboratories favoring multi-year service contracts versus field operators prioritizing operational expenditure flexibility.
- Laboratories:Centralized analytical facilities with dedicated instrumentation budgets and trained chromatographers. These sites operate under multi-year service agreements that penalize early termination, slowing portable unit adoption.
- Field Testing:Mobile analytical services and environmental contractors requiring rapid deployment without fixed infrastructure. Dutch and Belgian environmental agencies now contract chromatographic monitoring as operational expenditure.
- Manufacturing Plants:In-process quality control and environmental compliance at industrial facilities. Cold storage operators deploy portable leak detection systems under EU F-Gas Regulation phase-down requirements.
- Research Institutions:Method development and academic investigation requiring maximum analytical flexibility. These users drive early adoption of hyphenated detection configurations.
Laboratories anchor the volume base while Field Testing climbs the fastest as managed service contracts displace capital purchase models.
Deployment:
Physical form factor determines addressable use cases, with weight and power constraints filtering out certain field environments while desktop configurations retain resolution advantages for complex separations.
- Portable:Battery-operated units under five kilograms with MEMS-based detection. These systems deploy at remote environmental monitoring stations where helium carrier gas supply disruptions complicate logistics.
- On-site:Vehicle-mounted or trailer-housed systems transported to temporary field locations. Petrochemical operators favor this architecture for pipeline integrity testing campaigns.
- Desktop:Laboratory-grade resolution in transportable enclosures requiring external power. These units serve industrial hygiene laboratories facing expanded workloads that fixed capacity cannot absorb.
- Hybrid:Configurable systems switching between benchtop precision and field portability through modular detector swaps. Rental service providers favor this flexibility for fleet standardization.
Desktop anchors the volume base while Portable expands most quickly as silicon-micro machined architectures compress instrument footprints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German environmental monitoring agencies export field-deployable analytical systems to shale corridor operators across the United States, establishing a transatlantic trade flow in portable chromatographic instrumentation.
United States
Shale gas operators in Texas and North Dakota deploy portable units for wellhead hydrocarbon fingerprinting to bypass laboratory turnaround delays. EPA Method TO-15 enforcement mandates benzene detection upgrades at municipal air stations in California and Pennsylvania. Field testing contractors in the Permian Basin now lease MEMS-based systems under managed service contracts rather than capital purchase.
Germany
Environmental remediation firms specify chip-based micro-GC systems for same-day soil vapor intrusion assessments in the Ruhr industrial region. ECHA REACH framework restrictions on halogenated volatiles tighten detection thresholds at fence-line monitors along the Rhine chemical corridor. Municipal air quality networks in Bavaria contract chromatographic monitoring as operational expenditure to transfer calibration liability to vendors.
China
Industrial hygiene laboratories in the Yangtze River Delta face expanded workloads from import screening under tightened consumer product safety standards. The Ministry of Ecology and Environment mandates continuous ambient air monitoring in tier-two industrial cities lacking fixed laboratory infrastructure. Customs facilities at Shanghai port deploy portable photoionization detection units to triage samples before laboratory confirmation.
India
The Central Pollution Control Board mandates continuous ambient air quality monitoring in tier-two industrial cities across Maharashtra and Gujarat where laboratory infrastructure remains underdeveloped. Pharmaceutical manufacturers in Hyderabad and Bangalore field-deploy portable units for cGMP-compliant chromatographic verification under CDSCO guidelines. Environmental contractors in the Delhi-NCR corridor lease battery-operated systems for rapid deployment at construction sites.
Netherlands
Dutch environmental agencies contract chromatographic monitoring as operational expenditure under EU F-Gas Regulation phase-down requirements for cold storage leak detection. Port of Rotterdam customs facilities deploy portable units with photoionization detection to screen imported textiles and toys for polycyclic aromatic hydrocarbons. Research institutions in Eindhoven drive early adoption of hyphenated detection configurations for method development.
Portable Gas Chromatograph Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers: diversified analytical instrument conglomerates, specialized chromatography houses, and emerging MEMS-based disruptors. Tier-one players leverage ion trap mass spectrometer integration and capillary flow technology to sustain premium positioning. Tier-two competitors compete on modular detector architectures and rapid column chemistry validation. Dominant competitive moves include technology licensing agreements for micro-fabricated substrates and strategic partnerships with environmental service contractors to embed instruments in managed monitoring networks.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Agilent Technologies occupy positions defined by hyphenated detection convergence and pharmaceutical field audit penetration. PerkinElmer exemplifies the modular specialist archetype through detector configuration flexibility. Among precision instrumentation houses, Shimadzu Corporation and Bruker represent scale-driven manufacturing depth, while Horiba anchors the environmental monitoring application vector. Emerson Electric Co., ABB Ltd., and Siemens AG sit within the industrial automation integrator segment, leveraging process control distribution channels to place analytical instruments at manufacturing plant sites.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Thermo Fisher Scientific |
| Agilent Technologies |
| PerkinElmer |
| Shimadzu Corporation |
| ABB Ltd. |
| Siemens AG |
| Bruker |
| Horiba |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in MEMS-micro machined detector fabrication facilities across Germany and the United States is compressing supplier margins while elevating pricing power for qualified chip-based column substrates. This utilization squeeze forces instrument vendors to prioritize pharmaceutical and environmental compliance buyers who accept premium positioning, while municipal air quality networks face extended lead times or tier-downgrades to legacy fused-silia architectures.
Pricing Analysis
Current-generation MEMS-based units command a substantial premium over prior-generation single-column systems with external oven control, while next-generation hyphenated detection configurations with ion mobility spectrometry sit at the apex of the price pyramid. Three-tier pricing structure across premium, standard, and economy levels stratifies by detector sophistication and validation documentation depth. Price differentiation hinges on EPA Method TO-15 certification tier and after-sales calibration bundling. Cost compression in the standard tier is intensifying because MEMS foundries are achieving yield improvements that transfer downstream. Municipal environmental agencies exhibit the highest price sensitivity, while pharmaceutical manufacturers under FDA cGMP Annex 15 pressure demonstrate the lowest.
Supply Chain Analysis
Upstream helium refining capacity concentrates in Qatar and the United States, exposing chromatograph operators to allocation disruptions that ripple through carrier gas pricing and instrument deployment economics. Raw material dependencies extend to silicon wafer substrates for MEMS fabrication, fused-silica capillary stock from specialized glass manufacturers, and noble gas supply contracts. Single-source vulnerability in helium logistics represents the dominant structural risk, with Qatar's export policy shifts capable of disrupting field testing operations globally. Distribution runs through analytical instrument distributors serving laboratory and industrial hygiene channels, with direct vendor-to-contractor relationships expanding in the environmental remediation segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from calibration and validation contracts is expanding faster than hardware unit sales, creating a recurring-revenue layer that justifies premium valuations for vendors who can embed their instruments in managed monitoring networks. This shift rewards players who transition from transactional equipment sales to operational expenditure partnerships.
For Market Incumbents: Build certification moats around EPA Method TO-15 and ECHA REACH compliance documentation to lock out MEMS-based challengers lacking pharmacopeial validation histories. Defensive moves should concentrate on backward integration into helium recycling systems to neutralize carrier gas supply volatility, paired with capacity addition in Bavaria and Texas to anchor service response times for shale corridor and Rhine chemical belt clients.
For New Entrants and Emerging Players: Pursue white-space capture in India's tier-two industrial cities where Central Pollution Control Board mandates outrun laboratory infrastructure development. The most penetrable segment lies in battery-operated portable units for construction site monitoring in the Delhi-NCR corridor. A rental-service-first go-to-market angle bypasses capital purchase friction at municipal agencies.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among modular-detector specialists with fleet-standardization capabilities serving multi-site pharmaceutical manufacturers. Long-term viability across the analysis window favors vendors with hyphenated detection roadmaps and established EMA rapport. Acquisition target archetype: MEMS-foundry-integrated instrument houses with unresolved pharmacopeial validation gaps. The signal to watch is EPA detection threshold tightening announcements that force replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Helium Recycling Infrastructure Investment | Captive carrier gas supply neutralizes Qatar allocation risk for field-deployed fleets. |
| Pharmacopeial Validation Fast-Track | USP and EP monograph qualification accelerates pharmaceutical market entry against incumbents. |
| Managed Service Contract Expansion | Operational expenditure models transfer calibration liability and compress municipal procurement cycles. |
| Hyphenated Detection Integration | Ion mobility spectrometry convergence expands addressable use cases into explosive trace detection. |
| Regional Foundry Partnership | MEMS fabrication access in Germany or the United States secures substrate supply for miniaturized architectures. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with chromatography product managers, environmental compliance officers at petrochemical operators, municipal air quality instrumentation leads, and aftermarket service directors; and secondary validation against EPA enforcement bulletins, ECHA REACH restriction updates, FDA cGMP guidance documents, and customs trade data on analytical instrument imports. Bottom-up unit economics triangulated against top-down market sizing across product architectures, application verticals, and deployment form factors.
Forecast inputs considered MEMS yield improvement trajectories, helium supply contract renewal patterns, and regulatory detection threshold adjustment probabilities across the projection horizon. Segmentation dimensions modeled include column architecture tier, compliance application intensity, end-user capital availability, and regional laboratory infrastructure maturity. CAGRs derived from replacement cycle compression rates in environmental monitoring versus pharmaceutical validation-heavy segments, with shale corridor deployment velocity and EU F-Gas Regulation enforcement intensity as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles or helium spot pricing would shift the trajectory for instrument procurement and field service profitability. Forecasts reflect assumptions about regulatory enforcement continuity and MEMS fabrication scale-up success. Cross-checking against EPA and ECHA enforcement budget disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Atomic Spectroscopy Market
Analytical Instruments
Flashpoint Analyzer Market
Analytical Instruments
Illuminometer Market
Analytical Instruments
Handheld XRF Spectrometer Market
Analytical Instruments
TDLAS Moisture Analyzers Market
Analytical Instruments
Coating Thickness Measurement Instruments Market
Analytical Instruments
Surface Plasmon Resonance (SPR) System Market
Analytical Instruments
Battery Testers and Analyzers Market
Analytical Instruments
Global IR Spectroscopy Market
Analytical Instruments
Bolometer Market
Analytical Instruments
Global Particle Size Analyzer Market
Analytical Instruments
Ultraviolet (UV) Analyzer Market
Analytical Instruments
Trace Chemical Detector Market
Analytical Instruments
Air Sampling Equipment Market
Analytical Instruments
Modular Instruments Market
Analytical Instruments
Dissolved Gas Analyzer Market