
 Middle East and Africa Processed Meat Market | 2026-2036
Middle East and Africa Processed Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Processed Meat Market Foresight
EU Green Deal-aligned sustainability benchmarks are shifting procurement criteria for Middle East and Africa foodservice buyers, who now prioritize suppliers with verified carbon accounting and water stewardship protocols. Al Islami Foods leverages its integrated halal supply chain to sustain premium positioning across Gulf retail channels. BRF S.A. anchors its regional competitiveness through large-scale poultry processing complexes in Saudi Arabia. JBS competes on beef and lamb product breadth, while Tanmiah Food Group differentiates through localized feed-to-fork operations in the Kingdom.
Processed meat comprises animal proteins subjected to curing, smoking, fermentation, thermal processing, or mechanical restructuring to extend shelf life, enhance flavor profiles, and ensure microbial safety, typically achieving water activity below 0.95 and incorporating nitrite or natural preservative systems for color stabilization and botulism inhibition. Sausages and deli meats dominate volume throughput across Middle East and Africa retail and foodservice channels, reflecting their compatibility with flatbread-based consumption patterns and quick-service restaurant formats. Modified atmosphere packaging is gaining share over vacuum packs in premium urban supermarkets, as retailers seek extended case-life for chilled sliced products. Online retail remains the fastest-growing distribution channel, though cold-chain reliability constraints limit penetration outside major metropolitan zones.
SFDA in Saudi Arabia and Emirates Food Safety in the UAE enforce halal integrity and additive labeling standards that determine market access for imported and domestically produced processed meats. Egypt's Food Safety National Authority and South Africa's Department of Health apply parallel microbiological criteria and import inspection regimes that shape regional trade flows. Stakeholders must monitor evolving national halal certification reciprocity agreements and cold-chain infrastructure investments as determinants of competitive positioning in this fragmented but expanding market.
Market Dynamics
Halal certification mandates from Saudi Arabia's SFDA and the UAE's Emirates Food Safety are restructuring procurement protocols across Gulf Cooperation Council foodservice channels, forcing ingredient traceability investments that reshape supplier economics.
Growth Catalysts
- EU Green Deal Benchmarks:Carbon accounting and water stewardship protocols from European sustainability frameworks are now required by Middle East and Africa foodservice buyers, redirecting procurement toward verified suppliers.
- Urban Retail Modernization:Cold-chain infrastructure expansion in Egypt and Nigeria is accelerating packaged meat penetration into previously underserved metropolitan zones.
- Flatbread Compatibility:Sausage and deli meat formats align with regional consumption patterns in quick-service restaurant formats across Gulf states, sustaining volume throughput.
Market Restraints
- Feed Input Volatility:Poultry and cattle feed grain prices fluctuate with Black Sea supply disruptions, compressing margin predictability for processors operating in Saudi Arabia and the UAE.
- Cold-Chain Gaps:Refrigerated logistics reliability constraints outside major metropolitan zones in Nigeria and Egypt limit distribution reach for chilled sliced products.
- Halal Reciprocity Fragmentation:Non-uniform national certification standards between Gulf Cooperation Council states and North African markets create import inspection friction and compliance duplication.
Strategic Opportunities
- Nigerian Secondary Cities:Cold-chain underpenetration in Kano, Ibadan, and Port Harcourt presents first-mover advantage for shelf-stable processed protein distribution.
- Modified Atmosphere Packaging:Premium urban supermarkets in Dubai, Riyadh, and Cairo are replacing vacuum packs with gas-flushed formats to extend case-life for chilled deli items.
- Online Retail Infrastructure:E-commerce meat delivery platforms are expanding fastest in Saudi Arabia and South Africa, bypassing traditional wholesale layers.
Industry Challenges
- Halal Auditor Scarcity:Certified halal inspection personnel shortages across Egypt and Nigeria delay facility approvals and constrain production ramp timelines.
- Nitrite Substitution Complexity:Natural preservative system reformulation to meet clean-label preferences while maintaining botulism inhibition and color stability requires extended R&D cycles.
- Legacy Cold-Asset Stranding:Existing refrigerated warehouse networks in South Africa and Kenya face retrofit costs to meet modified atmosphere handling requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Processed Meat Market |
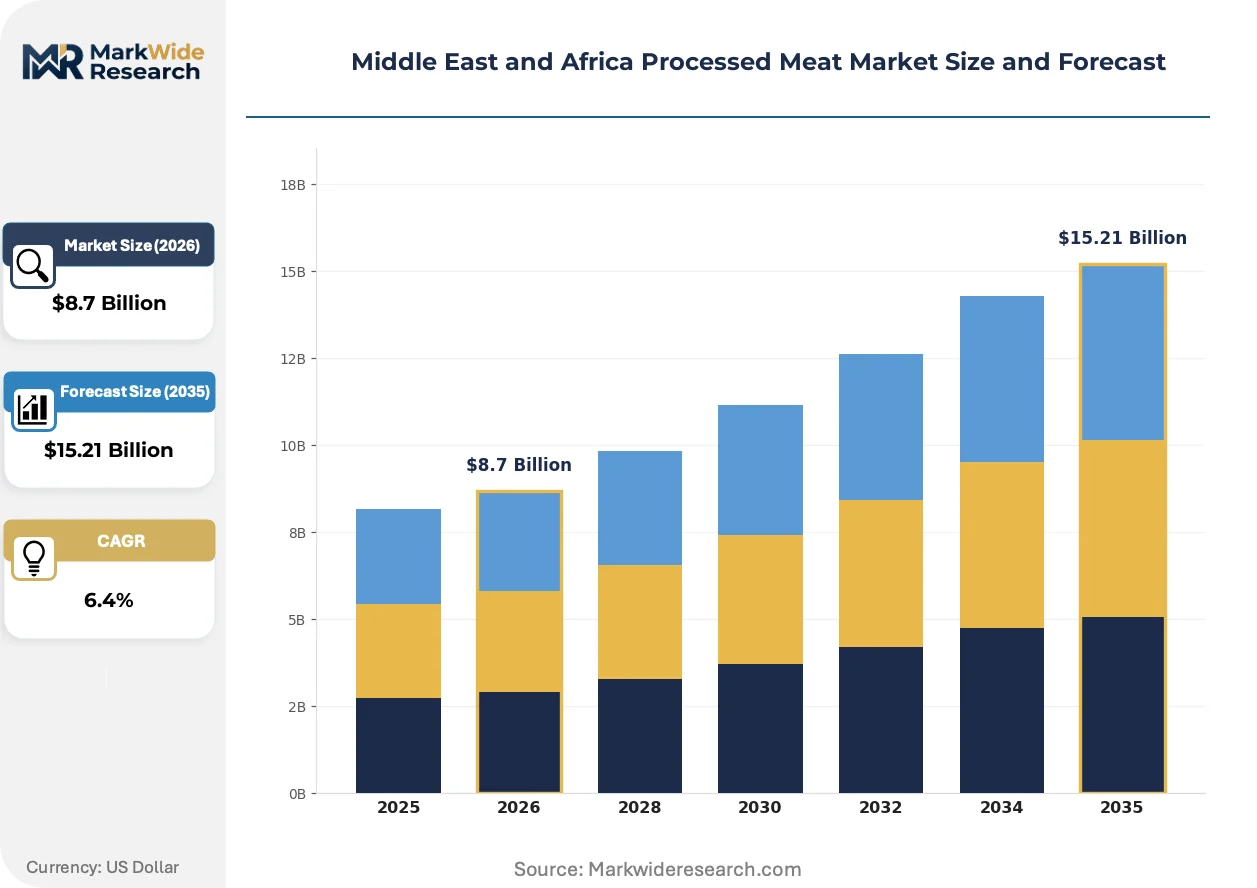
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sausages, Bacon, Deli Meats, Ham Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores End User: Restaurants, Retail Consumers, Hotels, Catering Services Packaging Type: Vacuum Packs, Canned, Modified Atmosphere Packaging, Trays |
| Companies Covered | Almarai Company, Al Kabeer Group, Al Islami Foods, BRF S.A., JBS, Americana Group, Tanmiah Food Group, Siniora Food Industries Company, Sunbulah Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Processed Meat Market Shifts & Advancements
Processing technology and packaging formats are converging to extend shelf stability while satisfying halal integrity and clean-label demands across Middle East and Africa distribution channels.
High-pressure processing technology is overtaking traditional thermal treatments for premium chilled deli meats in Saudi Arabia and UAE retail channels. Gulf supermarket operators are adopting HPP-equipped central kitchens to deliver extended refrigerated case-life without chemical preservatives. This equipment shift is compressing the viable supplier base to capitalized processors capable of six-figure equipment investments.
Emirates Food Safety and SFDA are synchronizing additive labeling standards and halal integrity documentation requirements across the Gulf Cooperation Council. This regulatory convergence is eliminating duplicate testing costs for multi-market suppliers while disqualifying processors lacking integrated supply chain visibility. Egyptian and South African exporters must now maintain parallel certification tracks to access both Gulf and domestic North African markets.
Foodservice procurement from hotels and catering services is consolidating toward direct supplier relationships with verified carbon accounting. Large hospitality groups in Dubai and Riyadh are bypassing traditional wholesale intermediaries to secure shelf-stable proteins with documented water stewardship protocols. South African casino resort chains and Nigerian hotel developments are replicating this procurement model, though cold-chain reliability gaps delay full implementation in secondary cities.
Middle East and Africa Processed Meat Market Segmentation
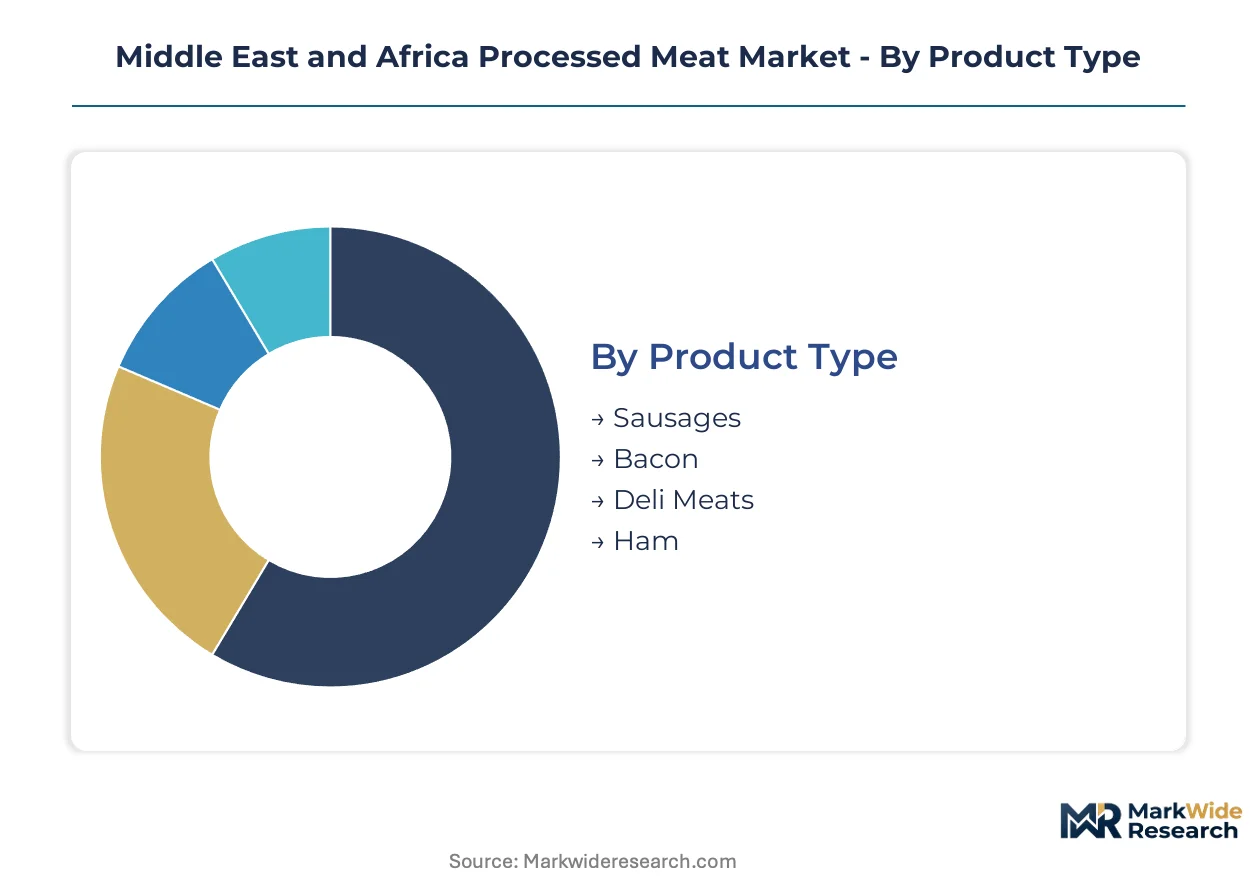
Segmentation across product format, channel, and packaging technology reveals divergent margin structures and capital requirements across Middle East and Africa processed meat value chains. Upgrade cycles in packaging equipment and cold-chain logistics are reconfiguring competitive positions within each category.
Product Type:
Replacement of legacy thermal processing lines with high-pressure equipment is concentrating investment among capitalized processors serving Gulf retail channels.
- Sausages:Ground meat emulsions stuffed into natural or collagen casings, achieving water activity below 0.95 through fermentation or thermal processing. Demand concentrates in quick-service restaurant chains across Saudi Arabia and the UAE, where flatbread compatibility drives volume throughput in breakfast and sandwich formats.
- Deli Meats:Sliced cured or cooked whole-muscle products, including turkey breast and beef pastrami, requiring precise pH control and nitrite stabilization for color retention. Cairo and Dubai supermarkets are expanding chilled deli counters, though cold-chain gaps in Nigerian secondary cities limit penetration.
- Bacon:Cured and smoked pork belly strips, predominantly consumed in South Africa's foodservice sector and non-Muslim hospitality segments.
- Ham:Cured pork leg products, processed through brine injection and thermal smoking, with demand concentrated in South African retail and Egyptian hotel catering.
Volume placements concentrate in Sausages; the faster expansion belongs to Deli Meats.
Distribution Channel:
Channel economics vary sharply by working capital intensity and temperature control requirements, with modern retail formats capturing disproportionate shelf-stable protein volumes.
- Supermarkets:Full-service retail formats with dedicated chilled meat counters and modified atmosphere display cases. Lulu Hypermarket and Carrefour UAE are retrofitting stores with HPP-compatible cold rooms to extend case-life for premium sliced products.
- Online Retail:E-commerce platforms bypassing traditional wholesale layers, expanding fastest in Saudi Arabia where delivery infrastructure investments outpace other Gulf markets. Cold-chain reliability constraints outside Riyadh and Jeddah limit serviceable geographic scope.
- Convenience Stores:Small-format urban outlets prioritizing shelf-stable canned and vacuum-packed items over chilled inventory.
- Specialty Stores:Halal-certified butchers and premium meat shops concentrated in affluent Dubai and Riyadh districts, emphasizing provenance labeling and custom cutting.
Transaction volumes dominate Supermarkets; Online Retail is climbing the fastest as logistics infrastructure matures.
End User:
Procurement sophistication diverges between institutional buyers with direct supplier relationships and fragmented retail consumption patterns.
- Hotels:Large hospitality groups in Dubai and Riyadh consolidating procurement through verified carbon accounting requirements, bypassing wholesale intermediaries for shelf-stable proteins with documented water stewardship protocols.
- Catering Services:Institutional foodservice operators across Gulf Cooperation Council states expanding direct supplier relationships, though halal auditor scarcity delays facility approvals for new entrants.
- Restaurants:Independent and chain foodservice operators, with quick-service formats driving sausage and deli meat volumes through flatbread-based menu items.
- Retail Consumers:Household purchasers through modern trade and traditional retail channels, with Egyptian and Nigerian urbanization accelerating packaged meat adoption.
Procurement volumes concentrate in Hotels; Catering Services are gaining share fastest as Gulf foodservice consolidates.
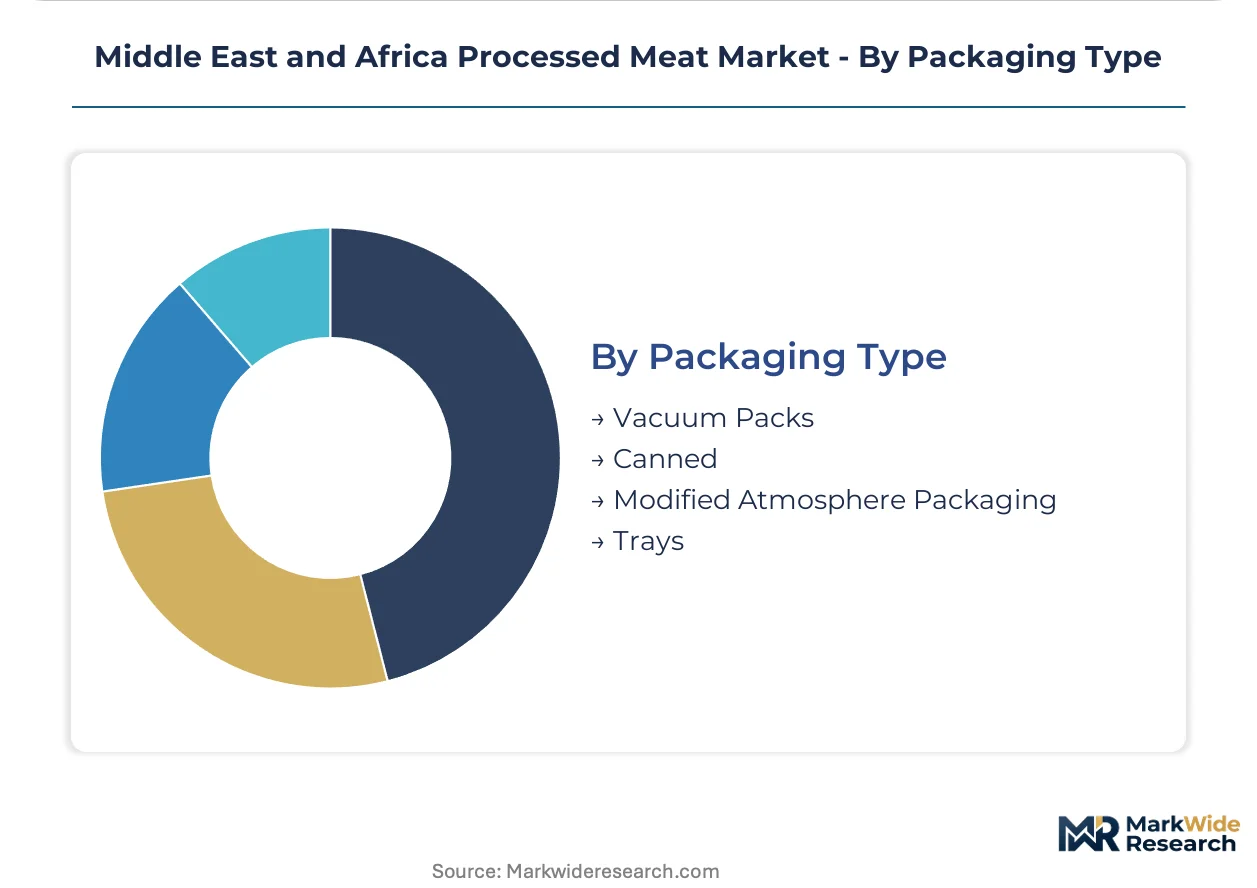
Packaging Type:
Packaging technology selection determines shelf-life extension capabilities and compliance with evolving halal integrity documentation requirements.
- Modified Atmosphere Packaging:Gas-flushed barrier films replacing residual oxygen with nitrogen and carbon dioxide mixtures, extending refrigerated case-life for chilled sliced deli items. Dubai and Riyadh premium supermarkets are displacing vacuum formats with MAP for premium positioning.
- Vacuum Packs:Oxygen-exclusion barrier systems for cooked and cured products, remaining dominant in price-sensitive Egyptian and Nigerian retail channels where cold-chain reliability is inconsistent.
- Canned:Thermally processed shelf-stable formats, critical for distribution in Kano, Ibadan, and Port Harcourt where refrigerated logistics remain underdeveloped.
- Trays:Overwrapped foam or rigid plastic containers for fresh-case presentation, common in South African supermarket meat counters.
Installed base concentrates in Vacuum Packs; Modified Atmosphere Packaging shows the steepest expansion trajectory as Gulf retail modernizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai anchors processed meat distribution across the Gulf Cooperation Council, with Jebel Ali port handling the bulk of refrigerated imports for re-export to Saudi Arabia, Qatar, and Kuwait.
Saudi Arabia
Hotels and catering services in Riyadh and Jeddah are consolidating procurement through direct supplier relationships. SFDA enforces halal integrity and additive labeling standards that determine market access for imported and domestically produced processed meats. The Eastern Province hosts large-scale poultry processing complexes serving domestic retail and regional export channels.
United Arab Emirates
Emirates Food Safety mandates are tightening ingredient traceability requirements across Dubai and Abu Dhabi foodservice channels. Lulu Hypermarket and Carrefour UAE are retrofitting stores with modified atmosphere-compatible cold rooms to extend case-life for premium sliced products. Sharjah's logistics corridors function as halal certification consolidation points for re-export to African markets.
Egypt
Urban retail modernization in Cairo and Alexandria is accelerating cold-chain penetration for packaged meat products. The Food Safety National Authority applies microbiological criteria and import inspection regimes that shape regional trade flows. Secondary cities including Port Said and Suez are emerging as distribution hubs for shelf-stable processed proteins targeting North African markets.
South Africa
Casino resort chains and hotel developments are replicating Gulf procurement models with verified carbon accounting requirements. The Department of Health regulates additive standards and cold-chain compliance for both domestic production and imported processed meats. Gauteng province concentrates meat processing capacity serving retail and institutional buyers across Southern Africa.
Nigeria
Cold-chain underpenetration in Kano, Ibadan, and Port Harcourt presents first-mover advantage for shelf-stable processed protein distribution. Lagos anchors demand from quick-service restaurant chains and modern retail formats expanding into packaged meat categories. National food safety authorities are developing parallel halal certification tracks to access both domestic and Gulf export markets.
Middle East and Africa Processed Meat Market Competitive Landscape
The competitive structure tilts toward integrated halal supply chain operators with captive feed-to-fork visibility. Gulf-based processors with Saudi and UAE regulatory approvals capture disproportionate foodservice volume from hospitality procurement consolidation. Three archetypes dominate: vertically integrated poultry specialists, diversified protein conglomerates with beef and lamb breadth, and localized feed-to-fork operators with Kingdom-specific infrastructure. Capacity expansion and direct supplier relationships with large hospitality groups represent the dominant competitive moves reshaping channel access.
Within the integrated halal tier, Al Islami Foods and Tanmiah Food Group exemplify feed-to-fork positioning with Kingdom-based operations. BRF S.A. anchors the scale-driven segment through Brazilian-origin supply networks serving Gulf retail and foodservice channels. JBS occupies a position in the diversified protein archetype with beef and lamb product breadth across regional markets.
| Leading Market Players |
|---|
| Almarai Company |
| Al Kabeer Group |
| Al Islami Foods |
| BRF S.A. |
| JBS |
| Americana Group |
| Tanmiah Food Group |
| Siniora Food Industries Company |
| Sunbulah Group |
| Others |
Supply & Pricing Matrix
Verified carbon accounting mandates from Dubai and Riyadh hospitality procurement departments are forcing feed-to-fork documentation investments that compress margins for processors lacking integrated supply chain visibility. This buyer-driven specification shift rewards capitalized operators with captive halal certification infrastructure while squeezing commodity traders dependent on spot-market sourcing.
Pricing Analysis
Yield-guaranteed throughput contracts anchor value-based pricing for Gulf foodservice accounts, with documented water stewardship protocols commanding tiered premiums above standard halal-certified supply. Price differentiation rests on feed-to-fork traceability depth and SFDA audit reciprocity coverage. Cost compression in standard-tier poultry supply is intensifying as Brazilian-origin imports face extended logistics cycles. Quick-service restaurant chains exhibit highest price sensitivity; luxury hotel groups prioritize certification grade over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian poultry feedstock flows through Jebel Ali, where port congestion and Black Sea grain price volatility cascade into margin unpredictability. Geographic supply concentration centers on Saudi Arabia's Eastern Province complexes, UAE re-export corridors, and Brazilian-origin maritime routes. Raw material dependencies encompass soy-meal protein inputs, natural-casing collagen supplies, and nitrite preservative systems. Tariff exposure from non-reciprocal halal certification standards between Gulf Cooperation Council states and North African markets fragments distribution efficiency. Distribution runs through Dubai-based logistics consolidators serving multi-market retail and institutional accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
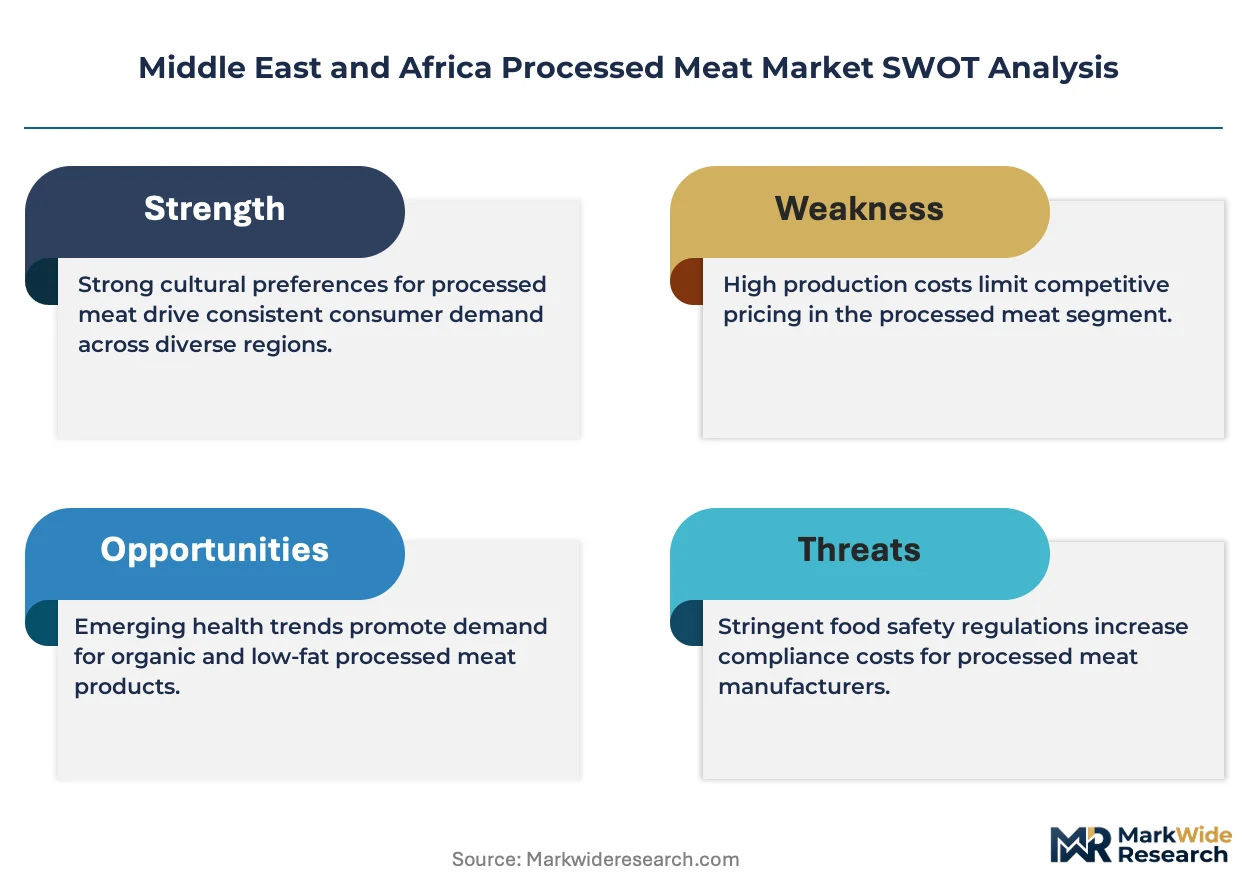
The Middle East and Africa processed meat market functions as a vertical-integration race where feed-to-fork halal certification control determines procurement access to consolidating Gulf hospitality accounts. Players lacking upstream captive supply or downstream direct-buyer relationships face systematic margin erosion.
For Market Incumbents: Deploy modified atmosphere packaging retrofit programs across Egyptian and Nigerian distribution networks to capture premium urban retail positioning before cold-chain infrastructure matures. Consolidate halal auditor training partnerships with SFDA-accredited bodies to accelerate facility approval timelines for regional expansion. Natural preservative system R&D investment represents essential defensive positioning against clean-label substitution threats from emerging regional processors. For New Entrants and Emerging Players: Enter via shelf-stable canned and vacuum-packed formats targeting Kano, Ibadan, and Port Harcourt where refrigerated logistics gaps exclude chilled-product incumbents. Nigerian secondary cities present the most penetrable geography given underdeveloped cold-chain assets and quick-service restaurant format expansion. Go-to-market execution should prioritize direct relationships with institutional catering operators bypassing traditional wholesale intermediaries. For Investors and Strategic Acquirers: Re-rating potential sits with feed-to-fork poultry specialists possessing Kingdom-specific infrastructure and verified carbon accounting documentation given procurement consolidation tailwinds. Long-term viability over the analysis window favors operators with integrated halal supply chains capable of serving both Gulf retail and foodservice channels. Monitor Emirates Food Safety and SFDA certification reciprocity negotiations as the signal indicating accelerated market access consolidation or continued fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Production | Captive soy-meal supply secures margin stability against Black Sea price volatility for Saudi processors. |
| Halal Certification Reciprocity Investment | Parallel SFDA and Emirates Food Safety approvals eliminate duplicate testing costs for multi-market suppliers. |
| Modified Atmosphere Packaging Scale-Up | Gas-flushed barrier film deployment extends case-life for Dubai and Riyadh premium supermarket deli counters. |
| Direct Hospitality Procurement Relationships | Bypassing wholesale layers captures verified carbon accounting premiums from consolidating hotel groups. |
| Natural Preservative System R&D | Clean-label reformulation maintains botulism inhibition while meeting EU Green Deal-aligned buyer specifications. |
Research Methodology
Independent corroboration across primary interviews with halal certification auditors, foodservice procurement directors at Gulf hospitality groups, and cold-chain logistics operators underwrites the qualitative findings. Secondary validation draws from SFDA additive labeling directives, Emirates Food Safety halal integrity documentation requirements, Egyptian Food Safety National Authority import inspection protocols, and customs trade data tracking Brazilian-origin poultry flows through Jebel Ali. Bottom-up channel volume estimates triangulate against top-down macroeconomic consumption proxies for protein demand across urbanization gradients.
Comparable-period anchoring to historical cold-chain penetration rates and halal certification facility approval timelines structured the projection methodology. Segmentation dimensions span product format, packaging technology, distribution channel, and end-user procurement sophistication across the modeling period. CAGRs derive from fitted growth curves incorporating feed input cost trajectories, regulatory reciprocity scenario weighting, and e-commerce logistics maturity indices specific to Saudi and South African delivery infrastructure.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained Black Sea grain supply disruption or accelerated Gulf halal standard harmonization. Forecasts reflect documented assumptions regarding urban retail modernization pace and cold-chain infrastructure investment flows. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Pea Processed Ingredients Market
Processed Foods
Processed Mango Products Market
Processed Foods
Spray Cheese Market
Processed Foods
Artisanal Ice Cream Market
Processed Foods
Low Fat Pasta Market
Processed Foods
Fat Free Food Market
Processed Foods
Processed Peanut Market
Processed Foods
United States Food Spread Market
Processed Foods
Ready-To-Whip Toppings Market
Processed Foods
Low Fat Puddings Market
Processed Foods
Processed Fruit Bases Market
Processed Foods
Fermented Foods Market
Processed Foods
US Tomato Paste Market
Processed Foods
Broth Market
Processed Foods
Imitation Whipped Cream Market
Processed Foods
Chocolate Filling Market