
 Liquid Egg Market | 2026-2036
Liquid Egg Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Egg Market Outlook
Foodservice distribution networks are reconfiguring as institutional buyers consolidate procurement around pasteurized liquid egg suppliers. Rose Acre Farms leverages its vertically integrated layer farms to secure consistent volume for national foodservice contracts. Cal-Maine Foods Inc. anchors the retail channel through private-label and branded liquid egg programs in conventional and organic grades. Eurovo Group competes on specialized egg yolk and egg white fractionation for industrial bakery and confectionery clients across Southern Europe.
Liquid egg comprises shell-less, homogenized egg contents—whole egg, separated whites, separated yolks, or formulated blends—typically pasteurized at 60–64°C to eliminate Salmonella while preserving functional proteins for emulsification, foaming, and coagulation. The product serves industrial food manufacturing where batch consistency, labor reduction, and food safety compliance outweigh commodity shell egg pricing. Whole liquid eggs occupy the largest volume share due to universal applicability across sauces, pasta, and prepared foods. Egg white segments are expanding fastest as protein-fortified beverages and clean-label bakery formulations gain traction in health-positioned product lines. Pouch and carton packaging formats dominate institutional channels, while Tetra Pak aseptic systems are penetrating ambient-stable liquid egg markets in regions with limited cold chain infrastructure.
The USDA's Agricultural Marketing Service enforces grade standards for liquid egg solids content and microbiological limits, while the FDA's Egg Safety Rule mandates continuous refrigeration and Salmonella prevention protocols for producers with 3,000+ hens. EU Regulation 853/2004 requires HACCP-based hazard control and specific hygiene standards for egg products entering the European food manufacturing supply chain. Stakeholders must monitor evolving cage-free and welfare-grade mandates in California's Proposition 12 framework and comparable state-level ballot initiatives, as these production standards cascade through liquid egg pricing and sourcing strategies.
Market Dynamics
Consolidation among layer farm operators is compressing supplier margins while tightening pathogen standards under FDA's Egg Safety Rule reshape qualification protocols for institutional buyers converting from shell to liquid formats.
Growth Catalysts
- QSR chain standardization:National quick-service restaurant networks are mandating liquid egg formats to eliminate shell cracking labor and reduce kitchen cross-contamination risks.
- California Proposition 12:Cage-free production mandates in the United States' largest state economy are accelerating welfare-grade liquid egg supply chain investments.
- High-pressure pasteurization:Non-thermal processing technologies are extending refrigerated shelf life without protein denaturation, opening ambient distribution channels.
Market Restraints
- Feed grain volatility:Corn and soybean meal input costs swing with commodity futures, compressing processor margins during price spikes.
- Midwest layer concentration:Iowa and Indiana house disproportionate hen population, creating regional supply disruption exposure from avian influenza or extreme weather.
- Plant-based emulsifier substitution:Aquafaba and modified starches are displacing egg yolk in vegan bakery formulations.
Strategic Opportunities
- Southeast Asia cold chain expansion:Tetra Pak aseptic packaging partnerships can unlock ambient-stable liquid egg distribution in Indonesia and Vietnam.
- Sports nutrition fortification:Ready-to-drink protein beverages are incorporating pasteurized egg white isolates as clean-label alternatives to whey concentrates.
- EU organic conversion subsidies:Common Agricultural Policy incentives are funding layer farm transitions to certified organic liquid egg production.
Industry Challenges
- Salmonella serotype surveillance:Continuous environmental monitoring and PCR testing protocols require specialized microbiology talent scarce in rural processing regions.
- Fractionation equipment scale-up:Separating yolk and white at industrial throughput demands membrane filtration capex that mid-tier processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Egg Market |
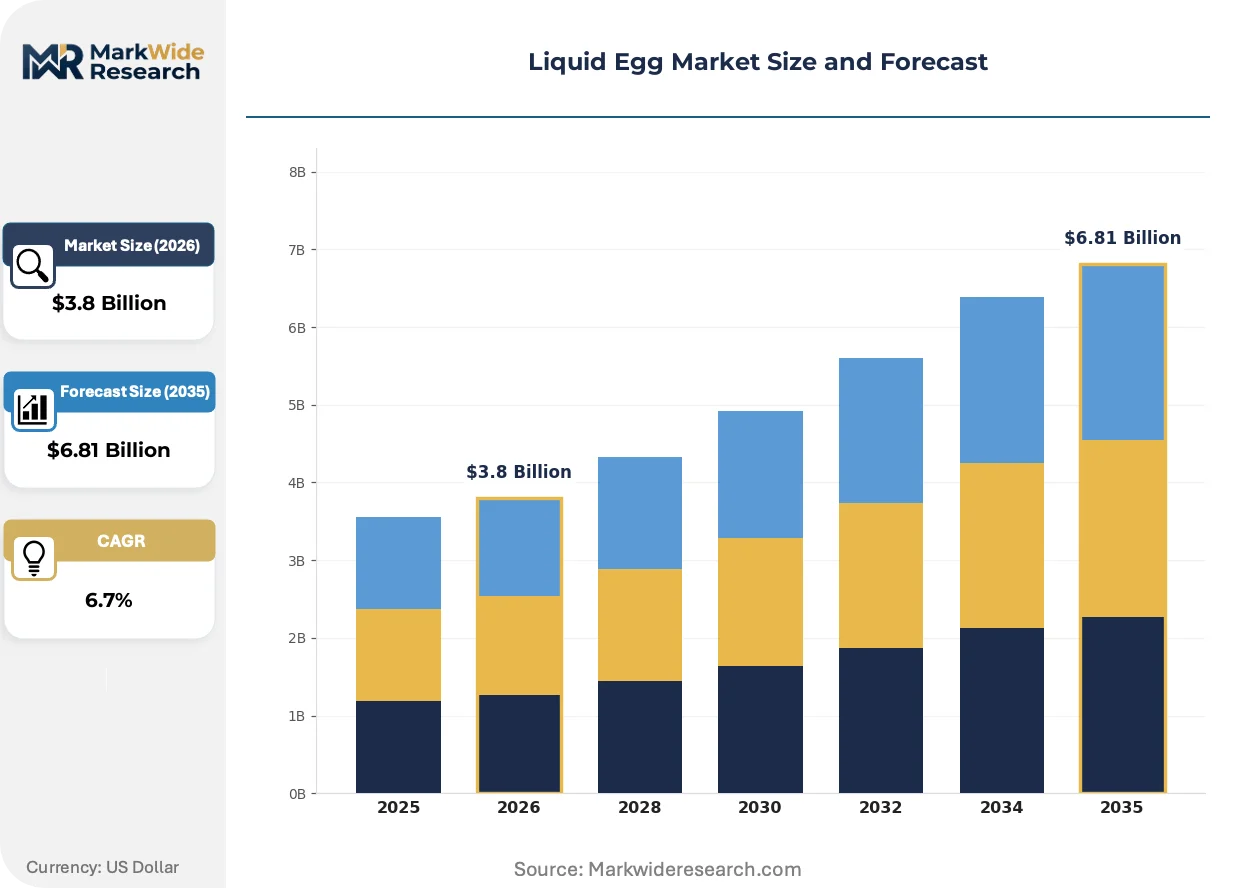
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Liquid Eggs, Egg White, Egg Yolk, Liquid Egg Blends End User: Food Service, Bakeries, Food Manufacturers, Retail Packaging Type: Cartons, Pouches, Tetra Packs, Bottles Distribution Channel: Supermarkets, Online Retailers, Wholesalers, Specialty Stores |
| Companies Covered | Igreca S.A., Rose Acre Farms, Cal-Maine Foods Inc., Interovo Egg Group, Rembrandt Enterprises, Michael Foods Inc., Ovobest Eiprodukte GmbH & Co. KG, Eurovo Group, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Egg Market Strategic Shifts
Processing automation and alternative proteins are forcing liquid egg suppliers to defend functional performance claims while cold chain infrastructure gaps in emerging markets drive packaging format experimentation.
Inline near-infrared spectroscopy is digitizing real-time solids content verification during liquid egg pasteurization. Large-scale bakeries in Germany and the Netherlands are retrofitting production lines with these sensors to eliminate batch-to-batch viscosity variation. The technology is digitizing quality assurance workflows that previously required laboratory hold times, compressing order-to-shipment cycles for just-in-time food manufacturing customers.
EU Regulation 853/2004 hygiene standard updates are mandating enhanced environmental sampling frequencies for egg breaking operations. Processing facilities across France and Spain are investing in automated clean-in-place systems to meet tightened Enterobacteriaceae limits. Industrial bakery clients in Southern Europe are now requiring third-party audit certifications beyond baseline regulatory compliance, shifting supplier selection criteria toward capital-intensive operations.
Food manufacturers are consolidating liquid egg procurement through distributor-managed inventory programs rather than direct mill relationships. National broadline distributors in the United States are capturing volume previously handled by regional egg processors, disintermediating smaller layer cooperatives. This concentration is most visible in the prepared foods sector, where multinational CPG brands are reducing approved supplier lists to simplify traceability compliance under FDA enforcement priorities.
Liquid Egg Market Segmentation
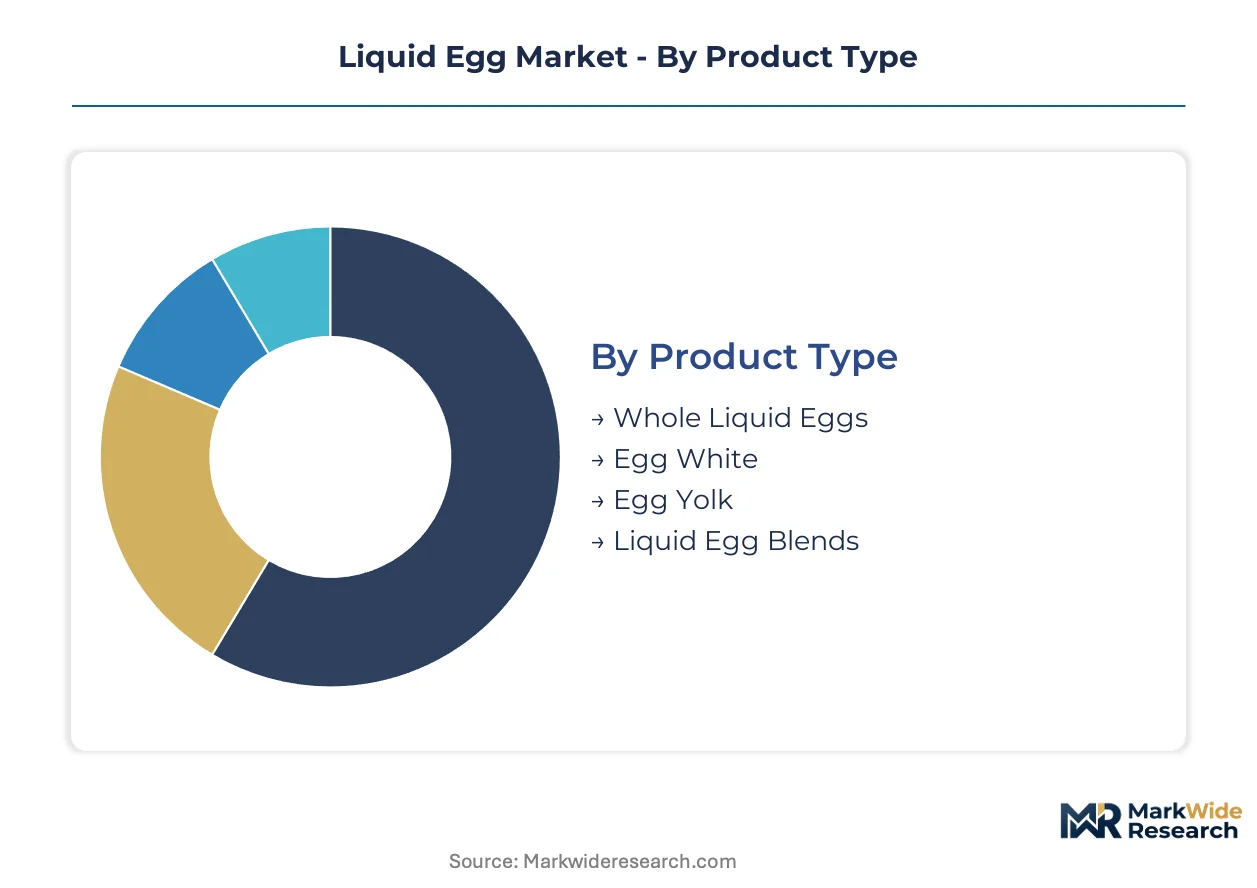
Liquid egg segmentation reflects divergent functional requirements across industrial food manufacturing and consumer channels. Product form, packaging resilience, and distribution reach determine supplier qualification and margin capture in this safety-regulated category.
Product Type:
Industrial applications span emulsification, foaming, and protein fortification needs that dictate viscosity specifications and pasteurization intensity.
- Whole Liquid Eggs:Homogenized blend of yolk and white in natural proportions, pasteurized at 60–64°C for universal sauce, pasta, and prepared food manufacturing. Large-scale bakeries in the United States specify this format for operational simplicity in high-throughput production lines.
- Egg White:Separated albumen fraction with 10–12% protein content, filtered for clarity and standardized for foaming stability. Sports nutrition beverage manufacturers are specifying this segment for clean-label protein fortification in ready-to-drink formulations.
- Egg Yolk:Concentrated lipid-protein emulsion containing lecithin, separated via centrifugal force for mayonnaise and custard applications. Industrial confectionery clients in Southern Europe demand this fraction for texture control in premium chocolate and pastry fillings.
- Liquid Egg Blends:Formulated combinations with salt, citric acid, or gums for specific functional performance. Quick-service restaurant chains specify custom blends to standardize scramble texture and extend refrigerated holding times.
The dominant share belongs to Whole Liquid Eggs, while Egg White is closing the gap fastest.
End User:
Channel requirements diverge sharply on batch size, safety documentation, and delivery frequency.
- Food Service:Institutional kitchens and restaurant chains requiring portion-controlled formats with HACCP compliance documentation. National broadline distributors are consolidating procurement for hotel and cafeteria networks under FDA-mandated traceability protocols.
- Bakeries:Artisan and industrial producers specifying viscosity-tolerant products for consistent dough and batter performance. German industrial bakeries are retrofitting production lines with inline spectroscopy to verify solids content from liquid egg suppliers.
- Food Manufacturers:Multinational CPG brands demanding aseptic or extended-shelf-life formats for prepared meal and sauce production. These buyers are reducing approved supplier lists to simplify compliance with evolving Salmonella surveillance requirements.
- Retail:Conventional and organic grades packaged for home consumption, competing with shell eggs on convenience positioning. Private-label programs at major supermarket chains are capturing volume through cage-free and welfare-grade certifications.
Food Manufacturers command the largest procurement volumes, though Food Service is expanding most quickly as QSR chains convert from shell eggs.
Packaging Type:
Cold chain maturity and shelf-life requirements determine format selection across geographies.
- Cartons:Gable-top paperboard with polyethylene lining for refrigerated distribution in established cold chain markets. This format dominates North American retail and foodservice channels where seven-to-fourteen-day shelf life suffices.
- Pouches:Flexible multilayer films with spout or tear-notch configurations for institutional portion control. European industrial bakeries prefer this format for reduced storage footprint and precise dispensing.
- Tetra Packs:Aseptic carton systems enabling ambient distribution where refrigerated logistics remain underdeveloped. Tetra Pak partnerships are penetrating Southeast Asian markets including Indonesia and Vietnam for shelf-stable liquid egg distribution.
- Bottles:High-density polyethylene or PET containers for retail visibility and resealability. This format competes in premium organic segments where packaging transparency supports clean-label positioning.
Cartons retain the largest installed base, yet Tetra Packs are climbing the fastest as ambient distribution unlocks emerging market penetration.
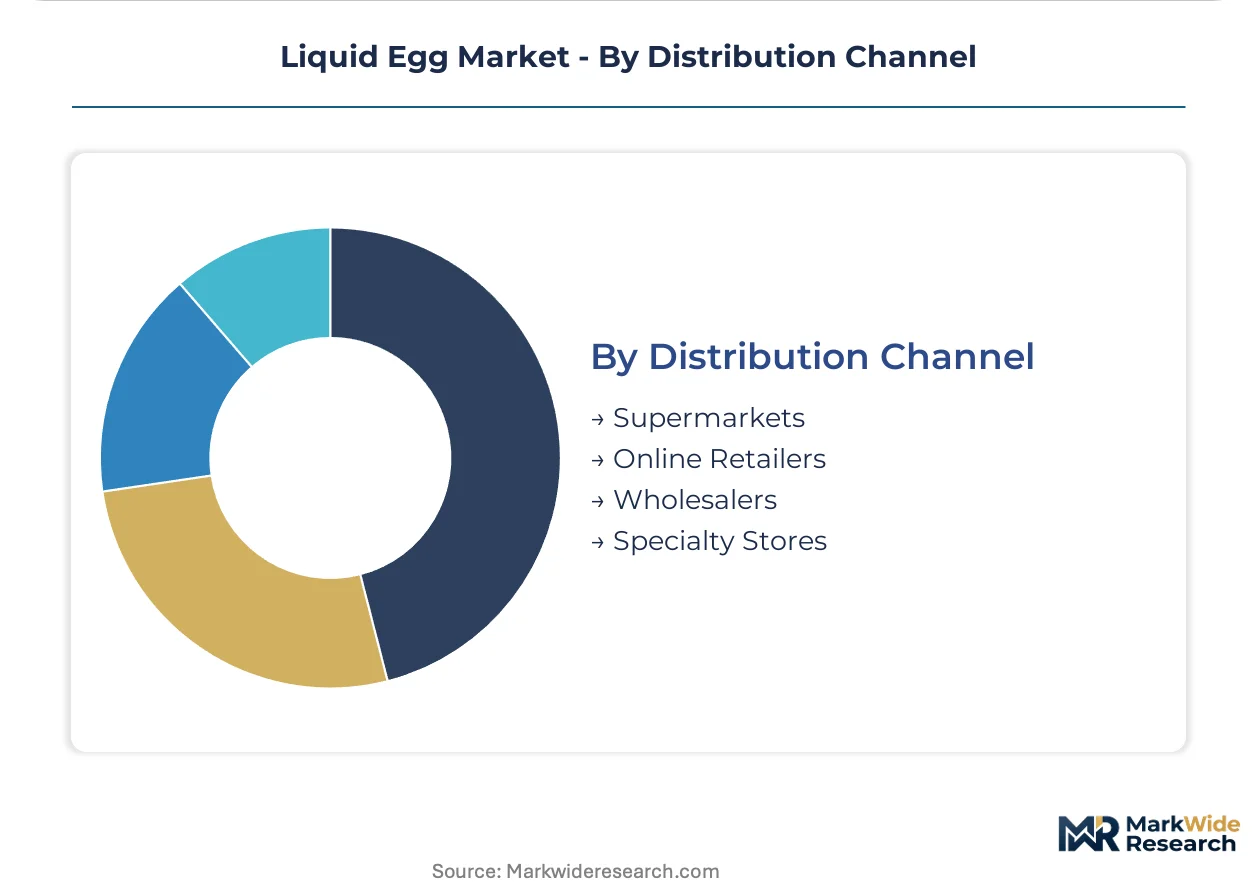
Distribution Channel:
Channel control determines margin retention and traceability compliance burden.
- Supermarkets:Conventional and natural grocery retailers carrying branded and private-label liquid egg in refrigerated dairy cases. Cage-free mandates in California are reshaping shelf allocation toward welfare-certified products.
- Online Retailers:E-commerce platforms with cold-chain delivery capabilities for subscription and bulk home delivery. This channel is capturing urban convenience-seeking consumers in dense metropolitan markets.
- Wholesalers:Broadline distributors managing inventory for foodservice and smaller food manufacturing accounts. These intermediaries are disintermediating regional egg processors as institutional buyers consolidate procurement.
- Specialty Stores:Natural food cooperatives and gourmet retailers emphasizing organic, pasture-raised, or locally sourced liquid egg products. EU organic conversion subsidies are expanding supply for this channel across France and Germany.
Wholesalers handle the greatest throughput volume, while Online Retailers are gaining share fastest in urban delivery zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites Europe's liquid egg import capacity, while Union Pacific's refrigerated rail network anchors North American distribution velocity.
United States
Large-scale bakeries in Chicago and QSR chains converting from shell eggs drive procurement consolidation. The FDA's Egg Safety Rule mandates continuous refrigeration and Salmonella prevention protocols for producers with 3,000-plus hens. Iowa and Indiana house disproportionate hen populations, creating regional supply disruption exposure from avian influenza outbreaks.
Germany
Industrial bakeries in Bavaria retrofit production lines with inline near-infrared spectroscopy for real-time solids verification. EU Regulation 853/2004 requires HACCP-based hazard control and specific hygiene standards for egg products entering food manufacturing supply chains. The Eindhoven-Rotterdam corridor concentrates Tetra Pak aseptic packaging partnerships for ambient-stable distribution.
France
Confectionery manufacturers in Paris Basin demand separated yolk fractions for premium chocolate and pastry texture control. Common Agricultural Policy subsidies fund layer farm transitions to certified organic liquid egg production. Processing facilities across Lyon and Toulouse invest in automated clean-in-place systems to meet tightened Enterobacteriaceae limits.
China
Urban food manufacturers in Yangtze River Delta cities accelerate pasteurized liquid egg adoption for ready-to-eat meal production. The country's national food safety regulator enforces grade standards for liquid egg solids content and microbiological limits. Shanghai's cold chain expansion enables pouch and carton distribution to institutional kitchens previously dependent on shell eggs.
Brazil
Foodservice distributors in São Paulo consolidate procurement around pasteurized suppliers for hotel and cafeteria networks. The country's national agricultural regulator monitors pathogen standards in egg breaking operations. Minas Gerais layer cooperatives face margin compression as national broadline distributors capture volume through distributor-managed inventory programs.
Liquid Egg Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The supplier base exhibits moderate consolidation, with national broadline distributors capturing foodservice volume previously handled by regional processors. Three archetypes dominate: vertically integrated layer-to-liquid operators, specialized fractionation houses, and distributor-managed procurement platforms. Competitive moves concentrate on capacity expansion in cage-free production and strategic partnerships for Tetra Pak aseptic distribution.
Among vertically integrated operators, Rose Acre Farms and Cal-Maine Foods Inc. anchor the North American supply base, while Eurovo Group exemplifies the specialized fractionation tier serving Southern European industrial clients. These three occupy positions that reflect divergent strategic bets on channel control versus functional specialization.
| Leading Market Players |
|---|
| Igreca S.A. |
| Rose Acre Farms |
| Cal-Maine Foods Inc. |
| Interovo Egg Group |
| Rembrandt Enterprises |
| Michael Foods Inc. |
| Ovobest Eiprodukte GmbH & Co. KG |
| Eurovo Group |
| Cargill Incorporated |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Iowa and Indiana layer operations is compressing spot pricing for conventional liquid egg while simultaneously accelerating investment into cage-free capacity that commands structural premiums. This utilization asymmetry between commodity-grade surplus and certified-grade tightness is reshaping procurement negotiations across institutional channels.
Pricing Analysis
Volume-discount tiering structures dominate institutional procurement, with national broadline distributors extracting 8-15% price concessions on annual offtake commitments above 500,000 pounds. Three-tier pricing structure across premium, standard, and economy levels separates cage-free welfare-certified product from conventional pasteurized liquid egg and economy-grade blends for QSR scramble formulations. Pricing pressure stems from feed grain volatility, with corn and soybean meal futures transmitting directly into processor margins. Food manufacturers with multinational procurement desks exhibit lowest price sensitivity due to traceability compliance requirements, while regional bakeries and independent restaurants retain highest elasticity.
Supply Chain Analysis
Export-control regime angles are absent in this commodity category, though the USDA's Egg Safety Rule functions as a de facto capacity restriction by disqualifying producers below 3,000 hens from institutional supply chains. Geographic supply concentration centers on the United States, Germany, and France, with Iowa and Indiana housing disproportionate hen populations that create single-source vulnerability to avian influenza. Raw material dependencies rest on corn, soybean meal, and calcium carbonate for shell formation in layer operations. Distribution runs through national broadline distributors that are disintermediating regional egg processors through distributor-managed inventory programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
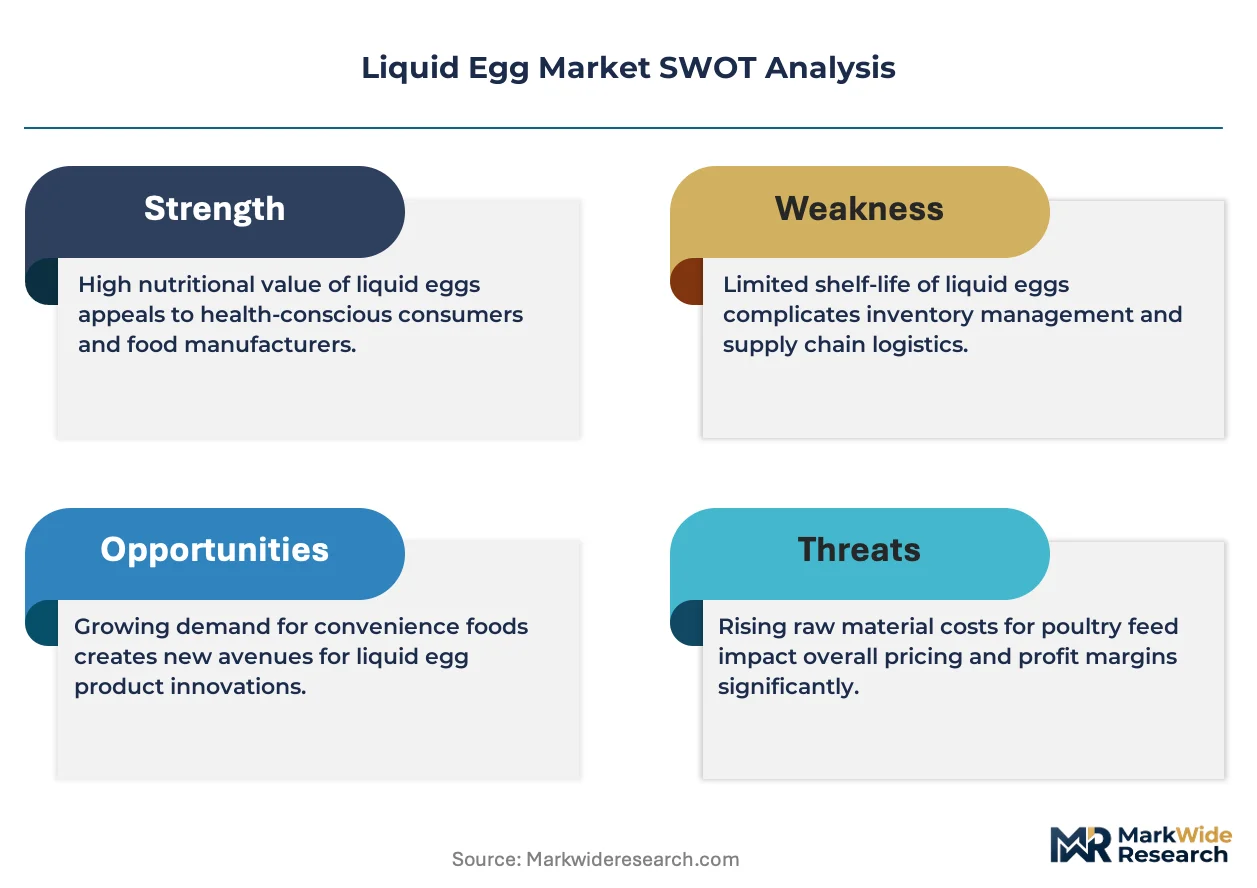
This market presents a defensive-moat story anchored in regulatory entrenchment: FDA and EU hygiene mandates create compliance switching costs that institutional buyers cannot absorb from unqualified suppliers.
For Market Incumbents: Harden supply security through backward integration into cage-free layer farms in California and Midwest corridors, insulating against Proposition 12 supply shocks. Deepen fractionation capabilities to capture premium yolk and white separation demand from Southern European confectionery clients, defending against specialized fractionation houses. Prioritize Tetra Pak aseptic partnerships for Southeast Asian ambient distribution channels where cold chain gaps limit competitor penetration.
For New Entrants and Emerging Players: Pursue white-space opportunities in organic liquid egg production where EU Common Agricultural Policy subsidies are accelerating layer farm conversions in France and Germany. Target sports nutrition beverage manufacturers specifying clean-label egg white isolates as whey alternatives, a segment with penetrable technical barriers and premium positioning. Deploy direct-to-food-manufacturer sales models bypassing consolidated broadline distributors to capture margin and traceability relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated operators with captive layer supply and established broadline distributor relationships, as these assets compound regulatory compliance advantages. Long-term viability favors processors with fractionation technology and aseptic packaging partnerships that unlock emerging market distribution. Watch avian influenza surveillance protocols as the inflection indicator that would force capacity rationalization and pricing power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Cage-Free Capacity Expansion | California Proposition 12 mandates are reshaping procurement qualification requirements across institutional buyers. |
| Backward Integration into Layer Farms | Captive hen supply insulates processors from feed grain volatility and regional avian influenza disruption exposure. |
| Tetra Pak Aseptic Partnership | Ambient-stable formats unlock distribution in Indonesia and Vietnam where refrigerated logistics remain underdeveloped. |
| Fractionation Equipment Scale-Up | Membrane filtration capacity captures premium demand from Southern European confectionery and sports nutrition clients. |
| Inline Spectroscopy Deployment | Real-time solids verification eliminates batch-to-batch viscosity variation for German industrial bakery customers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with food manufacturing procurement directors, layer farm operations managers, broadline distributor category heads, and regulatory compliance officers providing operational data. Secondary validation drew from FDA Egg Safety Rule enforcement records, USDA Agricultural Marketing Service grade standards, EU Regulation 853/2004 hygiene updates, and SEC filings of publicly traded layer processors. Bottom-up volume estimates from processor capacity utilization were triangulated against top-down demand models from end-use consumption patterns.
Calibration approaches anchored volume and value outputs to historical production data and disclosed capacity expansion announcements across the analysis window. Segmentation dimensions modeled include product type, end-user channel, packaging format, and distribution reach, with additional granularity on cage-free versus conventional certification tiers. CAGRs were derived from regression analysis of historical volume trajectories applied to projected demand shifts, incorporating feed cost indices and regulatory compliance cost burdens as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in feed grain futures, energy costs for refrigeration, and exchange rate movements affecting export competitiveness would shift the trajectory. Material shifts in FDA enforcement priorities, EU hygiene standard updates, or state-level welfare mandate expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Durian Powder Market
Ingredients
Low Calorie Oil Market
Ingredients
Soy Peptones Market
Ingredients
Blackcurrant Concentrate Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Encapsulated Ingredients Market
Ingredients
Gelatin Substitutes Market
Ingredients
Halal Ingredients Market
Ingredients
Oat Grass Powder Market
Ingredients
North America Prebiotic Ingredients Market
Ingredients
South America Phytosterols Market
Ingredients
Asia-Pacific Fats and Oil Market
Ingredients
Rice Bran Fatty Alcohols Market
Ingredients
Global Amaranth Oil Market
Ingredients
Agave Inulin Market
Ingredients
Europe Insoluble Dietary Fibers Market