
 Margarine Market | 2026-2036
Margarine Market Size, Share, and Industry Trends Forecast 2026-2036
Margarine Market Intelligence
Private label development programs offered by manufacturers to large retailers are restructuring the competitive landscape. Upfield BV leverages its extensive brand portfolio to command significant shelf space in supermarkets globally. In contrast, Bunge Ltd. specializes in the upstream supply of oils and fats, providing critical inputs for both branded and private label producers. Wilmar International Ltd. controls a substantial portion of the palm oil supply chain, influencing raw material costs for the entire sector.
Margarine is a water-in-oil emulsion, produced primarily from vegetable oils like palm, soybean, or canola oil. It serves as a butter substitute in baking, cooking, and as a spread, with fat content often legally mandated to be above 80% for block products. Block margarine continues to dominate the food service industry and bakery segments due to its functional properties in lamination and doughs. Spreadable and whipped forms in tubs cater primarily to household end-users, with sales concentrated in supermarkets and hypermarkets.
Product formulation is heavily influenced by food safety regulations, including the US FDA's rules on partially hydrogenated oils and the European Food Safety Authority's (EFSA) guidance on contaminants. International standards from the Codex Alimentarius Commission provide a baseline for composition and labeling, impacting trade between countries. Producers must navigate the strategic trade-off between utilizing cost-effective palm oil and meeting rising consumer and investor demand for sustainably sourced ingredients.
Market Dynamics
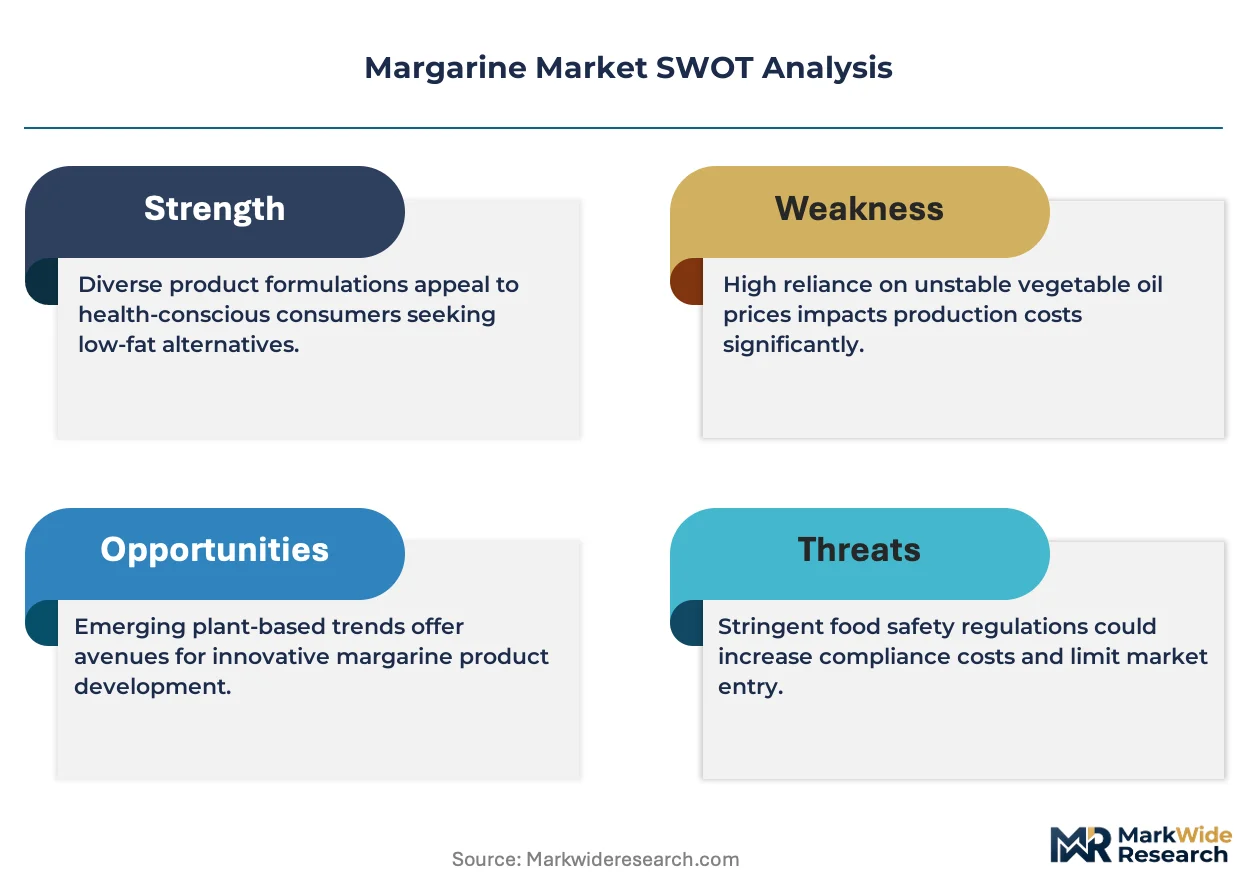
The central structural force shaping the margarine market is the persistent tension between the need for cost-effective, functional fats for industrial baking and the simultaneous regulatory and consumer pressure for non-hydrogenated, sustainably sourced formulations for household use.
Growth Catalysts
- Food Service Expansion:Demand from commercial bakeries and food service operators in countries like Germany and the United States is rising as they seek reliable, lower-cost alternatives to butter for lamination and dough preparation.
- Regulatory Mandates:Stricter food safety rules from the FDA and EFSA regarding trans fats have spurred innovation in non-hydrogenated formulations, creating a new product baseline that builds consumer and commercial trust.
- Private Label Programs:The expansion of private label development programs by large supermarket chains creates consistent, high-volume demand for manufacturers capable of producing specific formulations for retail channels.
Market Restraints
- Input Cost Volatility:Heavy reliance on palm oil as a primary feedstock exposes the entire sector to price shocks and supply disruptions originating from major producing regions in Southeast Asia.
- Negative Consumer Perception:Despite reformulations, a persistent negative health perception linking margarine to artificial ingredients and historical trans fat content continues to challenge brand positioning in household segments.
- Substitution from Butter:In periods of low dairy commodity prices, butter can become a more cost-competitive and preferred ingredient for both consumers and food service buyers, creating direct substitution pressure.
Strategic Opportunities
- Clean Label Formulations:A significant opportunity exists for products formulated with a minimal number of recognizable ingredients, appealing to health-conscious consumers and commanding a premium in retail.
- Sustainable Sourcing Certification:Securing and promoting certifications like those from the Roundtable on Sustainable Palm Oil (RSPO) can provide a distinct advantage in supplying large corporations and retailers with ESG mandates.
- Fortified Product Lines:Developing margarines enriched with vitamins, omega-3 fatty acids, or plant sterols allows producers to target specific health and wellness segments within the consumer market.
Industry Challenges
- Sensory Profile Replication:A primary technical challenge for R&D teams is achieving the precise flavor, mouthfeel, and melting characteristics of butter, particularly in demanding baking applications like croissants and puff pastry.
- Supply Chain Traceability:Implementing and maintaining the robust tracking systems required to verify and document the origin of palm oil for sustainability certification presents a significant operational and cost burden for producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Margarine Market |
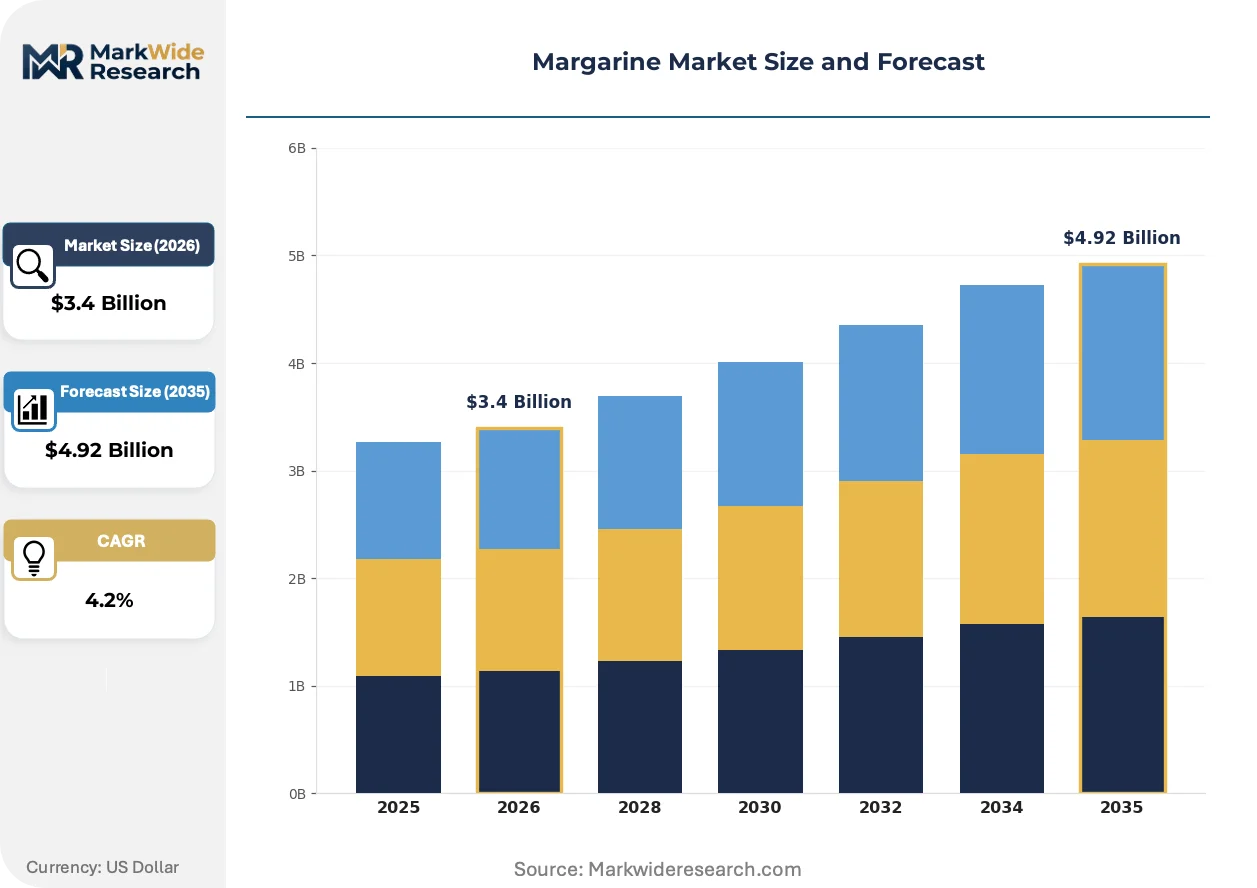
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $4.92 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Margarine, Non-Hydrogenated Margarine, Whipped Margarine, Flavored Margarine Form: Spread, Block, Liquid, Cream Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores End User: Households, Food Service Industry, Bakery, Restaurants |
| Companies Covered | Bunge Ltd., Upfield BV, Wilmar International Ltd., Vandemoortele NV, BRF SA, Conagra Brands Inc., Fuji Oil Holdings Inc., Puratos Group NV, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Margarine Market Strategic Shifts & Innovations
Product development is bifurcating, with one track focused on achieving butter-like functional performance for industrial clients and another centered on clean-label, plant-based attributes for retail consumers. This divergence influences everything from raw material sourcing to R&D investment.
Interesterification is a key technology used to modify the structure of vegetable oils without creating trans fats. Industrial food manufacturers are the primary adopters, using it to create block margarines with specific melting points and crystallization behaviors. The market for solid fats is absorbing this technique to engineer functional, non-hydrogenated butter substitutes essential for bakery and confectionery applications.
European Food Safety Authority (EFSA) opinions on process contaminants like 3-MCPD and glycidyl esters in refined oils have triggered significant process reviews. This regulatory scrutiny compels producers to refine their heating and purification processes to minimize the formation of these substances. Block margarine producers are most affected, as they must balance contaminant reduction with maintaining the functional properties critical for their food service customers.
A clear shift in household purchasing behavior favors spreads marketed with explicit health and ethical claims. This trend disrupts the retail placement of conventional block margarine, as shelf space increasingly prioritizes tub-based products highlighting plant-based origins, omega-3 fortification, or sustainable palm oil certification. This pattern is most pronounced in supermarkets across North America and Western Europe, where wellness-oriented branding directly influences consumer choice.
Margarine Market Segmentation
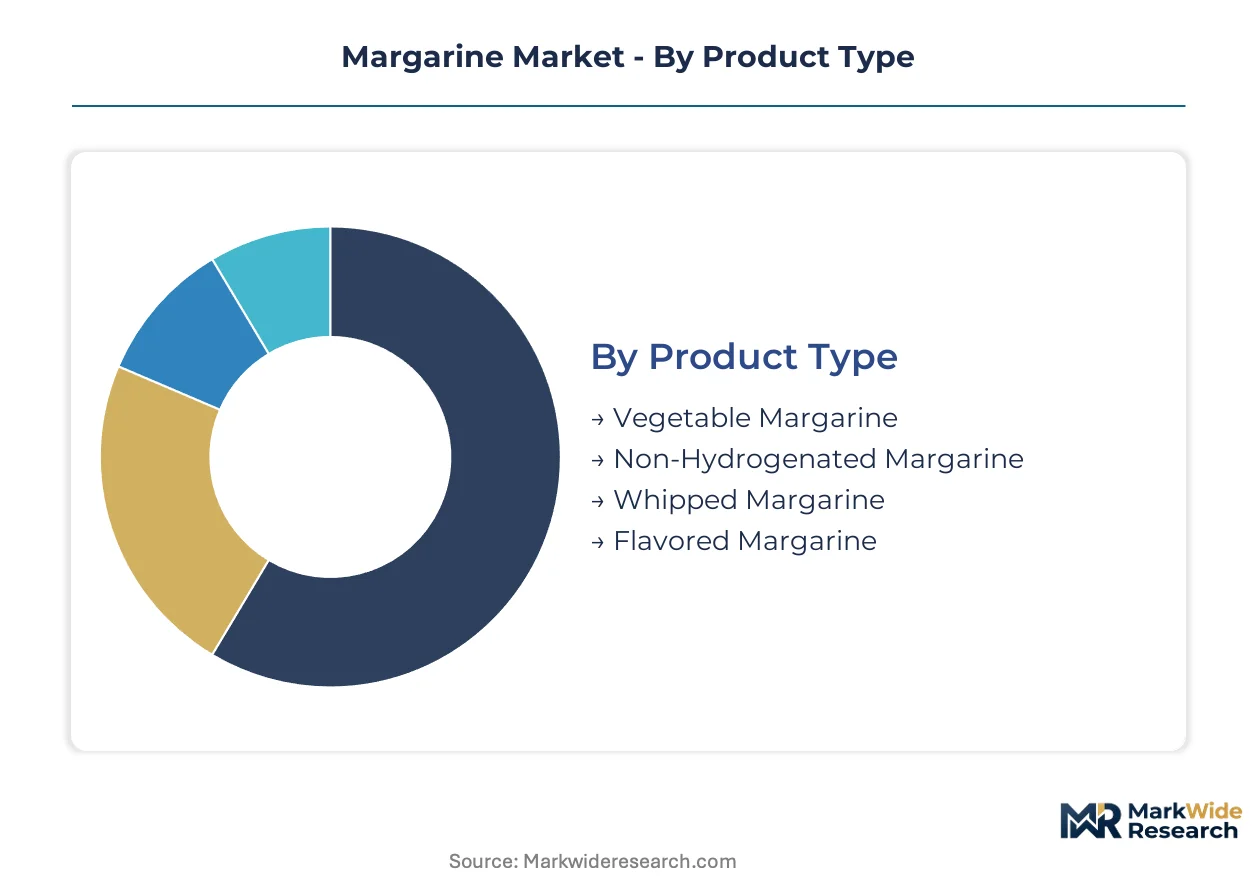
The margarine market's segmentation reveals diverse product formulations and end-user applications. Understanding these distinct segments allows producers to tailor offerings for specific functional requirements and consumer preferences. This detailed analysis highlights the varied demand patterns across industrial and retail channels.
Product Type:
Product types within the margarine market delineate formulations for both standalone consumption and integrated use within more complex food systems.
- Non-Hydrogenated Margarine:This formulation avoids partially hydrogenated oils, adhering to stricter food safety standards from regulators like the FDA and EFSA. Demand concentrates in both household retail and commercial bakeries seeking healthier alternatives for doughs and spreads.
- Vegetable Margarine:Composed primarily of vegetable oils such as palm, soybean, or canola, this foundational product serves as a cost-effective butter substitute. Its functional properties are critical for lamination and general cooking applications in the food service industry.
- Whipped Margarine:Incorporates air to create a lighter texture and increased volume, primarily targeting household consumers for easy spreading applications.
- Flavored Margarine:Infused with various natural or artificial flavors, this segment caters to specific culinary preferences, enhancing taste profiles in cooking or as a spread.
Volume placements concentrate in Vegetable Margarine; the faster expansion belongs to Non-Hydrogenated Margarine.
Form:
The market's forms offer distinct cost structures and functional attributes, influencing their suitability for different end-user applications.
- Block:This solid form often contains over 80% fat, making it ideal for industrial baking processes requiring specific plasticity and melting points. Commercial bakeries in Germany and the United States rely on block margarine for consistent lamination and dough structure.
- Spread:Packaged in tubs, this softer, often lower-fat alternative caters primarily to household consumers for direct consumption on bread or toast. Supermarkets and hypermarkets are the primary distribution channels for spreadable margarine products.
- Liquid:Designed for easy pouring and mixing, liquid margarine finds use in cooking and baking applications where precise measurement and rapid incorporation are desired.
- Cream:Characterized by its smooth, emulsified texture, cream margarine is often used in confectionery and dessert preparations, providing richness and stability.
Functional requirements for industrial users drive the substantial consumption of Block forms, while Spread products are gaining share most quickly in retail channels.
Distribution Channel:
Distribution channels reflect the varied purchasing habits of both individual consumers and large-volume commercial buyers within the market.
- Supermarkets:These large retail outlets serve as the primary point of sale for household consumers, offering a wide array of branded and private label margarine products. Upfield BV leverages extensive shelf space in these stores globally.
- Online Retail:E-commerce platforms facilitate direct-to-consumer sales and bulk purchases for smaller businesses, providing convenience and access to specialized formulations. This channel is experiencing significant expansion in North America and Western Europe.
- Specialty Stores:These niche retailers cater to specific dietary needs or gourmet preferences, often stocking premium or organic margarine varieties.
- Convenience Stores:Providing quick access for immediate consumption needs, convenience stores offer smaller pack sizes of margarine, primarily for individual household use.
High-volume transactions dominate through Supermarkets, with Online Retail demonstrating the steepest expansion trajectory for consumer access.
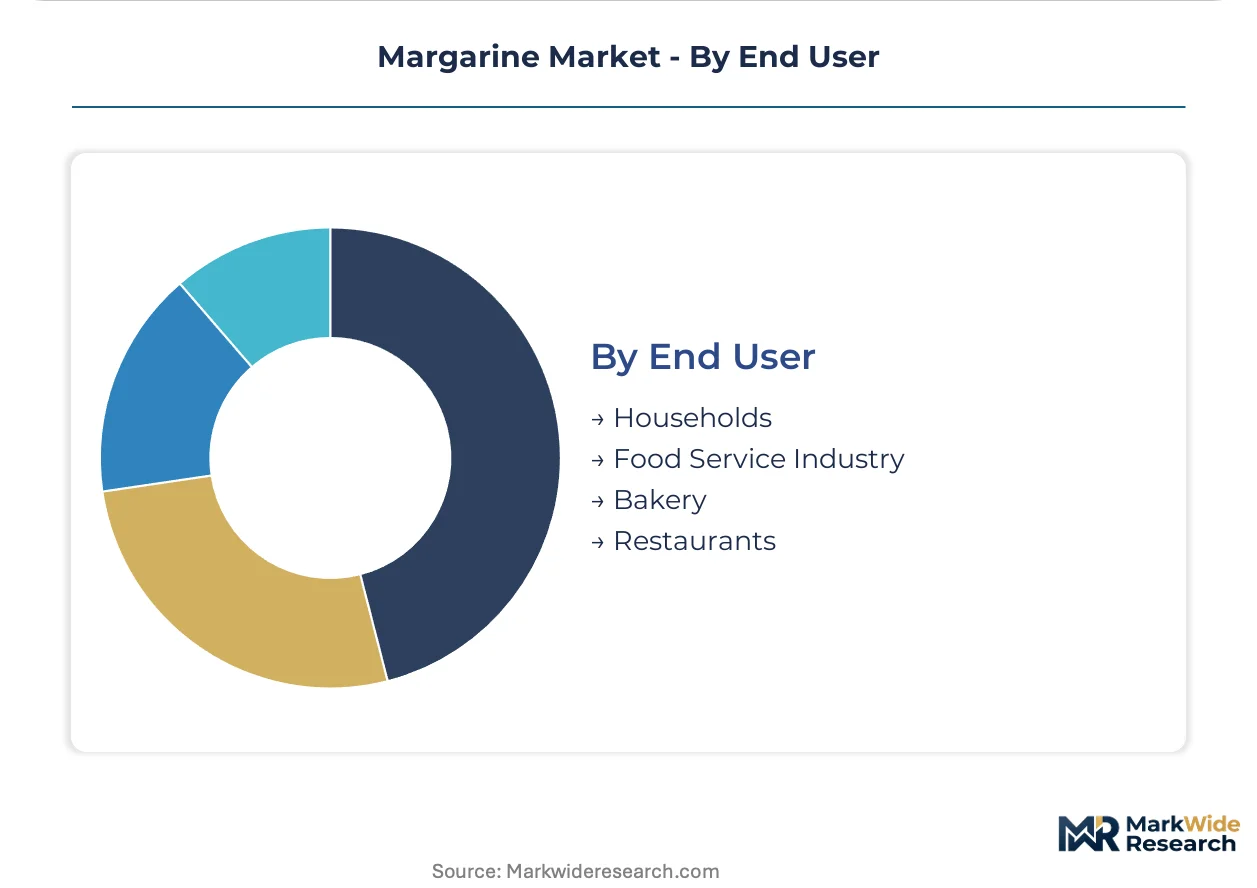
End User:
End-user segments highlight the distinct volume requirements and application demands across industrial, commercial, and individual consumption contexts.
- Food Service Industry:This segment encompasses large-scale operations requiring bulk quantities of margarine for diverse culinary applications, including hotels, catering services, and institutional kitchens. Cost-effectiveness and functional consistency are paramount for these buyers.
- Households:Individual consumers purchase margarine for daily cooking, baking, and spreading, with preferences heavily influenced by health claims, brand recognition, and convenience. Sales are concentrated in supermarkets across North America and Western Europe.
- Bakery:Commercial bakeries represent a specialized sub-segment of the food service industry, demanding specific margarine formulations for lamination, doughs, and confectionery.
- Restaurants:As part of the broader food service sector, restaurants utilize margarine for cooking, frying, and as a butter alternative, prioritizing taste, texture, and cost.
The Food Service Industry commands significant industrial volumes, while Households represent a consistent and expanding consumer base for retail products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global margarine market exhibits a distinct geographical divide, with primary raw material production often concentrated in specific regions, while consumption of finished products is distributed across major industrial and retail markets. Industrial demand for functional fats in baking frequently drives volume in developed economies. Consumer preferences for healthier, plant-based spreads increasingly shape retail segments globally.
Germany
Commercial bakeries in Germany drive significant demand for block margarine, seeking cost-effective butter alternatives for lamination and dough preparation. The European Food Safety Authority (EFSA) opinions on process contaminants influence local producers to refine oil purification methods. Food ingredient manufacturers located in North Rhine-Westphalia are actively developing non-hydrogenated formulations to meet evolving regulatory standards.
United States
Food service expansion, particularly in commercial bakeries, fuels margarine consumption across the United States. Stricter FDA regulations regarding partially hydrogenated oils have spurred innovation in non-hydrogenated formulations. Major food processing hubs in the Midwest are adapting production lines to incorporate interesterified oils for functional block products.
Indonesia
Indonesia remains a foundational supplier of palm oil, a critical feedstock for global margarine production. Government policies, including those from the Ministry of Agriculture, influence palm oil cultivation practices and export volumes. Processing facilities around Medan and Kalimantan are key nodes in the upstream supply chain, impacting raw material costs worldwide.
Netherlands
The Netherlands serves as a significant processing and distribution hub for margarine ingredients and finished products within Europe. EFSA's comprehensive guidance on food safety and contaminants directly impacts product development for Dutch manufacturers. Port cities like Rotterdam facilitate the import of raw oils and export of refined margarine products across the continent.
Japan
Japanese consumers increasingly seek spreads with explicit health and ethical claims, driving demand for fortified and sustainably sourced margarine. The Ministry of Health, Labour and Welfare (MHLW) sets food additive and safety standards influencing product formulations. Food technology companies in the Kanto region are investing in R&D to replicate butter's sensory profile using plant-based ingredients.
Margarine Market Key Industry Players
Top-tier vendors anchor the global margarine market through extensive brand portfolios and wide distribution networks, while specialized ingredient suppliers and private label manufacturers carve out distinct niches. The market structure exhibits a tiered consolidation, with large food corporations competing against focused producers. Strategic partnerships for raw material sourcing and continuous investment in non-hydrogenated formulation R&D represent dominant competitive moves.
Among diversified food ingredient providers, Upfield BV exemplifies a company leveraging an extensive brand portfolio to command significant supermarket shelf space globally. Bunge Ltd., a US-based agribusiness and food ingredient company, occupies a critical position in the upstream supply of oils and fats, providing essential inputs for both branded and private label producers. Wilmar International Ltd., an Asia-based agricultural business, anchors a substantial portion of the palm oil supply chain, influencing raw material costs for the entire sector.
| Leading Market Players |
|---|
| Bunge Ltd. |
| Upfield BV |
| Wilmar International Ltd. |
| Vandemoortele NV |
| BRF SA |
| Conagra Brands Inc. |
| Fuji Oil Holdings Inc. |
| Puratos Group NV |
| Unilever |
Cost & Logistics Intelligence
Family-owned mid-caps and large agribusiness conglomerates dictate supply behavior in the margarine market, influencing raw material procurement and finished product pricing discipline. These diverse ownership structures impact strategic investments in sustainable sourcing and processing technologies.
Pricing Analysis
Cost-down pressure on commercial bakeries accelerates because of intense competition and demand for cost-effective butter alternatives. The dominant pricing structure combines commodity spot pricing for raw oils with contract-based long-term offtake agreements for industrial customers. Price differentiation stems from volume scale for large food service buyers and specific certifications like RSPO for sustainable palm oil. Households in retail channels exhibit higher price sensitivity compared to industrial bakery clients, who prioritize functional performance.
Supply Chain Analysis
Distribution runs through extensive supermarket networks for household products and specialized food service distributors for industrial clients. Geographic supply concentration for critical raw materials centers on Indonesia and Malaysia, which provide significant palm oil volumes. The market relies heavily on vegetable oils like palm, soybean, and canola oil for its primary feedstock. Commodity price volatility for these agricultural inputs represents a significant structural risk for the entire supply chain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The margarine market presents a cost-of-compliance story, where stricter FDA regulations on partially hydrogenated oils create a significant barrier-to-entry moat. This regulatory environment favors established players capable of investing in non-hydrogenated formulations.
For Market Incumbents: To counter the persistent negative consumer perception and substitution from butter, incumbents must invest heavily in clean label formulation R&D. Deepen vertical integration into sustainable palm oil sourcing, leveraging RSPO certification as a competitive lever. Consolidate market share through private label development programs with large retailers. Optimize production lines in food processing hubs like the Midwest for interesterified oils.
For New Entrants and Emerging Players: Begin with targeting niche health and wellness segments in North America and Western Europe, focusing on fortified product lines. The most penetrable segment lies within online retail channels, offering specialized, plant-based spreads. Develop unique sensory profiles that closely mimic butter, appealing to discerning household consumers. Promote sustainable sourcing certifications like RSPO through transparent branding.
For Investors and Strategic Acquirers: Increased adoption of interesterification technology by mid-sized producers is the leading indicator that the market is shifting towards advanced non-hydrogenated solutions. The long-term viability of the margarine sector over the next 5-10 years depends on innovation in functional, plant-based formulations. Target acquisition profiles include specialized ingredient manufacturers with proprietary clean label technologies or strong sustainable sourcing credentials. Monitor regulatory updates from EFSA regarding process contaminants.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean Label Formulation R&D | Developing new non-hydrogenated formulations addresses consumer demand for healthier, transparent ingredients. |
| RSPO Certification Investment | Securing sustainable palm oil certification meets ESG mandates from large corporations and retailers. |
| Private Label Program Expansion | Offering tailored products for large supermarket chains ensures consistent, high-volume demand. |
| Interesterification Technology Adoption | Implementing this process allows manufacturers to create functional, trans-fat-free block margarines. |
| Fortified Product Line Development | Enriching margarine with omega-3 fatty acids targets specific health and wellness segments in retail. |
Research Approach
Document review covered FDA filings, EFSA guidance, and Codex Alimentarius Commission standards, complemented by interviews with R&D directors, procurement leads, and commercial bakery operators. Primary insights from food technologists and retail buyers were triangulated with secondary data. This approach combined bottom-up market sizing with top-down validation, ensuring comprehensive data integrity.
The analytical model produced comprehensive volume and value projections across the analysis window, segmented by product type, form, distribution channel, and end-user. Compound Annual Growth Rates (CAGRs) were derived from historical data trends and projected demand drivers. Key inputs included raw material price forecasts and regulatory compliance investment trends.
Palm oil supply disruptions, evolving food safety regulations, and shifts in consumer health perceptions are the dominant revision risks for market forecasts. These projections inherently reflect current market assumptions. Practitioners should monitor global agricultural commodity markets and regulatory bodies like EFSA for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
India Ready to Mix Food Market
Processed Foods
Processed Peanut Market
Processed Foods
Fat Free Food Market
Processed Foods
Apple Butter Market
Processed Foods
Spray Cheese Market
Processed Foods
Global Potato Flake Market
Processed Foods
Broth Market
Processed Foods
United States Ice Cream Market
Processed Foods
Low Fat Puddings Market
Processed Foods
Processed Meat Market
Processed Foods
Ready-To-Whip Toppings Market
Processed Foods
Spreadable Fats Market
Processed Foods
Fat Free Soup Market
Processed Foods
Low Fat Chicken Soup Market
Processed Foods
Asia-Pacific Soup Market
Processed Foods
North America Ice Cream Market