
 United States Food Spread Market | 2026-2036
United States Food Spread Market Size, Share, and Industry Trends Forecast 2026-2036
United States Food Spread Market Analytics
Multi-source ingredient procurement is broadening among major spread manufacturers seeking supply resilience. The J.M. Smucker Company anchors its position through dominant peanut butter brands and extensive retail partnerships. Conagra Brands Inc. leverages diversified manufacturing infrastructure to compete across multiple spread categories. Mondelez International differentiates through premium chocolate-hazelnut positioning and global recipe standards adapted for US palates.
United States food spreads comprise semi-solid or viscous edible preparations formulated from nuts, fruits, dairy, cocoa, or oil-based emulsions, typically containing 20-60% fat content and processed through grinding, homogenization, or thermal treatment to achieve spreadable rheology. These products serve as condiments, meal components, or baking inputs across retail and foodservice channels. Peanut butter maintains the largest volume share within product type segmentation, reflecting entrenched breakfast and snacking rituals. Online retail represents the fastest-growing distribution channel, driven by subscription models and direct-to-consumer specialty brands. Spreadable and creamy forms command premium shelf space in supermarkets, while chunky variants sustain niche loyalty among texture-seeking households.
FDA food-labeling requirements, USDA organic certification standards, and state-level California Proposition 65 enforcement collectively govern ingredient disclosure, allergen management, and permissible additive profiles across the category. These frameworks elevate compliance costs for smaller entrants while rewarding established players with in-house regulatory affairs capacity. Stakeholders must monitor evolving FDA guidance on added-sugar disclosure and emerging state legislation targeting palm oil sourcing transparency.
Market Dynamics
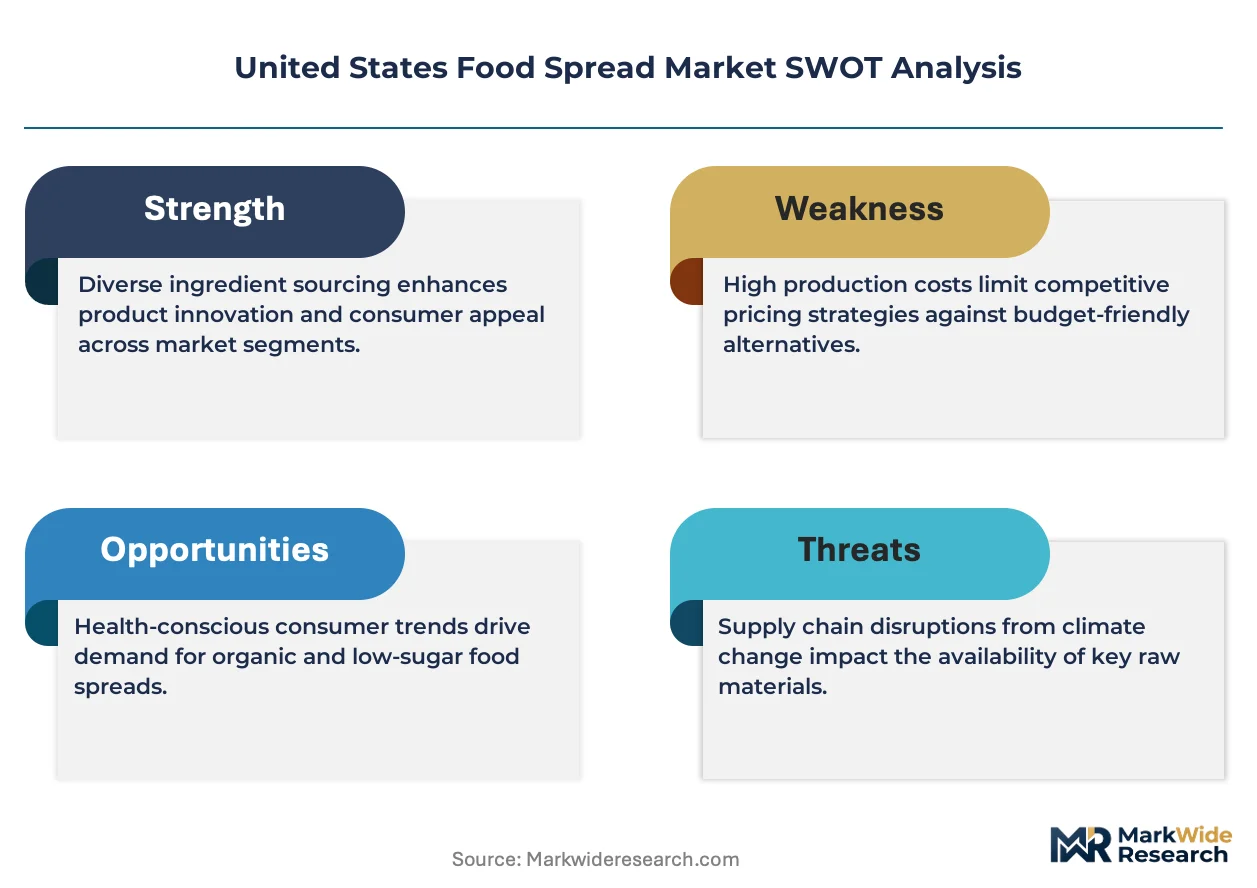
Clean-label mandates from California Proposition 65 and FDA added-sugar disclosure rules are forcing reformulation across the category, compressing margins for manufacturers dependent on conventional emulsifiers and refined sweeteners while rewarding firms with captive R&D infrastructure.
Growth Catalysts
- California Proposition 65 enforcement:State-level litigation exposure around acrylamide and heavy metals is accelerating removal of synthetic additives, opening shelf space for verified clean-label alternatives in West Coast retail chains.
- Foodservice menu expansion:Restaurant operators are embedding artisan spreads into limited-time offerings and breakfast-all-day formats, creating pull-through demand for bulk and portion-control packaging formats.
- Metropolitan corridor concentration:Private-label penetration in Dallas-Fort Worth and Los Angeles metro areas is deepest, generating price competition that expands category trial among value-seeking households.
Market Restraints
- Peanut input cost volatility:Domestic peanut harvest variability and futures market speculation create margin compression for manufacturers without forward-contracting capabilities or diversified nut sourcing.
- Palm oil supply concentration:Southeast Asian sourcing exposure generates ESG compliance risk as state-level transparency mandates in Vermont and New York require deforestation-free certification documentation.
- Allergen cross-contamination liability:FDA Food Safety Modernization Act traceability requirements impose capital-intensive facility segregation protocols that disadvantage smaller co-manufacturers.
Strategic Opportunities
- Texas Hill Country and Florida Panhandle underpenetration:These sub-regions show below-average specialty spread penetration relative to household income, suggesting whitespace for premium positioning ahead of population growth.
- Direct-to-consumer subscription models:Specialty brands are bypassing slotting-fee barriers in conventional retail by building recurring revenue through curated flavor rotations and personalized nutrition profiling.
- USDA organic certification tailwind:Federal procurement preference for organic products in school nutrition programs creates institutional demand channel distinct from retail and foodservice.
Industry Challenges
- Clean-label R&D talent scarcity:Formulation chemists with expertise in natural emulsification and shelf-life extension without synthetic preservatives command premium compensation, constraining mid-tier manufacturer innovation pipelines.
- Dual-track facility certification:Simultaneous organic and conventional production lines require segregated equipment and sanitation protocols, extending capital deployment timelines and complicating capacity planning.
- Legacy ERP integration with traceability systems:FDA Section 204 food traceability mandates require real-time lot tracking that conflicts with decades-old inventory management infrastructure at established plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Food Spread Market |
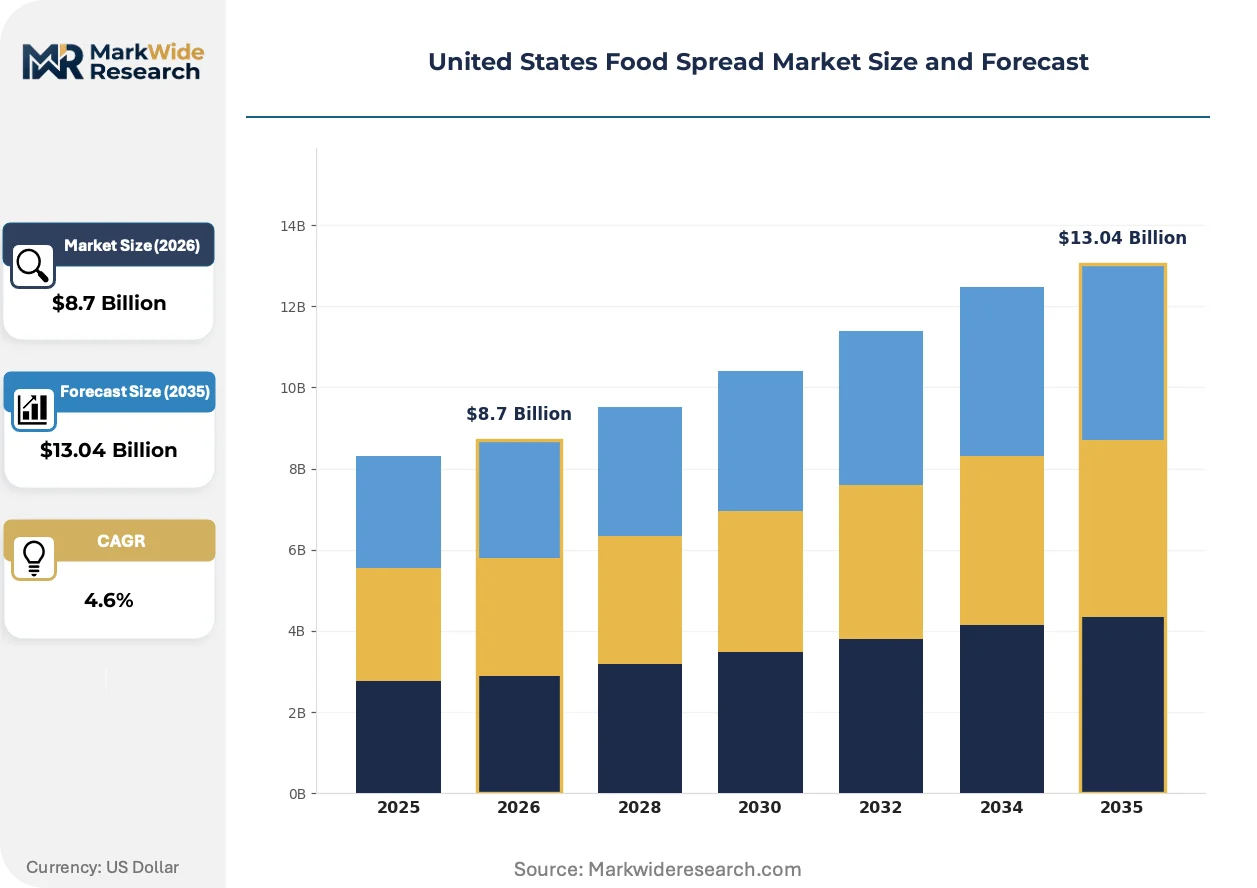
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peanut Butter, Jelly, Marmalade, Nutella Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops End User: Households, Restaurants, Cafes, Catering Services Form: Spreadable, Liquid, Creamy, Chunky |
| Companies Covered | Conagra Brands Inc., The Hershey Company, The J.M. Smucker Company, Mondelez International, Kraft Heinz Company, Unilever PLC, Hormel Foods Corporation, Land O' Lakes, Inc., Ferrero International S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Food Spread Market Evolving Landscape
Spread manufacturing is experiencing technology-driven segmentation as equipment modularity meets regulatory pressure and channel fragmentation, compressing batch economics while enabling micro-SKU proliferation.
High-pressure processing equipment is modularizing production footprints for refrigerated spreads, allowing regional dairies and nut processors to enter pasteurized categories without centralized thermal infrastructure. Mid-size co-manufacturers in Wisconsin and Oregon are adopting these systems to serve emerging brands with 500-case minimums rather than 10,000-case thresholds. The technology is modularizing what was previously captive capacity at major integrated processors, fragmenting supply concentration.
FDA guidance on "healthy" nutrient content claims is tightening fat and added-sugar thresholds, disqualifying legacy formulations that previously qualified for front-of-package labeling. Manufacturers are responding with blended nut-vegetable oil emulsions and fruit-puree sweetening systems that maintain spreadable rheology within revised parameters. Chocolate-hazelnut and sweetened fruit spread segments face the steepest compliance timelines given existing consumer taste expectations.
Retail buyer consolidation around club and e-commerce channels is compressing SKU survival thresholds, with surviving products requiring velocity justification within 90-day trial windows. Direct-to-consumer brands are capturing lifetime value through subscription commitments that offset higher customer acquisition costs, while conventional supermarkets are rationalizing shelf sets toward velocity-proven national labels. This channel bifurcation is most visible in California and Texas, where Amazon Fresh and Costco penetration rates exceed national averages by substantial margins.
United States Food Spread Market Segmentation
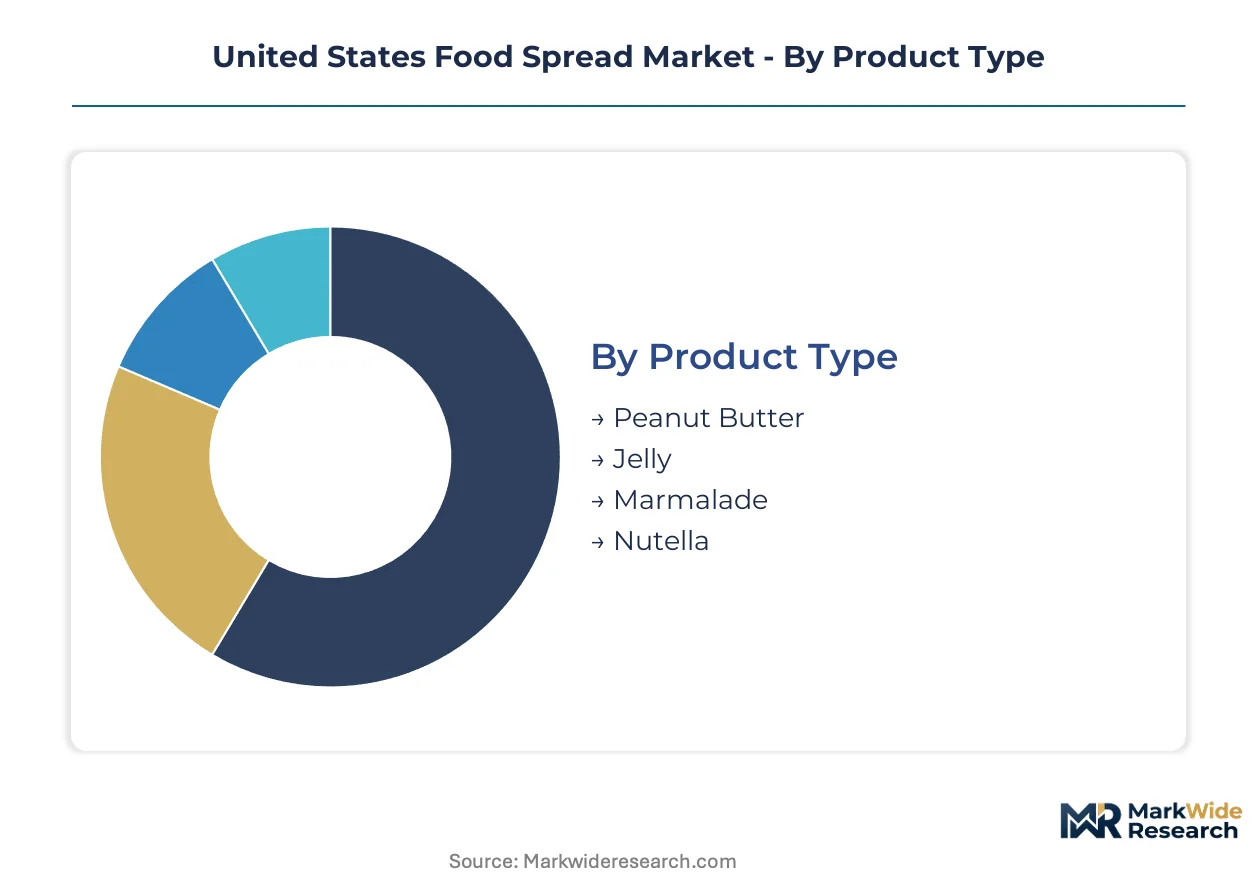
Spread manufacturers navigate divergent margin profiles across product formats and channel tiers. Segmentation reveals where formulation investment concentrates versus where volume scale accumulates.
Product Type:
Composition standards and fat-content specifications differentiate spread categories for distinct meal occasions and dietary applications.
- Peanut Butter:Ground roasted peanuts with 90%+ peanut content under FDA standard of identity, yielding stable emulsions through hydrogenated oil stabilization. Demand concentrates in Texas and California metropolitan corridors where private-label penetration drives price-based trial among value-seeking households. Breakfast and snacking rituals sustain volume leadership despite input cost volatility from domestic harvest variability.
- Nutella:Chocolate-hazelnut emulsion with 13% hazelnut content and palm oil base, positioned as premium indulgence with European recipe heritage adapted for US palates. California Proposition 65 enforcement on acrylamide disclosure is accelerating clean-label reformulation pressure in West Coast retail chains. Premium positioning commands shelf space in club channels despite tightening FDA "healthy" claim thresholds on added-sugar content.
- Jelly:Fruit-sugar pectin gels at 65-68 Brix, offering lower fat content for health-positioned households.
- Marmalade:Citrus-based preserves with suspended peel fragments, sustaining niche loyalty among texture-seeking consumers in Northeast urban markets.
Peanut butter leads on scale; Nutella leads on momentum.
Distribution Channel:
Channel economics determine packaging formats, velocity requirements, and slotting-fee exposure for spread manufacturers.
- Online Retail:Subscription models and direct-to-consumer specialty brands bypass conventional retail barriers through curated flavor rotations and personalized nutrition profiling. Amazon Fresh penetration in California and Texas exceeds national averages, compressing delivery economics for temperature-stable spreads. Recurring revenue structures offset higher customer acquisition costs through lifetime value capture.
- Supermarkets:Velocity-proven national labels dominate shelf sets with 90-day trial windows and slotting-fee structures that disadvantage emerging entrants. Spreadable and creamy forms command premium positioning while chunky variants sustain dedicated facings. Buyer consolidation around conventional grocers is rationalizing SKU counts toward proven performers.
- Convenience Stores:Single-serve and portion-control formats address immediate consumption occasions with limited refrigeration.
- Specialty Shops:Artisan and small-batch spreads access premium pricing through provenance storytelling and local sourcing claims.
Supermarkets dominate absolute volume; online retail is expanding most quickly.
End User:
Application requirements separate institutional bulk procurement from household portion preferences.
- Households:Jarred retail formats with 16-18 ounce standard sizing for pantry stocking and multi-use occasions.
- Restaurants:Foodservice menu expansion embeds artisan spreads into limited-time offerings and breakfast-all-day formats, creating pull-through demand for bulk and portion-control packaging. Dallas-Fort Worth metro area concentration generates price competition that expands category trial.
- Cafes:Single-serve sachets and pump dispensers for beverage accompaniment and pastry applications.
- Catering Services:Institutional-scale tubs with extended shelf-life requirements for event-based consumption.
Households anchor volume scale; restaurants drive formulation innovation.
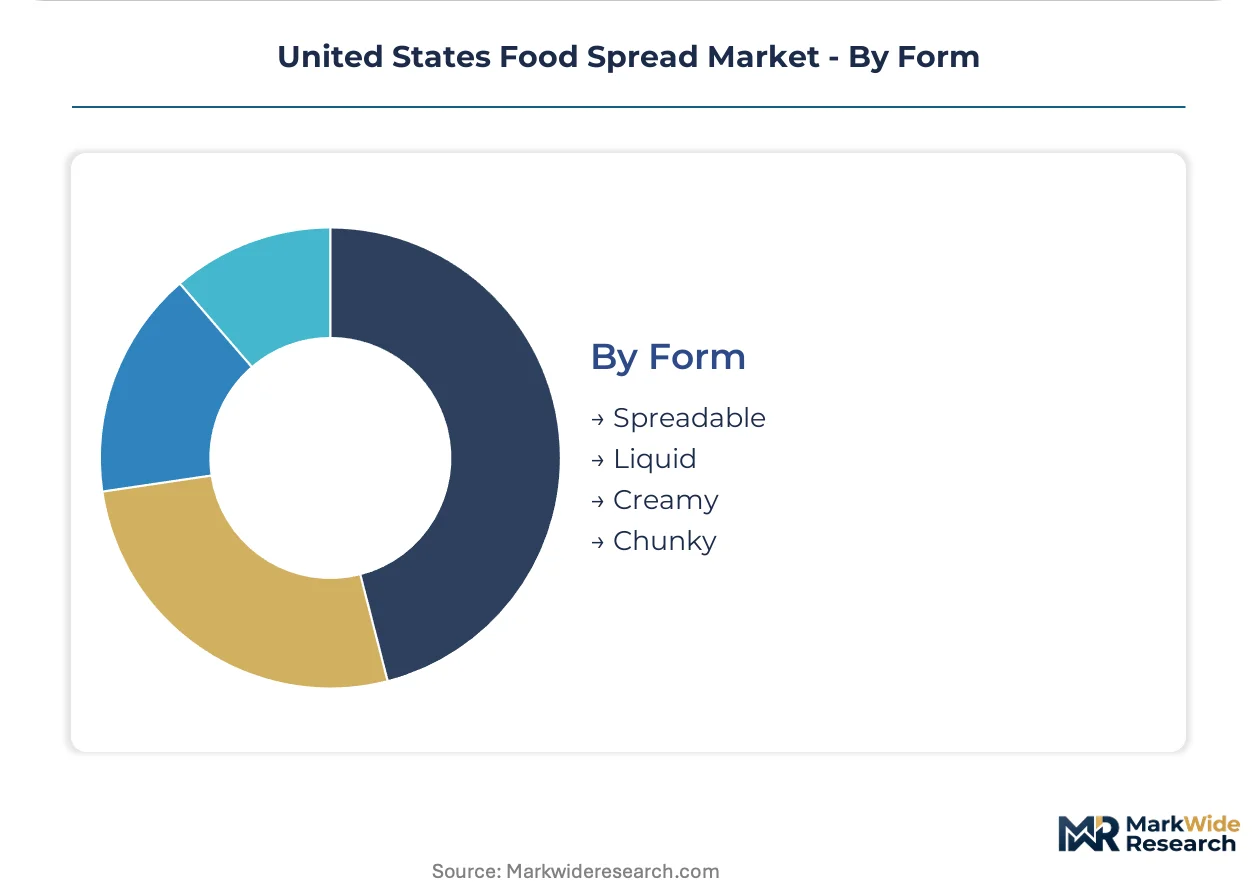
Form:
Rheological properties determine processing equipment requirements and sensory positioning.
- Spreadable:Optimized viscosity for knife-spread application at refrigeration temperatures, commanding premium shelf space.
- Creamy:Homogenized particle size below 20 microns for smooth mouthfeel, sustaining dominant share in peanut butter segmentation. Texas Hill Country and Florida Panhandle underpenetration relative to household income suggests whitespace for premium creamy positioning ahead of population growth.
- Chunky:Suspended nut or fruit particulates above 2mm, maintaining texture-seeking household loyalty in niche segments.
- Liquid:Reduced viscosity for drizzle and sauce applications, emerging in specialty chocolate-hazelnut segments.
Creamy forms dominate production scale; spreadable variants gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metropolitan corridor anchors spread consumption volume through dense foodservice penetration and aggressive private-label retail competition. Texas and California metropolitan areas collectively concentrate demand acceleration, with state-level regulatory divergence creating distinct formulation requirements across sub-regional markets.
California
Los Angeles and San Francisco metropolitan areas drive clean-label premiumization through Proposition 65 enforcement on acrylamide and heavy metals disclosure. FDA added-sugar labeling requirements intersect with state transparency mandates to accelerate synthetic additive removal. West Coast retail chains are expanding shelf space for verified clean-label alternatives ahead of national compliance timelines.
Texas
Dallas-Fort Worth and Houston metro areas concentrate private-label penetration deepest among US markets, generating price competition that expands category trial. Restaurant operators in these corridors embed artisan spreads into breakfast-all-day formats and limited-time offerings. The Texas Hill Country sub-region shows below-average specialty spread penetration relative to household income, indicating whitespace for premium positioning.
New York
The New York metropolitan area sustains niche loyalty for texture-forward formats including marmalade and chunky nut spreads through diverse immigrant consumption patterns. State-level palm oil transparency mandates require deforestation-free certification documentation for retail distribution. Foodservice procurement in the metro area favors portion-control and bulk packaging for cafe and catering applications.
Florida
The Florida Panhandle exhibits underpenetration in specialty and premium spread categories relative to household income benchmarks, suggesting expansion opportunity ahead of population growth. Convenience store channels dominate single-serve format distribution for immediate consumption occasions. USDA organic certification tailwinds are penetrating institutional procurement for school nutrition programs in the Southeast corridor.
Illinois
Chicago anchors Midwest distribution infrastructure with co-manufacturing concentration serving national retail and foodservice accounts. The metropolitan area processes peanut and tree nut inputs through diversified sourcing networks that mitigate harvest volatility exposure. Legacy ERP integration challenges with FDA Section 204 traceability mandates are most acute among established processing plants in this industrial cluster.
United States Food Spread Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and retail channel access, producing a tiered structure where scale advantages intersect with specialty agility. The vendor base concentrates around integrated processors with captive R&D infrastructure and co-manufacturers serving emerging brands through flexible production minimums. Three archetypes dominate: diversified CPG conglomerates with multi-category spread portfolios, nut-focused specialists with backward integration into sourcing, and premium chocolate-hazelnut players with European recipe heritage. Competitive moves center on clean-label reformulation acceleration and direct-to-consumer subscription channel development.
Within the diversified CPG tier, The J.M. Smucker Company and Conagra Brands Inc. occupy positions reflecting extensive retail partnership networks and multi-format manufacturing capabilities. Mondelez International exemplifies the premium international specialist archetype through chocolate-hazelnut positioning adapted for US palates. These three entities represent the competitive anchors against which mid-tier manufacturers and emerging direct-to-consumer brands define differentiation strategies.
| Leading Market Players |
|---|
| Conagra Brands Inc. |
| The Hershey Company |
| The J.M. Smucker Company |
| Mondelez International |
| Kraft Heinz Company |
| Unilever PLC |
| Hormel Foods Corporation |
| Land O' Lakes, Inc. |
| Ferrero International S.A. |
| Others |
Value Network & Pricing Analysis
Family-owned peanut processors and private-equity-rolled-up specialty brands anchor supply discipline through forward-contracting programs and captive storage infrastructure, translating input cost stability into pricing power that resists the margin compression hitting conventionally financed competitors.
Pricing Analysis
Domestic peanut futures volatility and palm oil tariff exposure drive pass-through pricing adjustments across conventional tiers. Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic from conventional from private-label offerings. Cost compression in the standard tier is intensifying because of California Proposition 65 compliance investments. Foodservice buyers exhibit highest price sensitivity due to menu-margin constraints, while direct-to-consumer subscribers show lowest sensitivity through recurring revenue lock-in.
Supply Chain Analysis
Regional distribution centers in Chicago, Dallas-Fort Worth, and Los Angeles operate hub-and-spoke patterns that consolidate temperature-stable inventory before last-mile deployment. Raw material sourcing draws from Georgia and Alabama peanut acreage, Southeast Asian palm oil plantations, and Oregon hazelnut orchards. Single-source vulnerability concentrates in Indonesian and Malaysian crude palm oil supply. Distribution runs through club-channel consolidation and Amazon Fresh cold-chain partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States food spread market reads as a late-cycle quality story where clean-label certification and deforestation-free sourcing credentials command shelf-space allocation ahead of population-driven volume expansion.
For Market Incumbents: Deploy captive R&D infrastructure to accelerate natural emulsifier reformulation ahead of FDA added-sugar disclosure enforcement. Consolidate manufacturing footprint around dual-certified organic-conventional lines to capture school nutrition program procurement. Channel control through exclusive club-retailer partnerships defends against direct-to-consumer subscription erosion.
For New Entrants and Emerging Players: Enter via Texas Hill Country and Florida Panhandle whitespace where household income exceeds current specialty spread penetration. Target USDA organic certification as the most penetrable segment given federal procurement preference tailwinds. Curated flavor rotation subscriptions bypass slotting-fee barriers in conventional retail.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier co-manufacturers with modular high-pressure processing capacity and clean-label formulation expertise. Long-term viability favors targets with backward integration into domestic nut sourcing and established retail velocity proof points. Monitor FDA Section 204 traceability mandate implementation as the inflection indicator for facility modernization capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Acceleration | California Proposition 65 enforcement is disqualifying synthetic additive formulations from West Coast retail chains. |
| Direct-to-Consumer Subscription Launch | Amazon Fresh penetration in Texas and California compresses customer acquisition economics for temperature-stable spreads. |
| USDA Organic Certification Investment | Federal school nutrition procurement preference creates institutional demand channel distinct from retail velocity competition. |
| Backward Integration into Domestic Sourcing | Georgia and Alabama peanut acreage contracts mitigate futures market speculation exposure for margin stability. |
| Dual-Track Facility Certification | Simultaneous organic and conventional production lines capture price premiums while maintaining volume scale. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers, category buyers at retailers, co-manufacturing plant managers, and supply planners with secondary validation against Nielsen retail audit data, FDA filing records, USDA crop production reports, and customs import documentation. Bottom-up segment sizing and top-down category triangulation cross-checked volume and value estimates.
Segment-weighting approaches modeled product type, distribution channel, end-user application, and form rheology across the analysis window. CAGRs derived from historical velocity trends, channel penetration trajectories, and regulatory compliance timeline impacts. Forecast inputs incorporated peanut harvest variability patterns and clean-label shelf-space expansion rates.
Inputs from retail audit databases and federal crop reports were available through the study window; gaps in real-time foodservice procurement transaction data introduce uncertainty bands around institutional demand estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Pates Market
Processed Foods
India Spray Dried Food Market
Processed Foods
Processed Vegetable Market
Processed Foods
Fast-Food Reusable Market
Processed Foods
Asia-Pacific Soup Market
Processed Foods
Global Dried Processed Food Market
Processed Foods
North America Ice Cream Market
Processed Foods
United States Ice Cream Market
Processed Foods
Porridge Market
Processed Foods
Artisanal Ice Cream Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
Potato Soup Market
Processed Foods
Ready-To-Whip Toppings Market
Processed Foods
Processed Cashew Market
Processed Foods
Soup & Broth Market
Processed Foods
Asia-Pacific Food Spread Market