
 Processed Egg Market | 2026-2036
Processed Egg Market Size, Share, and Industry Trends Forecast 2026-2036
Processed Egg Market Outlook
Avian health specialist labor is rotating toward biosecurity and automated grading operations as processors confront persistent pathogen detection demands. Cal-Maine Foods leverages its vertically integrated feed-to-table network across the southeastern United States to secure supply continuity. Rose Acre Farms anchors its competitive stance through large-scale shell-to-liquid conversion capacity at multiple Midwest facilities. Michael Foods differentiates via institutional channel control, supplying prepared egg products to national foodservice distributors.
Processed eggs denote shell eggs transformed through breaking, pasteurization, drying, or pre-cooking into shelf-stable or refrigerated formats with defined solids content and microbial safety thresholds. These products serve industrial buyers requiring consistent functional performance in emulsification, foaming, or coagulation without shell-handling labor. Liquid eggs dominate volume throughput due to their direct substitutability for shell eggs in commercial kitchens and industrial formulations. Powdered eggs command premium positioning in military rations, emergency food programs, and export markets where refrigeration infrastructure remains limited. The bakery end-user segment sustains above-average growth as artisan and industrial bakers alike adopt pre-weighed liquid blends to reduce batch variability.
The USDA enforces pasteurization standards and Salmonella reduction protocols that dictate plant design and operational compliance for domestic processors. The FDA's Food Safety Modernization Act mandates hazard analysis and preventive controls across egg-breaking and further-processing facilities. China's SAMR implements GB standards for egg product labeling and additive limits that govern import eligibility and domestic formulation. Stakeholders must monitor evolving cage-free housing mandates and their feed-cost implications when assessing long-term supply contracts and capital allocation.
Market Dynamics
The EU F-Gas Regulation is forcing processors to retrofit refrigeration infrastructure for cold-chain storage, while foodservice automation accelerates demand for pre-portioned liquid formats that eliminate shell-handling labor.
Growth Catalysts
- Quick-service restaurant breakfast expansion:Chains in China are scaling baked-goods production and morning menu items, driving procurement of liquid egg blends for operational consistency.
- EU decarbonization mandates:The F-Gas Regulation creates retrofit demand for lower-emission refrigeration systems, pulling capital into energy-efficient cold-chain infrastructure at processing facilities.
- Powdered egg functional advantages:Military rations and emergency food programs require shelf-stable formats where refrigeration infrastructure remains limited, sustaining premium positioning for dried products.
Market Restraints
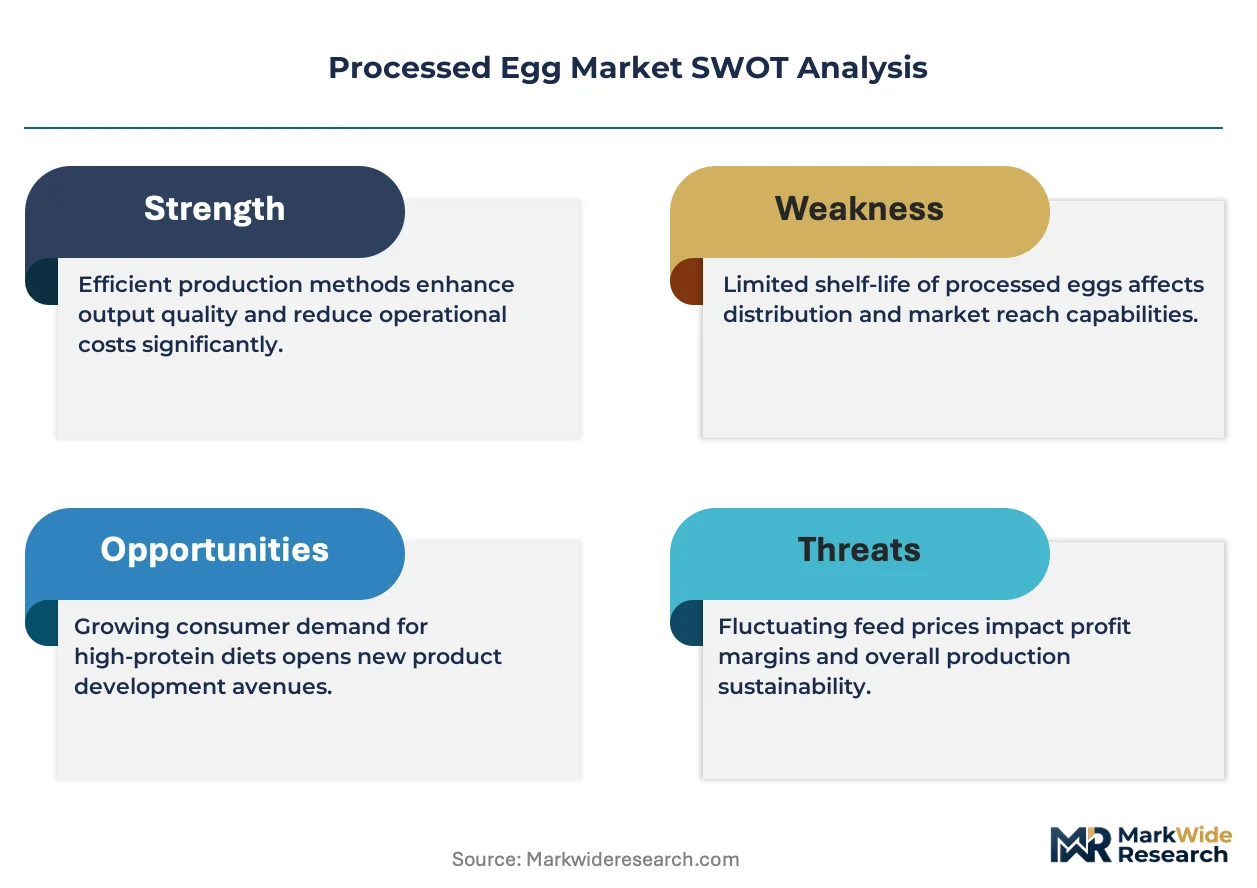
- Feed cost volatility:Soybean and corn prices fluctuate with commodity cycles, squeezing processor margins and complicating long-term contract pricing with institutional buyers.
- Cage-free housing transition costs:State-level mandates in the US require capital-intensive barn conversions, elevating production costs before supply scales to meet pledged commitments.
- Plant-based emulsifier substitution:Aquafaba and modified starches are displacing egg proteins in select vegan bakery formulations, narrowing addressable demand in niche segments.
Strategic Opportunities
- Southeast Asia cold-chain gaps:Indonesia and Vietnam lack refrigerated distribution density, creating first-mover advantage for ambient-stable powdered egg formats in food manufacturing.
- Pre-weighed liquid blend adoption:Artisan and industrial bakers are adopting portion-controlled liquid products to reduce batch variability and labor measurement errors.
- Biosecurity automation convergence:Pathogen detection robotics and automated grading systems are converging to reduce labor dependency in breaking operations.
Industry Challenges
- Avian health specialist scarcity:Veterinary talent with biosecurity and automated systems expertise is rotating toward larger integrated operations, leaving mid-scale processors exposed.
- Pasteurization compliance timelines:USDA Salmonella reduction protocols require extended validation periods for new plant designs, delaying capacity expansion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processed Egg Market |
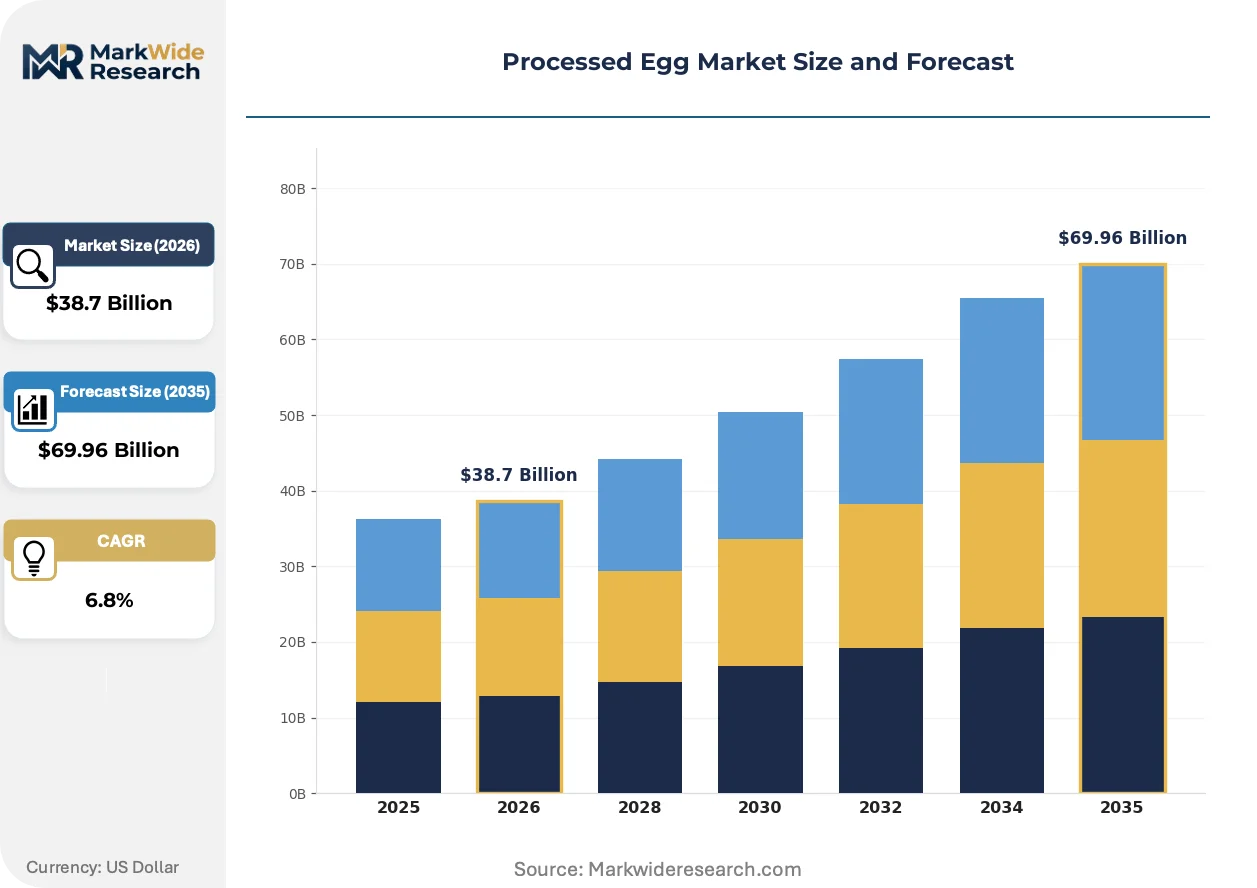
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Eggs, Powdered Eggs, Dried Eggs, Pre-cooked Eggs End User: Foodservice, Retail, Bakery, Dairy Industry Application: Food Processing, Food Preparation, Catering, Confectionery Packaging Type: Bottles, Pouches, Tetra Packs, Cans |
| Companies Covered | Cal-Maine Foods, Rose Acre Farms, Rembrandt Enterprises, Eurovo Group, Interovo Egg Group, Sanovo Technology Group, Michael Foods, Daybreak Foods, Avril SCA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processed Egg Market Strategic Shifts
Automation in breaking and grading operations is compressing labor requirements while elevating food safety thresholds, and regulatory pressure on refrigeration emissions is reshaping facility capital planning.
Hyperspectral imaging systems are decomposing traditional visual inspection workflows in egg-breaking facilities. Industrial processors are adopting these optical sorting platforms to detect hairline cracks and interior defects at line speeds exceeding manual capacity. This technology is decomposing the historical trade-off between throughput and detection accuracy, enabling simultaneous volume scaling and safety threshold elevation.
The EU F-Gas Regulation is mandating phasedown of hydrofluorocarbon refrigerants in cold-chain storage systems. Processors face retrofit deadlines or replacement capital cycles for warehouse and transport refrigeration units. European facilities are responding by piloting ammonia-CO2 cascade systems and magnetic-bearing centrifugal compressors to maintain temperature integrity during compliance transitions.
Foodservice procurement is consolidating toward direct supplier relationships that bypass traditional distribution tiers. National restaurant chains are negotiating liquid egg supply contracts directly with breaking operations, disintermediating regional distributors. This pattern is most visible in China, where quick-service operators are securing dedicated production lines for breakfast-menu scale-up.
Processed Egg Market Segmentation
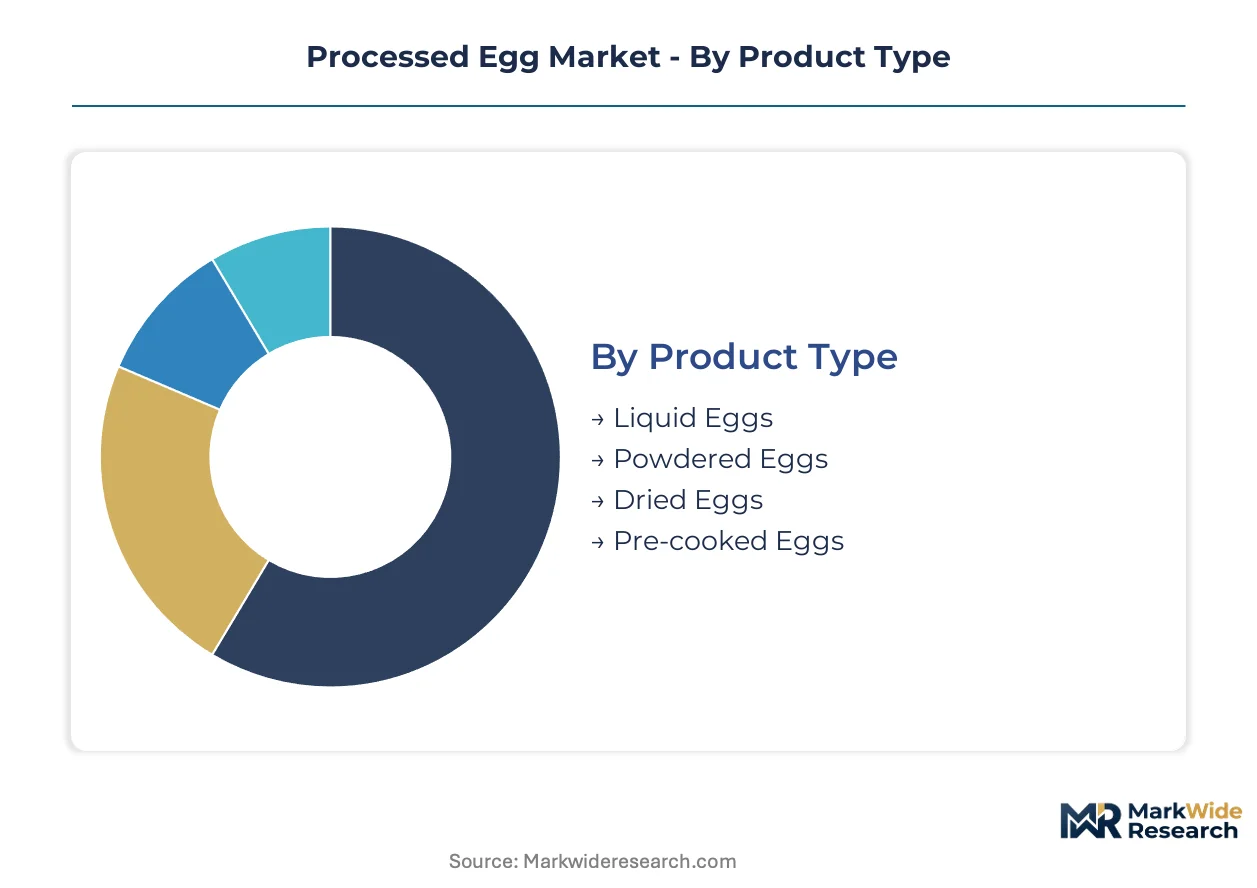
Processed egg segmentation reflects divergent margin structures across preservation technologies and customer procurement patterns. Product format determines cold-chain investment intensity, while end-user channel selection dictates pricing power and contract tenure.
Product Type:
Liquid eggs concentrate the highest margin pools due to foodservice volume commitments and operational substitution value for shell eggs.
- Liquid Eggs:Refrigerated or frozen blends with defined yolk-to-white ratios for direct kitchen substitution. Demand concentrates in Chinese quick-service restaurant chains scaling breakfast menus, where operational consistency requirements override commodity price sensitivity.
- Powdered Eggs:Spray-dried whole egg, white, or yolk powders with extended ambient shelf stability. Military rations and emergency food programs in Southeast Asia sustain premium positioning where refrigerated distribution remains underdeveloped.
- Dried Eggs:Dehydrated formats produced through drum-drying or freeze-drying methods for industrial ingredient applications. Export markets with limited cold-chain infrastructure absorb significant volume.
- Pre-cooked Eggs:Hard-boiled or scrambled products in ready-to-eat formats for institutional and retail channels. Convenience-driven procurement in healthcare and education sectors supports niche positioning.
The dominant share belongs to Liquid Eggs, while Powdered Eggs is closing the gap fastest.
End User:
Channel selection determines margin capture through contract structure, with direct foodservice relationships commanding pricing premiums over distributor-mediated retail.
- Foodservice:National restaurant chains and institutional feeders procuring liquid blends in bulk totes or bag-in-box formats. Direct supplier negotiations in China are disintermediating traditional distribution tiers.
- Retail:Supermarkets and convenience stores stocking shell egg substitutes and value-added egg products. Private-label penetration intensifies price competition in developed markets.
- Bakery:Artisan and industrial bakers adopting pre-weighed liquid blends to reduce batch variability and labor measurement errors. Above-average growth trajectory reflects formulation standardization demands.
- Dairy Industry:Ice cream and custard manufacturers utilizing egg yolk solids for emulsification and texture modification. Functional performance specifications govern supplier qualification.
Foodservice holds the dominant position, though Bakery is expanding most quickly as formulation precision requirements intensify.
Application:
Application segmentation tracks functional performance requirements, with food processing commanding volume leadership and confectionery sustaining technical premium tiers.
- Food Processing:Industrial manufacturers incorporating egg ingredients into pasta, noodles, and prepared meals for binding and texture modification. Scale economies favor liquid and dried formats.
- Food Preparation:Commercial kitchens utilizing liquid eggs for scratch cooking and recipe execution. Labor reduction through shell elimination drives procurement decisions.
- Catering:Event and contract foodservice operators requiring consistent portion control and food safety documentation. Pre-cooked formats reduce on-site labor and equipment needs.
- Confectionery:Chocolate and candy producers leveraging egg white foaming properties and yolk emulsification in premium formulations. Technical specifications command supplier certification overhead.
Food Processing dominates volume throughput, while Confectionery maintains the steepest premium pricing tier.
Packaging Type:
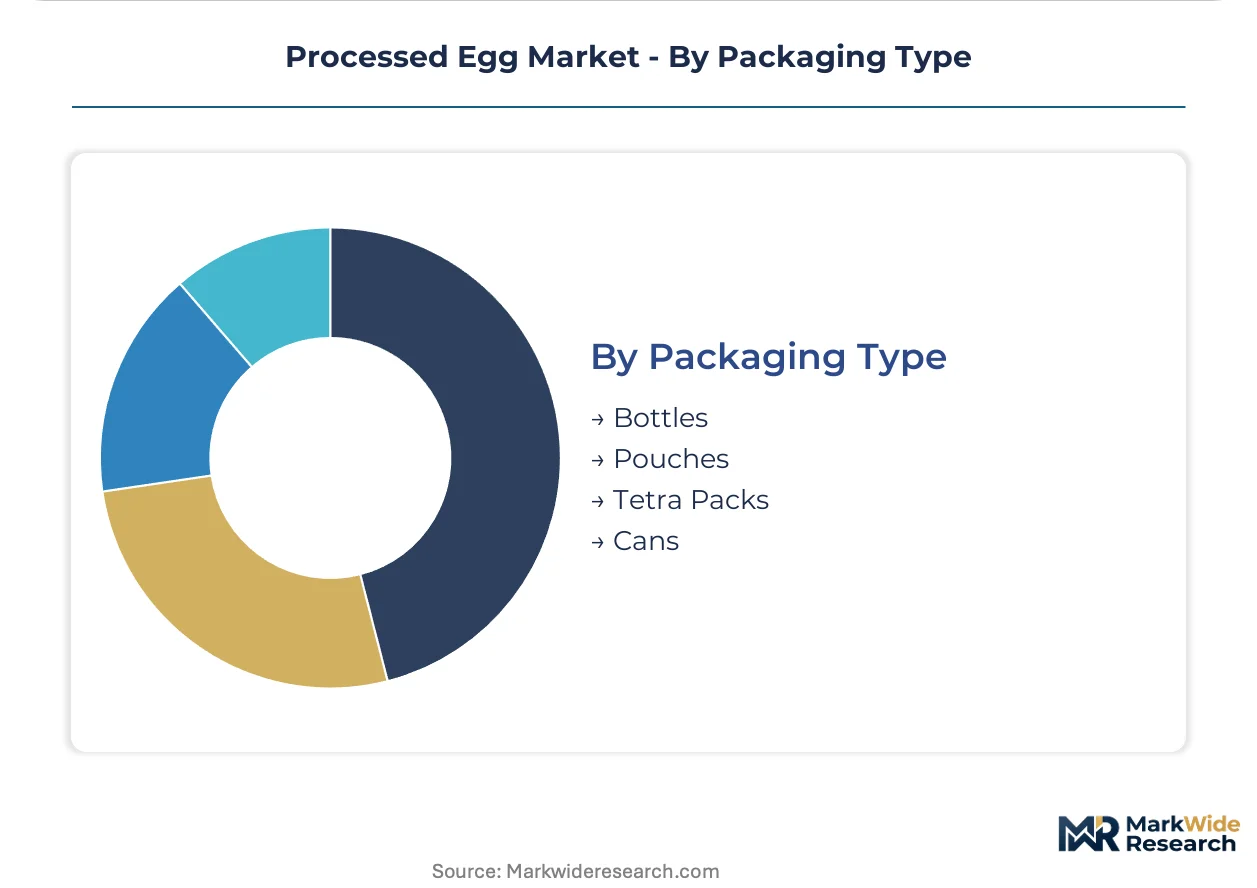
Packaging selection reflects distribution channel requirements and shelf-life extension needs, with pouches and Tetra Packs capturing growth in ambient-stable segments.
- Bottles:Rigid polyethylene containers for refrigerated liquid eggs in retail and small-format foodservice. Visibility and pour control support consumer-facing applications.
- Pouches:Flexible multilayer films for liquid and dried egg products reducing shipping cube and disposal weight. Adoption accelerates in foodservice direct delivery.
- Tetra Packs:Aseptic carton systems for extended-shelf-life liquid eggs without refrigeration. European processors pilot these formats for export market penetration.
- Cans:Metal containers for dried egg powders in military and institutional procurement. Shelf stability and handling durability override unit cost considerations.
Bottles retain the dominant installed base, though Pouches are gaining share fastest through foodservice logistics optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The USDA anchors the regulatory framework for processed egg commerce through pasteurization mandates and Salmonella reduction protocols that shape plant design across North America. Foodservice procurement patterns diverge sharply between mature cold-chain markets and regions where ambient-stable formats command premium positioning.
United States
Quick-service restaurant chains in the Southeast are scaling dedicated liquid egg production lines for breakfast-menu expansion. The FDA's Food Safety Modernization Act mandates hazard analysis across breaking facilities, elevating compliance costs for mid-scale processors. Iowa and Ohio host concentrated shell-to-liquid conversion capacity serving institutional distribution networks.
China
Quick-service operators are negotiating direct supply contracts that bypass traditional distribution tiers for operational consistency in morning-menu scale-up. SAMR enforces GB standards for egg product labeling and additive limits that govern both import eligibility and domestic formulation requirements. Yangtze River Delta processing clusters are retrofitting capacity to meet chain-restaurant procurement specifications.
Germany
Bakery manufacturers are adopting pre-weighed liquid blends to reduce batch variability in artisan and industrial formulations. The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon refrigerants, forcing cold-chain infrastructure retrofits at storage facilities. Bavarian processors are piloting ammonia-CO2 cascade systems to maintain temperature integrity during compliance transitions.
Netherlands
Export-oriented breaking operations are consolidating toward Tetra Pack aseptic formats for ambient-stable liquid egg penetration in Southeast Asian markets. EFSA oversight harmonizes with EU-wide safety thresholds while permitting flexible formulation for destination-market requirements. Rotterdam-Antwerp logistics corridors support refrigerated distribution density across Northern European foodservice networks.
Indonesia
Food manufacturers are absorbing powdered egg volumes where refrigerated distribution infrastructure remains underdeveloped, creating first-mover positioning for shelf-stable formats. The national food and drug regulator enforces labeling and safety standards that govern import eligibility for dried egg products. Java-based industrial zones are emerging as conversion points for reconstituted egg ingredients in noodle and prepared-meal production.
Processed Egg Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier that concentrates on single-format production or regional distribution. The upper tier commands pricing power through captive feed supply and direct foodservice relationships, while specialists compete on flexibility and niche certification. Three archetypes dominate: vertically integrated feed-to-table operators, large-scale shell-to-liquid converters, and institutional-channel controllers. Competitive intensity centers on capacity expansion in Southeast Asian markets and retrofit investments for EU refrigeration compliance.
Among North American integrated operators, Cal-Maine Foods and Rose Acre Farms exemplify the feed-to-table and large-scale conversion archetypes respectively. Michael Foods occupies a position within the institutional-channel tier, supplying prepared formats to national foodservice distributors. Eurovo Group and Interovo Egg Group represent European-based specialists with export-oriented positioning. These named entities anchor broader patterns of geographic specialization and format concentration without exhausting the competitive map.
| Leading Market Players |
|---|
| Cal-Maine Foods |
| Rose Acre Farms |
| Rembrandt Enterprises |
| Eurovo Group |
| Interovo Egg Group |
| Sanovo Technology Group |
| Michael Foods |
| Daybreak Foods |
| Avril SCA |
| Others |
Value Chain & Pricing Dynamics
Plant-based emulsifier substitution in vegan bakery formulations is compressing egg protein premiums while simultaneously pulling procurement gravity toward Southeast Asian markets where cold-chain gaps favor ambient-stable powdered formats. This dual displacement dynamic concentrates margin pressure on liquid egg processors in mature markets while rewarding shelf-stable specialists with export pricing power.
Pricing Analysis
Long-term offtake contracts dominate institutional foodservice procurement, with annual volume commitments securing price stability against commodity feed cost swings. Price differentiation rests on cage-free certification tiers and direct supplier relationships that bypass distributor markups. Cost compression in standard-grade liquid blends is intensifying because soybean and corn price volatility squeezes processor margins. Quick-service restaurant chains in China exhibit the lowest price sensitivity due to operational consistency requirements, while private-label retail channels absorb the highest pricing pressure.
Supply Chain Analysis
Just-in-time inventory strategies prevail among European bakery manufacturers leveraging dense cold-chain infrastructure, while Southeast Asian food manufacturers maintain strategic stockpiles of powdered eggs where refrigerated distribution remains underdeveloped. Supply concentrates in the United States, China, and the Netherlands, with Iowa and Ohio hosting shell-to-liquid conversion clusters and Yangtze River Delta facilities scaling for domestic foodservice. Feed grain inputs, refrigeration equipment, and packaging materials constitute critical dependencies. Tariff exposure on imported feed additives represents the primary structural risk. Distribution runs through direct supplier negotiations that disintermediate traditional regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's forced refrigeration retrofits constitute a technological-regulatory inflection that will bifurcate competitive positioning between compliant integrated operators and capital-constrained mid-scale processors.
For Market Incumbents: Consolidate shell-to-liquid conversion capacity in Iowa and Ohio to capture foodservice volume commitments before compliance-driven capital costs escalate. Lock in direct supplier relationships with quick-service restaurant chains in China to defend against emerging regional competitors. Prioritize ammonia-CO2 cascade system investments to meet EU retrofit deadlines while maintaining temperature integrity.
For New Entrants and Emerging Players: Artisan bakery pre-weighed liquid blend under-service in Germany offers a service-layer gap where incumbents under-serve formulation precision demands. Target Indonesian food manufacturers lacking refrigerated distribution infrastructure with ambient-stable powdered egg formats. Penetrate through technical certification partnerships with local reconstitution facilities in Java-based industrial zones.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale shell-to-liquid converters in the Midwest facing cage-free housing transition costs and pasteurization compliance delays. Long-term viability over the projection horizon favors operators with captive feed supply and direct foodservice channel control. Watch for EU F-Gas retrofit completion rates as an inflection indicator separating compliant from stranded capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Retrofit | EU F-Gas Regulation compliance mandates ammonia-CO2 cascade system adoption at European storage facilities. |
| Direct Supplier Relationship Expansion | Quick-service restaurant chains in China are bypassing distributors to secure dedicated liquid egg production lines. |
| Biosecurity Automation Investment | Pathogen detection robotics and automated grading systems reduce labor dependency in breaking operations. |
| Shelf-Stable Format Development | Tetra Pack aseptic systems enable ambient-stable liquid egg penetration in Southeast Asian export markets. |
| Backward Integration into Feed Supply | Captive grain sourcing insulates processors from soybean and corn price volatility squeezing margins. |
Study Parameters
Operator-level perspectives from plant managers at breaking facilities, procurement leads at national foodservice distributors, veterinary biosecurity specialists, and channel sales heads at refrigeration equipment suppliers anchored the qualitative base. These primary inputs combined with customs and trade data, USDA pasteurization compliance records, EU F-Gas Regulation implementation timelines, and SEC filings from publicly traded processors. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across preservation technologies and end-user channels.
Sensitivity analysis tested forecast robustness against feed cost volatility scenarios and cage-free housing mandate acceleration timelines across the projection horizon. Segmentation dimensions modeled include product format, end-user channel, application function, and regional regulatory cluster. CAGRs derived from historical volume trajectories and projected penetration rates in quick-service restaurant breakfast expansion and bakery formulation standardization. Industry-specific inputs incorporated SAMR labeling standard enforcement intensity and Southeast Asian cold-chain infrastructure development pace.
Material uncertainties — avian pathogen outbreak severity, EU refrigeration retrofit deadline extensions, and plant-based emulsifier substitution rates in vegan formulations — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and commodity feed price mean reversion. Revision becomes warranted when cage-free housing transition cost pass-through crosses foodservice buyer elasticity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Fresh Pasta Market
Processed Foods
Shelf-Stable Soup Market
Processed Foods
Ice Cream Parlor Market
Processed Foods
High Pressure Processing (HPP) for Rice and Grain Market
Processed Foods
Pates Market
Processed Foods
Potato Soup Market
Processed Foods
Asia-Pacific Soup Market
Processed Foods
Fermented Food and Drinks Market
Processed Foods
United States Processed Meat Market
Processed Foods
Europe Egg Powder Market
Processed Foods
Fast-Food Reusable Market
Processed Foods
Imitation Whipped Cream Market
Processed Foods
Egg White Cubes Market
Processed Foods
Asia-Pacific Ice Cream Market
Processed Foods
Casual Marinated Products Market
Processed Foods
Tomato Paste Market