
 Porridge Market | 2026-2036
Porridge Market Size, Share, and Industry Trends Forecast 2026-2036
Porridge Market Analysis
Subscription-based breakfast delivery and personalized nutrition planning is shifting how porridge brands monetize recurring consumer relationships. The Quaker Oats Company leverages its century-old supply infrastructure to sustain bulk retail dominance across North American supermarkets. General Mills anchors its portfolio through diversified grain platforms that compete on both price and nutritional positioning. Nature's Path Foods specializes in certified organic sourcing that differentiates its channel presence in premium health food stores.
Porridge comprises milled or whole oat grains cooked with water or milk to achieve a semi-liquid consistency, typically containing beta-glucan soluble fiber at concentrations between three and five percent by weight, and serves as a shelf-stable, nutrient-dense breakfast staple across consumer and foodservice channels. Instant Porridge captures the largest volume share due to time-scarcity dynamics among urban commuters, while Steel-Cut Oats commands premium shelf positioning in specialty retail with higher margin structures. Single-Serve Cups represent the fastest-growing Packaging Type as convenience-seeking buyers prioritize portability and portion control in on-premise consumption settings.
The FDA oversees nutrition labeling and health claim substantiation for oat-based products in the United States, while EFSA governs novel food approvals and organic certification standards across European markets, collectively elevating barrier costs for new entrants lacking regulatory compliance infrastructure. India's FSSAI enforces progressively stricter fortification mandates that reshape export-bound formulation strategies. Stakeholders must monitor evolving clean-label thresholds and regional fortification mandates to determine where reformulation investments yield sustainable market access.
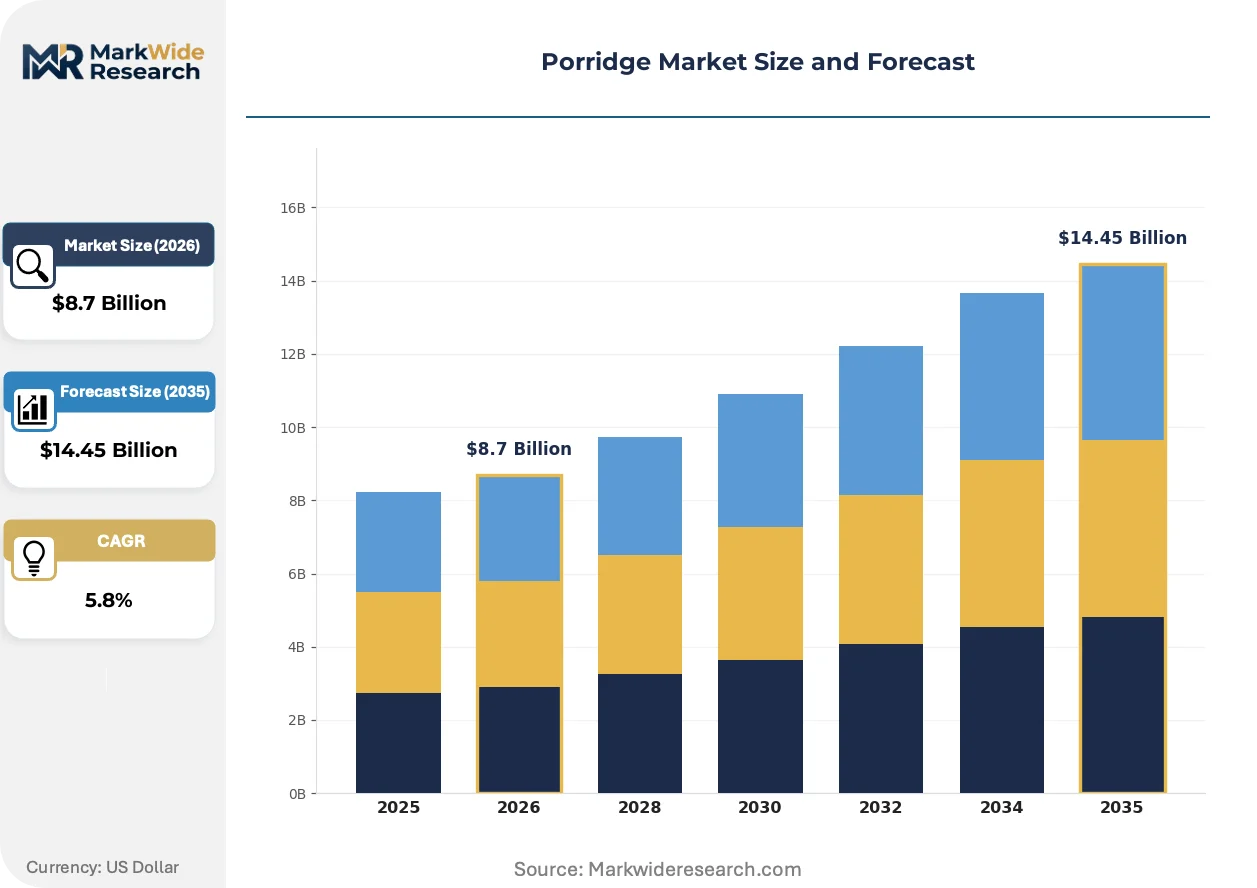
Market Dynamics
Clean-label mandates from EFSA and FDA are forcing simultaneous reformulation across legacy oat portfolios, compressing R&D timelines while opening premium positioning for compliant brands.
Growth Catalysts
- EU Organic Certification:EFSA's tightened novel food approval pathways reward early organic adopters with shelf-space advantages in German and French retail.
- FSSAI Fortification Mandates:India's micronutrient requirements for export-bound products pull investment toward iron and vitamin D enrichment capabilities.
- Urban Commuter Time-Scarcity:Single-serve instant formats capture morning consumption occasions previously lost to out-of-home breakfast alternatives.
Market Restraints
- Oat Input Volatility:Prairie drought cycles in Canada and Russia generate raw material price swings that compress margin stability for non-integrated processors.
- Steel-Cut Supply Concentration:Traditional Irish and Scottish millers control premium groat supply, creating bottleneck risk for brands without long-term contracting relationships.
- Clean-Label Compliance Costs:EFSA's additive restrictions and FDA's health claim substantiation requirements elevate fixed regulatory infrastructure costs beyond mid-tier entrant capacity.
Strategic Opportunities
- Southeast Asia Penetration:Vietnam and Indonesia present underdeveloped breakfast cereal habits where localized flavor adaptations can establish first-mover positioning.
- Subscription Channel Expansion:Direct-to-consumer replenishment models bypass slotting fee structures and capture lifetime value through personalized nutrition bundling.
- Functional Ingredient Convergence:Collagen peptides and adaptogenic mushroom extracts create premium hybrid categories at intersection of sports nutrition and traditional breakfast.
Industry Challenges
- Legacy Equipment Retrofitting:Existing roller mills require capital-intensive modification to handle gluten-free certification protocols and allergen segregation.
- Regulatory Timeline Compression:EFSA's evolving novel food definitions force simultaneous multi-jurisdiction dossier preparation without guaranteed approval sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Porridge Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Porridge, Rolled Oats, Steel-Cut Oats, Gluten-Free Porridge Ingredient Source: Whole Grains, Organic Grains, Flavored Varieties, Conventional Grains Packaging Type: Bags, Boxes, Single-Serve Cups, Bulk Containers Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Specialty Shops |
| Companies Covered | The Quaker Oats Company, General Mills, Nestle, Kellogg Company, Bob's Red Mill Natural Foods, Nature's Path Foods, B&G Foods, Grain Millers, Blue Lake Milling Pty Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Porridge Market Emerging Trajectories
Reformulation priorities are converging on protein fortification and fermentation-derived flavor enhancement, reshaping both ingredient sourcing patterns and production equipment specifications.
Spray-dried protein isolates from pea and fava sources are unifying nutritional density targets with clean-label positioning. Sports nutrition buyers and wellness-focused millennials adopt these fortified formats faster than traditional demographic cohorts. This convergence is compressing the gap between commodity oats and premium functional nutrition categories.
REACH chemical safety registrations and EU Green Deal agricultural sustainability criteria are tightening traceability requirements across European supply chains. Oat processors must now document cultivation inputs and carbon intensity at field level. German and Nordic retail channels enforce these standards most aggressively, filtering non-compliant suppliers from shelf access.
Portion-controlled single-serve formats are displacing bulk bag purchasing in urban household contexts. Convenience retailers and workplace micro-markets capture consumption previously routed through supermarket center aisles. United Kingdom and Netherlands metropolitan areas exhibit the fastest channel rotation toward grab-and-go breakfast solutions.
Porridge Market Segmentation
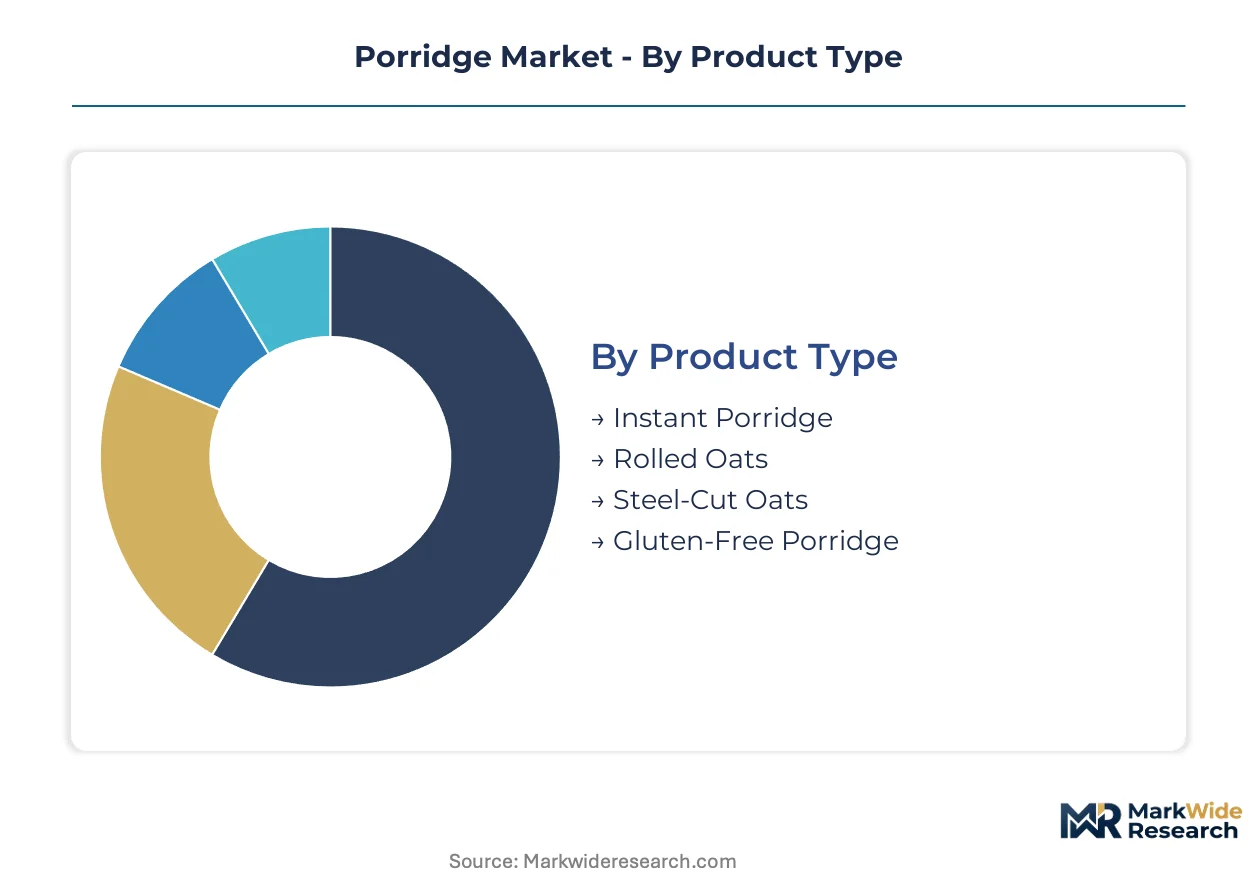
Porridge manufacturers navigate distinct demand profiles across preparation formats, sourcing credentials, and consumption occasions. Each segmentation axis reveals divergent margin structures and channel access requirements that shape portfolio investment priorities.
Product Type:
Standalone breakfast formats dominate retail shelf space, while embedded ingredient applications in foodservice and bakery supply chains operate under different specification regimes.
- Instant Porridge:Pre-cooked and dehydrated oat flakes reconstitute with hot water or milk in under two minutes, achieving semi-liquid consistency through modified starch stabilization. Urban commuters in the United Kingdom and Germany drive volume, prioritizing speed over texture nuance during weekday consumption windows.
- Steel-Cut Oats:Whole oat groats sliced into pinhead pieces require 20-30 minute stovetop preparation, yielding chewy texture and lower glycemic response. Specialty retailers in Ireland and Scotland command premium positioning, with heritage millers controlling limited groat supply through long-term agricultural contracts.
- Rolled Oats:Steamed and flattened groats balance preparation speed with nutritional retention, serving as the default reference standard for home cooking and overnight soaking methods.
- Gluten-Free Porridge:Certified oat varieties processed in segregated facilities meet celiac and sensitivity requirements, carrying third-party verification premiums in North American and European health food channels.
Instant Porridge leads volumes today; Steel-Cut Oats is gaining share fastest in premium positioning.
Ingredient Source:
Cost tier stratification separates commodity grain procurement from certified organic and value-added flavor systems.
- Whole Grains:Intact oat kernels retain bran, germ, and endosperm layers, delivering beta-glucan concentrations at the upper range of nutritional labeling thresholds. German and Nordic retail buyers enforce whole grain front-of-pack claims as listing prerequisites.
- Organic Grains:Cultivation without synthetic pesticides or fertilizers meets EU Organic Certification and USDA Organic standards, qualifying for shelf-space advantages in Edeka, REWE, and Whole Foods Market assortments.
- Flavored Varieties:Cinnamon, apple, and maple formulations target children's breakfast occasions and convenience-seeking adults through pre-sweetened single-serve formats.
- Conventional Grains:Standard agricultural inputs support price-competitive positioning in mass-market retail and foodservice bulk purchasing.
Conventional Grains anchor volume throughput; Organic Grains is climbing the fastest on clean-label momentum.
Packaging Type:
Portability requirements and household size demographics determine format selection across urban and suburban purchasing contexts.
- Single-Serve Cups:Microwaveable containers with pre-portioned dry mix and separate topping compartments capture workplace micro-market and convenience retail distribution in the Netherlands and United Kingdom metropolitan corridors.
- Bags:Flexible multilayer films with resealable closures dominate family-size purchasing in supermarket center aisles, optimizing shipping cube efficiency.
- Boxes:Rigid paperboard structures support brand billboard visibility and premium gifting occasions in specialty retail.
- Bulk Containers:Foodservice pails and institutional dispensers serve hospitality, education, and healthcare feeding operations with cost-per-serving optimization.
Bags lead volumes today; Single-Serve Cups is expanding most quickly through convenience channel rotation.
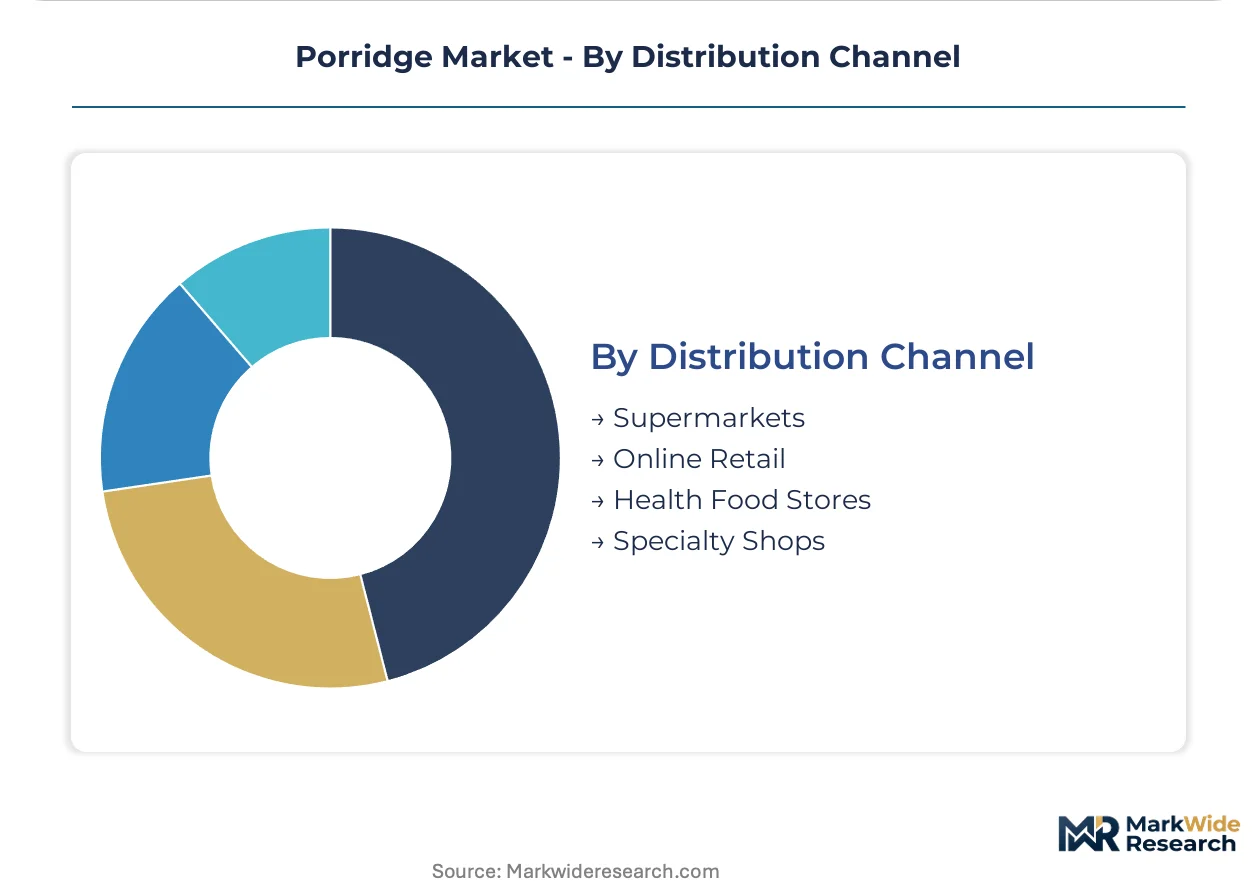
Distribution Channel:
Customer acquisition economics and margin retention vary sharply across self-service retail and assisted-selling environments.
- Supermarkets:Center-aisle placement in Tesco, Sainsbury's, and Kroger stores drives impulse and replenishment purchasing through promotional pricing and loyalty program integration.
- Online Retail:Amazon and direct-to-consumer subscription models bypass slotting fees while capturing recurring revenue through personalized nutrition bundling and auto-replenishment algorithms.
- Health Food Stores:Assisted selling environments like Holland & Barrett and independent natural products retailers prioritize certified organic and functional fortified assortments with higher staff engagement.
- Specialty Shops:Irish and Scottish heritage millers operate branded retail channels emphasizing provenance narrative and limited-edition seasonal releases.
Supermarkets anchor volume today; Online Retail is gaining share fastest on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting porridge manufacturing toward jurisdictions with lower compliance costs while premium positioning gravitates toward markets with stringent clean-label standards. FDA and EFSA additive restrictions elevate fixed costs for North American and European producers, incentivizing contract manufacturing migration to South Asia where FSSAI fortification mandates align with export-bound formulation requirements.
United States
FDA nutrition labeling and health claim substantiation requirements compress R&D timelines for reformulating legacy oat portfolios. Urban commuter time-scarcity drives single-serve cup adoption in metropolitan corridors. Chicago and Minneapolis-St. Paul anchor North American processing infrastructure, with roller mill concentration supporting instant format scale.
Germany
EFSA novel food approval pathways and EU Organic Certification standards reward early clean-label adopters with shelf-space advantages in Edeka and REWE assortments. REACH chemical safety registrations tighten traceability requirements across supply chains. Hamburg and Bremen harbor zones concentrate import processing for Nordic and Scottish groat supply.
United Kingdom
Traditional oat consumption intersects with modern convenience formats, with London and Manchester metropolitan areas exhibiting fastest channel rotation toward grab-and-go breakfast solutions. Heritage millers in Scotland and Ireland control premium steel-cut groat supply through long-term agricultural contracts. Clean-label thresholds from post-Brexit regulatory divergence create formulation complexity for cross-border trade.
India
FSSAI fortification mandates for iron and vitamin D enrichment reshape export-bound formulation strategies for processors supplying Middle East and Southeast Asian markets. Punjab and Haryana agricultural belts concentrate oat cultivation trials as climate adaptation shifts traditional wheat-rice rotation patterns. Mumbai and Bangalore anchor contract manufacturing capacity for international brands seeking cost-competitive production.
Vietnam
Underdeveloped breakfast cereal habits present first-mover positioning opportunities for localized flavor adaptations targeting emerging middle-class consumption. Ho Chi Minh City and Hanoi metropolitan corridors drive modern trade expansion in convenience retail channels. Import tariff structures on processed foods incentivize domestic blending and packaging investments over finished goods importation.
Porridge Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage millers controlling premium groat supply and multinational food conglomerates dominating mass-market instant formats. Market structure tilts toward consolidated retail shelf presence contested by three to four dominant branded portfolios, while private-label and co-manufacturing capacity fragments across regional processors. Strategic archetypes include century-old supply infrastructure holders, certified organic sourcing specialists, and diversified grain platform operators. Competitive moves concentrate on portfolio diversification into functional ingredient convergence and geographic expansion through localized flavor adaptation.
Within the heritage infrastructure tier, The Quaker Oats Company and General Mills occupy positions as scale-driven North American anchors. Nature's Path Foods exemplifies the certified organic sourcing archetype, differentiating channel presence in premium health food retail. Bob's Red Mill Natural Foods represents employee-owned structure specialization in whole-grain and gluten-free certified formats. These three companies collectively illustrate the competitive spectrum from mass-market convenience positioning through premium clean-label segmentation.
| Leading Market Players |
|---|
| The Quaker Oats Company |
| General Mills |
| Nestle |
| Kellogg Company |
| Bob's Red Mill Natural Foods |
| Nature's Path Foods |
| B&G Foods |
| Grain Millers |
| Blue Lake Milling Pty Ltd |
| Others |
Supply Flow & Price Mechanics
Urban commuter concentration in United Kingdom and German metropolitan corridors anchors demand for single-serve instant formats, locking in premium pricing for convenience-positioned portfolios while compressing margins on bulk bag offerings. This buyer archetype's time-scarcity preferences create asymmetric pricing power across preparation format tiers.
Pricing Analysis
Capacity additions in India and Vietnam are reshaping price floors for export-bound conventional grain supply. Three-tier pricing structure across premium, standard, and economy levels separates heritage-miller steel-cut positioning from mass-market instant and private-label commodity tiers. Price differentiation hinges on organic certification grade and volume scale, with FSSAI fortification compliance adding cost layers that squeeze mid-tier processors. Cost compression in conventional grain segments is intensifying because prairie drought cycles in Canada and Russia generate raw material volatility. Foodservice bulk buyers exhibit highest price sensitivity; specialty retail channels demonstrate lowest sensitivity due to provenance narrative premiums.
Supply Chain Analysis
Direct-to-retail channels handle hyperscale supermarket demand while specialty millers maintain controlled distribution through heritage retail partnerships. Geographic supply concentrates in Canada, Russia, and India for raw oat cultivation, with processing gravity in United States, United Kingdom, and Germany. Raw material dependencies rest on groat supply from traditional Irish and Scottish millers, modified starch stabilizers for instant formats, and spray-dried protein isolates from pea and fava sources. Single-source vulnerability in premium groat supply creates bottleneck risk for brands lacking long-term contracting relationships. Distribution runs through supermarket center aisles, online retail platforms, and convenience micro-markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Porridge market margin expansion rests on clean-label compliance cost recovery through premium positioning and operational scale efficiencies in single-serve format manufacturing.
For Market Incumbents: Extend organic certification coverage across instant portfolios to capture EFSA shelf-space advantages in German and French retail. Deepen backward integration into groat supply through long-term agricultural contracts with Scottish and Irish heritage millers, insulating against steel-cut supply concentration risk. Fortification infrastructure investment in iron and vitamin D enrichment capabilities defends against FSSAI mandate displacement of non-compliant export formulations. For New Entrants and Emerging Players: EU Organic Certification in Germany and France opens a window for certified organic positioning in premium health food channels where incumbent coverage remains thin. Target Vietnam and Indonesia for localized flavor adaptations in convenience retail corridors where breakfast cereal habits remain underdeveloped. Direct-to-consumer subscription models bypass slotting fee structures and capture lifetime value through personalized nutrition bundling. For Investors and Strategic Acquirers: Diversified grain platform operators are the most active acquirer in this space, seeking functional ingredient convergence capabilities at the sports nutrition-breakfast intersection. Acquisition target archetype: certified organic sourcing specialists with established Edeka, REWE, or Whole Foods Market channel presence. Signal to watch: EFSA novel food approval timeline compression that elevates compliance infrastructure value for dossier-ready assets.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | EFSA additive restrictions reward early compliant brands with premium shelf positioning in German retail. |
| Functional Ingredient Convergence | Collagen peptide and adaptogenic mushroom integration captures sports nutrition buyer migration toward breakfast occasions. |
| Subscription Channel Expansion | Auto-replenishment algorithms bypass supermarket slotting fees while capturing recurring revenue in United Kingdom urban corridors. |
| Southeast Asia Localization | Vietnam and Indonesia flavor adaptation establishes first-mover positioning where breakfast cereal penetration remains low. |
| Heritage Supply Contracting | Long-term groat agreements with Scottish and Irish millers secure premium steel-cut positioning against supply bottleneck risk. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining executive interviews with brand managers, category buyers at Tesco and Kroger, supply planners at roller mill processors, and regulatory affairs leads at export-oriented manufacturers. Secondary validation draws from FDA nutrition labeling guidance, EFSA novel food registers, FSSAI fortification circulars, and Nielsen retail audit data. Bottom-up volume modeling triangulates with top-down category spend analysis.
Granularity-level modeling disaggregates volume and value across preparation format, ingredient source certification tier, packaging type, and distribution channel throughout the forecast period. CAGRs derive from segment-level growth rate reconciliation against macroeconomic consumption indicators. Industry-specific forecast inputs include urban commuter time-scarcity indices and clean-label regulatory compliance cost curves.
Revisions become necessary when EFSA novel food definitions shift, prairie drought cycles intensify oat input volatility, or FSSAI fortification mandates expand beyond current iron and vitamin D requirements. Forecasts reflect documented assumptions regarding regulatory timeline stability and supply chain traceability cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Ready to Serve Prefabricated Dishes Market
Processed Foods
Tomato Paste Market
Processed Foods
Margarine Market
Processed Foods
India Spray Dried Food Market
Processed Foods
North America Ice Cream Market
Processed Foods
Processed Vegetable Market
Processed Foods
Tomato Puree Market
Processed Foods
Processed Cashew Market
Processed Foods
Processed Peanut Market
Processed Foods
Noodles Market
Processed Foods
Soup Market
Processed Foods
Fat Free Food Market
Processed Foods
China Freeze-Dried Food Market
Processed Foods
Apple Butter Market
Processed Foods
Potato Soup Market
Processed Foods
Accompanying Marinated Product Market