
 North America Ice Cream Market | 2026-2036
North America Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ice Cream Market Intelligence
Dairy processor capacity in Wisconsin and New York is decoupling from traditional seasonal production cycles. Nestlé leverages its frozen dessert infrastructure to sustain year-round distribution across the Upper Midwest. Blue Bell Creameries anchors its competitive position through deep channel relationships in the South Central states. Unilever competes via specialized non-dairy and plant-based formulation capabilities that differentiate its portfolio from conventional offerings.
Ice cream denotes a frozen dairy confection typically containing milk fat, sweeteners, and air overrun of 20 to 100 percent, churned at sub-zero temperatures to achieve a semi-solid foam structure; its primary commercial purpose centers on refreshment, indulgence, and portion-controlled dessert occasions in both retail and food service environments. Non-dairy formulations now represent the fastest-expanding product type as lactose-intolerant consumers and flexitarian households shift purchasing patterns. The food service distribution channel captures disproportionate margin pools in high-traffic metropolitan markets, while supermarkets remain the volume foundation through multi-pack carton and tub formats. Sugar-free and low-fat segments occupy mature growth trajectories with stable but slower expansion relative to premium and alternative-dairy innovations.
The FDA governs standard of identity requirements for ice cream and frozen desserts, including minimum milk fat thresholds and labeling disclosures, while the USDA oversees dairy ingredient grading and safety protocols that affect raw material sourcing across the supply chain. State-level dairy commissions in California, Wisconsin, and New York impose additional quality certifications that shape processor compliance costs and market access conditions. Stakeholders must monitor evolving plant-based labeling disputes and sugar-reduction mandates that will determine which formulation investments secure shelf space and consumer loyalty in the decade ahead.
Market Dynamics
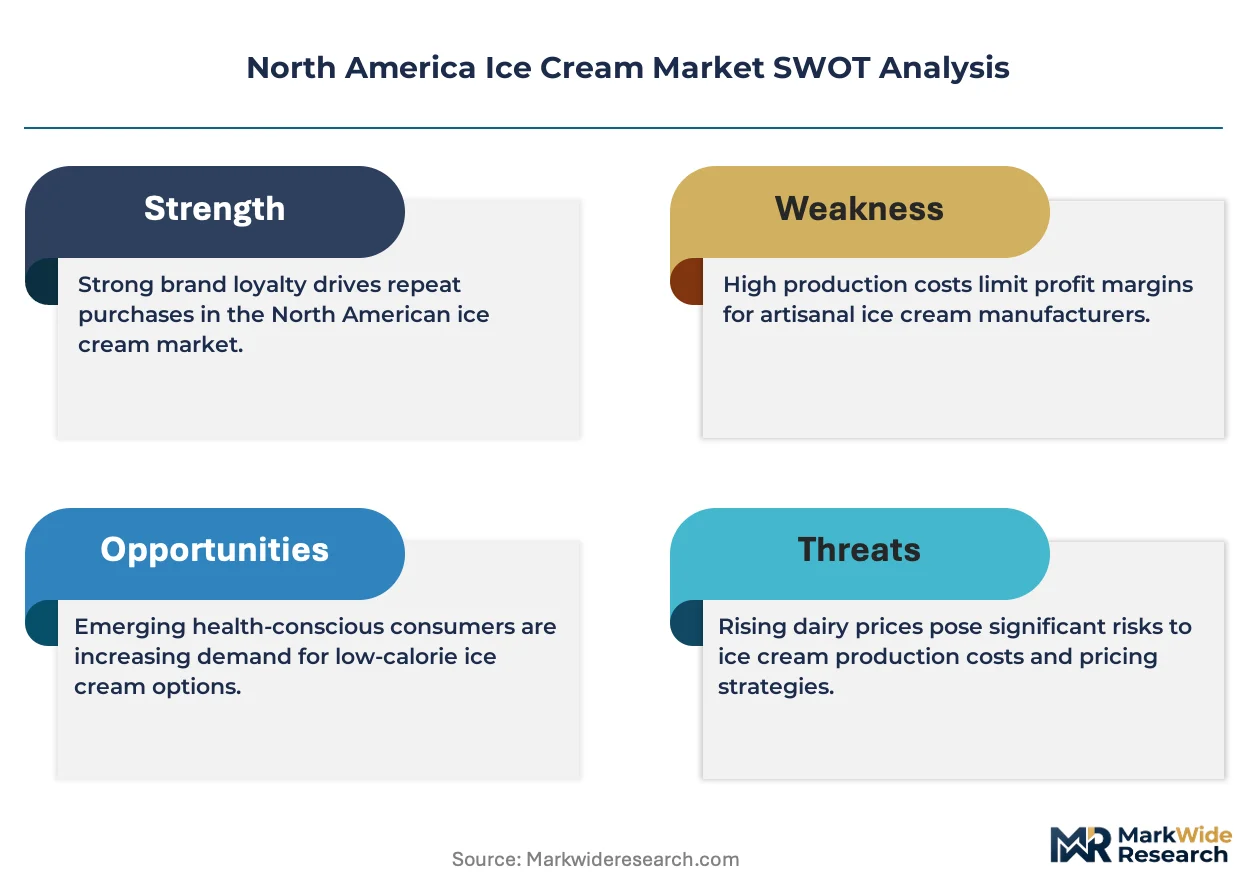
The FDA's updated Nutrition Facts labeling requirements for added sugars are forcing reformulation priorities across the North American ice cream supply chain. Premium artisanal scoop shops and mass-market producers alike must recalibrate ingredient sourcing and product positioning to maintain shelf space and consumer trust.
Growth Catalysts
- Plant-Based Formulation Advances:Oat and coconut milk processing technologies enable texture parity with conventional dairy bases. Flexitarian households in urban retail corridors drive trial and repeat purchase velocity.
- California's Dairy Processing Corridor:Concentrated infrastructure supports year-round production decoupled from traditional seasonal cycles. Proximity to ingredient innovation clusters accelerates new product development timelines.
- Food Service Channel Expansion:High-traffic metropolitan markets capture disproportionate margin pools through experiential scoop shop formats. Destination retail positioning in urban corridors sustains premium pricing power.
Market Restraints
- Butterfat Supply Volatility:Dairy commodity price swings compress margin predictability for premium formulations. Wisconsin and New York processor contracts face renegotiation pressure during feed cost spikes.
- Regulatory Friction from Plant-Based Labeling Disputes:State-level dairy commissions impose additional quality certifications that shape compliance costs. Definition battles over "milk" and "cream" terminology create market access uncertainty.
- Substitution Threat from Frozen Novelty Alternatives:Gelato, sorbet, and frozen yogurt capture indulgence occasions with lower fat positioning. Health-conscious consumers rotate across frozen dessert categories without brand loyalty.
Strategic Opportunities
- Underpenetrated Canadian Specialty Segment:Premium artisanal formats remain concentrated in Toronto and Vancouver corridors. Expansion into Calgary, Edmonton, and secondary Quebec markets offers whitespace capture.
- Sugar-Reduction Technology Convergence:Allulose and monk fruit sweetener systems combined with flavor masking innovations enable clean-label reduced-sugar positioning. FDA guidance on added sugars disclosure accelerates adoption incentives.
- Direct-to-Consumer Subscription Channels:Pint club models bypass traditional retail slotting fees and build recurring revenue. Regional flavor customization strengthens brand affinity in the Northeast specialty frozen dessert sector.
Industry Challenges
- Artisanal Production Skill Scarcity:Small-batch pasteurization and overrun control expertise concentrates among legacy dairy professionals. Scoop shop expansion outpaces trained workforce availability in high-growth urban markets.
- Cold Chain Capex Intensity:Last-mile frozen distribution requires specialized fleet and storage infrastructure. Independent operators face capital barriers to multi-state expansion.
- USDA Organic Certification Timelines:Dairy ingredient grading and safety protocol compliance extends new product launch windows. Sourcing certified organic milk fat constrains formulation flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ice Cream Market |
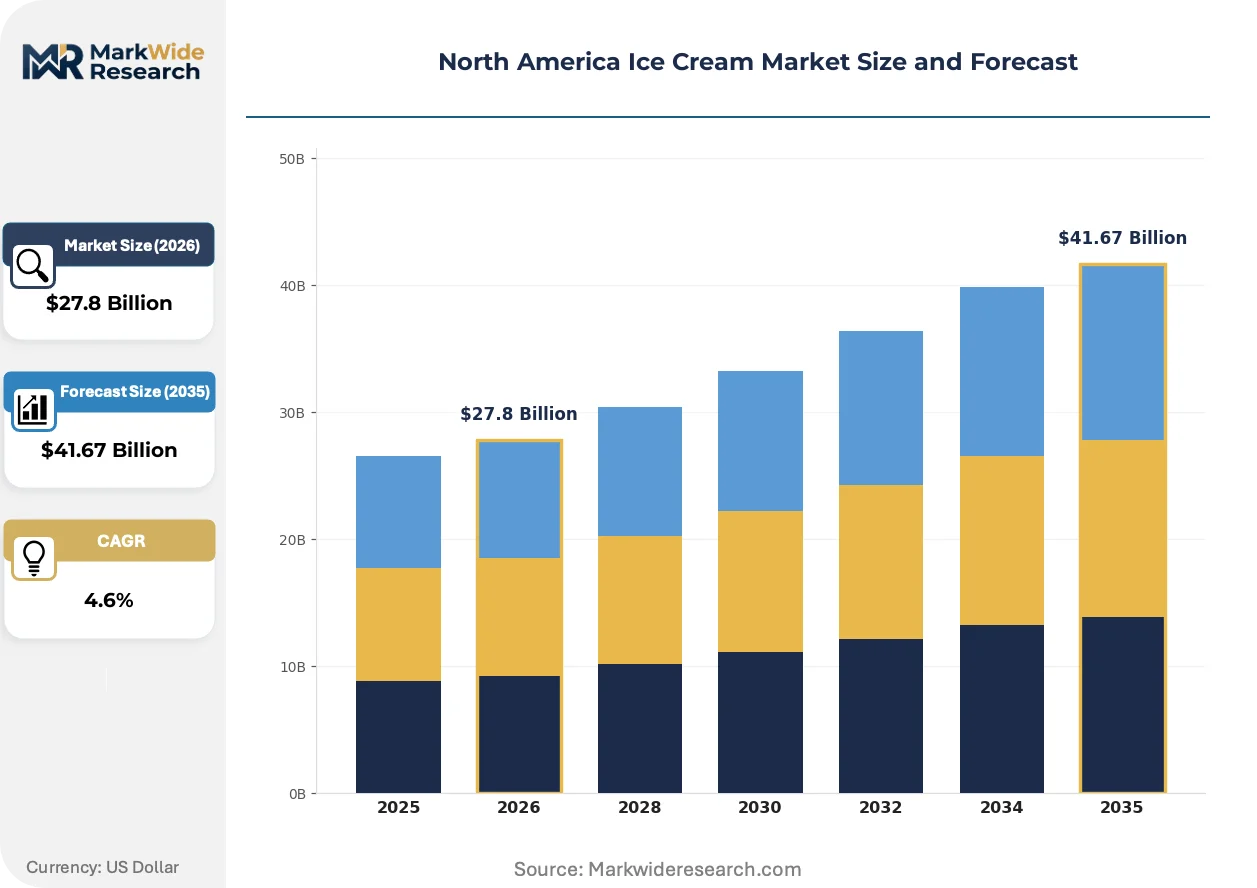
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $41.67 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Low-Fat, Sugar-Free, Non-Dairy Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service Flavor: Chocolate, Vanilla, Strawberry, Mint Packaging Type: Carton, Tub, Cone, Cup |
| Companies Covered | Blue Bell Creameries, Nestlé, Froneri International Limited, Turkey Hill Dairy, General Mills, Wells Enterprises Inc., Tillamook County Creamery Association, Baskin-Robbins, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ice Cream Market Strategic Shifts & Innovations
Reformulation priorities are converging with channel diversification to reshape competitive positioning across the North American ice cream landscape. Technology investment and regulatory adaptation now determine which producers secure sustained growth trajectories.
Precision fermentation-derived dairy proteins are expanding into ice cream bases to deliver authentic mouthfeel without lactose or cholesterol burden. Clean-label seekers and lactose-intolerant consumers adopt these formulations at accelerating rates. This technology is expanding into premium pint formats previously dominated by conventional dairy, compressing the price-performance gap between alternative and traditional segments.
The FDA's updated Nutrition Facts labeling requirements mandate added sugars disclosure with standardized serving sizes. Reformulation teams prioritize glycemic index reduction and natural sweetener blends to preserve indulgence perception. Sugar-free and low-fat segments face the steepest compliance adaptation costs as legacy recipes require complete reconstruction.
Urban food halls and mixed-use developments are consolidating dessert occasion capture through experiential scoop shop formats. Supermarket multi-pack carton volumes face displacement from impulse-driven single-serve purchases. California's dairy processing corridor and the Northeast specialty frozen dessert sector exhibit the most pronounced channel rotation, with food service distribution infrastructure expanding fastest in high-density metropolitan markets.
North America Ice Cream Market Segmentation
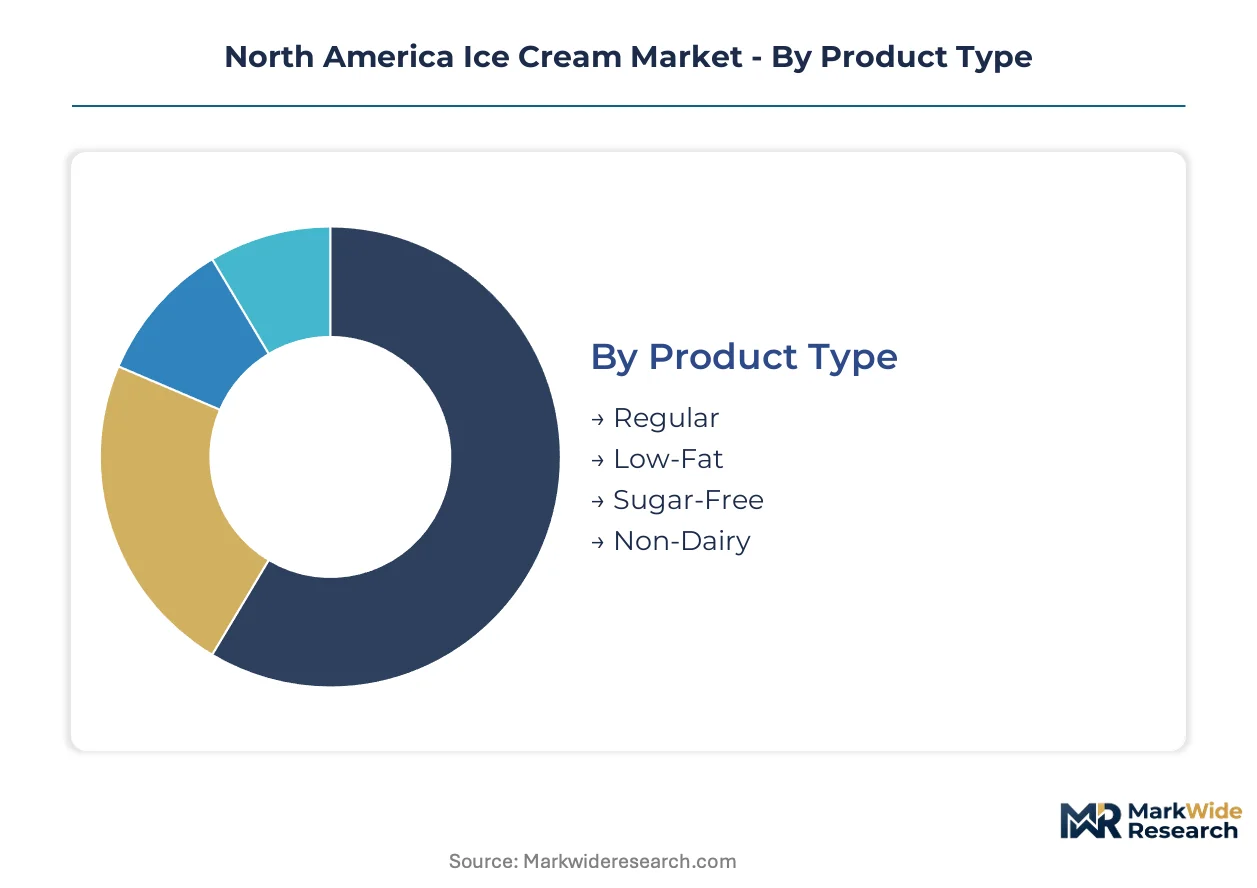
Ice cream segmentation in North America tracks evolving dietary preferences and channel migration patterns. Reformulation investments cluster where consumer definitions of indulgence are shifting fastest.
Product Type:
Upgrade cycles accelerate as households rotate between traditional dairy and alternative bases based on health priorities and occasion type.
- Regular:Full-fat dairy formulations with 10-16% milkfat content deliver the densest mouthfeel and air overrun control. Demand concentrates in the Northeast's specialty frozen dessert sector where scoop shops command premium pricing for artisanal executions.
- Non-Dairy:Oat, coconut, and almond milk bases achieve texture parity through modified fat structuring and protein stabilization. California's dairy processing corridor anchors production scale as flexitarian households in urban retail corridors drive velocity.
- Low-Fat:Reduced milkfat formulations rely on bulking agents and emulsifier systems to compensate for structural loss.
- Sugar-Free:Polyol and high-intensity sweetener combinations serve diabetic and ketogenic diet adherents.
Regular sits at the top of the volume ranking, with Non-Dairy climbing the fastest.
Distribution Channel:
Channel economics diverge sharply between volume-driven retail and margin-rich food service, with capital requirements determining operator access.
- Food Service:Scoop shops, quick-service restaurants, and dessert-focused concepts capture impulse occasions with 60-70% gross margins. High-traffic metropolitan markets in Toronto and Vancouver sustain destination retail positioning.
- Supermarkets:Multi-pack cartons and bulk tubs anchor household stock-up trips with efficient logistics and year-round shelf presence.
- Convenience Stores:Single-serve novelties and grab-and-go pints serve immediate consumption needs.
- Online Retail:Direct-to-consumer pint clubs and frozen delivery platforms bypass slotting fees.
Supermarkets dominate absolute volume, though Food Service captures the steepest expansion trajectory.
Flavor:
Flavor preference stability in core varieties contrasts with seasonal limited-edition velocity, creating dual production planning requirements.
- Vanilla:The most versatile base for mix-ins and dessert applications, with Madagascar and Tahitian bean sourcing tiers. Demand concentrates in food service channels where customization drives attachment.
- Chocolate:Cocoa butter and liquor ratios differentiate premium from mass-market positioning. The South Central states show particular concentration for regional processor formulations.
- Strawberry:Fruit preparation inclusions require careful freeze-thaw stability engineering.
- Mint:Peppermint oil and chocolate chip combinations serve seasonal peaks.
Vanilla maintains the broadest penetration, while Chocolate gains share fastest in premium tier repositioning.
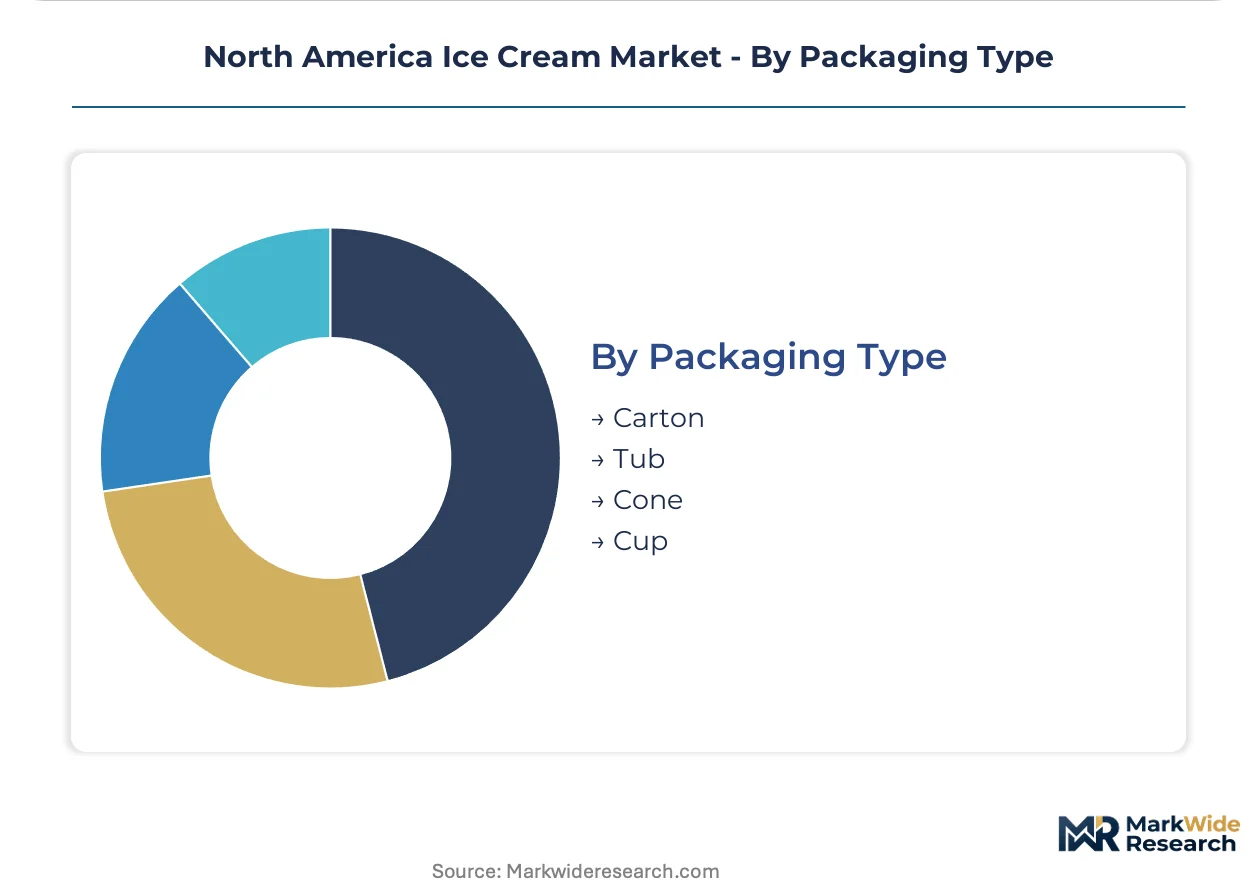
Packaging Type:
Packaging selection signals consumption occasion and price tier, with sustainability pressures reshaping material specifications.
- Tub:Wide-mouth polypropylene containers dominate family-size and premium pint formats. The Upper Midwest shows concentrated demand for 48-64oz value offerings.
- Carton:Paperboard with polyethylene lining serves multi-pack novelty and bulk ice cream. Retailers in Calgary and Edmonton prioritize shelf-efficient rectangular formats.
- Cone:Pre-filled sugar and waffle cones enable immediate consumption without additional serving ware.
- Cup:Single-serve polystyrene or paper cups anchor food service portion control.
Tub formats lead household purchasing frequency, with Carton gaining fastest in club channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns across North America trace divergent regulatory cost structures. FDA labeling mandates and state-level dairy commission requirements create compliance arbitrage between established processing corridors and emerging manufacturing zones.
United States
California's dairy processing corridor anchors non-dairy formulation scale as oat and coconut milk technologies achieve texture parity. The FDA's updated Nutrition Facts requirements for added sugars disclosure reshape reformulation priorities among mass-market producers. Wisconsin and New York processors decouple from seasonal cycles through year-round infrastructure investment.
Canada
Premium artisanal scoop shops concentrate in Toronto and Vancouver urban corridors with disproportionate margin capture. Health Canada and the Canadian Food Inspection Agency enforce bilingual labeling and dairy grading standards that extend product launch timelines. Calgary and Edmonton present underpenetrated whitespace for specialty frozen dessert expansion.
Mexico
Central Mexican dairy clusters supply cost-competitive milk fat to North American formulation networks. The national health regulator COFEPRIS aligns ingredient disclosure requirements with FDA frameworks to facilitate cross-border distribution. Guadalajara and Monterrey processing zones expand cold chain infrastructure for frozen novelty export.
North America Ice Cream Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue plant-based and precision fermentation alternatives. The market structures around three tiers: multinational scale players with frozen dessert infrastructure, regional dairy cooperatives with deep channel relationships, and artisanal specialists with experiential retail formats. Dominant competitive moves include portfolio diversification into non-dairy lines and strategic partnerships with ingredient technology providers.
Among North American-based operators, Blue Bell Creameries and Tillamook County Creamery Association represent the regional cooperative archetype with concentrated geographic channel control. Nestlé and Unilever occupy positions exemplifying multinational scale advantages in formulation R&D and year-round distribution network leverage. Wells Enterprises Inc. sits within the independent processor tier, demonstrating mid-scale operational flexibility without captive retail footprint dependency.
| Leading Market Players |
|---|
| Blue Bell Creameries |
| Nestlé |
| Froneri International Limited |
| Turkey Hill Dairy |
| General Mills |
| Wells Enterprises Inc. |
| Tillamook County Creamery Association |
| Baskin-Robbins |
| Unilever |
| Others |
Cost & Logistics Intelligence
Captive dairy processing infrastructure across Wisconsin, New York, and California anchors both supply security and margin control for North American ice cream producers. FDA labeling mandates for added sugars disclosure reshape procurement priorities as reformulation costs feed into premium tier positioning.
Pricing Analysis
Food service channel margins of 60-70% sustain premium artisanal pricing power in urban retail corridors. Three-tier pricing structure across premium, standard, and economy levels differentiates by milk fat content and certification grade. Price erosion runs through conventional retail tiers as private label volume expands. Supermarket buyers exhibit highest price sensitivity; experiential scoop shop consumers show lowest.
Supply Chain Analysis
Direct-to-food-service channels handle high-traffic metropolitan demand with specialized cold chain fleet requirements. Raw milk sourcing concentrates in Wisconsin, New York, and California dairy corridors. Butterfat, organic stabilizers, and flavor inclusions constitute critical input dependencies. Single-source vulnerability in organic dairy certification creates supply risk. Distribution runs through refrigerated logistics networks with last-mile frozen handling specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA added sugars disclosure mandates compound formulation investment requirements, creating regulatory-driven demand for clean-label sweetener technologies across the North American ice cream sector.
For Market Incumbents: Deploy precision fermentation partnerships to secure alternative protein supply before commodity cost spikes. Nestlé and Unilever demonstrate scale advantages in year-round distribution infrastructure; regional cooperatives must defend channel relationships through exclusive flavor development. Reformulation R&D spend protects shelf space against plant-based substitutes. For New Entrants and Emerging Players: Capture Calgary and Edmonton whitespace in Canadian specialty frozen dessert corridors. Direct-to-consumer subscription models bypass slotting fee barriers in saturated US retail. Food service distribution partnerships with urban mixed-use developers offer fastest path to margin-positive scale. For Investors and Strategic Acquirers: Roll-up economics work for regional artisanal scoop shop networks because cold chain capex intensity fragments independent expansion capability. Five-to-ten year viability hinges on FDA plant-based labeling resolution. Monitor Health Canada bilingual compliance timelines as inflection signal for Canadian market access costs.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Alternative dairy protein sourcing reduces butterfat cost volatility exposure. |
| Food Service Channel Expansion | Urban scoop shop formats capture 60-70% gross margins in Toronto corridors. |
| Clean-Label Reformulation Investment | Allulose and monk fruit systems meet FDA added sugars disclosure requirements. |
| Direct-to-Consumer Subscription Launch | Pint club models bypass supermarket slotting fees in Northeast specialty sector. |
| Canadian Geographic Expansion | Calgary and Edmonton present underpenetrated whitespace for premium artisanal formats. |
Research Approach
Multiple input streams — regulatory filing analysis, dairy processor production data, and retail audit records — were reconciled across primary interviews with formulation R&D directors, food service procurement managers, and cold chain logistics specialists. Secondary validation drew from FDA guidance documents, USDA dairy grading reports, Health Canada labeling standards, and Nielsen retail tracking data. Bottom-up volume modeling and top-down market sizing approaches were cross-referenced for triangulation.
Historical consumption patterns were cross-referenced against panel input from dairy cooperative executives and supermarket category buyers. Segmentation dimensions modeled include product type, distribution channel, flavor category, and packaging format across the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory milestone impacts. Forecast inputs incorporated California dairy corridor capacity expansion and oat milk processing technology adoption curves.
Underlying measurement precision varies by segment; food service channel estimates carry tighter precision than emerging direct-to-consumer subscription volumes. Forecasts reflect assumptions about FDA enforcement timelines and plant-based labeling dispute resolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Casual Marinated Products Market
Processed Foods
High Pressure Processing (HPP) for Rice and Grain Market
Processed Foods
Yogurt Dip Market
Processed Foods
United States Ice Cream Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
Global Pasta Market
Processed Foods
Shelf-Stable Soup Market
Processed Foods
Fresh Pasta Market
Processed Foods
Global Potato Flake Market
Processed Foods
Spreadable Fats Market
Processed Foods
Processed Eucheuma Seaweed Market
Processed Foods
Processed Superfruits Market
Processed Foods
Ice Cream Parlor Market
Processed Foods
Dairy Desserts Market
Processed Foods
Egg White Cubes Market
Processed Foods
Fermented Food and Drinks Market