
 Polypropylene Corrugated Packaging Market | 2026-2036
Polypropylene Corrugated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Polypropylene Corrugated Packaging Market Outlook
The direct-to-manufacturer supply channel is tilting away from disposable corrugated fiberboard toward returnable polypropylene systems in automotive and electronics logistics. Coroplast leverages its North American manufacturing footprint to dominate extruded sheet supply for reusable container fabrication. Primex Plastics Corporation anchors its position through deep extrusion capabilities and custom fabrication services for pharmaceutical cold-chain applications. Distriplast SAS competes aggressively across European automotive tier networks with standardized foldable container programs.
Polypropylene corrugated packaging consists of twin-wall extruded polypropylene sheets formed into rigid, lightweight structures with flute diameters typically ranging from 2 mm to 10 mm, delivering moisture resistance and impact protection across multiple use cycles. Its primary commercial purpose centers on replacing single-use fiberboard in closed-loop logistics, reducing per-trip packaging costs and waste generation in high-velocity supply chains. The boxes segment leads volume due to universal applicability across food, electronics, and automotive end users, while the reusable packaging type captures the fastest expansion as OEMs mandate returnable container programs. High-density grade formulations concentrate margin pools where load-bearing specifications for automotive powertrain components command premium pricing.
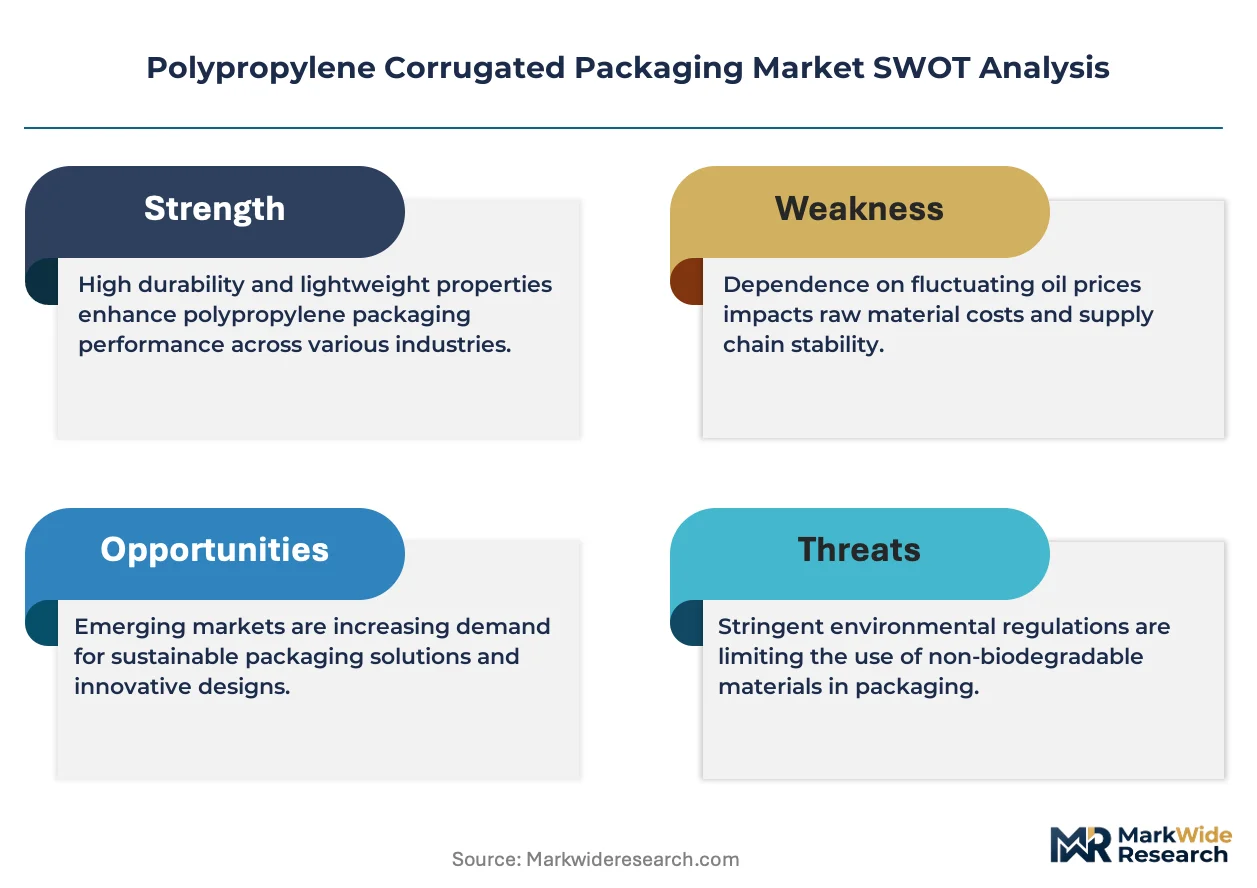
The EPA regulates volatile organic compound emissions from extrusion processes under Clean Air Act standards, while OSHA mandates workplace exposure limits for polypropylene processing fumes in US manufacturing facilities. REACH registration requirements in Europe restrict certain additive chemistries in polypropylene compounds, redirecting formulation strategies toward compliant stabilizer packages. Stakeholders must monitor evolving extended producer responsibility frameworks in multiple jurisdictions, as these programs will determine cost allocation between packaging manufacturers and end users for collection, sorting, and reprocessing infrastructure.
Market Dynamics
The automotive sector's standardization of returnable container pools is compressing demand cycles for disposable alternatives while concentrating procurement authority with tier-one logistics coordinators.
Growth Catalysts
- REACH compliance pressure:European converters are abandoning multi-material laminates in favor of recyclable polypropylene monostructures to satisfy ECHA registration requirements for circular packaging.
- Closed-loop automotive logistics:OEM assembly plants in Germany and the US Midwest are mandating reusable tote systems for powertrain component delivery, eliminating single-trip fiberboard from supplier contracts.
- Flute diameter standardization:The shift toward 4 mm and 6 mm standardized wall profiles is reducing custom tooling costs and accelerating container fabrication turnaround for electronics manufacturers.
Market Restraints
- Propylene feedstock volatility:Crude-linked naphtha cracking margins are transmitting price instability to extrusion-grade polypropylene resin, compressing converter margins during upstream spikes.
- Extrusion equipment concentration:High-output twin-screw extrusion lines are concentrated among a limited pool of machinery suppliers in Germany and Japan, creating capacity expansion bottlenecks.
- Fiberboard substitution resilience:Lightweight e-commerce shipments under 5 kg continue defaulting to recycled corrugated paper due to lower per-unit material cost and established recycling infrastructure.
Strategic Opportunities
- Pharmaceutical cold-chain expansion:Temperature-validated polypropylene shippers with integrated phase-change materials are penetrating vaccine distribution networks as thermal performance requirements tighten.
- India's PLI scheme alignment:Electronics manufacturing clusters in Tamil Nadu and Karnataka are qualifying local polypropylene container fabricators for component export logistics under production-linked incentive programs.
- RFID-embedded smart containers:Convergence of extruded sheet fabrication with printed electronics is enabling real-time location tracking for high-value automotive parts in transit.
Industry Challenges
- Multi-cycle fatigue testing:Validating container structural integrity beyond 50 use cycles requires capital-intensive accelerated aging protocols that smaller fabricators cannot fund.
- ERP integration complexity:Returnable container asset tracking demands API connectivity with customer warehouse management systems, stretching IT capabilities at mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polypropylene Corrugated Packaging Market |
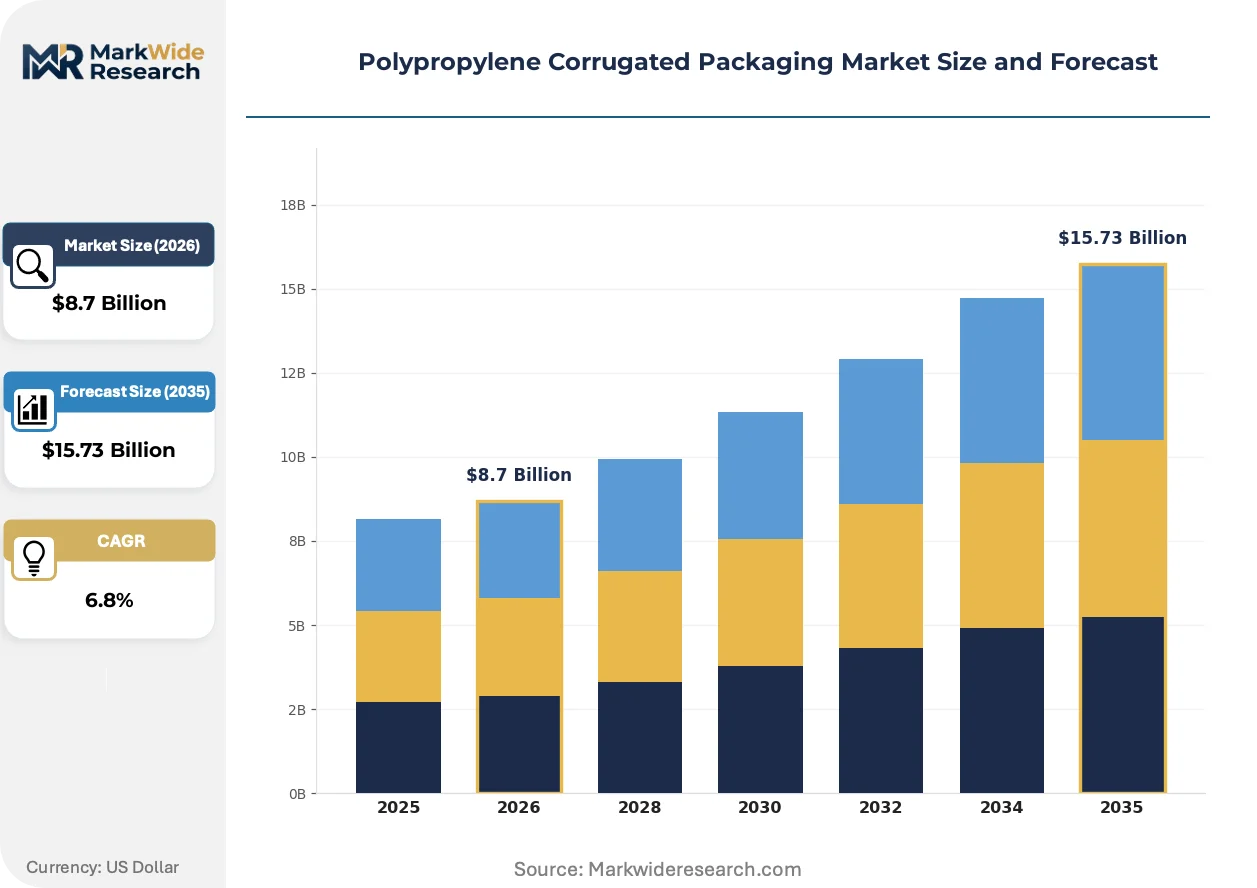
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Trays, Pallets, Sheets End User: Food & Beverage, Electronics, Pharmaceuticals, Automotive Packaging Type: Reusable, Disposable, Custom, Standard Grade: High-Density, Low-Density, Medium-Density, Others |
| Companies Covered | Coroplast, Primex Plastics Corporation, Distriplast SAS, Karton S.p.A., Twinplast Ltd., Shish Industries Ltd., Sangeeta Group, Zibo Kelida Plastic Co., Ltd., Technology Container Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polypropylene Corrugated Packaging Market Strategic Shifts
Extrusion technology advances and regulatory chemistry restrictions are simultaneously enabling performance upgrades and forcing material reformulation across the value chain.
Co-extruded barrier layers with ethylene-vinyl alcohol are rendering obsolete unmodified polypropylene in moisture-sensitive electronics applications. Semiconductor logistics providers in South Korea and Taiwan are specifying these structures for wafer cassette transport. The technology is compressing the addressable market for conventional extruded sheet in precision component packaging.
REACH Annex XVII restrictions on certain phthalate-based plasticizers are compelling reformulation of impact-modified grades for food-contact applications. European compounders are migrating to bio-based citrate ester alternatives at 15-30% additive cost premiums. Cold-chain food exporters in the Netherlands and Spain are absorbing these premiums to maintain EU market access.
Asset-pooling service contracts are displacing direct container purchases among mid-sized automotive suppliers. Third-party logistics operators in Stuttgart and Detroit are offering per-trip pricing with container maintenance bundled, transferring capex burden and residual value risk from parts manufacturers. This model is most advanced in German automotive tier networks where OEMs dictate packaging standards.
Polypropylene Corrugated Packaging Market Segmentation
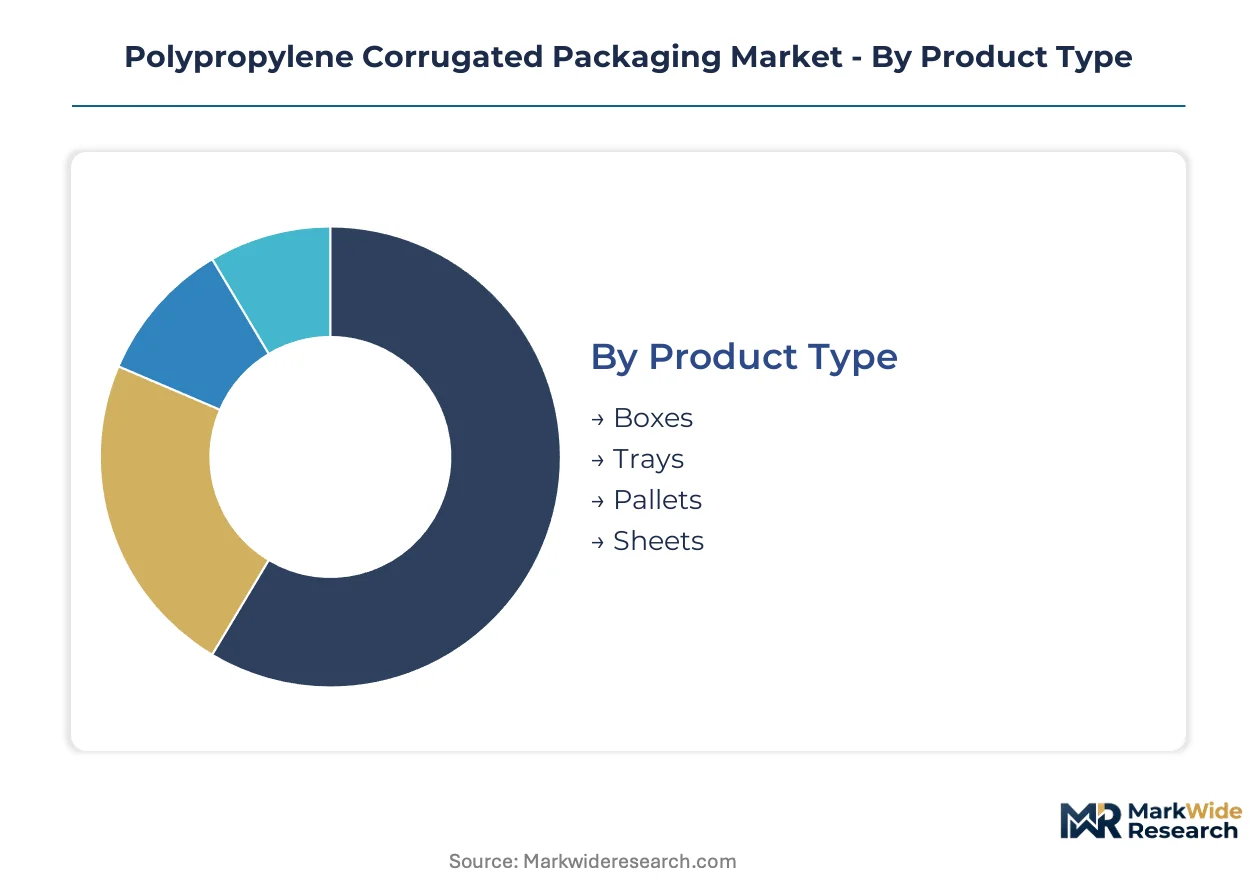
Segmentation in polypropylene corrugated packaging reveals divergent margin structures and technical requirements across product geometries and end-use specifications. Each category maps distinct investment priorities for extrusion capacity, formulation chemistry, and logistics integration.
Product Type:
Mature container geometries dominate procurement volumes while emerging formats capture specification upgrades in precision logistics.
- Boxes:Twin-wall extruded structures with flute diameters of 4 mm to 10 mm form the backbone of closed-loop automotive and electronics logistics. German OEM assembly plants in Stuttgart and Wolfsburg mandate standardized box footprints for powertrain component delivery, compressing demand for disposable alternatives.
- Trays:Shallow-depth configurations with integrated stacking features address semiconductor wafer cassette transport and pharmaceutical cold-chain dunnage. South Korean semiconductor logistics providers specify co-extruded barrier variants for moisture-sensitive precision components.
- Pallets:Rackable and nestable designs with reinforced perimeter profiles serve unit-load consolidation in retail distribution networks.
- Sheets:Raw extruded board supply feeds downstream container fabrication and point-of-purchase display manufacturing.
Boxes handle the majority of throughput; trays are expanding most quickly on share as precision component logistics tighten specifications.
End User:
Cost tier differentiation separates commodity food applications from premium-certified pharmaceutical and automotive segments.
- Food & Beverage:Cold-chain exporters in the Netherlands and Spain absorb 15-30% additive cost premiums for citrate ester plasticizers to satisfy REACH Annex XVII food-contact compliance.
- Electronics:Wafer cassette transport and component dunnage demand co-extruded ethylene-vinyl alcohol barrier layers that render unmodified polypropylene obsolete in moisture-sensitive applications.
- Pharmaceuticals:Temperature-validated shippers with integrated phase-change materials penetrate vaccine distribution networks as thermal performance requirements tighten.
- Automotive:OEM assembly plants in Detroit and the US Midwest mandate reusable tote systems for powertrain component delivery, eliminating single-trip fiberboard from supplier contracts.
Automotive commands the steepest margin pool; pharmaceuticals is climbing the fastest on specification intensity.
Packaging Type:
Volume concentration sits with established logistics models while customer type divergence splits procurement authority between asset owners and third-party operators.
- Reusable:Returnable container programs with 50-plus use cycle validation capture procurement concentration as tier-one logistics coordinators standardize pool management. Third-party operators in Stuttgart and Detroit offer per-trip pricing with maintenance bundled, transferring capex burden from parts manufacturers.
- Disposable:Single-trip applications persist in lightweight e-commerce shipments under 5 kg where recycled corrugated paper retains cost advantage.
- Custom:Tooling-intensive designs with proprietary footprints serve captive automotive tier networks with OEM-mandated specifications.
- Standard:Off-the-shelf dimensions reduce lead times for mid-sized electronics manufacturers without dedicated packaging engineering resources.
Reusable formats command the dominant share of value; custom specifications are gaining share fastest through OEM standardization mandates.
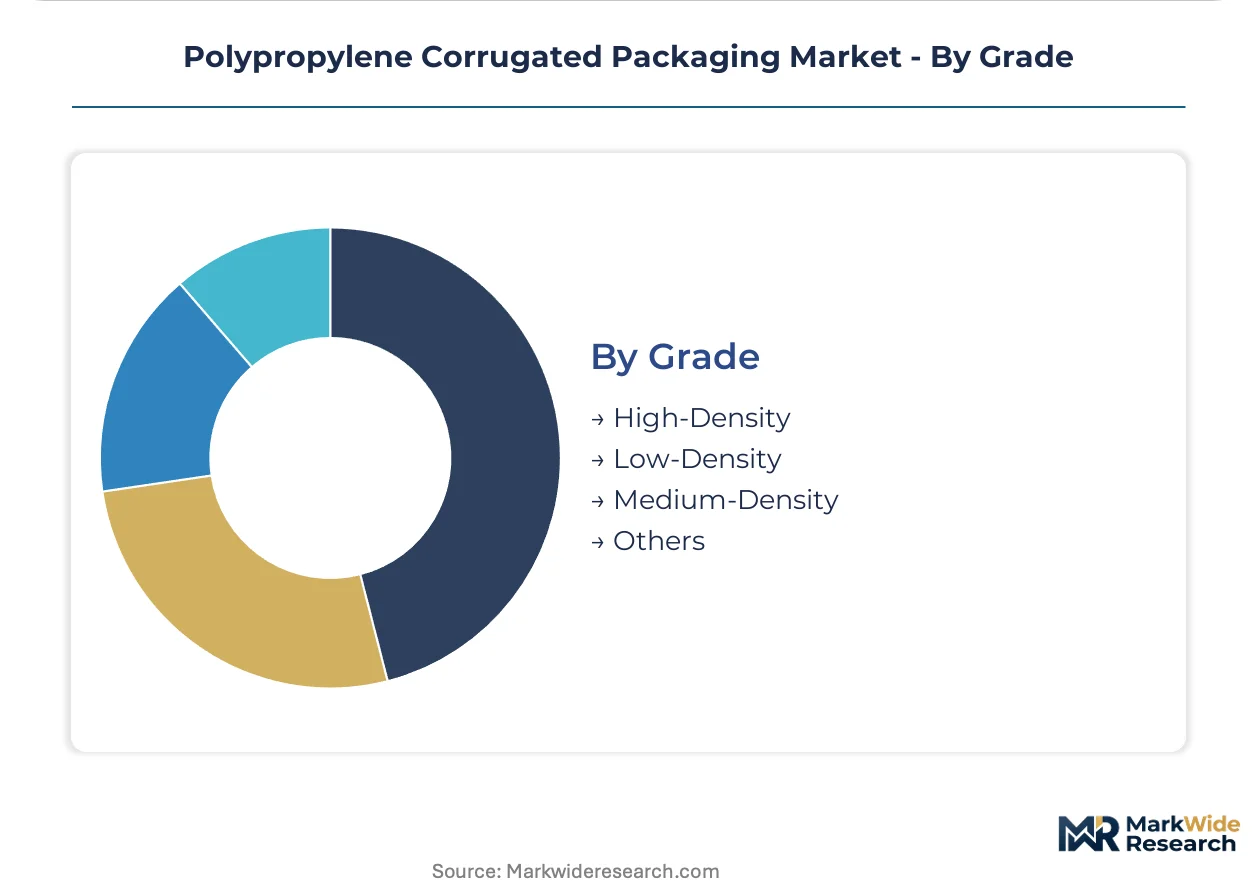
Grade:
Margin concentration aligns with load-bearing specifications in heavy-component logistics.
- High-Density:Formulations with elevated crystallinity and enhanced stiffness serve automotive powertrain component dunnage where compression resistance commands premium pricing.
- Medium-Density:Balanced impact resistance and weight characteristics address general-purpose electronics and food distribution applications.
- Low-Density:Lightweight grades with expanded cellular structures reduce per-trip shipping costs for low-stress consumer goods logistics.
- Others:Specialty compounded grades with UV stabilizers or conductive additives serve niche outdoor and electrostatic-sensitive applications.
High-density grades concentrate margin pools; medium-density formulations move the greatest physical volume across end-use segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput infrastructure underwrites the Netherlands' central role in European reusable packaging logistics, while the Rhine-Main-Danube waterway network connects German automotive clusters to downstream fabrication capacity.
United States
Automotive OEM assembly plants in Detroit and the US Midwest mandate reusable tote systems for powertrain component delivery, eliminating single-trip fiberboard from supplier contracts. EPA Clean Air Act standards regulate volatile organic compound emissions from extrusion processes, redirecting capital toward emission-control upgrades. Chicago-area logistics coordinators concentrate procurement authority for returnable container pools serving tier-one automotive networks.
Germany
OEM assembly plants in Stuttgart and Wolfsburg standardize box footprints for powertrain component delivery, compressing demand for disposable alternatives. REACH registration requirements restrict certain additive chemistries in polypropylene compounds, compelling reformulation toward compliant stabilizer packages. Stuttgart-based third-party logistics operators offer per-trip pricing with container maintenance bundled, transferring capex burden from parts manufacturers.
China
Electronics manufacturing clusters in the Yangtze River Delta and Pearl River Delta demand co-extruded barrier layers for moisture-sensitive semiconductor component transport. GB standards and MIIT regulations govern food-contact polypropylene formulations for cold-chain export applications. Shenzhen-based fabricators supply standardized foldable containers for consumer electronics export logistics.
South Korea
Semiconductor logistics providers specify co-extruded ethylene-vinyl alcohol barrier structures for wafer cassette transport, rendering unmodified polypropylene obsolete in precision applications. MFDS pharmaceutical packaging regulations drive temperature-validated shipper specifications for vaccine distribution networks. Busan-Ulsan industrial corridors concentrate extrusion capacity serving display panel and memory chip manufacturers.
India
Electronics manufacturing clusters in Tamil Nadu and Karnataka qualify local container fabricators for component export logistics under PLI scheme production-linked incentive programs. BIS standards govern polypropylene grades for food-contact applications in cold-chain distribution. Chennai-area fabricators expand extrusion capacity to serve smartphone and component assembly operations.
Polypropylene Corrugated Packaging Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in extruded sheet supply. The market structures around a concentrated upstream layer of twin-screw extrusion equipment operators and a fragmented downstream of container fabricators and logistics integrators. Two archetypes dominate: integrated extrusion-to-fabrication operators with captive resin conversion, and asset-pooling service providers offering per-trip pricing with maintenance bundled. Competitive moves concentrate on geographic expansion through distribution partnerships and capacity expansion via high-output extrusion line installation.
Among North American integrated operators, Coroplast and Primex Plastics Corporation occupy positions anchoring extruded sheet supply for reusable container fabrication. Distriplast SAS represents the European platform archetype, sitting within automotive tier networks with standardized foldable container programs. These three exemplify the geographic segmentation of procurement authority, with each anchoring regional supply relationships rather than competing directly across borders.
| Leading Market Players |
|---|
| Coroplast |
| Primex Plastics Corporation |
| Distriplast SAS |
| Karton S.p.A. |
| Twinplast Ltd. |
| Shish Industries Ltd. |
| Sangeeta Group |
| Zibo Kelida Plastic Co., Ltd. |
| Technology Container Corp. |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Main-Danube waterway corridor links German automotive clusters to extrusion capacity in Central Europe, and its freight cost volatility feeds directly into container pricing tiers while concentrating procurement leverage with Stuttgart-based logistics coordinators who manage pooled asset networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates high-density automotive grades certified for powertrain dunnage from medium-density electronics formats and low-density consumer goods variants. Price differentiation rests on load-bearing certification tier and volume commitment scale, with tier-one automotive suppliers locking multi-year contracts. Cost compression in standard grades is intensifying because propylene feedstock volatility transmits naphtha-cracking margin swings to converter pricing. Small electronics fabricators exhibit highest price sensitivity; pharmaceutical cold-chain operators absorb premium additives with minimal negotiation.
Supply Chain Analysis
Export-control restrictions on semiconductor manufacturing equipment limit barrier-layer co-extrusion technology transfers to South Korean and Taiwanese precision logistics providers. Geographic supply concentrates in Germany, China, and the United States, with twin-screw extrusion equipment anchored in German and Japanese machinery suppliers. Raw material flows draw from naphtha crackers in the US Gulf Coast and Middle Eastern propylene export hubs. Single-source vulnerability sits with concentrated machinery suppliers creating capacity expansion bottlenecks. Distribution runs through third-party logistics operators offering per-trip container pricing with maintenance bundled.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-loop automotive logistics mandates from OEMs in Stuttgart and Detroit represent a regulatory-technology inflection compressing disposable packaging demand while expanding returnable container service contracts.
For Market Incumbents: Entrench position through captive extrusion capacity in the US Midwest and Germany's automotive corridor, locking tier-one supplier relationships before asset-pooling operators consolidate procurement authority. Prioritize REACH-compliant stabilizer package R&D to preempt formulation obsolescence as ECHA restrictions tighten on phthalate-based additives.
For New Entrants and Emerging Players: Pursue qualification under India's PLI scheme for electronics manufacturing clusters in Tamil Nadu and Karnataka, where local fabrication capacity lags behind component assembly growth. Target pharmaceutical cold-chain validation services as the most penetrable premium segment, leveraging temperature-shipper specifications from MFDS and FDA pathways as entry credentials.
For Investors and Strategic Acquirers: Regional extrusion-to-fabrication operators with established automotive tier relationships present the most defensible acquisition profile for long-term positioning across the analysis window. Monitor standardization mandates from German OEMs as the critical signal for when pooled container asset models achieve irreversible procurement dominance over direct purchase structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | High-output twin-screw extrusion lines in Germany and Japan relieve machinery bottlenecks serving automotive tier networks. |
| Backward Integration | Captive polypropylene resin conversion insulates converter margins from naphtha-cracking volatility in Gulf Coast feedstock markets. |
| REACH Compliance Reformulation | Citrate ester stabilizer packages maintain EU market access for food-contact applications at 15-30% additive cost premiums. |
| Asset-Pooling Service Contracts | Per-trip pricing with maintenance bundled transfers capex burden from mid-sized automotive suppliers to third-party operators. |
| RFID-Printed Electronics Convergence | Real-time location tracking integration captures specification upgrades for high-value automotive parts in transit. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including extrusion plant managers, automotive tier-one procurement leads, pharmaceutical cold-chain logistics coordinators, and third-party pooling service operators. Secondary validation drew from customs and trade flow databases, ECHA REACH registration filings, EPA Clean Air Act enforcement records, and automotive OEM packaging standard disclosures. Bottom-up container fabrication capacity estimates and top-down end-use demand projections were triangulated to anchor volume and value outputs.
Calibration against historical resin price cycles and automotive production volatility shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product geometry, end-use industry, packaging type, and density grade tier. CAGRs were derived from elasticity-adjusted demand curves incorporating OEM standardization mandate timelines and regulatory compliance phase-in schedules. Feedstock cost pass-through coefficients and extrusion equipment lead times served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in propylene-naphtha cracking spreads or automotive assembly plant utilization would shift the trajectory. Forecasts reflect documented assumptions regarding REACH Annex XVII enforcement intensity and PLI scheme continuation for Indian electronics manufacturing. Material shifts in OEM reusable container mandate scope or ECHA additive restriction expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
US Plastic Packaging Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market
Plastic Packaging
Banding Stretch Film Market
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
Reusable Plastic Water Bottles Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
South America Polyethylene Terephthalate (PET) Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
Morocco Plastic Bottles Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
GCC PET Packaging Market
Plastic Packaging
MDPE Bottles Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market
Plastic Packaging
Plastic Ready Meal Trays Market
Plastic Packaging
North America Single-Use Plastic Packaging Market
Plastic Packaging
Plastic Jar Packaging Market