
 Rewritable PVC Cards Market | 2026-2036
Rewritable PVC Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Rewritable PVC Cards Market Analytics
Corporate offices is bifurcating from educational institutions as the dominant buyer archetype for rewritable PVC cards, driven by hybrid workplace credentialing and sustainability procurement mandates. Zebra Technologies leverages its thermal-retransfer expertise to dominate enterprise-scale deployments across North America and Europe. Evolis anchors the mid-market through compact desktop systems that specialize in on-demand personalization for SMEs. HID Global extends its access-control ecosystem by integrating rewritable credentials into its physical identity platform.
Rewritable PVC cards are thermoplastic substrates coated with reversible thermal-sensitive layers that enable erasure and reprinting through heat cycles without card replacement, typically rated for hundreds of rewrite operations. These cards serve commercial applications requiring frequent data updates such as temporary access badges, reusable gift programs, and dynamic loyalty credentials. Standard cards occupy the largest volume position due to universal compatibility with existing thermal printers, while loyalty cards capture expanding margin pools as retailers seek to eliminate disposable plastic waste. Access control applications lead technology integration with contactless chip embedding, whereas retail services represent the fastest structural expansion as point-of-sale systems adopt rewrite-capable terminals.
FDA guidelines on material safety in healthcare-adjacent environments, REACH compliance requirements for chemical substances in EU-manufactured cards, and ISO/IEC 7810 dimensional standards collectively shape product specifications and cross-border market access. The EU Green Deal's circular-economy directives are tightening restrictions on virgin PVC consumption, forcing manufacturers toward recycled-content formulations or alternative thermoplastics. Stakeholders must monitor regulatory divergence between European chemical restrictions and North American material safety frameworks when configuring regional supply chains and product portfolios.
Market Dynamics
The EU Green Deal's circular-economy mandates are forcing manufacturers to abandon virgin PVC formulations, creating a supply-side pivot toward recycled-content thermoplastics and bio-based alternatives that rewrites procurement criteria across enterprise credentialing programs.
Growth Catalysts
- REACH chemical compliance:The EU's substance restrictions on phthalates and heavy metals in plastic cards are accelerating demand for reformulated rewritable substrates that meet ECHA safety thresholds without performance degradation.
- Smart building automation:Commercial real estate operators in Germany are deploying rewritable badges for hot-desking and visitor management, driving volume procurement from facility management integrators.
- Contactless chip embedding:RFID and NFC integration into rewritable PVC substrates is enabling dynamic access credential updates without physical card replacement, expanding addressable use cases beyond static identification.
Market Restraints
- Petrochemical input volatility:Crude oil price fluctuations directly impact PVC resin costs, compressing margins for card manufacturers locked into annual enterprise supply contracts.
- Thermal printer hardware concentration:Dependency on Japanese and German thermal printhead suppliers creates single-source vulnerability for rewritable card system deployers.
- Digital credential substitution:Smartphone-based mobile access solutions from Apple Wallet and Google Wallet are eroding physical card demand in premium commercial segments.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Domestic production incentives are attracting card printer assembly operations, creating localized supply hubs for South Asian credentialing markets.
- Reusable retail gift programs:Supermarket chains are piloting reloadable rewritable cards to eliminate single-use plastic waste, opening volume contracts previously served by disposable substrates.
- ISO/IEC 7810-4 rewrite durability standards:Emerging international certification for multi-cycle card performance is creating premium tier differentiation for manufacturers achieving 500+ rewrite ratings.
Industry Challenges
- Color stability engineering:Achieving consistent thermal retransfer image quality across hundreds of erase-print cycles requires materials science expertise that outpaces current workforce training pipelines.
- Legacy access control integration:Rewritable cards must maintain backward compatibility with installed HID and LenelS2 reader infrastructures, constraining chip architecture choices and certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rewritable PVC Cards Market |
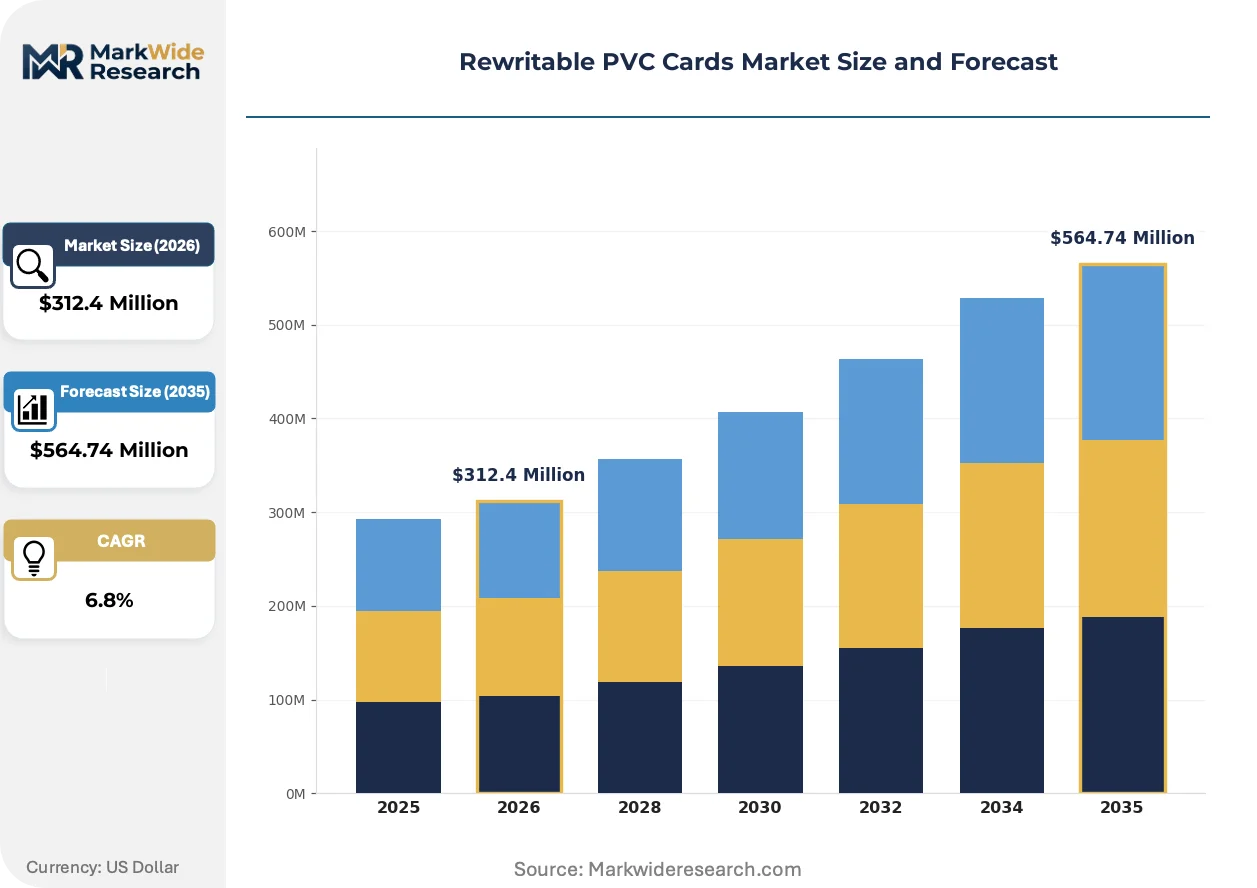
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cards, Keycards, Loyalty Cards, Gift Cards Application: Access Control, Event Management, Membership Programs, Retail Services End User: Corporate Offices, Educational Institutions, Hospitals, Retail Outlets Distribution Channel: Online Retailers, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Zebra Technologies, Entrust Datacard, AlphaCard, Evolis, NXP Semiconductors, ID Card Group, HID Global, CPI Card Group, SMART ONE Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rewritable PVC Cards Market Evolving Landscape
Thermal-retransfer printing precision is advancing rewrite resolution beyond 300 dpi, enabling photo-quality imagery that expands rewritable cards into premium hospitality and corporate branding applications previously reserved for lithographed substrates.
Polylactic acid (PLA) bio-based substrates are supplanting conventional petroleum-derived PVC in European credentialing programs. Retailers in France and the Netherlands are mandating PLA content thresholds in supplier RFPs. This material transition is compressing the addressable market for virgin PVC card manufacturers while opening formulation partnerships between biopolymer producers and thermal coating specialists.
REACH Annex XVII restrictions on short-chain chlorinated paraffins are compelling coating reformulations across EU-manufactured rewritable cards. The chemical substitution timeline is accelerating R&D budgets at substrate producers. Germany's KBA and France's ANSM are coordinating enforcement, with industrial credentialing programs facing the steepest compliance verification requirements.
Enterprise buyers are consolidating vendor relationships around full-stack credentialing platforms rather than discrete card supply contracts. Facility managers are bundling card procurement with printer leasing and cloud-based template management. This bundling behavior is most pronounced in North American corporate campuses, where procurement teams prioritize single-source accountability over component cost optimization.
Rewritable PVC Cards Market Segmentation
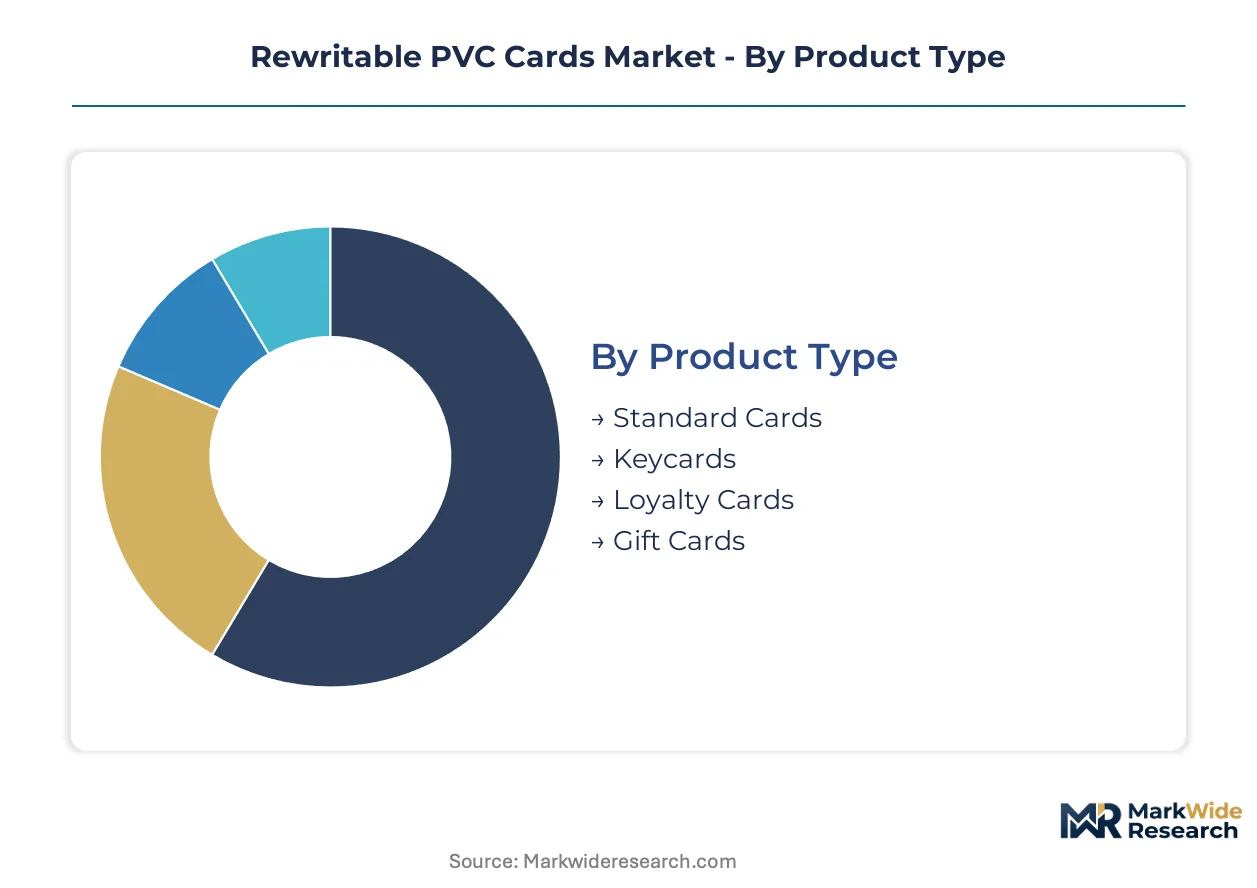
Rewritable PVC card procurement patterns diverge sharply across deployment contexts, with thermal printer compatibility and rewrite cycle ratings determining segment viability. Manufacturers configure substrate formulations and chip architectures differently for each use case, creating distinct margin profiles and certification requirements.
Product Type:
Standard cards dominate domestic manufacturing footprints across Germany and France, while specialty formats concentrate in export-oriented production hubs serving North American and Asian markets.
- Standard Cards:Universal thermal printer compatibility positions these as the volume foundation, with substrates engineered for 300+ rewrite cycles. German industrial automation buyers specify these for visitor badge programs requiring frequent data refresh without card replacement.
- Loyalty Cards:Retailers in France and the Netherlands mandate bio-based PLA content thresholds, compressing margins for virgin PVC suppliers while opening formulation partnerships. These cards carry the highest rewrite durability specifications as supermarkets pilot reloadable programs to eliminate single-use plastic waste.
- Keycards:RFID embedding requirements from HID and LenelS2 reader infrastructures constrain chip architecture choices.
- Gift Cards:Seasonal demand volatility from North American retail chains creates inventory management complexity.
Standard cards command the established base. The steepest expansion runs through loyalty cards.
Application:
Access control deployments concentrate procurement spend in facility management integrators, while retail services fragment demand across independent point-of-sale terminal operators.
- Access Control:Commercial real estate operators in Germany deploy these for hot-desking and visitor management, with contactless chip embedding enabling dynamic credential updates. ECHA REACH compliance on phthalate content adds substrate certification costs.
- Retail Services:Point-of-sale system upgrades across French supermarket chains are driving rewrite-capable terminal adoption. This segment captures expanding margin pools as disposable plastic elimination becomes a procurement mandate.
- Event Management:Temporary credentialing for trade shows and conferences requires rapid-turn personalization capabilities.
- Membership Programs:Fitness chains and coworking spaces specify mid-cycle durability ratings for monthly data refresh.
Access control anchors procurement volume. Retail services are gaining share fastest.
End User:
Corporate offices consolidate vendor relationships around full-stack platforms, while educational institutions and hospitals fragment procurement across departmental budgets.
- Corporate Offices:Hybrid workplace credentialing and sustainability procurement mandates are bifurcating this segment from educational buyers. Facility managers bundle card supply with printer leasing and cloud-based template management, prioritizing single-source accountability.
- Educational Institutions:Campus-wide access systems require backward compatibility with legacy reader infrastructures, constraining chip architecture choices and extending certification timelines.
- Hospitals:FDA material safety guidelines for healthcare-adjacent environments shape substrate specifications.
- Retail Outlets:Franchise networks create distributed procurement patterns with limited standardization.
Corporate offices concentrate the premium tier. Educational institutions present the most complex integration requirements.
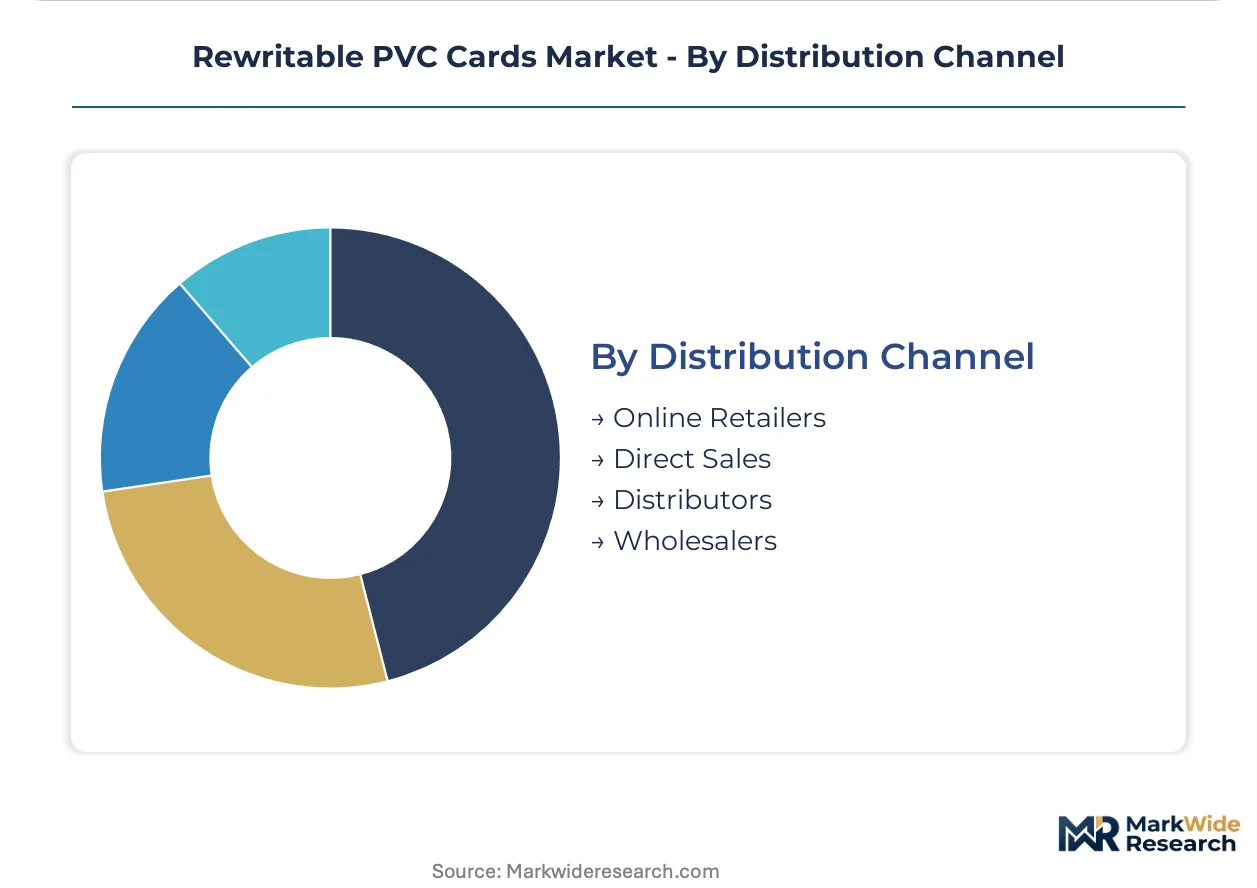
Distribution Channel:
Direct sales relationships dominate enterprise-scale deployments, while online retailers capture SME demand for desktop printer systems.
- Direct Sales:Annual supply contracts with facility management integrators lock in volume commitments. These relationships compress working capital flexibility for manufacturers facing petrochemical input volatility.
- Distributors:Regional stocking requirements in Germany and France create inventory carrying costs.
- Online Retailers:Compact desktop system sales to SMEs concentrate in North American markets.
- Wholesalers:Generic card supply for non-branded applications faces price pressure from Asian imports.
Direct sales secure the anchor accounts. Online retailers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cargo throughput underwrites European supply chain integration for rewritable PVC card substrates, while the Trans-Siberian Railway connects Asian resin suppliers to German manufacturing clusters.
Germany
Industrial automation buyers in Bavaria and Baden-Württemberg specify rewritable badges for visitor management and hot-desking programs. ECHA REACH Annex XVII restrictions on phthalates and heavy metals compel substrate reformulations. The Frankfurt-Rhine-Main metropolitan area concentrates facility management integrators bundling card procurement with cloud-based template platforms.
France
French supermarket chains in the Île-de-France and Auvergne-Rhône-Alpes regions mandate bio-based PLA content thresholds in supplier RFPs. ANSM coordinates with Germany's KBA on enforcement of short-chain chlorinated paraffin restrictions. The Lyon-Grenoble industrial corridor hosts thermal coating specialists partnering with biopolymer producers.
United States
Corporate campuses in California and Texas consolidate vendor relationships around full-stack credentialing platforms bundling printer leasing and template management. FDA material safety guidelines shape substrate specifications for healthcare-adjacent deployments. The Dallas-Fort Worth metroplex anchors North American distribution for enterprise-scale card supply contracts.
India
The PLI scheme for electronics manufacturing attracts card printer assembly operations to Gujarat and Karnataka, creating localized supply hubs for South Asian credentialing markets. BIS standards on plastic materials intersect with state-level sustainability procurement mandates. The Mumbai-Pune industrial corridor concentrates mid-market desktop system demand from SME facility operators.
Netherlands
Retailers in the Randstad region pilot reloadable rewritable gift programs to eliminate single-use plastic waste, opening volume contracts previously served by disposable substrates. EU Green Deal circular-economy directives tighten restrictions on virgin PVC consumption. The Eindhoven high-tech cluster drives thermal-retransfer printing precision advances for photo-quality imagery applications.
Rewritable PVC Cards Market Competitive Landscape
Listed leaders compete with private specialists across thermal printing expertise and substrate formulation capabilities. The vendor base organizes into three tiers: enterprise-scale platform providers, mid-market desktop system specialists, and regional substrate fabricators. Strategic differentiation runs through thermal-retransfer resolution ratings, rewrite cycle durability certifications, and full-stack credentialing platform bundling. Capacity expansion in Indian assembly operations and formulation partnerships for bio-based alternatives represent dominant competitive vectors.
Among North American-listed technology providers, Zebra Technologies and HID Global exemplify the enterprise-scale platform archetype, while France-based Evolis S.A. anchors the mid-market desktop specialization tier. Zebra Technologies represents thermal-retransfer expertise dominance across enterprise deployments. HID Global exemplifies access-control ecosystem extension through physical identity platform integration. Evolis occupies the compact desktop system position serving SME on-demand personalization requirements. These three companies illustrate the geographic and capability stratification defining competitive positioning.
| Leading Market Players |
|---|
| Zebra Technologies |
| Entrust Datacard |
| AlphaCard |
| Evolis |
| NXP Semiconductors |
| ID Card Group |
| HID Global |
| CPI Card Group |
| SMART ONE Technology |
| Others |
Value Network & Pricing Analysis
ISO/IEC 7810-4 rewrite durability certification gates supplier qualification while simultaneously stratifying price tiers across enterprise credentialing programs, compressing margins for uncertified substrate fabricators and creating premium capture opportunities for manufacturers achieving 500+ cycle ratings. Buyers in Germany and France now bundle card procurement with printer leasing and cloud template management, shifting price negotiation leverage toward full-stack platform providers and away from component suppliers.
Pricing Analysis
Volume-discount tiering structures dominate enterprise supply contracts, with annual commitments from facility management integrators locking in preferential rates for standard card substrates while specialty PLA formulations command premium-mid-economy pricing differentiation based on bio-content thresholds. Price differentiation hinges on rewrite cycle certification tier and thermal-retransfer resolution ratings, with photo-quality 300+ dpi capabilities capturing branding premiums from hospitality deployers. Cost compression in virgin PVC substrates is intensifying because EU Green Deal circular-economy mandates are forcing formulation switches to recycled-content thermoplastics. Educational institutions exhibit highest price sensitivity due to fragmented departmental procurement budgets, whereas corporate offices prioritize single-source accountability over unit cost optimization.
Supply Chain Analysis
Germany and France anchor European substrate manufacturing, with the Lyon-Grenoble corridor hosting thermal coating specialists and Bavarian industrial clusters producing standard card formulations for visitor management programs. Raw material flows draw from petrochemical resin suppliers, Japanese and German thermal printhead manufacturers, and biopolymer producers developing PLA alternatives. Single-source vulnerability concentrates in thermal printhead supply from Japanese precision component makers, creating chokepoint exposure for card printer assembly operations. Distribution runs through direct sales relationships with facility management integrators, with regional distributors in Germany and France carrying inventory for SME desktop system demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity runs through sustainability-driven procurement bifurcation, as corporate offices consolidate around full-stack platforms while educational institutions and retail chains fragment across competing credentialing standards, creating niche entry points for specialized substrate formulators and regional system integrators.
For Market Incumbents: Consolidate backward integration into thermal coating formulation capabilities to defend margin position against bio-based substrate disruptors, while expanding captive supply of PLA-content cards to capture French and Dutch retailer RFP mandates. Prioritize ISO/IEC 7810-4 certification investment to maintain pricing power as enterprise buyers consolidate vendor relationships around durability-verified suppliers.
For New Entrants and Emerging Players: CE marking fast-track for REACH-compliant PLA formulations opens white-space penetration in European retail services, where supermarket chains seek reloadable gift program suppliers with verified chemical safety documentation. India's PLI scheme for electronics manufacturing presents the most penetrable geography for card printer assembly localization, with go-to-market execution through partnerships with Gujarat and Karnataka state-level facility management integrators.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across bio-based substrate formulation, as R&D spend on PLA thermal coating compatibility exceeds legacy PVC process economics. Acquisition targets should prioritize thermal-retransfer coating specialists with existing biopolymer partnerships, with signal concentration in ECHA enforcement coordination between Germany's KBA and France's ANSM as inflection indicator for compliance-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Coating Formulation | German manufacturers capture margin pools from Japanese printhead suppliers through in-house substrate engineering. |
| Bio-Based Substrate Certification Program | French retailers mandate PLA content thresholds, creating premium tier differentiation for compliant suppliers. |
| Full-Stack Platform Bundling | Corporate offices in Texas and California prioritize single-source accountability combining printer leasing with cloud template management. |
| Geographic Manufacturing Footprint Expansion | India's PLI scheme attracts card printer assembly to Gujarat, creating localized supply hubs for South Asian credentialing markets. |
| Regulatory Compliance Fast-Track | REACH Annex XVII reformulation timelines compress competitive windows for coating specialists achieving ECHA safety thresholds. |
Research Methodology
A spread of perspectives from facility management integrators, thermal printer OEM procurement leads, substrate R&D directors, and retail sustainability officers converged on the working assumptions shaping demand trajectories. Primary fieldwork combined structured interviews with secondary validation through ECHA regulatory filings, EU Green Deal directive documentation, SEC disclosures from listed technology providers, and customs data on PVC resin trade flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include product type, application context, end-user archetype, and distribution channel structure, with thermal-retransfer resolution ratings and rewrite cycle durability specifications as industry-specific performance tiers. CAGRs were derived from installed base growth rates for rewrite-capable terminals, enterprise credentialing program expansion, and regulatory compliance-driven replacement cycles. Forecast inputs incorporated petrochemical price volatility indices and smart building automation deployment data from German commercial real estate operators.
Underlying assumptions cover sustained EU circular-economy enforcement, thermal printhead supply continuity, and corporate hybrid workplace permanence, with deviation risk concentrated in digital credential substitution from mobile wallet platforms and REACH chemical restriction scope expansion. Recalibration cycles align with material shifts in ECHA Annex XVII enforcement coordination and PLA substrate performance validation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Saudi Arabia Plastic Bottles Market
Plastic Packaging
HDPE Jug Market
Plastic Packaging
United States PET Packaging Market
Plastic Packaging
Blow Molded Plastics Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
South America Polyethylene Terephthalate (PET) Market
Plastic Packaging
PCR Plastic Packaging Market
Plastic Packaging
Plastic Ready Meal Trays Market
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
Thermoforming Plastic Market
Plastic Packaging
Cast Films Market
Plastic Packaging
Mushroom Plastics Market
Plastic Packaging
Europe PET Packaging Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market