
 Plastic Lab Totes Market | 2026-2036
Plastic Lab Totes Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Lab Totes Market Analytics
Multi-source procurement toward captive manufacturing is consolidating among large laboratory supply distributors. Thermo Fisher Scientific leverages its vertically integrated plastics molding network to control resin specifications and lot traceability across clinical and research channels. Nasco anchors its position through specialized biohazard and cold-chain configurations purpose-built for CDC-compliant specimen transport protocols. Corning Incorporated differentiates via precision-engineered polypropylene formulations that meet autoclave cycling requirements in high-throughput diagnostic labs.
Plastic lab totes are rigid or semi-rigid containers molded from autoclavable polymers, typically polypropylene or high-density polyethylene, designed for sterile transport, storage, and waste containment of laboratory specimens, reagents, and cultured materials. Wall thicknesses range from 2 mm to 6 mm with gasket-sealed lids rated for liquid-tight integrity per DOT and IATA biological substance shipping guidelines. Standard totes dominate volume shipments for general laboratory storage, while insulated totes command premium positioning in pharmaceutical cold-chain logistics where temperature excursion tolerance sits within 2°C to 8°C ranges. Biohazard totes sustain above-average growth rates as clinical laboratories expand molecular diagnostics and infectious disease testing workflows requiring UN-certified packaging.
The US FDA enforces medical device and biological product transport validation standards that directly shape tote design specifications for pharmaceutical and clinical end users. OSHA's Bloodborne Pathogens Standard mandates puncture-resistant, leak-proof secondary containment, reinforcing demand for biohazard-rated polypropylene constructions with integrated absorbent liners. Stakeholders must monitor evolving EPA guidance on medical plastics recycling streams and state-level extended producer responsibility frameworks that could reshape material selection and end-of-life economics for single-use laboratory containers.
Market Dynamics
Consolidation among laboratory supply distributors is compressing procurement channels, forcing manufacturers to secure direct relationships with pharmaceutical cold-chain operators and diagnostic networks to maintain margin control.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard:Mandates for puncture-resistant secondary containment drive replacement cycles in clinical laboratories upgrading to UN-certified biohazard-rated polypropylene constructions with integrated absorbent liners.
- Molecular diagnostics expansion:Infectious disease testing workflows at contract research organizations in Germany require CDC-compliant specimen transport protocols, accelerating demand for validated cold-chain configurations.
- Autoclave cycling durability:High-throughput diagnostic labs prioritize precision-engineered polypropylene formulations that withstand repeated sterilization without dimensional degradation.
Market Restraints
- Resin specification volatility:Medical-grade polypropylene and high-density polyethylene feedstock costs fluctuate with petrochemical pricing, compressing margins for molded container producers without captive resin supply.
- Single-use plastics scrutiny:EPA guidance on medical plastics recycling streams and emerging state-level extended producer responsibility frameworks threaten end-of-life economics for disposable laboratory containers.
- Silicone gasket substitution:Alternative sealing technologies in reusable metal transport cases compete for premium pharmaceutical logistics applications requiring liquid-tight integrity.
Strategic Opportunities
- India's diagnostic infrastructure:CDSCO regulatory alignment with international cold-chain standards creates entry pathways for biohazard-rated container suppliers serving the country's expanding molecular testing capacity.
- Smart temperature logging convergence:Integration of IoT sensors with insulated tote designs enables real-time excursion monitoring for pharmaceutical distributors seeking 2°C to 8°C compliance documentation.
- EU Green Deal material innovation:Bio-based polypropylene formulations certified under REACH-compliant frameworks attract sustainability-focused procurement at European contract research organizations.
Industry Challenges
- DOT and IATA certification timelines:Biological substance shipping validation for UN-certified packaging requires 12-18 month testing protocols, delaying product launches for redesigned tote geometries.
- Lot traceability system integration:Pharmaceutical cold-chain operators demand resin specification documentation compatible with existing enterprise resource planning platforms, forcing middleware development investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Lab Totes Market |
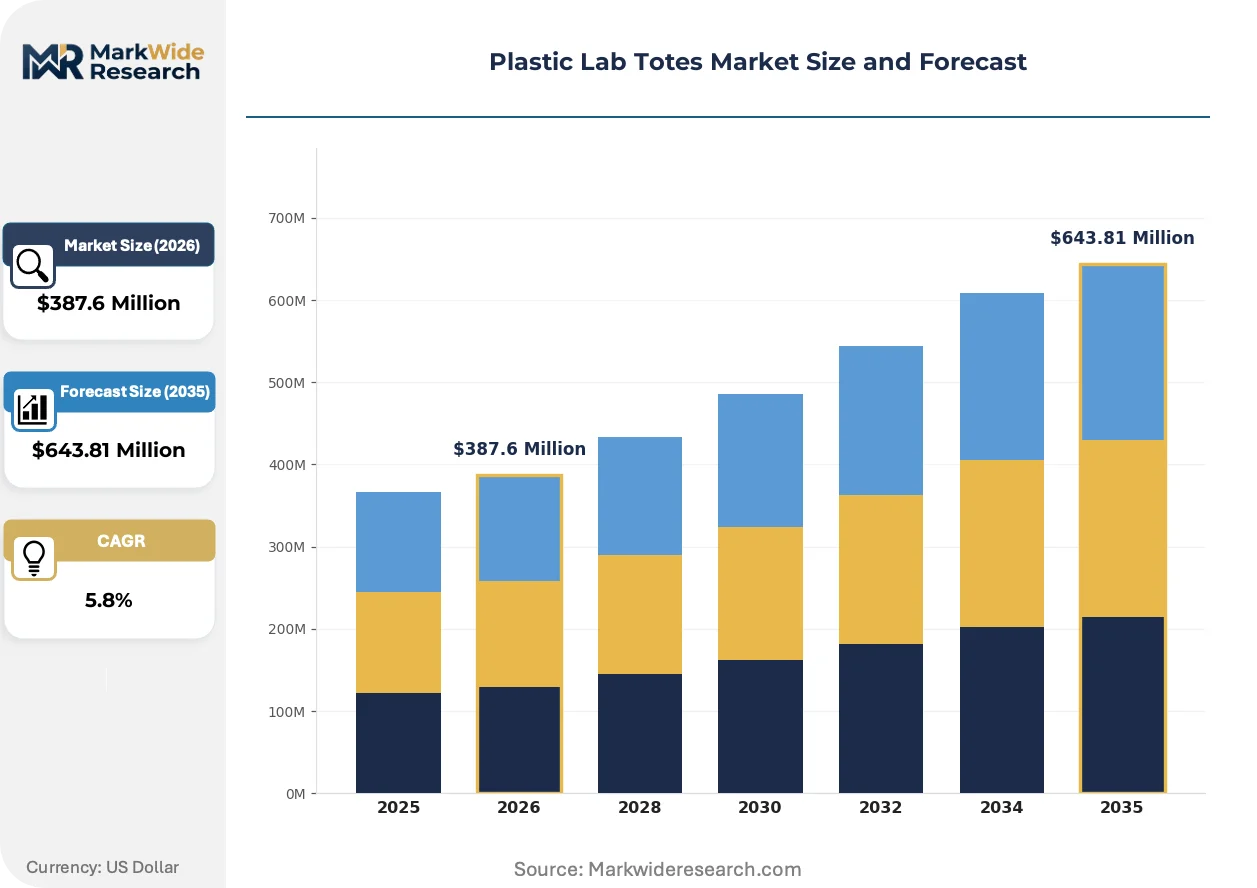
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Totes, Insulated Totes, Biohazard Totes, Modular Totes Material: Polypropylene, Polyethylene, PVC, ABS Application: Clinical Laboratories, Research Facilities, Educational Institutions, Pharmaceutical Companies End User: Laboratory Technicians, Researchers, Students, Quality Control Inspectors |
| Companies Covered | Thermo Fisher Scientific, Nasco, MTC Bio, Labplas, American Precision Plastics, Inteplast, Corning Incorporated, VWR International, Eppendorf AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Lab Totes Market Evolving Landscape
Active temperature control systems and connected monitoring platforms are redefining performance benchmarks for specimen transport, while regulatory validation requirements harden around documented chain-of-custody integrity.
Phase-change material inserts with engineered thermal mass is overtaking traditional gel pack configurations in pharmaceutical cold-chain applications. Vaccine distributors and biologics manufacturers are adopting these systems for 72-hour autonomous temperature maintenance. The technology is overtaking conventional insulated designs by eliminating active power dependency during transit.
REACH restrictions on persistent organic pollutants in polymer additives are forcing reformulation of legacy polypropylene compounds used in laboratory containers. European manufacturers face compliance deadlines for substance restrictions affecting colorants and stabilizers. Diagnostic labs in Germany and France are prioritizing suppliers with pre-certified material dossiers to avoid supply interruption.
Direct sourcing contracts between pharmaceutical cold-chain operators and specialized molders are displacing traditional distributor intermediation. Large diagnostic networks in the United States now negotiate resin specification control and dedicated production capacity in exchange for volume commitments. This pattern concentrates most visibly among reference laboratories consolidating regional testing volumes under single procurement umbrellas.
Plastic Lab Totes Market Segmentation
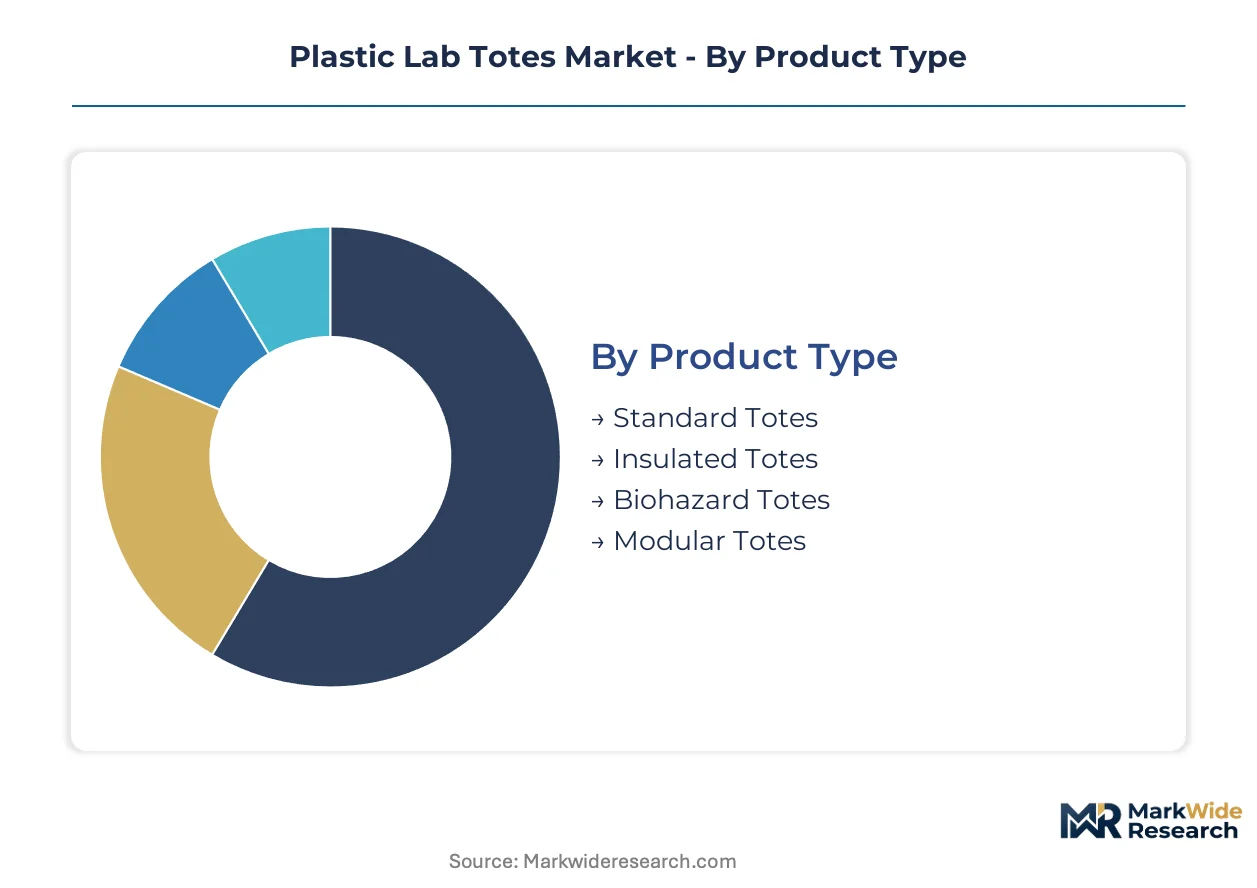
Segmentation in plastic lab totes reveals how procurement criteria diverge across sterile storage, temperature-controlled logistics, and biohazard containment workflows. Buyers prioritize autoclave durability, UN certification status, or cold-chain performance depending on end-use regulatory exposure.
Product Type:
Application temperature requirements and contamination risk levels drive product selection across clinical and pharmaceutical channels.
- Standard Totes:Rigid polypropylene or high-density polyethylene containers with 2-6 mm wall thickness for general sterile storage and reagent handling. High-throughput diagnostic labs in Germany specify these for autoclave cycling durability under ISO 17665 sterilization protocols.
- Insulated Totes:Double-walled constructions with phase-change material inserts maintaining 2°C to 8°C ranges for pharmaceutical cold-chain logistics. Vaccine distributors specify these for 72-hour autonomous temperature maintenance without active power dependency.
- Biohazard Totes:UN-certified secondary containment with integrated absorbent liners and gasket-sealed lids per DOT and IATA biological substance shipping guidelines.
- Modular Totes:Interlocking designs with standardized footprints for automated laboratory storage and retrieval systems.
Standard Totes leads on scale; Biohazard Totes leads on momentum.
Material:
Autoclave compatibility, chemical resistance, and REACH compliance timelines shape resin selection decisions.
- Polypropylene:Autoclavable thermoplastic with dimensional stability across repeated sterilization cycles. Precision-engineered formulations dominate high-throughput diagnostic lab procurement in France where autoclave cycling requirements are most stringent.
- Polyethylene:High-density and low-density variants offering impact resistance and chemical inertness for general laboratory storage applications.
- PVC:Rigid formulations with transparency for visual specimen verification in educational and research settings.
- ABS:Engineering plastic selected for structural rigidity in modular stacking configurations.
Polypropylene dominates procurement volumes; Bio-based polypropylene formulations under EU Green Deal frameworks are climbing the fastest.
Application:
Regulatory validation requirements and specimen throughput intensity determine tote performance specifications.
- Clinical Laboratories:Molecular diagnostics and infectious disease testing workflows requiring CDC-compliant specimen transport protocols. Contract research organizations in Germany concentrate demand for biohazard-rated configurations with lot traceability documentation.
- Research Facilities:Cell culture and reagent storage applications with autoclave cycling frequency driving polypropylene formulation priorities.
- Educational Institutions:Basic laboratory instruction with cost-sensitive procurement of standard storage configurations.
- Pharmaceutical Companies:Cold-chain biologics distribution with FDA medical device transport validation requirements shaping insulated tote specifications.
Clinical Laboratories anchors volume concentration; Pharmaceutical Companies shows steepest expansion trajectory from biologics pipeline growth.
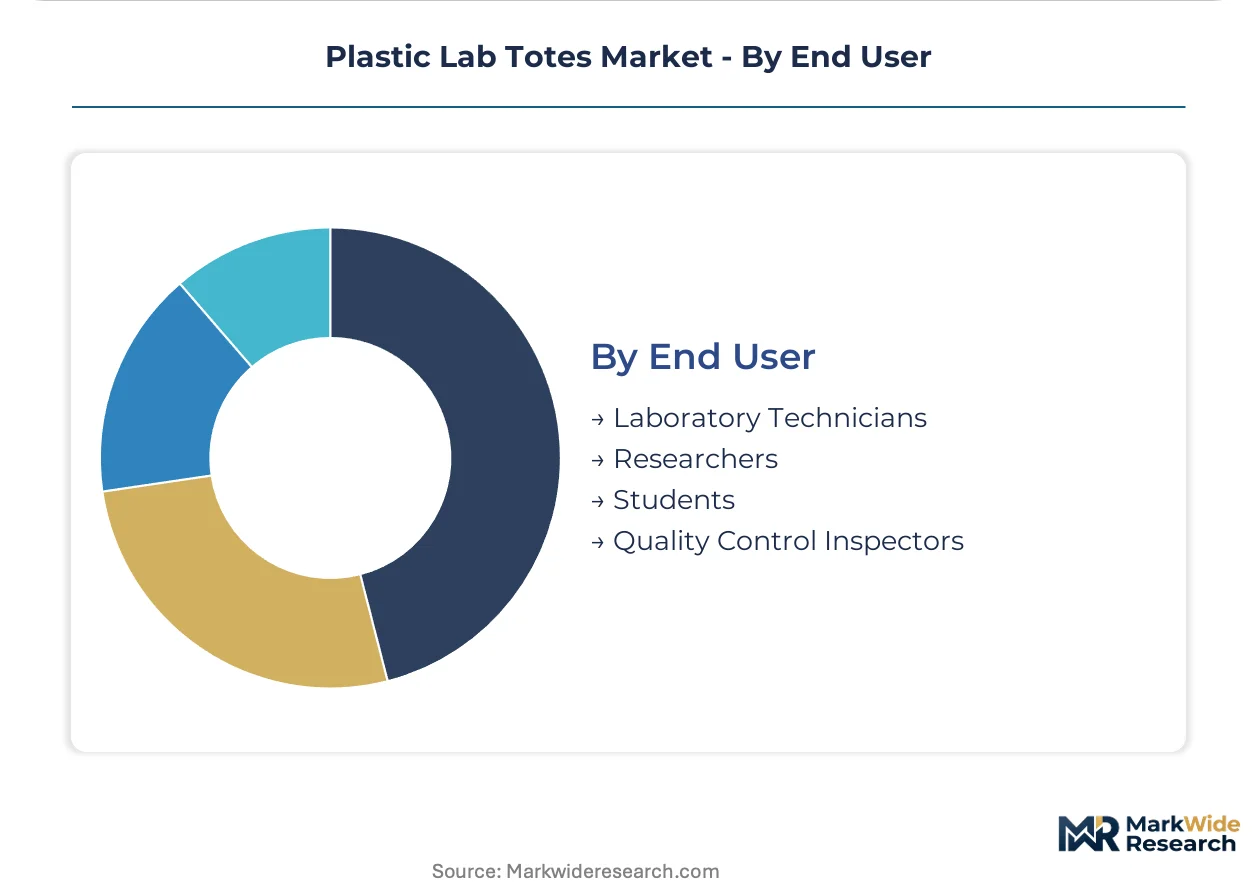
End User:
Workflow autonomy and regulatory accountability levels determine whether users specify certified configurations or delegate procurement to centralized supply functions.
- Laboratory Technicians:Frontline operators handling specimen processing and transport in clinical settings with direct exposure to OSHA Bloodborne Pathogens Standard compliance requirements.
- Researchers:Principal investigators specifying autoclave-compatible materials for cell culture workflows with publication-grade reproducibility demands.
- Students:Trainees in educational settings with institutional procurement limiting individual specification authority.
- Quality Control Inspectors:Validation specialists enforcing FDA and EPA documentation requirements for pharmaceutical and environmental testing laboratories.
Laboratory Technicians represents the largest user population; Quality Control Inspectors is gaining influence fastest through validation documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's dense cluster of contract research organizations anchors procurement concentration for biohazard-rated cold-chain configurations. Regulatory validation requirements and molecular diagnostics expansion reshape demand patterns across key national markets.
United States
FDA medical device transport validation standards tighten performance requirements for insulated and temperature-controlled designs. OSHA Bloodborne Pathogens Standard mandates puncture-resistant secondary containment with integrated absorbent liners. Reference laboratories in the Greater Boston area consolidate regional testing volumes under direct sourcing contracts with specialized molders.
Germany
Contract research organizations and clinical testing facilities concentrate demand for CDC-compliant specimen transport protocols. REACH restrictions on persistent organic pollutants in polymer additives force reformulation of legacy polypropylene compounds. Diagnostic labs in Munich and Frankfurt prioritize suppliers with pre-certified material dossiers to avoid supply interruption.
India
CDSCO regulatory alignment with international cold-chain standards creates entry pathways for biohazard-rated container suppliers. The country's expanding molecular testing capacity drives procurement of UN-certified packaging. Diagnostic infrastructure buildout in Maharashtra and Karnataka accelerates replacement cycles for clinical laboratory equipment.
France
High-throughput diagnostic labs specify precision-engineered polypropylene formulations for autoclave cycling durability. EU Green Deal frameworks accelerate adoption of bio-based polypropylene formulations certified under REACH-compliant standards. Research facilities in Île-de-France and Auvergne-Rhône-Alpes prioritize suppliers with validated cold-chain documentation.
China
NMPA biologics distribution regulations shape insulated tote specifications for pharmaceutical cold-chain operators. Dual carbon goals and MEE guidance on medical plastics recycling streams reshape material selection economics. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta integrate IoT sensors for real-time temperature excursion monitoring.
Plastic Lab Totes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart-enabled and bio-based material specializations. The vendor base stratifies across vertically integrated laboratory supply distributors, captive plastics molders, and precision-engineered formulation specialists. Three archetypes dominate: resin-integrated conglomerates controlling lot traceability, biohazard-certified configuration specialists, and autoclave-durable polypropylene engineers. Competitive moves concentrate on direct sourcing contract negotiation and REACH-compliant material dossier pre-certification.
Among resin-integrated conglomerates, Thermo Fisher Scientific exemplifies backward integration into plastics molding networks. Nasco occupies a position within the biohazard-certified tier, while Corning Incorporated anchors the precision-engineered formulation segment. These three represent distinct competitive vectors: captive resin specification control, CDC-compliant transport protocol specialization, and autoclave cycling durability engineering.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Nasco |
| MTC Bio |
| Labplas |
| American Precision Plastics |
| Inteplast |
| Corning Incorporated |
| VWR International |
| Eppendorf AG |
| Others |
Value Network & Pricing Analysis
EU Green Deal bio-based polypropylene mandates gate qualified supply access and premium-tier pricing power for laboratory container manufacturers serving REACH-compliant procurement channels in Germany and France. Pharmaceutical cold-chain operators now require certified material dossiers as a precondition for supplier qualification, compressing margin structures for non-compliant molders while rewarding pre-certified producers with pricing leverage.
Pricing Analysis
Medical-grade polypropylene and high-density polyethylene feedstock pass-through dynamics dominate pricing structures for molded container producers without captive resin supply. Three-tier pricing structure across premium, standard, and economy levels separates UN-certified biohazard configurations with lot traceability from general-purpose autoclave totes and basic educational storage. Price differentiation centers on certification grade and vertical integration status. Cost compression in standard totes is intensifying because distributor consolidation forces volume discounting. Educational institutions exhibit highest price sensitivity; pharmaceutical cold-chain operators show lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Direct-to-diagnostic-network channels handle hyperscale buyer demand from reference laboratories consolidating regional testing volumes under single procurement umbrellas. Manufacturing concentration spans the United States, Germany, and China, with precision molding clusters in the Yangtze River Delta and Pearl River Delta feeding export markets. Supply chains draw from medical-grade polypropylene resin, silicone gasket components, and phase-change material thermal inserts. Single-source vulnerability in certified resin specifications poses structural risk as REACH restrictions eliminate legacy compound suppliers. Distribution runs through laboratory supply distributors, though direct sourcing contracts are displacing traditional intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic lab totes market functions as a regulatory compounder where OSHA Bloodborne Pathogens Standard mandates drive replacement cycles and certification investment requirements. FDA medical device transport validation standards tighten continuously, embedding compliance costs as permanent demand drivers.
For Market Incumbents: Anticipate silicone gasket substitution threats from reusable metal transport cases in premium pharmaceutical logistics by accelerating IoT sensor integration for real-time temperature excursion documentation. Defend market position through backward integration into resin specification control and dedicated production capacity commitments from large diagnostic networks. Prioritize REACH-compliant material dossier pre-certification to avoid supply interruption penalties in European contract research organization procurement.
For New Entrants and Emerging Players: Begin with India's diagnostic infrastructure buildout in Maharashtra and Karnataka where CDSCO regulatory alignment creates entry pathways for biohazard-rated container suppliers. Target molecular diagnostics expansion at contract research organizations requiring CDC-compliant specimen transport protocols as the most penetrable application segment. Pursue smart temperature logging convergence as the primary go-to-market angle, offering integrated IoT sensor platforms as differentiated value propositions.
For Investors and Strategic Acquirers: Roll-up economics work for precision-engineered polypropylene formulation specialists because autoclave cycling durability requirements concentrate procurement among suppliers with validated sterilization performance documentation. Long-term viability rests on consolidation of REACH-certified material capabilities and direct sourcing contract portfolios with pharmaceutical cold-chain operators. Watch CDSCO enforcement alignment with international cold-chain standards as the inflection indicator for geographic expansion returns.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Certification | Pre-certified dossiers prevent supply interruption at German diagnostic labs facing substance restriction deadlines. |
| IoT Sensor Platform Integration | Real-time temperature logging enables 2°C to 8°C compliance documentation for pharmaceutical distributors. |
| Direct Sourcing Contract Negotiation | Resin specification control exchanges secure dedicated production capacity from large diagnostic networks. |
| Phase-Change Material Thermal Insert Development | 72-hour autonomous temperature maintenance eliminates active power dependency for vaccine distribution. |
| Backward Integration into Resin Supply | Captive polypropylene molding networks control lot traceability across clinical and research channels. |
Research Methodology
Bottom-up clinical laboratory and pharmaceutical cold-chain modeling reconciled against top-down resin supply and distributor tracking forms the analytical core of this study. Primary interviews with laboratory supply procurement managers, diagnostic network operations directors, regulatory affairs specialists at container manufacturers, and biomedical engineers at high-throughput testing facilities combined with secondary validation from FDA guidance documents, EPA medical plastics recycling guidance, OSHA Bloodborne Pathogens Standard enforcement data, and customs trade records for medical-grade polymer imports. Triangulation across these sources ensures segment-level accuracy.
Historical trendline analysis of autoclave cycling replacement cycles, cold-chain logistics expansion patterns, and molecular diagnostics infrastructure buildout informs the projection framework. Segmentation dimensions modeled include product type, material formulation, application workflow, and end-user regulatory accountability level across the analysis window. CAGRs derive from weighted average of end-use demand trajectories and supply-side capacity expansion plans, with specific inputs from UN-certified packaging validation timelines and REACH substance restriction compliance deadlines.
Several conditions sit outside the modeled scope, including potential federal preemption of state-level extended producer responsibility frameworks and breakthrough alternatives to polypropylene in autoclave applications. Forecasts reflect documented assumptions about regulatory enforcement continuity and resin price volatility bands. Periodic stress-testing of base assumptions is recommended against EPA guidance evolution and CDSCO enforcement alignment milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
South Africa Plastic Packaging Films Market
Plastic Packaging
Germany Plastic Bottles Market
Plastic Packaging
Corrugated Plastic Trays Market
Plastic Packaging
Plastic Films Market
Plastic Packaging
Plastic Cutlery Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Plastic Keg Market
Plastic Packaging
Disposable Straw Market
Plastic Packaging
South Africa Flexible Packaging Market
Plastic Packaging
United Arab Emirates Plastic Packaging Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
South America Polyethylene Terephthalate (PET) Market
Plastic Packaging
Polypropylene Corrugated Packaging Market
Plastic Packaging
MENA Thermoform Plastic Packaging Market
Plastic Packaging
Clear Plastic Boxes Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market