
 Banding Stretch Film Market | 2026-2036
Banding Stretch Film Market Size, Share, and Industry Trends Forecast 2026-2036
Banding Stretch Film Market Analysis
The banding stretch film category is rebalancing between premium engineered films and commodity-grade polyethylene wraps. Berry Global leverages vertical integration from resin to finished roll to sustain margin control across thickness grades. Inteplast Group anchors its position through geographic dominance in North American distribution networks. Manuli Stretch differentiates via specialized cast film lines optimized for high-speed automatic wrapping systems.
Banding stretch film is a narrow-width polyethylene or polypropylene film, typically 2 to 5 inches wide, manufactured through blown or cast extrusion with cling additives on one or both sides, designed to secure multiple items into a single unit without full pallet encapsulation. Its primary purpose is bundling and reinforcing loads in logistics, retail distribution, and manufacturing workflows where full wrap coverage proves excessive. Machine-wrapped and automatic formats command structural attention as warehouse automation expands, while hand-wrapped segments face margin compression from labor cost escalation. Polyethylene formulations dominate volume, though polypropylene gains traction in temperature-sensitive pharmaceutical applications where higher tensile strength reduces breakage.
The US EPA and OSHA frameworks govern workplace chemical exposure and film dust particulate limits in converting facilities, while REACH and RoHS directives in Europe restrict certain plasticizers and additives in films contacting consumer goods. These regulations shape resin selection, additive packages, and market access certification requirements for cross-border suppliers. Stakeholders must monitor evolving extended producer responsibility schemes and mechanical recycling compatibility standards as these will determine which material platforms retain commercial viability.
Market Dynamics
Warehouse automation is compressing the hand-wrapped segment while expanding specification requirements for machine-grade films. The EU F-Gas Regulation and OSHA particulate limits are simultaneously reshaping resin formulations and converting facility investments.
Growth Catalysts
- Food and beverage logistics automation:High-velocity distribution centers in Germany's Rhine-Ruhr corridor are specifying cast film optimized for automatic wrapping heads.
- REACH-compliant additive packages:ECHA restrictions on phthalate plasticizers are accelerating migration to bio-based cling agents in films contacting consumer goods.
- Pharmaceutical cold chain expansion:Polypropylene banding films with higher tensile strength are displacing polyethylene in temperature-sensitive pharmaceutical bundling applications.
Market Restraints
- Ethylene feedstock volatility:Crude oil and natural gas price swings transmit directly to polyethylene resin costs, squeezing converter margins on fixed-price contracts.
- Blown film capacity concentration:Three US Gulf Coast resin producers control 60% of domestic high-density polyethylene supply, creating single-source vulnerability.
- Mechanical recycling incompatibility:Multi-layer films with incompatible resin combinations face rejection by European extended producer responsibility sorting facilities.
Strategic Opportunities
- Indian pharmaceutical export bundling:CDSCO-compliant packaging for temperature-controlled API shipments to European markets remains underserved by domestic converters.
- Post-consumer recycled content mandates:California's SB 54 and New York's extended producer responsibility laws create certified recycled-content film demand.
- RFID-embedded intelligent films:Convergence of stretch film with supply chain tracking technology enables unit-level traceability for high-value electronics shipments.
Industry Challenges
- Cast film line operator scarcity:Specialized extrusion technicians capable of tuning die gaps for micron-precision thickness control command premium wages in Düsseldorf and Cologne industrial zones.
- Multi-jurisdiction certification timelines:Simultaneous FDA food-contact, EPA workplace exposure, and REACH substance registration requirements extend product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banding Stretch Film Market |
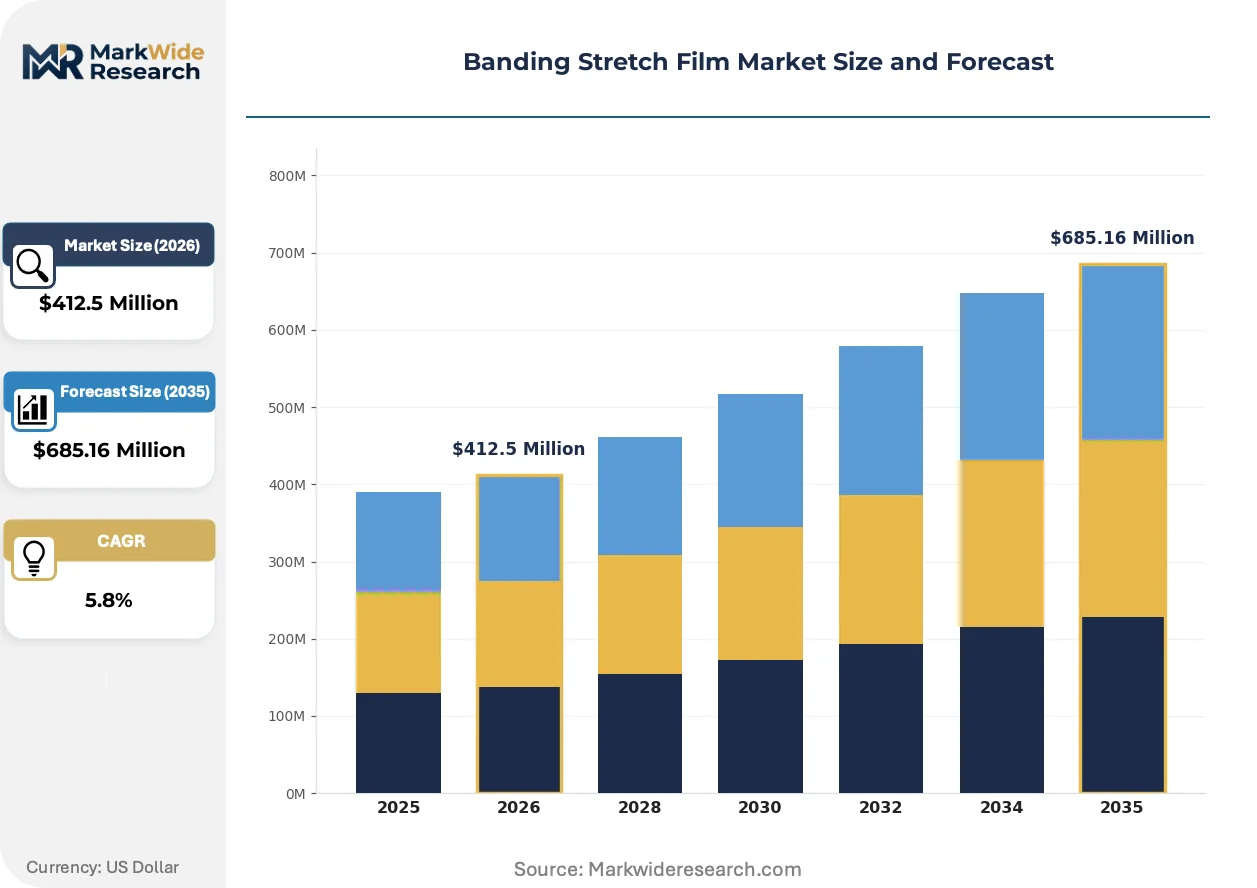
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Machine-Wrapped, Hand-Wrapped Material: Polyethylene, Polypropylene, PVC, Others End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics Thickness: Standard, Heavy-Duty, Light-Duty, Extra Heavy-Duty |
| Companies Covered | Berry Global, Inteplast Group, Goodwrappers (J.C. Parry & Sons), Intertape Polymer Group, Manuli Stretch, YOST Industrial, Sigma Plastics Group, Alpha Omega Plastic Manufacturing, Landsberg Orora, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banding Stretch Film Market Emerging Trajectories
Film specification is bifurcating between commodity polyethylene wraps and engineered multi-layer structures. Three concurrent developments are reshaping converter R&D priorities and buyer procurement criteria.
Downgauged five-layer coextruded films with metallocene polyethylene core layers is overtaking conventional monolayer blown film in automated warehouse applications. Food and beverage third-party logistics operators in the Netherlands and Belgium are specifying 8-micron equivalents that maintain 12-micron puncture resistance. The structural consequence is margin compression for commodity converters lacking cast line investment.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon blowing agents are forcing reformulation of low-density polyethylene foams used in protective banding applications. Converters serving appliance and electronics manufacturers must validate alternative physical foaming agents by 2027. German industrial packaging corridors are piloting nitrogen-assisted foam expansion to maintain cushioning performance.
Consolidated buying by national grocery chains is compressing supplier rosters and extending contract durations from annual to multi-year frameworks. Regional distributors in France and Spain are losing direct mill relationships as Carrefour and Mercadona centralize stretch film procurement through specialized packaging category managers. The shift is most visible in Iberian fresh produce export logistics, where three buyers now represent 40% of banding film volume.
Banding Stretch Film Market Segmentation
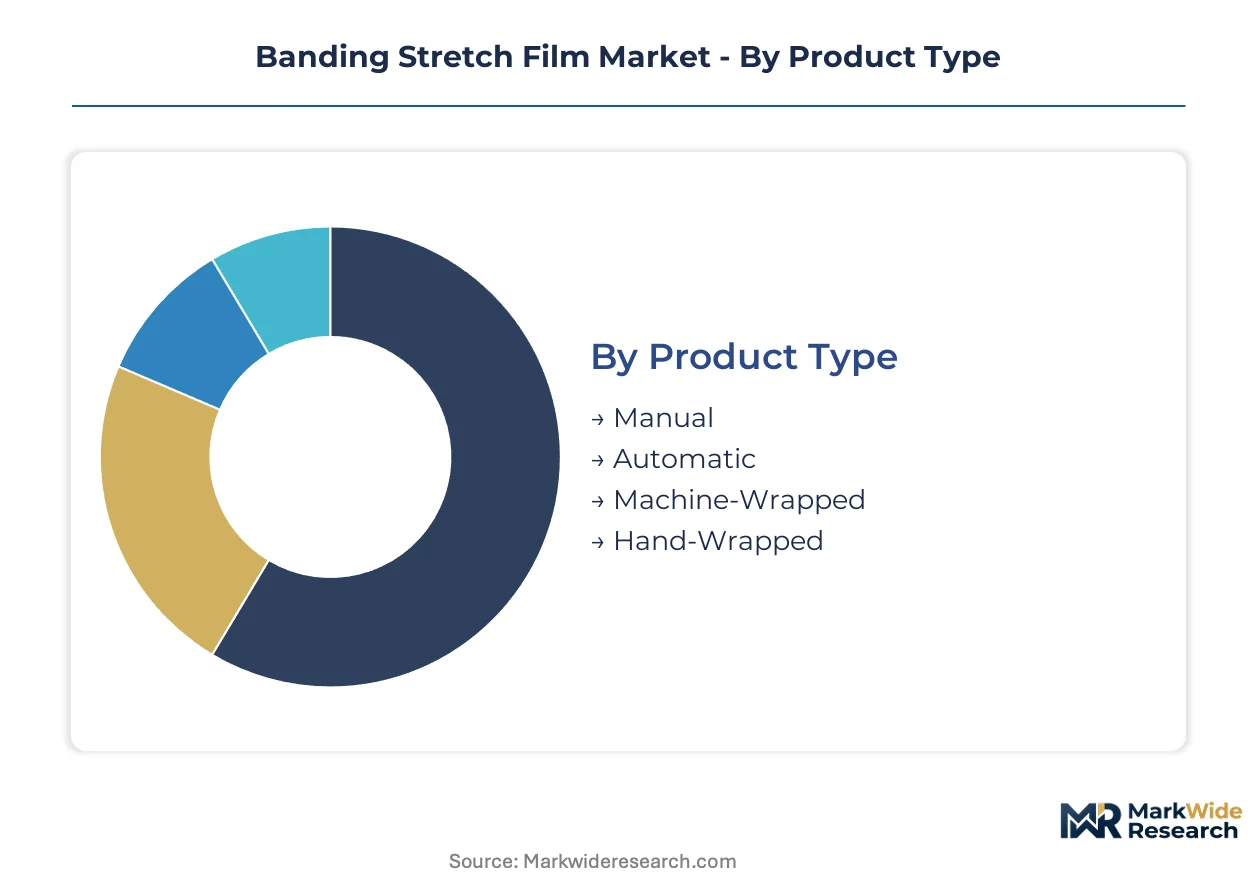
Banding stretch film procurement decisions pivot on certification requirements, automation compatibility, and load-bearing specifications. Buyers segment offerings by application environment, regulatory exposure, and handling methodology to align film performance with operational constraints.
Product Type:
FDA food-contact certification applies to all formats touching consumables, while machine-wrapped variants demand additional OSHA workplace exposure compliance for high-speed converting facilities.
- Automatic:Cast film formulations engineered for continuous-feed wrapping heads in high-velocity distribution centers. Demand concentrates in Germany's Rhine-Ruhr logistics corridor, where warehouse automation investments are displacing manual bundling operations.
- Machine-Wrapped:Blown or cast extrusions calibrated for semi-automatic turntable systems with tension-controlled pre-stretch mechanisms. Food and beverage third-party logistics operators in the Netherlands and Belgium specify micron-precision thickness control for pallet stability without overwrap waste.
- Manual:Hand-tearable rolls with single-sided cling for low-volume bundling in retail backrooms and small manufacturing cells.
- Hand-Wrapped:Pre-cut lengths or dispenser-fed rolls for irregular loads lacking uniform dimensions suitable for machine handling.
Leading the category by volume: Machine-Wrapped. Expanding most quickly: Automatic.
Material:
Resin selection determines REACH substance registration burdens, with polypropylene requiring more extensive ECHA documentation for pharmaceutical contact applications.
- Polyethylene:Linear low-density and metallocene grades dominate volume through blown and cast extrusion lines. Blown film capacity concentration along the US Gulf Coast creates feedstock cost exposure for converters on fixed-price contracts.
- Polypropylene:Higher tensile strength and temperature resistance suit pharmaceutical cold chain bundling where breakage reduction justifies premium positioning. CDSCO-compliant converters in India are expanding cast line investment for temperature-controlled API shipments to European markets.
- PVC:Legacy formulations facing mechanical recycling rejection by European extended producer responsibility sorting facilities.
- Others:Bio-based polyethylene and post-consumer recycled content grades responding to California SB 54 and New York extended producer responsibility mandates.
Dominant by tonnage: Polyethylene. Steepest expansion trajectory: Polypropylene.
End User:
Regulatory intensity varies sharply across verticals, with pharmaceutical and food applications triggering multi-jurisdiction certification timelines that extend product launches.
- Food & Beverage:Unitized pallet stability requirements in high-velocity distribution drive specification of downgauged five-layer coextruded films with metallocene core layers.
- Pharmaceuticals:Temperature-sensitive bundling applications favor polypropylene for tensile strength retention in cold chain logistics.
- Consumer Goods:REACH-compliant additive packages with bio-based cling agents replace phthalate plasticizers for films contacting retail merchandise.
- Electronics:RFID-embedded intelligent films enabling unit-level traceability for high-value shipments through automatic wrapping systems.
Highest volume concentration: Food & Beverage. Gaining share fastest: Pharmaceuticals.
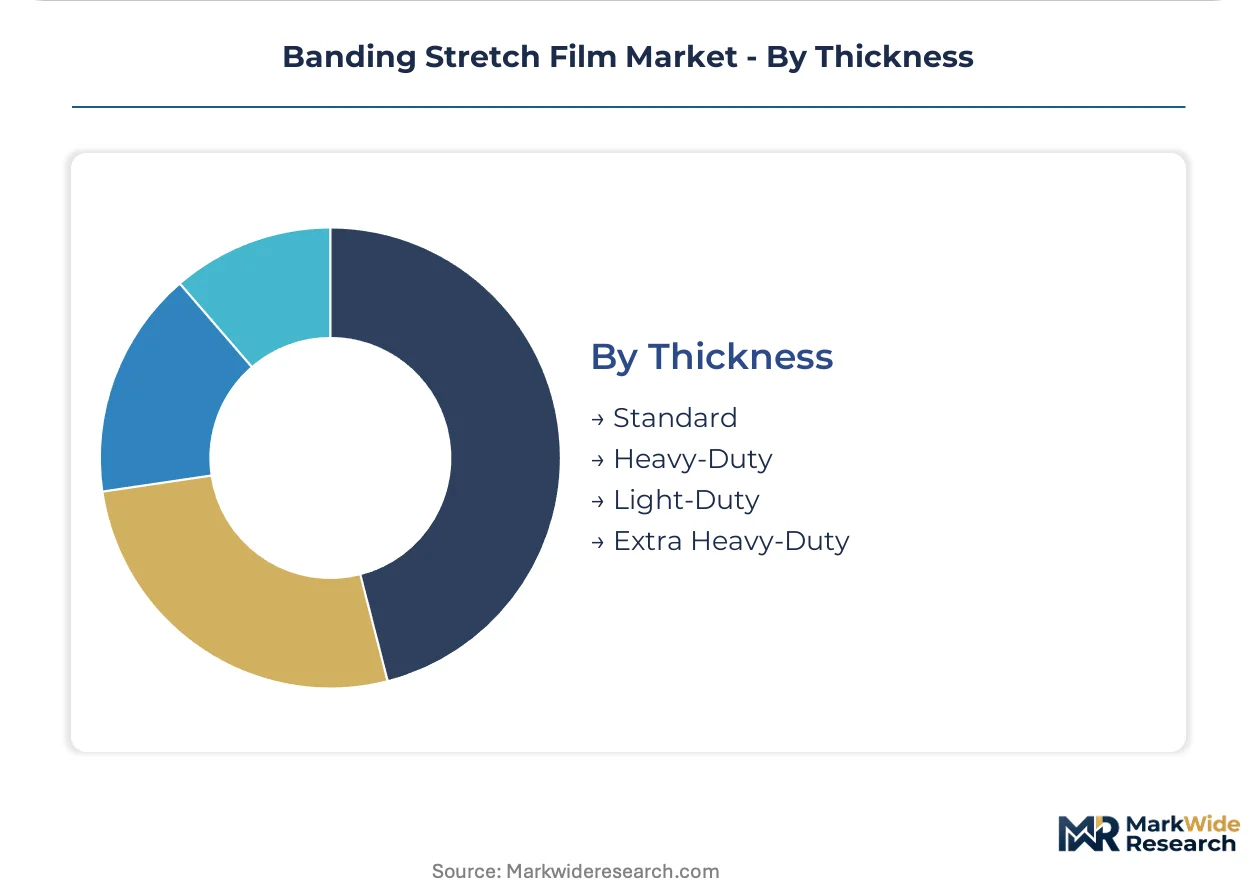
Thickness:
Downgauging trends compress margin structures for commodity converters lacking cast line investment, while heavy-duty specifications retain pricing power in specialized applications.
- Standard:12-15 micron monolayer blown film for general-purpose bundling with moderate puncture resistance requirements.
- Heavy-Duty:Multi-layer coextrusions with metallocene polyethylene cores delivering 20+ micron equivalent performance at reduced gauge. Appliance and electronics manufacturers in German industrial packaging corridors specify nitrogen-assisted foam expansion alternatives under EU F-Gas Regulation phase-down schedules.
- Light-Duty:Sub-10 micron cast films for retail display bundling where aesthetic clarity outweighs load security.
- Extra Heavy-Duty:Reinforced edge formulations for metal coil and construction material unitization with extreme puncture and tear propagation resistance.
Volume leader: Standard. Climbing the fastest: Heavy-Duty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf and Cologne anchor the industrial packaging corridor where warehouse automation investments are reshaping banding stretch film procurement. Germany's Rhine-Ruhr logistics cluster commands disproportionate specification influence for cast film formulations. Regulatory pressure from Brussels cascades through national compliance frameworks across multiple jurisdictions.
Germany
Food and beverage third-party logistics operators in the Netherlands-Belgium-Germany corridor specify micron-precision thickness control for high-velocity distribution centers. EU F-Gas Regulation phase-down schedules force nitrogen-assisted foam expansion pilots in protective banding applications. The Düsseldorf-Cologne industrial zone concentrates cast line investment for automatic wrapping head compatibility.
United States
OSHA particulate limits and EPA workplace exposure frameworks govern converting facility investments along the Gulf Coast resin corridor. California SB 54 and New York extended producer responsibility laws create certified recycled-content film demand. Chicago and Detroit distribution hubs drive specification for downgauged five-layer coextruded structures in automated warehouses.
India
CDSCO-compliant packaging for temperature-controlled API shipments to European markets attracts cast line investment from domestic converters. The central pharmaceutical regulator mandates documentation standards that extend product launch timelines. Maharashtra and Gujarat industrial zones host expanding capacity for pharmaceutical cold chain bundling applications.
China
GB standards and dual carbon goals reshape resin selection for export-oriented packaging manufacturers. MIIT industrial policy guides capacity consolidation in blown and cast extrusion sectors. The Yangtze River Delta logistics cluster generates specification pull for machine-grade films serving electronics export bundling.
Netherlands
REACH substance registration requirements accelerate migration to bio-based cling agents for films contacting consumer goods. ECHA restrictions on phthalate plasticizers reshape additive package formulation. Rotterdam port logistics operators specify cast film optimized for automatic wrapping heads in consolidated grocery chain procurement.
Banding Stretch Film Market Vendor Landscape
Capital-heavy producers compete with asset-light distributors across a bifurcated market structure. Blown and cast extrusion line ownership separates integrated compounders from roll converters dependent on merchant resin supply. Three archetypes dominate: resin-integrated multinationals, geographic-focused regional networks, and specialized cast film technicians. Capacity expansion and backward integration into resin sourcing represent the primary competitive vectors as feedstock volatility squeezes margin structures.
Within the integrated multinational tier, Berry Global exemplifies resin-to-roll vertical control across thickness grades. Inteplast Group anchors North American distribution network dominance through geographic density. Manuli Stretch occupies the specialized cast film position optimized for high-speed automatic wrapping systems. These three represent distinct strategic postures rather than direct segment overlap.
| Leading Market Players |
|---|
| Berry Global |
| Inteplast Group |
| Goodwrappers (J.C. Parry & Sons) |
| Intertape Polymer Group |
| Manuli Stretch |
| YOST Industrial |
| Sigma Plastics Group |
| Alpha Omega Plastic Manufacturing |
| Landsberg Orora |
| Others |
Supply Flow & Price Mechanics
Consolidated procurement by national grocery chains in Iberia and the Netherlands is forcing converters toward multi-year contract frameworks that compress spot-market pricing power and reward scale. This buyer concentration reshapes supplier economics across cast and blown film tiers.
Pricing Analysis
Wrapping-head uptime and pallet throughput anchor value-based pricing for automatic-grade cast films in German distribution centers. Three-tier pricing structure across premium metallocene-core formulations, standard blown film, and economy monolayer grades differentiates by certification burden and gauge precision. Cost compression in commodity polyethylene wraps intensifies as Gulf Coast resin volatility transmits through fixed-price contracts. Food and beverage third-party logistics operators show highest price sensitivity, while pharmaceutical cold chain buyers prioritize tensile performance over unit cost.
Supply Chain Analysis
Mechanical recycling flows and post-industrial film recovery are emerging as reverse-logistics priorities under European extended producer responsibility schemes. Resin supply concentrates in the United States, Saudi Arabia, and South Korea, with linear low-density polyethylene feedstock drawing from ethane-rich natural gas liquids. Blown film capacity clustering along the US Gulf Coast creates single-source vulnerability for converters lacking geographic diversification. Distribution runs through specialized packaging category managers at consolidated grocery chains and third-party logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
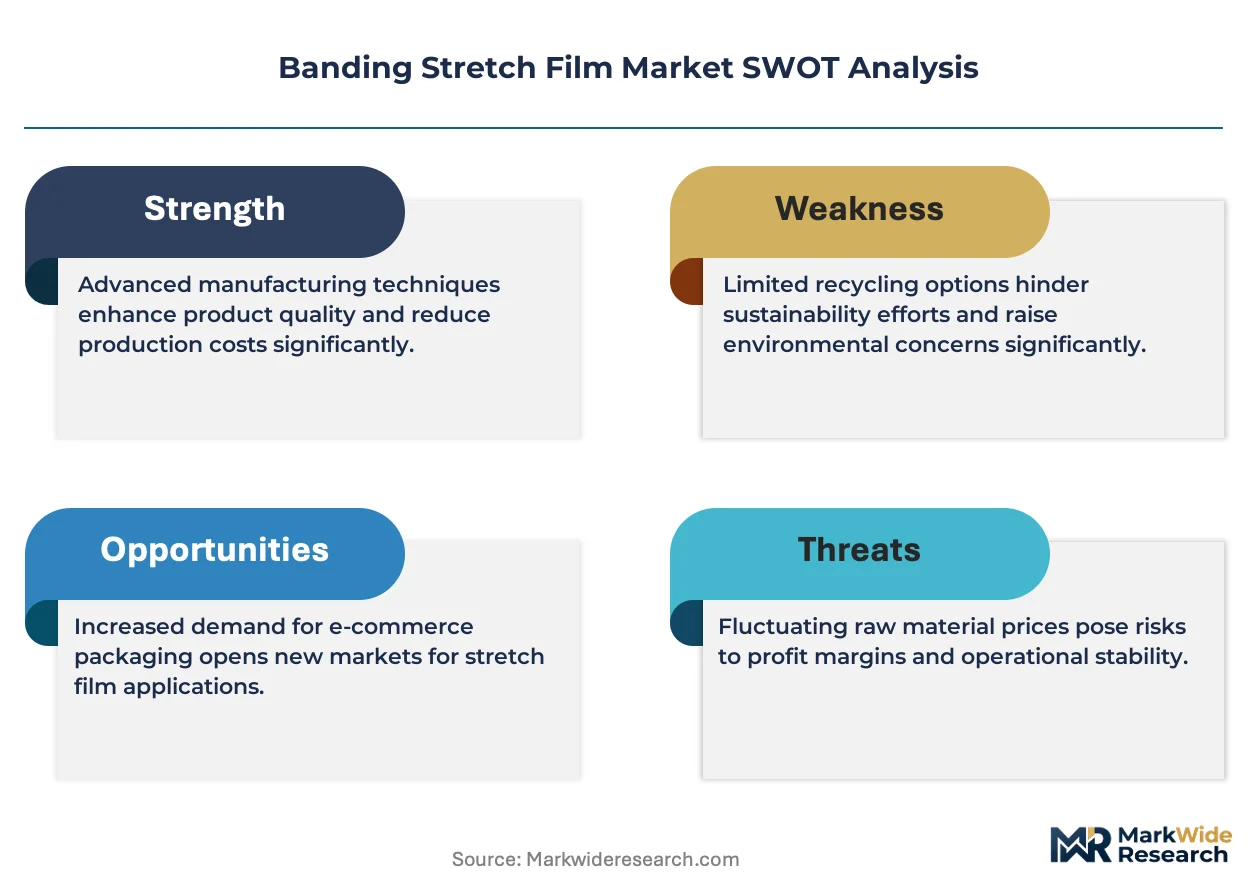
The Banding Stretch Film Market operates as a cost-of-compliance arena where REACH substance registration and EU F-Gas Regulation adherence erect barrier-to-entry moats that favor capitalized incumbents with dedicated regulatory affairs infrastructure.
For Market Incumbents: To counter margin erosion from downgauged five-layer coextrusion substitutes, prioritize backward integration into metallocene polyethylene resin sourcing and expand cast line investment in the Düsseldorf-Cologne corridor. Certification investment for CDSCO-compliant pharmaceutical exports represents a defensible pricing tier. For New Entrants and Emerging Players: Launch via private-label partnerships with regional distributors in Maharashtra and Gujarat serving temperature-controlled API export bundling to European markets. Indian pharmaceutical cold chain applications remain the most penetrable white space, with bio-based cling agent formulations offering differentiation against phthalate-restricted incumbents. For Investors and Strategic Acquirers: The window for entry favors resin-integrated compounders with existing cast extrusion technician pools and REACH-registered additive packages. Watch nitrogen-assisted foam expansion validation timelines under EU F-Gas phase-down schedules as the inflection signal for protective banding segment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallocene Resin | Captive supply of precision-grade polyethylene secures margin control against Gulf Coast feedstock volatility. |
| Cast Line Investment in Rhine-Ruhr Corridor | Proximity to German warehouse automation hubs reduces logistics cost and specification response time. |
| CDSCO Certification for Pharmaceutical Exports | Compliance with India's central pharmaceutical regulator unlocks temperature-controlled API bundling contracts. |
| Nitrogen-Assisted Foam Expansion Pilots | Alternative physical foaming maintains cushioning performance as EU F-Gas Regulation phases down hydrofluorocarbon agents. |
| Post-Consumer Recycled Content Certification | California SB 54 and New York extended producer responsibility laws create mandated demand for verified recycled grades. |
Methodological Framework
Multi-period observation of warehouse automation adoption rates, resin price spreads, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with plant managers at blown and cast extrusion facilities, procurement leads at food and beverage third-party logistics operators, technical R&D directors at additive suppliers, and packaging category managers at consolidated grocery chains. Secondary validation drew from customs and trade data, ECHA substance registration databases, SEC 10-K filings of resin-integrated multinationals, and extended producer responsibility scheme operator reports. Bottom-up volume modeling and top-down value reconciliation ensured cross-verification.
Input-output matrices structured the analytical framework across the projection horizon, with segmentation dimensions spanning product type, material formulation, end-use vertical, and regional production hub. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization trajectories. Industry-specific forecast inputs included warehouse automation capital expenditure pipelines and REACH substance restriction amendment schedules.
Feedstock price volatility, regulatory amendment acceleration, and mechanical recycling sorting technology adoption are the dominant revision risks to modeled outputs. Practitioners should monitor ethane-naphtha spread movements, ECHA restriction proposal timelines, and European sorting facility acceptance criteria for multi-layer films for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Global Micro Injection Molded Plastic Market
Plastic Packaging
South Africa Flexible Packaging Market
Plastic Packaging
MDPE Bottles Market
Plastic Packaging
Europe Plastic Packaging Films Market
Plastic Packaging
Mushroom Plastics Market
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Polypropylene Corrugated Packaging Market
Plastic Packaging
Brazil Plastic Bottles Market
Plastic Packaging
PCR Bottles Market
Plastic Packaging
Global Stretch Films Market
Plastic Packaging
Italy Plastic Bottles Market
Plastic Packaging
Plastic Carboy Market
Plastic Packaging
Global Plastic Packaging Sacks Market
Plastic Packaging
Corrugated Plastic Box Market
Plastic Packaging
Plastic Shrink Wrap Market