
 Global Aseptic Sampling Market | 2026-2036
Global Aseptic Sampling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aseptic Sampling Market Foresight
Contract manufacturing organizations is collapsing the historical dominance of in-house quality assurance departments as the primary procurement channel for aseptic sampling hardware. Sartorius AG leverages its German manufacturing base to dominate closed-system sampling across European biologics facilities. Merck KGaA anchors high-purity membrane and bag sampler portfolios for upstream cell-culture applications. Thermo Fisher Scientific competes through integrated workflow bundling that extends from sampling devices into analytical instrumentation.
Aseptic sampling encompasses the extraction of representative process fluids or solids under conditions that exclude microbial, particulate, or chemical contamination, typically employing gamma-sterilized single-use bags, sealed cannula assemblies, or closed-loop vacuum vessels rated for ISO 5 environments. The practice ensures batch integrity during bioreactor harvesting, vaccine fill-finish operations, and pharmaceutical water-system monitoring. Single-use systems lead product-type demand by eliminating steam-in-place validation burdens, while automated sampling technology captures the fastest growth trajectory as biopharma facilities pursue reduced human intervention and real-time process analytical technology integration. Manual sampling retains substantial share in food and beverage quality control where capital constraints limit robotics deployment.
FDA enforcement of updated Annex 1 sterility guidelines and EMA's good manufacturing practice inspections are forcing biopharmaceutical producers to replace open sampling methods with validated closed-system alternatives. The EPA and WHO water-quality frameworks further extend demand for vacuum sampling devices in pharmaceutical-grade water treatment verification. Stakeholders must monitor regulatory divergence between FDA and EMA validation requirements for single-use sampling assemblies as this friction will determine supplier certification costs and market access barriers.
Market Dynamics
Closed-system aseptic sampling technology is compressing validation timelines and eliminating steam-in-place infrastructure, forcing biopharmaceutical manufacturers to retire open-sampling protocols across upstream cell-culture operations.
Growth Catalysts
- FDA Annex 1 Enforcement:The sterility guideline revisions mandate validated closed-system alternatives for all sterile processes, compelling biologics producers to replace open sampling methods with gamma-sterilized single-use assemblies.
- Single-Use Technology Maturation:Pre-sterilized bag and membrane systems eliminate cleaning validation burdens, accelerating adoption in multi-product bioreactor facilities where campaign changeover speed determines throughput.
- German Biologics Cluster:Concentrated monoclonal antibody production in Baden-Württemberg and Bavaria generates sustained procurement volume for advanced sampling infrastructure serving contract manufacturing organizations.
Market Restraints
- Specialized Polymer Supply Concentration:Medical-grade thermoplastic elastomer and fluoropolymer film production concentrates among a limited supplier base, exposing sampling device manufacturers to resin allocation volatility.
- Cross-Atlantic Validation Divergence:EMA and FDA maintain non-harmonized certification requirements for single-use sampling assemblies, forcing suppliers to duplicate testing protocols and extending commercialization timelines.
- Gamma Irradiation Capacity Bottleneck:Sterilization service providers face capacity constraints in key European and North American logistics corridors, creating fulfillment delays for pre-sterilized sampling kits.
Strategic Opportunities
- Indian Biosimilar Manufacturing Expansion:CDSCO regulatory alignment with international GMP standards creates demand for closed-system sampling in emerging large-scale biologics facilities near Hyderabad and Bengaluru.
- Process Analytical Technology Integration:Convergence of automated sampling robotics with real-time spectroscopic analyzers enables closed-loop control systems that biopharma facilities will deploy for continuous manufacturing transitions.
- Cell and Gene Therapy Workflows:Viral vector production and autologous cell therapy processing require ultra-low volume aseptic sampling, opening specialized product development white space distinct from traditional bioreactor applications.
Industry Challenges
- Contamination Investigation Complexity:Closed-system failures require specialized forensic microbiology capabilities that many quality assurance departments lack, extending batch release investigations and tying up regulatory affairs personnel.
- Legacy Equipment Integration:Retrofitting stainless steel bioreactor trains with single-use sampling interfaces demands custom engineering for each vessel configuration, complicating standardization efforts across multi-site manufacturing networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aseptic Sampling Market |
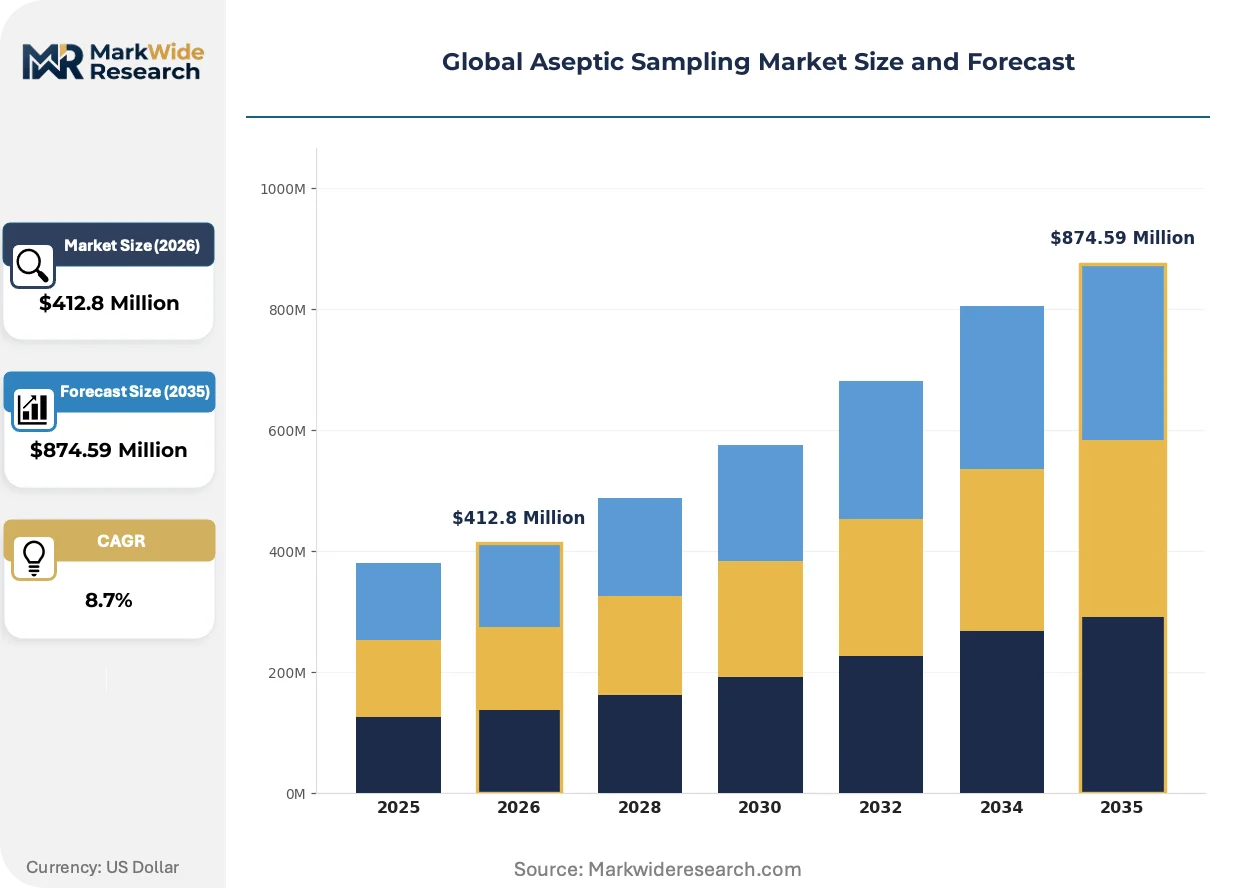
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $874.59 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle Sampling Devices, Syringe Sampling Devices, Vacuum Sampling Devices, Bag Samplers, Cannula Assemblies Technology: Sterile Barrier, Closed Sampling Systems, Automated Sampling, Manual Sampling, Single-Use Systems Application: Biopharmaceutical Production, Vaccine Development, Food & Beverage Quality Control, Water Treatment, Cosmetic Manufacturing End User: Contract Manufacturing Organizations, Research Laboratories, Quality Assurance Departments, Biotech Firms, Diagnostic Facilities |
| Companies Covered | Merck KGaA, Sartorius AG, Thermo Fisher Scientific Inc., Danaher Corporation, Cytiva, GEA Group AG, Keofitt A/S, Pall Corporation, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aseptic Sampling Market Shifts & Advancements
Automation and real-time analytics are collapsing the interval between sample extraction and quality decision, compressing batch release cycles and redefining where aseptic sampling sits within process control architecture.
Robotic sampling arms with integrated barcode tracking and chain-of-custody logging are supplanting manual grab-sample protocols in commercial biologics facilities. Cell-culture operators at multi-thousand-liter scales deploy these systems to eliminate human intervention during bioreactor harvesting. The technology is enabling 24/7 sampling schedules that manual staffing cannot sustain, compressing process development timelines and accelerating technology transfer between clinical and commercial manufacturing.
EMA's updated Annex 1 interpretation on contamination control strategy documentation is forcing biopharmaceutical manufacturers to demonstrate closed-system integrity through enhanced validation data packages. The industrial consequence extends beyond hardware procurement into quality management system restructuring, with sampling device suppliers now required to provide extractables and leachables profiles for every polymer contact surface. European facilities face the most intensive inspection scrutiny, driving preference for suppliers with established notified body relationships and comprehensive drug master file portfolios.
Contract manufacturing organizations are consolidating vendor relationships around full-line suppliers capable of bundling sampling devices with downstream filtration and analytical instrumentation. Single-source procurement contracts replace fragmented purchasing across quality, manufacturing, and analytical departments, with CMO procurement teams negotiating enterprise pricing spanning multiple facility locations. This concentration is most visible in Ireland and Singapore, where global biologics manufacturers have concentrated multi-product manufacturing campuses and seek to simplify supplier management overhead.
Global Aseptic Sampling Market Segmentation
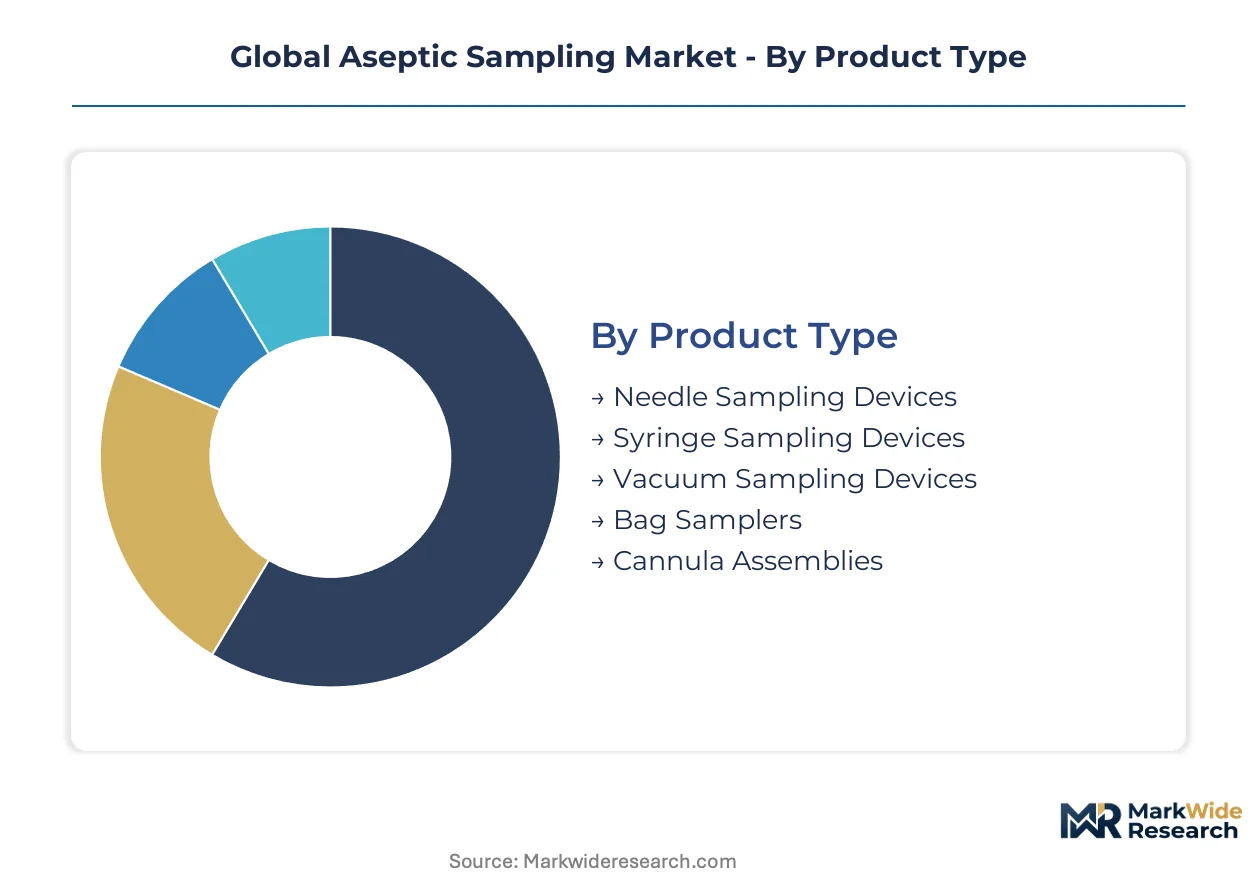
Segmentation in aseptic sampling reveals how regulatory pressure, automation economics, and end-user procurement consolidation reshape competitive positioning across hardware categories. Distinct technical specifications and validation requirements govern purchasing decisions in each dimension.
Product Type:
FDA Annex 1 and EMA sterility guidelines differentiate sampling hardware by contamination-risk profile and validation burden, with closed-system designs commanding preference in biopharmaceutical applications.
- Bag Samplers:Gamma-sterilized single-use polymer assemblies with sealed extraction ports eliminate steam-in-place protocols. German monoclonal antibody facilities in Baden-Württemberg deploy these for multi-product bioreactor campaigns where rapid changeover determines throughput economics.
- Vacuum Sampling Devices:Closed-loop vessel systems rated for ISO 5 environments extract representative fluids without breaching containment. Pharmaceutical-grade water treatment verification in US and European facilities drives procurement under EPA and WHO quality frameworks.
- Needle Sampling Devices:Stainless steel cannula with septum-penetration mechanisms for vial and container sampling.
- Syringe Sampling Devices:Pre-sterilized Luer-lock syringes for low-volume analytical extraction in quality control laboratories.
- Cannula Assemblies:Sealed needle-sleeve combinations for bioreactor port integration and cell-culture harvesting.
Bag samplers handle the majority of throughput in biologics manufacturing; vacuum sampling devices are gaining share fastest as water-system monitoring requirements expand.
Technology:
Capital deployment patterns separate mature sterilization methods from emerging automation platforms, with facility scale and labor cost structure determining technology selection.
- Single-Use Systems:Pre-sterilized disposable assemblies eliminate cleaning validation and cross-contamination risk. Contract manufacturing organizations in Ireland and Singapore consolidate procurement around these systems to support multi-product manufacturing campus operations.
- Automated Sampling:Robotic arms with barcode tracking and chain-of-custody logging enable 24/7 extraction schedules. Large-scale cell-culture facilities deploy these to compress process development timelines and reduce human intervention during bioreactor harvesting.
- Closed Sampling Systems:Sealed fluid-path architectures preventing environmental contact.
- Sterile Barrier:Physical separation technologies maintaining ISO 5 equivalence.
- Manual Sampling:Operator-dependent protocols retaining substantial share in food and beverage quality control where capital constraints limit robotics deployment.
Single-use systems dominate procurement volume; automated sampling is expanding most quickly as biopharma facilities pursue continuous manufacturing transitions.
Application:
End-use sector maturity and regulatory stringency create divergent performance requirements, with biopharmaceutical applications setting specifications that cascade into adjacent industries.
- Biopharmaceutical Production:Upstream cell-culture harvesting and downstream purification sampling demand extractables and leachables documentation for every polymer contact surface. EMA Annex 1 contamination control strategy requirements force quality management system restructuring across European facilities.
- Vaccine Development:Fill-finish operations and viral vector production require ultra-low volume aseptic extraction. Autologous cell therapy processing in specialized manufacturing suites opens product development white space distinct from traditional bioreactor applications.
- Food & Beverage Quality Control:Microbiological monitoring of production lines with less stringent validation protocols.
- Water Treatment:Pharmaceutical-grade and WFI system verification under pharmacopeial standards.
- Cosmetic Manufacturing:Sterility assurance for preservative-free and sensitive formulation lines.
Biopharmaceutical production commands the largest equipment investment; vaccine development shows the steepest expansion trajectory as cell and gene therapy manufacturing scales.
End User:
Procurement authority migration from quality departments to manufacturing operations and contract manufacturing organizations restructures vendor relationship economics.
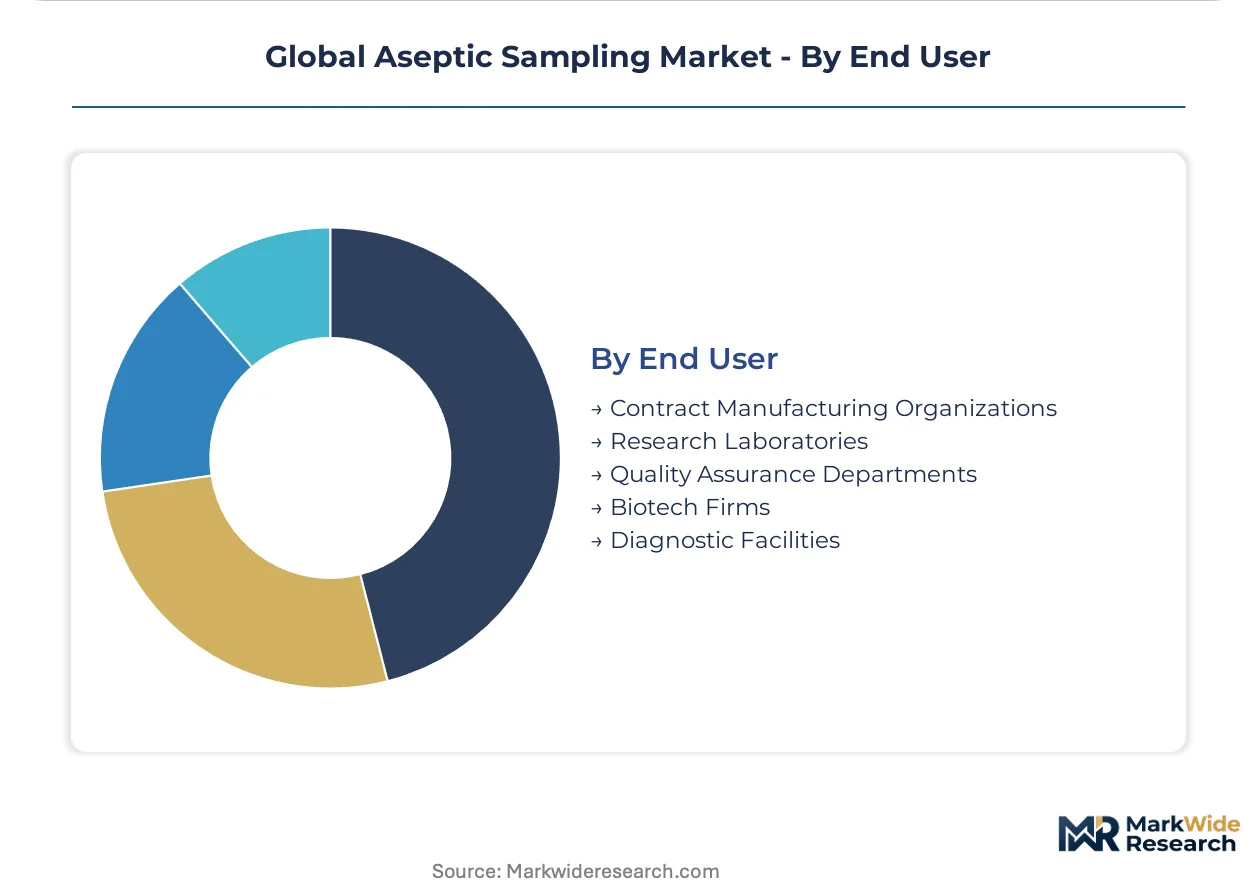
- Contract Manufacturing Organizations:Multi-product biologics facilities negotiate enterprise pricing spanning multiple locations. CMO procurement teams in Ireland and Singapore consolidate vendor relationships around full-line suppliers bundling sampling devices with downstream filtration and analytical instrumentation.
- Biotech Firms:Emerging developers prioritize single-use technology to eliminate infrastructure investment and accelerate technology transfer from clinical to commercial manufacturing stages.
- Research Laboratories:Early-stage process development with flexible, low-volume sampling requirements.
- Quality Assurance Departments:Traditional procurement channels now sharing authority with manufacturing operations.
- Diagnostic Facilities:Clinical laboratory and in-vitro diagnostic manufacturing quality control.
Contract manufacturing organizations drive the highest procurement volume; biotech firms are climbing fastest on share as biosimilar manufacturing expands in India and emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German suppliers of medical-grade fluoropolymer films and gamma-sterilization services anchor supply-side capacity for aseptic sampling hardware. Biopharmaceutical manufacturing clusters in three additional countries generate concentrated procurement demand for closed-system sampling infrastructure.
United States
FDA enforcement of updated Annex 1 sterility guidelines compels biologics producers to replace open sampling methods with validated closed-system alternatives. The EPA pharmaceutical-grade water monitoring frameworks extend procurement for vacuum sampling devices. Greater Boston and San Francisco Bay Area biotech clusters drive sustained demand for automated sampling robotics.
Germany
EMA contamination control strategy documentation requirements force quality management system restructuring across Baden-Württemberg and Bavaria monoclonal antibody facilities. The country's notified body relationships and comprehensive drug master file portfolios attract European procurement concentration. Sartorius AG and Merck KGaA anchor advanced sampling infrastructure serving contract manufacturing organizations.
India
CDSCO regulatory alignment with international GMP standards creates demand for closed-system sampling in emerging large-scale biologics facilities. The PLI scheme for pharmaceuticals incentivizes domestic manufacturing capacity expansion. Hyderabad and Bengaluru biosimilar production clusters generate procurement volume for single-use sampling assemblies.
Singapore
Multi-product biologics manufacturing campuses concentrate vendor relationship consolidation around full-line suppliers bundling sampling devices with downstream filtration. The Health Sciences Authority's GMP inspection regime mirrors FDA and EMA stringency. Tuas Biomedical Park facilities negotiate enterprise pricing spanning multiple global manufacturing locations.
Global Aseptic Sampling Market Competitive Landscape
Concentration sits with diversified life science conglomerates possessing integrated filtration and analytical instrumentation portfolios. The vendor base spans three tiers: full-line platform suppliers, specialized single-use technology developers, and regional sterilization service providers. German and American conglomerates occupy dominant positions through backward integration into polymer manufacturing and gamma irradiation capacity. Competitive moves center on strategic partnerships for extractables and leachables documentation and geographic expansion into Indian and Singaporean CMO corridors.
Among German-based diversified suppliers, Merck KGaA and Sartorius AG exemplify the full-line platform archetype, occupying positions that span membrane manufacturing through final assembly. Thermo Fisher Scientific represents the integrated workflow bundling approach, extending from sampling devices into analytical instrumentation. These three conglomerates anchor vendor relationship consolidation as contract manufacturing organizations pursue single-source procurement contracts.
| Leading Market Players |
|---|
| Merck KGaA |
| Sartorius AG |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Cytiva |
| GEA Group AG |
| Keofitt A/S |
| Pall Corporation |
| Saint-Gobain |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between German fluoropolymer film suppliers and sampling device manufacturers lock in gamma-sterilized bag assembly capacity while anchoring price visibility across multi-year procurement cycles. These arrangements insulate biopharmaceutical CMOs from resin allocation volatility while exposing contract manufacturers to fixed-volume obligations during demand fluctuations.
Pricing Analysis
Volume-discount tiering structures separate enterprise procurement contracts at Irish and Singaporean CMO campuses from spot purchases by emerging Indian biosimilar manufacturers. Three-tier pricing stratifies across validated closed-system assemblies, standard single-use bag samplers, and manual needle devices for quality control laboratories. Cost compression in standard-grade single-use systems is intensifying as Chinese polymer converters expand medical-grade thermoplastic elastomer capacity. Emerging biotech firms in Hyderabad and Bengaluru exhibit the highest price sensitivity, while German monoclonal antibody facilities prioritize certification grade over unit economics.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors constrain just-in-time delivery of gamma-irradiated sampling kits to European biologics facilities facing sterilization service bottlenecks. German and American conglomerates anchor fluoropolymer film and membrane manufacturing, while Chinese and South Korean suppliers dominate medical-grade polymer resin production. Raw material dependencies center on perfluoroalkoxy alkane films, thermoplastic elastomer port seals, and cobalt-60 sterilization isotope availability. Single-source vulnerability concentrates in gamma irradiation capacity across North Atlantic logistics lanes. Distribution runs through authorized distributor networks serving GMP-certified manufacturing campuses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized extractables and leachables documentation capabilities are scarce among sampling device suppliers, creating competitive moats for firms with established notified body relationships and comprehensive drug master file portfolios. This capability gap determines market access velocity across EMA-inspected European facilities.
For Market Incumbents: Fortify backward integration into medical-grade polymer manufacturing to secure resin allocation priority during supply crunches. Expand gamma irradiation captive capacity near Baden-Württemberg biologics clusters to eliminate sterilization service bottlenecks threatening fulfillment timelines. EMA-FDA validation divergence poses persistent certification cost pressure demanding duplicated testing protocol investment. For New Entrants and Emerging Players: CDSCO regulatory fast-track alignment offers entry into Indian biosimilar manufacturing corridors near Hyderabad and Bengaluru. Ultra-low volume aseptic sampling for cell and gene therapy workflows represents the most penetrable white space distinct from entrenched bioreactor sampling incumbents. Target process analytical technology integration partnerships with automated sampling robotics developers as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cap single-use technology specialists with established extractables profiles and EMA notified body relationships represent the priority acquisition archetype. Long-term viability hinges on regulatory certification velocity rather than manufacturing scale alone across the analysis window. Monitor EMA Annex 1 enforcement intensity as the critical inflection signal for closed-system substitution demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Regulatory Fast-Track Certification | Accelerates market entry into Indian PLI scheme biologics manufacturing corridors. |
| Extractables and Leachables Documentation Investment | Secures EMA contamination control strategy compliance for European monoclonal antibody facilities. |
| Gamma Irradiation Capacity Expansion | Eliminates sterilization bottlenecks constraining pre-sterilized sampling kit fulfillment. |
| Process Analytical Technology Integration Partnership | Enables closed-loop control systems for continuous manufacturing transitions at large-scale cell-culture facilities. |
| Cell and Gene Therapy Sampling Portfolio Development | Captures ultra-low volume demand from viral vector production and autologous therapy processing suites. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with biopharmaceutical quality assurance directors, CMO procurement leads, regulatory affairs specialists, and sterilization service operations managers. Secondary validation drew from FDA 483 inspection observations, EMA GMP inspection deficiency databases, CDSCO manufacturing license records, and USP extractables testing protocols. Bottom-up facility-level procurement estimates triangulated against top-down market sizing from polymer resin trade flows and gamma irradiation capacity utilization disclosures.
Across the analysis window, volume and value outputs reflect segmented modeling across product type, technology platform, application sector, and end-user procurement authority. CAGRs were derived from facility expansion announcements, regulatory inspection trend trajectories, and single-use technology adoption curves in multi-product biologics manufacturing. Forecast inputs incorporated EMA Annex 1 compliance timelines, Indian PLI scheme capacity buildout schedules, and cell and gene therapy manufacturing suite commissioning rates.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA-EMA regulatory harmonization pressure and gamma sterilization capacity expansion; material deviation would warrant model refresh. Forecasts incorporate assumptions regarding CDSCO enforcement intensity, polymer resin supply stability, and CMO vendor consolidation velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Aseptic Packaging Market
Aseptic & Retort Packaging
Global Aseptic Paper Packaging Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market
Aseptic & Retort Packaging
Europe Aseptic Packaging Market
Aseptic & Retort Packaging
Latin America Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Carton Bottles Market
Aseptic & Retort Packaging
Plastic Retort Cans Market
Aseptic & Retort Packaging
Aseptic Fillers Market
Aseptic & Retort Packaging
Retort Grade BOPET Films Market
Aseptic & Retort Packaging
Aseptic Containment Systems Market
Aseptic & Retort Packaging
Aseptic Formulation Processing Market
Aseptic & Retort Packaging
North America Retort Packaging Market
Aseptic & Retort Packaging
Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Transfer System Market
Aseptic & Retort Packaging
Aseptic Packaging Equipment Market
Aseptic & Retort Packaging
North America Aseptic Packaging Market