
 Europe BPA Free Plastic Market | 2026-2036
Europe BPA Free Plastic Market Size, Share, and Industry Trends Forecast 2026-2036
Europe BPA Free Plastic Market Analytics
Market Context
Food-grade specification tiers above general-purpose resin grades is collapsing the old commodity-parity model across European polymer supply chains. BASF SE leverages its integrated polyamide and specialty polyester operations to secure feedstock traceability for medical and infant-care applications. Covestro AG anchors its position through high-clarity polycarbonate alternatives engineered for hot-fill bottling lines. Novamont S.p.A. differentiates via compostable bio-polyester platforms that bypass fossil-based BPA chemistry entirely.
Technical Definition and Structural Segments
Europe BPA Free Plastic denotes thermoplastic materials formulated without bisphenol A monomer, typically achieving compliance below 0.05 mg/kg migration limits under EU food-contact frameworks, and serving as structural substitutes in packaging, medical devices, and consumer durables where endocrine disruption risks must be eliminated. Among material categories, Tritan copolyester commands premium positioning in reusable beverage bottles due to its hydrolytic stability and dishwasher durability, while polypropylene dominates unit volume in single-use food containers where cost sensitivity shapes procurement. The food and beverages end-use segment concentrates margin pools around certified-organic and infant-nutrition channels, whereas healthcare applications sustain slower volume growth but tighter specification premiums.
Regulatory Framework and Outlook
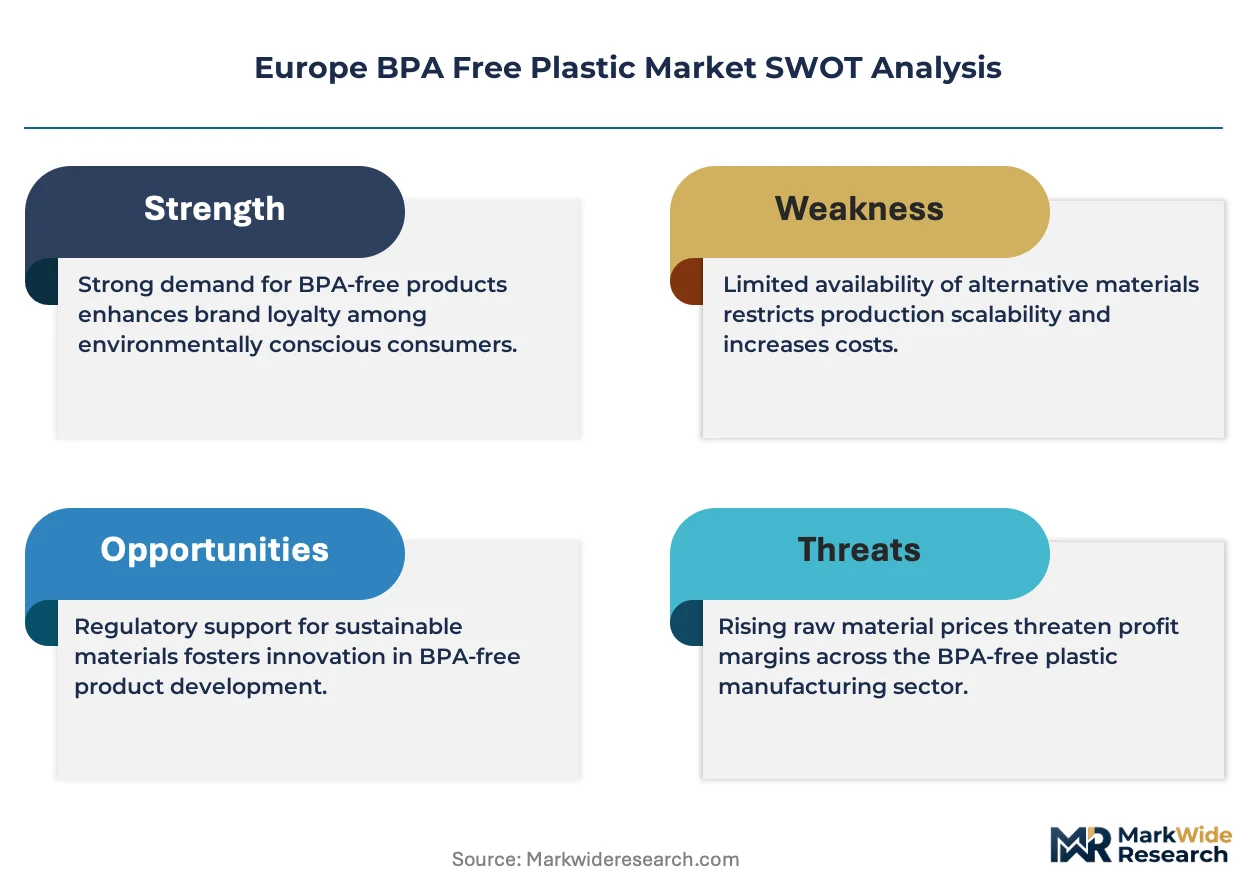
REACH restrictions on bisphenol A in thermal paper and food-contact articles, supplemented by EFSA migration limit enforcement and EU Packaging and Packaging Waste Regulation circularity mandates, collectively redirect formulation roadmaps toward non-BPA chemistries. CE marking under the EU Food Contact Materials Framework Regulation gates market access for imported articles, compelling non-European suppliers to establish certified testing partnerships. Stakeholders must monitor pending revisions to the EU Plastics Regulation as the Commission evaluates broader bisphenol analog restrictions beyond BPA alone.
Market Dynamics
REACH migration limits on bisphenol A in food-contact materials are collapsing legacy polycarbonate formulations across European polymer supply chains, forcing resin producers to rebuild formulation roadmaps around non-BPA chemistries before the 2026 enforcement window closes.
Growth Catalysts
- EFSA Compliance Mandates:Migration thresholds below 0.05 mg/kg under EU food-contact frameworks are compelling packaging converters to certify BPA-free alternatives, creating certified-supplier premiums for compliant resin grades.
- Infant Nutrition Channel Expansion:Bottling lines for baby formula and pediatric supplements across Germany and France are mandating Tritan copolyester to eliminate endocrine disruption liability in premium positioning.
- Hot-Fill Bottling Technology:Beverage manufacturers in Italy and Spain are adopting hydrolytically stable polyester formulations that withstand pasteurization temperatures without BPA-based thermal stability additives.
Market Restraints
- Petrochemical Feedstock Volatility:Propylene and purified terephthalic acid price swings compress margin stability for polypropylene and copolyester producers serving cost-sensitive single-use container markets.
- Specialty Resin Supply Concentration:High-clarity Tritan formulations depend on concentrated capacity at US-based Eastman Chemical facilities, exposing European converters to transatlantic logistics bottlenecks and currency risk.
- Performance Gap in Barrier Properties:Bio-based polylactic acid alternatives exhibit inferior oxygen and moisture barrier performance versus legacy polycarbonate in extended-shelf-life dairy applications.
Strategic Opportunities
- Central and Eastern European Manufacturing:Poland and Romania offer underpenetrated production bases where converters can establish EFSA-certified facilities serving German retail supply chains with lower labor cost structures.
- Compostable Bio-Polyester Platforms:Novamont's Mater-Bi technology demonstrates fossil-free chemistry that bypasses BPA entirely while meeting EU Packaging and Packaging Waste Regulation circularity mandates.
- Medical Device Sterilization Compatibility:Gamma-stable copolyester grades for surgical instrument trays and pharmaceutical packaging command specification premiums in healthcare procurement channels.
Industry Challenges
- Migration Testing Certification Timelines:EFSA notification procedures for novel food-contact substances require 18-24 month evaluation periods, delaying product launches and freezing R&D budgets in uncertainty.
- Polymer Processing Retrofit Costs:Hot-runner mold systems and drying equipment designed for polycarbonate require capital-intensive reconfiguration to handle copolyester viscosity profiles and moisture sensitivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe BPA Free Plastic Market |
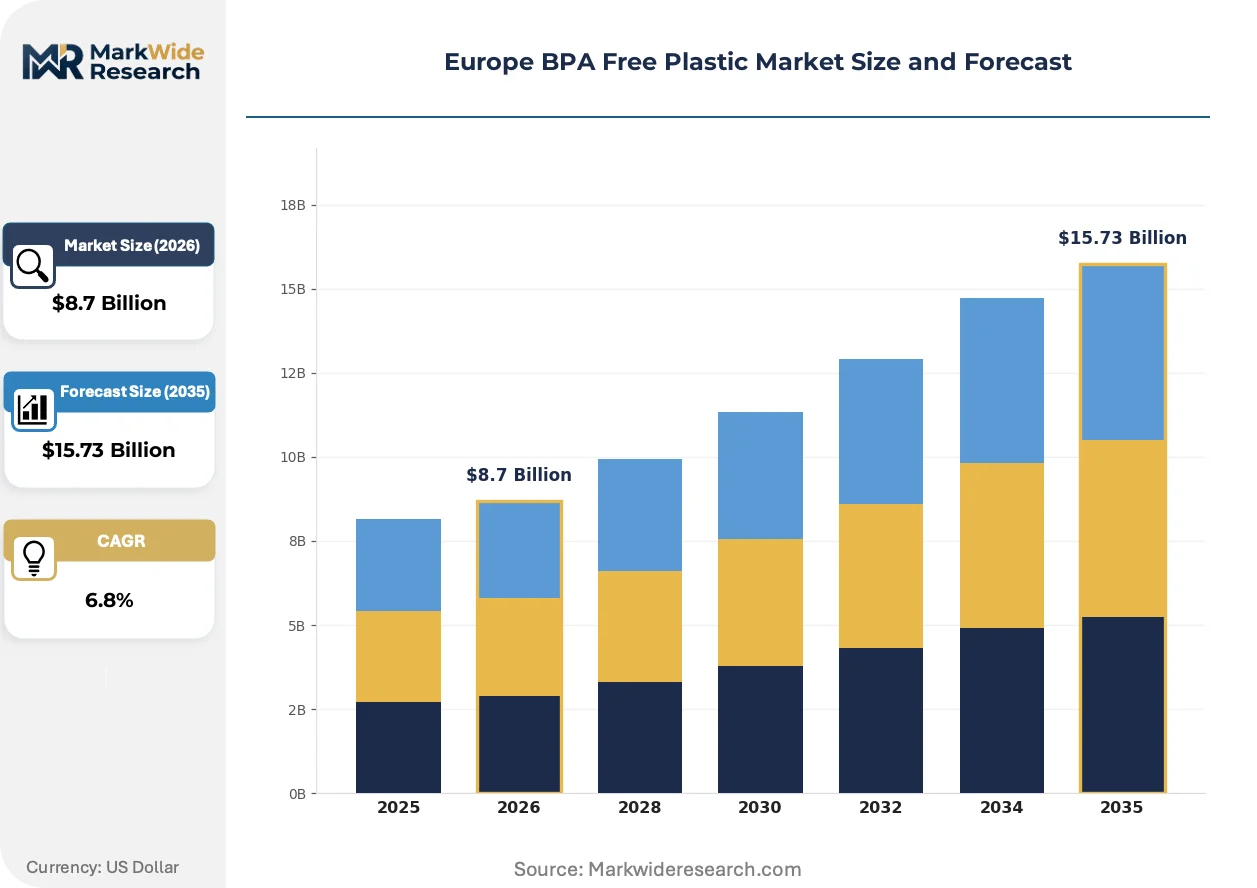
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Cups, Utensils End Use Industry: Food & Beverages, Healthcare, Consumer Goods, Automotive Material: Polyethylene, Polypropylene, Polystyrene, Tritan Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | BASF SE, Amcor plc, Eastman Chemical Company, DuPont de Nemours, Inc., Covestro AG, Tetra Pak International SA, Mondi PLC, Novamont S.p.A., Avantium N.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe BPA Free Plastic Market Evolving Landscape
Tritan copolyester is displacing legacy polycarbonate across European beverage packaging, while regulatory pressure expands beyond BPA to encompass structural analogs, and procurement patterns favor certified-supplier consolidation over spot-market resin purchasing.
Tritan copolyester delivers hydrolytic stability and dishwasher durability without BPA monomer content. Premium reusable bottle manufacturers in Germany and Scandinavia are converting production lines at accelerated pace to capture organic-certified retail placement. This material is displacing polycarbonate in hot-fill and reusable segments where clarity and thermal resistance previously demanded bisphenol A chemistry.
REACH restrictions now explicitly target bisphenol S and bisphenol F analogs in food-contact articles, closing the regulatory loophole of structural substitution. The European Commission's pending revision to the Plastics Regulation signals broader bisphenol family restrictions. Medical device and infant-care segments face the tightest compliance timelines, with notified bodies accelerating CE marking audits for alternative material dossiers.
Retail-led certification requirements are consolidating supplier relationships around EFSA-compliant resin producers with established testing partnerships. German and French supermarket chains now mandate third-party BPA-free documentation for private-label packaging, displacing spot-market purchasing behaviors. This concentration is most visible in organic and infant-nutrition channels where liability exposure drives zero-tolerance procurement policies.
Europe BPA Free Plastic Market Segmentation
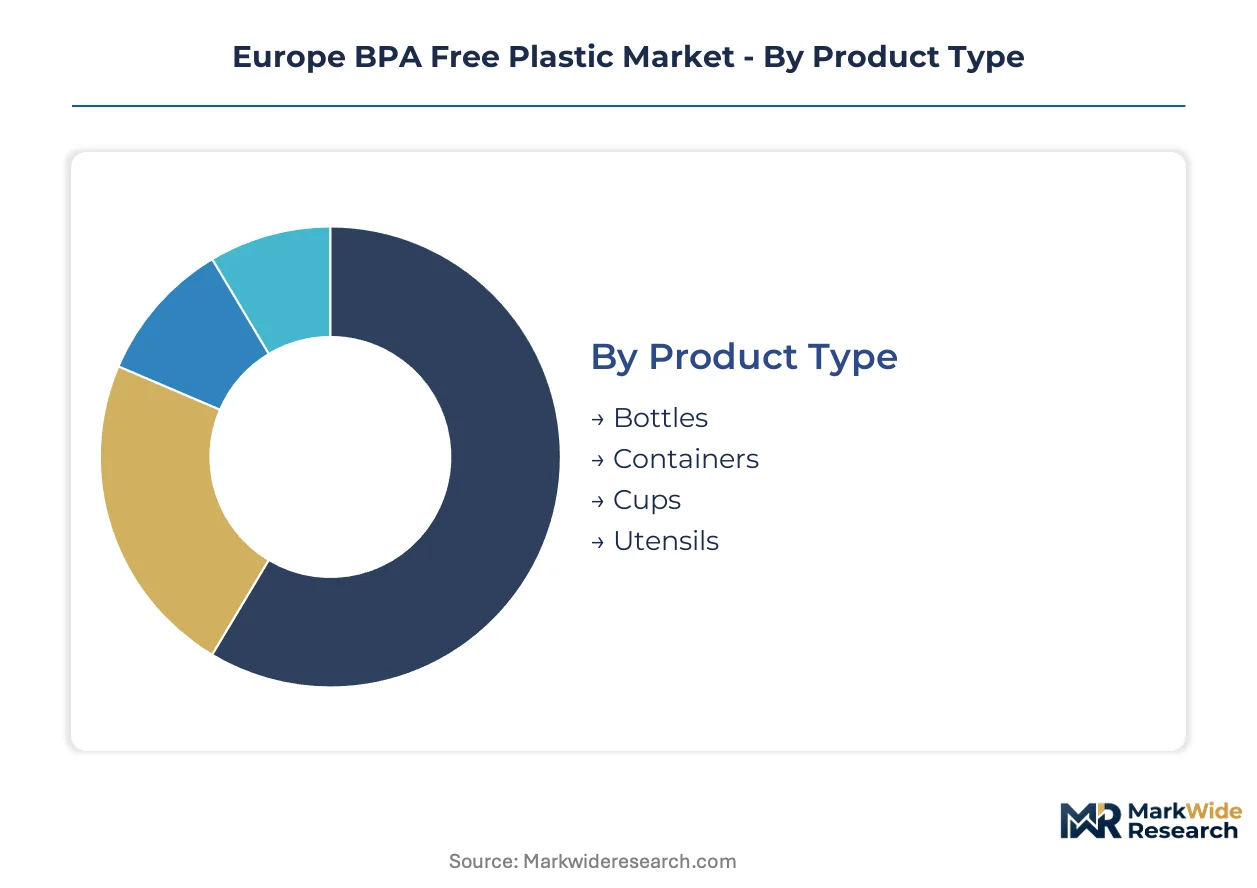
European BPA-free plastic procurement patterns diverge sharply across material grades and end-use specifications, with REACH compliance timelines forcing converters to requalify entire product portfolios simultaneously. Segmentation discipline separates margin-accretive medical and infant-care channels from commoditized single-use foodservice applications where cost pressure dominates supplier selection.
Product Type:
Bottles face the most acute substitution pressure as beverage manufacturers abandon polycarbonate for hot-fill and reusable formats under tightening EFSA migration limits.
- Bottles:Tritan copolyester formulations now dominate premium reusable and hot-fill segments across German and Italian bottling lines, though polypropylene retains share in cost-sensitive single-use water bottles. Dairy and infant-formula brands in France mandate certified BPA-free documentation for all bottle procurement.
- Containers:Polypropylene-based food storage and takeaway containers command unit volume across European quick-service restaurant supply chains, with EFSA-compliant grades capturing supermarket private-label placement. Deli and prepared-meal segments in Spain and Poland drive specification premiums for clarified random copolymer grades.
- Cups:Polystyrene alternatives face declining demand as France and Germany implement single-use plastic bans, pushing converters toward polypropylene or paper-lined barrier structures for cold beverages.
- Utensils:Compostable bio-polyesters from Novamont and similar suppliers penetrate institutional catering contracts in Italy and Scandinavia where EU Packaging and Packaging Waste Regulation circularity mandates shape procurement.
Containers retain volume leadership across European BPA-free plastic consumption; bottles hold the steepest expansion curve as beverage brands accelerate polycarbonate phase-outs.
End Use Industry:
Margin concentration follows liability exposure, with infant-nutrition and medical device channels sustaining specification premiums that offset raw material cost volatility.
- Food & Beverages:Packaging converters serving German and French retail chains face mandatory third-party BPA-free certification for all food-contact articles, collapsing spot-market purchasing behaviors. Organic-certified and premium positioning segments absorb Tritan copolyester price premiums more readily than private-label mass-market lines.
- Healthcare:Gamma-sterilizable copolyester grades for surgical instrument trays and pharmaceutical packaging command tight specification premiums, with CE marking under EU Medical Device Regulation gating market access. Medical device manufacturers in Switzerland and Germany consolidate supplier relationships around EFSA-compliant resin producers with established migration testing partnerships.
- Consumer Goods:Reusable water bottle and food storage segments in Scandinavia and Benelux favor Tritan clarity and dishwasher durability, though polypropylene competes aggressively on price in discount retail channels.
- Automotive:Interior trim and under-hood applications represent a minor share of BPA-free specification demand, with polycarbonate alternatives in headlamp lenses and instrument clusters facing separate material qualification timelines.
Food & Beverages dominates absolute consumption volume; Healthcare delivers the most stable margin profile through sterilization-grade material premiums.
Material:
Supply concentration and feedstock volatility create divergent risk profiles across polymer chemistries, with specialty polyester capacity constraints limiting Tritan penetration in cost-sensitive segments.
- Polyethylene:Low-density grades serve flexible food packaging and film applications across Southern European converting bases, though barrier limitations restrict use in extended-shelf-life dairy.
- Polypropylene:Random and impact copolymer formulations capture the largest share of European BPA-free plastic volume, with clarified grades displacing polystyrene in deli containers and thermoformed cups. Propylene price volatility from naphtha-cracker economics compresses margin stability for converters serving single-use markets.
- Polystyrene:General-purpose and high-impact grades face structural decline as France, Germany, and Italy implement single-use plastic restrictions and BPA-analog scrutiny expands to bisphenol S and F under REACH revisions.
- Tritan:Eastman Chemical's copolyester delivers hydrolytic stability and hot-fill performance without BPA, BPS, or BPF content, anchoring premium positioning in reusable beverage and infant-care segments. European converters depend on transatlantic supply chains, exposing procurement to logistics bottlenecks and currency risk.
Polypropylene maintains volume leadership across all BPA-free material categories; Tritan captures the most rapid share gains in premium positioning segments.
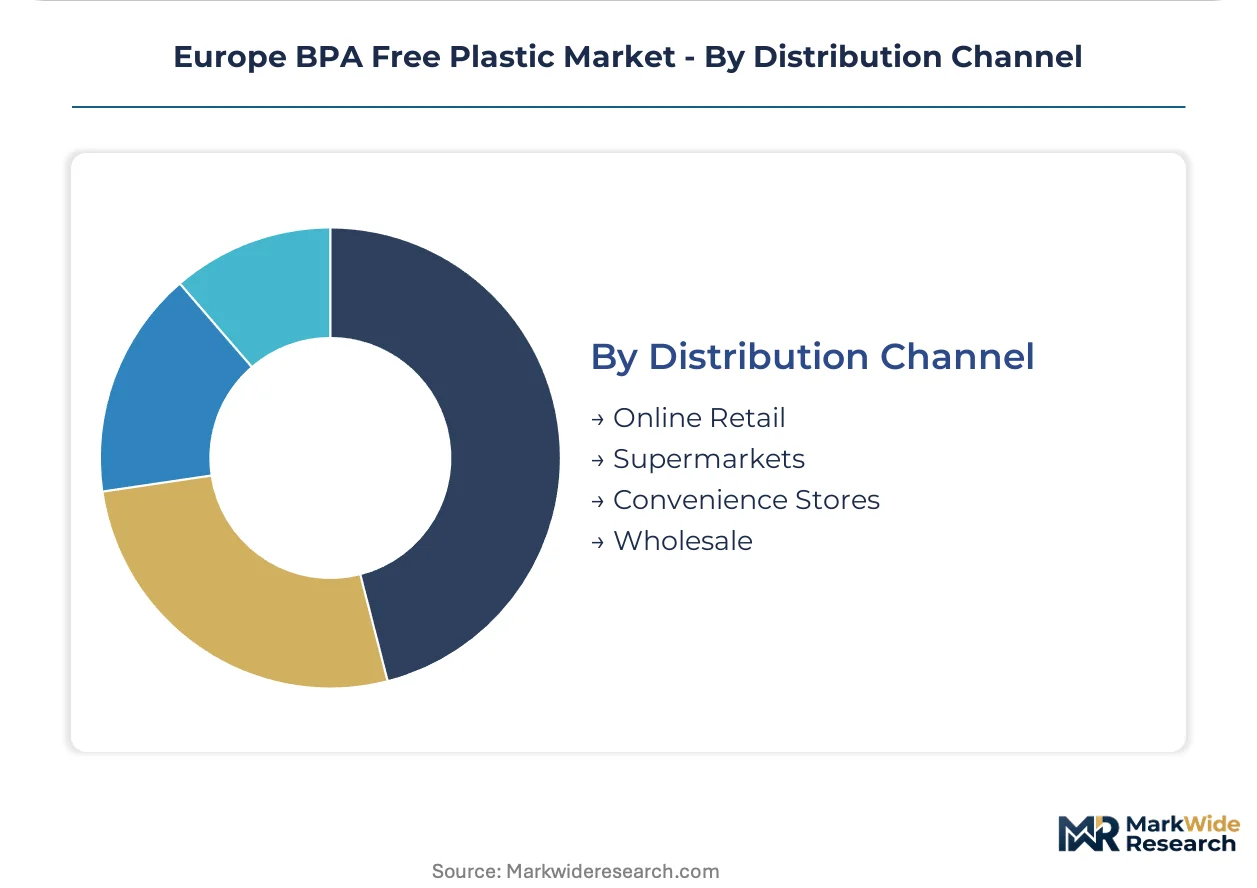
Distribution Channel:
Certification requirements and traceability mandates are restructuring channel economics, with EFSA-compliant documentation becoming a non-negotiable entry ticket for retail-facing supply chains.
- Online Retail:Direct-to-consumer brands in Germany and the UK leverage digital channels to market premium reusable bottle lines with transparent BPA-free messaging, bypassing traditional retail listing fees.
- Supermarkets:German and French supermarket chains now mandate third-party BPA-free documentation for all private-label packaging, consolidating supplier relationships around certified resin producers and displacing spot-market purchasing. Organic and infant-nutrition shelf sets enforce zero-tolerance procurement policies.
- Convenience Stores:Single-use foodservice items in high-traffic urban locations favor low-cost polypropylene over specialty alternatives, with price sensitivity limiting Tritan penetration.
- Wholesale:Institutional catering and foodservice distributors in Italy and Spain bundle BPA-free certification with volume commitments, locking converters into multi-year supply agreements.
Supermarkets anchor the highest-value procurement channel through certification mandates; online retail is climbing fastest as direct-to-consumer brands capture premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European BPA-free plastic trade flows reveal a structural deficit in specialty copolyester grades, with German and French converters importing Tritan formulations from transatlantic suppliers while exporting surplus polypropylene compounds to Central European processors. This imbalance shapes regional capacity investment decisions.
Germany
Infant-formula bottling lines in Bavaria and North Rhine-Westphalia mandate Tritan copolyester procurement to eliminate endocrine disruption liability, while REACH enforcement by ECHA accelerates polycarbonate phase-outs across food-contact applications. The Frankfurt-Rhine-Main polymer cluster hosts migration testing laboratories certifying EFSA compliance for export-bound packaging.
France
Supermarket chains including Carrefour and Auchan enforce third-party BPA-free documentation for all private-label packaging, collapsing spot-market purchasing behaviors in favor of certified-supplier consolidation. ANSM oversight of food-contact materials tightens scrutiny on bisphenol S and F analogs beyond baseline BPA restrictions. The Lyon-Saint-Étienne corridor concentrates dairy packaging conversion capacity serving organic-certified retail channels.
Italy
Hot-fill bottling technology adoption in Emilia-Romagna and Lombardy drives hydrolytically stable polyester demand for pasteurized beverage applications where thermal resistance previously required BPA-based additives. Novamont's Mater-Bi production in Novara anchors compostable bio-polyester supply for institutional catering contracts meeting EU Packaging and Packaging Waste Regulation mandates. Milan-based design houses influence premium reusable bottle aesthetics across European markets.
Spain
Quick-service restaurant supply chains in Madrid and Barcelona favor clarified polypropylene for takeaway containers, balancing cost sensitivity against EFSA migration limit compliance. The Valencia port complex handles import logistics for Asian resin suppliers serving Iberian converting bases. Andalusian olive oil bottlers are converting to BPA-free formats ahead of 2026 REACH enforcement deadlines.
Poland
Central European manufacturing expansion targets German retail supply chains with lower labor cost structures, with Warsaw and Łódź emerging as EFSA-certified production bases for export-bound food packaging. The country's petrochemical integration via PKN Orlen provides feedstock security for polypropylene compounders serving cost-sensitive single-use markets. Poznań-based converters specialize in thermoformed deli containers for Western European supermarket private-label programs.
Europe BPA Free Plastic Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and feedstock integration. BASF SE and Covestro AG anchor the publicly traded tier with integrated polyamide and specialty polyester operations, while family-held compounders and regional converters occupy mid-market positions. Three archetypes dominate: petrochemical majors with backward integration into purified terephthalic acid and propylene feedstocks; specialty resin innovators holding proprietary copolyester formulations; and packaging converters with established EFSA testing partnerships. Competitive moves concentrate on multi-year supply agreements locking in certified resin allocation, and geographic expansion into Central European manufacturing bases.
Within the petrochemical major tier, BASF SE and Covestro AG exemplify integrated operators securing feedstock traceability for medical and infant-care applications. Among specialty resin innovators, Eastman Chemical Company occupies a position as the concentrated capacity source for Tritan copolyester formulations. Novamont S.p.A. represents the bio-based alternative archetype with fossil-free chemistry bypassing bisphenol structures entirely.
| Leading Market Players |
|---|
| BASF SE |
| Amcor plc |
| Eastman Chemical Company |
| DuPont de Nemours, Inc. |
| Covestro AG |
| Tetra Pak International SA |
| Mondi PLC |
| Novamont S.p.A. |
| Avantium N.V. |
| Others |
Value Network & Pricing Analysis
Multi-year offtake agreements between German beverage converters and Eastman Chemical lock in Tritan copolyester allocation while capping price volatility exposure, embedding REACH compliance premiums directly into contract structures ahead of 2026 enforcement deadlines.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium Tritan grades, certified polypropylene compounds, and commodity resin tiers. EFSA migration testing certification and hot-fill thermal stability separate pricing bands, with cost compression in standard polypropylene intensifying due to propylene feedstock volatility. Private-label supermarket procurement shows highest price sensitivity, while infant-nutrition bottling lines absorb premiums for liability protection.
Supply Chain Analysis
Germany and France concentrate high-specification conversion capacity for EFSA-certified food packaging, while the United States anchors Tritan copolyester production. European converters draw from purified terephthalic acid and propylene feedstocks subject to naphtha-cracker economics. Single-source vulnerability in specialty polyester grades exposes procurement to transatlantic logistics chokepoints. Distribution runs through supermarket private-label supply chains and institutional catering distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH migration limits on bisphenol A analogs are accelerating material substitution across European polymer supply chains, creating a high-growth disruption as converters rebuild formulation portfolios around certified non-BPA chemistries.
For Market Incumbents: Compound certification depth through EFSA testing laboratory partnerships in Frankfurt-Rhine-Main and Lyon-Saint-Étienne corridors, locking out spot-market competitors. Anchor backward integration into propylene feedstocks via Central European manufacturing bases in Poland to defend margin position against resin price volatility. For New Entrants and Emerging Players: Lead with compostable bio-polyester platforms serving Italian institutional catering contracts where EU Packaging and Packaging Waste Regulation circularity mandates create procurement preference. Target underpenetrated Central European production bases in Romania for EFSA-certified facilities serving German retail supply chains. For Investors and Strategic Acquirers: The market sits at a regulatory-enforcement phase that favors specialty resin innovators with proprietary copolyester formulations and established migration testing dossiers. Long-term viability hinges on diversification beyond bisphenol chemistry entirely. Watch pending EU Plastics Regulation revisions targeting structural analogs as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Certification Investment | Establishes market access for food-contact applications under REACH enforcement timelines. |
| Central European Manufacturing Expansion | Captures labor cost advantages in Poland and Romania for German retail supply chains. |
| Compostable Bio-Polyester Platform Development | Bypasses fossil-based BPA chemistry while meeting EU circularity mandates through Novamont-type innovation. |
| Long-term Resin Supply Agreements | Locks in Tritan copolyester allocation from Eastman Chemical amid transatlantic supply concentration. |
| Hot-Fill Bottling Technology Partnership | Enables pasteurization-grade thermal stability without BPA-based additives in Italian beverage markets. |
Research Methodology
A spread of perspectives from polymer plant managers, EFSA compliance officers at packaging converters, supermarket category buyers, and resin procurement leads converged on the working assumptions. Primary fieldwork combined with secondary validation from REACH regulatory filings, ECHA substance dossiers, Cefic industry statistics, and customs trade data. Bottom-up volume modeling triangulated against top-down market sizing across material grades and end-use segments.
Segmentation dimensions modeled include material chemistry tier, food-contact certification level, end-use industry specification, and regional production hub concentration. CAGRs were derived from trend extrapolation of substitution rates and regulatory enforcement phasing across the projection horizon. Forecast inputs incorporated propylene price elasticity and EFSA notification timeline delays for novel food-contact substances.
Forecasts assume regulatory continuity in REACH and EU Food Contact Materials frameworks; material policy shifts expanding bisphenol analog restrictions would require re-modeling. Specific risk factors include feedstock price volatility and transatlantic logistics disruption. Recalibration cycles align with material shifts in EFSA migration limit enforcement and EU Plastics Regulation revision timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
HDPE Jug Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
Global Plastic Container Market
Plastic Packaging
South Africa Rigid Plastic Packaging Market
Plastic Packaging
Egypt Plastic Bottles Market
Plastic Packaging
United Kingdom Plastic Packaging Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
Europe Plastic Bottles Market
Plastic Packaging
Europe Plastic Packaging Films Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
Saudi Arabia Plastic Packaging Market
Plastic Packaging
Egypt Plastic Packaging Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
North America PET Bottle Market