
 Europe Pet Food Packaging Market | 2026-2036
Europe Pet Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pet Food Packaging Market Intelligence
Italian flexible packaging production is hardening as converters expand mono-material capacity for pet food applications. Amcor plc leverages its European film extrusion network to supply high-barrier laminates for wet food retort pouches. Mondi Group anchors sustainable paper-based solutions through its Advantage StretchWrap replacement programs. Constantia Flexibles specializes in aluminum-light barrier webs for sensitive nutritional formulations.
Europe Pet Food Packaging encompasses primary and secondary containment systems engineered to preserve organoleptic properties, prevent oxidation, and withstand distribution stress across varied climatic conditions; multilayer coextrusion and metallization dominate oxygen barrier specifications, while digital printing enables batch-level traceability mandated by the EU Feed Hygiene Regulation. Flexible Bags occupy the largest volume share due to their cost efficiency in dry kibble distribution, though Pouches command premium positioning in single-serve wet food segments where convenience drives repurchase behavior. Biodegradable materials represent the fastest-evolving category as brand owners respond to retailer sustainability scorecards, yet Plastic retains structural dominance in moisture-sensitive applications where polyethylene terephthalate glycol barriers remain technically indispensable.
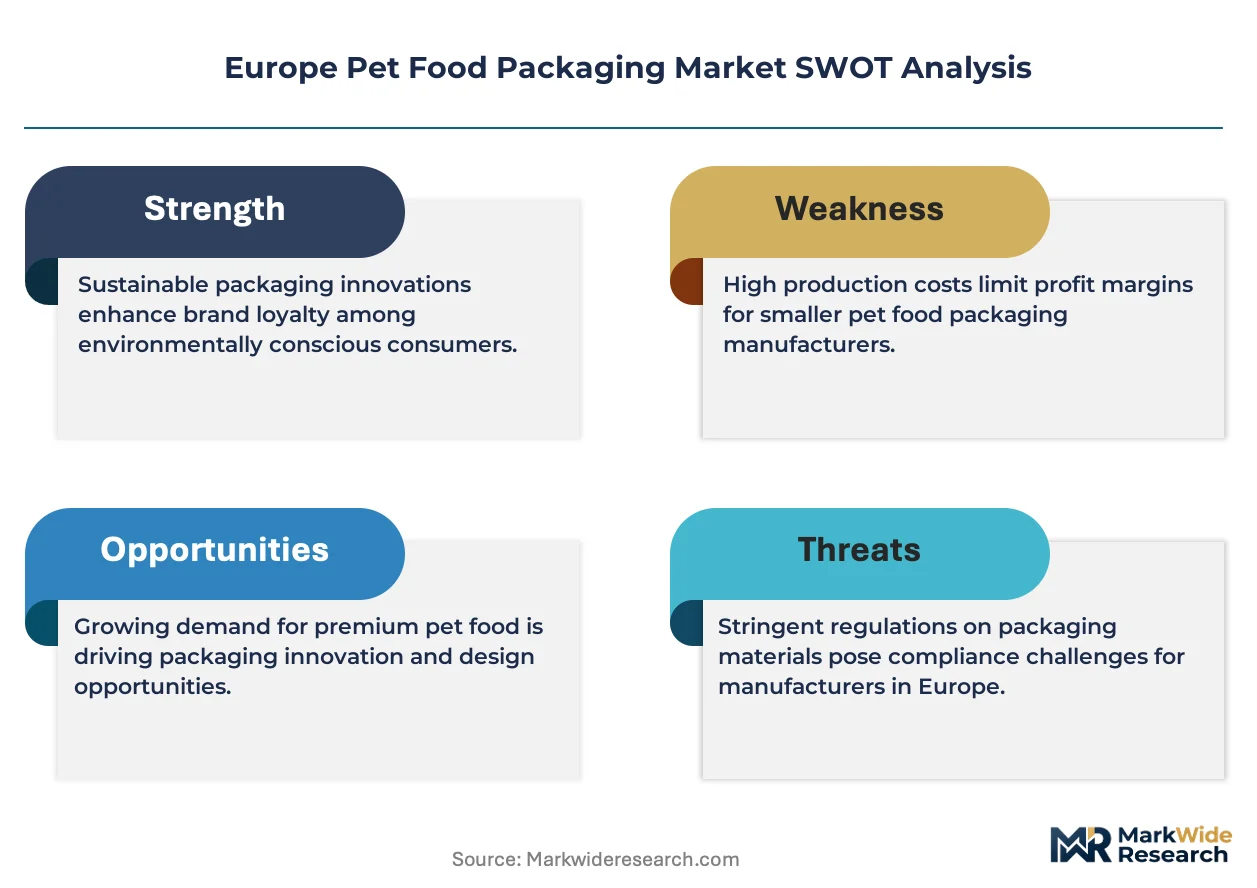
The EU Packaging and Packaging Waste Regulation (PPWR) and the REACH framework administered by ECHA are reshaping material compliance obligations, with extended producer responsibility schemes now requiring recyclability design verification before market placement. EFSA guidelines on food contact materials further constrain additive migration limits for fat-rich pet food matrices, compelling reformulation of sealant layers. Stakeholders must monitor delegated acts under the PPWR implementing recyclability performance grades, as these will determine which packaging formats retain shelf access across major European retail banners.
Market Dynamics
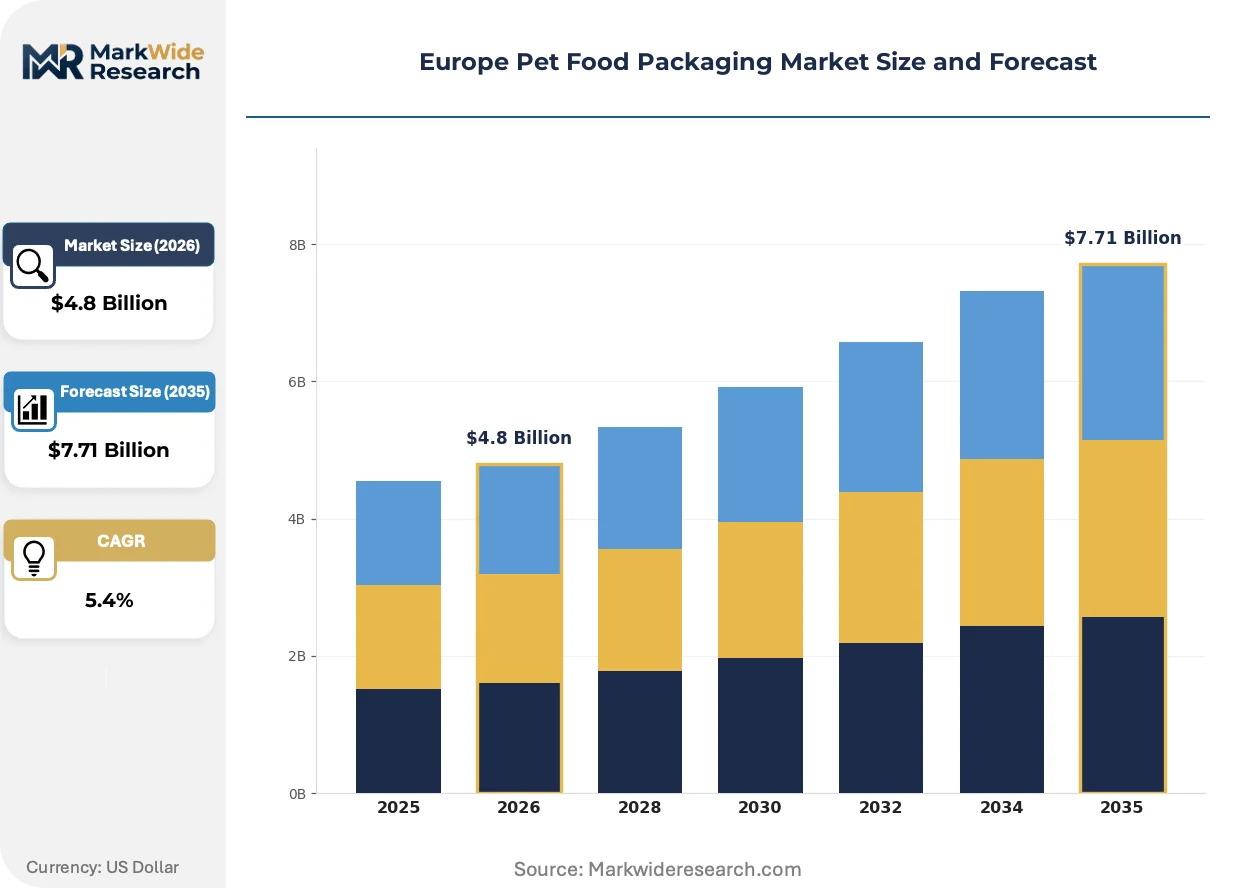
The EU Packaging and Packaging Waste Regulation (PPWR) is forcing a wholesale material transition across European pet food packaging, compelling converters to redesign multilayer structures for recyclability while maintaining barrier performance for moisture-sensitive formulations.
Growth Catalysts
- Mono-material flexible films:German and French converters are expanding extrusion capacity for polyethylene-based barrier webs that satisfy PPWR recyclability grades without aluminum lamination.
- REACH framework compliance:ECHA-mandated additive migration limits for fat-rich matrices are accelerating sealant layer reformulation investments among specialty film suppliers.
- Urban pet humanization:Premium wet food pouch demand concentrates in Paris, Berlin, and Milan metropolitan zones where single-serve convenience commands shelf space.
Market Restraints
- Aluminum price volatility:Metallized barrier web costs fluctuate with London Metal Exchange aluminum ingot pricing, squeezing converter margins on mid-tier dry food bags.
- Recyclability verification delays:Extended producer responsibility schemes under PPWR delegated acts require third-party recyclability testing before market placement, extending new product launch timelines.
- Biodegradable performance gaps:Polylactic acid and starch-based films lack the oxygen barrier specifications required for retort wet food applications, limiting material substitution.
Strategic Opportunities
- Poland and Romania underpenetration:Pet humanization rates trail Western Europe by 40-60 percentage points, creating white space for premium pouch formats as disposable incomes converge.
- Digital printing integration:HP Indigo and Xeikon press installations enable batch-level traceability compliance with EU Feed Hygiene Regulation while reducing plate changeover waste.
- Paper-based secondary packaging:Mondi Group's Advantage StretchWrap replacement programs demonstrate kraft paper substitution potential for pallet containment in ambient distribution.
Industry Challenges
- Multi-layer delamination expertise:Separating polyethylene, polyethylene terephthalate glycol, and ethylene vinyl alcohol layers for mechanical recycling requires specialized sorting infrastructure that remains scarce in Eastern European recovery facilities.
- Retort pouch line conversion:Shifting from aluminum-containing laminates to mono-material structures demands capital expenditure on modified sealing jaws and sterilization validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pet Food Packaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Bags, Rigid Containers, Pouches, Boxes Material: Plastic, Paper, Metal, Biodegradable End User: Retailers, E-Commerce Platforms, Pet Stores, Wholesalers Closure Type: Zip Lock, Heat Seal, Screw Cap, Easy Open |
| Companies Covered | Amcor plc, Mondi Group, Constantia Flexibles, Berry Global Group, Inc., Sonoco Products Company, Huhtamaki Oyj, Smurfit Kappa, Ardagh Group S.A., Coveris Holding S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pet Food Packaging Market Strategic Shifts & Innovations
Digital traceability requirements and material circularity mandates are converging to reshape specification standards across European pet food packaging, with converter R&D programs prioritizing barrier performance retention within single-substrate designs.
High-barrier mono-material coextrusion is unifying oxygen and moisture protection within polyethylene or polypropylene substrates, eliminating aluminum foil dependencies. Wet food brand owners in France and Germany are qualifying these structures for retort applications at accelerated timelines. This unification is compressing the addressable market for traditional metallized laminates while expanding the qualified supplier base for EPR-compliant packaging.
EFSA guidelines on food contact materials are tightening additive migration thresholds for sealant layers contacting fat-rich pet food matrices. Compounders must reformulate slip agents and antioxidants to satisfy updated specific migration limits, particularly for cat food formulations with elevated lipid content. Sensitive nutritional products targeting veterinary prescription channels face the most stringent compliance burdens.
Urban pet owners are consolidating purchases through subscription direct-to-consumer channels that demand single-serve portion formats. Premium wet food pouches displace multi-serve cans in Paris and Berlin household penetration, with repurchase cycles compressing from monthly stock-ups to weekly replenishment. This behavioral shift elevates convenience-driven packaging specifications over unit cost optimization.
Europe Pet Food Packaging Market Segmentation
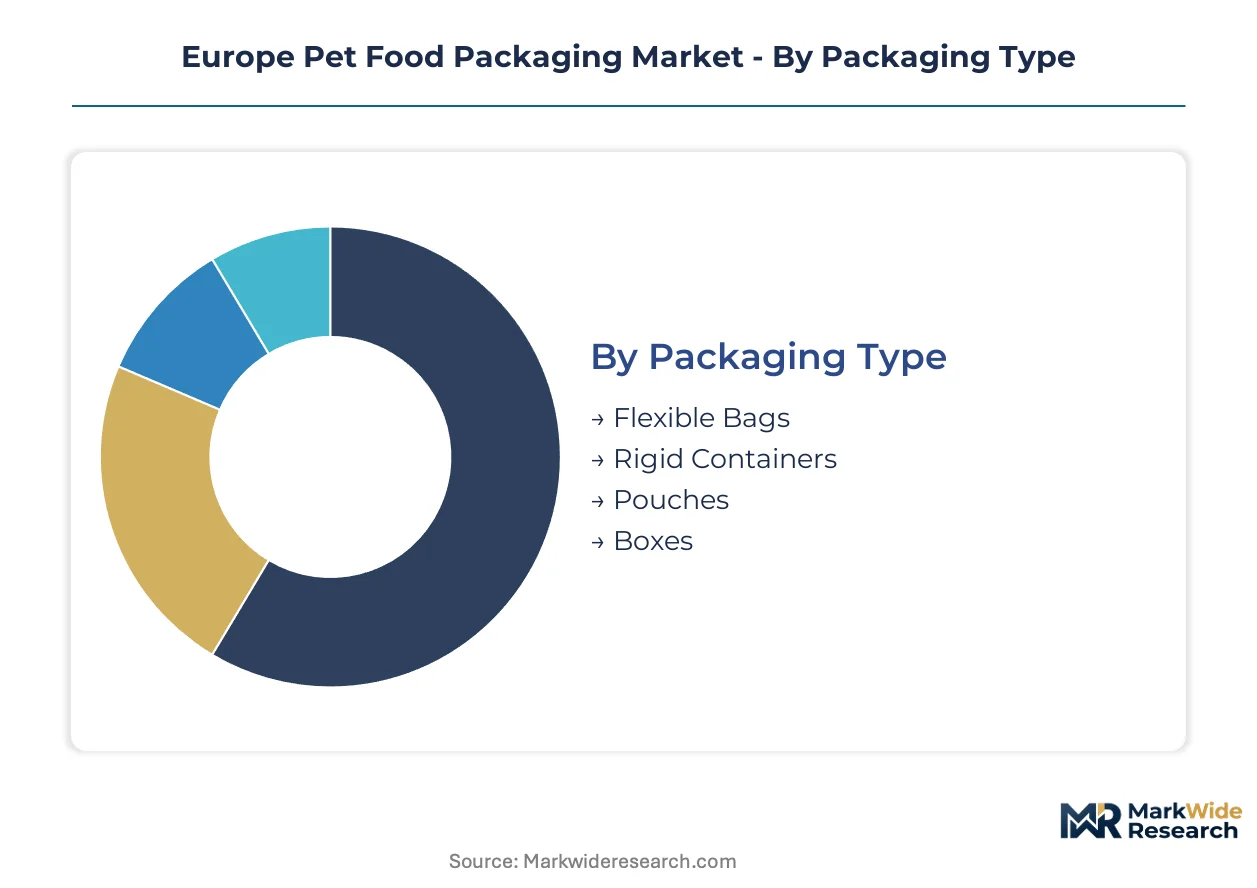
Packaging specification choices in European pet food distribution cascade through capital allocation, regulatory compliance, and shelf-access negotiations with major retail banners. Material and format selections determine converter investment priorities and brand owner sustainability positioning under PPWR mandates.
Packaging Type:
Capital intensity varies sharply across formats, with retort-capable pouch lines demanding 3-4x the extrusion and sealing equipment investment of standard flexible bag operations.
- Flexible Bags:Multilayer coextruded polyethylene or polypropylene webs dominate dry kibble distribution through German and French mass retail. Mono-material variants are displacing metallized laminates as PPWR recyclability grades tighten. Most installed capacity flows through Flexible Bags. Expansion is steepest in Pouches.
- Pouches:Stand-up and flat retort structures with high-barrier ethylene vinyl alcohol coextrusion serve single-serve wet food segments in Paris and Berlin metropolitan zones. Sealing jaw precision and sterilization validation protocols elevate line conversion costs. Convenience-driven repurchase behavior concentrates demand among urban pet owners.
- Rigid Containers:Injection-molded polyethylene terephthalate or polypropylene tubs with in-mold labels protect premium fresh and frozen formulations. Tooling costs for thin-wall designs run substantial, limiting adoption to high-margin veterinary prescription channels.
- Boxes:Corrugated and solid board secondary packaging consolidates multi-unit shipments for e-commerce fulfillment centers. Digital printing integration enables batch traceability compliance with minimal plate investment.
Flexible Bags absorb the majority of polyethylene extrusion capacity across Italian and German converter networks. Pouch qualification timelines are compressing as wet food brand owners accelerate mono-material transitions.
Material:
Cost tier stratification separates commodity substrates from engineered barrier solutions, with sustainability premiums widening spreads between plastic dominance and biodegradable alternatives.
- Plastic:Polyethylene, polypropylene, and polyethylene terephthalate glycol multilayers retain structural control in moisture-sensitive wet food applications. EFSA-mandated additive migration limits for fat-rich matrices compel sealant layer reformulation investments. EPR scheme compliance verification extends new product launch timelines.
- Biodegradable:Polylactic acid and starch-based films from specialty compounders target dry treat segments where oxygen sensitivity is moderate. Performance gaps in retort barrier specifications constrain substitution rates despite retailer sustainability scorecard pressure.
- Paper:Kraft-based secondary packaging and primary barrier boards with dispersed polymer coatings serve ambient distribution and premium dry food positioning. Mondi Group's stretch wrap replacement programs demonstrate pallet containment viability.
- Metal:Aluminum-light barrier webs and steel cans preserve ultra-sensitive nutritional formulations in veterinary channels. London Metal Exchange price volatility squeezes converter margins on mid-tier applications.
Plastic commands the largest volume position. Biodegradable materials are gaining share fastest in dry treat and snack segments where barrier demands permit.
End User:
Customer type determines order fragmentation, with direct-to-consumer channels compressing batch sizes and elevating digital printing requirements against pallet-scale wholesale efficiency.
- Retailers:Carrefour, REWE, and Auchan banners impose PPWR recyclability grades and sustainability scorecards that filter supplier qualification. Private label penetration drives flexible bag standardization.
- E-Commerce Platforms:Zooplus and Amazon subscription channels demand single-serve pouch formats with batch-level traceability for weekly replenishment cycles. Packaging must withstand individual shipment stress without secondary containment.
- Pet Stores:Fressnapf and Maxi Zoo specialty chains prioritize premium positioning with transparent windows and tactile finishes that support in-store discovery.
- Wholesalers:Metro and cooperative buying groups concentrate dry food volume in bulk flexible formats optimized for pallet efficiency and warehouse automation.
Retailers concentrate the largest procurement volume. E-Commerce Platforms are expanding most quickly as subscription penetration deepens.
Closure Type:
Application context dictates resealability investment, with multi-serve dry food formats justifying zip lock complexity against single-serve wet food heat seal simplicity.
- Heat Seal:Peelable and permanent sealant layers dominate retort pouch and flexible bag production, with ethylene vinyl alcohol coextrusion ensuring hermetic integrity through sterilization cycles.
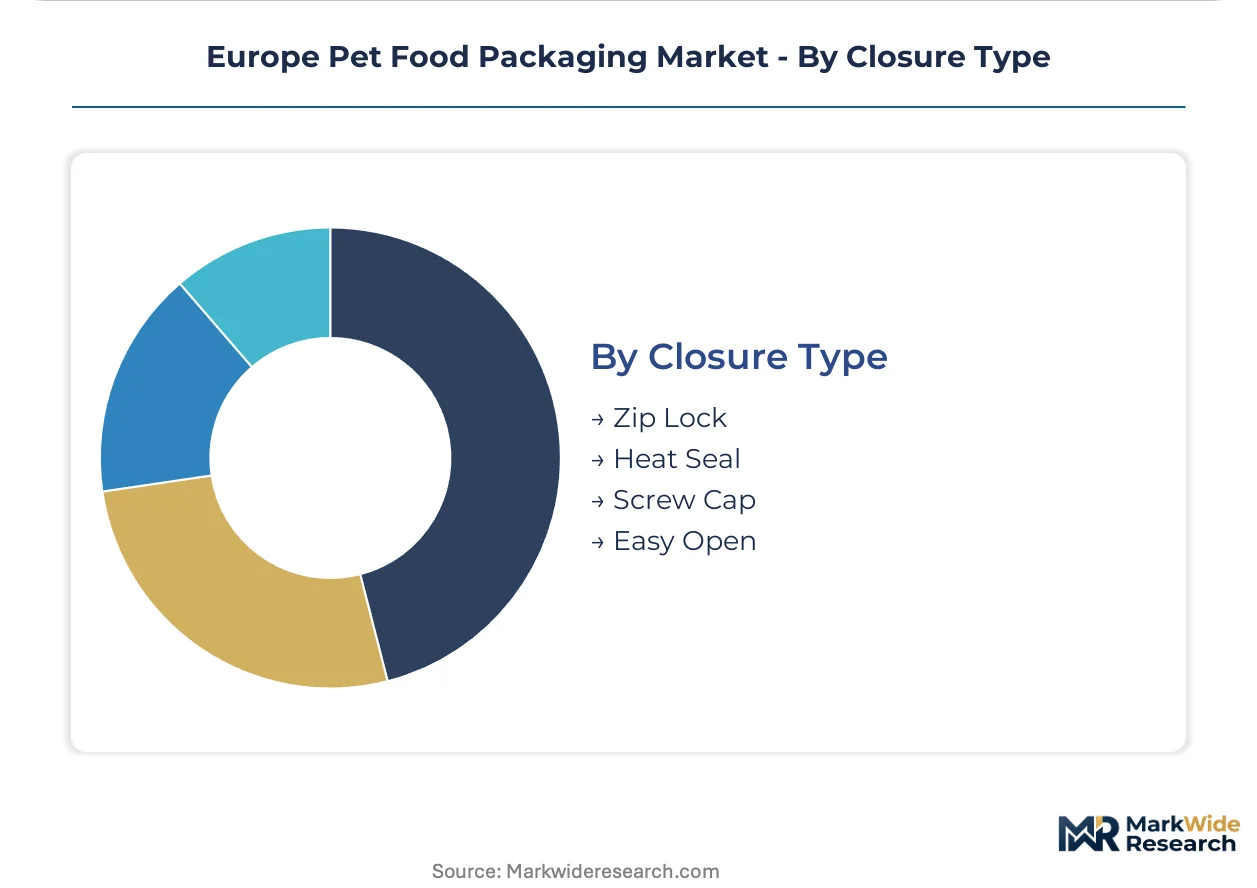
- Zip Lock:Press-to-close profiles with slider variants add 15-25% material cost to flexible bags, justified by kibble freshness preservation in multi-serve household formats.
- Screw Cap:Injection-molded polypropylene closures for rigid containers enable precise portion control in veterinary prescription and fresh food segments.
- Easy Open:Laser-scored tear notches and directional peel features accommodate aging pet owner demographics without compromising child safety requirements.
Heat Seal represents the dominant installed base. Zip Lock adoption is climbing fastest as multi-serve dry food formats expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the largest installed flexible packaging capacity, while France concentrates premium wet food pouch demand in its metropolitan corridors. The EU Packaging and Packaging Waste Regulation applies uniformly, yet national enforcement timelines and converter readiness diverge meaningfully across the region.
Germany
Mono-material polyethylene extrusion lines are multiplying across Bavaria and North Rhine-Westphalia to serve retort pouch qualification programs. The national packaging ordinance implements extended producer responsibility verification ahead of EU-wide deadlines. Munich and Hamburg harbor the densest clusters of film laminators retooling aluminum-light barrier webs for recyclability compliance.
France
Paris and Lyon metropolitan zones drive single-serve wet food pouch penetration through subscription direct-to-consumer channels. ANSM and DGCCRF coordinate enforcement of EFSA migration limits for fat-rich pet food contact materials. The Rhône-Alpes packaging belt hosts specialty converters reformulating sealant layers for veterinary prescription formats.
Italy
Flexible bag production hardens in Lombardy and Emilia-Romagna as converters displace metallized structures with coextruded barrier films. The national chemical agency supports REACH compliance documentation for additive reformulation in high-lipid applications. Bologna and Milan anchor the supplier network qualifying paper-based secondary packaging for ambient distribution.
United Kingdom
Post-Brexit regulatory divergence is delaying PPWR-aligned recyclability verification for exporters serving continental retail banners. The Food Standards Agency maintains parallel consultation on food contact material thresholds. The Midlands packaging corridor retains flexible film extrusion capacity despite uncertainty over future EU market access protocols.
Poland
Pet humanization rates trail Western European benchmarks by substantial margins, creating white space for premium format introduction as disposable incomes converge. The national waste management framework is accelerating mechanical recycling infrastructure investment. Warsaw and Kraków are emerging as distribution hubs for flexible bag formats targeting mass retail expansion.
Europe Pet Food Packaging Market Key Industry Players
Western European producers anchor the premium barrier film tier; Central European specialists hold cost-optimized flexible bag capacity. The vendor base stratifies across three tiers: integrated multinationals with extrusion-to-conversion networks, regional mono-material specialists, and paper-based sustainable packaging developers. Consolidation pressure is intensifying as extended producer responsibility schemes elevate compliance costs. Strategic moves concentrate on mono-material R&D partnerships and digital printing press installations for batch traceability.
Within the integrated multinational tier, Amcor plc and Mondi Group exemplify divergent sustainability positioning. Amcor leverages European film extrusion infrastructure to supply high-barrier laminates for moisture-sensitive applications. Mondi anchors paper-based substitution programs through kraft packaging development. Constantia Flexibles occupies a specialized position in aluminum-light barrier webs for sensitive nutritional formulations. These three entities represent the dominant archetypes shaping converter investment patterns under PPWR mandates.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi Group |
| Constantia Flexibles |
| Berry Global Group, Inc. |
| Sonoco Products Company |
| Huhtamaki Oyj |
| Smurfit Kappa |
| Ardagh Group S.A. |
| Coveris Holding S.A. |
| Others |
Cost & Logistics Intelligence
Backward integration into European film extrusion networks anchors both supply security and pricing power for converters serving PPWR-compliant pet food packaging. German and Italian producers with captive polyethylene capacity command margin insulation against London Metal Exchange aluminum volatility while mid-tier flexible bag specialists face persistent cost compression.
Pricing Analysis
Capacity additions in Germany and France are reshaping price floors for mono-material barrier webs as extrusion lines multiply across Bavaria and North Rhine-Westphalia. Three-tier pricing structure across premium, standard, and economy levels separates retort-capable pouch laminates from commodity dry food bags and biodegradable alternatives. Cost compression in mid-tier flexible bags intensifies because aluminum-light barrier web substitutes require qualification investments. Mass retail private label buyers exhibit highest price sensitivity while veterinary prescription channels absorb premium positioning.
Supply Chain Analysis
Regional distribution centers in Germany, Italy, and Poland orchestrate hub-and-spoke patterns for flexible film distribution across Western and Central European pet food manufacturing clusters. Raw material flows draw from Saudi Arabian polyethylene feedstock, Belgian ethylene vinyl alcohol resin production, and domestic recycled flake streams. Single-source vulnerability concentrates in metallized barrier web supply from specialized Austrian and Dutch converters. Distribution runs through pallet-scale shipments to mass retail consolidation centers and individual parcel networks for direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by urban pet owner consolidation toward single-serve wet food pouches with premium barrier specifications. Specification intensity is accelerating across all buyer archetypes.
For Market Incumbents: To counter aluminum price volatility and margin erosion in mid-tier dry food bags, prioritize backward integration into polyethylene extrusion capacity in Poland and Romania while accelerating EPR-compliant mono-material qualification timelines for retort applications. For New Entrants and Emerging Players: Digital printing press installations with batch-level traceability capability offer a technology-first wedge into fragmented e-commerce subscription channels demanding weekly replenishment cycles with minimal order minimums. For Investors and Strategic Acquirers: Roll-up economics work for regional mono-material specialists because PPWR compliance verification costs are elevating fixed investment thresholds beyond standalone operator capacity. Monitor delegated act implementation timelines for recyclability performance grades as the inflection signal determining which packaging formats retain shelf access.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Extrusion Capacity Expansion | Bavarian and North Rhine-Westphalian lines secure PPWR recyclability grade compliance before delegated act enforcement. |
| Digital Printing Press Installation | HP Indigo and Xeikon systems enable EU Feed Hygiene Regulation batch traceability with reduced plate waste. |
| Sealant Layer Reformulation Investment | Specialty compounders address EFSA-mandated additive migration limits for fat-rich veterinary prescription matrices. |
| Paper-Based Secondary Packaging Development | Mondi Group's kraft stretch wrap programs demonstrate pallet containment viability for ambient distribution. |
| Eastern European Distribution Hub Establishment | Warsaw and Kraków facilities capture mass retail expansion as Polish pet humanization rates converge toward Western benchmarks. |
Research Approach
Multiple input streams — converter production data, retail procurement records, regulatory filing repositories — were reconciled through structured primary interviews with film extrusion plant managers, pet food brand packaging directors, ECHA compliance officers, and mass retail category buyers. Secondary validation drew from EU Packaging and Packaging Waste Regulation delegated acts, EFSA food contact material guidelines, Cefic chemical industry reports, and customs trade flow databases. Bottom-up capacity installations and top-down demand segmentation were triangulated against historical pricing indices.
Historical volume trajectories were cross-referenced against panel input from converter technical directors and brand owner sustainability leads to construct the analytical framework across the analysis window. Segmentation dimensions modeled include packaging format, material substrate, end-user channel, and closure type alongside regional regulatory cluster alignment. CAGRs were derived from fitted growth curves incorporating pet humanization rate convergence patterns and PPWR implementation phase-in schedules.
The model holds under steady PPWR delegated act implementation timelines and sustained aluminum price volatility within recent historical bands; deviation in regulatory enforcement acceleration or metallized laminate substitution breakthroughs would shift trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food Packaging
Asia-Pacific Child Resistant Packaging Market
Baby Food Packaging
APAC Baby Food Packaging Market
Baby Food Packaging
North America Home Care Packaging Market
Baby Food Packaging
Global Pet Food and Pet Product Packaging Market
Baby Food Packaging
Middle East and Africa Baby Food Packaging Market
Baby Food Packaging
Breathable Films for Baby Care Market
Baby Food Packaging
Baby Food Packaging Market
Baby Food Packaging
United States and Canada Child Resistant Bottles Market
Baby Food Packaging
Europe Home Care Packaging Market
Baby Food Packaging
United States Baby Food Packaging Market
Baby Food Packaging
Infant Formula Packaging Market
Baby Food Packaging
US Pet Food Packaging Market
Baby Food Packaging
Europe Baby Food Packaging Market
Baby Food Packaging
Baby Care Packaging Market