
 United States and Canada Child Resistant Bottles Market | 2026-2036
United States and Canada Child Resistant Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
United States and Canada Child Resistant Bottles Market Analytics
Extended Producer Responsibility mandates across multiple US states and Canadian provinces is consolidating demand for recyclable, child-resistant formats. Berry Global Inc. leverages its North American manufacturing footprint to supply multi-material solutions. COMAR LLC. specializes in custom-molded pharmaceutical bottles with integrated closure systems. Berlin Packaging sustains broad distribution reach across both countries through its extensive warehouse network.
Child resistant bottles are rigid containers engineered with specialized closure mechanisms requiring coordinated dual-action or force sequences to open, typically manufactured through injection molding or blow-molding processes using polyethylene, polypropylene, or glass substrates. Their primary purpose is preventing accidental ingestion by children under five years while maintaining accessibility for adults. Plastic bottles lead volume due to cost scalability and design flexibility, though glass bottles command premium positioning in light-sensitive pharmaceutical applications. Push-down cap closures represent the fastest-expanding closure category, driven by pharmaceutical and cannabis sector requirements for tamper-evident, senior-friendly designs.
The US Consumer Product Safety Commission enforces Poison Prevention Packaging Act testing protocols, while Health Canada mandates comparable child-resistant standards through its Consumer Chemicals and Containers Regulations. These frameworks shape product development cycles, as manufacturers must certify each SKU through third-party testing before market entry. Stakeholders should monitor evolving state-level cannabis packaging rules and Canadian single-use plastic restrictions, as both will force material and design pivots.
Market Dynamics
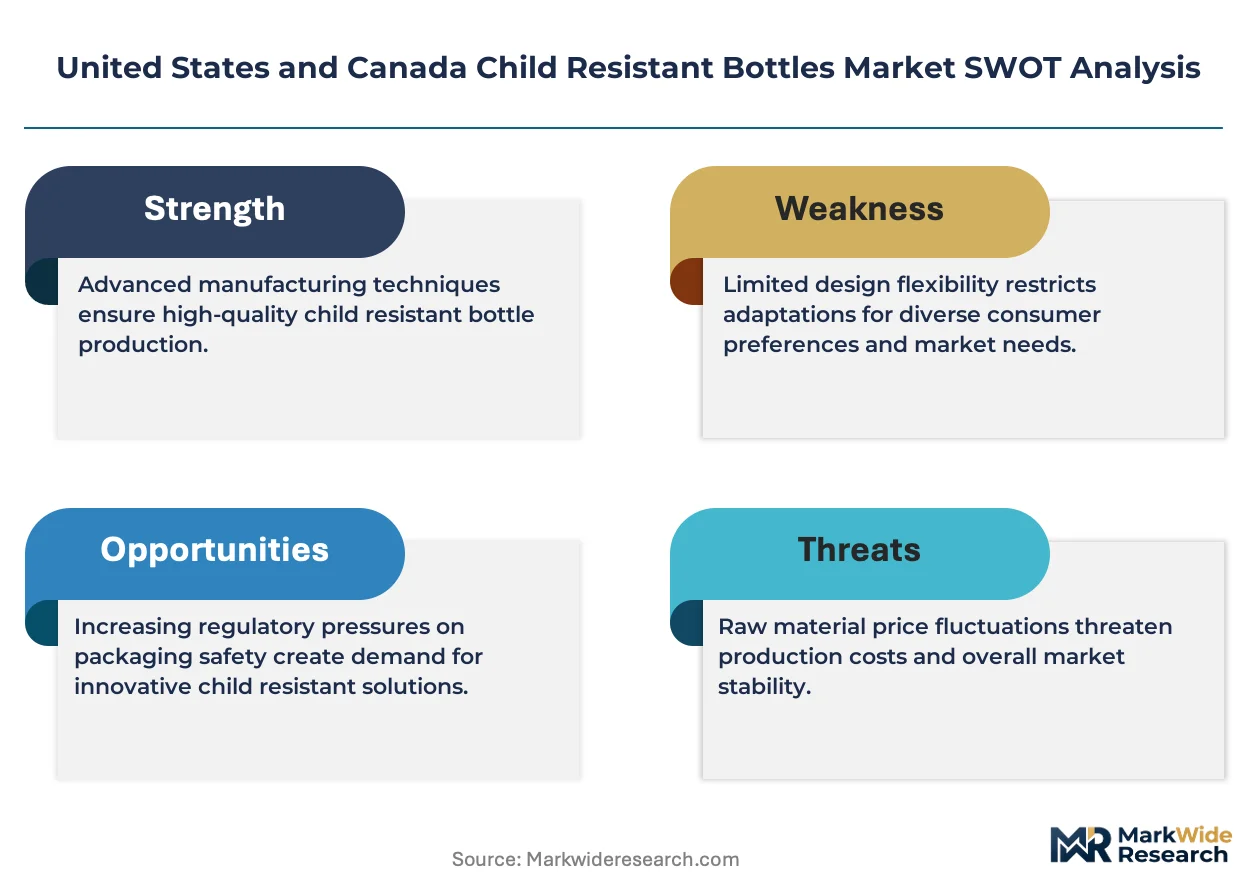
Extended Producer Responsibility mandates across California, New York, and Ontario are forcing pharmaceutical and cannabis packagers to absorb end-of-life recycling costs, compressing margins and consolidating supplier relationships around multi-material capable manufacturers.
Growth Catalysts
- Poison Prevention Packaging Act enforcement:The US Consumer Product Safety Commission's strict certification protocols create recurring demand for compliant SKUs as pharmaceutical manufacturers refresh packaging lines.
- Cannabis sector expansion:State-level legalization in California, Colorado, and Illinois generates sustained orders for tamper-evident, child-resistant formats with senior-friendly accessibility features.
- Ontario pharmaceutical clustering:Dense contract manufacturing and generic drug production around Toronto concentrates packaging procurement volumes for regional suppliers.
Market Restraints
- Resin price volatility:Polyethylene and polypropylene feedstock costs fluctuate with crude oil benchmarks, squeezing converter margins on fixed-price annual contracts.
- Closure mechanism concentration:Specialized dual-action cap production concentrates among a limited set of injection molders in the US Midwest, creating single-source vulnerability.
- Glass substrate fragility:Breakage rates during automated filling lines limit glass bottle adoption despite premium pharmaceutical demand for light-blocking amber formats.
Strategic Opportunities
- Alberta cannabis processing growth:Emerging extraction and packaging facilities in Calgary and Edmonton create underpenetrated demand for compliant bottles outside traditional Ontario and California clusters.
- Post-consumer recycled content mandates:California's SB 54 requirements for 30% recycled plastic in packaging by 2030 rewards early movers with rPET and rPP integration capabilities.
- Direct-to-patient pharmacy channels:Mail-order prescription growth is shifting volume toward smaller, unit-dose bottle formats with enhanced senior accessibility.
Industry Challenges
- Third-party certification bottlenecks:ISO 8317 and CPSC protocol testing backlogs at accredited laboratories extend new product launch timelines by four to eight weeks.
- Automation integration complexity:Pharmaceutical filling lines require precise torque specifications and vision-system compatibility that legacy child-resistant closures struggle to meet.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States and Canada Child Resistant Bottles Market |
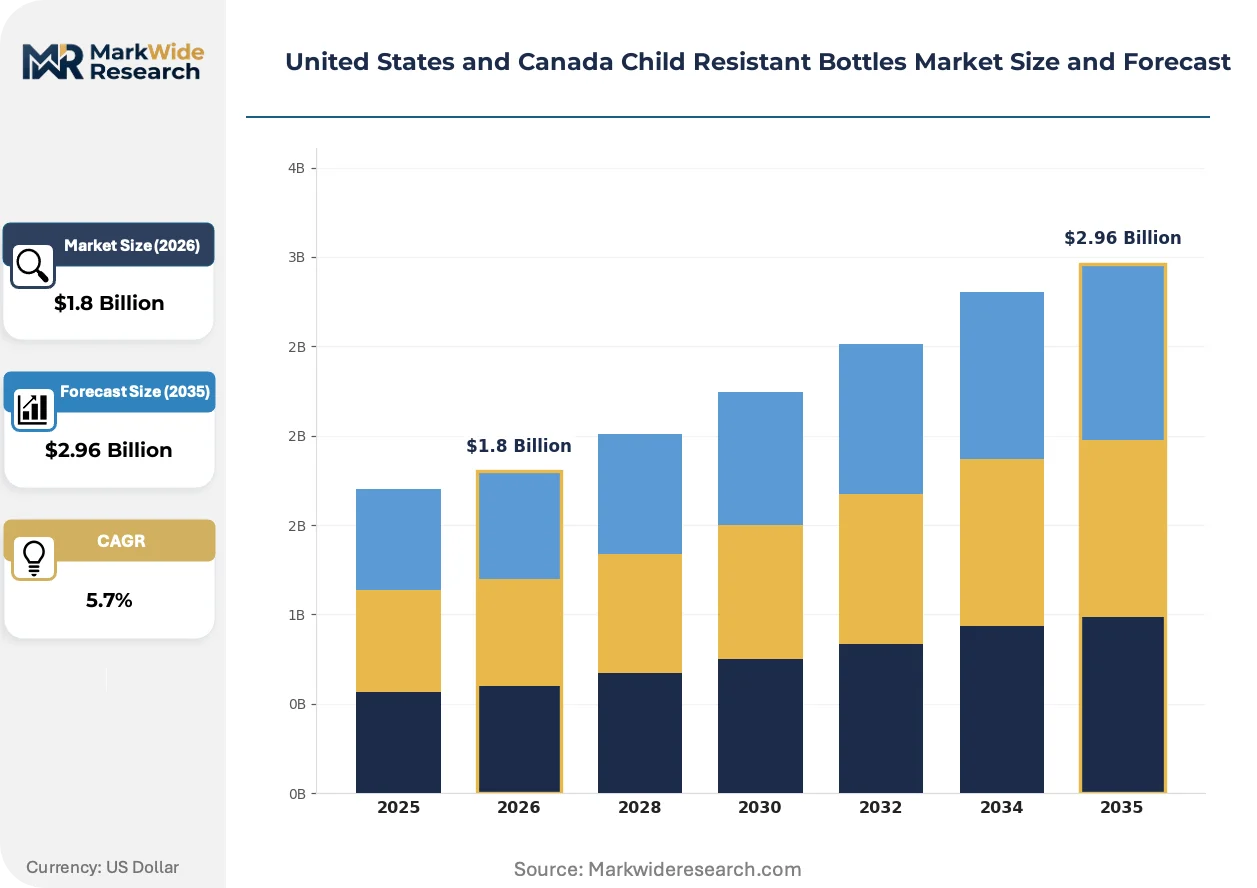
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bottles, Glass Bottles, Metal Containers, Hybrid Packaging Material: Polyethylene, Polypropylene, Glass, Aluminum Closure Type: Screw Cap, Push-Down Cap, Child Lock Cap, Snap-On Cap End User: Pharmaceuticals, Cosmetics, Household Products, Nutraceuticals |
| Companies Covered | Berry Global Inc., COMAR LLC., O.BERK, Origin Pharma Packaging, SGD Pharma, BERICAP, CL Smith, United States Plastics Corp, Berlin Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States and Canada Child Resistant Bottles Market Evolving Landscape
Smart closure technologies and sustainable material transitions are converging to redefine competitive differentiation, with regulatory pressure accelerating adoption curves beyond typical packaging innovation cycles.
Push-down-and-turn closure automation is automating quality assurance in high-speed pharmaceutical filling operations. Major generic drug manufacturers in New Jersey and Pennsylvania are retrofitting lines with torque-monitoring systems that reject out-of-spec closures in real time. This is automating labor-intensive manual inspection and reducing line stoppage frequency.
Health Canada's Consumer Chemicals and Containers Regulations amendments are tightening child-resistance testing protocols for cannabis topicals and edibles. The updated standards require additional senior-friendly accessibility demonstrations, forcing Ontario and British Columbia processors to redesign existing SKUs. Cannabis packaging suppliers are responding with dual-certified formats that satisfy both US CPSC and Canadian requirements.
Mail-order pharmacy procurement is consolidating volume among national distributors with integrated packaging specifications. CVS, Walgreens, and Amazon Pharmacy are unbundling after-sales compliance support and demanding direct-to-patient labeling capabilities. This shift is most visible in Florida and Arizona, where retiree populations drive high prescription mail volumes and senior accessibility lawsuits create liability exposure.
United States and Canada Child Resistant Bottles Market Segmentation
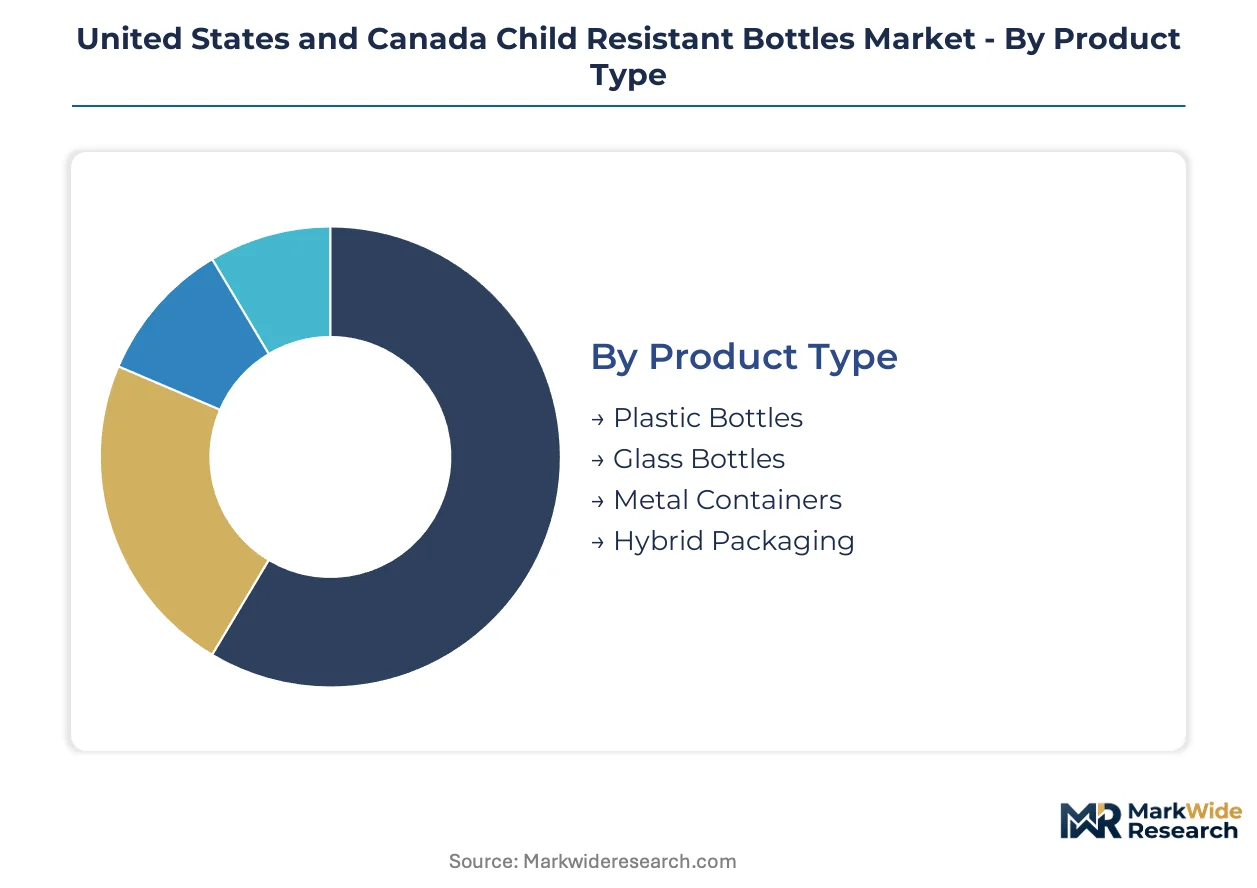
Child-resistant bottle procurement in the United States and Canada fragments across material specifications, closure mechanisms, and regulatory compliance tiers. Pharmaceutical and cannabis packagers specify formats based on filling line compatibility, senior accessibility mandates, and state-level recycling requirements.
Product Type:
Injection molders and glass converters in Michigan, Ohio, and Ontario concentrate capacity around substrate-specific production lines, with equipment lock-in creating distinct supply pools for each format category.
- Plastic Bottles:Blow-molded HDPE and PET containers dominate prescription pharmaceutical volumes due to cost scalability and design flexibility. California and New Jersey generic drug manufacturers specify these formats for high-speed automated filling lines.
- Glass Bottles:Amber and cobalt blue borosilicate formats command premium positioning in light-sensitive pharmaceutical applications. Breakage rates during automated handling limit adoption despite superior barrier properties.
- Metal Containers:Aluminum canisters serve niche nutraceutical and cosmetic segments requiring absolute light and oxygen barrier performance.
- Hybrid Packaging:Multi-material combinations integrate plastic bodies with metal or glass components for specialized cannabis and luxury cosmetic applications.
Plastic bottles absorb the bulk of installed capacity; hybrid packaging is expanding most quickly.
Material:
Resin selection in the United States and Canada hinges on Health Canada and US Consumer Product Safety Commission migration testing requirements, with post-consumer recycled content mandates in California and New York forcing material transitions.
- Polyethylene:HDPE and LDPE grades offer chemical resistance and processing ease for high-volume pharmaceutical applications. Ontario and Pennsylvania converters maintain dedicated extrusion lines for medical-grade specifications.
- Polypropylene:Superior heat resistance suits hot-fill pharmaceutical and nutraceutical applications. Alberta cannabis processors favor PP for extraction product stability.
- Glass:Type III borosilicate and soda-lime formats serve parenteral and oral solid dose packaging with inert surface properties.
- Aluminum:Lightweight barrier performance supports travel-size cosmetic and pharmaceutical aerosol applications.
Polyethylene commands the greatest production volume; polypropylene is climbing the fastest on cannabis sector demand.
Closure Type:
Closure mechanism selection determines certification pathway complexity, with dual-action designs requiring specialized injection molding capacity concentrated in the US Midwest.
- Push-Down Cap:Coordinated downward pressure and rotation actions balance child resistance with senior accessibility. Illinois and Colorado cannabis packagers specify these formats for tamper-evident compliance.
- Screw Cap:Standard threaded closures with optional child-resistant liners serve cost-sensitive over-the-counter pharmaceutical segments.
- Child Lock Cap:Specialized dual-action mechanisms exceed baseline Poison Prevention Packaging Act requirements for high-risk household chemical applications.
- Snap-On Cap:Press-fit designs with integrated locking tabs serve single-use pharmaceutical and diagnostic kit applications.
Push-down caps are gaining share fastest; screw caps retain the largest installed base.
End User:
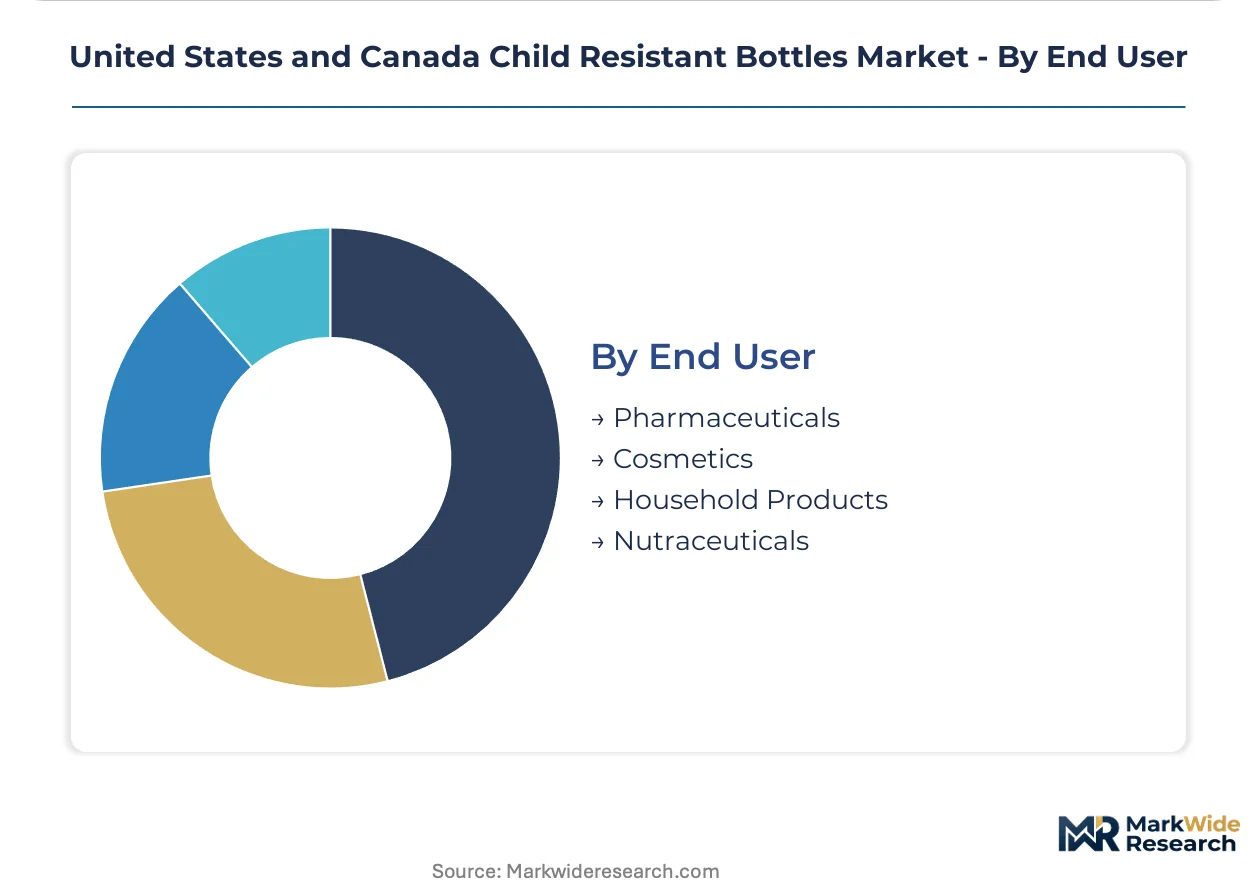
End-use concentration in the United States and Canada clusters around regulatory compliance intensity, with pharmaceutical and cannabis applications driving certification-intensive procurement.
- Pharmaceuticals:Prescription and over-the-counter drug manufacturers in New Jersey, Pennsylvania, and Ontario mandate ISO 8317-certified formats with documented senior accessibility testing.
- Cannabis:State-licensed processors in California, Colorado, and British Columbia require dual-certified child-resistant and tamper-evident packaging with opaque properties.
- Cosmetics:Premium skincare and personal care brands specify child-resistant formats for concentrated essential oil and active ingredient products.
- Household Products:Cleaning chemical and automotive fluid packagers face Consumer Product Safety Commission enforcement for laundry pod and concentrated cleaner containment.
- Nutraceuticals:Dietary supplement manufacturers in Utah and Florida adopt pharmaceutical-grade child-resistant formats for gummy and liquid formulations with pediatric poisoning risk.
Pharmaceuticals anchor procurement volumes; cannabis is expanding most quickly on continued state and provincial legalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toronto's pharmaceutical contract manufacturing corridor anchors North American procurement volumes for child-resistant bottles, with dense clusters of generic drug producers and cannabis processors driving compliant packaging demand across both countries.
United States
New Jersey and Pennsylvania pharmaceutical manufacturers mandate ISO 8317-certified bottles with documented senior accessibility testing for prescription drug distribution. The US Consumer Product Safety Commission enforces Poison Prevention Packaging Act protocols that require third-party certification before market entry. Illinois and Colorado cannabis packagers specify push-down cap formats for tamper-evident compliance in state-licensed retail channels.
Canada
Ontario's Toronto-Waterloo pharmaceutical belt concentrates generic drug production and contract packaging services requiring dual-certified formats. Health Canada's Consumer Chemicals and Containers Regulations mandate child-resistance testing that aligns with US CPSC standards. British Columbia cannabis processors in Vancouver and Victoria are redesigning SKUs to meet amended accessibility demonstrations for topicals and edibles.
California
California's pharmaceutical and cannabis packaging demand is shaped by SB 54 mandates requiring 30% post-consumer recycled plastic in packaging by 2030. The state's dense cannabis cultivation and processing clusters in Sacramento and Santa Rosa generate sustained orders for opaque, child-resistant formats. Los Angeles-area nutraceutical manufacturers specify pharmaceutical-grade bottles for gummy and liquid supplement formulations.
Alberta
Alberta's emerging cannabis extraction and packaging facilities in Calgary and Edmonton create underpenetrated demand outside traditional Ontario and California supply chains. Provincial energy sector workers transitioning to cannabis processing bring capital equipment expertise that accelerates facility commissioning. Edmonton-area processors favor polypropylene bottles for extraction product stability in concentrated oil applications.
New York
New York's Extended Producer Responsibility mandates force pharmaceutical packagers to absorb end-of-life recycling costs, consolidating supplier relationships around multi-material capable manufacturers. The state's mail-order pharmacy channels through New York City and Albany drive volume toward smaller, unit-dose bottle formats. Generic drug manufacturers in the Hudson Valley retrofit filling lines with torque-monitoring systems for real-time quality assurance.
United States and Canada Child Resistant Bottles Market Competitive Landscape
The competitive structure tilts toward diversified packaging conglomerates with multi-material capabilities and specialized pharmaceutical molders with integrated closure systems. Large-scale converters leverage North American manufacturing footprints to supply recyclable formats compliant with evolving state mandates. Mid-tier specialists concentrate custom-molded solutions for pharmaceutical and cannabis applications. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers respond to certification bottlenecks and resin price volatility.
Among diversified packaging conglomerates, Berry Global Inc. exemplifies scale-driven multi-material supply capabilities, while Berlin Packaging occupies a position anchoring broad distribution reach across both countries through extensive warehouse networks. COMAR LLC. represents the specialized pharmaceutical molder archetype, sitting within the custom-integrated closure tier that serves certification-intensive procurement cycles.
| Leading Market Players |
|---|
| Berry Global Inc. |
| COMAR LLC. |
| O.BERK |
| Origin Pharma Packaging |
| SGD Pharma |
| BERICAP |
| CL Smith |
| United States Plastics Corp |
| Berlin Packaging |
| Others |
Value Network & Pricing Analysis
California's SB 54 recycled-content mandates are forcing pharmaceutical packagers to specify rPET and rPP substrates, compelling converters to absorb material-premium costs and renegotiate annual contracts with tiered pricing that rewards early compliance adopters.
Pricing Analysis
Certification-grade throughput anchors value-based pricing tiers across the United States and Canada Child Resistant Bottles Market. Three-tier pricing structure across premium, standard, and economy levels separates ISO 8317 dual-certified formats with integrated torque-monitoring compatibility from basic push-down cap designs and commodity screw-cap alternatives. Cost compression in standard-grade HDPE bottles is intensifying because New Jersey and Pennsylvania generic drug manufacturers are consolidating procurement volumes among three national distributors. Cannabis processors in Colorado and Illinois demonstrate the least price sensitivity due to state-mandated opaque and tamper-evident specifications that limit supplier alternatives.
Supply Chain Analysis
Specialty dual-action cap injection molding rests on concentrated capacity in Ohio, Indiana, and Michigan, with equipment lock-in creating captive supply relationships for pharmaceutical-grade closure systems. Polyethylene and polypropylene feedstock draws from Gulf Coast petrochemical complexes and Alberta natural gas liquids processing, while amber borosilicate glass feeds from Pennsylvania and West Virginia specialty melt operations. Single-source vulnerability in Midwest injection molding creates structural risk if torque-precision equipment failures disrupt pharmaceutical filling line compatibility. Distribution runs through Berlin Packaging's continental warehouse network and Berry Global's direct-to-plant logistics for high-volume pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States and Canada Child Resistant Bottles Market is becoming a vertical-integration race as converters pursue backward integration into closure mechanism production to capture margin and eliminate certification bottlenecks at third-party testing laboratories.
For Market Incumbents: Acquire specialized dual-action cap injection molding assets in the US Midwest to eliminate single-source vulnerability and accelerate ISO 8317 certification timelines. Expand Ontario and Alberta blow-molding capacity to serve cannabis sector growth while retrofitting lines for 30% post-consumer recycled content integration. Defend against resin price volatility by negotiating indexed raw-material pass-through clauses in annual pharmaceutical contracts. For New Entrants and Emerging Players: Direct-to-patient pharmacy platforms offer the most penetrable route for regional bottle converters lacking established pharmaceutical relationships. Target mail-order prescription volume growth in Florida and Arizona with smaller unit-dose formats featuring enhanced senior accessibility. Enter through white-label manufacturing partnerships with Alberta cannabis processors seeking alternatives to Ontario and California supply chains. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier custom molders possessing integrated closure capabilities given Health Canada's tightening accessibility demonstration requirements for cannabis packaging. Long-term viability favors manufacturers with multi-material expertise spanning rPET, rPP, and hybrid formats across the 5-10 year regulatory transition horizon. Monitor California SB 54 compliance certification backlogs as an inflection signal for consolidation urgency among non-compliant converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Closure Manufacturing | Captures margin from Midwest injection molders and eliminates CPSC certification delays. |
| Post-Consumer Recycled Content Certification | Positions converters for California SB 54 pharmaceutical procurement requirements by 2030. |
| Alberta Cannabis Supply Agreement | Secures volume from underpenetrated extraction facilities in Calgary and Edmonton. |
| Direct-to-Patient Format Development | Aligns with CVS, Walgreens, and Amazon Pharmacy unit-dose specifications for mail-order channels. |
| Dual-Certification Investment | Enables simultaneous US CPSC and Health Canada compliance for cross-border pharmaceutical accounts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with pharmaceutical packaging procurement managers, cannabis processing facility operators, injection molding plant engineers, and third-party certification laboratory directors. FDA 510(k) submissions, Health Canada product license applications, US CPSC enforcement memoranda, and provincial cannabis packaging rulemakings provided regulatory trajectory validation. Bottom-up capacity assessments at Michigan, Ohio, and Ontario converter facilities were triangulated against top-down pharmaceutical and cannabis packaging spend estimates.
Data-stream reconciliation across material substrate volumes, closure mechanism shipments, and end-use procurement patterns informed the analytical framework across the analysis window. Segmentation modeling incorporated material grade tier, closure type complexity, end-use regulatory intensity, and regional production hub concentration. CAGRs were derived from trend extrapolation of pharmaceutical prescription growth, cannabis legalization expansion, and recycled-content mandate compliance curves.
The model holds under steady-state regulatory enforcement and resin price-band stability; deviation in Health Canada testing protocol amendments or Gulf Coast petrochemical supply disruptions would shift volume and value trajectories. Forecasts reflect documented assumptions regarding certification laboratory capacity expansion and pharmaceutical mail-order channel growth. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food Packaging
Asia-Pacific Child Resistant Packaging Market
Baby Food Packaging
Europe Pet Food Packaging Market
Baby Food Packaging
Breathable Films for Baby Care Market
Baby Food Packaging
North America Home Care Packaging Market
Baby Food Packaging
Global Pet Food and Pet Product Packaging Market
Baby Food Packaging
Middle East and Africa Baby Food Packaging Market
Baby Food Packaging
Baby Food Packaging Market
Baby Food Packaging
United States Baby Food Packaging Market
Baby Food Packaging
Infant Formula Packaging Market
Baby Food Packaging
Baby Care Packaging Market
Baby Food Packaging
APAC Baby Food Packaging Market
Baby Food Packaging
Europe Home Care Packaging Market
Baby Food Packaging
Europe Baby Food Packaging Market
Baby Food Packaging
US Pet Food Packaging Market