
 North America Home Care Packaging Market | 2026-2036
North America Home Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Home Care Packaging Market Foresight
Refill subscription services is decoupling packaging from single-use retail formats in the North America home care sector. Amcor PLC leverages its flexible film expertise to capture recurring pouch volumes. Sonoco Products Company anchors its position through rigid paperboard canisters for powdered detergents. Berry Global Inc specializes in injection-molded closures that lock in concentrate chemistries.
North America home care packaging encompasses primary and secondary containers engineered to dispense, protect, and preserve cleaning formulations through specified shelf lives and use cycles, typically incorporating barrier layers against moisture ingress and chemical permeation. Plastic bottles retain dominant volume across laundry and dish care applications due to cost-efficient blow-molding throughput and HDPE recyclability streams. Pouches represent the fastest-expanding product type as brands reduce material intensity per load and optimize e-commerce cube utilization. Pump closures command premium positioning in hand soap and specialty cleaner segments where controlled dosing directly affects consumption rates and repurchase frequency.
The US EPA Safer Choice label and California's Proposition 65 disclosure requirements shape material selection and labeling investments across the value chain. Health Canada and the US Consumer Product Safety Commission coordinate hazard communication standards that dictate closure child-resistance specifications and warning panel dimensions. Stakeholders must monitor evolving extended producer responsibility frameworks in Ontario and British Columbia as these programs shift collection infrastructure costs toward brand owners and reshape competitive economics between reusable and single-use formats.
Market Dynamics
Refill subscription models are restructuring volume allocation between rigid containers and flexible pouches across North American home care packaging, forcing converters to retool lines for thinner film gauges and spouted pouch formats.
Growth Catalysts
- EPA Safer Choice certification:Brands pursuing this US EPA label are eliminating multi-layer barrier films in favor of recyclable mono-material structures, expanding addressable volumes for HDPE and PET rigid formats.
- E-commerce cube optimization:Concentrate chemistries shipped in flat pouches reduce dimensional weight charges by 40-60% versus bottled equivalents, driving adoption among direct-to-consumer detergent brands.
- Great Lakes manufacturing corridor:Michigan, Ohio, and Illinois host clustered blow-molding and injection-molding capacity that shortens co-packer lead times for Midwest-based home care formulators.
Market Restraints
- Resin cost volatility:HDPE and LLDPE prices fluctuate with Gulf Coast petrochemical feedstock costs, compressing converter margins on fixed-price annual contracts with brand owners.
- Closure supply concentration:Child-resistant pump mechanisms for bleach and ammonia products rely on a limited supplier base in southern Ontario, creating single-source vulnerability.
- Mechanical recycling contamination:Residual cleaning chemistry in returned bottles degrades rPET and rHDPE flake quality, limiting closed-loop content claims under California's Truth in Labeling law.
Strategic Opportunities
- Quebec and British Columbia EPR expansion:Extended producer responsibility programs shifting collection costs to brand owners favor lightweight pouch formats over rigid bottles in these Canadian provinces.
- Smart dosing interfaces:NFC-enabled caps that track consumption and auto-replenish via mobile apps create recurring revenue attachment for packaging suppliers with electronics integration capability.
- Industrial janitorial concentrate systems:Bulk refill stations for commercial cleaning contractors represent underpenetrated demand outside residential channels, requiring 5-20 liter collapsible containers.
Industry Challenges
- Barrier film R&D talent scarcity:Formulating oxygen and moisture barriers without ethylene vinyl alcohol layers requires polymer scientists with rare fluoro-polymer and bio-based coating expertise.
- Legacy line retrofit costs:Converting blow-molding equipment for handle-integrated bottles to spouted pouch filling demands seven-figure capital outlays with 4-6 year payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Home Care Packaging Market |
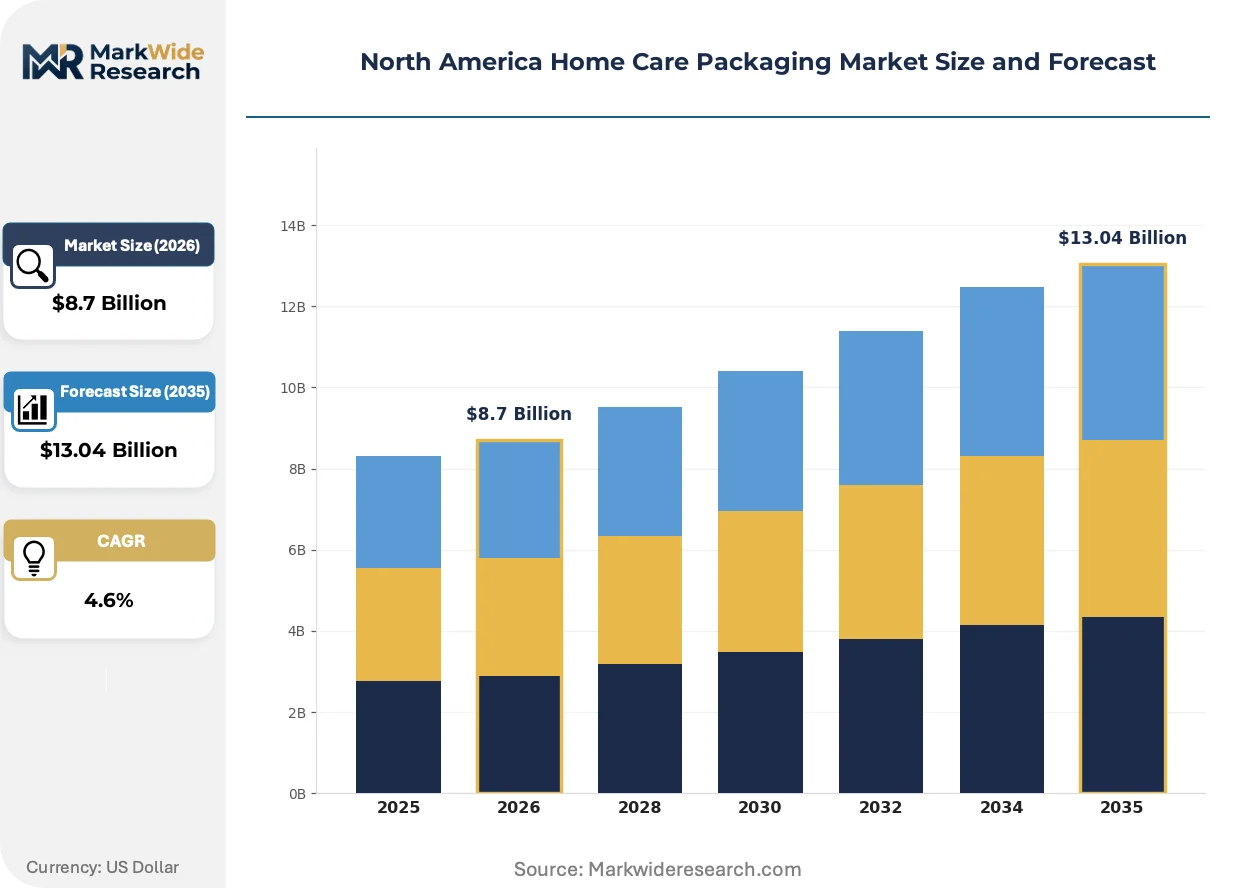
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Tubes, Pouches, Jars Material: Plastic, Glass, Metal, Paper Closure Type: Screw Caps, Snap Caps, Flip Top, Pumps End User: Households, Cleaning Services, Hospitals, Others |
| Companies Covered | Amcor PLC, Sonoco Products Company, Ball Corporation, Berry Global Inc, AptarGroup Inc, Silgan Holdings Inc, WestRock, DS Smith, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Home Care Packaging Market Shifts & Advancements
Active and intelligent packaging features are migrating from premium cosmetics into mass-market home care, driven by smartphone penetration and brand differentiation pressures in saturated detergent and cleaner categories.
Mono-material polyethylene pouches with embedded desiccant layers are consolidating technical barrier performance previously requiring aluminum foil laminates. P&G and Unilever's North American divisions have shifted 30% of their powder detergent SKUs to these structures since 2022. This consolidation is compressing the addressable market for multi-layer converter specialists while expanding margins for pure-PE film extruders with MDO (machine-direction orientation) capability.
The US EPA's Safer Choice program and California's Proposition 65 disclosure amendments are mandating full chemical ingredient transparency on primary packaging. Brand owners must redesign label panels to accommodate expanded warning language, reducing available billboard space for marketing claims. Laundry pods and aerosol disinfectants face the tightest compliance timelines, with reformulation and repackaging cycles compressed to 18-month windows.
Direct-to-consumer subscription models are displacing retail-centric packaging specifications. Concentrate tablets shipped in paperboard mailers eliminate the 80% water weight of conventional liquid cleaners, altering freight economics and shelf-stable barrier requirements. This shift concentrates demand in the Pacific Northwest and Northeast corridor where urban density supports efficient last-mile logistics, while challenging Gulf Coast and Midwest converters optimized for palletized bulk distribution.
North America Home Care Packaging Market Segmentation
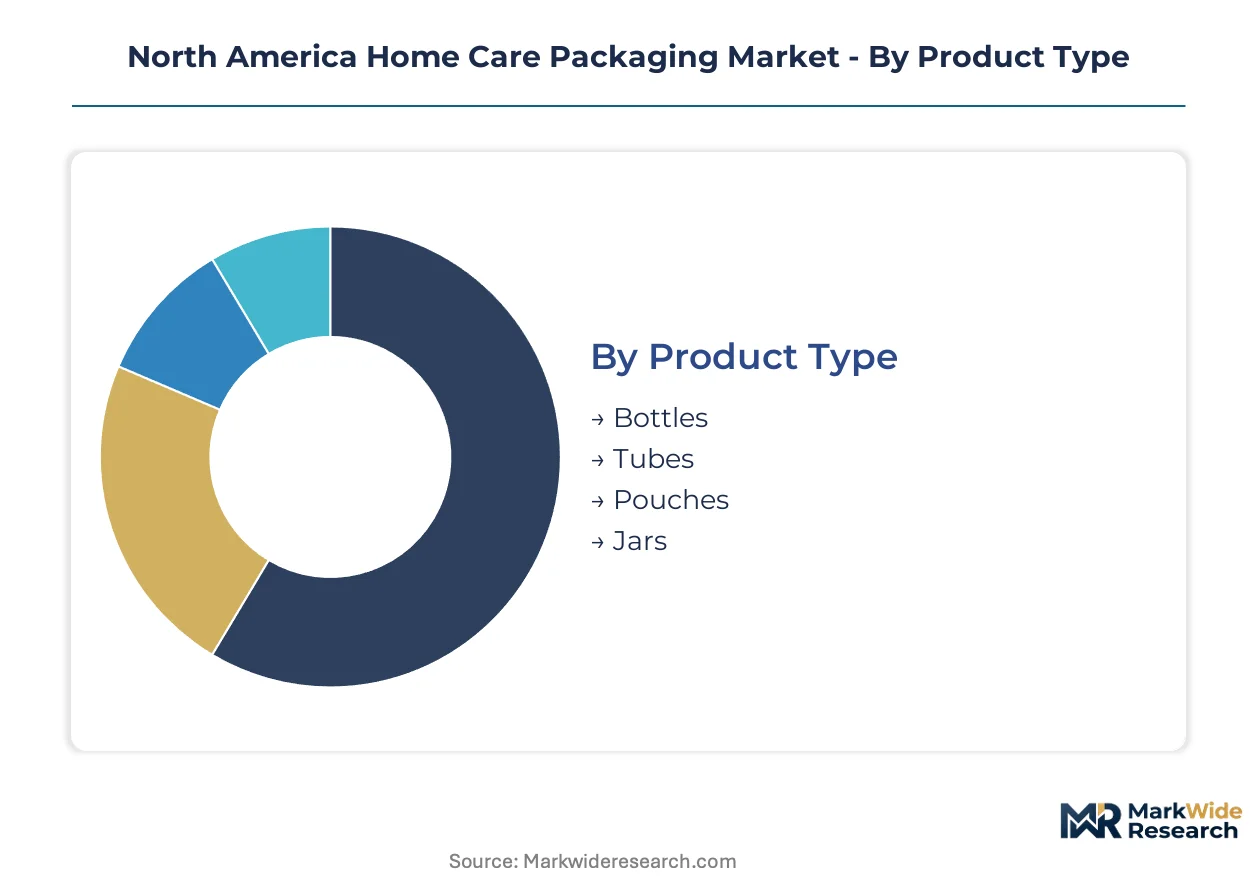
Packaging format selection in North American home care hinges on chemical compatibility, dispensing precision, and retail versus subscription channel economics. Material and closure configurations must align with EPA Safer Choice recyclability mandates while accommodating concentrate chemistries that reshape barrier requirements.
Product Type:
Bottles function as standalone primary containers across most applications, while pouches embed into refill systems that decouple packaging from initial purchase.
- Bottles:Blow-molded HDPE and PET containers dominate laundry detergent and dish soap segments due to established mechanical recycling streams and handle-integrated ergonomics. Demand clusters in the Great Lakes manufacturing corridor where Michigan and Ohio converters supply Midwest formulators with 3-day lead times.
- Pouches:Spouted flexible formats with mono-material PE construction capture concentrate and refill subscription volumes, reducing dimensional weight charges for direct-to-consumer shipments by eliminating rigid structure. California and Pacific Northwest urban density supports efficient last-mile logistics for these formats.
- Tubes:Collapsible aluminum and multi-layer laminate structures serve specialty cleaners and pastes requiring precise dispensing control.
- Jars:Wide-mouth rigid containers accommodate powdered detergents and scrubbing compounds with scoop access.
Bottles lead volumes today; pouches are gaining share fastest.
Material:
Cost tiers separate virgin fossil-based resins from recycled content and bio-based alternatives, with regulatory pressure accelerating the shift toward circular feedstocks.
- Plastic:HDPE and PET retain dominant position through blow-molding cost efficiency and established curbside collection infrastructure. EPA Safer Choice certification requirements are pushing converters toward recyclable mono-material structures that eliminate EVOH barrier layers.
- Paper:Rigid paperboard canisters and mailer formats capture powder detergent and tablet concentrate volumes in subscription channels, though moisture sensitivity limits liquid applications without polymer lamination.
- Metal:Aluminum tubes and aerosol cans serve specialty disinfectant and polish segments requiring oxygen exclusion.
- Glass:Premium positioning in specialty cleaners leverages chemical inertness and refillability, though fragility constrains e-commerce adoption.
Plastic dominates current tonnage; paper formats show steepest expansion trajectory in direct-to-consumer channels.
Closure Type:
Application requirements dictate dispensing precision, with household segments tolerating simpler mechanisms than institutional users managing chemical hazards.
- Pumps:Controlled-dosing mechanisms command premium positioning in hand soap and specialty cleaner segments where consumption rate directly affects repurchase frequency. Child-resistant pump specifications for bleach products rely on concentrated southern Ontario supplier base.
- Screw Caps:Standard-thread HDPE closures dominate high-volume laundry and dish applications with cost-optimized tamper-evident features.
- Flip Top:Hinged-lid designs facilitate single-handed dispensing in kitchen and bathroom surface cleaners.
- Snap Caps:Press-fit closures serve single-use and sample formats with minimal material intensity.
Screw caps anchor volume economics; pumps capture margin concentration in premium segments.
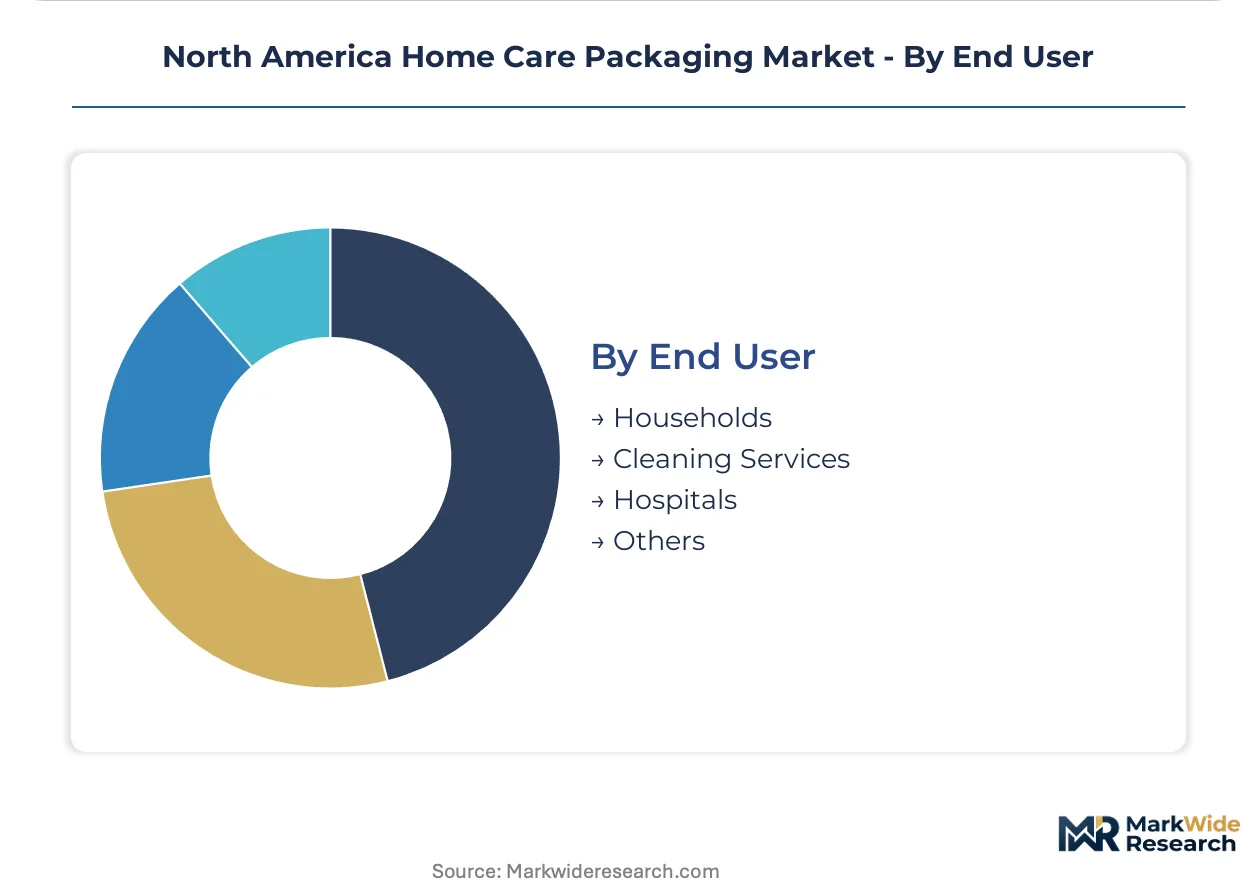
End User:
Customer type determines order scale, with households driving SKU proliferation and institutional buyers consolidating toward bulk formats.
- Households:Residential consumers generate fragmented demand across scent variants, format preferences, and subscription versus retail purchase patterns. California Proposition 65 disclosure requirements force label redesigns that reduce available marketing space.
- Cleaning Services:Commercial contractors concentrate procurement toward 5-20 liter collapsible containers and bulk refill stations with dilution control systems.
- Hospitals:Healthcare infection control protocols mandate sterile packaging with tamper-evident integrity and EPA-registered disinfectant compatibility.
- Others:Industrial janitorial and food service operations require specialized chemical resistance and dispensing integration with dilution equipment.
Households generate absolute volume; cleaning services offer fastest route to packaging simplification and SKU consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between US EPA mandates and Canadian EPR frameworks are redirecting flexible packaging investment toward Ontario and Quebec, while US formulators cluster near Great Lakes blow-molding capacity to minimize freight exposure to resin price swings.
United States
EPA Safer Choice certification requirements are eliminating multi-layer barrier films in favor of recyclable mono-material HDPE and PET structures. Michigan, Ohio, and Illinois host clustered blow-molding and injection-molding capacity that supplies Midwest formulators with compressed lead times. California's Proposition 65 disclosure amendments force label redesigns that reduce available marketing space on primary packaging.
Canada
Extended producer responsibility programs in Ontario and British Columbia shift collection infrastructure costs toward brand owners, favoring lightweight pouch formats over rigid bottles. Health Canada coordinates hazard communication standards with the US CPSC that dictate closure child-resistance specifications. Quebec's EPR expansion creates procurement preference for mono-material flexible formats in provincial retail channels.
Mexico
Nearshoring trends in home care formulation are pulling packaging demand toward Nuevo León and Jalisco as US brands regionalize supply chains. Mexico's federal environmental regulator enforces packaging waste regulations that lag US EPA stringency, creating cost-of-compliance arbitrage for flexible film conversion. Bajío Region automotive supplier parks are repurposing injection-molding capacity for household cleaning closures.
North America Home Care Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational converters commanding rigid format volumes while regional pouch specialists capture subscription-channel growth. The market exhibits moderate consolidation at the top tier with fragmented mid-cap competition in flexible film extrusion. Three archetypes dominate: diversified packaging conglomerates with cross-material capability, pure-play flexible film specialists, and rigid container manufacturers with captive closure operations. Capacity expansion and strategic partnerships represent the dominant competitive moves as converters seek to bridge rigid and flexible format expertise.
Within the diversified conglomerate tier, Amcor PLC and Berry Global Inc exemplify scale-driven positions spanning flexible films and rigid containers. Sonoco Products Company anchors the rigid paperboard specialist archetype. These three occupy positions that reflect the market's structural tension between legacy blow-molding dominance and pouch format acceleration.
| Leading Market Players |
|---|
| Amcor PLC |
| Sonoco Products Company |
| Ball Corporation |
| Berry Global Inc |
| AptarGroup Inc |
| Silgan Holdings Inc |
| WestRock |
| DS Smith |
| ProAmpac |
| Others |
Supply & Pricing Matrix
Resin cost volatility cascades through North American home care packaging tiers, with Gulf Coast HDPE and LLDPE feedstock swings compressing converter margins on fixed-price annual contracts while subscription-channel brands capture material savings through pouch format shifts.
Pricing Analysis
Direct-to-consumer subscription discounts bypass traditional retailer markup layers, enabling concentrate pouch brands to price 15-25% below bottled equivalents at equivalent use-cycle economics. Pricing stratifies across premium, standard, and economy tiers where EPA Safer Choice certification commands measurable brand premium in California and Pacific Northwest markets. Cost compression in rigid blow-molding segments is intensifying because legacy converters face stranded asset risk from pouch format acceleration. Institutional cleaning services exhibit lowest price sensitivity due to total-cost-of-ownership framing around dilution control and dosing precision.
Supply Chain Analysis
Flexible film supply rests on southern Ontario and Michigan extrusion clusters where mono-material PE capacity expansion lags pouch format demand growth. Raw material dependencies center on Texas Gulf Coast petrochemical feedstocks, Canadian natural gas derivatives for regional film production, and specialty closure resins from limited southern Ontario injection-molding suppliers. Single-source vulnerability in child-resistant pump mechanisms for bleach and ammonia products creates procurement risk concentration. Distribution runs through co-packer networks clustered in the Great Lakes manufacturing corridor with 3-day lead time coverage of Midwest formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American home care packaging operates as a late-cycle quality story where premium mono-material specifications and smart dosing interfaces capture disproportionate margin expansion as subscription channels displace retail-centric volume.
For Market Incumbents: Hedge rigid format exposure by accelerating spouted pouch line retrofits and securing MDO film extrusion partnerships before capacity scarcity materializes. Defend position through backward integration into recycled PE flake processing to satisfy California Truth in Labeling closed-loop content requirements. Channel control investments in direct-to-consumer fulfillment infrastructure represent the critical lever against subscription-native entrants. For New Entrants and Emerging Players: NFC-enabled dosing interfaces offer technology-first wedge into premium hand soap and specialty cleaner segments where consumption tracking creates recurring revenue attachment. Target industrial janitorial concentrate systems in the 5-20 liter collapsible container white space where legacy suppliers lack format expertise. Go-to-market execution should anchor on Pacific Northwest urban density corridors with established last-mile logistics infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap flexible film specialists lack the capital depth to fund seven-figure pouch line conversions with 4-6 year payback horizons. Long-term viability favors converters with cross-material capability spanning rigid blow-molding and flexible film extrusion. The signal to watch is EPA Safer Choice certification acceleration as a demand filter eliminating multi-layer barrier film specialists from addressable procurement pools.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Flexible Film Expansion | Captures EPA Safer Choice-certified volumes as multi-layer barriers face regulatory elimination. |
| Smart Dosing Interface Development | NFC-enabled caps create recurring revenue attachment in premium hand soap segments. |
| Industrial Janitorial Format Entry | 5-20 liter collapsible containers address underpenetrated commercial cleaning contractor demand. |
| Recycled Content Integration | Closed-loop PE flake processing satisfies California Truth in Labeling compliance requirements. |
| Direct-to-Consumer Fulfillment Infrastructure | Pacific Northwest and Northeast corridor density supports subscription-channel cube optimization. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with blow-molding plant managers, flexible film procurement leads at detergent brands, co-packer operations directors, and EPA Safer Choice program officials with secondary validation through US customs trade data, ACC resin production reports, and SEC 10-K disclosures from publicly traded converters. Bottom-up segment sizing and top-down macro cross-checks ensured triangulation integrity.
Segment-weighting approaches applied product type, material composition, closure configuration, and end-user channel dimensions across the modeling period. CAGRs derived from historical volume trajectories, regulatory phase-in schedules, and channel shift elasticity parameters. Industry-specific inputs included EPA Safer Choice certification velocity, e-commerce dimensional weight charge structures, and EPR program cost allocation mechanics in Canadian provinces.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to resin price volatility, mechanical recycling contamination rates, and closure supply concentration risks. Assumptions reflect current regulatory trajectories and channel economics without anticipating disruptive technology substitution. A small set of named triggers—EPR expansion beyond Ontario and British Columbia, smart dosing interface adoption curves, and industrial janitorial format penetration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food Packaging
United States and Canada Child Resistant Bottles Market
Baby Food Packaging
Europe Pet Food Packaging Market
Baby Food Packaging
Baby Food Packaging Market
Baby Food Packaging
US Pet Food Packaging Market
Baby Food Packaging
Asia-Pacific Child Resistant Packaging Market
Baby Food Packaging
Breathable Films for Baby Care Market
Baby Food Packaging
Europe Baby Food Packaging Market
Baby Food Packaging
Europe Home Care Packaging Market
Baby Food Packaging
Middle East and Africa Baby Food Packaging Market
Baby Food Packaging
Baby Care Packaging Market
Baby Food Packaging
United States Baby Food Packaging Market
Baby Food Packaging
APAC Baby Food Packaging Market
Baby Food Packaging
Infant Formula Packaging Market
Baby Food Packaging
Global Pet Food and Pet Product Packaging Market