
 Breathable Films for Baby Care Market | 2026-2036
Breathable Films for Baby Care Market Size, Share, and Industry Trends Forecast 2026-2036
Breathable Films for Baby Care Market Insights
Advanced microporous extrusion technology is reshaping how breathable films deliver moisture vapor transmission without compromising liquid barrier integrity in baby care applications. Procter & Gamble leverages extensive R&D infrastructure to sustain formulation leadership across premium diaper tiers. Kimberly-Clark anchors North American supply through integrated polymer sourcing and converting operations. Toray Industries specializes in ultra-thin polyolefin membranes that dominate Asian OEM supply chains.
Breathable films for baby care are microporous polymer membranes, typically 10–30 micrometers thick, engineered with controlled pore densities of 0.1–3.0 microns to permit water vapor escape while blocking aqueous fluid penetration. Manufacturers employ cast extrusion or blown film processes with calcium carbonate fillers, subsequently stretched to create interconnected void structures that achieve MVTR values exceeding 2,500 g/m²/24hr for infant skin health management. Polyethylene formulations occupy the largest material position due to cost scalability and sealability, though biodegradable polymers represent the fastest-expanding category as European retailers enforce plastic-reduction commitments. Diapers command the dominant product-type volume, while wipes and liners concentrate margin pools through specialized dermatological certifications and pharmacy channel positioning.
REACH substance restrictions and the EU F-Gas Regulation constrain fluorinated polymer alternatives in European breathable film supply, redirecting formulation investment toward non-fluorinated microporous technologies. FDA biocompatibility requirements for infant contact materials and China's SAMR national standards for disposable hygiene products establish divergent compliance pathways that fragment regional product specifications. Stakeholders must monitor evolving state-level extended producer responsibility legislation in the United States and biodegradable certification thresholds in Germany to align capital allocation with compliance-driven material transitions.
Market Dynamics
Microporous extrusion technology is compressing the performance gap between premium and mid-tier diaper tiers, forcing manufacturers to differentiate through dermatological certifications rather than base material specifications.
Growth Catalysts
- REACH substance restrictions:European fluorinated polymer bans redirect R&D investment toward non-fluorinated microporous alternatives, accelerating material innovation cycles.
- China's GB standards for infant product safety:SAMR national standards for disposable hygiene products tighten specifications, elevating compliance barriers that favor established film suppliers with testing infrastructure.
- Calcium carbonate filler stretching processes:Cast extrusion with controlled biaxial orientation achieves MVTR values exceeding 2,500 g/m²/24hr, enabling skin health claims in pharmacy channel positioning.
Market Restraints
- Polyethylene resin price volatility:Feedstock cost fluctuations compress margin pools for converters lacking backward integration into polymer sourcing.
- Asian OEM supply chain concentration:Ultra-thin polyolefin membrane production clusters in Japan and South Korea, creating single-source vulnerability for Western diaper brands.
- Biodegradable polymer performance ceiling:PLA and PHA alternatives fail to match polyethylene sealability at equivalent line speeds, limiting substitution in high-volume converting operations.
Strategic Opportunities
- India's underpenetrated premium diaper segment:BIS certification requirements and rising middle-class dermatological awareness create white space for MVTR-optimized films in tier-one cities.
- EU Green Deal packaging mandates:Extended producer responsibility legislation drives demand for certified compostable backsheet films in German and French retail channels.
- E-commerce direct-to-parent subscription models:Bypassing traditional retail distribution enables customized SKU development with specialized breathable film specifications.
Industry Challenges
- Biocompatibility testing timeline compression:FDA 510(k) clearance pathways for novel infant contact materials extend development cycles by 12-18 months.
- Dual certification complexity:Simultaneous compliance with EU F-Gas Regulation and China's dual carbon goals fragments product architectures and multiplies qualification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breathable Films for Baby Care Market |
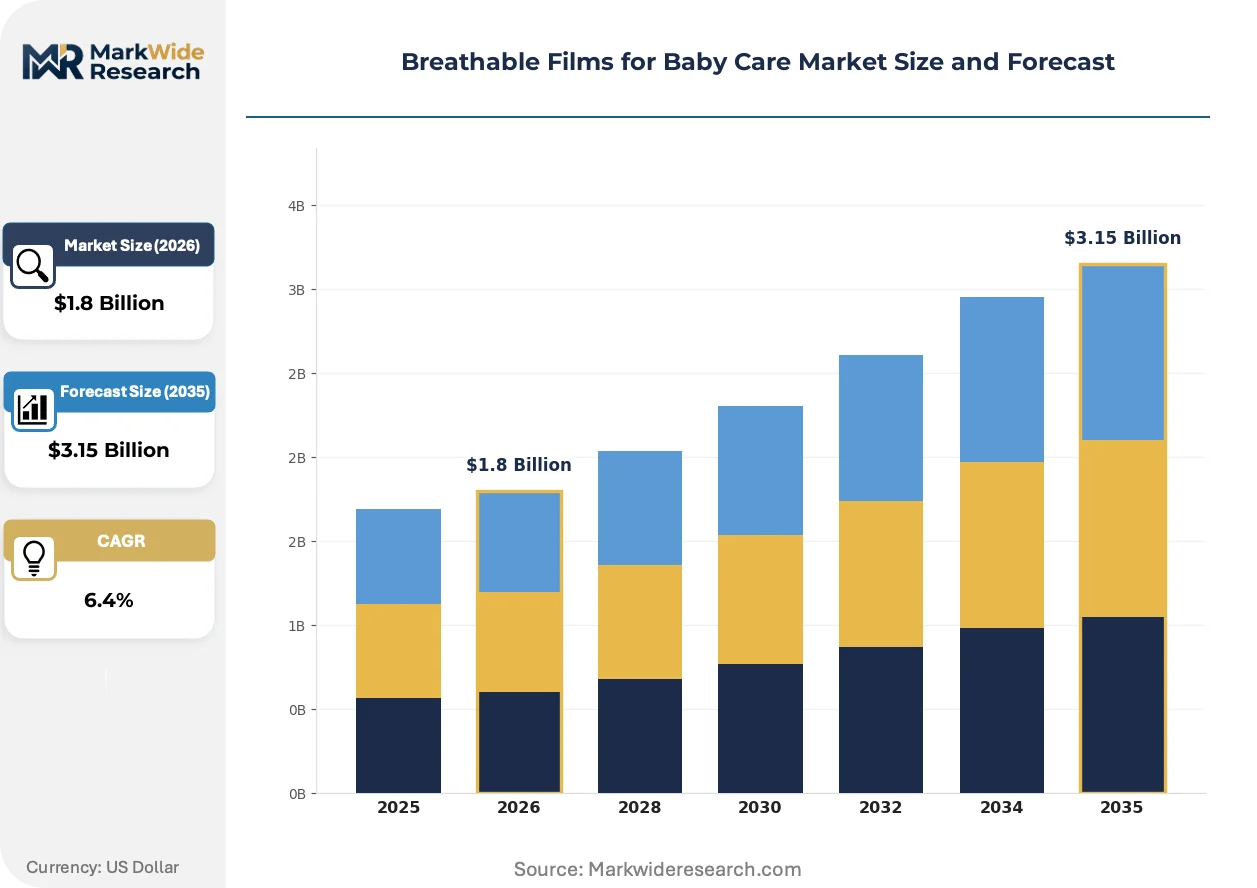
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diapers, Wipes, Liners, Underpads Material: Polyethylene, Polyurethane, Biodegradable Polymers, Nylon Form: Sheets, Laminates, Coatings, Films End User: Parents, Caregivers, Hospitals, Childcare Centers |
| Companies Covered | Procter & Gamble, Kimberly-Clark Corporation, Unicharm Corporation, Berry Global Inc., Toray Industries Inc., Schweitzer-Mauduit International, Inc., Arkema, Fatra, a.s., RKW Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breathable Films for Baby Care Market Trends and Innovations
Material science convergence with sustainability mandates is rewriting competitive differentiation rules. Manufacturers now compete on certification depth rather than throughput scale.
Biodegradable polymer formulations are migrating from laboratory validation to commercial diaper backsheet deployment. European retailers with plastic-reduction commitments pilot PLA-PHA blends in private-label SKUs. This migration from petroleum-based polyethylene is compressing the premium pricing umbrella for conventional microporous films.
REACH substance restrictions and the EU F-Gas Regulation now prohibit per- and polyfluoroalkyl substances in infant contact materials. European converters accelerate non-fluorinated microporous technology qualification. Premium diaper tiers in Germany and France absorb reformulation costs through pharmacy channel markups.
Parent purchasing behavior now prioritizes dermatological safety certifications over absorbency metrics. Pharmacy and specialty retail channels capture volume from mass-market outlets. This shift concentrates margin pools in wipe and liner categories with specialized skin health positioning.
Breathable Films for Baby Care Market Segmentation
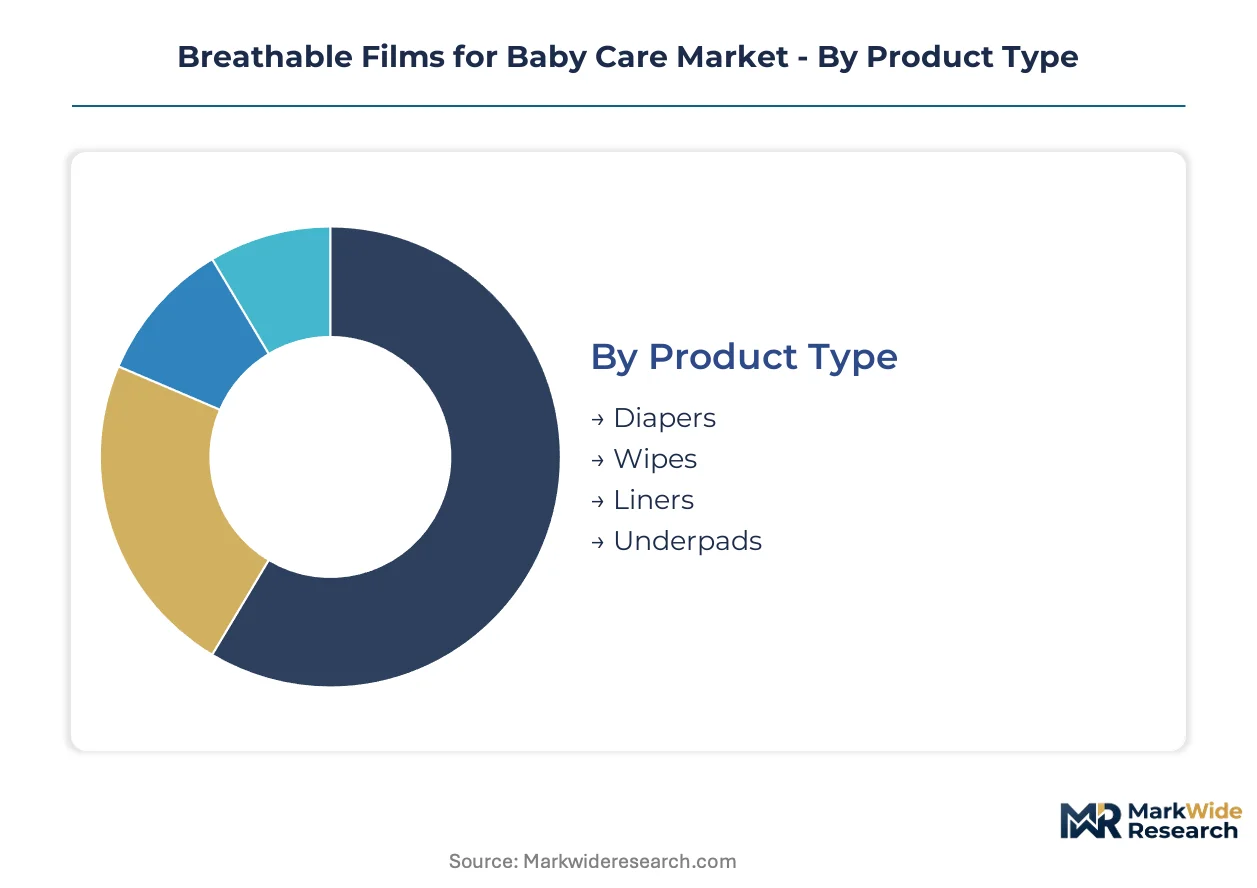
Breathable film specifications diverge sharply across baby care applications, with moisture vapor transmission rates and dermatological safety certifications determining material selection. Each segment category reflects distinct performance thresholds and regulatory compliance burdens that reshape supplier positioning.
Product Type:
Application function dictates film architecture, with liquid containment versus skin contact intensity driving pore density and laminate complexity.
- Diapers:Microporous polyethylene backsheet films with MVTR values exceeding 2,500 g/m²/24hr dominate volume. Demand concentrates in the United States and Germany where pharmacy-channel premium tiers absorb reformulation costs for fluorinated-free alternatives under REACH and EU F-Gas Regulation constraints.
- Wipes:Nonwoven-film laminates require lower breathability but stricter FDA biocompatibility certification for direct infant skin contact. Margin pools concentrate through specialized dermatological positioning in French and German pharmacy retail.
- Liners:Ultra-thin polyolefin membranes for diaper inserts prioritize cost scalability over advanced MVTR performance.
- Underpads:Multi-layer breathable barriers for bedding protection emphasize liquid strike-through resistance over vapor transmission efficiency.
Diapers command the established base. The steepest expansion runs through wipes.
Material:
Cost tier and sustainability positioning split procurement patterns between petroleum-derived standards and emerging biodegradable alternatives.
- Polyethylene:Cast extrusion with calcium carbonate filler stretching achieves commercial MVTR thresholds at lowest unit cost. Feedstock price volatility in Asian polymer markets compresses margins for converters lacking backward integration.
- Biodegradable Polymers:PLA-PHA blends are migrating from laboratory validation to commercial diaper backsheet deployment in European private-label SKUs. Germany and France pilot certified compostable films under EU Green Deal packaging mandates, though sealability gaps at high line speeds constrain volume scaling.
- Polyurethane:Thermoplastic formulations deliver superior elasticity for fitted diaper applications but carry premium pricing that limits mass-market penetration.
- Nylon:High-tensile strength films serve niche medical-grade underpad segments requiring puncture resistance.
Polyethylene anchors current supply. Biodegradable alternatives are climbing the fastest.
Form:
Manufacturing integration depth determines whether converters purchase raw films or pre-assembled functional laminates.
- Films:Standalone microporous membranes, typically 10–30 micrometers thick with controlled 0.1–3.0 micron pore densities, supply integrated diaper manufacturers with in-house converting capabilities.
- Laminates:Pre-bonded multi-layer structures combining breathable films with nonwoven topsheets reduce line complexity for mid-tier converters lacking biaxial orientation equipment.
- Sheets:Flat-stock supply for custom die-cutting operations in specialized medical and childcare institutional procurement.
- Coatings:Liquid-applied breathable barriers for retrofit wipe substrate upgrades in private-label manufacturing.
Films retain the volume base. Laminates are gaining share fastest through outsourcing trends among mid-tier brands.
End User:
Customer type fragments purchasing criteria between retail parent convenience and institutional procurement compliance.
- Parents:Direct-to-consumer subscription models enable customized SKU development with specialized breathable film specifications, bypassing traditional retail distribution markups.
- Hospitals:Neonatal intensive care units demand FDA-cleared materials with extended biocompatibility documentation, extending supplier qualification timelines.
- Caregivers:Home health aides prioritize cost efficiency and reliable supply continuity over advanced dermatological certifications.
- Childcare Centers:Bulk procurement through institutional distributors emphasizes unit economics and standardization across age-group product lines.
Parents drive premium innovation through direct channels. Hospitals impose the most demanding certification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German microporous film manufacturers export specialized backsheet materials to North American diaper converters, establishing a transatlantic trade corridor that channels REACH-compliant formulations into premium private-label supply chains.
United States
FDA biocompatibility requirements for infant contact materials elevate qualification barriers for imported films. Procter & Gamble and Kimberly-Clark anchor domestic demand through integrated polymer sourcing and captive converting operations in Wisconsin and Ohio. Pharmacy-channel premium tiers absorb reformulation costs for dermatological certifications.
Germany
EU F-Gas Regulation and REACH substance restrictions prohibit fluorinated polymers in baby care applications, redirecting R&D toward non-fluorinated microporous alternatives. RKW Group and specialized converters cluster in North Rhine-Westphalia, piloting certified compostable backsheet films under EU Green Deal packaging mandates for French and Dutch retail channels.
China
SAMR national standards for disposable hygiene products tighten material specifications, favoring established film suppliers with testing infrastructure. Toray Industries supplies ultra-thin polyolefin membranes to domestic OEMs concentrated in the Yangtze River Delta, where diaper production scales for both domestic consumption and Southeast Asian export.
Japan
METI industrial standards and PMDA biocompatibility frameworks govern infant contact material approvals. Toray Industries and specialized chemical divisions in the Kansai region dominate Asian OEM supply chains for ultra-thin membrane technologies, with production gravity in Osaka-Kobe industrial corridors serving South Korean and Taiwanese converters.
India
BIS certification requirements and rising middle-class dermatological awareness create white space for MVTR-optimized films in Mumbai and Delhi-NCR tier-one markets. Unicharm Corporation and regional distributors expand technical sales presence to capture premium diaper segment growth ahead of localized manufacturing scale-up.
Breathable Films for Baby Care Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where integrated hygiene manufacturers hold volume leverage while independent film converters capture margin in certified specialty grades. The vendor base separates into three strategic archetypes: multinational hygiene conglomerates with captive film production, independent microporous specialists serving OEM private-label channels, and diversified chemical conglomerates with polymer science legacies. Competitive moves concentrate on backward integration into calcium carbonate filler compounding and strategic partnerships with European retailers seeking compostable certification pathways.
Among integrated hygiene manufacturers, Procter & Gamble and Kimberly-Clark exemplify the channel-control archetype through captive supply chains spanning polymer sourcing to retail shelf placement. Toray Industries occupies a specialist position as a Japanese manufacturer supplying ultra-thin polyolefin membranes to Asian OEMs and Western premium brands seeking dermatological-grade performance specifications. These three entities represent distinct competitive vectors: volume scale, regulatory compliance depth, and materials science specialization respectively.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark Corporation |
| Unicharm Corporation |
| Berry Global Inc. |
| Toray Industries Inc. |
| Schweitzer-Mauduit International, Inc. |
| Arkema |
| Fatra, a.s. |
| RKW Group |
| Others |
Pricing and Supply Chain Analysis
Japanese ultra-thin polyolefin membrane production clusters in Osaka-Kobe industrial corridors anchor margin pools in Western premium diaper tiers. Calcium carbonate filler compounding and biaxial orientation equipment ownership determine which converters capture value from MVTR-optimized specifications.
Pricing Analysis
Current-generation microporous polyethylene films with MVTR values exceeding 2,500 g/m²/24hr command premium positioning against prior-generation non-breathable barriers, while next-generation PLA-PHA biodegradable alternatives carry certification markups that compress the pricing umbrella for conventional petroleum-based films. Three-tier pricing structure across premium, standard, and economy levels separates pharmacy-channel dermatological certifications from mass-market leakage-prevention claims from private-label cost-optimized tiers. Price differentiation hinges on REACH compliance depth and FDA biocompatibility documentation tier. Pricing pressure stems from Asian OEM supply chain concentration in Japan and South Korea. Mid-tier converters lacking backward integration into polymer sourcing exhibit highest price sensitivity.
Supply Chain Analysis
REACH substance restrictions and EU F-Gas Regulation on fluorinated polymers limit technology transfer to non-European converters seeking REACH-compliant formulation access. Ultra-thin polyolefin membrane supply concentrates in Japan, South Korea, and Germany. Raw material dependencies rest on polyethylene resin, calcium carbonate fillers, and specialty polymer additives. Single-source vulnerability runs through Toray Industries' dominance in Asian OEM supply chains. Distribution runs through integrated hygiene manufacturers with captive converting operations and independent film converters serving private-label channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Breathable films for baby care constitute a defensive-moat market where regulatory entrenchment creates sustainable competitive advantages. Switching costs multiply through dual-certification requirements spanning FDA biocompatibility and REACH substance restrictions.
For Market Incumbents: Entrench market position through backward integration into calcium carbonate filler compounding and captive biaxial orientation equipment ownership. Accelerate non-fluorinated microporous technology qualification ahead of EU F-Gas Regulation enforcement. Defend against biodegradable polymer substitution by embedding compostable certification pathways into European retail partnerships. For New Entrants and Emerging Players: India's underpenetrated premium diaper segment in Mumbai and Delhi-NCR tier-one cities represents the most penetrable entry point for MVTR-optimized films with BIS certification compliance. German and French pharmacy-channel private-label SKUs piloting certified compostable backsheet films under EU Green Deal packaging mandates offer white-space positioning. Direct-to-parent e-commerce subscription models enable customized SKU development bypassing traditional retail distribution markups. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap independent microporous specialists serving OEM private-label channels with established testing infrastructure for SAMR and REACH compliance. Long-term viability across the analysis window favors converters with dual-certification capabilities spanning FDA and EU regulatory frameworks. Monitor biodegradable polymer sealability breakthroughs at high line speeds as inflection indicator for petroleum-based film displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Non-Fluorinated Microporous Technology Qualification | REACH and EU F-Gas Regulation compliance redirects R&D investment toward alternative formulations. |
| Backward Integration into Calcium Carbonate Filler Compounding | Captive raw material control insulates converters from polyethylene resin price volatility. |
| Certified Compostable Backsheet Film Deployment | EU Green Deal packaging mandates drive demand in German and French retail channels. |
| Direct-to-Consumer Subscription Model Launch | Pharmacy-channel premium tiers absorb reformulation costs through bypassed distribution markups. |
| Dual-Certification Testing Infrastructure Investment | SAMR and FDA compliance capabilities fragment regional product specifications favoring established suppliers. |
Research Methodology
Initial hypotheses were tested against primary input from microporous film R&D directors, diaper brand procurement managers, regulatory affairs leads at hygiene manufacturers, and European retail sustainability officers and refined through secondary validation. Technical specifications from SAMR national standards, FDA biocompatibility guidance documents, ECHA REACH substance restriction updates, and customs trade data on polyethylene resin flows anchored quantitative inputs. Bottom-up demand modeling across diaper, wipes, and liner applications triangulated against top-down market sizing from integrated hygiene manufacturer disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included product type, material formulation, manufacturing form, and end-user channel. CAGRs were derived from elasticity-adjusted volume projections calibrated to regulatory compliance timeline assumptions. Industry-specific forecast inputs incorporated MVTR performance tier adoption curves and biodegradable polymer line-speed compatibility milestones.
Practitioners should monitor regulatory enforcement intensity in Europe and China, biodegradable polymer sealability breakthroughs, and Asian OEM supply chain consolidation for early signals of forecast revision. Forecasts reflect assumptions on calcium carbonate filler cost trajectories and REACH substance restriction expansion scope. Material shifts in EU Green Deal packaging mandate enforcement timelines or FDA biocompatibility pathway modifications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food Packaging
North America Home Care Packaging Market
Baby Food Packaging
Europe Baby Food Packaging Market
Baby Food Packaging
Global Pet Food and Pet Product Packaging Market
Baby Food Packaging
Infant Formula Packaging Market
Baby Food Packaging
Europe Pet Food Packaging Market
Baby Food Packaging
Baby Care Packaging Market
Baby Food Packaging
Middle East and Africa Baby Food Packaging Market
Baby Food Packaging
APAC Baby Food Packaging Market
Baby Food Packaging
Baby Food Packaging Market
Baby Food Packaging
United States and Canada Child Resistant Bottles Market
Baby Food Packaging
US Pet Food Packaging Market
Baby Food Packaging
Asia-Pacific Child Resistant Packaging Market
Baby Food Packaging
United States Baby Food Packaging Market
Baby Food Packaging
Europe Home Care Packaging Market