
 Europe Home Care Packaging Market | 2026-2036
Europe Home Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Home Care Packaging Market Foresight
Private-label retailers and direct-to-consumer subscription services are bifurcating demand away from traditional mass-market channels in the Europe home care packaging landscape. Amcor PLC leverages its European film extrusion network to supply high-barrier mono-material pouches for concentrated laundry detergents. Berry Global Inc. sustains leadership in injection-molded containers through scale advantages across its German and French manufacturing footprint. Constantia Flexibles Group GmbH specializes in aluminum-based barrier laminates that preserve volatile fragrance compounds in fabric softener sachets.
Europe home care packaging encompasses rigid and flexible primary containers, closures, and secondary wrapping engineered to protect chemically active formulations from moisture ingress, oxidation, and mechanical damage during distribution and consumer use. These systems typically incorporate ethylene vinyl alcohol copolymer layers or metallized films to achieve oxygen transmission rates below 0.1 cc per square meter per day, ensuring twelve-to-twenty-four-month shelf stability for bleach and enzyme-containing products. Plastic bottles and pouches represent the dominant product type pairing, with pouches capturing incremental share as brands convert liquid detergents to concentrated refill formats that reduce shipping cube and resin intensity per wash load. Screw caps and flip tops lead closure type adoption, though spout-equipped pouches are displacing traditional bottle formats in automatic dishwasher gel and floor cleaner segments where controlled dosing matters.
The EU Green Deal and Packaging and Packaging Waste Regulation mandate minimum recycled content thresholds and design-for-recycling standards that reshape material selection across the value chain. ECHA maintains REACH restrictions on phthalate plasticizers and bisphenol derivatives that limit certain polymer options for food-contact-adjacent home care applications. France's AGEC law and extended producer responsibility schemes in Italy and Spain impose eco-modulated fees that penalize non-recyclable multimaterial constructions. Stakeholders must monitor evolving recyclability assessment protocols and pre-emptively validate alternative barrier technologies before compliance deadlines tighten material specifications.
Market Dynamics
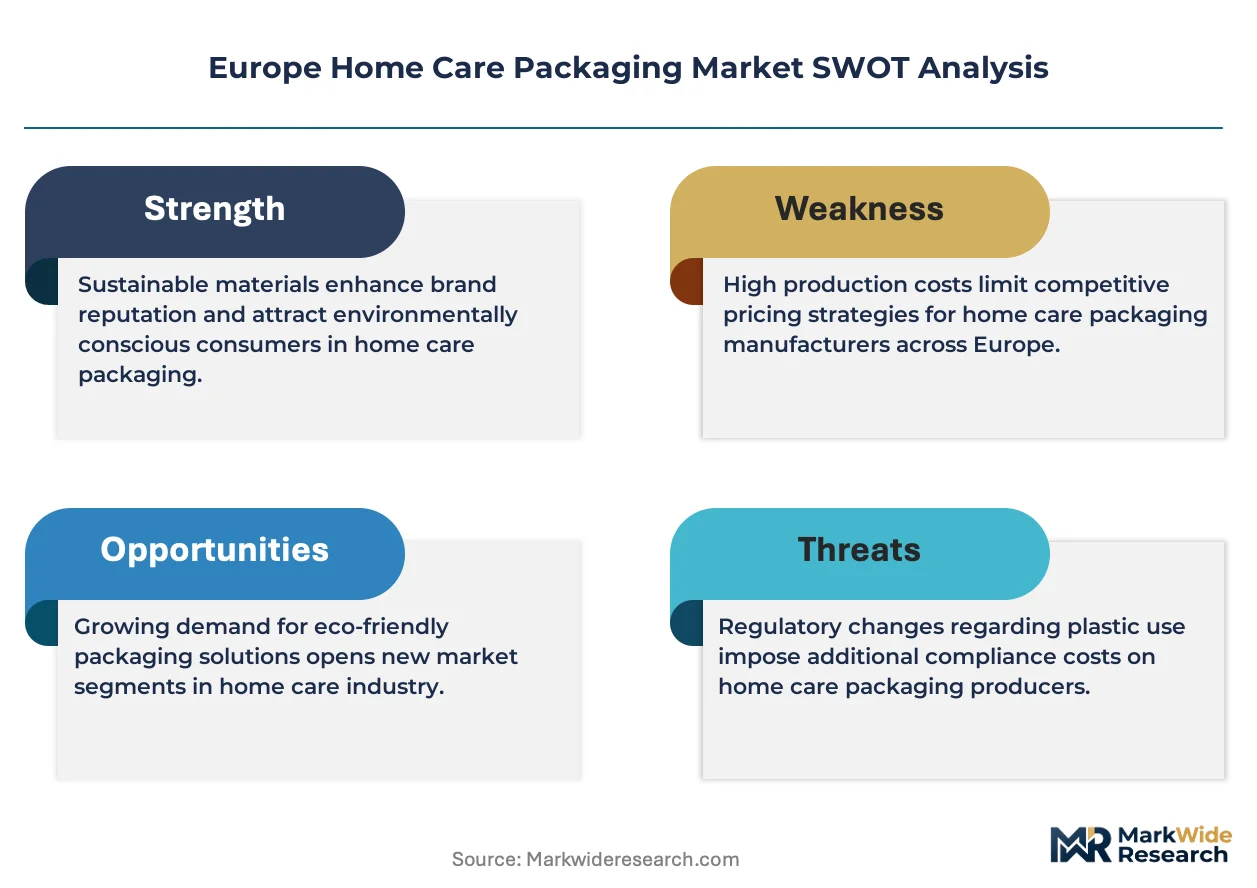
The EU Green Deal and Packaging and Packaging Waste Regulation are forcing a wholesale redesign of material specifications across European home care packaging value chains, with mono-material constructions and post-consumer recycled content mandates now determining procurement criteria for major retailers.
Growth Catalysts
- Concentrated Refill Formats:Premium eco-conscious households in Germany and France are expanding purchases of pouch-based laundry detergents that reduce resin intensity per wash load while cutting distribution costs.
- Ecodesign Mandates:The EU Green Deal's recyclability standards are accelerating investment in compatible barrier technologies and sorting infrastructure across member states.
- Extended Producer Responsibility:France's AGEC law and Italian eco-modulated fee structures are penalizing multimaterial constructions and rewarding design-for-recycling compliance.
Market Restraints
- Barrier Technology Limitations:Current mono-material films struggle to match ethylene vinyl alcohol copolymer oxygen transmission rates below 0.1 cc per square meter per day for bleach formulations.
- Recycled Feedstock Scarcity:Food-grade post-consumer recycled resin availability concentrates in Germany and the Netherlands, creating geographic supply bottlenecks.
- ECHA REACH Restrictions:Phthalate plasticizer and bisphenol derivative limitations constrain polymer selection for kitchen-surface-adjacent home care applications.
Strategic Opportunities
- Spanish and Italian Market Expansion:Private-label sustainability commitments in these markets lag northern Europe, creating first-mover advantage for compliant packaging suppliers.
- Direct-to-Consumer Subscription Channels:Concentrated refill pouches paired with returnable containers are bypassing traditional retail distribution in the United Kingdom.
- Digital Watermark Integration:Combination of invisible marker technologies with existing mono-material structures enables improved sortation accuracy at European recycling facilities.
Industry Challenges
- Barrier Material R&D Timeline:Developing EVOH-equivalent performance in recyclable mono-material films requires 18-24 month validation cycles against twelve-month regulatory deadlines.
- Legacy Equipment Retrofit Costs:Converting existing form-fill-seal lines to handle spout-equipped pouches demands capital outlay that mid-tier converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Home Care Packaging Market |
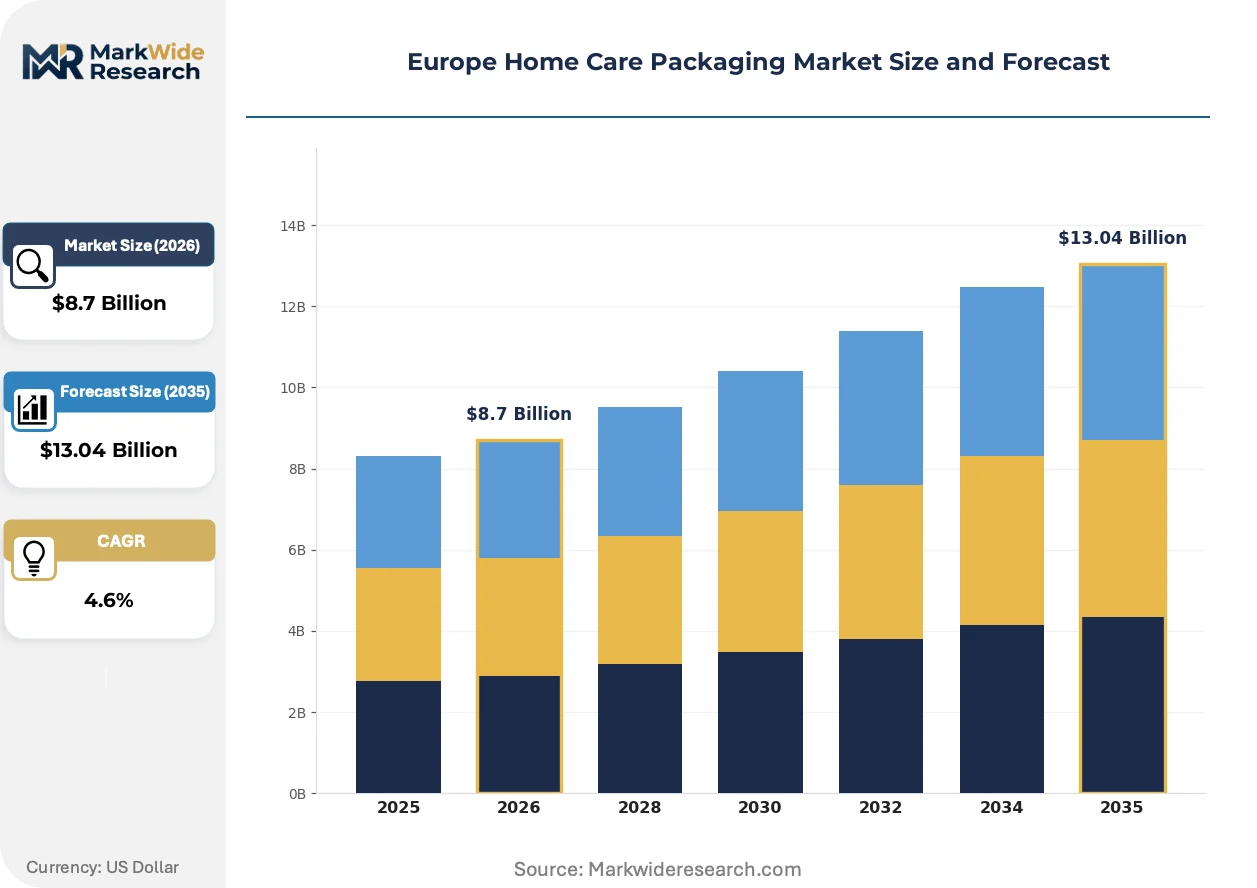
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Glass, Metal, Paper Product Type: Bottles, Containers, Pouches, Tubs Closure Type: Screw Caps, Flip Tops, Spouts, Rigid Seals Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Constantia Flexibles Group GmbH, Berry Global Inc., Amcor PLC, Silgan Holdings, Ball Corporation, Sonoco Products Company, DS Smith PLC, RPC Group, AptarGroup Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Home Care Packaging Market Shifts & Advancements
Material science breakthroughs and regulatory compliance pressures are converging to transform how European home care products are contained, dosed, and recovered at end-of-life.
Spout-equipped stand-up pouches is displacing rigid bottles in automatic dishwasher gel and floor cleaner segments where controlled dosing matters. German and British retailers are expanding shelf space allocation for these formats at the expense of traditional screw-cap containers. The shift is compressing demand for injection-molded HDPE bottles while expanding orders for high-barrier film laminates and precision-molded dispensing closures.
France's AGEC law and the broader EU Packaging and Packaging Waste Regulation are mandating minimum recycled content thresholds and standardized recyclability assessment protocols. These rules are disqualifying multimaterial laminates from premium retail placement and forcing reformulation of fragrance-preserving barrier systems. Italian and Spanish converters are accelerating pilot programs with aluminum-based mono-material alternatives to preserve volatile compounds while meeting design-for-recycling standards.
Subscription-based replenishment models are displacing supermarket bulk purchasing among urban professional households in London, Paris, and Berlin. These services specify concentrated refill pouches in returnable outer containers, eliminating secondary cardboard packaging and compressing last-mile delivery volumes. The model is most visible in fabric care and surface cleaner categories where brand loyalty is lower and convenience premiums are accepted.
Europe Home Care Packaging Market Segmentation
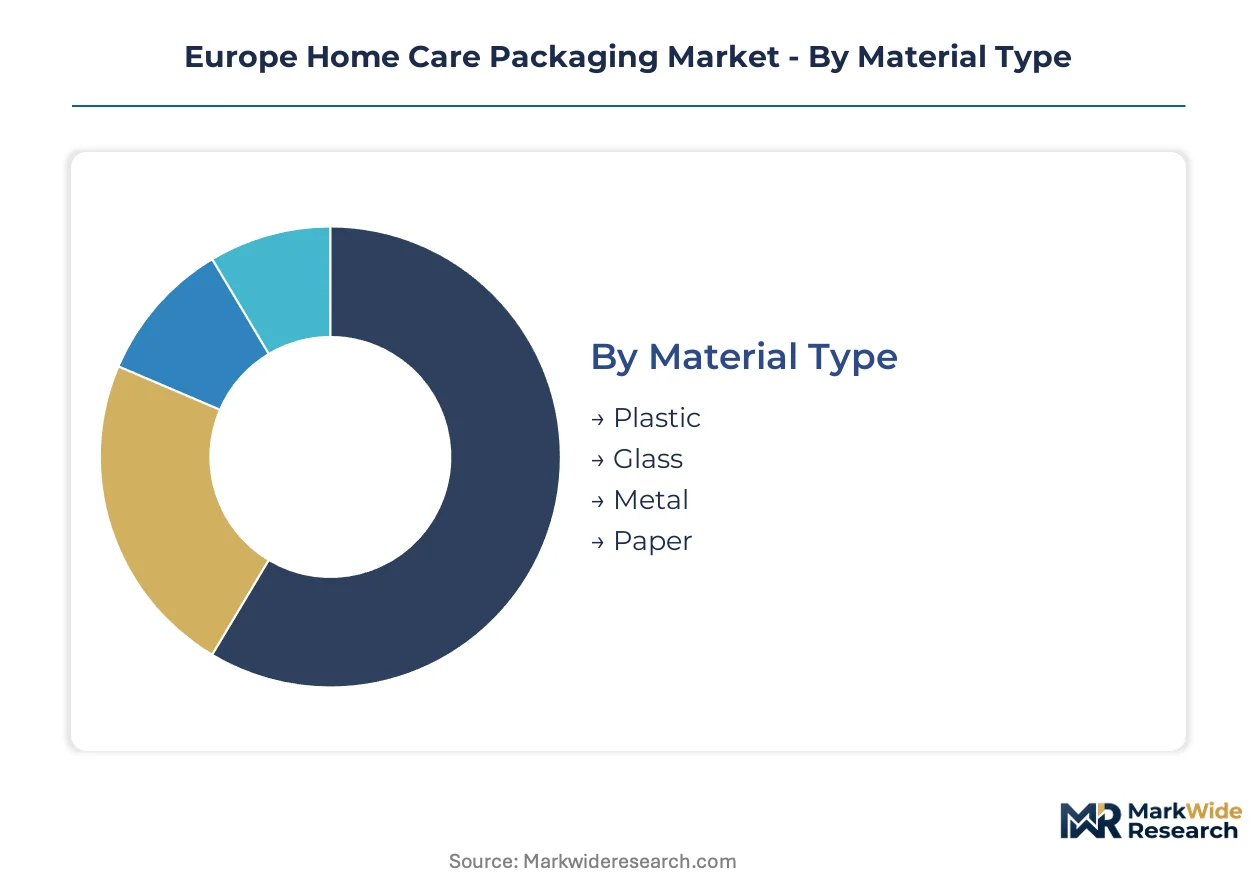
Home care packaging procurement in Europe splits across material technologies, format geometries, and channel economics. Understanding these segment boundaries clarifies where compliance costs concentrate and where margin expansion remains achievable.
Material Type:
Plastic commands the largest channel flow through supermarkets and wholesale, while glass and metal see premium placement in online retail and specialty convenience formats.
- Plastic:Polyethylene terephthalate and high-density polyethylene dominate rigid formats, with linear low-density polyethylene films capturing flexible pouch growth. German converters supply mono-material constructions to Aldi and Lidl private-label programs under EU Green Deal recyclability mandates.
- Glass:Amber and flint borosilicate containers preserve aromatic surface cleaners and premium dish soaps. French AGEC law eco-modulated fees disadvantage glass versus lighter alternatives, compressing volume in mass-market channels while sustaining niche online subscription presence.
- Metal:Tinplate and aluminum aerosol cans serve oven cleaners and air fresheners. Italian extended producer responsibility schemes impose lower fees on aluminum versus steel, tilting procurement toward aluminum-based mono-material solutions.
- Paper:Molded fiber and corrugated secondary packaging see demand from e-commerce fulfillment centers in the Netherlands and Poland. REACH restrictions on fluorinated coatings limit grease-resistance performance for paper-primary formats.
Plastic dominates installed base. Paper is where expansion concentrates.
Product Type:
Format selection tracks dosing precision requirements and supply chain cube efficiency, with concentrated chemistry driving pouch adoption and dilutable formulations sustaining bottle volumes.
- Bottles:Injection-molded HDPE and PET containers with handle geometries serve bulk laundry detergents and bleach in German and British supermarkets. EVOH multilayer co-injection maintains oxygen barrier for enzyme stability.
- Pouches:Spout-equipped stand-up laminates displace bottles in automatic dishwasher gels and floor cleaners where controlled dosing matters. French retailers allocate expanding shelf space to these formats.
- Containers:Wide-mouth polypropylene tubs package powder detergents and dissolvable pods. Italian converters supply tamper-evident rim designs for child-safety compliance.
- Tubs:Thin-wall injection-molded formats serve institutional bulk purchases through wholesale channels in Spain and Portugal. Lower unit economics versus pouches constrain retail penetration.
Bottles retain the largest production footprint. Pouches are climbing the fastest.
Closure Type:
Dispensing precision and child-resistance specifications determine closure selection, with spout geometries gaining traction in direct-to-consumer channels requiring controlled dosing.
- Screw Caps:Polypropylene continuous-thread designs dominate bottle formats across all retail channels. German tooling suppliers maintain capacity leadership for high-cavitation molds serving pan-European brand owners.
- Flip Tops:Living-hinge polyolefin closures serve frequent-access surface cleaners in kitchen and bathroom segments. British private-label retailers specify tethered designs for litter-reduction compliance.
- Spouts:Precision-molded dispensing fitments integrate with pouch laminates for viscous gels and concentrates. Dutch converters develop mono-material spout solutions to satisfy design-for-recycling protocols.
- Rigid Seals:Peelable aluminum and induction-sealed membranes protect powder tubs and wipe canisters from moisture ingress. Italian packaging machinery suppliers specialize in high-speed sealing lines.
Screw caps anchor volume. Spouts are gaining share fastest.
Distribution Channel:
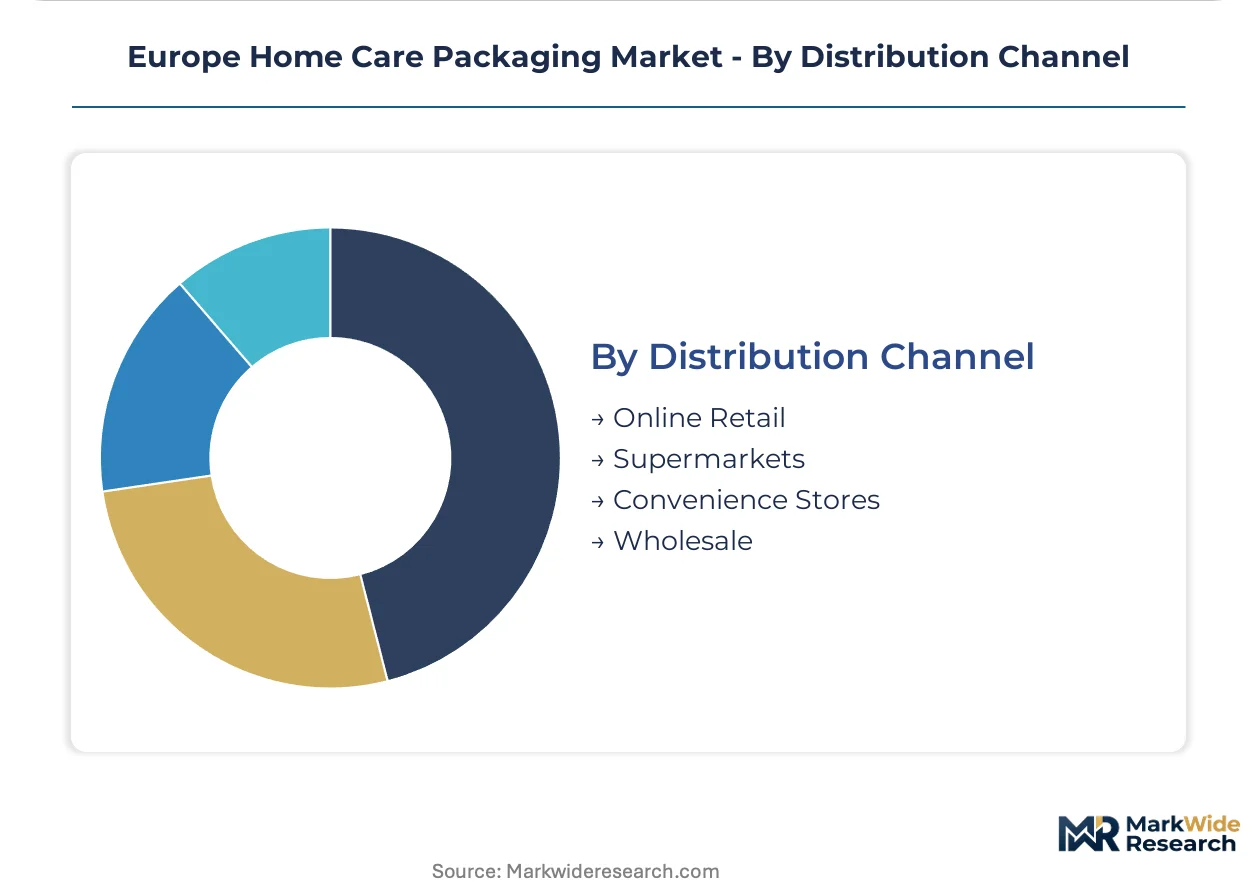
Channel mix determines format specifications and order economics, with online retail demanding damage-resistant secondary packaging and supermarkets driving shelf-ready primary designs.
- Supermarkets:Aldi, Lidl, Carrefour, and Tesco set packaging specifications through private-label procurement. Shelf-ready secondary packaging and standardized pallet configurations dominate volume.
- Online Retail:Amazon and direct-to-consumer subscription services specify concentrated refill pouches in returnable outer containers. Last-mile cube reduction drives format innovation.
- Convenience Stores:Smaller format bottles and single-use sachets serve immediate-need purchasing in urban locations. Higher unit economics versus bulk formats constrain margin.
- Wholesale:Institutional and hospitality supply through Metro and Booker demands bulk containers and drum formats. Lower frequency, higher volume orders favor rigid packaging durability.
Supermarkets command procurement volume. Online retail is where steepest expansion trajectory sits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters export high-barrier mono-material films to French and British retailers under EU Green Deal compliance deadlines, anchoring cross-border procurement flows in the region.
Germany
Aldi and Lidl private-label programs drive concentrated refill pouch adoption across laundry and dishwasher categories. The country's national packaging regulator enforces extended producer responsibility schemes that penalize multimaterial constructions. The Rhine-Main industrial corridor hosts film extrusion clusters supplying pan-European brand owners with recyclable barrier laminates.
France
Urban professional households in Paris and Lyon subscribe to direct-to-consumer fabric care services specifying returnable outer containers. France's AGEC law imposes eco-modulated fees that reward design-for-recycling compliance and disadvantage glass formats. The Lyon-Auvergne-Rhône-Alpes region concentrates aluminum-based mono-material pilot programs for fragrance-preserving applications.
United Kingdom
Tesco and Sainsbury's sustainability commitments reshape procurement criteria for surface cleaner bottles and closures. British tethered closure mandates under litter-reduction protocols influence living-hinge polyolefin specifications. The Midlands packaging machinery cluster specializes in high-speed sealing lines for powder tub applications.
Italy
Institutional bulk purchasing through wholesale channels sustains wide-mouth polypropylene tub demand for powder detergents. Italian extended producer responsibility schemes impose lower fees on aluminum versus steel aerosol formats. The Emilia-Romagna converter base supplies tamper-evident rim designs meeting child-safety compliance standards.
Spain
Private-label sustainability commitments lag northern European benchmarks, creating first-mover advantage for compliant packaging suppliers entering Carrefour and Mercadona supply chains. Spanish eco-modulated fee structures under EU Packaging and Packaging Waste Regulation implementation timelines accelerate local converter investment in sorting infrastructure. The Barcelona metropolitan area hosts emerging flexible packaging operations targeting southern European distribution networks.
Europe Home Care Packaging Market Competitive Landscape
Listed leaders compete with private specialists across film extrusion and injection-molding capabilities in the Europe home care packaging landscape. The supplier base organizes around three strategic archetypes: integrated multinationals with European manufacturing footprints, mid-tier regional converters serving private-label retailers, and specialized barrier technology developers. Capacity expansion and strategic partnerships dominate competitive moves as firms position for EU Green Deal compliance deadlines.
Within the integrated multinational tier, Amcor PLC and Berry Global Inc. exemplify scale-driven positions anchored in German and French production networks. Constantia Flexibles Group GmbH occupies a specialist position focused on aluminum-based barrier solutions. These three entities represent distinct strategic postures—film extrusion leadership, injection-molded container scale, and metallized laminate specialization—without overlapping core capability claims.
| Leading Market Players |
|---|
| Constantia Flexibles Group GmbH |
| Berry Global Inc. |
| Amcor PLC |
| Silgan Holdings |
| Ball Corporation |
| Sonoco Products Company |
| DS Smith PLC |
| RPC Group |
| AptarGroup Inc |
| Others |
Supply & Pricing Matrix
EU Green Deal recyclability certification gates supplier qualification and price differentiation simultaneously, with mono-material barrier compliance separating premium-tier converters from commodity resin processors across German and French procurement networks.
Pricing Analysis
Prior-generation EVOH multilayer films command premium pricing against emerging mono-material alternatives, while next-generation aluminum-based barrier laminates trade at mid-tier positioning. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with Aldi and Lidl private-label programs squeezing mid-tier converters through consolidated annual contracts. Cost compression in standard-tier injection-molded containers is intensifying because German retailers are consolidating supplier panels. Mass-market supermarket buyers exhibit highest price sensitivity, while direct-to-consumer subscription services accept convenience premiums for returnable outer container systems.
Supply Chain Analysis
Just-in-time inventory strategies dominate flexible film procurement from German extrusion clusters, while strategic stockpiling of post-consumer recycled resin concentrates in Dutch and Belgian hub facilities. Raw material supply draws from Saudi Arabian polyethylene feedstock, German ethylene vinyl alcohol copolymer production, and Italian aluminum rolling mills. Single-source vulnerability runs through EVOH barrier film supply anchored in Japanese and German chemical conglomerates. Distribution runs through pan-European logistics networks serving Aldi, Lidl, Carrefour, and Tesco regional distribution centers with standardized pallet configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation compliance deadlines are compressing supplier qualification windows, creating high-growth disruption as mono-material barrier R&D separates viable competitors from stranded asset holders.
For Market Incumbents: Shield market position by accelerating backward integration into post-consumer recycled resin supply through Dutch and Belgian hub partnerships. Prioritize certification investment for EU Green Deal design-for-recycling protocols before French AGEC law eco-modulated fees tighten. Defend against emerging mono-material specialists by locking multi-year supply agreements with German retailer private-label programs.
For New Entrants and Emerging Players: Lead with aluminum-based mono-material barrier laminates targeting fragrance-preserving fabric softener applications where Italian and Spanish converters lag northern European compliance benchmarks. Target Carrefour and Mercadona supply chains in Spain where sustainability commitments trail German benchmarks. Pursue direct-to-consumer channel partnerships in London and Paris subscription services as the go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier European converters burdened by legacy EVOH multilayer equipment and stranded resin supply contracts. Five-to-ten-year viability hinges on successful mono-material transition before regulatory deadlines eliminate multimaterial formats. Watch Italian and Spanish converter consolidation activity as the inflection signal indicating compliance-driven market restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier R&D Investment | Amcor and Constantia Flexibles are racing to validate EVOH-equivalent oxygen transmission in recyclable films before EU deadlines. |
| Post-Consumer Recycled Resin Integration | German converters are securing long-term supply agreements with Dutch recycling facilities to meet minimum content thresholds. |
| Spout-Equipped Pouch Capacity Expansion | French retailers are allocating expanded shelf space to controlled-dosing formats in automatic dishwasher and floor cleaner segments. |
| Direct-to-Consumer Channel Partnership | London and Berlin subscription services are specifying concentrated refill pouches in returnable outer containers. |
| Digital Watermark Technology Pilot | Dutch converters are integrating invisible marker technologies with mono-material structures to improve European recycling facility sortation accuracy. |
Research Methodology
A spread of perspectives from packaging procurement managers at Aldi and Lidl, technical R&D directors at German film extrusion facilities, sustainability compliance officers at French retailers, and machinery specialists in the Midlands converged on the working assumptions. Primary interview insights combined with secondary validation from EU Packaging and Packaging Waste Regulation implementation documents, ECHA REACH restriction updates, French AGEC law fee schedules, and customs trade data for polyethylene and aluminum imports. Bottom-up capacity estimates from converter facilities triangulated against top-down demand projections from retailer private-label procurement volumes.
Segmentation dimensions modeled include material type, product format geometry, closure dispensing mechanism, and distribution channel economics across the analysis window. CAGRs were derived from regression analysis of historical procurement volumes and regulatory compliance-driven substitution elasticities. Forecast inputs incorporated EU Green Deal implementation timelines, extended producer responsibility fee structures, and post-consumer recycled resin availability constraints from German and Dutch supply hubs.
Forecasts assume regulatory continuity in EU Green Deal and Packaging and Packaging Waste Regulation implementation; material policy shifts accelerating or delaying mono-material mandates would require re-modeling. ECHA REACH restriction expansions beyond phthalates and bisphenols could constrain polymer options further. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food Packaging
Middle East and Africa Baby Food Packaging Market
Baby Food Packaging
Baby Care Packaging Market
Baby Food Packaging
US Pet Food Packaging Market
Baby Food Packaging
APAC Baby Food Packaging Market
Baby Food Packaging
Baby Food Packaging Market
Baby Food Packaging
Europe Baby Food Packaging Market
Baby Food Packaging
Asia-Pacific Child Resistant Packaging Market
Baby Food Packaging
United States Baby Food Packaging Market
Baby Food Packaging
Infant Formula Packaging Market
Baby Food Packaging
Europe Pet Food Packaging Market
Baby Food Packaging
Breathable Films for Baby Care Market
Baby Food Packaging
Global Pet Food and Pet Product Packaging Market
Baby Food Packaging
United States and Canada Child Resistant Bottles Market
Baby Food Packaging
North America Home Care Packaging Market