
 United States Baby Food Packaging Market | 2026-2036
United States Baby Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States Baby Food Packaging Market Analytics
Market Context
Buyer concentration among national supermarket chains and mass merchandisers is hardening, pressuring regional baby food brands to align with centralized packaging specifications. Amcor PLC leverages its North American flexibles footprint to secure multi-year supply agreements with top grocery retailers. Sonoco Products Company anchors its position through rigid paperboard composite expertise tailored to shelf-stable infant nutrition. Mondi PLC competes via fiber-based barrier innovations that address retailer sustainability scorecards.
Technical Definition and Segment Structure
United States Baby Food Packaging encompasses primary and secondary containment systems engineered to preserve nutritional integrity, prevent microbial ingress, and enable controlled dispensing for commercially prepared infant and toddler foods. These systems typically incorporate oxygen-barrier laminates, tamper-evident closures, and sterilization-compatible substrates to satisfy shelf-stability requirements from manufacture through consumption. Pouches command the fastest expansion among packaging types, driven by parental demand for portability and reduced per-serving waste. Plastic retains volume leadership across materials, though fiber-based alternatives are capturing margin pools in organic and premium-positioned product lines. Glass jar demand persists in conventional retail segments where transparency and resealability sustain consumer trust.
Regulatory Framework
FDA food contact notification protocols govern substance migration limits for all packaging materials touching infant formula and baby food, while state-level extended producer responsibility legislation in California and Oregon reshapes post-consumer recovery obligations for brand owners. USDA organic certification requirements indirectly influence packaging material selection by restricting certain adhesives and coatings in certified-product supply chains. Stakeholders must monitor evolving state patchworks for recycled-content mandates and assess whether current barrier technologies can maintain shelf life under reformulated substrate compositions.
Market Dynamics
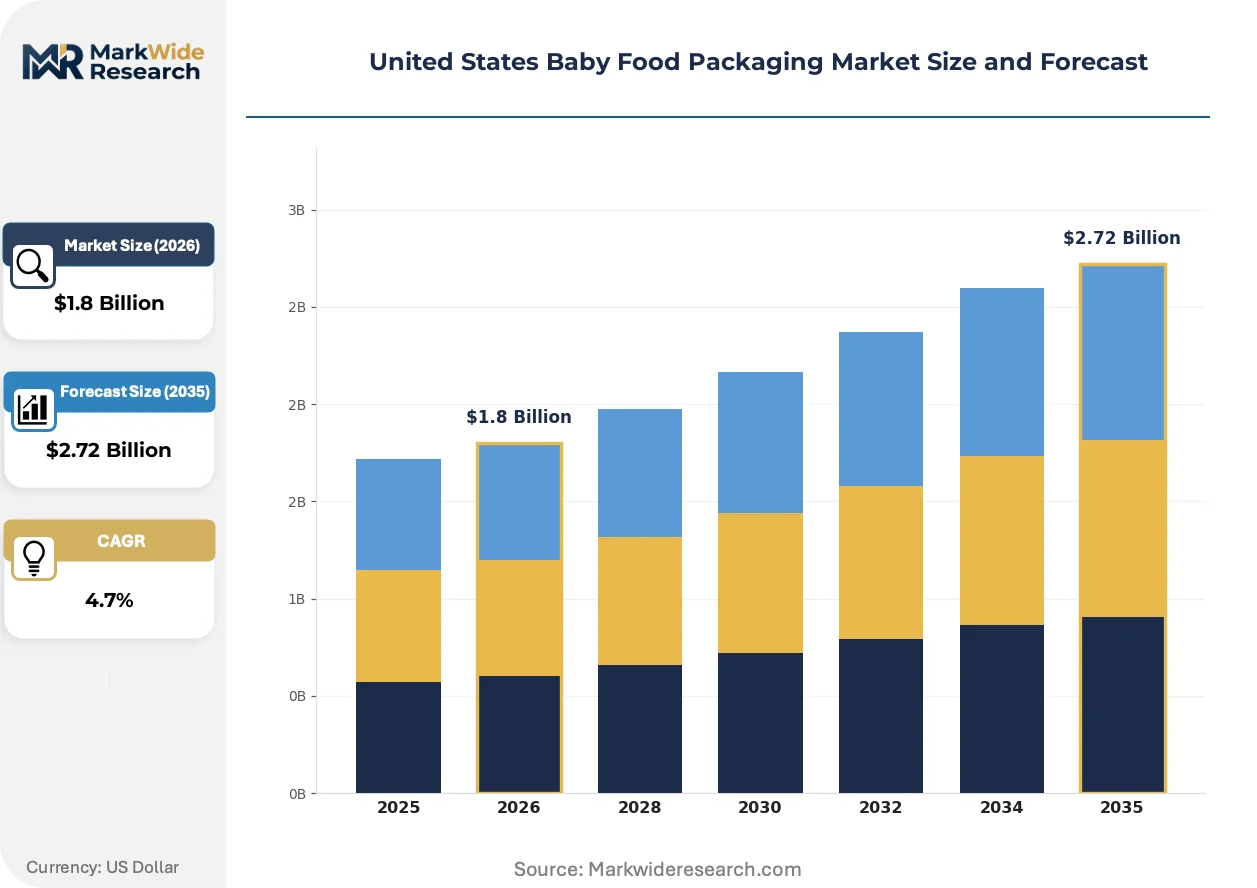
Retailer sustainability scorecards are forcing baby food brands to reformulate packaging substrates ahead of federal mandates, compressing supplier qualification timelines and elevating fiber-based barrier technologies from niche to mainstream specification requirements.
Growth Catalysts
- California EPR frameworks:Extended producer responsibility legislation in California and Oregon mandates post-consumer recovery targets that accelerate demand for recyclable mono-material pouches and paperboard composites.
- Pouch portability preference:Parental demand for on-the-go feeding solutions drives rapid format conversion from rigid glass and plastic jars to flexible stand-up pouches with spout fitments.
- Organic certification spillover:USDA organic restrictions on adhesives and coatings in certified supply chains push brands toward cleaner substrate formulations that incidentally improve recyclability profiles.
Market Restraints
- Resin supply concentration:Ethylene and propylene feedstock volatility tied to Gulf Coast petrochemical clusters exposes flexible film converters to margin compression during energy price spikes.
- Barrier performance ceilings:Current fiber-based oxygen barriers fail to match multi-layer plastic laminate shelf-life performance for lipid-rich infant formulas, limiting format substitution.
- FDA notification timelines:Food contact substance notification review periods for novel biodegradable polymers extend commercialization cycles by 18-24 months versus conventional materials.
Strategic Opportunities
- Texas private-label clusters:Concentrated contract manufacturing capacity in Dallas-Fort Worth and Houston metro areas creates regional packaging procurement hubs serving emerging organic brands.
- Curbside-recyclable pouch formats:How2Recycle store drop-off compatible structures open shelf access at mass merchandisers with strict sustainability vendor scorecards.
- Smart dispensing integration:Convergence of near-field communication tags with portion-control spouts enables pediatric nutrition tracking apps and subscription replenishment models.
Industry Challenges
- Barrier chemist scarcity:Formulation expertise spanning both polymer science and paper fiber engineering remains concentrated at a handful of legacy flexible packaging firms, constraining new supplier entry.
- Retooling capex burdens:Converting lines optimized for three-side-seal pouches require six-figure modifications to handle spouted stand-up formats with ultrasonic sealing specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Baby Food Packaging Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Jars, Pouches, Tetra Packs, Cans Material: Plastic, Glass, Metal, Paper Closure Type: Screw Caps, Snap Lids, Peel Off, Flip Top End User: Retailers, Online Stores, Supermarkets, Distributors |
| Companies Covered | Amcor PLC, Sonoco Products Company, Mondi PLC, Berry Global Inc., DS Smith PLC, Tetra Pak, Silgan Holdings, Ardagh Group, AptarGroup Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Baby Food Packaging Market Evolving Landscape
Material science breakthroughs and regulatory pressure are converging to transform substrate selection from a cost-driven procurement decision into a strategic compliance and brand positioning function.
High-barrier paper laminates incorporating bio-based coatings are decentralizing oxygen protection away from aluminum foil and ethylene vinyl alcohol coextrusions. Premium organic brands in California and the Pacific Northwest are specifying these structures for wet-fill applications previously reserved for plastics. The shift is compressing aluminum foil demand in infant nutrition while expanding coated-paper converter capacity.
State-level recycled-content mandates in California and emerging EPR legislation in New York are forcing brand owners to pre-qualify packaging against post-consumer recovery infrastructure rather than theoretical recyclability. This is accelerating mono-material pouch development and pressuring multi-layer laminate suppliers to simplify structures or absorb extended producer fees.
Subscription-based direct-to-consumer infant nutrition brands are compressing traditional retail procurement cycles by specifying custom packaging formats outside supermarket chain centralized specifications. This channel fragmentation is most visible in Brooklyn, Austin, and Denver metro areas where venture-backed startups bypass mass merchandiser compliance gates entirely.
United States Baby Food Packaging Market Segmentation
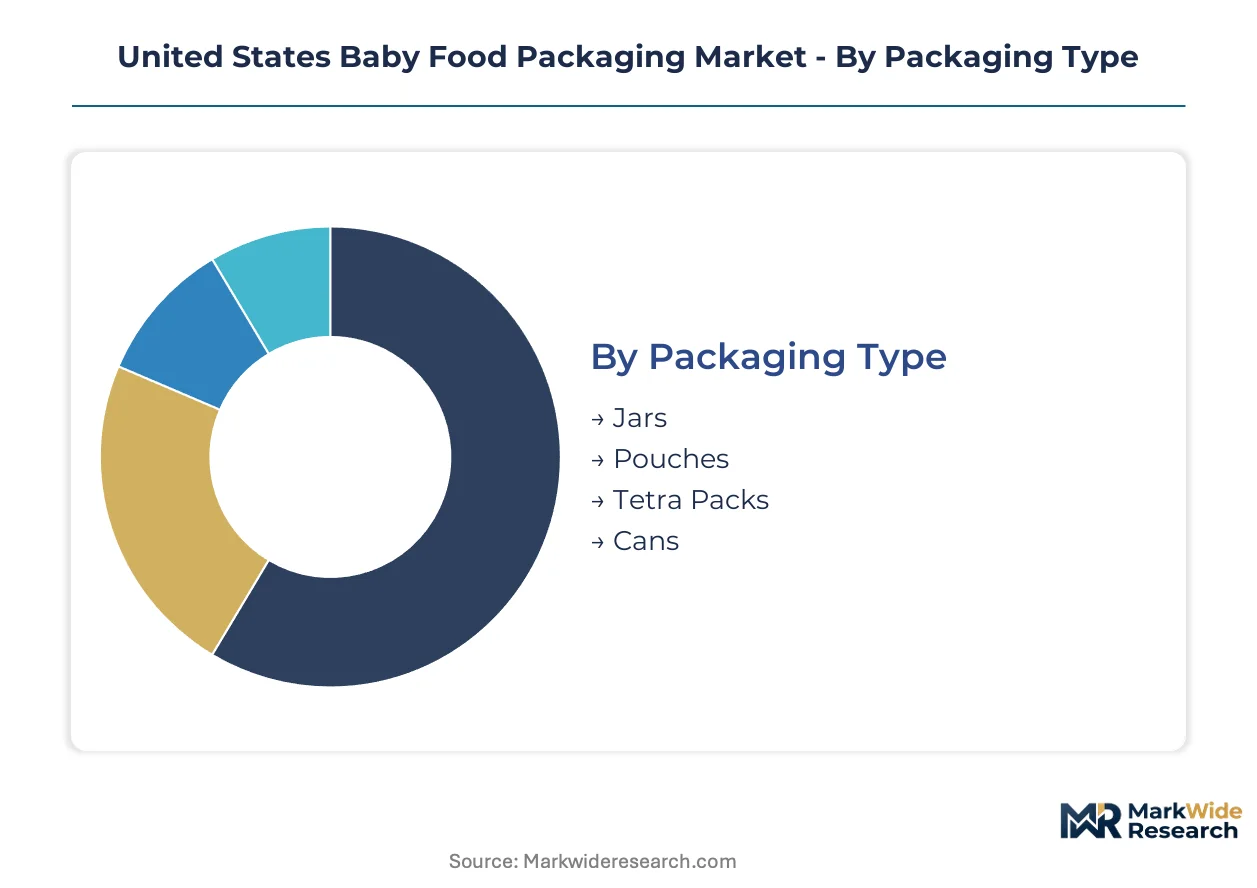
Packaging specification divergence across the United States baby food market reflects concentrated retailer procurement power and state-level regulatory fragmentation. Material and format selection now carries compliance risk as California EPR frameworks reshape recovery obligations.
Packaging Type:
Supply concentration in flexible film converting capacity favors pouch formats, while legacy glass jar infrastructure maintains regional strongholds in conventional retail.
- Jars:Borosilicate and soda-lime glass containers with metal lug closures dominate shelf-stable purees and toddler meals. Texas and Ohio manufacturing clusters sustain volume production for Walmart and Kroger centralized procurement.
- Pouches:Multi-layer stand-up structures with spout fitments capture parental preference for portability and reduced per-serving waste. California organic brands specify these formats at premium price points, though EPR fees pressure substrate simplification toward mono-material designs.
- Tetra Packs:Aseptic carton systems with aluminum foil barriers serve liquid infant formula and ready-to-feed products.
- Cans:Two-piece aluminum and steel containers persist in powdered formula segments where oxygen exclusion and stacking strength matter.
Pouches absorb the bulk of installed capacity; Tetra Packs are expanding most quickly in liquid formula applications.
Material:
Cost tier stratification separates commodity resin grades from fiber-based barrier innovations qualifying for retailer sustainability scorecards.
- Plastic:Polypropylene and polyethylene laminates retain volume leadership across pouch and rigid formats. Gulf Coast petrochemical concentration exposes converters to ethylene feedstock volatility during energy price spikes.
- Glass:Transparency and resealability sustain consumer trust in conventional retail segments, though weight and breakage elevate logistics costs versus flexible alternatives.
- Metal:Tinplate and aluminum provide absolute oxygen barriers for extended shelf-life requirements in powdered formula cans.
- Paper:Coated fiberboard composites and molded pulp trays gain specification in USDA organic supply chains where adhesive restrictions incidentally improve recyclability profiles.
Plastic commands current procurement volumes; Paper is climbing the fastest as California recycled-content mandates tighten.
Closure Type:
Customer type differentiation separates mass-merchandiser efficiency requirements from premium-channel dispensing experience priorities.
- Screw Caps:Polypropylene threaded closures with tamper-evident bands dominate jar formats across conventional retail. Standardization enables high-speed capping lines at Texas contract manufacturing clusters.
- Snap Lids:Press-fit polyethylene seals serve single-serve cups and portion-control formats in foodservice and institutional channels.
- Peel Off:Foil membrane lidding provides hermetic seals for single-use puree cups and yogurt-style formats.
- Flip Top:Hinged polypropylene dispensers enable one-handed feeding and controlled portion release, commanding specification in premium pouch lines targeting urban millennial parents.
Screw Caps retain the widest equipment compatibility; Flip Top is gaining share fastest in direct-to-consumer subscription channels.
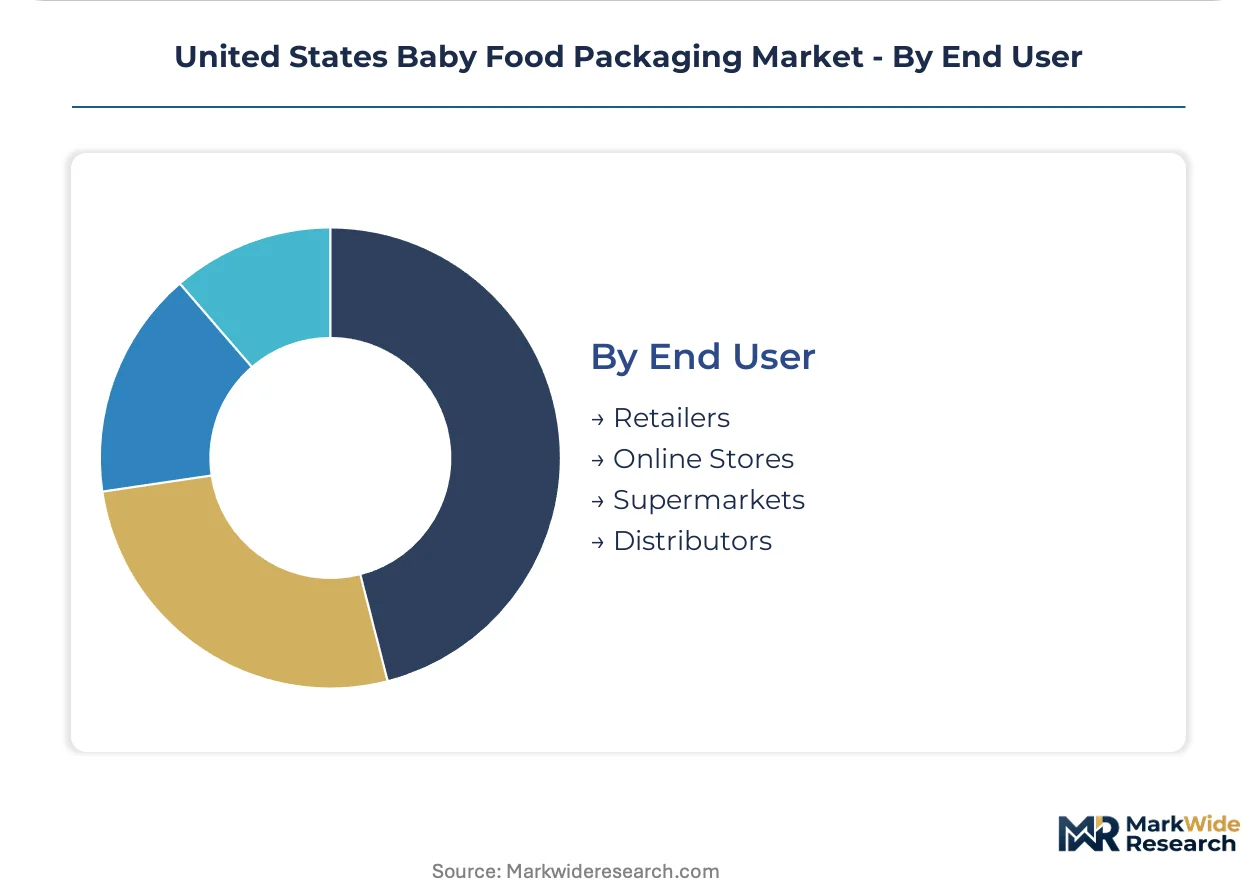
End User:
Geography drives procurement pattern divergence between centralized retail compliance and fragmented e-commerce specification.
- Retailers:National supermarket chains impose unified packaging specifications across private-label and branded portfolios, compressing regional supplier qualification timelines.
- Online Stores:Direct-to-consumer infant nutrition startups in Brooklyn, Austin, and Denver metro areas bypass mass-merchandiser compliance gates entirely, specifying custom formats.
- Supermarkets:Albertsons and Publix regional banners maintain distinct sustainability scorecards that pre-qualify packaging against store drop-off recovery infrastructure.
- Distributors:Foodservice and institutional channels concentrate procurement through broadline operators with standardized stock-keeping unit requirements.
Supermarkets absorb the bulk of specification volume; Online Stores are expanding most quickly as venture-backed brands proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene and propylene feedstock availability from Gulf Coast petrochemical clusters anchors packaging material supply chains across the United States. State-level regulatory fragmentation creates divergent compliance obligations that reshape procurement patterns. Birth-rate resilience and manufacturing concentration determine regional demand intensity.
California
Premium organic infant formula brands drive specification for fiber-based barrier laminates and recyclable mono-material pouches. CalRecycle's extended producer responsibility framework mandates post-consumer recovery targets that accelerate substrate simplification. Los Angeles and San Francisco Bay Area manufacturing clusters host contract packaging operations serving direct-to-consumer subscription brands.
Texas
Private-label manufacturing concentration in Dallas-Fort Worth and Houston metro areas sustains high-volume procurement of polypropylene and polyethylene laminates. State environmental regulations remain less prescriptive than California counterparts, permitting flexible format diversity. Port of Houston petrochemical infrastructure supplies regional converters with feedstock cost advantages.
New York Metro
Venture-backed infant nutrition startups in Brooklyn bypass mass-merchandiser compliance gates through direct-to-consumer channels. Emerging state-level extended producer responsibility legislation shapes pre-qualification requirements for recyclable packaging structures. Contract manufacturing capacity concentrates in northern New Jersey industrial corridors.
Pacific Northwest
Oregon's extended producer responsibility framework parallels California mandates, driving demand for How2Recycle-compatible pouch formats. USDA organic certification restrictions on adhesives and coatings push brands toward cleaner substrate formulations. Seattle and Portland metro areas host specialty coated-paper converter capacity for premium organic product lines.
Midwest
Ohio and Illinois manufacturing clusters sustain legacy glass jar production for conventional retail segments where transparency and resealability sustain consumer trust. Birth-rate stability supports consistent procurement volumes for shelf-stable puree formats. Regional distribution infrastructure serves Walmart and Kroger centralized procurement operations.
United States Baby Food Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue fiber-based barrier innovations and smart dispensing integration. Market structure reflects moderate consolidation with tiered specialization across rigid, flexible, and aseptic format domains. Three archetypes dominate: integrated multinational converters with North American flexibles footprints, rigid paperboard composite specialists, and fiber-based barrier technology innovators. Competitive moves center on multi-year supply agreement capture with national retailers and substrate reformulation to meet sustainability scorecard thresholds.
Within the integrated multinational tier, Amcor PLC and Berry Global Inc. represent scale-driven positions anchored in flexible film converting capacity. Sonoco Products Company exemplifies rigid composite expertise tailored to shelf-stable infant nutrition applications. Mondi PLC occupies a fiber-based innovation position addressing retailer sustainability compliance requirements.
| Leading Market Players |
|---|
| Amcor PLC |
| Sonoco Products Company |
| Mondi PLC |
| Berry Global Inc. |
| DS Smith PLC |
| Tetra Pak |
| Silgan Holdings |
| Ardagh Group |
| AptarGroup Inc. |
| Others |
Value Network & Pricing Analysis
National supermarket chains and mass merchandisers concentrate procurement power across the United States baby food packaging market, compressing supplier margins and enforcing contract-based long-term offtake structures that lock in volume commitments against price volatility.
Pricing Analysis
Volume procurement separates from premium-margin positioning across the market. Three-tier pricing structure across premium, standard, and economy levels tracks organic certification status and barrier performance specifications. Cost compression in fiber-based laminate tiers is intensifying because CalRecycle EPR fees pressure substrate simplification. Private-label manufacturers exhibit highest price sensitivity; direct-to-consumer organic brands show lowest sensitivity.
Supply Chain Analysis
Direct-to-contract-manufacturer channels handle hyperscale demand from Walmart and Kroger centralized procurement operations. Raw material supply draws from Gulf Coast petrochemical clusters for ethylene and propylene feedstocks, coated-paper converters in the Pacific Northwest, and Ohio glass manufacturing infrastructure. Single-source vulnerability concentrates in ethylene vinyl alcohol barrier film supply. Distribution runs through regional private-label manufacturing hubs in Dallas-Fort Worth and Houston.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States baby food packaging market is becoming a vertical-integration race as converters pursue captive supply of high-barrier paper substrates to escape petrochemical feedstock volatility and capture EPR-compliant margin pools.
For Market Incumbents: Hedge against fiber-based barrier disruption by securing multi-year pulp supply agreements with Pacific Northwest coated-paper converters. Expand ultrasonic sealing capacity in Texas manufacturing clusters to capture spouted pouch conversion demand from organic brands. FDA food contact notification expertise represents a defendable moat against biodegradable polymer entrants facing extended review timelines.
For New Entrants and Emerging Players: Venture-backed direct-to-consumer infant nutrition startups in Brooklyn and Austin represent an underserved buyer archetype bypassing mass-merchandiser compliance gates entirely. White-space concentration sits in How2Recycle-compatible mono-material pouches for California EPR compliance. Go-to-market leverage emerges through subscription-channel custom format specification outside retailer scorecard constraints.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier flexible film converters with established FDA notification portfolios and underutilized spouted-pouch capacity in the Midwest. Long-term viability hinges on substrate reformulation capabilities bridging plastic and fiber barrier technologies. The signal to monitor is CalRecycle enforcement intensity accelerating brand-owner packaging pre-qualification against post-consumer recovery infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Pouch Development | CalRecycle EPR mandates force substrate simplification to avoid extended producer fees. |
| Backward Integration into Coated Paper | Pacific Northwest pulp supply anchors fiber-based barrier cost control for organic lines. |
| Smart Dispensing Integration | AptarGroup NFC-enabled spouts enable pediatric nutrition tracking app subscriptions. |
| Texas Capacity Expansion | Dallas-Fort Worth clusters capture private-label procurement from emerging organic brands. |
| FDA Notification Pipeline Investment | Extended review timelines for biodegradable polymers favor incumbents with established dossiers. |
Research Methodology
Independent corroboration across packaging procurement executives at national retailers, flexible film converting plant managers, and regulatory affairs specialists at organic infant formula brands underwrites the qualitative findings. Primary interviews with category buyers, supply planners, and sustainability compliance officers combined with secondary validation against FDA food contact substance notifications, CalRecycle EPR rulemakings, and SEC 10-K filings from listed packaging converters. Bottom-up shipment data triangulates against top-down birth-rate elasticity models.
Comparable-period anchoring tied projection baselines to historical procurement cycles spanning shelf-stable puree and liquid formula format transitions. Segmentation dimensions modeled include packaging type, material substrate, closure mechanism, and end-user channel across the analysis window. CAGRs derived from elasticity-adjusted volume projections incorporating ethylene feedstock price indices and retailer sustainability scorecard adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to state-level EPR legislative expansion beyond California and Oregon. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food Packaging
Europe Pet Food Packaging Market
Baby Food Packaging
North America Home Care Packaging Market
Baby Food Packaging
Global Pet Food and Pet Product Packaging Market
Baby Food Packaging
APAC Baby Food Packaging Market
Baby Food Packaging
Baby Food Packaging Market
Baby Food Packaging
United States and Canada Child Resistant Bottles Market
Baby Food Packaging
Middle East and Africa Baby Food Packaging Market
Baby Food Packaging
Europe Home Care Packaging Market
Baby Food Packaging
Europe Baby Food Packaging Market
Baby Food Packaging
US Pet Food Packaging Market
Baby Food Packaging
Infant Formula Packaging Market
Baby Food Packaging
Breathable Films for Baby Care Market
Baby Food Packaging
Asia-Pacific Child Resistant Packaging Market
Baby Food Packaging
Baby Care Packaging Market