
 Infant Formula Packaging Market | 2026-2036
Infant Formula Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Infant Formula Packaging Market Outlook
Premium aseptic-grade packaging is bifurcating the competitive landscape as brands race to signal nutritional integrity through container quality. Tetra Pak leverages its laminated carton expertise to dominate shelf-stable formula segments in emerging markets. Amcor plc sustains leadership in high-barrier plastic bottles through proprietary multilayer coextrusion technology. AptarGroup differentiates via precision dosing closure systems that reduce contamination risk during repeated use.
Infant formula packaging encompasses engineered containment systems designed to protect hygroscopic powdered and liquid formulations from oxygen ingress, moisture, and light degradation, typically employing aluminum-laminate composites, ethylene-vinyl alcohol copolymer barrier layers, and nitrogen-flush sealing protocols to preserve lipid and probiotic stability through distribution. Metal cans retain the largest installed base for powdered formula but face margin compression from rising aluminum input costs and sustainability scrutiny. Plastic bottles represent the fastest-expanding segment as liquid ready-to-feed formulations gain preference among urban working parents. Tetra packs capture growing share in organic and follow-on formula categories where shelf appeal and retail differentiation command premium positioning.
The FDA regulates infant formula packaging through food contact notification protocols and stringent migration testing under 21 CFR standards, while the EU enforces the Packaging and Packaging Waste Regulation alongside REACH compliance for chemical constituents in plastic and laminate structures. China's SAMR imposes GB national standards for infant food packaging materials that increasingly reference EU safety benchmarks. Stakeholders must monitor evolving extended producer responsibility frameworks and bio-based material certification schemes that will reshape supplier qualification criteria and capital allocation priorities.
Market Dynamics
Aseptic carton technology and multi-layer barrier films are redrawing competitive boundaries as brands weaponize packaging integrity to signal nutritional safety and command shelf price premiums in premium formula segments.
Growth Catalysts
- SAMR's GB Standards Alignment:China's national food safety regulator tightened infant food packaging material benchmarks to mirror EU EFSA migration limits, forcing domestic dairy brands to upgrade from conventional metal cans to laminated carton systems with ethylene-vinyl alcohol barrier layers.
- Urban Working Parent Schedules:Time-compressed dual-income households in metropolitan China and South Korea are pivoting from powdered to ready-to-feed liquid formats, driving demand for precision-dosing plastic bottles with nitrogen-flush sealing protocols.
- Aluminum-Laminate Composites:Advanced coextrusion bonding techniques now enable thinner aluminum foil layers without compromising oxygen ingress protection, reducing material intensity while maintaining lipid stability for probiotic-enriched formulations.
Market Restraints
- Aluminum Input Cost Volatility:Primary aluminum ingot prices on the London Metal Exchange have subjected metal can producers to margin compression, accelerating the shift toward polymer-based alternatives despite higher conversion capital requirements.
- REACH Compliance Burden:EU chemical registration protocols for novel food contact substances impose multi-year toxicological assessment timelines, delaying commercialization of bio-based barrier coatings and recycled content laminates.
- Technical Limitation of Mono-Material Designs:Current mechanical recycling infrastructure cannot process multi-layer aseptic cartons without delamination, creating a structural barrier to circular economy claims and extended producer responsibility compliance.
Strategic Opportunities
- India's Underpenetrated Premium Segment:FSSAI's evolving standards for infant food packaging have yet to mandate barrier specifications equivalent to EU or China benchmarks, creating first-mover advantage for aseptic carton suppliers targeting emerging organic formula brands in Mumbai and Bangalore.
- Digital Printing Convergence:Integration of UV-cured inkjet systems with in-line quality inspection enables lot-specific traceability coding and personalized nutrition messaging without compromising barrier integrity.
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content thresholds and design-for-recycling criteria will reshape supplier qualification, rewarding early investments in chemically recyclable mono-material structures and solvent-free adhesive systems.
Industry Challenges
- Barrier Coating Formulation Expertise:The specialized knowledge required to balance oxygen transmission rates with heat-seal performance in bio-based coatings remains concentrated among a narrow cohort of polymer scientists and application engineers.
- Migration Testing Timeline Compression:FDA's food contact notification review periods and third-party laboratory queue congestion are extending time-to-market for innovative laminate structures, particularly those incorporating novel nanoclay or bio-derived barrier additives.
- Legacy Equipment Retrofit Complexity:Converting existing can-filling lines to accommodate aseptic carton or high-barrier bottle formats requires substantial mechanical and control system reconfiguration, straining capital allocation decisions for mid-sized dairy processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infant Formula Packaging Market |
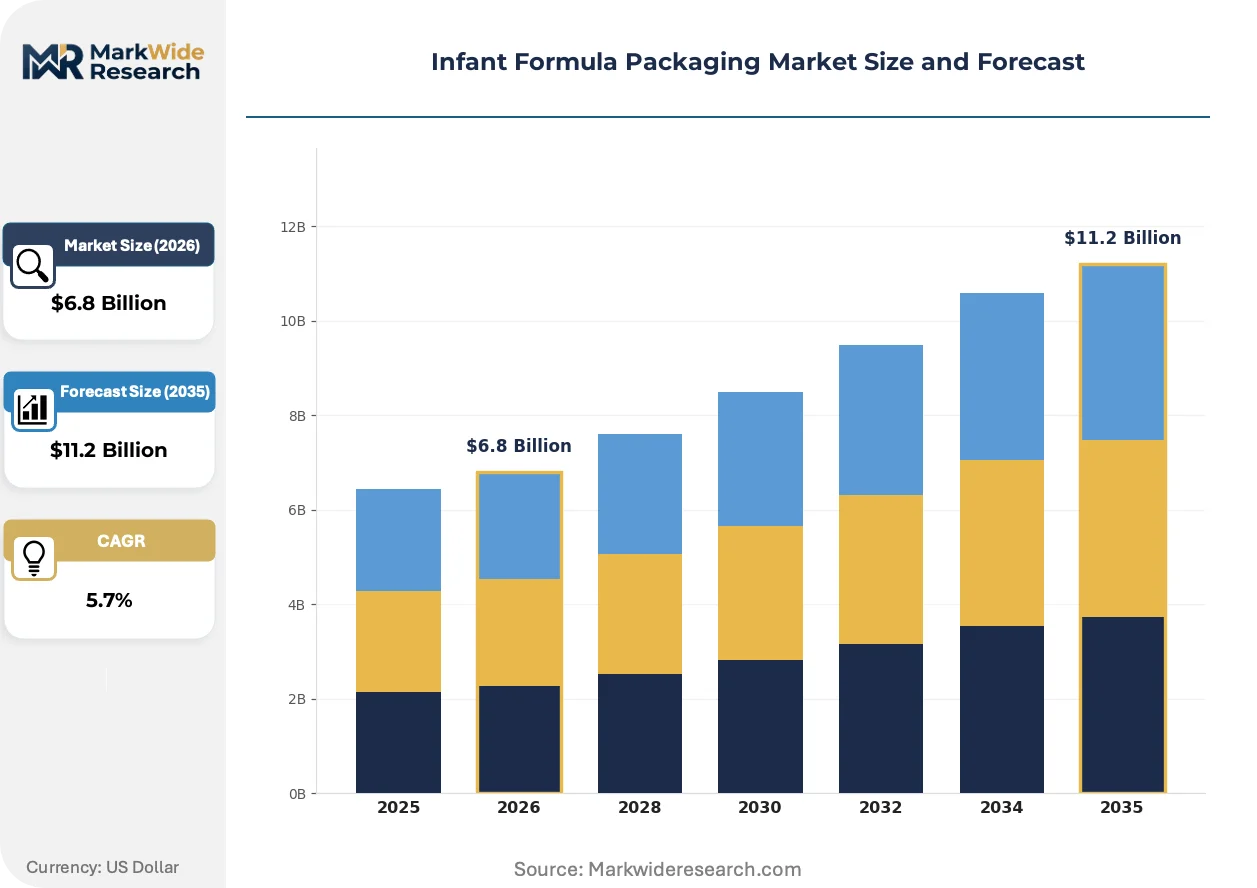
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Metal Cans, Plastic Bottles, Tetra Packs, Glass Jars Closure Type: Screw Caps, Flip Tops, Child-Resistant Caps, Tamper-Evident Seals Material: Polyethylene, Polypropylene, Aluminum, Glass Size: 200g, 400g, 800g, 1kg |
| Companies Covered | Amcor plc, Tetra Pak, Silgan Holdings, AptarGroup, Sonoco Products Company, Ardagh Group, Trivium Packaging, DS Smith, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infant Formula Packaging Market Strategic Shifts
Packaging format diversification is accelerating as sustainability mandates and convenience expectations collide, forcing material scientists and brand managers to reconcile conflicting performance requirements within single containment systems.
Multi-layer coextruded barrier films incorporating ethylene-vinyl alcohol and polyamide layers are fragmenting the traditional metal can dominance in powdered formula segments. Premium organic brands in Germany and the Netherlands are adopting these structures for their retail differentiation potential and reduced carbon footprint claims. The technology is fragmenting supplier hierarchies by enabling regional converters to compete with established multinational can manufacturers on specification compliance rather than scale economies.
REACH's revised authorization list for food contact substances is tightening permissible migration thresholds for bisphenol-derived compounds and certain phthalate plasticizers. European laminate producers are accelerating substitution programs toward non-phthalate plasticizers and epoxy-phenolic coating alternatives. Small-batch organic formula specialists face disproportionate compliance costs relative to multinational brands with dedicated regulatory affairs teams.
Direct-to-consumer subscription models are compressing traditional retail distribution dependencies for specialty formula brands. Parents in Seoul, Tokyo, and Singapore are prioritizing auto-replenishment platforms with temperature-controlled last-mile delivery over supermarket shelf selection. This channel rotation is most visible in hypoallergenic and goat-milk formula categories where brand loyalty and convenience premiums override price sensitivity.
Infant Formula Packaging Market Segmentation
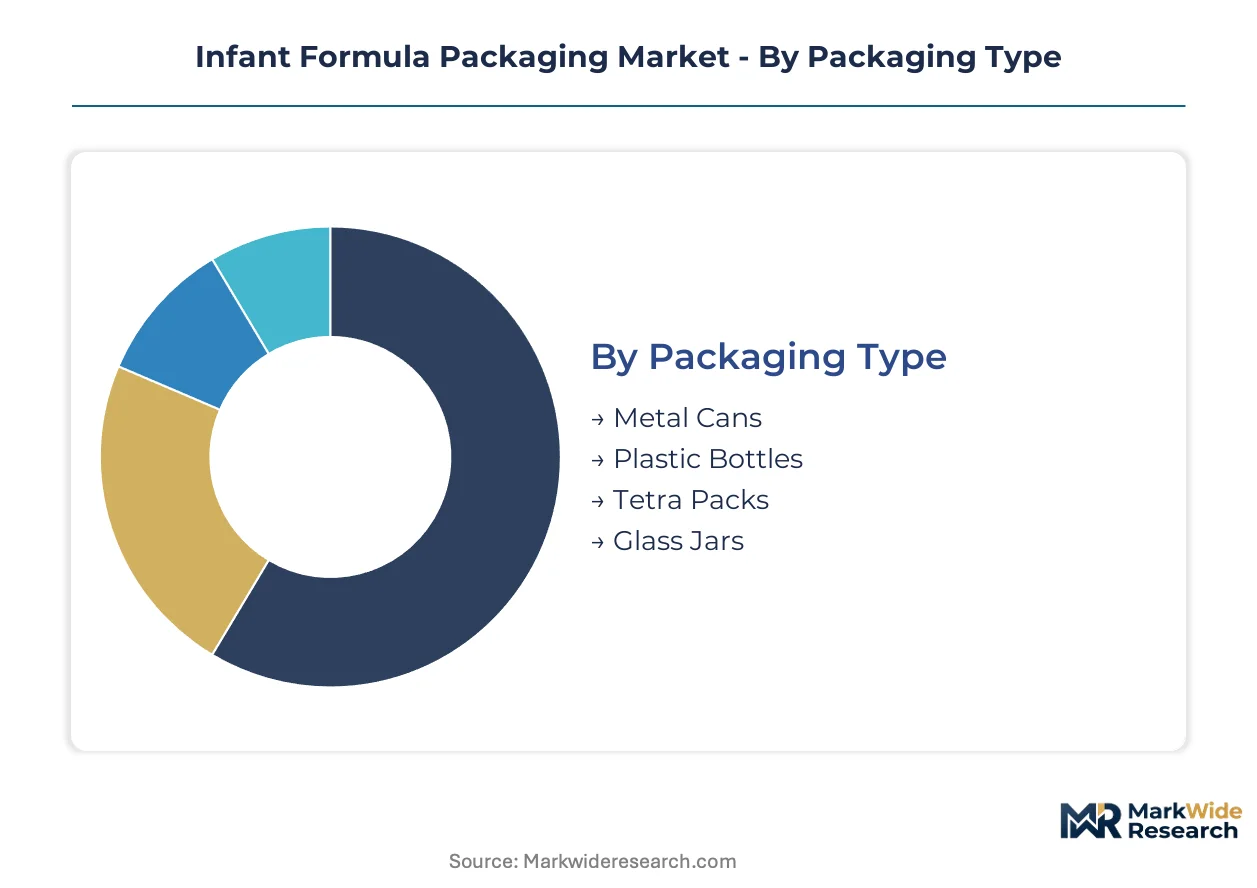
Segmentation in infant formula packaging reflects divergent channel strategies. E-commerce platforms favor lightweight formats with precision-dosing features, while brick-and-mortar retail prioritizes shelf differentiation and tamper-evident security.
Packaging Type:
Metal cans dominate mass-market retail channels, while aseptic cartons and barrier bottles capture premium online subscriptions and pharmacy networks.
- Metal Cans:Three-piece welded steel or aluminum cylinders with double-seamed ends provide crush resistance and light protection for powdered formulations. Demand concentrates in China's tier-three cities where price-sensitive consumers purchase through hypermarkets and mom-and-pop stores, though aluminum input costs are compressing margins for domestic can manufacturers.
- Plastic Bottles:Multi-layer coextruded structures incorporating ethylene-vinyl alcohol barrier layers enable nitrogen-flush sealing for ready-to-feed liquid formulas. Urban working parents in Seoul and Singapore drive procurement through auto-replenishment platforms, prioritizing convenience and precise dosing over unit economics.
- Tetra Packs:Laminated paperboard composites with aluminum foil cores serve organic and follow-on formula brands seeking shelf differentiation in European pharmacy chains.
- Glass Jars:Borosilicate and soda-lime containers retain niche positioning for artisanal goat-milk and hypoallergenic formulations sold through specialty retailers.
By volume, metal cans lead. By growth pace, plastic bottles are expanding most quickly.
Closure Type:
Closure selection tracks format sophistication and regulatory stringency, with premium liquid formats demanding precision-engineered dispensing systems.
- Screw Caps:Standardized polypropylene or polyethylene threaded closures dominate powdered formula cans and economy liquid bottles across mass retail channels in India and Southeast Asia.
- Flip Tops:Hinged polyolefin designs enable single-handed operation for time-compressed caregivers, capturing share in South Korean convenience store channels.
- Child-Resistant Caps:Push-and-turn or squeeze-and-turn mechanisms comply with poison prevention packaging mandates in the US and EU, adding cost but mandatory for pharmacy distribution.
- Tamper-Evident Seals:Induction-sealed foil membranes and shrink bands provide first-open assurance, critical for e-commerce shipments where chain-of-custody verification replaces physical shelf inspection.
Screw caps retain the largest installed base. Child-resistant systems command the highest unit margins.
Material:
Material specifications balance barrier performance against recyclability claims, with regulatory migration limits increasingly dictating formulation choices.
- Polyethylene:Low-density and linear low-density grades provide moisture resistance and heat-sealability for inner liner bags and bottle bodies, though oxygen transmission rates limit standalone use for lipid-sensitive formulations.
- Polypropylene:High crystallinity homopolymer and random copolymer grades deliver stiffness and chemical resistance for caps, closures, and rigid containers in steam-sterilized applications.
- Aluminum:Rolled foil and impact-extruded can bodies provide absolute light and oxygen barrier properties, though mechanical recycling infrastructure cannot process laminate-bonded foil residues.
- Glass:Type III soda-lime and neutral borosilicate compositions offer inert contact surfaces and infinite recyclability, offset by weight penalties and breakage risk in last-mile delivery.
Polyethylene leads by tonnage. Aluminum commands premium positioning.
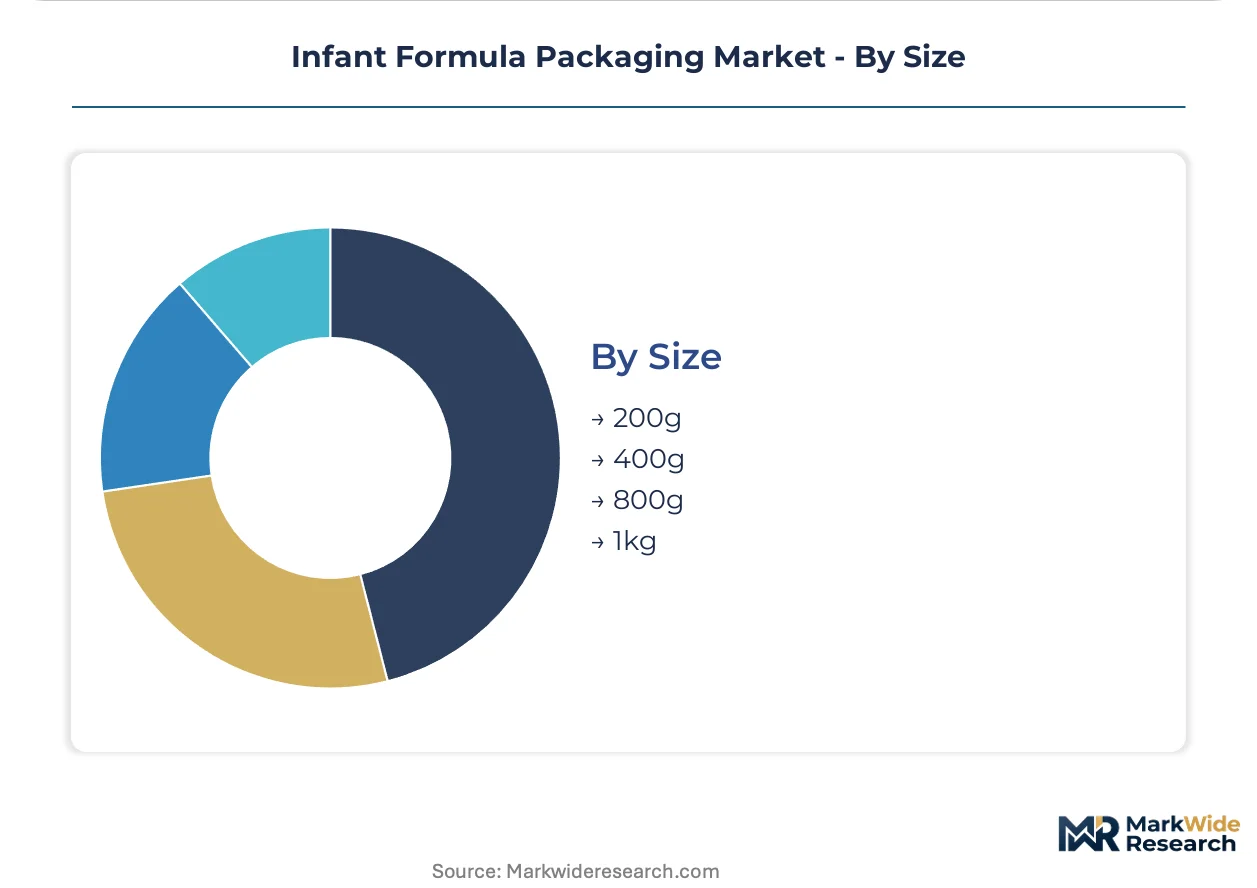
Size:
Format sizing reflects consumption velocity, storage constraints, and trial-to-loyalty progression in customer lifecycle management.
- 200g:Compact trial sizes target new parent acquisition and travel segments, prevalent in hospital discharge gift packs and airline amenity kits.
- 400g:Mid-range formats balance freshness preservation with weekly replenishment cycles, dominant in Japanese convenience store channels.
- 800g:Standard household stock-keeping units optimize per-gram economics for established consumers with predictable consumption patterns.
- 1kg:Bulk formats serve institutional buyers and value-oriented households in price-sensitive markets, though hygroscopic degradation risks limit shelf life.
Eight-hundred-gram formats lead by volume. Two-hundred-gram sizes gain share fastest in subscription channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for high-barrier packaging materials concentrates procurement leverage in Germany and Switzerland, while China and the United States drive format innovation through divergent regulatory pathways. Export-oriented converters in the Netherlands and Japan supply laminated carton systems to emerging formula brands across Southeast Asia and the Middle East.
China
Domestic dairy brands in Shanghai and Guangzhou are upgrading from conventional metal cans to multi-layer laminated cartons with ethylene-vinyl alcohol barrier layers. SAMR's tightened GB standards for infant food packaging materials now mirror EU EFSA migration limits, accelerating compliance investments. Qingdao and Tianjin host concentrated clusters of aseptic carton converters serving local organic formula specialists.
Germany
Premium organic formula brands in Munich and Hamburg prioritize retail differentiation through Tetra Pak laminated cartons with aluminum foil cores. ECHA's REACH authorization protocols for food contact substances impose multi-year toxicological assessments on novel bio-based barrier coatings. The Baden-Württemberg region anchors specialized coextrusion equipment manufacturing for multi-layer film systems.
United States
Pharmacy-distributed liquid ready-to-feed formats in Chicago and New York Metro drive demand for precision-dosing plastic bottles with child-resistant closure systems. FDA's 21 CFR food contact notification protocols mandate stringent migration testing for ethylene-vinyl alcohol copolymer structures. Wisconsin and Ohio concentrate metal can production for mass-market powdered formula retail channels.
Japan
Urban working parents in Tokyo and Osaka auto-replenish premium liquid formulas through temperature-controlled subscription platforms. METI's guidance on sustainable packaging design encourages thinner aluminum-laminate composites without compromising oxygen barrier performance. The Nagoya industrial corridor specializes in nitrogen-flush sealing equipment for probiotic-enriched formulations.
India
Emerging organic formula brands in Mumbai and Bangalore seek aseptic carton suppliers as FSSAI standards for infant food packaging evolve toward EU-equivalent barrier specifications. Import dependence for high-barrier films creates first-mover opportunities for laminated carton specialists. Gujarat's polymer processing cluster is expanding coextrusion capacity to serve domestic dairy packaging upgrades.
Infant Formula Packaging Market Competitive Environment
Concentration sits with diversified packaging conglomerates possessing integrated material science capabilities and established regulatory compliance infrastructures. The vendor base stratifies across three tiers: multinational laminate specialists with aseptic carton dominance, regional high-barrier plastic converters, and niche metal can fabricators facing margin compression. Strategic moves center on backward integration into barrier film production and technology licensing partnerships with dairy processors seeking format conversion.
Among Switzerland-based packaging specialists, Tetra Pak occupies a position exemplifying aseptic carton archetype dominance through laminated paperboard expertise. Amcor plc represents the high-barrier plastic bottle segment with multilayer coextrusion capabilities. AptarGroup sits within the precision closure tier, anchoring dosing system specialization for liquid formula applications.
| Leading Market Players |
|---|
| Amcor plc |
| Tetra Pak |
| Silgan Holdings |
| AptarGroup |
| Sonoco Products Company |
| Ardagh Group |
| Trivium Packaging |
| DS Smith |
| Mondi Group |
| Others |
Value Chain & Pricing Dynamics
Aluminum-laminate composite substitution for conventional metal can structures is redrawing supply geography from Midwestern US can fabrication clusters toward Southeast Asian coextrusion film hubs while simultaneously compressing pricing premiums for oxygen-barrier packaging tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the infant formula packaging spectrum. Three-tier pricing structure across premium aseptic cartons, standard multi-layer bottles, and economy metal cans reflects certification grade differentiation under FDA 21 CFR and EU REACH compliance tiers. Cost compression in standard-tier barrier bottles is intensifying because ethylene-vinyl alcohol resin supply concentrates among three Japanese and European chemical producers. Mass-market dairy processors in China's tier-three cities exhibit highest price sensitivity, while organic formula specialists in Germany and Japan accept premium positioning for laminated carton shelf differentiation.
Supply Chain Analysis
Just-in-time inventory preferences dominate liquid ready-to-feed bottle procurement through auto-replenishment platforms, whereas strategic stockpiling of aluminum-laminate rollstock persists among powdered formula can converters hedging against London Metal Exchange volatility. Geographic supply concentration centers on Germany and Switzerland for aseptic carton equipment, China and South Korea for barrier film coextrusion, and the United States for precision-dosing closure systems. Raw material dependencies draw from rolled aluminum foil, ethylene-vinyl alcohol copolymer resins, and nitrogen-flush sealing membranes. Single-source vulnerability in specialty barrier coating formulations creates structural exposure. Distribution runs through dairy processor direct procurement, regional converter networks, and third-party logistics providers managing temperature-controlled last-mile delivery for liquid formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent packaging suppliers face sustained substitution pressure from bio-based barrier coating technologies that promise circular economy compliance without multi-layer delamination complexity, forcing defensive capability investments.
For Market Incumbents: Secure backward integration into ethylene-vinyl alcohol copolymer resin production to insulate margin structures from petrochemical feedstock volatility. Deepen certification investment under China's evolving GB standards and EU Packaging and Packaging Waste Regulation to disqualify regional converters lacking dedicated regulatory affairs infrastructure. Channel control through exclusive equipment-lease arrangements with mid-sized dairy processors in India and Southeast Asia raises switching costs against laminated carton entrants. For New Entrants and Emerging Players: Precision dosing system integration for liquid ready-to-feed formats represents the most penetrable service-layer gap where incumbents under-serve subscription-platform channel requirements. Target Mumbai and Bangalore organic formula brands seeking aseptic carton differentiation ahead of FSSAI barrier specification mandates. Pursue technology licensing partnerships with Gujarat polymer processors expanding coextrusion capacity rather than greenfield manufacturing investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European laminate specialists carrying REACH compliance infrastructure but limited Asia-Pacific manufacturing footprint. Five-to-ten year viability hinges on chemical recycling pathway commercialization for multi-layer structures. Acquisition target archetype: mid-cap aseptic carton converters with established SAMR relationships in China and underutilized equipment capacity. Watch for EU Packaging and Packaging Waste Regulation recycled content threshold announcements as inflection indicator for mono-material R&D prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Pathway Investment | Enables circular economy claims for multi-layer aseptic cartons under EU extended producer responsibility frameworks. |
| Barrier Film Backward Integration | Captive ethylene-vinyl alcohol supply insulates margins from petrochemical volatility and Japanese resin producer concentration. |
| Precision Dosing System Licensing | AptarGroup-style closure technology partnerships penetrate liquid ready-to-feed subscription channels in Seoul and Singapore. |
| GB Standards Compliance Certification | SAMR-aligned testing infrastructure qualifies suppliers for China's domestic dairy brand upgrade cycle from metal cans. |
| Nitrogen-Flush Sealing Equipment Scale-Up | Probiotic formula stability requirements drive demand for Nagoya-specialized machinery in organic segment expansion. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with packaging procurement directors at dairy processors, regulatory affairs managers at laminate converters, and equipment engineering leads at aseptic filling line manufacturers; and secondary validation against FDA food contact substance notification databases, EU EFSA migration limit guidelines, SAMR GB standard publications, and trade flow records for aluminum-laminate composite imports. Bottom-up demand modeling triangulated against top-down market sizing from barrier material consumption data.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning packaging format type, closure sophistication tier, material barrier specification, and regional regulatory cluster alignment. CAGRs were derived from trend extrapolation of format substitution rates, input cost trajectory assumptions, and compliance investment elasticity estimates. Forecast inputs incorporated ethylene-vinyl alcohol resin capacity expansion timelines and nitrogen-flush sealing equipment deployment patterns in probiotic formula segments.
Forecasts assume regulatory continuity in FDA 21 CFR enforcement, EU REACH authorization protocols, and SAMR GB standards alignment; material policy shifts toward accelerated bio-based material mandates or tightened migration thresholds would require re-modeling. Revision becomes warranted when aluminum-laminate composite recycling pathway economics cross commercial viability thresholds or when India's FSSAI implements EU-equivalent barrier specifications ahead of baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food Packaging
Middle East and Africa Baby Food Packaging Market
Baby Food Packaging
Baby Food Packaging Market
Baby Food Packaging
Europe Pet Food Packaging Market
Baby Food Packaging
North America Home Care Packaging Market
Baby Food Packaging
APAC Baby Food Packaging Market
Baby Food Packaging
Asia-Pacific Child Resistant Packaging Market
Baby Food Packaging
Baby Care Packaging Market
Baby Food Packaging
Global Pet Food and Pet Product Packaging Market
Baby Food Packaging
US Pet Food Packaging Market
Baby Food Packaging
United States Baby Food Packaging Market
Baby Food Packaging
United States and Canada Child Resistant Bottles Market
Baby Food Packaging
Breathable Films for Baby Care Market
Baby Food Packaging
Europe Home Care Packaging Market
Baby Food Packaging
Europe Baby Food Packaging Market